
 Hollow Fiber Ceramic Membrane Market | 2026-2036
Hollow Fiber Ceramic Membrane Market Size, Share, and Industry Trends Forecast 2026-2036
Hollow Fiber Ceramic Membrane Market Foresight
Multi-source procurement of ceramic membrane modules is shifting toward captive in-house fabrication as OEMs seek supply security. Koch Membrane Systems leverages its polymer-ceramic hybrid expertise to anchor North American industrial accounts. Sartorius AG sustains pharmaceutical-grade positioning through stringent quality protocols. CoorsTek, Inc. dominates advanced alumina formulations for high-temperature process streams.
Hollow fiber ceramic membranes are tubular filtration elements manufactured from alumina, titania, or zirconia, with pore diameters spanning microfiltration to ultrafiltration ranges and operating temperatures exceeding 300°C. These structures separate particulates, bacteria, and macromolecules from liquid or gas feeds in aggressive chemical environments where polymeric alternatives degrade. Ultrafiltration product types command premium positioning due to biopharmaceutical sterility requirements and extended service intervals. Water treatment applications absorb baseline volume, though wastewater treatment is accelerating fastest as refineries and chemical plants face intensified effluent mandates. Membrane bioreactor technology concentrates R&D investment, integrating biological degradation with ceramic mechanical resilience for high-strength industrial effluent.
EPA effluent limitation guidelines shape United States demand by mandating ceramic durability in heavy industrial discharge systems, while REACH compliance in Europe restricts extractables from polymeric alternatives in food-contact and pharmaceutical applications. FDA process validation requirements for sterile filtration create barrier-to-entry dynamics favoring established ceramic suppliers with documented qualification protocols. Stakeholders must monitor evolving PFAS treatment regulations, as ceramic membrane thermal stability positions the technology for destruction-concentration hybrid processes.
Market Dynamics
Biologics manufacturers are consolidating sterile filtration procurement around ceramic durability as FDA process validation requirements harden qualification barriers against polymeric alternatives. This regulatory tightening concentrates supplier relationships among membrane fabricators with documented pharmaceutical-grade protocols.
Growth Catalysts
- EPA Effluent Limitation Guidelines:Heavy industrial discharge mandates in the United States are compelling refineries and chemical plants toward ceramic mechanical resilience in wastewater systems.
- Membrane Bioreactor Integration:Biological degradation coupled with ceramic structural integrity is capturing R&D investment for high-strength industrial effluent treatment.
- German Chemical Processing:Aggressive solvent stream handling requirements are prioritizing long-lifecycle membrane systems over polymeric alternatives in Rhineland industrial clusters.
Market Restraints
- Alumina Feedstock Concentration:Advanced ceramic formulation depends on specialized alumina supply chains concentrated among limited high-purity producers.
- Capital Intensity Barrier:Sintering infrastructure for hollow fiber geometries requires substantial furnace investment that excludes mid-scale entrants.
- REACH Extractable Limits:European chemical compliance creates friction for polymeric-ceramic hybrid systems in food-contact applications.
Strategic Opportunities
- PFAS Destruction-Concentration Hybrids:Thermal stability positioning enables ceramic membranes to capture and concentrate perfluorinated compounds for subsequent destruction.
- India Pharmaceutical Manufacturing:CDSCO sterility requirements and expanding biologics capacity create demand for qualified ceramic filtration systems.
- Captive In-House Fabrication:OEMs are internalizing module production to secure supply continuity against procurement volatility.
Industry Challenges
- Qualification Timeline Compression:FDA process validation documentation requirements extend sales cycles for new ceramic membrane suppliers.
- Specialized Sintering Expertise:Hollow fiber geometry production demands ceramic engineering talent scarce outside established industrial ceramics regions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hollow Fiber Ceramic Membrane Market |
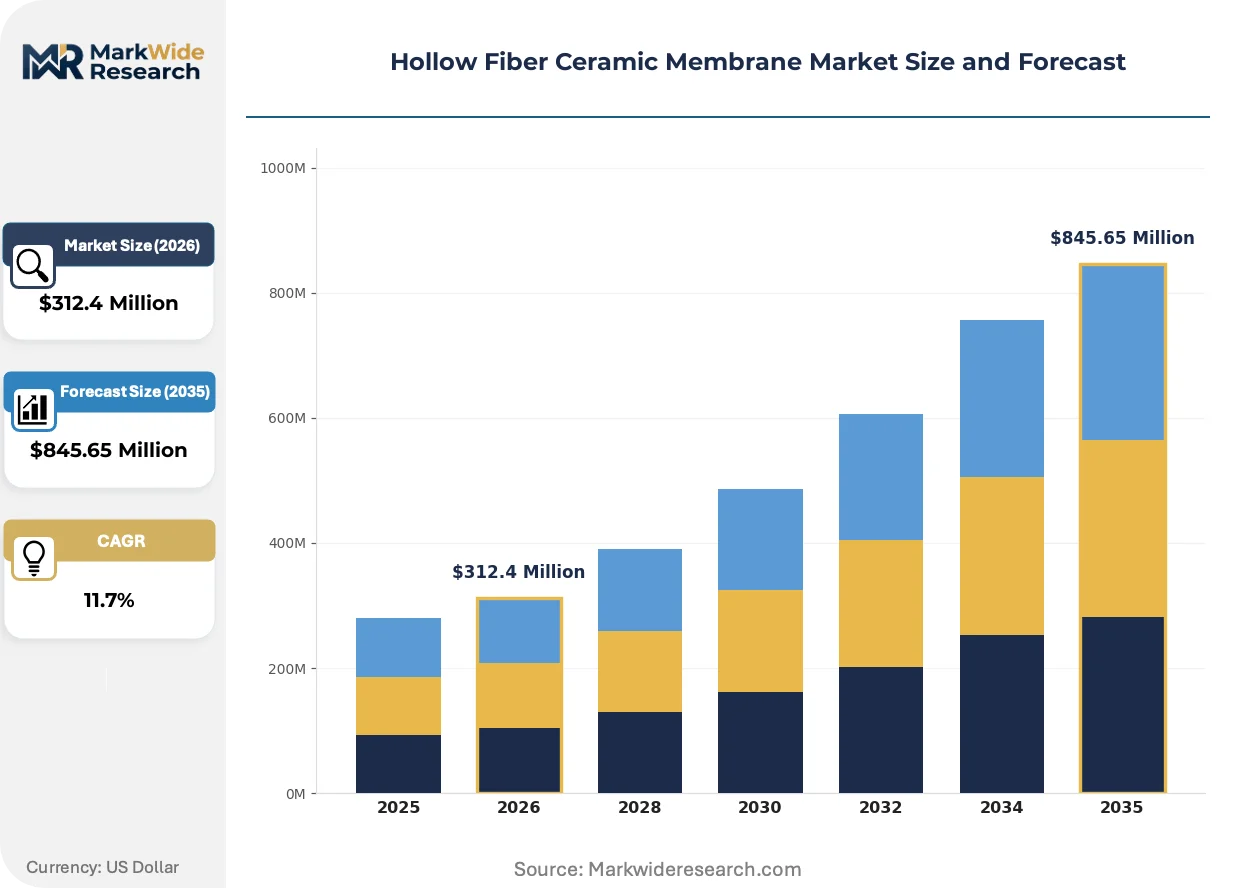
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $845.65 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Microfiltration, Ultrafiltration, Nanofiltration, Reverse Osmosis Application: Water Treatment, Food & Beverage Processing, Pharmaceutical Manufacturing, Wastewater Treatment End User: Municipalities, Industrial Facilities, Research Institutes, Beverage Companies Technology: Membrane Bioreactor, Pressure-driven Membrane Separation, Cross-flow Filtration, Dead-end Filtration |
| Companies Covered | Nanostone, Sartorius AG, Koch Membrane Systems, Microdyn-Nadir, QUA Group LLC, CoorsTek, Inc., TAMI Industries, Media and Process Technology Inc., Atech Innovations GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hollow Fiber Ceramic Membrane Market Shifts & Advancements
Membrane architecture is evolving toward hybrid biological-mechanical systems that exploit ceramic thermal and chemical stability in previously polymeric-dominated niches. Fabrication methods and procurement patterns are simultaneously transforming.
Multi-layer asymmetric membrane structures with gradient porosity are decentralizing filtration performance across broader pH and temperature ranges. Pharmaceutical sterile filtration adopters are specifying these architectures for extended validation intervals. The technology is decentralizing competitive advantage from polymer chemistry toward ceramic process engineering capabilities.
REACH compliance in Europe is restricting extractable leachates from polymeric alternatives in pharmaceutical and food-contact streams. Industrial membrane selectors are disqualifying polymer-based systems for applications requiring thermal sterilization. Ultrafiltration product categories in Germany and Switzerland are responding with accelerated ceramic qualification protocols.
Service unbundling is separating membrane module supply from installation and validation support. Water treatment integrators are sourcing bare ceramic elements directly from fabricators while retaining commissioning expertise in-house. This pattern concentrates most visibly in United States municipal and industrial accounts facing compressed capital expenditure timelines.
Hollow Fiber Ceramic Membrane Market Segmentation
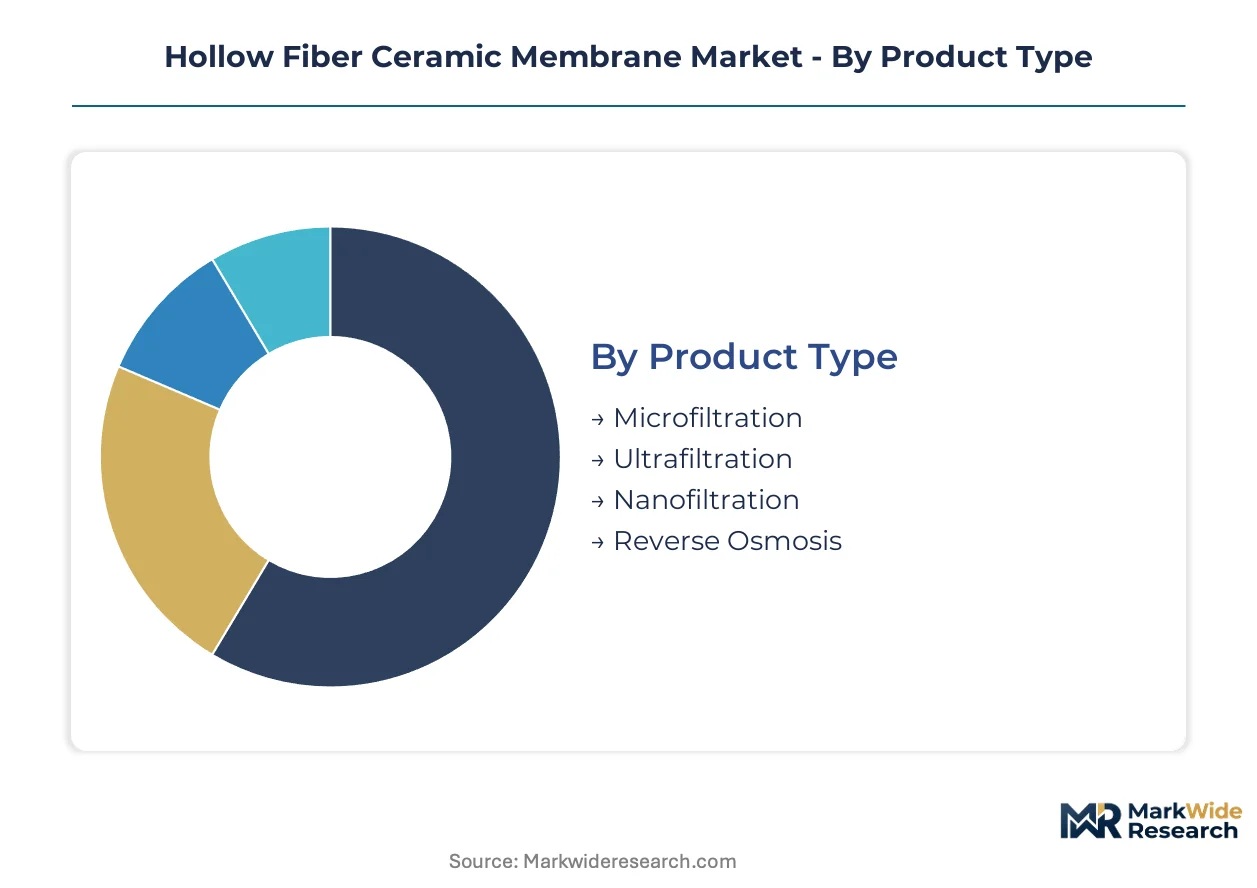
Product architecture and application intensity determine margin capture in hollow fiber ceramic membranes. Segmentation reveals where alumina-titania-zirconia formulations command premium positioning versus baseline volume absorption.
Product Type:
Ultrafiltration commands premium positioning while microfiltration absorbs baseline volume across industrial accounts.
- Microfiltration:Pore diameters of 0.1–10 micrometers target suspended solids and bacterial removal in pre-treatment stages. Demand concentrates in United States municipal water facilities facing EPA turbidity mandates. Capital constraints favor this entry-tier ceramic option.
- Ultrafiltration:0.01–0.1 micrometer pores deliver macromolecular separation for pharmaceutical sterile filtration. German and Swiss biologics manufacturers specify these membranes for validated aseptic processes. FDA process validation requirements harden qualification barriers, concentrating supplier relationships.
- Nanofiltration:Divalent ion and small organic rejection for selective separation in aggressive chemical streams.
- Reverse Osmosis:Highest pressure operation for desalination and ultrapure water generation in semiconductor fabrication.
Mature deployment sits with microfiltration. Newer deployment is concentrated in ultrafiltration.
Application:
Water treatment holds volume leadership while wastewater treatment climbs the fastest on regulatory pressure.
- Water Treatment:Municipal and industrial potable water production leverages ceramic durability against chlorine and ozone exposure. Baseline volume concentrates in United States Great Lakes region utilities updating aging infrastructure. Procurement favors standardized module geometries to minimize spare parts complexity.
- Wastewater Treatment:Refinery and chemical plant effluent polishing exploits thermal and chemical resilience for high-strength industrial streams. German Rhineland industrial clusters prioritize long-lifecycle systems for aggressive solvent handling. EPA effluent limitation guidelines are forcing United States facilities toward ceramic mechanical durability.
- Pharmaceutical Manufacturing:Sterile filtration and virus removal for biologics production with validated qualification protocols.
- Food & Beverage Processing:Thermal sterilization compatibility drives displacement of polymeric membranes in dairy and beverage clarification.
Established deployment dominates water treatment. Accelerating deployment centers on wastewater treatment.
End User:
Industrial facilities drive premium procurement while municipalities anchor volume on capital efficiency.
- Industrial Facilities:Chemical processors, refineries, and pharmaceutical manufacturers specify ceramic membranes for aggressive pH and temperature extremes. Demand concentrates in Germany's solvent-handling sectors and United States petrochemical corridors. REACH extractable limits and EPA discharge mandates reinforce ceramic specification.
- Municipalities:Public water and wastewater utilities prioritize lifecycle cost over first-cost in procurement evaluations. United States infrastructure replacement cycles favor proven ceramic durability. Budget compression limits adoption to critical high-fouling applications.
- Research Institutes:Pilot-scale membrane testing and process development for technology validation.
- Beverage Companies:Quality-sensitive producers in Switzerland and Germany specify ceramic for thermal sterilization compatibility.
Volume concentration rests with municipalities. Margin expansion sits with industrial facilities.
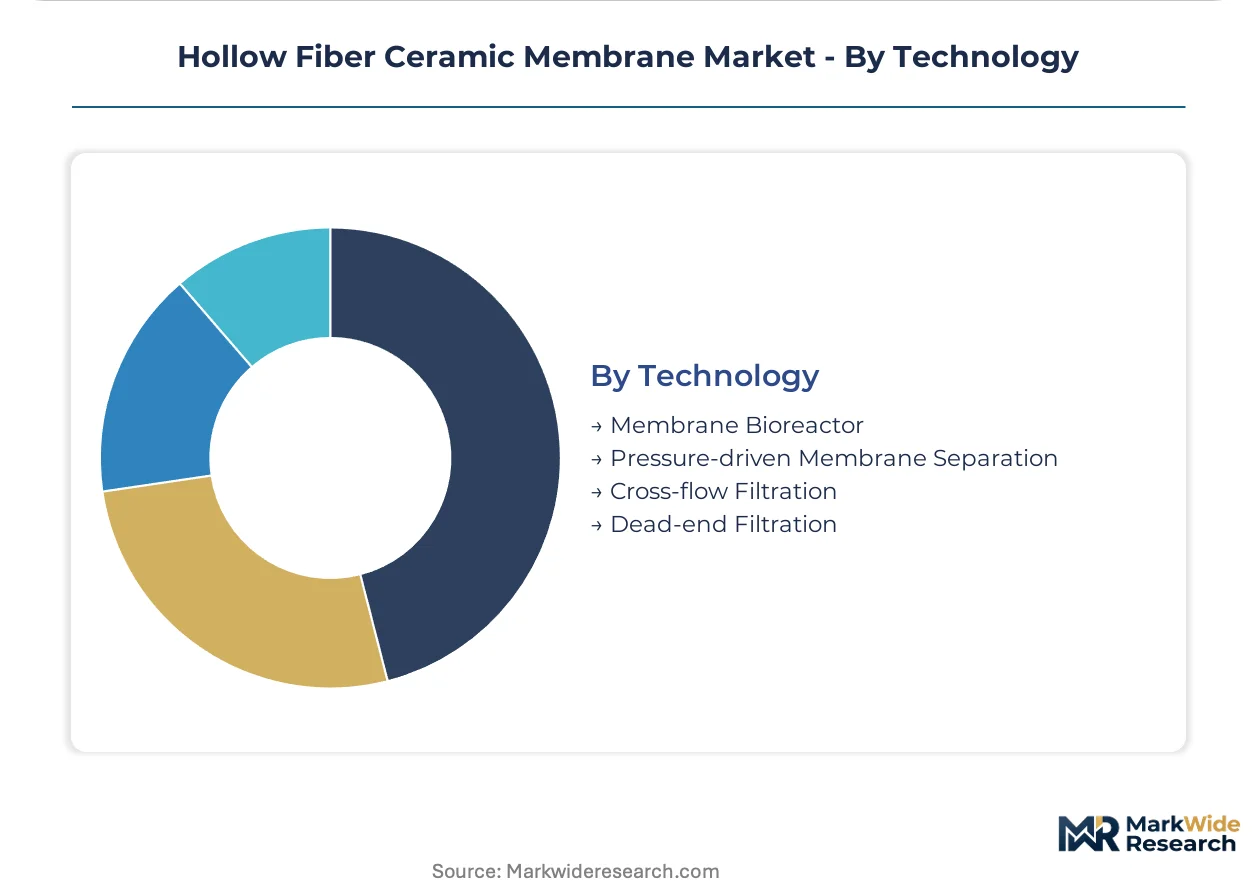
Technology:
Pressure-driven separation dominates installed base while membrane bioreactor integration captures R&D investment.
- Membrane Bioreactor:Biological degradation coupled with ceramic structural integrity targets high-strength industrial effluent. German engineering firms lead integration design for chemical plant wastewater. Thermal stability enables steam sterilization protocols impossible with polymeric alternatives.
- Pressure-driven Membrane Separation:Transmembrane pressure operation across microfiltration to reverse osmosis spans the broadest application range. Baseline deployment concentrates in United States and German water treatment accounts. Standardization of module dimensions reduces system integration cost.
- Cross-flow Filtration:Tangential flow operation minimizes fouling in high-solids pharmaceutical and food streams.
- Dead-end Filtration:Direct flow configuration for low-solids applications with periodic backwash cleaning cycles.
Installed maturity concentrates in pressure-driven separation. Technology evolution centers on membrane bioreactor systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial demand for ceramic membrane durability concentrates in Germany's chemical corridors and the United States petrochemical belt, where aggressive process streams and regulatory pressure intersect. Pharmaceutical-grade procurement gravitates toward Switzerland and the United Kingdom, driven by sterilization validation requirements. Wastewater treatment mandates are accelerating adoption across Japanese industrial prefectures and Indian pharmaceutical manufacturing zones.
United States
EPA effluent limitation guidelines compel refineries and chemical plants toward ceramic mechanical resilience in discharge systems. The agency's tightening heavy industrial mandates favor membranes with documented thermal stability. Texas and Louisiana petrochemical corridors prioritize long-lifecycle systems for high-temperature process stream handling.
Germany
Chemical processors in Rhineland industrial clusters specify ceramic membranes for aggressive solvent stream compatibility. REACH extractable limits restrict polymeric alternatives in pharmaceutical and food-contact applications. North Rhine-Westphalia engineering firms lead membrane bioreactor integration design for chemical plant wastewater treatment.
Switzerland
Biologics manufacturers demand ultrafiltration membranes with validated sterile filtration protocols for aseptic processing. Swissmedic quality requirements harden qualification barriers against non-ceramic alternatives. Basel pharmaceutical clusters specify ceramic systems for extended validation intervals and thermal sterilization compatibility.
Japan
Industrial prefectures deploy ceramic membranes for high-strength effluent treatment under METI environmental compliance frameworks. PMDA process validation requirements reinforce pharmaceutical-grade ceramic specification. Osaka-Kobe manufacturing belts prioritize ceramic durability in chemical and electronics process water systems.
India
CDSCO sterility requirements and expanding biologics capacity create demand for qualified ceramic filtration systems. Pharmaceutical contract manufacturers in Maharashtra and Gujarat specify ceramic membranes for FDA-aligned export production. Bangalore and Hyderabad biotech clusters are accelerating ceramic qualification protocols for sterile processing.
Hollow Fiber Ceramic Membrane Market Competitive Landscape
Captive in-house fabrication dominates the current landscape as OEMs internalize module production to secure supply continuity. The vendor base stratifies across three tiers: integrated industrial ceramics conglomerates with sintering infrastructure, specialized membrane fabricators with pharmaceutical-grade protocols, and regional water treatment integrators sourcing bare ceramic elements. Strategic archetypes include upstream material controllers securing alumina supply chains, validation-heavy pharmaceutical specialists, and process engineering firms bundling installation with commissioning support. Capacity expansion and strategic partnerships represent the dominant competitive moves, with players securing furnace investment and cross-licensing ceramic formulation expertise.
Among Germany-based fabricators, Sartorius AG exemplifies the pharmaceutical-grade specialist archetype through stringent quality protocols. Koch Membrane Systems occupies a position anchoring North American industrial accounts through polymer-ceramic hybrid expertise. CoorsTek, Inc. sits within the advanced materials tier, representing dominance in alumina formulations for high-temperature process streams.
| Leading Market Players |
|---|
| Nanostone |
| Sartorius AG |
| Koch Membrane Systems |
| Microdyn-Nadir |
| QUA Group LLC |
| CoorsTek, Inc. |
| TAMI Industries |
| Media and Process Technology Inc. |
| Atech Innovations GmbH |
| Others |
Supply & Pricing Matrix
Captive in-house fabrication among OEMs anchors both supply security and pricing power, as pharmaceutical and chemical end-users internalize module production to escape procurement volatility in high-purity alumina markets. This integration choice concentrates cost control with buyers while compressing margins for standalone membrane fabricators competing on validation documentation and furnace capacity.
Pricing Analysis
Service unbundling separates membrane module supply from installation and validation support, with water treatment integrators sourcing bare ceramic elements directly from fabricators while retaining commissioning expertise. Three-tier pricing structure across premium, standard, and economy levels reflects FDA validation tier, volume scale, and after-sales bundling intensity. Cost compression in standard-tier microfiltration runs through municipal procurement consolidation. Pharmaceutical sterile filtration buyers exhibit least price sensitivity due to qualification timeline risks.
Supply Chain Analysis
Advanced alumina formulation rests on specialized feedstock chains concentrated in Germany, the United States, and Japan. High-purity alumina, titania, and zirconia precursors draw from limited sintering-grade producers. Single-source vulnerability in pharmaceutical-grade alumina supply creates exposure to export licensing shifts. Distribution runs through direct OEM relationships for industrial accounts and water treatment integrators for municipal procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Sintering furnace capacity scarcity props pricing across all tiers, as qualified ceramic engineering talent concentrates outside established industrial ceramics regions and extends equipment lead times.
For Market Incumbents: Hedge against polymeric-ceramic hybrid disruption by securing long-term alumina offtake agreements with German and Japanese specialty chemical producers. Add sintering capacity in the United States to anchor EPA-mandated industrial accounts facing compressed procurement timelines. Certification investment in CDSCO-aligned protocols captures Indian pharmaceutical contract manufacturing expansion. For New Entrants and Emerging Players: Digital-channel validation support packages offer entry into United States municipal water utilities seeking compressed capital expenditure timelines. White-space concentration sits with membrane bioreactor integration design for German chemical plant wastewater. Pilot-scale testing partnerships with research institutes build qualification documentation without furnace capital intensity. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by industrial ceramics conglomerates seeking membrane fabrication capabilities. Long-term viability favors fabricators with documented pharmaceutical-grade protocols and captive alumina supply relationships. Watch EPA PFAS treatment regulation advancement as inflection trigger for thermal stability positioning.| Strategic Initiative | Industry Significance |
|---|---|
| Captive In-House Fabrication | OEMs internalize module production to secure supply continuity against alumina procurement volatility. |
| Membrane Bioreactor Integration | German engineering firms couple biological degradation with ceramic structural integrity for chemical effluent. |
| Pharmaceutical Validation Investment | FDA process documentation hardens qualification barriers against polymeric alternatives in sterile filtration. |
| Alumina Supply Agreement | Long-term offtake with high-purity producers mitigates single-source vulnerability in sintering-grade feedstock. |
| PFAS Treatment Positioning | Thermal stability enables ceramic membranes to concentrate perfluorinated compounds for destruction processes. |
Research Methodology
Independent corroboration across membrane fabrication executives, pharmaceutical procurement directors, chemical plant engineers, and water treatment integrators underwrites the qualitative findings. Primary interviews with ceramic engineering specialists and secondary validation through EPA effluent guideline documents, FDA validation protocol filings, and REACH compliance records establish demand-side ground truth. Bottom-up module shipment analysis triangulates against top-down industrial ceramics market sizing.
Rate-of-change decomposition across product type, application intensity, end-user procurement archetype, and regional regulatory framework generates segment-level trajectories over the projection horizon. CAGRs derive from installed base replacement cycles, regulatory mandate effective dates, and capacity expansion announcements. Forecast inputs incorporate sintering furnace utilization rates and pharmaceutical sterile filtration qualification pipeline status.
The model holds under stable alumina supply conditions and continued EPA effluent enforcement; deviation in export licensing for high-purity ceramics or PFAS regulatory acceleration would shift demand trajectories. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ceramics & Fibers
Synthetic Quartz Market
Ceramics & Fibers
Global Fireclay Tiles Market
Ceramics & Fibers
Ceramic Matrix Composites Market
Ceramics & Fibers
Feldspar Market
Ceramics & Fibers
Brown Fused Alumina Market
Ceramics & Fibers
Fluorite Pellets Market
Ceramics & Fibers
Global Zircon Sand Market
Ceramics & Fibers
Fly Ash Microspheres Market
Ceramics & Fibers
Silicon Carbide Fiber Market
Ceramics & Fibers
Zabuyelite Market
Ceramics & Fibers
Rutile Market
Ceramics & Fibers
Melamine Pyrophosphate Market
Ceramics & Fibers
Global Ceramic Fiber Paper Market
Ceramics & Fibers
Global Rice Husk Ash Market