
 Fluorite Pellets Market | 2026-2036
Fluorite Pellets Market Size, Share, and Industry Trends Forecast 2026-2036
Fluorite Pellets Market Analysis
Metallurgical-grade pellet specifications is unwinding legacy acid-grade dominance across the fluorite supply base. Yingda Mining (Ningbo) Co., Ltd leverages integrated mine-to-pellet operations to control CaF₂ consistency for steel flux buyers. Zhengzhou Zhongzhou Briquette Machinery Plant anchors equipment-linked supply contracts across central Chinese metallurgy corridors. SR Group competes on ceramic-grade specialization, diverging from commodity flux positioning.
Fluorite pellets are compressed or briquetted agglomerates of calcium fluoride (CaF₂) concentrate, typically bound with organic or inorganic additives and sized between 10 and 50 millimeters for controlled dissolution in high-temperature processes; they serve as engineered fluxing media to lower slag melting points, improve metal fluidity, and stabilize refractory interactions in pyrometallurgical operations. Industrial-grade pellets command volume leadership through steelmill procurement scale, while optics-grade formulations concentrate margin pools due to stringent purity thresholds and limited qualified supply. Ceramic-grade demand tracks specialty glass expansion, with polishing applications expanding fastest among application categories as precision manufacturing tolerances tighten across electronics substrates.
China's SAMR enforces GB standards on industrial mineral purity and briquette mechanical strength, directly qualifying pellet suppliers for domestic metallurgy tenders. REACH registration requirements in Europe restrict fluorine compound imports lacking full substance dossiers, reshaping export-oriented pellet certification strategies. India's BIS certification for refractory-grade minerals creates parallel compliance pathways for cross-border suppliers. Buyers must monitor regulatory divergence between mineral-content rules and carbon-border adjustment mechanisms to secure long-term contract viability.
Market Dynamics
Blast furnace efficiency mandates across Asian steel corridors are compressing demand for raw lump fluorite in favor of engineered pellet formats with controlled dissolution profiles and lower dust emissions during charging.
Growth Catalysts
- GB Standard 2024 Revisions:China's SAMR tightened mechanical strength and fluorine purity thresholds for industrial mineral briquettes, directly qualifying pellet suppliers for state-backed metallurgy tenders.
- Integrated Steel Mill Expansion:POSCO and Tata Steel are expanding pelletized flux consumption to reduce slag viscosity variability and improve hot metal yields in high-volume oxygen blast furnaces.
- Carbon Border Adjustment Mechanisms:The EU's CBAM is forcing export-oriented Chinese pellet producers to document embedded emissions, accelerating cleaner briquetting process investments.
Market Restraints
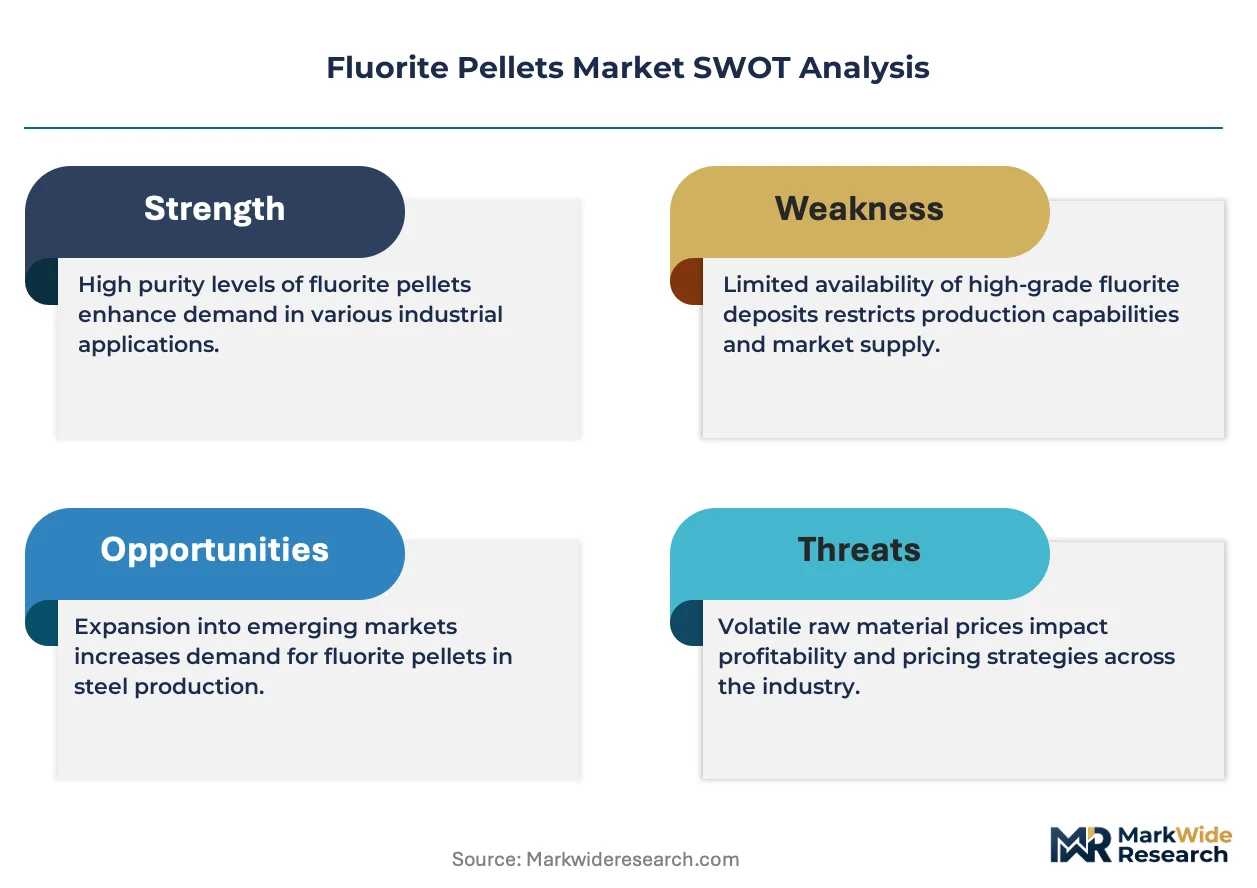
- Acid-Grade Concentrate Price Volatility:Metallurgical pellet margins compress when 97% CaF₂ acid-grade feedstock prices spike, as pellet producers lack pricing power to pass through input cost swings.
- Mongolian Supply Concentration:Over 60% of high-grade fluorite concentrate for Asian pelletizing originates from Mongolian open-pit operations, creating geopolitical transit risk through Chinese border crossings.
- Synthetic Cryolite Substitution:Aluminum smelters are reducing metallurgical-grade fluorite pellet offtake as synthetic cryolite from fluosilicic acid waste streams achieves cost parity in bath chemistry applications.
Strategic Opportunities
- Indian Refractory Corridor Penetration:BIS certification pathways for refractory-grade minerals create first-mover advantages for pellet suppliers establishing tolling partnerships with Bhilai and Rourkela steel complexes.
- Optics-Grade Formulation White Space:Semiconductor lithography equipment manufacturers require 99.9%+ CaF₂ pellets with sub-50ppm rare earth contamination, a specification only two qualified suppliers currently meet.
- Direct Reduced Iron (DRI) Integration:Hydrogen-based DRI shaft furnaces in Sweden and Germany need low-silica pellet fluxes, opening premium positioning for ultra-pure fluorite agglomerates.
Industry Challenges
- REACH Dossier Compilation Timelines:European pellet importers face 18-24 month substance registration delays with ECHA, freezing contract renewals until full fluorine compound toxicology packages are submitted.
- Refractory Compatibility Testing Burden:Each new pellet formulation requires 6-12 month cupola and blast furnace lining interaction studies, straining R&D budgets at mid-cap producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fluorite Pellets Market |
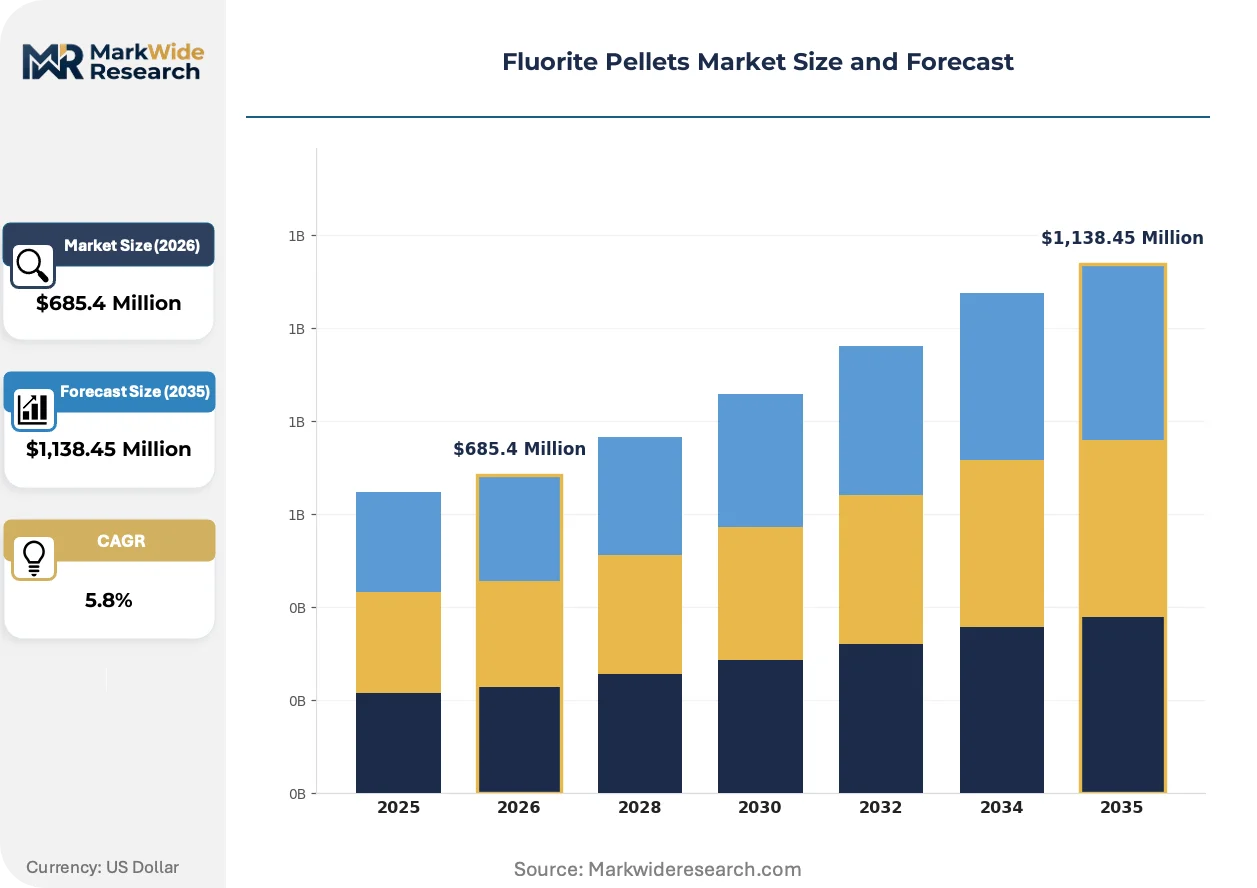
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,138.45 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Industrial Grade, Metallurgical Grade, Ceramic Grade, Optics Grade End User: Ceramics, Metallurgy, Chemical Processing, Glass Manufacturing Application: Fluxing Agent, Glass Production, In metallurgy, Polishing Distribution Channel: Direct Sales, Online Sales, Distributors, Retailers |
| Companies Covered | Yingda Mining (Ningbo) Co., Ltd, Zhengzhou Zhongzhou Briquette Machinery Plant, SR Group, Shree Bajrang Sales Ltd., Zhengzhou Dayang Briquette Machinery Co.,Ltd, MaxTon Industrial Co., Ltd., Shree Ram Lime Products Pvt, Reverso Technologies Inc., ZY mining, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fluorite Pellets Market Emerging Trajectories
Engineered dissolution control and emissions compliance are reshaping pellet formulation priorities, with producers investing in binder chemistry and size distribution optimization to meet tightening pyrometallurgical process specifications.
Cold briquetting with organic starch binders is displacing traditional sintered pellet routes in Chinese metallurgy corridors. Mid-sized steel mills in Hebei and Shandong provinces are adopting starch-bound pellets to eliminate the 120-150°C thermal curing stage and cut natural gas consumption. This shift is displacing capital-intensive rotary kiln investments among second-tier pellet suppliers who cannot amortize sintering equipment at current scale.
REACH Annex XVII restrictions on per- and polyfluoroalkyl substances are forcing fluorite pellet exporters to reformulate process water treatment and dust suppression chemistries. ECHA's 2023 restriction proposal on PFAS in industrial applications has triggered supply chain audits across German and Dutch steel procurement offices. Pellet producers are responding by substituting fluorine-free surfactants in pellet curing and packaging operations.
Steel mill technical buyers are consolidating supplier panels and demanding pellet performance guarantees tied to slag chemistry outcomes rather than simple CaF₂ content. Japanese integrated mills through JIS procurement frameworks now specify pellet dissolution rates at 1450°C as primary acceptance criteria. This specification compression is most visible in South Korean POSCO and Hyundai Steel contracts, where three-year sole-source agreements replace annual spot purchasing.
Fluorite Pellets Market Segmentation
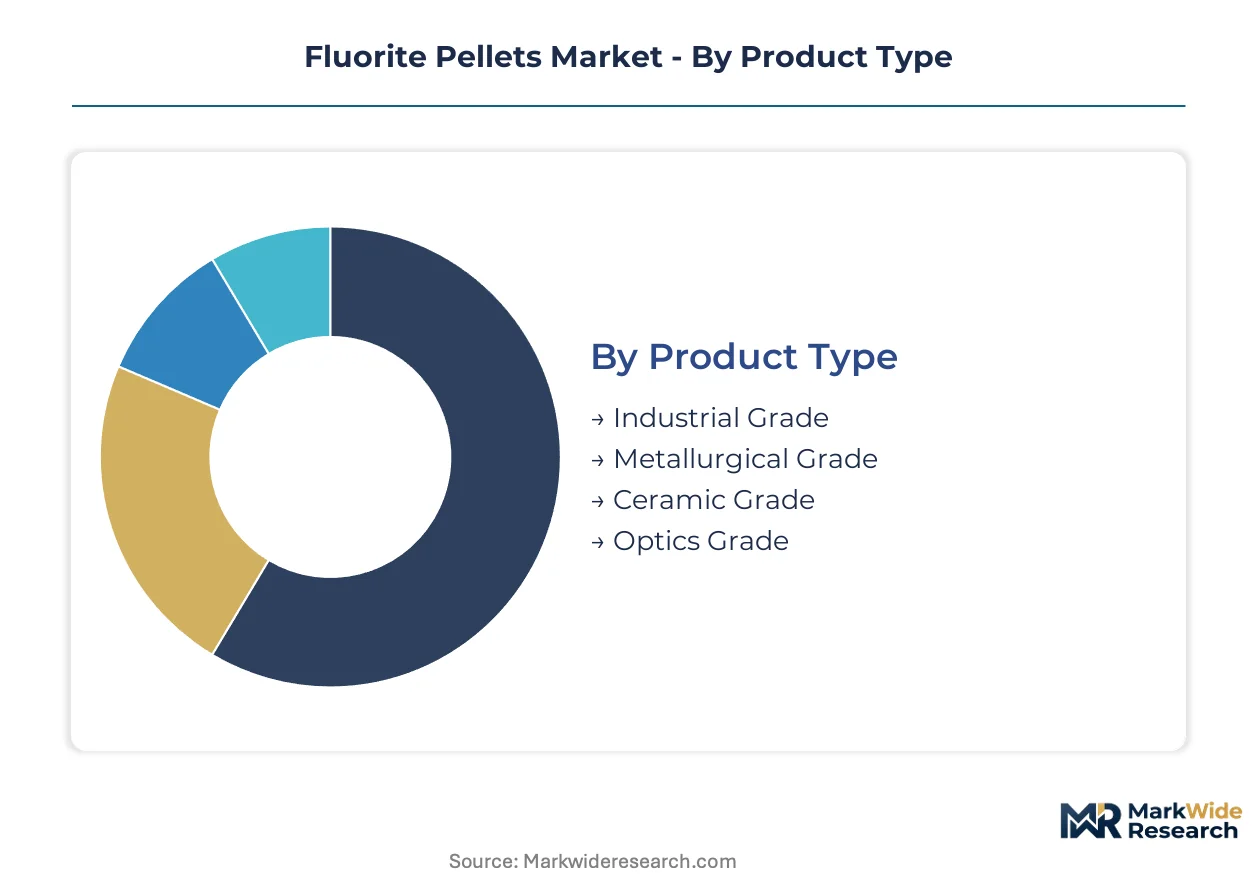
Segmentation in fluorite pellets reveals how formulation chemistry and procurement channels split across divergent technical requirements. Buyers in steelmaking prioritize dissolution control and mechanical strength, while optics and ceramic segments demand purity thresholds that reshape supplier qualification criteria entirely.
Product Type:
Domestic Chinese steel mills absorb metallurgical and industrial grades through mine-adjacent supply chains, whereas optics-grade pellets travel through specialized export channels to semiconductor equipment manufacturers in Japan, South Korea, and Germany.
- Industrial Grade:These pellets carry 75-85% CaF₂ content with higher silica tolerance, bound with bentonite or cementitious additives for bulk metallurgical applications. Chinese provincial steel clusters in Hebei and Shandong dominate procurement volumes, driven by GB standard compliance mandates for blast furnace flux consistency.
- Metallurgical Grade:Engineered for 90-97% CaF₂ purity with controlled dissolution rates at 1400-1500°C, these formulations serve integrated steel mills requiring slag fluidity management. POSCO and Tata Steel procurement offices specify pellet size distributions and compressive strength thresholds that filter supplier pools.
- Ceramic Grade:Higher purity thresholds with controlled iron and sulfur content support specialty glass and enamel production.
- Optics Grade:99.9%+ CaF₂ specifications with sub-50ppm rare earth contamination serve lithography equipment manufacturers.
Industrial grade commands the established base. The steepest expansion runs through optics grade.
End User:
Cost tier differentiation separates commodity flux buyers from premium formulation purchasers, with metallurgy and ceramics occupying opposite ends of the pricing spectrum.
- Metallurgy:Oxygen blast furnaces and electric arc operations consume pelletized flux to lower slag melting points and stabilize hot metal chemistry. Chinese, Indian, and South Korean integrated mills are expanding pelletized flux consumption as efficiency standards tighten and dust emissions during charging face regulatory pressure.
- Ceramics:Specialty enamel and advanced ceramic manufacturers require low-iron formulations with precise particle size distribution. Japanese and German ceramic producers drive specification refinement through JIS and DIN procurement frameworks that emphasize batch-to-batch consistency.
- Chemical Processing:Hydrofluoric acid precursor applications demand acid-grade feedstock conversion.
- Glass Manufacturing:Optical and specialty glass producers use ceramic-grade pellets for melting acceleration.
Metallurgy anchors volume concentration. Ceramics delivers the strongest margin expansion trajectory.
Application:
Application segmentation tracks how pellets dissolve and interact across pyrometallurgical temperature regimes, from steel bath chemistry to precision polishing.
- Fluxing Agent:The dominant application employs pellets as engineered slag conditioners in iron and steelmaking, where controlled calcium fluoride release reduces viscosity and improves sulfur removal. Blast furnace operators in Asia-Pacific specify dissolution rates and mechanical strength as primary acceptance criteria rather than simple CaF₂ percentage.
- Polishing:Precision manufacturing of semiconductor substrates and optical components drives demand for ultra-fine fluorite abrasives. Electronics manufacturing clusters in Taiwan, South Korea, and Japan are tightening tolerances on substrate flatness, expanding consumption of high-purity pellet-derived polishing compounds.
- Glass Production:Melting acceleration and color control in specialty glass batches.
- In Metallurgy:Direct injection and ladle metallurgy applications for sulfur control.
Fluxing agent retains the volume base. Polishing applications are climbing the fastest.
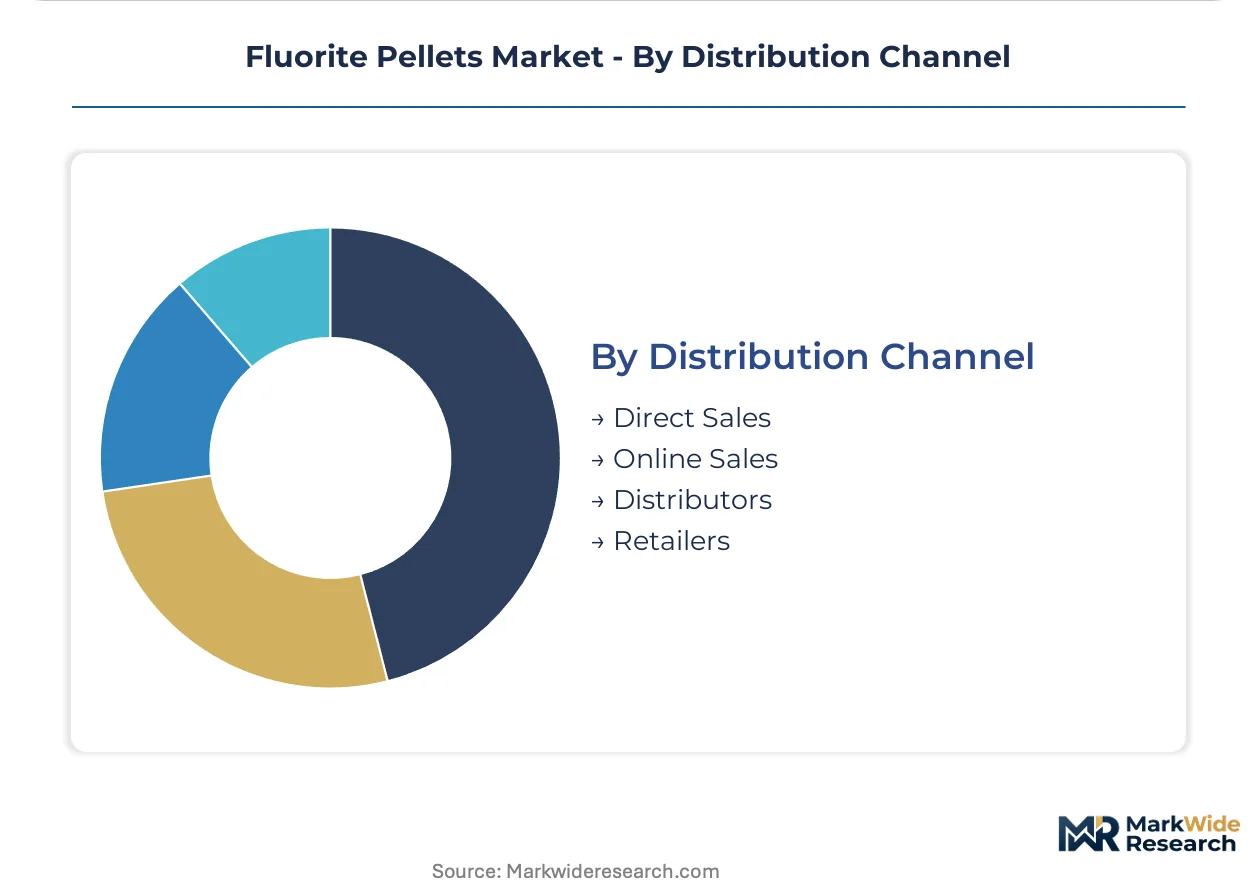
Distribution Channel:
Channel structure reflects customer scale and technical service requirements, with direct relationships dominating high-volume steel procurement and intermediaries serving fragmented ceramic and chemical buyers.
- Direct Sales:Integrated steel mills and major ceramic manufacturers negotiate multi-year pellet supply agreements with performance guarantees tied to slag chemistry outcomes. POSCO, Hyundai Steel, and Tata Steel procurement frameworks specify dissolution rates and technical service support that mandate direct supplier relationships.
- Distributors:Regional mineral traders and industrial chemical distributors aggregate demand from mid-sized ceramic producers and chemical processors. Indian refractory corridors and Southeast Asian glass manufacturing clusters rely on distributor networks for smaller lot sizes and technical consultation.
- Online Sales:Limited to standardized industrial-grade specifications and sample procurement.
- Retailers:Minimal presence confined to laboratory and research-scale quantities.
Direct sales lock in the core volume base. Distributor channels are gaining share fastest among mid-cap ceramic and chemical processors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in fluorite pellets track metallurgical demand corridors and regulatory divergence across major steel-producing economies. Trade balances shift as domestic pellet capacity expands in consuming markets while concentrate sourcing concentrates in mineral-rich border regions.
China
Hebei and Shandong steel clusters drive pellet consumption as GB standards tighten mechanical strength requirements for blast furnace flux. SAMR enforcement of 2024 briquette purity thresholds qualifies domestic suppliers for state procurement tenders. Mongolian concentrate crosses through Inner Mongolian border ports to feed pelletizing operations in Ningbo and Zhengzhou industrial zones.
India
Bhilai and Rourkela integrated steel complexes expand pelletized flux trials to reduce slag viscosity variability in oxygen blast furnaces. BIS certification for refractory-grade minerals creates compliance pathways for cross-border pellet suppliers. Distributor networks in Maharashtra and Gujarat aggregate demand from mid-sized ceramic processors seeking smaller lot technical consultation.
South Korea
POSCO procurement frameworks specify pellet dissolution rates at 1450°C as primary acceptance criteria for three-year sole-source agreements. MFDS alignment with international mineral purity standards streamlines import qualification for Chinese pellet exporters. Pohang and Gwangyang steel complexes anchor regional pellet consumption as dust emission regulations tighten charging protocols.
Germany
ThyssenKrupp and Salzgitter procurement offices demand REACH-compliant pellet dossiers for fluorine compound imports. ECHA registration timelines of 18-24 months freeze contract renewals until full toxicology packages are submitted. Ruhr industrial corridor steel mills pilot hydrogen-based DRI shaft furnaces requiring low-silica pellet fluxes from qualified suppliers.
Japan
JIS procurement frameworks through Nippon Steel and JFE Holdings emphasize batch-to-batch consistency in pellet slag chemistry outcomes. METI carbon neutrality targets accelerate cleaner briquetting process investments among import partners. Chiba and Kawasaki steel mill technical buyers consolidate supplier panels around performance guarantees rather than simple CaF₂ content metrics.
Fluorite Pellets Market Vendor Landscape
Listed leaders compete with private specialists across equipment-linked supply contracts and mine-to-pellet integration depth. The vendor base organizes around three strategic tiers: integrated mining-pelletizing operators controlling concentrate feedstock, machinery fabricators anchoring equipment-linked supply agreements, and specialty grade formulators serving optics and ceramic niches. Dominant competitive moves include backward integration into concentrate sourcing and geographic expansion through tolling partnerships with steel mill complexes.
Within the integrated operator tier, Yingda Mining (Ningbo) Co., Ltd and SR Group exemplify divergent positioning strategies. Among Chinese machinery-linked fabricators, Zhengzhou Zhongzhou Briquette Machinery Plant and Zhengzhou Dayang Briquette Machinery Co.,Ltd occupy positions anchored to central Chinese metallurgy corridors. These named entities represent archetypal competitive approaches rather than exhaustive market coverage, with private specialists and limited liability structures dominating the mid-cap supplier pool.
| Leading Market Players |
|---|
| Yingda Mining (Ningbo) Co., Ltd |
| Zhengzhou Zhongzhou Briquette Machinery Plant |
| SR Group |
| Shree Bajrang Sales Ltd. |
| Zhengzhou Dayang Briquette Machinery Co.,Ltd |
| MaxTon Industrial Co., Ltd. |
| Shree Ram Lime Products Pvt |
| Reverso Technologies Inc. |
| ZY mining |
| Others |
Supply Flow & Price Mechanics
Long-term offtake contracts between Mongolian concentrate suppliers and Chinese pellet producers lock in both feedstock access and cost visibility for metallurgical-grade formulations, insulating integrated operators from acid-grade price spikes while exposing toll-dependent processors to margin compression when spot concentrate markets tighten.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures across Chinese and South Korean steel corridors. Three-tier pricing stratifies across metallurgical, ceramic, and optics grades, with purity thresholds and dissolution rate guarantees as primary differentiation drivers. Cost compression in metallurgical tiers is intensifying as acid-grade concentrate feedstock volatility transfers downstream. Mid-sized ceramic processors exhibit highest price sensitivity; semiconductor lithography equipment manufacturers show least.
Supply Chain Analysis
Ganqimaodu border crossing chokepoints underwrite transit risk for over sixty percent of Asian pelletizing feedstock. Concentrate sourcing draws from Mongolian open-pit operations, Chinese domestic mines, and Mexican acid-grade refiners. Pellet production rests on fluorspar concentrate, organic starch binders, and bentonite additives. Single-source vulnerability concentrates in Mongolian transit corridors. Distribution runs through direct sales to integrated steel mills and regional mineral traders serving fragmented ceramic buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fluorite pellets sit in early-cycle expansion as hydrogen-based DRI shaft furnace adoption in Europe creates premium demand for ultra-pure flux formulations.
For Market Incumbents: Shield metallurgical-grade margins through backward integration into Mongolian concentrate offtake and captive briquetting capacity in Hebei industrial zones. Synthetic cryolite substitution in aluminum smelters threatens legacy flux volumes; optics-grade certification investment opens semiconductor equipment procurement channels. For New Entrants and Emerging Players: Lead with tolling partnerships at Bhilai and Rourkela steel complexes to penetrate India's BIS-certified refractory corridor. Indian refractory-grade mineral compliance creates the most penetrable white space. Direct technical service teams to steel mill slag chemistry optimization delivers differentiated positioning against commodity traders. For Investors and Strategic Acquirers: Capital is best deployed toward integrated mine-to-pellet operators with captive concentrate supply and existing SAMR qualification for Chinese state tenders. Long-term viability favors upstream-controlled structures over toll-dependent processors. Watch hydrogen-based DRI furnace commissioning announcements in Sweden and Germany as inflection signals for premium pellet demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Concentrate Supply | Mongolian offtake agreements secure feedstock access for SAMR-qualified pellet producers. |
| Optics-Grade Certification Investment | Sub-50ppm rare earth contamination thresholds unlock semiconductor lithography equipment procurement. |
| Tolling Partnership with Steel Complexes | Bhilai and Rourkela integrations bypass distributor channels for direct mill relationships. |
| REACH Dossier Compilation | ECHA registration completion unfreezes contract renewals for European steel mill supply. |
| Starch Binder Process Transition | Cold briquetting eliminates thermal curing stages and cuts natural gas consumption for Hebei mills. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted across primary interview programs with steel mill procurement officers, pellet plant technical directors, refractory-grade mineral traders, and ECHA registration consultants. Secondary validation drew from SAMR GB standard filings, Indian BIS certification records, Mongolian customs transit data, and integrated steel mill technical specifications. Bottom-up volume modeling and top-down market sizing were triangulated against producer capacity disclosures.
Across the analysis window, forecasts segment by grade tier, end-use industry, and regional regulatory cluster. CAGRs were derived from production capacity expansion trajectories and steel mill flux intensity ratios. Hydrogen-based DRI furnace adoption curves and REACH registration completion timelines served as industry-specific forecast inputs.
The analysis sits within stated boundaries; outcomes outside sustained Mongolian border transit stability and acid-grade concentrate price regimes would require recalibration. Forecasts reflect documented assumptions on steel production intensity and regulatory compliance timelines. Practitioners should keep alternative scenarios live as EU CBAM documentation requirements and synthetic cryolite cost parity evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ceramics & Fibers
Global Fireclay Tiles Market
Ceramics & Fibers
Rutile Market
Ceramics & Fibers
Brown Fused Alumina Market
Ceramics & Fibers
Global Ceramic Fiber Paper Market
Ceramics & Fibers
Zabuyelite Market
Ceramics & Fibers
Fly Ash Microspheres Market
Ceramics & Fibers
Global Rice Husk Ash Market
Ceramics & Fibers
Silicon Carbide Fiber Market
Ceramics & Fibers
Melamine Pyrophosphate Market
Ceramics & Fibers
Global Zircon Sand Market
Ceramics & Fibers
Hollow Fiber Ceramic Membrane Market
Ceramics & Fibers
Synthetic Quartz Market
Ceramics & Fibers
Ceramic Matrix Composites Market
Ceramics & Fibers
Feldspar Market