
 Global Anaerobic Digestion Market | 2026-2036
Global Anaerobic Digestion Market Size, Share, and Industry Trends Forecast 2026-2036
Global Anaerobic Digestion Market Analysis
Modular plug-flow reactor designs are reshaping how anaerobic digestion plants are deployed across distributed agricultural and municipal waste streams. EnviTec Biogas AG leverages its standardized containerized systems to reduce on-site construction timelines for European farm operators. WELTEC BIOPOWER GmbH anchors its position through integrated stainless-steel digester manufacturing that controls quality from raw steel to final weld inspection. Clarke Energy competes by specializing in gas-engine genset integration, converting raw biogas into grid-synchronized electricity with minimal methane slip.
Anaerobic digestion is the biological decomposition of organic matter in oxygen-free environments, typically operating at mesophilic temperatures between 35°C and 42°C with hydraulic retention times of 15 to 30 days to produce biogas rich in methane and carbon dioxide. Continuous reactor technology dominates commercial installations due to predictable throughput and automated feeding systems that minimize labor intensity. Agricultural residues represent the largest feedstock volume globally, though food waste streams are expanding fastest as municipalities implement source-separated collection mandates that redirect organic fractions from landfills. Energy generation captures the majority of revenue value through combined heat and power output, while organic fertilizer production offers margin expansion where digestate certification unlocks premium agricultural markets.
The EU Green Deal and F-Gas Regulation shape project economics by penalizing methane venting and rewarding verified carbon-negative outputs through national renewable gas certificates. EPA biogas capture incentives in the United States and China's MEE enforcement of agricultural pollution discharge standards are pulling capital toward compliant digester infrastructure in both markets. Stakeholders must track evolving digestate contamination thresholds and biomethane grid injection specifications, as these standards will determine which facility configurations retain long-term offtake access.
Market Dynamics
Modular reactor standardization is compressing project development cycles from years to months, forcing capital-light deployment models across agricultural and municipal waste streams.
Growth Catalysts
- EU Green Deal methane penalties:Livestock operators in Denmark and Germany face tightening emission caps that make on-farm digesters economically unavoidable rather than optional sustainability investments.
- Food waste diversion mandates:Municipal source-separated collection laws in California, France, and South Korea redirect organic fractions from landfills toward centralized anaerobic digestion facilities.
- District heating network integration:Danish farm-based digester clusters secure offtake certainty through long-term thermal contracts with municipal utilities.
Market Restraints
- Feedstock supply volatility:Agricultural residue availability fluctuates with seasonal harvest patterns and weather disruption, destabilizing digester loading rates and biogas output predictability.
- Specialized stainless steel concentration:European fabricators dominate high-grade digester vessel manufacturing, exposing project developers to currency risk and extended lead times during demand surges.
- Grid injection specification fragmentation:Biomethane upgrading to pipeline quality faces divergent national standards for hydrogen sulfide limits, siloxane removal, and odorization requirements.
Strategic Opportunities
- Indonesia palm oil mill effluent:Untapped processing capacity across Sumatra and Kalimantan offers feedstock volumes exceeding European agricultural residues with minimal collection infrastructure.
- Power-to-gas electrolysis coupling:Excess renewable electricity converts to hydrogen for methanation with biogas carbon dioxide, producing grid-ready synthetic natural gas.
- US EPA Renewable Fuel Standard:Cellulosic biofuel credit values for biogas-derived compressed natural gas incentivize landfill and dairy digester project development.
Industry Challenges
- Digestate contamination thresholds:Emerging EU limits on microplastics and persistent organic pollutants in organic fertilizers threaten existing certification pathways and premium pricing.
- Process control expertise scarcity:Anaerobic microbiology specialists capable of optimizing volatile fatty acid balance and ammonia inhibition prevention remain concentrated in German and Danish technical institutes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Anaerobic Digestion Market |
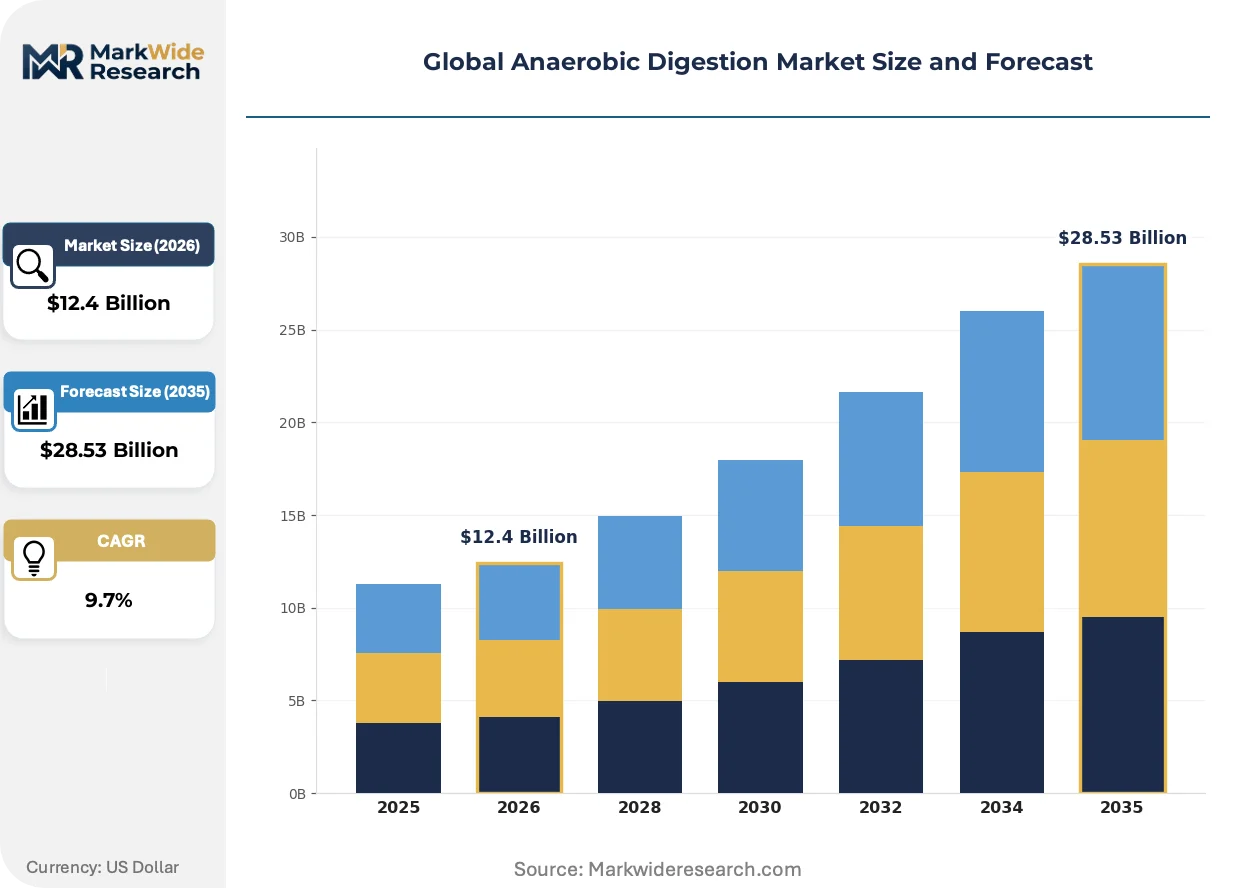
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $28.53 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology Type: Batch, Continuous, Semi-Continuous, Plug Flow Feedstock Type: Agricultural Residues, Food Waste, Wastewater Sludge, Industrial Waste Application Area: Energy Generation, Organic Fertilizer Production, Waste Management, Biogas Generation End User Sector: Agriculture, Municipalities, Industrial, Energy |
| Companies Covered | EnviTec Biogas AG, WELTEC BIOPOWER GmbH, Clarke Energy, Bioenergy DevCo, Anaergia Inc., Veolia Environnement, Xylem Inc., SUEZ, Schneider Electric, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Anaerobic Digestion Market Emerging Trajectories
Equipment miniaturization and digital process control are dissolving the traditional scale threshold for viable anaerobic digestion, enabling distributed deployment at volumes previously uneconomic.
Dry fermentation batch reactors are collapsing the minimum viable scale for agricultural biogas production. Swine and poultry operations with manure volumes below 5,000 tons annually now deploy containerized systems without liquid effluent management burdens. This technology is collapsing the capital barrier that previously restricted digester adoption to large dairy and crop farms.
The EU F-Gas Regulation phase-down of hydrofluorocarbon refrigerants is accelerating membrane and pressure-swing adsorption adoption for biogas upgrading. Equipment suppliers must certify alternative upgrading pathways that avoid high-global-warming-potential cooling systems. German and Dutch upgrading facilities are retrofitting existing amine scrubbers with water-based absorption to maintain compliance.
Aggregators are consolidating fragmented agricultural feedstock supply through long-term offtake contracts with multiple smallholder farms. Danish biogas cooperatives pool manure and crop residues from dozens of members into centralized digesters, replacing single-source supply risk with portfolio diversification. This procurement restructuring is most advanced in Jutland's farm-owned energy companies.
Global Anaerobic Digestion Market Segmentation
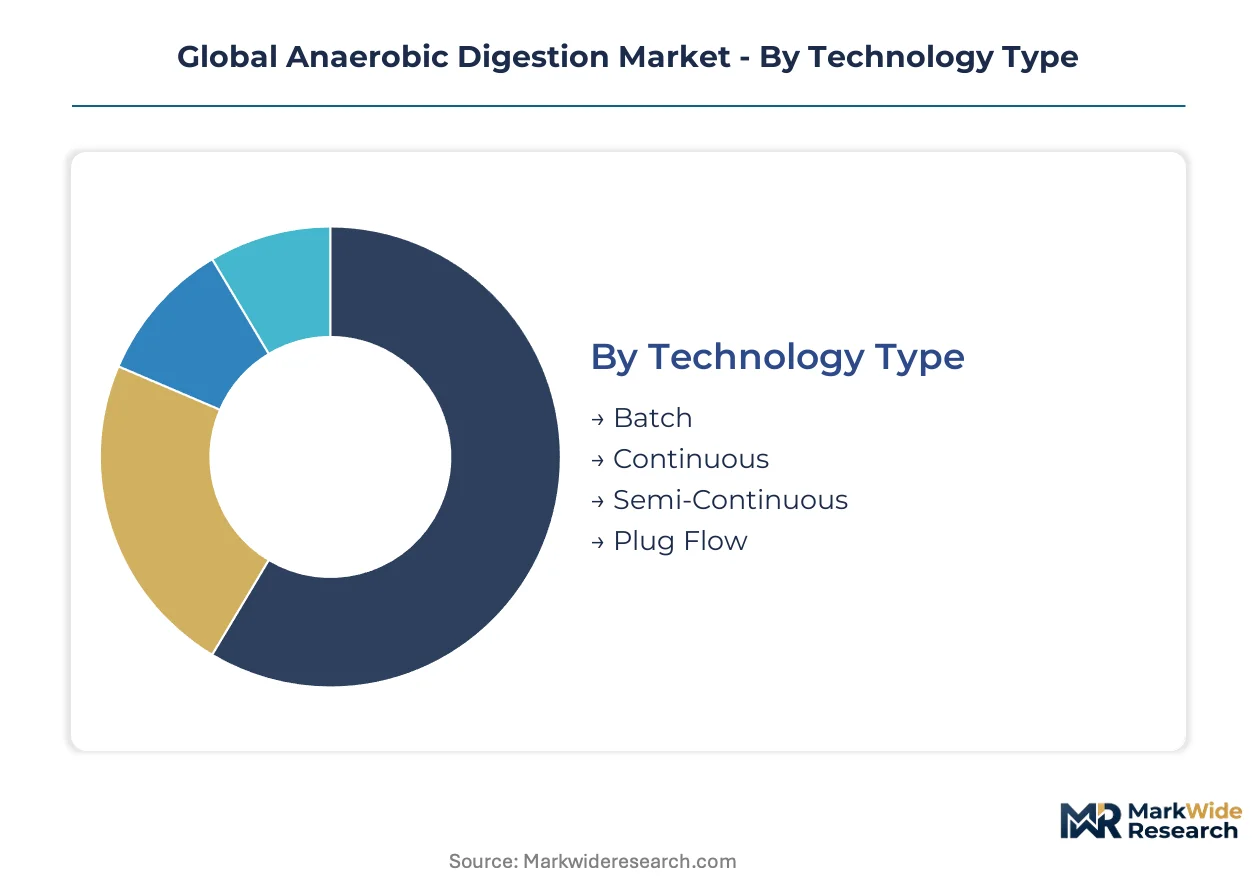
Segmentation reveals how reactor configuration, feedstock chemistry, and offtake economics partition capital allocation across the anaerobic digestion value chain. Cycle times vary dramatically: continuous systems operate perpetually while batch reactors demand weeks between loading cycles, and food waste streams turn over faster than lignocellulosic agricultural residues.
Technology Type:
Continuous systems compress hydraulic retention times to 15-30 days while batch configurations stretch cycles to 60-90 days, creating divergent working capital intensity across deployment models.
- Continuous:Automated feeding systems maintain steady-state microbial populations with minimal operator intervention. Danish farm clusters and German agricultural cooperatives concentrate procurement here, driven by labor scarcity and the EU Green Deal's methane penalty enforcement timeline.
- Plug Flow:Long, narrow reactor geometry handles high-solids feedstocks without mechanical mixing. US dairy operations in California and Wisconsin favor this configuration for manure streams above 10% total solids, leveraging EPA Renewable Fuel Standard credits for compressed natural gas offtake.
- Batch:Sealed vessels process discrete loads with complete digestion before unloading. Containerized deployments suit Indonesian palm oil mill effluent sites lacking continuous feedstock logistics.
- Semi-Continuous:Hybrid feeding schedules balance operational flexibility with throughput predictability. Municipal operators in France deploy this mode for variable food waste volumes under source-separated collection mandates.
Continuous systems anchor the volume base while Plug Flow gains share at the steepest rate.
Feedstock Type:
Collection infrastructure costs and contamination risk stratify procurement economics, with liquid streams commanding lower logistics spend per energy unit than solid residues requiring size reduction and pre-treatment.
- Agricultural Residues:Crop straw, manure, and silage deliver the largest aggregate tonnage globally. German biogas cooperatives in Lower Saxony and Bavaria concentrate demand here, securing long-term supply contracts with cereal farms facing EU Common Agricultural Policy sustainability conditionality.
- Food Waste:Source-separated municipal collections achieve higher methane yields per ton than mixed organic fractions. South Korea's Jeju Island and California's SB 1383 enforcement drive capacity expansion for centralized anaerobic digestion facilities processing supermarket and restaurant discards.
- Wastewater Sludge:Municipal treatment plants generate predictable, low-contamination streams. Chinese MEE enforcement of agricultural pollution discharge standards pulls capital toward compliant sludge-to-energy infrastructure in Jiangsu and Zhejiang provinces.
- Industrial Waste:Brewery effluent, dairy processing residues, and paper mill sludge offer concentrated organic loads. Brazilian sugarcane ethanol distilleries in São Paulo state deploy digesters for vinasse management under ANA water quality regulations.
Agricultural Residues dominate installed capacity while Food Waste climbs the fastest amid landfill diversion mandates.
Application Area:
Revenue capture mechanisms diverge sharply: energy sales require grid interconnection investment while fertilizer output demands certification compliance for premium agricultural markets.
- Energy Generation:Combined heat and power systems convert biogas to electricity and thermal output. Danish district heating networks in Aarhus and Copenhagen absorb steady biogas flows through 20-year municipal utility contracts.
- Biogas Generation:Raw gas production for on-site boiler fuel or vehicle fueling bypasses upgrading capital. German farm operators in Schleswig-Holstein deploy this mode for captive tractor fueling under national renewable gas certificate frameworks.
- Organic Fertilizer Production:Digestate processing into pelletized or liquid soil amendments. Dutch facilities in Gelderland pursue PAS 100 and EU organic regulation certification to access premium horticultural markets.
- Waste Management:Gate fee revenue from accepting organic waste streams. French operators around Paris leverage this model under extended producer responsibility packaging regulations.
Energy Generation commands the revenue base while Organic Fertilizer Production expands most quickly on digestate certification premiums.
End User Sector:
Capital access and regulatory exposure segment deployment risk, with municipal balance sheets tolerating longer payback periods than agricultural operators facing commodity price volatility.
- Agriculture:Farm-scale and cooperative digesters process on-farm residues and neighboring feedstocks. German livestock operators in North Rhine-Westphalia expand capacity as EU F-Gas Regulation and Green Deal methane penalties tighten.
- Municipalities:City-owned facilities handle residential food waste and wastewater sludge. California's CalRecycle grant programs accelerate deployment under SB 1383 organic waste reduction targets.
- Industrial:Food processors and beverage manufacturers manage high-strength effluent on-site. Indonesian palm oil mills in Riau province deploy covered lagoon systems for POME treatment under Ministry of Environment forestry sector compliance.
- Energy:Utility and independent power producers operate centralized biomethane upgrading facilities. Dutch grid operators in Groningen inject upgraded biogas into national transmission networks under Gasunitechnische Regeling specifications.
Agriculture anchors deployment volume while Municipalities gain share fastest on landfill diversion mandate enforcement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers cluster in agricultural cooperatives seeking methane compliance, municipal utilities pursuing landfill diversion mandates, and industrial processors managing high-strength effluent. Capital deployment concentrates where regulatory enforcement creates unavoidable compliance deadlines.
Germany
Livestock cooperatives in Lower Saxony and Bavaria expand digester capacity as EU F-Gas Regulation and Green Deal methane penalties tighten enforcement timelines. The national renewable gas certificate framework rewards verified carbon-negative outputs. Farm-based clusters around Oldenburg anchor biogas-to-biomethane upgrading infrastructure serving municipal utilities.
Denmark
Jutland's farm-owned energy companies pool manure and crop residues from dozens of member farms into centralized digesters. District heating networks in Aarhus and Copenhagen absorb steady biogas flows through twenty-year municipal utility contracts. The country's technical institutes concentrate process control expertise for volatile fatty acid optimization.
United States
California dairy operations deploy covered lagoon systems and plug-flow reactors under SB 1383 organic waste reduction mandates. EPA Renewable Fuel Standard cellulosic biofuel credits incentivize landfill and dairy digester project development. Wisconsin manure processors favor plug-flow configurations for high-solids streams above ten percent total solids.
China
Jiangsu and Zhejiang provinces direct capital toward compliant sludge-to-energy infrastructure as MEE enforces agricultural pollution discharge standards. Municipal treatment plants generate predictable, low-contamination wastewater sludge streams. Yangtze River Delta industrial zones process brewery effluent and dairy residues under tightening water quality regulations.
Indonesia
Palm oil mills in Riau province and across Sumatra deploy covered lagoon systems for POME treatment under Ministry of Environment forestry sector compliance. Untapped processing capacity offers feedstock volumes exceeding European agricultural residues. Batch reactor containerized systems suit sites lacking continuous feedstock logistics infrastructure.
Global Anaerobic Digestion Market Vendor Landscape
Channel-controlling players compete with product-specialist players across reactor fabrication, gas-engine integration, and upgrading equipment segments. The vendor base stratifies between integrated stainless-steel manufacturers and modular containerized system providers. Three archetypes dominate: captive digester fabricators with in-house steel production, gas-engine integrators specializing in grid synchronization, and waste management conglomerates leveraging gate fee revenue streams. Competitive moves concentrate on strategic partnerships with municipal utilities and technology licensing for regional deployment.
Among German fabricators, EnviTec Biogas AG and WELTEC BIOPOWER GmbH exemplify the integrated manufacturing archetype with captive quality control from raw material through final weld inspection. Clarke Energy occupies a position within the gas-engine integration specialist tier, converting raw biogas into grid-synchronized electricity. These three anchors represent divergent strategic positions: standardized containerization, vertical manufacturing control, and power generation specialization.
| Leading Market Players |
|---|
| EnviTec Biogas AG |
| WELTEC BIOPOWER GmbH |
| Clarke Energy |
| Bioenergy DevCo |
| Anaergia Inc. |
| Veolia Environnement |
| Xylem Inc. |
| SUEZ |
| Schneider Electric |
| Others |
Supply Flow & Price Mechanics
Stainless steel tariff exposure between Germany and East Asian fabricators determines both the premium spread for high-grade digester vessels and the geographic clustering of reactor manufacturing capacity. Project developers face compressed margins when currency volatility intersects with extended lead times for specialized vessel orders.
Pricing Analysis
Cost-plus contracts with stainless steel indexation dominate project procurement, linking final vessel pricing to LME nickel and ferrochrome benchmarks. Three-tier pricing structure across premium certified, standard compliant, and economy containerized systems separates buyers by digestate certification requirements and grid injection specifications. Cost compression in economy-tier modular systems is intensifying because Chinese fabricators are expanding automated welding capacity. Municipal utilities exhibit lowest price sensitivity due to long-term offtake mandates, while Indonesian palm oil mill operators face acute capital constraints.
Supply Chain Analysis
Tariff exposure between German stainless steel producers and Southeast Asian project developers dominates supply chain risk planning for reactor vessels. Manufacturing concentrates in Germany, Denmark, and the Netherlands for high-grade digester fabrication, drawing from specialized nickel-alloy plate, precision welding consumables, and membrane upgrading components. Single-source vulnerability persists for automated feeding system controllers sourced from Danish technical institutes. Distribution runs through EPC contractors with captive installation crews rather than open merchant channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market rewards regulatory entrenchment as a defensive moat. Operators with certified biomethane grid injection access and established digestate offtake contracts face prohibitively high switching costs for municipal utility customers.
For Market Incumbents: Pre-empt emerging membrane upgrading specialists by locking exclusive long-term service contracts with Danish and German district heating utilities. Anchor backward integration into stainless steel plate distribution to neutralize currency volatility on vessel procurement. Threat vector: Chinese containerized system exporters targeting Indonesian and Brazilian feedstock clusters with compressed delivery timelines. For New Entrants and Emerging Players: Establish a beachhead in Indonesian palm oil mill effluent processing through batch reactor containerized deployments bypassing continuous logistics infrastructure. Target California dairy operations seeking SB 1383 compliance with plug-flow reactor leasing models rather than capital sales. Go-to-market angle: digestate-as-a-service contracts bundling fertilizer certification with biogas output. For Investors and Strategic Acquirers: Gas-engine integration specialists with grid synchronization capabilities and established utility relationships represent the priority acquisition archetype. Long-term viability hinges on regulatory enforcement durability across EU Green Deal methane penalties and EPA Renewable Fuel Standard credit stability. Signal to watch: digestate microplastic threshold tightening in EU organic fertilizer regulations as inflection indicator for certification-premium sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| Biomethane Grid Injection Certification | Locks 20-year utility offtake contracts under Gasunitechnische Regeling and national renewable gas frameworks. |
| Digestate Premium Certification Investment | Unlocks PAS 100 and EU organic regulation access for Dutch and German horticultural markets. |
| Modular Containerized System Licensing | Accelerates deployment in Indonesian and Brazilian markets lacking continuous feedstock logistics. |
| Stainless Steel Backward Integration | Neutralizes currency risk and lead time volatility for German and Danish fabricators. |
| Power-to-Gas Electrolysis Coupling | Converts excess renewable electricity to synthetic natural gas for Dutch grid operators. |
Methodological Framework
Cross-validation between EPC contractor project databases and national renewable gas certificate registries anchors the qualitative findings in documented capacity deployment. Primary interviews with digester operators, utility procurement managers, and stainless steel vessel fabricators combined with secondary validation from EIA biogas statistics, IEA renewable energy reports, EPA Renewable Fuel Standard filings, and EU ETS emissions data. Bottom-up project aggregation and top-down regulatory mandate analysis triangulate market sizing.
Calibration against historical capacity additions and announced project pipelines shapes the analytical framework across the projection horizon. Segmentation dimensions include reactor configuration, feedstock chemistry, application area, and end-user sector, with regional regulatory enforcement timelines as an industry-specific overlay. CAGRs derive from fitted trend extrapolation moderated by policy implementation lag assumptions. Forecast inputs incorporate EU F-Gas Regulation phase-down schedules and MEE pollution discharge enforcement intensity.
Sensitivities concentrate around biomethane grid injection specification harmonization and digestate contamination threshold evolution. Forecasts reflect documented assumptions on regulatory enforcement durability and feedstock supply contract renewal rates. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Environmental Biotechnology
Plastic-Eating Bacteria Market
Environmental Biotechnology
North America Biosolids Market
Environmental Biotechnology
Global Bio Decontamination Market
Environmental Biotechnology
Blue Biotechnology Market
Environmental Biotechnology
Europe Anaerobic Digestion Market
Environmental Biotechnology
Bioremediation Market
Environmental Biotechnology
Enzymatic Cleaning Market
Environmental Biotechnology
Bio-Detection Market