
 Bio-Detection Market | 2026-2036
Bio-Detection Market Size, Share, and Industry Trends Forecast 2026-2036
Bio-Detection Market Analysis
Subscription-based assay panel services is repositioning how clinical laboratories consume bio-detection capabilities, shifting capital expenditure into recurring operational budgets. Abbott Laboratories leverages its installed base of diagnostic platforms to sustain high-margin consumable revenue streams. Thermo Fisher Scientific anchors North American supply chains through captive manufacturing of PCR reagents and thermal cyclers. Danaher Corporation differentiates via integrated workflow automation that reduces hands-on time in high-throughput screening environments.
Bio-detection encompasses analytical systems and consumables engineered to identify biological threat agents, pathogens, toxins, and genetically modified organisms through molecular recognition events, typically achieving detection limits in the picogram-per-milliliter range for protein targets and single-copy sensitivity for nucleic acid sequences. PCR Devices command the largest installed base among product types due to their entrenched role in infectious disease diagnostics, while Biosensors represent the fastest-expanding category as electrochemical and optical transducer platforms miniaturize for point-of-care deployment. Fluorescence technology leads in revenue contribution among technology segments, though Mass Spectrometry gains share in environmental monitoring applications requiring non-targeted compound identification.
FDA clearance pathways for in vitro diagnostic devices shape product development timelines and commercialization strategies for U.S.-focused manufacturers, while EPA methods such as those derived from the Clean Water Act framework mandate specific bio-detection protocols for environmental compliance monitoring. The EU In Vitro Diagnostic Regulation imposes new clinical evidence requirements that extend certification cycles for European market access. Stakeholders must evaluate how multiplexing capabilities align with evolving regulatory expectations for simultaneous pathogen detection claims.
Market Dynamics
CRISPR-enhanced nucleic acid amplification is compressing detection timelines from hours to minutes, forcing incumbent platform manufacturers to reengineer thermal cycling architectures or cede installed base to emerging biosensor architectures.
Growth Catalysts
- EU In Vitro Diagnostic Regulation:Extended certification cycles for European market access create first-mover advantages for manufacturers with pre-certified multiplex platforms. Laboratories accelerate procurement of compliant systems ahead of enforcement deadlines.
- Environmental compliance mandates:EPA methods derived from the Clean Water Act framework mandate specific bio-detection protocols for water utilities. Monitoring stations upgrade to nucleic acid-based systems to meet detection sensitivity requirements.
- Point-of-care miniaturization:Electrochemical transducer platforms achieve single-copy sensitivity in handheld formats. Field-deployable systems displace centralized laboratory workflows in remote screening applications.
Market Restraints
- Reagent supply concentration:PCR enzyme production concentrates among three captive suppliers in Germany and the United States. Disruptions propagate through downstream assay manufacturing within weeks.
- Fluorophore cost volatility:Rare earth elements in optical reporter molecules face extraction bottlenecks. Price swings compress margins for fluorescence-dependent platform operators.
- Technical ceiling in multiplexing:Current thermal cycler architectures face hard limits in simultaneous target detection beyond 20-plex configurations. Complex pathogen panels require sequential processing.
Strategic Opportunities
- India bio-surveillance infrastructure:CDSCO fast-track pathways for epidemic preparedness devices create regulatory tailwinds. Domestic manufacturing incentives under PLI schemes attract component localization.
- Wastewater epidemiology expansion:Sewer network monitoring for pathogen surveillance emerges as a municipal procurement category. Mass spectrometry platforms gain entry for non-targeted compound identification.
- Cloud-connected assay panels:Subscription telemetry services enable real-time outbreak mapping. Public health agencies in Brazil and South Korea pilot networked detection grids.
Industry Challenges
- Bioinformatics talent scarcity:Interpretation of multiplex nucleic acid outputs requires computational pathology expertise. Clinical laboratories compete with technology firms for pipeline development specialists.
- Legacy immunoassay integration:Hospital networks with sunk capital in ELISA workflows face workflow retraining costs. Parallel validation studies delay CRISPR platform adoption.
- ISO 15189 accreditation timelines:Molecular testing certification for clinical laboratories extends 12-18 months. Capacity expansion lags demand surges during outbreak events.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bio-Detection Market |
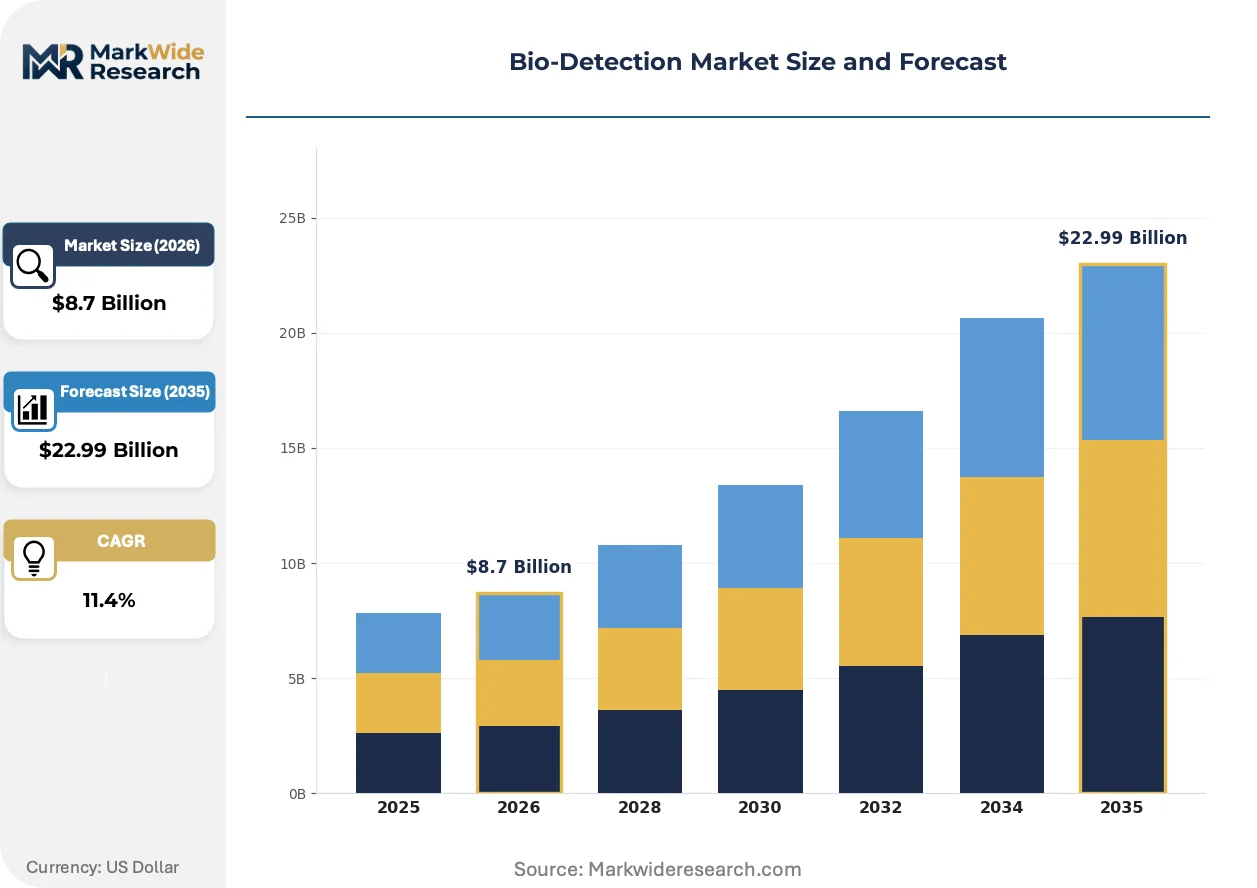
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Immunoassays, PCR Devices, Nucleic Acid Test Kits, Biosensors Technology: Mass Spectrometry, Microarray, Fluorescence, Enzymatic Reaction End User: Clinical Laboratories, Research Institutions, Food & Beverage Companies, Pharmaceutical Firms Application: Pathogen Detection, Environmental Monitoring, Food Safety Testing, Biodefense |
| Companies Covered | Abbott Laboratories, Agilent Technologies, Thermo Fisher Scientific, PerkinElmer, Merck KGaA, Danaher Corporation, Becton, Dickinson and Company, Bio-Rad Laboratories, Roche Holding AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bio-Detection Market Emerging Trajectories
Workflow automation and cloud-native assay interpretation are compressing the gap between sample collection and actionable intelligence, reshaping how defense, clinical, and environmental operators consume biological threat detection capabilities.
Digital microfluidics is automating droplet manipulation for PCR preparation, eliminating manual pipetting error in high-throughput screening environments. Reference laboratories in the United States and Germany are retrofitting existing thermal cycler bays with cartridge-based sample prep modules. The technology is automating labor cost structures that previously constrained 24/7 outbreak monitoring operations.
REACH restrictions on per- and polyfluoroalkyl substances are forcing reagent manufacturers to reformulate hydrophobic surface coatings used in microfluidic cartridges. European suppliers face 18-month substitution timelines for fluoropolymer alternatives. Clinical diagnostic platforms with EU market exposure are accelerating validation of silicone-based surface treatments to maintain certification continuity.
Consolidated procurement by integrated delivery networks is displacing individual laboratory purchasing autonomy in the United States. Hospital systems negotiate enterprise-wide assay panel subscriptions that bundle instrumentation, consumables, and cloud analytics. The Southwest and Southeast regions show earliest concentration of this buying-pattern shift among multi-facility health systems.
Bio-Detection Market Segmentation
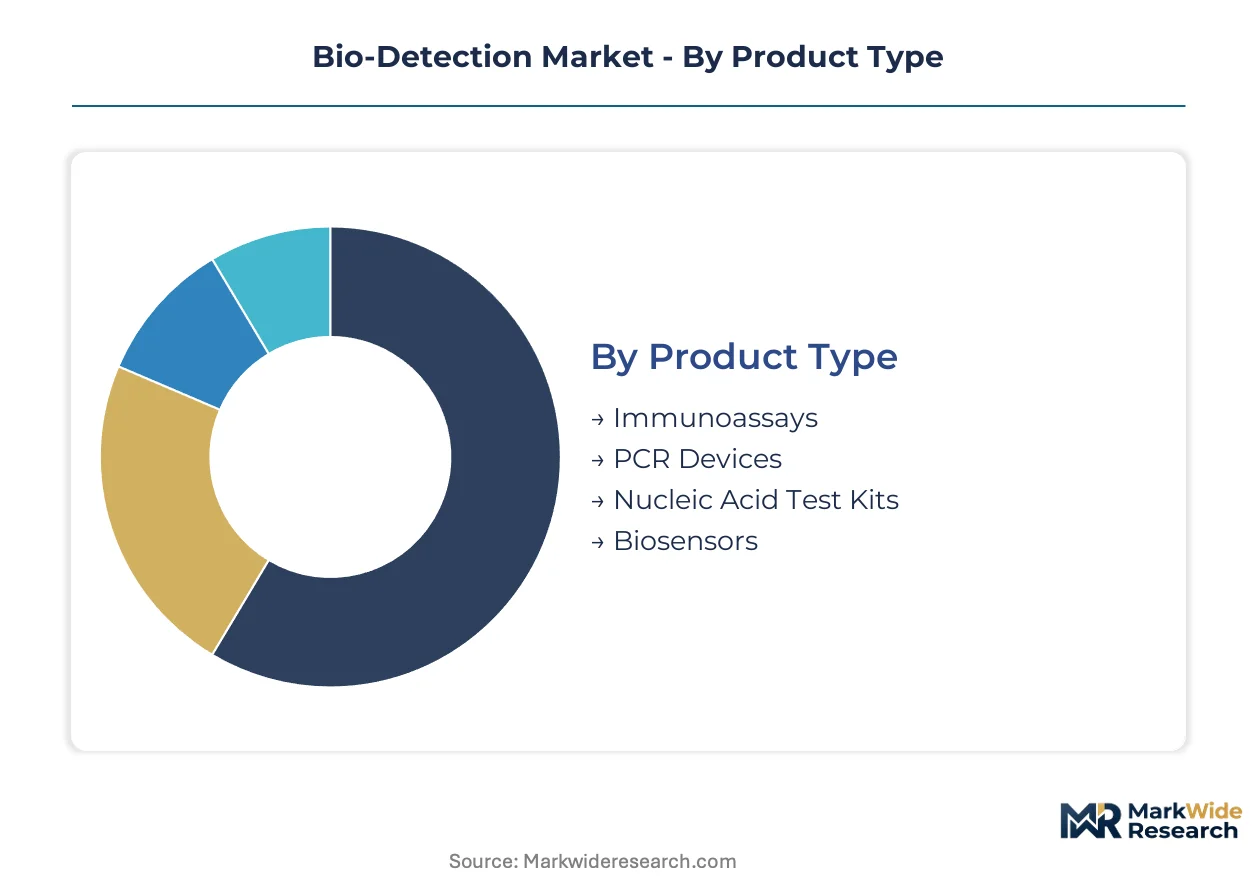
Segmentation in bio-detection reveals divergent procurement logics across defense, clinical, and environmental operators. Each dimension—product architecture, detection modality, end-use workflow, and threat application—carries distinct margin profiles and regulatory compliance burdens.
Product Type:
Buyers in this category sort by capital intensity versus consumable dependency, with installed base stickiness determining lifetime value capture.
- PCR Devices:Thermal cycling platforms achieve single-copy nucleic acid sensitivity through enzymatic amplification. Demand concentrates in United States clinical laboratories where FDA-cleared infectious disease panels anchor diagnostic revenue. Reagent pull-through economics sustain margins despite instrument commoditization.
- Biosensors:Electrochemical and optical transducer architectures miniaturize for point-of-care deployment without thermal cycling. Field screening applications in NATO defense procurement and remote environmental monitoring drive fastest expansion. Sensitivity convergence with benchtop systems is compressing price premiums.
- Immunoassays:Antibody-antigen binding platforms dominate food safety and veterinary screening with lower technical complexity.
- Nucleic Acid Test Kits:Lyophilized reagent cartridges enable distributed testing without cold chain logistics.
PCR Devices lead volumes today; Biosensors are gaining share fastest.
Technology:
Technology selection hinges on multiplexing depth versus detection speed trade-offs, with regulatory validation timelines amplifying switching costs.
- Fluorescence:Optical reporter systems using rare earth fluorophores achieve real-time quantification in qPCR and microarray formats. Revenue concentrates in high-throughput clinical laboratories processing epidemic surveillance panels. Supply concentration in Chinese rare earth extraction creates price volatility exposure.
- Mass Spectrometry:Non-targeted compound identification enables unknown pathogen characterization without prior sequence knowledge. Environmental compliance monitoring under EPA Clean Water Act methods and wastewater epidemiology applications in São Paulo and Seoul drive adoption. Capital cost and technical expertise requirements limit penetration.
- Microarray:Solid-phase hybridization enables parallel detection of hundreds of targets on single substrates.
- Enzymatic Reaction:Colorimetric and chemiluminescent readouts anchor low-cost screening in resource-limited settings.
Fluorescence dominates revenue contribution; Mass Spectrometry is climbing the fastest in environmental applications.
End User:
End-user segmentation reflects divergent budget authority and workflow integration requirements, with subscription models reshaping procurement patterns.
- Clinical Laboratories:CAP-accredited and ISO 15189-certified facilities process diagnostic samples with regulatory liability exposure. United States hospital networks and German reference laboratories concentrate demand for automated workflow systems. Cloud-connected assay panels are shifting capital expenditure to operational budgets.
- Research Institutions:Academic and government laboratories prioritize flexibility and publication-grade sensitivity over regulatory clearance. CRISPR-enhanced platforms and novel biosensor architectures achieve early validation here before clinical translation.
- Food & Beverage Companies:HACCP compliance and export certification requirements drive pathogen screening in processing facilities.
- Pharmaceutical Firms:Biomanufacturing contamination control and cell line authentication sustain demand for rapid mycoplasma and viral detection.
Clinical Laboratories anchor procurement volumes; Research Institutions are expanding fastest as technology translation accelerates.
Application:
Application segmentation tracks threat prioritization across public health, security, and commerce, with funding volatility distinguishing government from commercial demand.
- Pathogen Detection:Infectious disease diagnostics and epidemic surveillance command largest revenue share through recurring testing volumes. United States federal bio-surveillance infrastructure and European hospital network consolidation sustain procurement. Multiplex panel expansion is broadening addressable test menus.
- Biodefense:Field-deployable screening for biological threat agents serves military and first-responder missions. NATO preparedness directives and national stockpile requirements in United States, United Kingdom, and Germany create concentrated demand spikes. Procurement cycles align with defense budget authorization timelines.
- Environmental Monitoring:Water quality and air bioaerosol surveillance expand under regulatory compliance mandates.
- Food Safety Testing:Supply chain verification and import screening sustain steady commercial demand.
Pathogen Detection leads revenue today; Biodefense is expanding most quickly on preparedness investment cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States federal bio-surveillance infrastructure outspends German hospital network consolidation, while Indian epidemic preparedness programs accelerate faster than Brazilian municipal procurement cycles.
United States
FDA clearance pathways and CDC epidemic surveillance contracts drive procurement of multiplex PCR platforms. The Biomedical Advanced Research and Development Authority funds field-deployable pathogen screening under national preparedness directives. Boston-Cambridge biotech clusters anchor CRISPR-enhanced platform development, with reference laboratories retrofitting thermal cycler bays for 24/7 outbreak monitoring.
Germany
ISO 15189 accreditation requirements and EU In Vitro Diagnostic Regulation compliance timelines concentrate demand in automated workflow systems. REACH restrictions on per- and polyfluoroalkyl substances force 18-month reagent reformulation cycles for microfluidic cartridge suppliers. Munich-Stuttgart industrial corridors host captive PCR enzyme manufacturing, buffering supply disruptions for European assay producers.
India
CDSCO fast-track pathways for epidemic preparedness devices and PLI scheme domestic manufacturing incentives attract component localization. Central government bio-surveillance infrastructure spending under the Integrated Disease Surveillance Programme expands nucleic acid testing capacity. Maharashtra and Karnataka pharmaceutical clusters pilot cloud-connected assay panels for real-time outbreak mapping.
South Korea
MFDS regulatory frameworks and municipal wastewater epidemiology programs drive mass spectrometry platform adoption for non-targeted compound identification. Seoul metropolitan sewer network monitoring contracts create dedicated procurement categories for pathogen surveillance. Daegu-Gyeongbuk manufacturing zones produce electrochemical biosensor components for handheld point-of-care deployment.
Brazil
ANVISA diagnostic device registration pathways and Ministry of Health epidemic response budgets sustain demand for lyophilized reagent cartridges. São Paulo state environmental monitoring stations upgrade to nucleic acid-based systems under Clean Water Act-aligned federal mandates. Southeastern industrial corridors concentrate food safety testing laboratories serving export certification requirements.
Bio-Detection Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated life science conglomerates commanding diagnostic platform installed bases while boutique biosensor firms capture point-of-care niches. The vendor base concentrates around three strategic tiers: diversified conglomerates with reagent pull-through economics, mid-scale automation specialists, and regional assay kit suppliers. M&A activity targets workflow automation capabilities, while strategic partnerships secure rare earth fluorophore supply chains.
Within the diversified conglomerate tier, Abbott Laboratories, Thermo Fisher Scientific, and Danaher Corporation exemplify distinct competitive positions. Abbott leverages diagnostic platform installed bases to sustain consumable revenue streams. Thermo Fisher anchors North American supply chains through captive manufacturing positions. Danaher occupies a position emphasizing integrated workflow automation that reduces hands-on time in high-throughput environments.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Agilent Technologies |
| Thermo Fisher Scientific |
| PerkinElmer |
| Merck KGaA |
| Danaher Corporation |
| Becton, Dickinson and Company |
| Bio-Rad Laboratories |
| Roche Holding AG |
| Others |
Supply Flow & Price Mechanics
Captive PCR enzyme manufacturing in Germany and the United States anchors supply positions for platform manufacturers while enabling premium pricing on consumable pull-through. This backward integration into reagent production insulates incumbent vendors from raw material volatility and sustains margins on high-throughput thermal cycler installations.
Pricing Analysis
Capacity additions in South Korea and India are reshaping price floors for electrochemical biosensor components. The market runs on a subscription-based assay panel structure that bundles instrumentation, consumables, and cloud analytics into recurring operational budgets. Price differentiation hinges on FDA clearance tier and multiplexing depth, with clinical laboratories showing lowest sensitivity due to accreditation switching costs while research institutions negotiate aggressively on capital equipment. Pricing pressure intensifies in fluorescence-dependent platforms as rare earth extraction bottlenecks compress margins.
Supply Chain Analysis
ISO 13485 and FDA Quality System Regulation certifications gate supplier qualification for microfluidic cartridge manufacturers. Production concentrates in Germany, the United States, and China, with lyophilized reagent formulation drawing from rare earth fluorophore deposits and enzymatic precursors. Single-source vulnerability in PCR polymerase supply creates systemic risk propagation timelines measured in weeks. Distribution runs through integrated delivery networks consolidating procurement authority across multi-facility hospital systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage between United States FDA clearance timelines and Indian CDSCO fast-track pathways creates cost-advantaged manufacturing positions for epidemic preparedness devices. Regulatory divergence in certification cycles enables component localization under production-linked incentive schemes.
For Market Incumbents: Lock in reagent pull-through economics by retrofitting installed thermal cycler bases with cloud-connected telemetry modules. Secure backward integration into rare earth fluorophore supply chains through strategic partnerships with extraction consortiums. Defend against CRISPR-enhanced platform displacement by accelerating multiplexing capabilities beyond 20-plex configurations.
For New Entrants and Emerging Players: Direct-to-clinic digital distribution routes bypass consolidated procurement gatekeepers at integrated delivery networks. Target wastewater epidemiology applications in Brazilian municipal systems and South Korean metropolitan sewer networks where mass spectrometry platforms face limited incumbent saturation. Lead with handheld electrochemical biosensors achieving single-copy sensitivity without thermal cycling infrastructure.
For Investors and Strategic Acquirers: Roll-up economics work for boutique biosensor firms because point-of-care miniaturization fragments addressable markets below conglomerate radar. Five-to-ten year viability rests on workflow automation capabilities reducing hands-on time in high-throughput environments. Watch for CDSCO fast-track clearance announcements as inflection indicators for Indian manufacturing localization.
| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Connected Assay Panel Launch | Subscription telemetry enables real-time outbreak mapping for Brazilian and South Korean public health agencies. |
| CRISPR Platform Regulatory Submission | FDA clearance compresses detection timelines from hours to minutes in clinical laboratory settings. |
| Backward Integration into Fluorophore Supply | Captive rare earth sourcing buffers margin compression from Chinese extraction bottlenecks. |
| Wastewater Epidemiology Partnership | São Paulo and Seoul municipal contracts create dedicated procurement categories for mass spectrometry platforms. |
| Digital Microfluidics Cartridge Validation | Silicone-based surface treatments maintain EU certification continuity under REACH fluoropolymer restrictions. |
Methodological Framework
Bottom-up clinical laboratory procurement modeling reconciled against top-down PCR reagent manufacturing tracking forms the analytical core. Primary interviews with diagnostic platform executives, hospital GPO contracts managers, biomedical engineers, and CDSCO regulatory affairs specialists combined with secondary validation against FDA 510(k) filings, EPA Clean Water Act method databases, EU MDR technical documentation, and hospital procurement contract repositories. Triangulation across supply-side capacity announcements and demand-side instrument placement data ensures convergence.
Input-output matrices map thermal cycler installations to consumable pull-through volumes across product type, technology modality, end-user certification tier, and application threat category segments. CAGRs derive from regression analysis of historical instrument placement against projected bio-surveillance infrastructure budgets throughout the forecast period. Forecast inputs incorporate NATO defense procurement cycles, EU In Vitro Diagnostic Regulation enforcement timelines, and PLI scheme manufacturing incentive disbursements.
Biodefense budget authorization delays, REACH fluoropolymer substitution bottlenecks, and CRISPR patent litigation outcomes are the dominant revision risks. A model refresh is warranted upon material change in FDA multiplex panel clearance timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Environmental Biotechnology
Enzymatic Cleaning Market
Environmental Biotechnology
Global Bio Decontamination Market
Environmental Biotechnology
Europe Anaerobic Digestion Market
Environmental Biotechnology
North America Biosolids Market
Environmental Biotechnology
Bioremediation Market
Environmental Biotechnology
Blue Biotechnology Market
Environmental Biotechnology
Plastic-Eating Bacteria Market
Environmental Biotechnology
Global Anaerobic Digestion Market