
 Bioremediation Market | 2026-2036
Bioremediation Market Size, Share, and Industry Trends Forecast 2026-2036
Bioremediation Market Intelligence
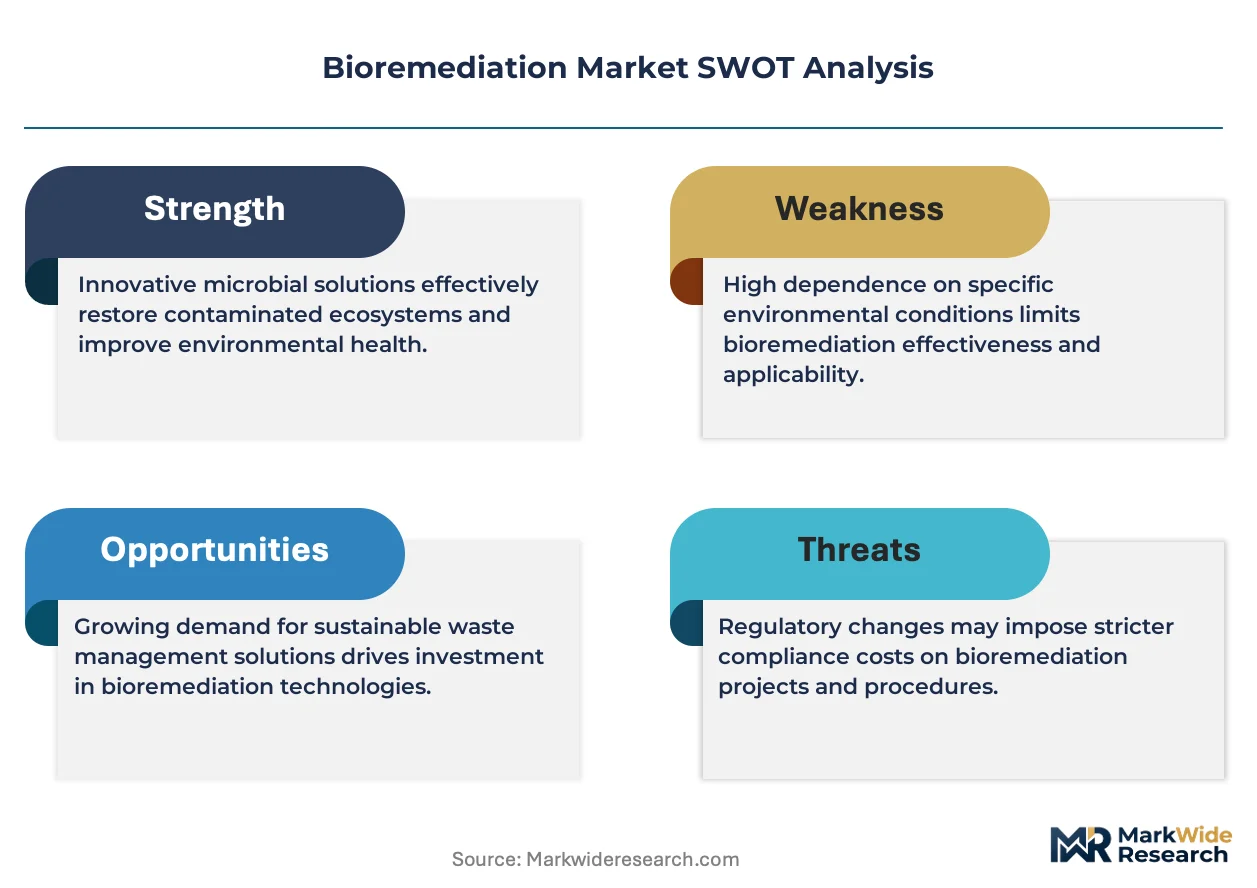
Project finance for brownfield redevelopment is fragmenting the competitive landscape by lowering capital barriers for regional remediation contractors. SUEZ Group leverages its integrated water-waste platform to anchor large-scale bioremediation contracts across municipal and industrial accounts. Veolia Environnement SA sustains competitive positioning through geographic density in European contaminated site management. Regenesis Corporation specializes in in-situ chemical oxidation paired with biological enhancement, occupying a differentiated niche in groundwater restoration.
Bioremediation employs microorganisms or plants to degrade, transform, or immobilize environmental contaminants, typically operating at temperatures between 10°C and 30°C with moisture content of 50-80% for optimal microbial activity. Its primary purpose is restoring soil and water matrices to regulatory-compliant states without the excavation or thermal destruction costs of physical remediation. Bioaugmentation commands attention where indigenous microbial populations prove insufficient for targeted contaminant classes, particularly chlorinated solvents and polycyclic aromatic hydrocarbons. Phytoremediation attracts interest for its low energy footprint in heavy metal stabilization, though margin pools remain thinner than technology-intensive alternatives. Wastewater treatment applications are expanding fastest as industrial discharge standards tighten across manufacturing clusters.
The EPA enforces Comprehensive Environmental Response, Compensation, and Liability Act provisions that directly shape site remediation timelines and technology selection criteria. REACH in Europe restricts hazardous substance releases that subsequently trigger mandatory bioremediation obligations for soil and groundwater matrices. Japan's Soil Contamination Countermeasures Act mandates investigation and remediation of designated substances, creating compliance-driven demand for biological treatment approaches. Stakeholders must monitor evolving per- and polyfluoroalkyl substances regulatory thresholds, as these persistent contaminants challenge conventional bioremediation efficacy and may force technology portfolio adjustments.
Market Dynamics
The bioremediation market is experiencing a fundamental restructuring as regulatory liability frameworks tighten across industrialized economies, forcing asset owners to accelerate site closure timelines and favor in-situ biological treatments over excavation-based alternatives.
Growth Catalysts
- REACH enforcement in Europe:The ECHA's expanded substance restrictions are triggering mandatory soil and groundwater remediation obligations across manufacturing clusters, creating compliance-driven demand for biological treatment approaches.
- Petrochemical sector expansion:Refinery and pipeline operators in the United States are deploying bioaugmentation protocols for hydrocarbon-contaminated sites to preempt EPA Superfund listing and associated liability.
- Japan's Soil Contamination Countermeasures Act:Designated substance investigations are mandating remediation at former industrial facilities, accelerating contracting for biological groundwater restoration technologies.
Market Restraints
- Microbial culture supply concentration:Specialized bioaugmentation inoculants rely on a limited base of fermentation-capable suppliers, creating input vulnerability for regional contractors.
- Per- and polyfluoroalkyl substances recalcitrance:Conventional bioremediation efficacy drops sharply against PFAS contaminants, forcing technology portfolio gaps at sites with mixed contamination profiles.
- Phytoremediation margin compression:Heavy metal stabilization via plant-based approaches generates thinner returns than technology-intensive alternatives, deterring specialized contractor investment.
Strategic Opportunities
- Industrial cluster wastewater expansion:Tightening discharge standards across manufacturing zones in Germany and Japan are accelerating biological treatment adoption for process water remediation.
- Climate adaptation funding:EU Green Deal-aligned financing mechanisms are subsidizing brownfield redevelopment projects that incorporate in-situ bioremediation as a carbon-efficient alternative to excavation.
- Genomic screening convergence:Metagenomic analysis paired with targeted bioaugmentation is opening precision remediation protocols for chlorinated solvent plumes previously deemed intractable.
Industry Challenges
- Microbial ecologist talent scarcity:Site-specific bioremediation design requires specialized expertise in contaminant-microbe interaction modeling that outpaces current training pipeline output.
- Performance guarantee standardization delays:Absence of unified efficacy metrics for biological treatment completion creates contracting friction between technology providers and liability insurers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bioremediation Market |
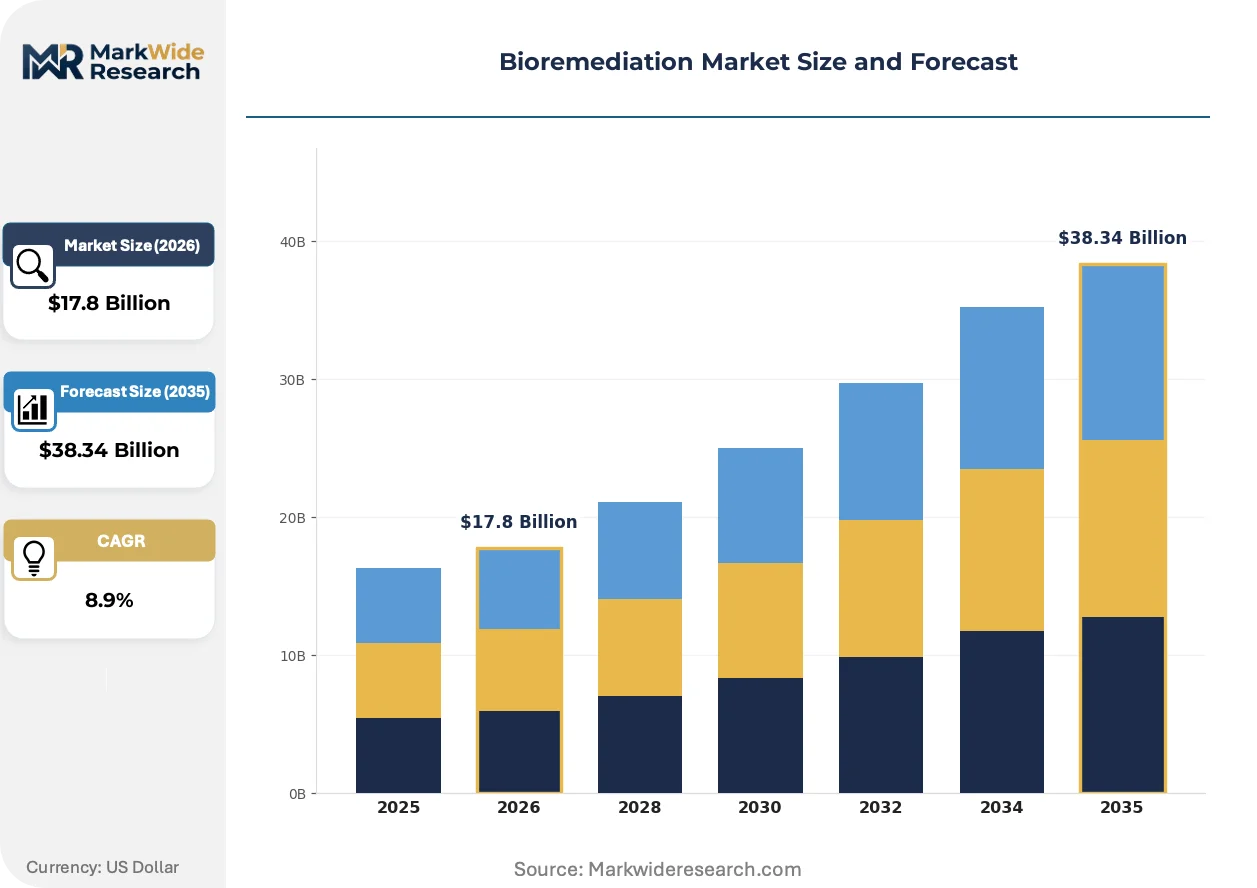
| Market Size in 2026 | $17.8 Billion |
| Market Size in 2035 | $38.34 Billion |
| CAGR (2026 – 2036) | 8.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Bioventing, Phytoremediation, Bioaugmentation, Landfarming Application: Oil Spill Cleanup, Heavy Metal Removal, Soil Remediation, Wastewater Treatment End User: Industrial Sector, Government Agencies, Environmental Consultants, Research Institutions Service Type: Consulting Services, Laboratory Services, Monitoring Services, Remediation Services |
| Companies Covered | SUEZ Group, Aquatech International Corporation, Regenesis Corporation, Probiosphere Inc., Drylet Inc., Xylem Inc., Ecolab Inc., Newterra Ltd., Veolia Environnement SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bioremediation Market Strategic Shifts & Innovations
Bioremediation technology trajectories are converging on precision delivery systems and real-time monitoring integration, compressing treatment timelines while expanding addressable contamination classes beyond legacy petroleum hydrocarbons.
Electrokinetic bioremediation is migrating from laboratory demonstration to field deployment at clay-heavy sites where microbial nutrient delivery fails through conventional infiltration. Mining operators in Canada and Australia are piloting electrode arrays to mobilize heavy metals toward rhizosphere capture zones. The technology is compressing treatment durations at dense soil matrices from decades toward multi-year horizons, though capital intensity limits adoption to high-liability asset closures.
REACH authorization requirements are expanding the roster of substances requiring mandatory remediation across European industrial portfolios. The ECHA's sunset clause mechanism is accelerating site investigations as downstream users face supply chain disruption from substance restrictions. Germany's contaminated site managers are prioritizing in-situ biological approaches to minimize excavation volumes and associated carbon reporting under CSRD disclosure rules.
Asset owners are unbundling remediation performance risk from capital provision through availability-based contracting structures. Municipal brownfield developers in the United States are transferring biological treatment outcome accountability to specialized contractors while retaining site control. This reconfiguration concentrates technical risk with technology-integrated service providers and is most visible at former manufacturing facilities in Michigan and Ohio where legacy petroleum contamination drives extended liability exposure.
Bioremediation Market Segmentation
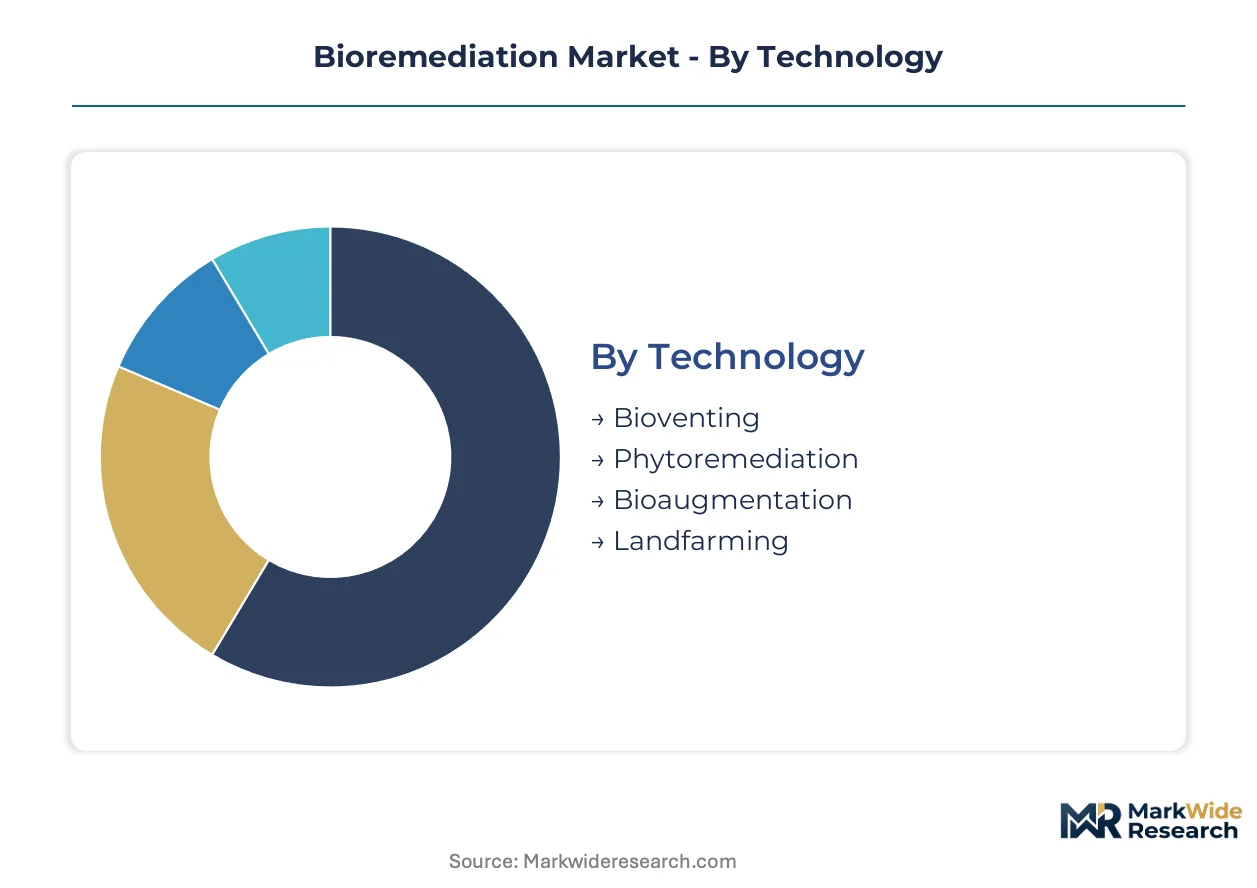
Bioremediation technology selection hinges on contaminant chemistry, site hydrogeology, and regulatory closure timelines. Segment boundaries blur as contractors bundle monitoring with remediation execution to capture recurring revenue streams.
Technology:
Cost tier determines technology deployment patterns across liability-exposed asset portfolios.
- Bioaugmentation:Specialized microbial consortia are introduced to accelerate degradation rates at sites with recalcitrant chlorinated solvents or high-molecular-weight hydrocarbons. Demand concentrates at former dry cleaning facilities and electronics manufacturing sites in Germany and Japan where indigenous populations prove insufficient for targeted contaminant classes.
- Phytoremediation:Plant-based extraction and stabilization operate at lower capital intensity than engineered alternatives, utilizing hyperaccumulator species for heavy metal sequestration. Margins remain compressed relative to technology-intensive approaches, limiting contractor specialization in lead and cadmium stabilization projects.
- Bioventing:Oxygen delivery through soil vapor extraction enhances aerobic biodegradation of petroleum hydrocarbons at shallow contamination plumes.
- Landfarming:Ex-situ biotreatment of excavated soils through controlled tilling and nutrient amendment suits high-volume, low-toxicity waste streams.
Bioaugmentation holds installed capacity. Phytoremediation is rotating up the share rankings.
Application:
Volume characteristics shape treatment modality selection across contamination scenarios.
- Wastewater Treatment:Biological process water remediation is expanding fastest as industrial discharge standards tighten across manufacturing clusters in Germany and Japan. Facilities integrate membrane bioreactors with specialized inoculum delivery to meet tightening COD and heavy metal limits.
- Soil Remediation:In-situ biological approaches are displacing excavation at legacy industrial sites where carbon reporting under CSRD disclosure rules and EPA liability frameworks favor minimal soil disturbance. Treatment timelines extend across multi-year horizons at dense clay matrices.
- Oil Spill Cleanup:Marine and coastal bioaugmentation protocols address hydrocarbon releases through nutrient-enriched shoreline application.
- Heavy Metal Removal:Immobilization and extraction approaches target arsenic, chromium, and mercury contamination at mining legacy sites and former tannery facilities.
Soil remediation holds installed capacity. Wastewater treatment is climbing the fastest.
End User:
Customer type dictates contracting structure complexity and performance guarantee requirements.
- Industrial Sector:Refinery and petrochemical operators deploy bioaugmentation protocols to preempt EPA Superfund listing and associated joint-and-several liability. Procurement patterns favor availability-based contracts that transfer technical risk to specialized remediation contractors while retaining site control.
- Government Agencies:Municipal brownfield redevelopment authorities in the United States concentrate demand through performance-specified tenders that bundle investigation, treatment, and verification phases.
- Environmental Consultants:Technical advisory firms specify biological treatment approaches and oversee contractor performance without direct execution risk.
- Research Institutions:Academic and government laboratories pilot electrokinetic bioremediation and metagenomic screening protocols for technology validation.
Industrial sector holds installed capacity. Government agencies is rotating up the share rankings.
Service Type:
Maturity gradients separate commoditized offerings from specialized technical capabilities.
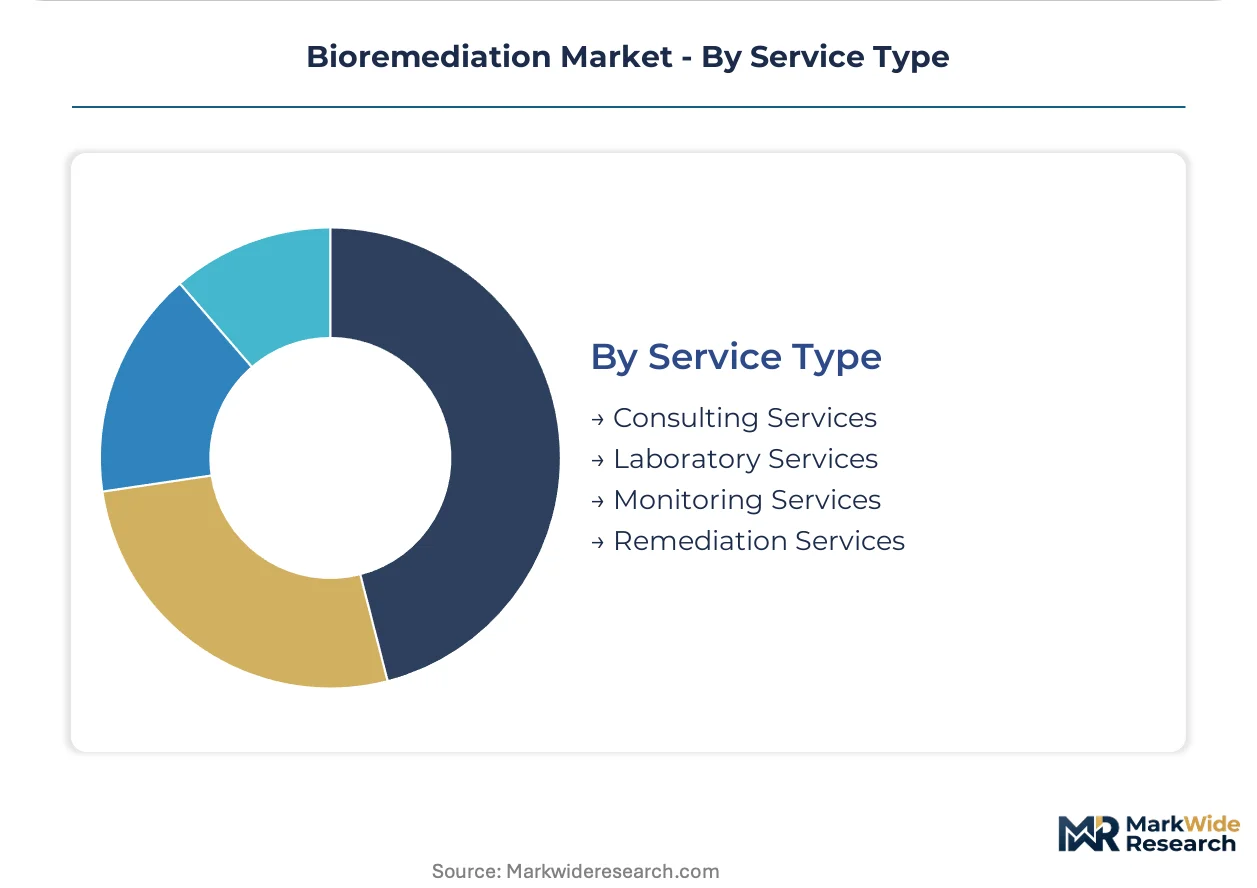
- Remediation Services:Full-scope biological treatment execution commands premium positioning through integrated inoculum supply, nutrient delivery system installation, and performance verification. Contractors with captive fermentation capacity defend margin position against regional competitors dependent on third-party microbial culture procurement.
- Monitoring Services:Long-term groundwater and soil vapor surveillance generates recurring revenue streams extending decades past active treatment completion. Metagenomic analysis integration is opening precision protocol refinement for chlorinated solvent plumes previously deemed intractable.
- Consulting Services:Site-specific bioremediation design requires specialized expertise in contaminant-microbe interaction modeling that outpaces current training pipeline output.
- Laboratory Services:Analytical verification of treatment completion against regulatory thresholds supports contracting friction reduction between technology providers and liability insurers.
Remediation services holds installed capacity. Monitoring services is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics for specialized microbial inoculants and remediation equipment favor established manufacturing bases in Western Europe and North America, while project execution revenue concentrates in jurisdictions with mature liability frameworks. Capital flows into remediation contracting track regulatory enforcement intensity rather than manufacturing capacity.
United States
Legacy petroleum contamination at former manufacturing facilities in Michigan and Ohio drives sustained demand for bioaugmentation protocols. EPA Superfund liability provisions force asset owners toward in-situ biological treatments to preempt joint-and-several exposure. The Rust Belt industrial corridor hosts the densest concentration of active remediation contracting.
Germany
REACH authorization requirements and the ECHA sunset clause mechanism accelerate site investigations across chemical manufacturing portfolios. CSRD disclosure rules on carbon reporting favor minimal-excavation biological approaches over soil removal. The Rhine-Ruhr industrial cluster generates concentrated demand for groundwater restoration technologies.
Japan
The Soil Contamination Countermeasures Act mandates investigation and remediation of designated substances at former industrial facilities. Electronics manufacturing legacy sites in the Kanto region require specialized treatment for chlorinated solvent plumes. METI enforcement patterns concentrate contracting in metropolitan manufacturing belts.
Canada
Mining operators in Ontario and British Columbia pilot electrokinetic bioremediation for heavy metal mobilization at clay-heavy tailings sites. Health Canada and PMRA guidelines on contaminated site management tighten closure standards for resource extraction liabilities. The Canadian Shield mining belt represents an emerging testbed for electrode-array field deployment.
Australia
Legacy mining contamination across Western Australia and Queensland drives adoption of phytoremediation for arsenic and chromium stabilization. State environmental protection agencies enforce progressive rehabilitation obligations on extractive industries. The Pilbara region hosts concentrated contracting for biological heavy metal immobilization at iron ore legacy sites.
Bioremediation Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream supplying fermentation-derived inoculants and monitoring instrumentation. The vendor base organizes around three tiers: water-waste conglomerates with captive remediation divisions, dedicated bioremediation contractors with captive microbial culture capacity, and regional service providers dependent on third-party supply. Competitive positioning hinges on geographic density in contaminated site clusters and vertical control over bioaugmentation inputs. Consolidation pressure operates through availability-based contracting structures that transfer performance risk to technically capable executors.
Within the integrated platform tier, SUEZ Group and Veolia Environnement SA anchor large-scale municipal and industrial account access through water-waste infrastructure relationships. Regenesis Corporation occupies a differentiated position among specialized contractors, exemplifying the technology-integrated archetype that pairs in-situ chemical oxidation with biological enhancement for groundwater restoration applications.
| Leading Market Players |
|---|
| SUEZ Group |
| Aquatech International Corporation |
| Regenesis Corporation |
| Probiosphere Inc. |
| Drylet Inc. |
| Xylem Inc. |
| Ecolab Inc. |
| Newterra Ltd. |
| Veolia Environnement SA |
| Others |
Cost & Logistics Intelligence
Overcapacity in European fermentation facilities is compressing microbial culture pricing while simultaneously incentivizing suppliers to bundle nutrient formulations with inoculum deliveries. This utilization dynamic is reshaping contractor procurement posture across bioaugmentation-dependent remediation portfolios in Germany and Japan.
Pricing Analysis
Industrial OEM buyers anchor project-based contracting structures that transfer performance risk to specialized remediation contractors. Pricing stratifies across premium, standard, and economy tiers based on certification tier and volume scale, with EPA Superfund-preemptive contracts commanding premium positioning. Cost compression in the standard tier is intensifying because regional contractors without captive fermentation capacity face input vulnerability. Municipal brownfield developers exhibit highest price sensitivity, while petrochemical operators with joint-and-several liability exposure demonstrate lowest sensitivity.
Supply Chain Analysis
Specialized fermentation capacity concentrates in Germany, the United States, and Japan, with contract manufacturers serving both proprietary culture developers and integrated water-waste platforms. The supply chain draws from agricultural substrate feedstocks, specialized bioreactor equipment, and analytical verification instrumentation. Single-source vulnerability concentrates around chlorinated solvent-degrading consortia suppliers. Distribution runs through direct contractor-procurement relationships with limited intermediary presence.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The bioremediation market is experiencing high-growth disruption as genomic screening convergence enables precision protocols for previously intractable contaminant classes, while REACH sunset clauses and EPA liability frameworks compress site closure timelines.
For Market Incumbents: Pre-empt genomic screening convergence by acquiring metagenomic analysis capabilities or partnering with specialized laboratories. Captive fermentation capacity in the Rhine-Ruhr corridor and Rust Belt industrial clusters will defend margin position against regional competitors dependent on third-party microbial culture procurement. Vertical integration into nutrient formulation production addresses input cost pressure.
For New Entrants and Emerging Players: Build out electrokinetic bioremediation deployment capabilities targeting Canadian and Australian mining legacy sites with clay-heavy tailings matrices. The Pilbara region and Canadian Shield mining belt represent underpenetrated white-space where electrode-array field deployment is migrating from laboratory demonstration. A go-to-market angle anchored to carbon-efficient alternatives under CSRD disclosure rules will accelerate contracting access.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across monitoring services as metagenomic analysis integration opens recurring revenue streams extending decades past active treatment completion. Acquisition targets should screen for contractors with captive fermentation capacity and established presence in EPA Superfund-prevalent jurisdictions. The signal to watch is ECHA authorization list expansion velocity as a demand inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fermentation Capacity | Captive microbial culture production defends margin position against input cost volatility in bioaugmentation protocols. |
| Metagenomic Analysis Partnership | Precision remediation protocols for chlorinated solvent plumes open contracting access to previously intractable site categories. |
| Electrokinetic Technology Field Deployment | Electrode-array pilot programs at Canadian and Australian mining sites compress treatment durations at dense soil matrices. |
| Availability-Based Contracting Structure | Performance risk transfer to specialized contractors accelerates municipal brownfield redevelopment procurement in Michigan and Ohio. |
| EU Green Deal-Aligned Financing Access | Subsidized brownfield redevelopment projects incorporating in-situ bioremediation capture carbon-efficient alternative demand. |
Research Approach
Initial hypotheses were tested against primary input from remediation contractors, municipal brownfield development officers, petrochemical site managers, and microbial culture fermentation specialists and refined through secondary validation. Primary fieldwork encompassed EPA regional office enforcement pattern analysis, ECHA authorization timeline tracking, and METI compliance directive review. Secondary sources included SEC 10-K filings from integrated water-waste platforms, customs data on specialized bioreactor equipment trade flows, and contaminated site liability insurance underwriting guidelines. Bottom-up project pipeline aggregation and top-down regulatory obligation modeling were triangulated to cross-validate volume estimates.
Demand-supply balance dynamics across the projection horizon were modeled through segmentation across technology type, application scenario, end-user contracting structure, and service delivery maturity. The analytical framework incorporated treatment timeline compression from electrokinetic deployment, bioaugmentation efficacy rates against chlorinated solvent plumes, and wastewater discharge standard tightening velocity in German and Japanese manufacturing clusters. CAGRs were derived from regulatory obligation flow-through analysis and contractor capacity expansion announcements.
The forecast holds incumbent behavior within observed patterns; aggressive moves by genomic screening technology providers or electrokinetic equipment manufacturers would shift outcomes beyond modeled ranges. Quarterly review of ECHA sunset clause activation rates, EPA Superfund listing velocity, and PFAS regulatory threshold adjustments is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Environmental Biotechnology
Europe Anaerobic Digestion Market
Environmental Biotechnology
Global Anaerobic Digestion Market
Environmental Biotechnology
Plastic-Eating Bacteria Market
Environmental Biotechnology
Bio-Detection Market
Environmental Biotechnology
Enzymatic Cleaning Market
Environmental Biotechnology
Blue Biotechnology Market
Environmental Biotechnology
North America Biosolids Market
Environmental Biotechnology
Global Bio Decontamination Market