
 North America Biosolids Market | 2026-2036
North America Biosolids Market Size, Share, and Industry Trends Forecast 2026-2036
North America Biosolids Market Outlook
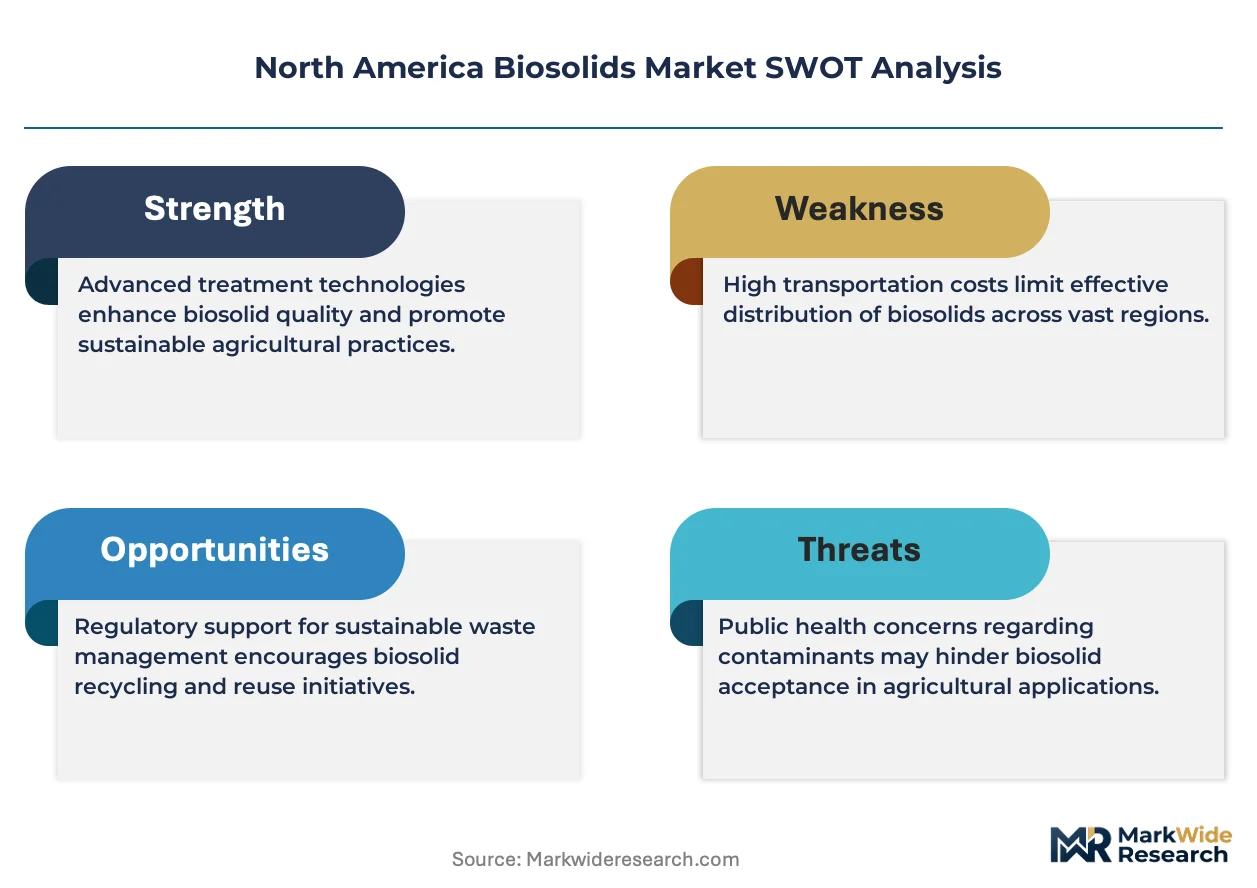
The capital-intensity gap between thermal drying specialists and conventional dewatering operators is collapsing as EPA nutrient recovery mandates force technology upgrades across the value chain. Synagro Technologies leverages its national hauling network and long-term municipal contracts to sustain volume leadership in Class A production. Lystek International differentiates through its alkaline hydrolysis platform, which occupies a niche in pathogen reduction for agricultural land application markets. BCR Environmental competes on modular system design, allowing smaller wastewater treatment operators to navigate capital constraints without sacrificing regulatory compliance.
Biosolids are organic materials derived from wastewater treatment processes, typically containing 50-70% organic matter with regulated limits on pathogens, heavy metals, and vector attraction reduction before land application or energy recovery. Their primary commercial purpose centers on nutrient recycling for soil amendment and renewable energy feedstock, displacing synthetic fertilizers and fossil-derived fuels in circular economy frameworks. Dried and pelletized biosolids command premium positioning in bagged retail and specialty crop markets where storage stability and transport efficiency concentrate margin pools. Liquid biosolids sustain dominant volume flows through direct injection equipment tied to municipal contracts and agricultural partnerships, while dewatered cake occupies an intermediate tier serving landfill alternative daily cover and bulk land application segments.
The EPA Part 503 rule and state-level nutrient management frameworks enforced by provincial regulators in Canada shape product classification, pathogen treatment requirements, and land application site restrictions across the market. USDA conservation programs and Canadian Environmental Protection Act standards further influence end-user eligibility and subsidy structures for agricultural biosolids utilization. Stakeholders must monitor emerging PFAS testing protocols and state-level concentration limits that threaten to redraw processing investment priorities and liability exposure across the value chain.
Market Dynamics
The EPA Part 503 rule revisions are compressing capital deployment timelines across the value chain, forcing municipal operators and private processors to accelerate Class A pathogen reduction upgrades before compliance deadlines crystallize.
Growth Catalysts
- Class A Processing Mandates:EPA Part 503 rule revisions tighten pathogen standards, compelling wastewater treatment facilities to invest in thermal drying and advanced digestion systems.
- Ontario Nutrient Management:Provincial regulations in Canada accelerate adoption of alkaline hydrolysis and thermal drying for agricultural land application compliance.
- Midwestern Agricultural Partnerships:Corn and soybean producers across Iowa, Illinois, and Ohio expand direct injection programs to displace synthetic phosphorus fertilizers.
Market Restraints
- Natural Gas Price Volatility:Thermal drying operations face margin compression from fluctuating energy input costs, particularly in US Midwest processing clusters.
- PFAS Testing Uncertainty:Emerging state-level concentration limits for per- and polyfluoroalkyl substances create liability exposure without standardized federal thresholds.
- Compost Substitution:Municipal green waste composting programs in California and Pacific Northwest municipalities divert organic waste streams from biosolids processing.
Strategic Opportunities
- Specialty Crop Retail:Dried pelletized biosolids command premium positioning in California almond and Washington apple markets where organic certification drives input selection.
- Methane Capture Integration:Anaerobic digestion facilities in Texas and Oklahoma combine biogas upgrading with Class A production to serve renewable natural gas offtake agreements.
- USDA Conservation Programs:Environmental Quality Incentives Program subsidies expand eligible acreage for agricultural biosolids application in nutrient-impaired watersheds.
Industry Challenges
- Operations Specialist Shortage:Thermal drying and pyrolysis facilities compete for process engineers with oil and gas sector employers in the Permian Basin and Alberta oil sands.
- Legacy Dewatering Retrofit Complexity:Conventional belt press and centrifuge installations require substantial civil works modification to accommodate advanced digestion pre-treatment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Biosolids Market |
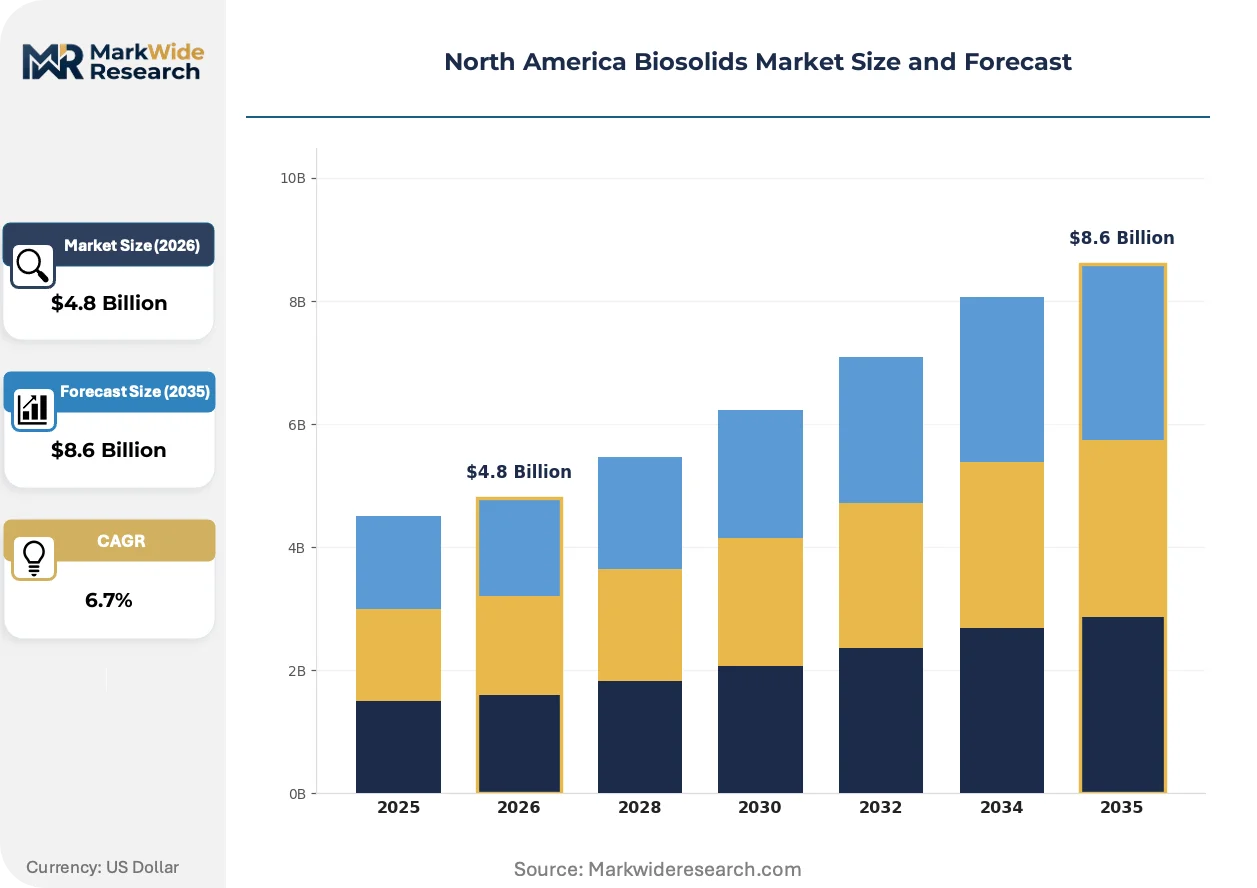
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dried Biosolids, Dewatered Biosolids, Pelletized Biosolids, Liquid Biosolids Application: Land Rehabilitation, Soil Amendment, Non-Agricultural Land Use, Energy Production End User: Wastewater Treatment Operators, Agricultural Managers, Renewable Energy Producers, Environmental Agencies Distribution Channel: Direct Sales, Distributors, Municipal Contracts, Third-party Vendors |
| Companies Covered | BCR Environmental, Lystek International, Synagro Technologies, Englobe, Walker Industries Holdings Limited, DC Water, Merrell Bros., Inc., Terrapure Environmental, Casella Waste Systems, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Biosolids Market Strategic Shifts
Thermal hydrolysis pre-treatment is reshaping solids handling economics across North American wastewater infrastructure. Three interconnected developments are compressing technology adoption cycles and redrawing competitive positioning among processing specialists.
Advanced alkaline hydrolysis is supplanting conventional lime stabilization for Class A pathogen reduction in agricultural land application markets. Midwestern corn belt cooperatives and municipal utilities in Minnesota and Wisconsin are retrofitting existing digestion trains with low-temperature thermal hydrolysis to reduce polymer consumption and increase cake dryness. The technology is compressing operating expenditure differentials between regional haulers and integrated processors with captive drying capacity.
EPA Part 503 rule revisions targeting vector attraction reduction and pathogen monitoring are forcing quarterly compliance reporting upgrades across US municipal operators. The regulatory pressure is accelerating capital allocation toward automated sampling and real-time pathogen detection systems. Canadian provincial regulators in Ontario and Quebec are harmonizing testing protocols with US federal standards, creating cross-border equipment procurement efficiencies for technology vendors.
Agricultural buyers are consolidating procurement decisions through cooperative purchasing agreements and long-term application service contracts. Direct equipment ownership is yielding to contracted land application services in Iowa, Nebraska, and Kansas where equipment specialization and regulatory compliance expertise concentrate among regional operators. The shift is most visible in the Corn Belt, where nutrient management plan complexity and seasonal application windows favor outsourced logistics over in-house handling.
North America Biosolids Market Segmentation
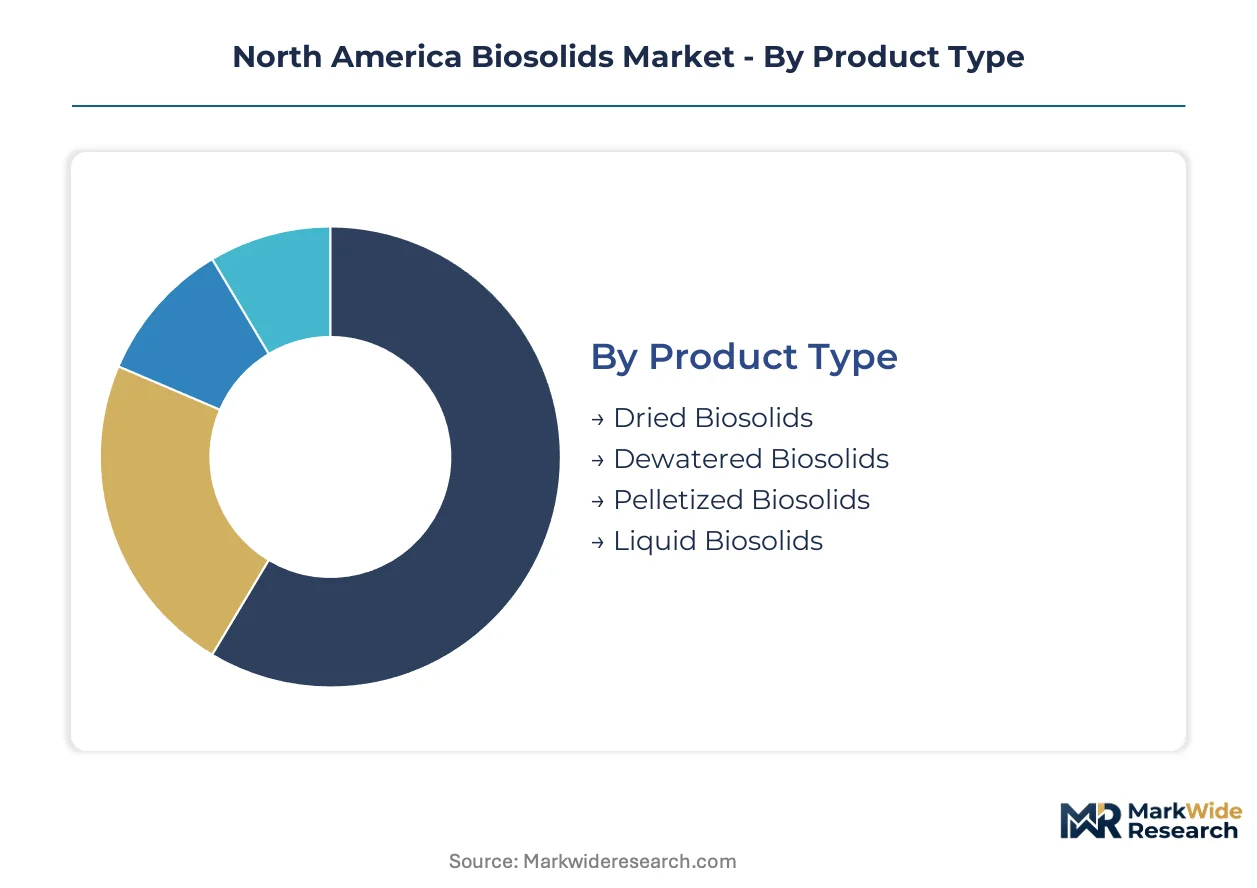
Product form dictates regulatory classification, transport economics, and end-use eligibility across North American biosolids value chains. Segmentation reveals how EPA Part 503 pathogen tiers and provincial nutrient management rules concentrate margin pools in specific product categories while excluding others from premium agricultural markets.
Product Type:
EPA Part 503 Class A and Class B designations create divergent commercial pathways for each physical form, with pathogen reduction technology investments determining market access rather than intrinsic material properties alone.
- Dried Biosolids:Thermal drying reduces moisture content below 10%, achieving Class A pathogen standards and extended storage stability for bagged retail distribution. Premium positioning in California almond orchards and Washington apple operations depends on organic certification compatibility and synthetic fertilizer displacement economics.
- Liquid Biosolids:Raw or digested slurry at 2-7% solids dominates total volume flows through direct injection equipment and municipal contract structures. Iowa and Illinois corn belt operations favor this format for phosphorus recovery at scale, though seasonal application windows and haul distance constraints limit geographic reach.
- Dewatered Biosolids:Centrifuge or belt press cake at 15-25% solids occupies intermediate positioning for landfill alternative daily cover and bulk agricultural application. Polymer conditioning costs and odor control requirements shape regional competitiveness.
- Pelletized Biosolids:Dried material densified into uniform granules commands transport efficiency premiums and specialty crop market access. Blending flexibility with conventional fertilizers supports custom formulation for turf and nursery segments.
Established volume favors liquid biosolids; emerging adoption favors dried biosolids.
Application:
End-use segmentation tracks how provincial regulators and USDA conservation programs allocate subsidy eligibility and liability exposure across competing soil amendment and energy recovery pathways.
- Soil Amendment:Agricultural land application for nutrient recovery represents the dominant commercial outlet, with Ontario corn producers and Midwestern soybean operations driving contracted service demand. EPA Part 503 vector attraction reduction standards and emerging PFAS testing protocols reshape site eligibility quarterly.
- Energy Production:Anaerobic digestion biogas upgrading and thermal conversion to renewable natural gas concentrate in Texas and Oklahoma processing clusters. FERC interconnection standards and utility offtake agreements determine project finance viability.
- Land Rehabilitation:Mine reclamation and construction site restoration utilize dewatered cake for erosion control and topsoil reconstruction. Pennsylvania and West Virginia abandoned mine programs specify metal content limits that exclude certain municipal sources.
- Non-Agricultural Land Use:Golf course turf management, cemetery maintenance, and highway median fertilization support pelletized product premiums. Seasonal demand concentration and aesthetic performance requirements favor consistent quality specifications.
Soil amendment anchors current revenue; energy production exhibits steepest expansion trajectory.
End User:
Customer type determines procurement structure complexity, with long-term municipal contracts favoring integrated processors and agricultural spot markets rewarding regional haulers with application equipment specialization.
- Wastewater Treatment Operators:Municipal utilities and industrial pretreatment facilities control upstream volume and regulatory compliance liability. Class A upgrade capital decisions at these nodes cascade through downstream pricing and availability.
- Agricultural Managers:Corn belt cooperatives and California specialty crop operations consolidate purchasing through nutrient management planning services. Equipment ownership is yielding to contracted land application expertise.
- Renewable Energy Producers:Biogas upgrading facilities and waste-to-energy developers source high-organic-content streams for methane capture. Texas and Oklahoma pipeline injection projects compete with agricultural offtake for digester capacity.
- Environmental Agencies:Federal and state remediation programs specify biosolids for superfund site capping and erosion control. Procurement runs through competitive bidding with extended performance bonding requirements.
Contracted relationships favor wastewater treatment operators; spot market flexibility favors agricultural managers.
Distribution Channel:
Channel structure reflects capital intensity asymmetries between national hauling networks and regional equipment specialists, with municipal procurement regulations favoring incumbent contract holders.
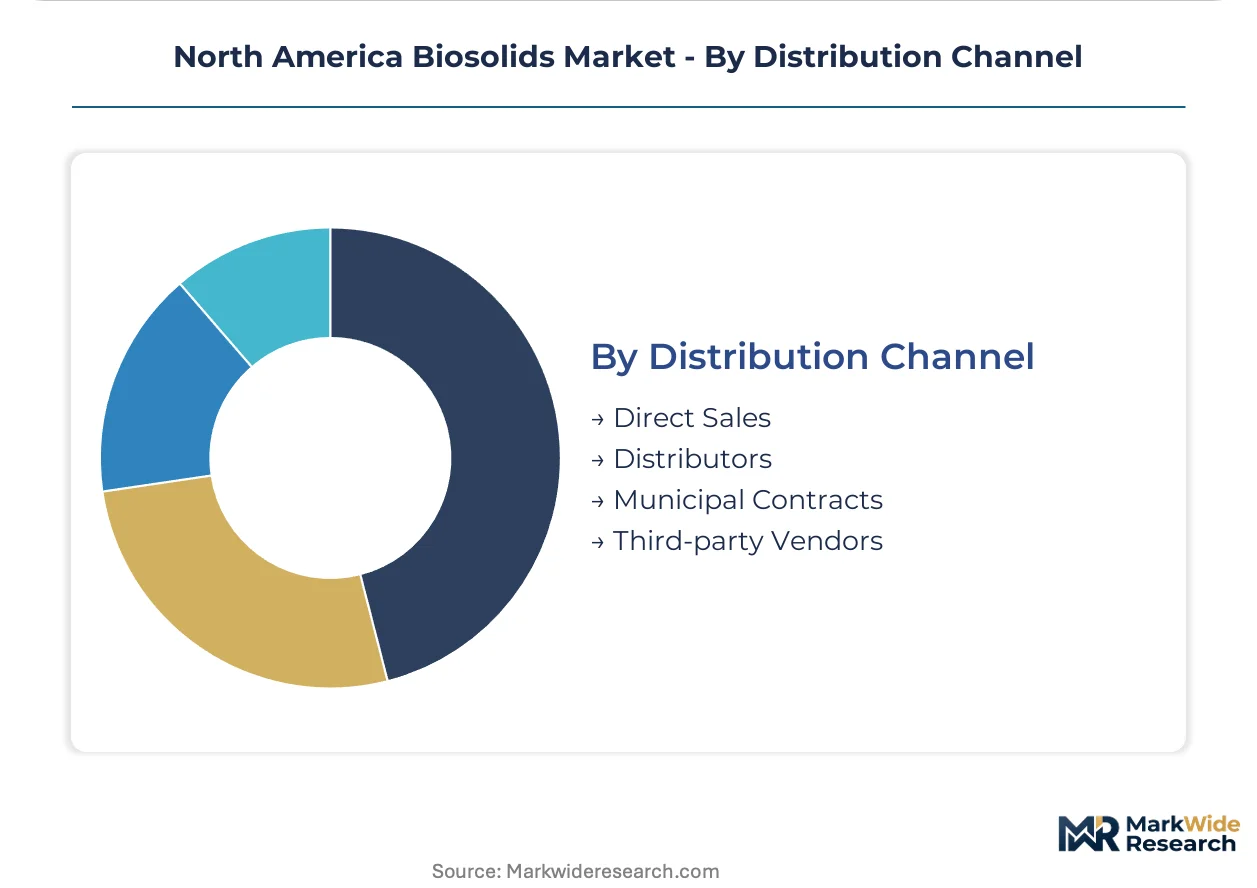
- Municipal Contracts:Long-term service agreements spanning 10-20 years lock in volume commitments and tipping fee structures. Ontario nutrient management regulations and EPA Part 503 compliance reporting requirements raise barriers for new entrants.
- Direct Sales:Large agricultural operations and energy developers negotiate bilateral offtake for specified quality and volume. Price discovery depends on synthetic fertilizer parity and natural gas benchmark correlations.
- Distributors:Regional aggregators inventory dried and pelletized products for bagged retail and specialty crop markets. California and Washington distribution networks concentrate margin in blending and logistics rather than processing.
- Third-party Vendors:Independent haulers and application contractors serve spot markets with seasonal equipment deployment. Iowa and Nebraska seasonal windows favor outsourced logistics over in-house handling.
Volume concentration favors municipal contracts; margin capture favors direct sales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Midwestern agricultural buyers exhibit acute price sensitivity to synthetic fertilizer parity, while California specialty crop operators absorb premiums for certified organic inputs. Canadian provincial mandates create regulatory-driven demand inelasticity distinct from US spot-market dynamics.
United States
Corn belt cooperatives in Iowa and Illinois expand direct injection programs for phosphorus recovery. EPA Part 503 rule revisions compel municipal utilities to accelerate Class A thermal drying upgrades before compliance deadlines. Texas and Oklahoma processing clusters integrate anaerobic digestion with biogas upgrading for renewable natural gas offtake.
Canada
Ontario corn producers drive contracted land application services under provincial nutrient management regulations. Quebec and Ontario regulators harmonize testing protocols with US federal standards, creating cross-border equipment procurement efficiencies. Thermal drying adoption accelerates in Toronto-area municipal facilities to meet agricultural land application compliance.
Mexico
Central Mexico wastewater infrastructure expansion generates upstream volume for regional processors. National water commission standards for treated sludge disposal remain less stringent than US EPA thresholds, limiting premium product development. Guadalajara and Monterrey municipal utilities represent emerging demand nodes for basic dewatering services.
North America Biosolids Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with national hauling networks commanding volume leadership against regional equipment operators. Municipal contract incumbency creates substantial barriers for new entrants facing decade-long service agreements and compliance reporting requirements. Two strategic archetypes dominate: integrated processors with captive drying capacity and regional haulers with application equipment specialization. Competitive moves concentrate on long-term municipal contract renewals and alkaline hydrolysis technology licensing to smaller wastewater treatment operators.
Within the integrated processor tier, Synagro Technologies exemplifies national-scale contract aggregation, while Lystek International occupies a position as alkaline hydrolysis platform specialists. BCR Environmental anchors the modular system design segment, serving smaller operators navigating capital constraints. These three companies represent distinct competitive vectors: volume leadership through hauling infrastructure, pathogen reduction technology differentiation, and capital-efficient compliance solutions.
| Leading Market Players |
|---|
| BCR Environmental |
| Lystek International |
| Synagro Technologies |
| Englobe |
| Walker Industries Holdings Limited |
| DC Water |
| Merrell Bros., Inc. |
| Terrapure Environmental |
| Casella Waste Systems, Inc. |
| Others |
Value Chain & Pricing Dynamics
EPA Part 503 Class A certification gates both supply qualification and price differentiation simultaneously, creating tiered access where pathogen reduction investments determine agricultural market eligibility and synthetic fertilizer parity anchors value capture.
Pricing Analysis
Long-term municipal service contracts drive lifetime value through decade-long tipping fee structures and renewal premiums. Pricing stratifies across Class A thermal-dried, Class B dewatered cake, and liquid injection tiers based on pathogen reduction certification and transport distance economics. Cost compression in thermal drying operations intensifies because natural gas input volatility erodes margin at Midwest processing clusters. Agricultural cooperatives in Iowa and Illinois exhibit acute price sensitivity to synthetic fertilizer indices, while California almond growers absorb organic certification premiums.
Supply Chain Analysis
Polymer conditioning chemical availability at Gulf Coast petrochemical hubs creates a chokepoint for dewatering operations across the value chain. Raw material flows concentrate in US Midwest agricultural zones, Ontario corn belt regions, and Texas-Oklahoma energy processing clusters. The supply chain draws from municipal wastewater utilities for upstream volume, synthetic fertilizer distributors for pricing benchmarks, and natural gas pipelines for thermal drying energy inputs. Single-source vulnerability runs through long-haul trucking capacity for liquid biosolids seasonal application. Distribution runs through municipal contract structures, direct agricultural offtake agreements, and regional distributor networks for bagged retail.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market tracks a cyclical recovery anchored to agricultural commodity price cycles, where corn and soybean futures directly determine synthetic fertilizer displacement economics and biosolids demand elasticity.
For Market Incumbents: Secure multi-decade municipal contract renewals before EPA Part 503 compliance deadlines crystallize competitive positioning. Invest in captive thermal drying capacity at Ontario and Midwest processing nodes to defend margin against natural gas volatility and regional hauler competition.
For New Entrants and Emerging Players: Differentiate on alkaline hydrolysis technology licensing for smaller wastewater treatment operators facing capital constraints. Target Texas and Oklahoma anaerobic digestion facilities seeking Class A pathogen reduction add-ons for renewable natural gas offtake compliance.
For Investors and Strategic Acquirers: EPA Part 503 rule revisions reshape the acquisition landscape toward integrated processors with proven Class A production track records. Five-to-ten year viability favors municipal contract incumbents with hauling network density over regional equipment specialists. Monitor PFAS testing protocol harmonization across US states and Canadian provinces as the inflection signal for liability repricing.
| Strategic Initiative | Industry Significance |
|---|---|
| Class A Thermal Drying Capacity Expansion | EPA Part 503 compliance deadlines force municipal upgrade investments at Midwest processing clusters. |
| Alkaline Hydrolysis Technology Licensing | Smaller wastewater operators adopt modular pathogen reduction to navigate capital constraints. |
| Anaerobic Digestion Biogas Integration | Texas and Oklahoma facilities combine Class A production with FERC pipeline injection agreements. |
| Long-term Agricultural Service Contracts | Corn Belt cooperatives outsource nutrient management planning to specialized regional operators. |
| PFAS Testing Infrastructure Investment | State-level concentration limits create first-mover advantage in liability-compliant supply qualification. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with municipal wastewater utility managers, agricultural cooperative procurement directors, thermal drying facility process engineers, and EPA regional compliance officers. Secondary validation drew from EPA Part 503 regulatory filings, USDA Environmental Quality Incentives Program enrollment data, Ontario Ministry of Agriculture nutrient management plan records, and municipal bond disclosures for wastewater infrastructure capex. Bottom-up volume estimates triangulated against top-down agricultural land application acreage projections.
Across the analysis window, the forecasting framework modeled product form segmentation by pathogen class, application channel by end-use eligibility, and geographic cluster by regulatory regime alignment. CAGRs were derived from synthetic fertilizer price elasticity correlations and municipal contract renewal probability weightings. Industry-specific inputs included natural gas benchmark volatility coefficients and corn-soybean planting intention surveys.
Forecasts assume regulatory continuity in EPA Part 503 and Ontario Nutrient Management Act regimes; material policy shifts would require re-modeling pathogen reduction technology adoption curves. Practitioners should keep alternative scenarios live as PFAS federal threshold harmonization and state-level concentration limit enforcement evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Environmental Biotechnology
Global Anaerobic Digestion Market
Environmental Biotechnology
Plastic-Eating Bacteria Market
Environmental Biotechnology
Bio-Detection Market
Environmental Biotechnology
Europe Anaerobic Digestion Market
Environmental Biotechnology
Bioremediation Market
Environmental Biotechnology
Blue Biotechnology Market
Environmental Biotechnology
Global Bio Decontamination Market
Environmental Biotechnology
Enzymatic Cleaning Market