
 Baby Nipple/Teat Market | 2026-2036
Baby Nipple/Teat Market Size, Share, and Industry Trends Forecast 2026-2036
Baby Nipple/Teat Market Analytics
Specialty baby retail is narrowing as e-commerce platforms and direct-to-parent subscription models capture volume once held by traditional brick-and-mortar chains. Pigeon Corporation leverages its manufacturing scale to dominate Asian pharmacy and maternity hospital channels. Koninklijke Philips N.V. (Philips Avent) sustains R&D intensity across European markets with clinical-grade flow-rate engineering. Mayborn Group (Tommee Tippee) competes through brand strength in Anglo-American big-box retail, though its geographic footprint remains narrower than rivals.
A baby nipple or teat is a flexible, flow-controlled feeding interface typically molded from silicone, natural latex, or thermoplastic elastomer, designed to simulate maternal anatomy and regulate liquid delivery during infant feeding. Medical-grade liquid silicone rubber dominates premium manufacturing due to thermal stability, hypoallergenic properties, and compliance with repeated sterilization cycles. Silicone material commands the widest margin pool as parents prioritize durability and odor resistance over lower-cost rubber alternatives. Anti-colic design is the fastest-growing structural segment, driven by clinical validation of vented systems that reduce swallowed air and infant gastrointestinal distress.
FDA regulates teat composition and choking hazard dimensions under 16 CFR Part 1511, while the EU Green Deal and REACH restrict phthalate and bisphenol migration in elastomer formulations sold across European member states. BIS certification in India mandates migration testing for volatile substances, creating compliance barriers for uncertified imports. Stakeholders must monitor how fragmented national standards for flow-rate testing reshape product development roadmaps and regional launch sequencing.
Market Dynamics
Hospital procurement departments are consolidating supplier relationships around anti-colic vented systems, creating volume concentration that favors manufacturers with clinical validation data and sterilization-durable silicone formulations.
Growth Catalysts
- REACH substance restrictions:The EU Green Deal's tightening limits on phthalate migration in elastomer products are accelerating formulation upgrades toward medical-grade liquid silicone rubber, opening premium positioning for compliant suppliers.
- Maternity hospital channel expansion:Institutional buyers in China and India are specifying anti-colic designs for newborn feeding protocols, creating anchored demand streams that reduce customer acquisition costs for certified vendors.
- Silicone thermal stability:The material's resistance to repeated autoclave cycles supports extended product lifespans, justifying higher price points among parents prioritizing durability over natural latex alternatives.
Market Restraints
- Raw material concentration:Medical-grade liquid silicone rubber supply concentrates among a limited pool of specialty chemical producers, creating input cost volatility that compresses margin flexibility for finished goods manufacturers.
- BIS certification timelines:India's mandatory migration testing for volatile substances extends product launch cycles by 8-14 months for uncertified imports, creating compliance barriers that favor established domestic assemblers.
- Natural latex substitution:Lower-cost rubber alternatives retain price-sensitive segments despite inferior odor resistance and sterilization degradation, capping silicone penetration in economy-tier distribution.
Strategic Opportunities
- Direct-to-parent subscription models:E-commerce platforms are capturing volume once held by brick-and-mortar specialty retailers, enabling recurring revenue streams through age-based nipple flow-rate replacement schedules.
- Indian domestic manufacturing:BIS certification requirements create localization incentives for foreign suppliers to establish captive production facilities serving the South Asian market.
- Clinical-grade flow-rate engineering:Convergence of pediatric feeding research with precision molding technology enables differentiated positioning through peer-validated reduction in infant gastrointestinal distress.
Industry Challenges
- Multi-jurisdiction compliance talent:Manufacturers face scarcity of regulatory affairs specialists capable of navigating simultaneous FDA 16 CFR Part 1511, REACH, and BIS filing requirements without launch delays.
- Legacy sterilization infrastructure:Hospital buyers with capital-tied autoclave systems resist migrating to novel materials requiring alternative sterilization protocols, creating adoption friction for next-generation formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Baby Nipple/Teat Market |
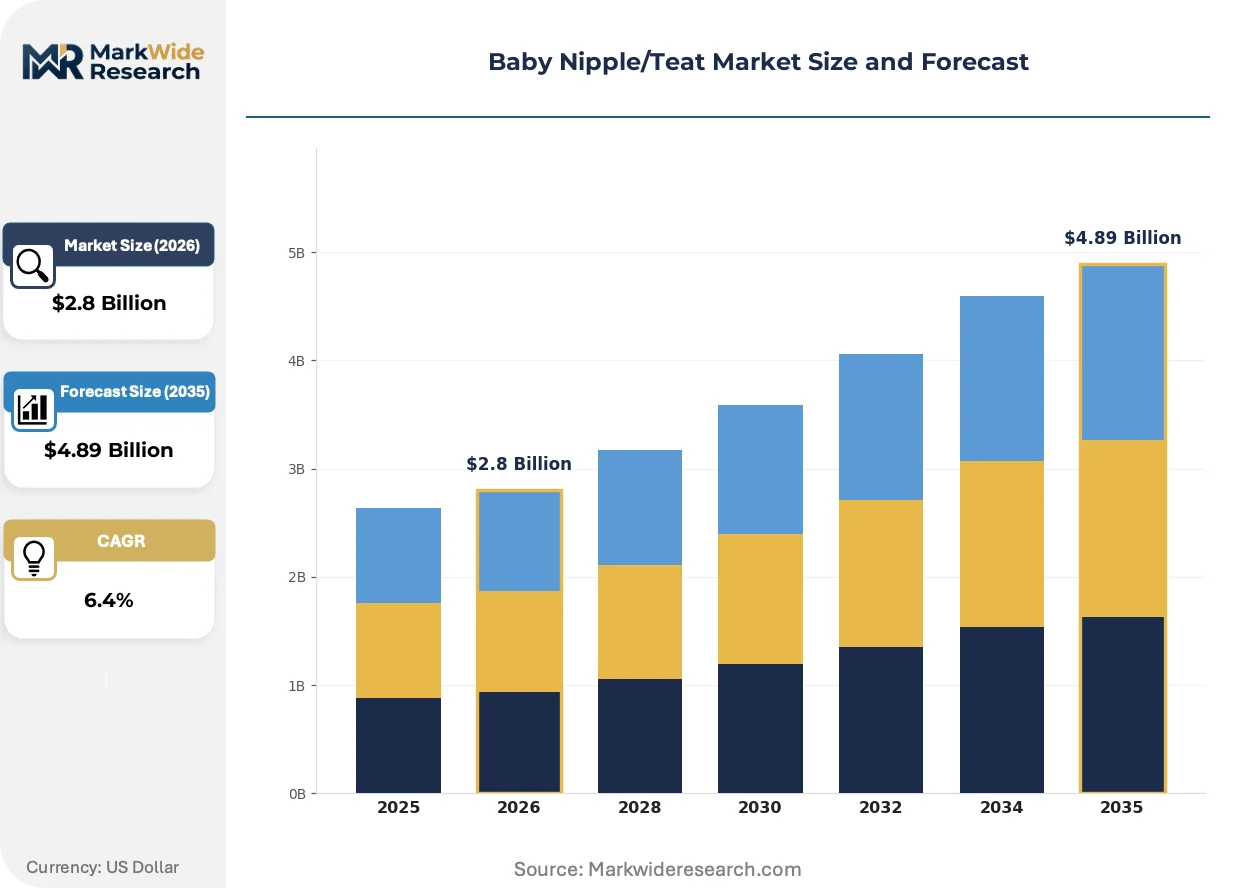
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.89 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material: Silicone, Rubber, Natural Latex, Polypropylene Design: Wide Neck, Standard Neck, Orthodontic, Anti-Colic Flow Rate: Slow Flow, Medium Flow, Fast Flow, Variable Flow End User: Parents, Daycare Centers, Hospitals, Retailers |
| Companies Covered | Koninklijke Philips N.V. (Philips Avent), Pigeon Corporation, Mayborn Group (Tommee Tippee), Newell Brands (NUK), Chicco (Artsana S.p.A.), Hegen, Medela AG, Abbott Laboratories, Dr. Brown's, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Baby Nipple/Teat Market Evolving Landscape
Product development is converging on biomimetic flow control and connected monitoring capabilities, while regulatory fragmentation forces parallel certification tracks across major economies.
Vented anti-colic architecture is migrating from premium positioning toward standard equipment across hospital and retail channels. Neonatal intensive care units in China and India are specifying these systems for early feeding protocols. The technology is migrating from discretionary upgrade to baseline expectation, compressing margin pools for non-vented legacy designs and forcing rapid R&D catch-up among lagging suppliers.
REACH substance restrictions and the EU Green Deal are tightening migration limits for bisphenol and phthalate compounds in elastomer formulations. Manufacturers serving European member states must reformulate toward compliant silicone grades or exit the market. Pediatric equipment suppliers with established medical-grade supply chains are absorbing compliance costs more efficiently than consumer-grade competitors, reshaping competitive tiers.
Parents are consolidating purchase decisions around e-commerce platforms and subscription services that automate flow-rate progression as infants develop. Traditional pharmacy and big-box retail channels are losing traffic to direct-to-consumer models offering personalized replacement scheduling. This behavioral shift is most visible in Anglo-American markets where digital-native millennial parents dominate newborn product research and purchasing.
Baby Nipple/Teat Market Segmentation
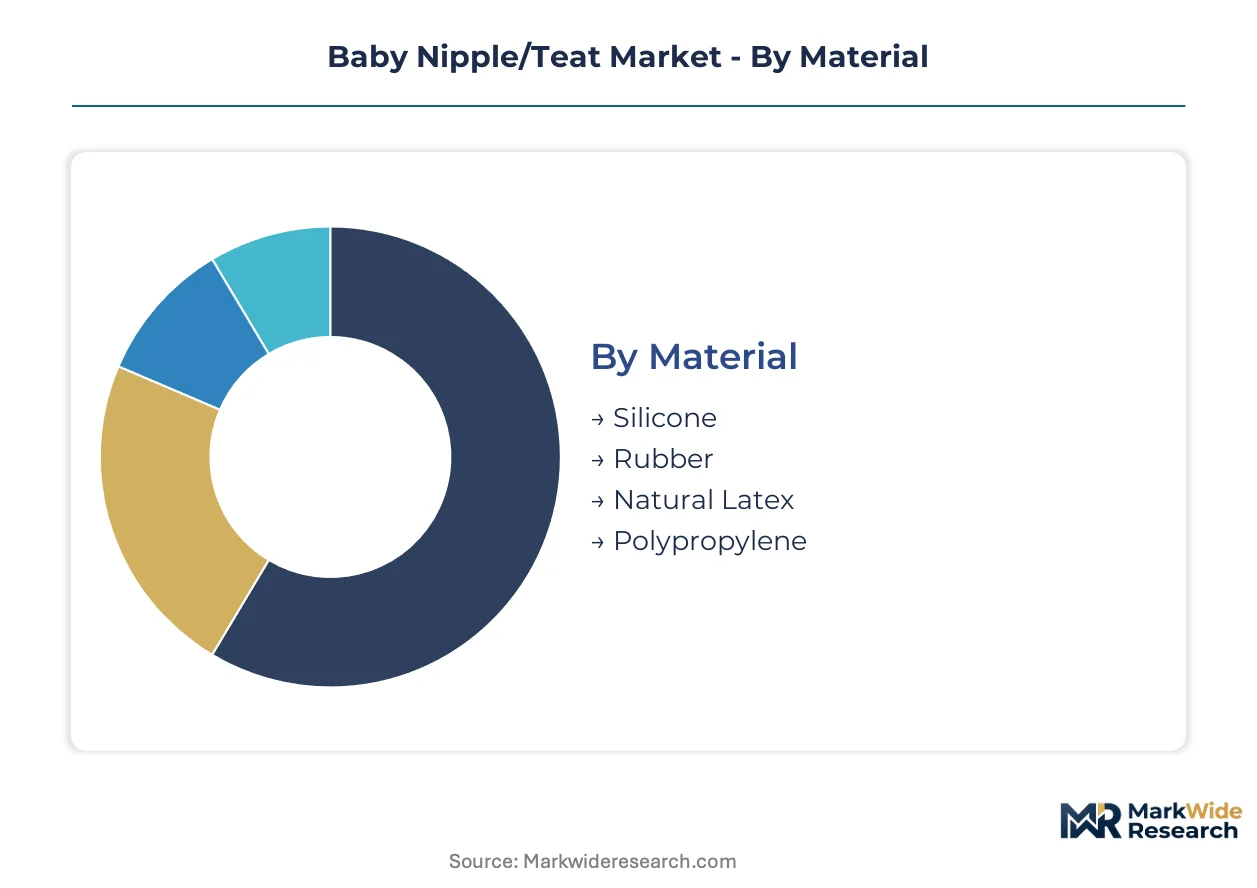
Material selection determines sterilization tolerance and replacement cadence across this market. Design architecture and flow-rate calibration shape purchasing patterns by infant developmental stage and feeding context.
Material:
Silicone formulations command the shortest replacement cycles due to wear visibility, while natural latex degrades faster but costs less per unit.
- Silicone:Medical-grade liquid silicone rubber delivers thermal stability across autoclave cycles and resists odor absorption. Hospital procurement in China specifies this material for newborn intensive care protocols, prioritizing durability over per-unit cost in institutional purchasing.
- Rubber:Synthetic rubber compounds occupy economy-tier retail positioning with inferior heat tolerance and faster surface degradation. Price-sensitive segments in India favor this material despite accelerated replacement schedules.
- Natural Latex:Harvested from Hevea brasiliensis with inherent elasticity mimicking maternal tissue, though protein content triggers allergy concerns in clinical settings.
- Polypropylene:Rigid thermoplastic used in collar and ring components rather than the teat itself, valued for chemical resistance in high-temperature sterilization environments.
Silicone dominates installed base in premium channels. Rubber is where expansion concentrates in emerging economy retail.
Design:
Neck geometry shapes bottle compatibility and parental brand loyalty, while functional architecture determines clinical adoption rates.
- Anti-Colic:Vented internal channels redirect swallowed air away from the infant stomach, reducing colic symptoms validated in pediatric feeding studies. Maternity hospitals in India and China specify these systems for early feeding protocols, creating anchored demand streams.
- Orthodontic:Asymmetric nipple profiles support palatal development and proper tongue positioning during suckling. European parents favor this design for extended feeding durations beyond six months.
- Wide Neck:Broad base diameter simplifies cleaning access and supports thicker formula flow, popular in North American big-box retail.
- Standard Neck:Narrow traditional profile maintains compatibility with legacy bottle systems, retaining volume in replacement-purchase scenarios.
Standard neck dominates installed base. Anti-colic is where expansion concentrates.
Flow Rate:
Age-appropriate calibration determines feeding safety and infant satiety, with progression schedules driving subscription replenishment models.
- Variable Flow:Adjustable aperture mechanisms accommodate shifting suction strength without nipple replacement, reducing inventory complexity for multi-infant daycare operations.
- Slow Flow:Restricted orifices suit newborn feeding with limited suckling strength, specified for preterm infants in hospital discharge kits.
- Medium Flow:Balanced delivery rate for infants aged three to six months, representing the highest-volume replacement segment in direct-to-parent subscription services.
- Fast Flow:Maximum aperture diameter for cereal-thickened formulas and infants over six months, with shorter usage windows per child.
Medium flow dominates installed base. Variable flow is where expansion concentrates.
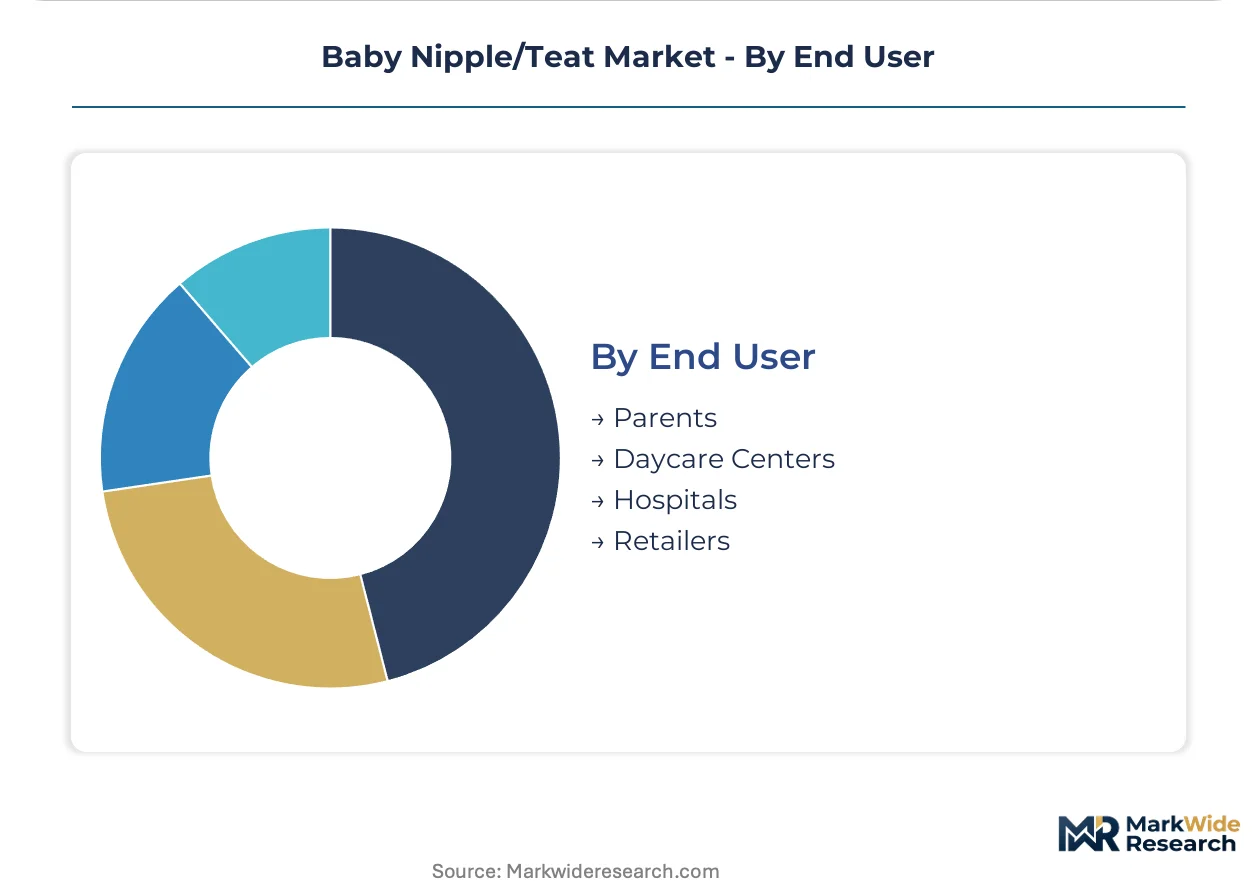
End User:
Procurement authority and volume scale vary sharply across customer types, from individual discretion to institutional tender processes.
- Hospitals:Maternity wards and neonatal units specify anti-colic silicone systems through centralized procurement, creating volume concentration around clinically validated suppliers with sterilization documentation.
- Parents:Individual purchasers research flow-rate progression and material safety online, consolidating decisions around e-commerce platforms with subscription automation.
- Daycare Centers:Multi-infant facilities prioritize standardization and rapid sanitization turnaround, favoring wide-neck designs compatible with commercial dishwashing protocols.
- Retailers:Pharmacy chains and specialty baby stores curate assortment by margin tier, allocating shelf space to brands with proven inventory velocity.
Parents dominate installed base. Hospitals is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium silicone teats command 40% price premiums in German pharmacy channels versus economy rubber alternatives dominating Indian mass retail, creating divergent margin architectures across geographies.
United States
FDA 16 CFR Part 1511 enforcement drives choking-hazard testing investments, while direct-to-parent subscription models capture volume from declining brick-and-mortar specialty chains. Greater Boston anchors pediatric feeding research clusters where clinical validation partnerships with NICU networks shape product development pipelines.
Germany
REACH substance restrictions and EU Green Deal phthalate limits accelerate medical-grade silicone formulation upgrades. Baden-Württemberg hosts precision molding equipment suppliers serving compliant manufacturers absorbing certification costs more efficiently than consumer-grade competitors.
China
Stabilizing domestic birth rates concentrate demand for premium silicone products as maternity hospitals specify anti-colic vented systems for newborn protocols. SAMR oversight of GB standards for infant feeding products tightens migration testing requirements, favoring domestic assemblers with established certification pathways.
India
BIS certification mandates for volatile substance migration testing extend launch cycles 8-14 months for uncertified imports, creating localization incentives for foreign suppliers. Maharashtra and Gujarat host emerging domestic production facilities serving price-sensitive mass retail segments where synthetic rubber retains volume share.
Japan
METI industrial standards for infant product safety sustain premium positioning for medical-grade liquid silicone rubber formulations. Kansai region manufacturing clusters leverage precision molding heritage to supply orthodontic design segments favored by parents extending feeding durations beyond six months.
Baby Nipple/Teat Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying medical-grade elastomer formulations and precision molding equipment. The vendor base organizes around three tiers: multinational consumer health conglomerates with clinical validation infrastructure, regional specialists dominating maternity hospital procurement channels, and private-label assemblers serving economy retail segments. Dominant competitive moves include geographic expansion through BIS-compliant manufacturing localization and portfolio diversification into subscription-based flow-rate replacement services.
Among Asia-Pacific headquartered specialists, Pigeon Corporation exemplifies the hospital-channel archetype with manufacturing scale advantages in pharmacy and maternity procurement networks. Koninklijke Philips N.V. (Philips Avent) occupies the R&D-intensive position with European clinical-grade flow-rate engineering capabilities. Mayborn Group (Tommee Tippee) represents brand-driven Anglo-American retail positioning, though with narrower geographic footprint than rivals.
| Leading Market Players |
|---|
| Koninklijke Philips N.V. (Philips Avent) |
| Pigeon Corporation |
| Mayborn Group (Tommee Tippee) |
| Newell Brands (NUK) |
| Chicco (Artsana S.p.A.) |
| Hegen |
| Medela AG |
| Abbott Laboratories |
| Dr. Brown's |
| Others |
Value Network & Pricing Analysis
Undercapacity in medical-grade liquid silicone rubber production across East Asian specialty chemical plants is tightening input availability and forcing finished goods manufacturers to absorb cost volatility through pricing adjustments or formulation downgrades.
Pricing Analysis
The customization-premium spread between hospital-configured anti-colic systems and standard retail SKUs spans three distinct pricing tiers across premium silicone, mid-grade thermoplastic elastomer, and economy rubber alternatives. Price differentiation centers on FDA 510(k) equivalence certification and REACH-compliant formulation grades, with German pharmacy channels commanding the widest spreads. Pricing pressure stems from raw material concentration among Japanese and South Korean silicone suppliers, compressing margin flexibility for European and North American assemblers. Hospital procurement departments exhibit the lowest price sensitivity due to clinical validation requirements, while Indian mass retail buyers prioritize per-unit cost over durability specifications.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk planning for multinational teat manufacturers with cross-border component flows. Geographic supply concentration centers on China for precision molding equipment, Japan for medical-grade silicone formulations, and Germany for high-tolerance injection molding systems. Raw material dependencies include liquid silicone rubber from Shin-Etsu and Dow Corning supply chains, polypropylene collar resins from Sinopec and LyondellBasell, and anti-colic vent membranes from specialized Taiwanese film producers. Single-source vulnerability persists for autoclave-compatible silicone grades certified to FDA 16 CFR Part 1511. Distribution runs through hospital GPO contracts in China and India, direct-to-parent subscription platforms in Anglo-American markets, and pharmacy chains across Continental Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is recovering from a cyclical trough driven by post-pandemic birth rate normalization in China and India, with institutional procurement volumes now expanding ahead of retail replacement demand.
For Market Incumbents: Insulate margin pools by securing captive supply of medical-grade liquid silicone rubber through backward integration into Japanese or South Korean chemical partnerships, while accelerating BIS certification for Indian domestic production to preempt compliance barriers. Channel control through maternity hospital GPO contracts in China and India remains the critical defensive lever against direct-to-consumer subscription entrants. R&D investment should concentrate on clinical-grade flow-rate validation partnerships with neonatal intensive care research networks. For New Entrants and Emerging Players: Southeast Asian hospital procurement channels in Vietnam, Indonesia, and Thailand represent the most penetrable geographic whitespace, with anti-colic silicone systems specified at rates below Chinese and Indian penetration levels. Subscription-based flow-rate replacement services targeting Anglo-American millennial parents offer the fastest customer acquisition pathway outside institutional channels. A go-to-market angle anchored in pediatric feeding study partnerships with regional medical universities differentiates against established brand recognition. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among direct-to-parent subscription platforms with automated age-based replacement scheduling, positioning these archetypes for premium valuation multiples over transactional retail-dependent competitors. Long-term viability across the analysis window favors manufacturers with simultaneous FDA, REACH, and BIS certification infrastructure, as regulatory fragmentation intensifies compliance capital requirements. The signal to watch is hospital procurement consolidation around sterilization-durable silicone formulations in China and India, indicating volume concentration that rewards scaled clinical validators over consumer-grade assemblers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silicone Supply | Captive sourcing from Shin-Etsu or Dow Corning affiliates reduces input cost volatility for hospital-grade production. |
| BIS Certification Localization | Maharashtra and Gujarat production facilities bypass 8-14 month import testing timelines for Indian market access. |
| Direct-to-Parent Subscription Launch | Automated flow-rate progression captures millennial parents migrating from pharmacy and big-box retail channels. |
| Clinical Validation Partnership | Peer-reviewed NICU studies in Greater Boston or Baden-Württemberg anchor anti-colic positioning against commodity competitors. |
| Anti-Colic Design Standardization | Vented architecture migration from premium to baseline specification compresses margin pools for non-compliant legacy suppliers. |
Research Methodology
Initial hypotheses were tested against primary input from hospital procurement managers, neonatal intensive care clinicians, regulatory affairs specialists at multinational consumer health companies, and category buyers at Anglo-American pharmacy chains, then refined through secondary validation against FDA 510(k) filings, BIS certification registries, SAMR GB standard updates, and customs trade data for medical-grade elastomer imports. Bottom-up demand modeling from hospital discharge kit specifications and retail SKU velocity data was triangulated against top-down market sizing from silicone raw material consumption disclosures.
Demand-supply balance dynamics across the analysis window were modeled through segmentation by material grade, design architecture, flow-rate calibration, and end-user procurement authority, with CAGRs derived from infant demographic projections and replacement cycle assumptions tied to sterilization durability testing. Forecast inputs included maternity hospital anti-colic specification rates in China and India, REACH substance restriction implementation timelines, and e-commerce platform subscription penetration curves in North American and Western European markets.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese domestic assemblers or accelerated FDA clearance pathways by emerging entrants would shift outcomes beyond modeled ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Baby Products
AI Smart Baby Monitors Market
Baby Products
Baby Nose Suckers Market
Baby Products
Baby Portable Co-Sleeper Market
Baby Products
Baby High Chair Market
Baby Products
Feeding Bra Market
Baby Products
Luxury Baby Stroller Market
Baby Products
Baby Wet Wipes Market
Baby Products
Postpartum Products Market
Baby Products
Global Baby Mattresses Market
Baby Products
Global Smart Connected Baby Monitors Market
Baby Products
China Maternity Goods Market
Baby Products
Asia-Pacific Baby Care Products Market
Baby Products
Crib Mattress Market
Baby Products
Stroller Rental Market
Baby Products
Baby Digital Monitor Market
Baby Products
Baby Food Dispensing Spoon Market