
 Australia Denim Jeans Market | 2026-2036
Australia Denim Jeans Market Size, Share, and Industry Trends Forecast 2026-2036
Australia Denim Jeans Market Insights
Multi-source fabric procurement is broadening across Australian denim manufacturers seeking supply chain resilience. Nobody Denim Online Pty Ltd. leverages domestic cut-make-trim partnerships to sustain shorter lead times for premium selvedge lines. Outland Denim anchors its competitive edge through transparent employment programs that differentiate its brand narrative in crowded specialty retail channels.
Denim jeans constitute twill-woven cotton garments with indigo-dyed warp threads, typically constructed from 12–14 ounce fabric weights that deliver structural durability and aesthetic fading characteristics over repeated wear cycles. Skinny fit and tapered fit categories dominate unit volumes among young adult demographics, while organic cotton and recycled denim fabric types command margin premiums as sustainability credentials reshape consumer willingness-to-pay thresholds. Specialty stores and online retailers concentrate distribution power, though market stalls retain relevance in seasonal fashion circuits across Melbourne and Sydney.
Australian Competition and Consumer Commission product safety mandates govern flammability and labeling standards, while the ACCC's consumer guarantees framework shapes warranty and return obligations that online retailers must integrate into digital storefronts. The Woolmark Company's fiber certification protocols and Australian Made Campaign Limited labeling rules further constrain market access for imports lacking verified provenance documentation. Stakeholders must monitor how evolving textile recycling regulations and potential extended producer responsibility schemes will reshape raw material sourcing economics and post-consumer collection infrastructure requirements.
Market Dynamics
Ethical sourcing mandates and recycled fiber manufacturing standards are compressing lead times for Australian denim producers while elevating compliance costs across Victoria and New South Wales supply chains.
Growth Catalysts
- Australian Competition and Consumer Commission product safety standards:Mandatory flammability testing and labeling protocols are filtering out low-quality imports, creating protected market space for compliant domestic manufacturers.
- Recycled denim manufacturing:Mechanical recycling of post-consumer cotton waste into new warp yarns is reducing virgin cotton dependence and attracting sustainability-focused young adult buyers in Sydney and Melbourne.
- Direct-to-consumer online channels:Boutique denim brands are bypassing wholesale markups through owned digital storefronts, capturing margin premiums from urban consumers seeking selvedge and raw denim specialties.
Market Restraints
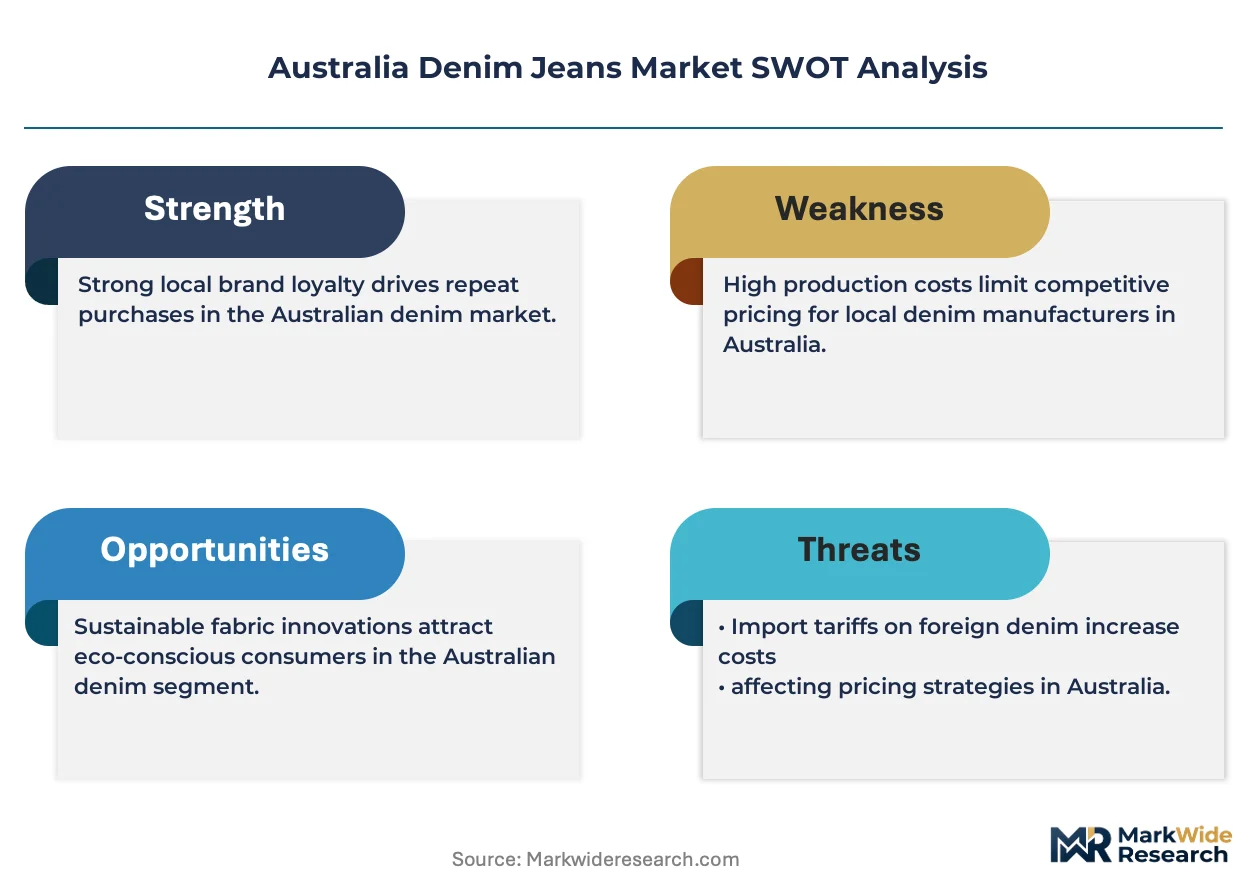
- Organic cotton input cost volatility:Australian organic cotton acreage constraints and irrigation water allocation pressures are elevating raw material costs for premium denim lines.
- Cut-make-trim concentration in Victoria:Domestic garment finishing capacity clusters disproportionately in Melbourne, exposing supply chains to localized labor shortages and logistics bottlenecks.
- Technical limitation in closed-loop recycling:Current mechanical shredding processes degrade cotton fiber length, limiting the recycled content ratio achievable in high-durability 12-14 ounce denim fabrics.
Strategic Opportunities
- Underpenetrated Western Australia:Perth's boutique retail density lags Sydney and Melbourne, presenting first-mover positioning for direct-to-consumer denim brands with sustainable credentials.
- Extended producer responsibility schemes:Anticipated textile waste collection mandates will reward brands with established post-consumer take-back infrastructure and resale channel partnerships.
- Laser finishing technology convergence:Integration of laser surface treatment with ozone washing is eliminating water-intensive stone washing while enabling localized small-batch production.
Industry Challenges
- Specialized pattern-making skill scarcity:Domestic expertise in selvedge denim pattern engineering is concentrated among aging craftspeople, constraining premium line expansion for emerging labels.
- Australian Made Campaign Limited certification timelines:Provenance verification documentation requirements are extending product launch schedules for brands sourcing blended fiber compositions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia Denim Jeans Market |
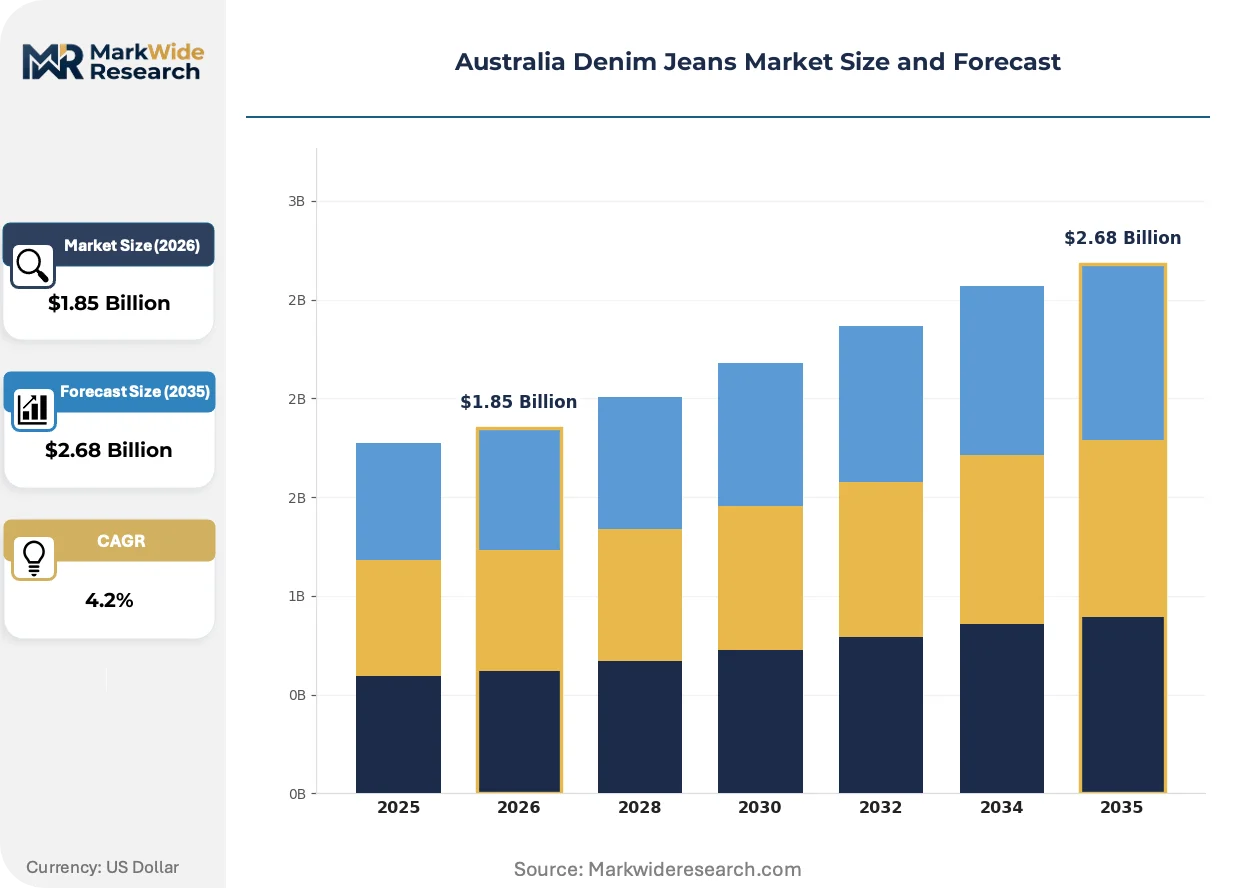
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $2.68 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Straight Fit, Skinny Fit, Bootcut, Relaxed Fit, Tapered Fit, Wide Leg Fabric Type: Stretch Denim, Organic Cotton, Selvedge Denim, Raw Denim, Recycled Denim Target Consumer: Teens, Young Adults, Middle-aged Adults, Seniors, Plus Size Distribution Channel: Specialty Stores, Online Retailers, Department Stores, Boutiques, Market Stalls |
| Companies Covered | Godspeed, Neuw, Nobody Denim Online Pty Ltd., Flux Denim, R.M. Williams, Outland Denim, Ksubi, Denimsmith, Rolla's, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia Denim Jeans Market Trends and Innovations
Digital product passports and waterless finishing technologies are disrupting traditional denim manufacturing economics while consumer transparency expectations reshape brand communication strategies.
Laser-based surface distressing equipment is modularizing production workflows across Australian cut-make-trim facilities. Small-batch manufacturers in Melbourne are adopting configurable laser systems that switch between whiskering, knee abrasion, and pocket fading patterns without hardware changeovers. This flexibility is compressing minimum viable order quantities and enabling made-to-measure denim services previously uneconomical at domestic wage rates.
Australian Competition and Consumer Commission consumer guarantee enforcement is tightening warranty obligations for online denim retailers. Digital storefronts must now integrate explicit durability disclosures and return logistics for fit-related claims, elevating operational complexity. Specialty e-commerce operators are responding by investing in virtual try-on tools and detailed size calibration databases to reduce return rates.
Young adult buyers in Sydney and Melbourne are rotating toward circular ownership models including resale platforms and rental subscriptions. Traditional retail channels are losing volume to peer-to-peer marketplaces where authenticated pre-owned selvedge denim commands price premiums based on wear patterns. This behavioral shift is most visible among 25-34 year old consumers in inner-urban postcodes with established vintage fashion circuits.
Australia Denim Jeans Market Segmentation
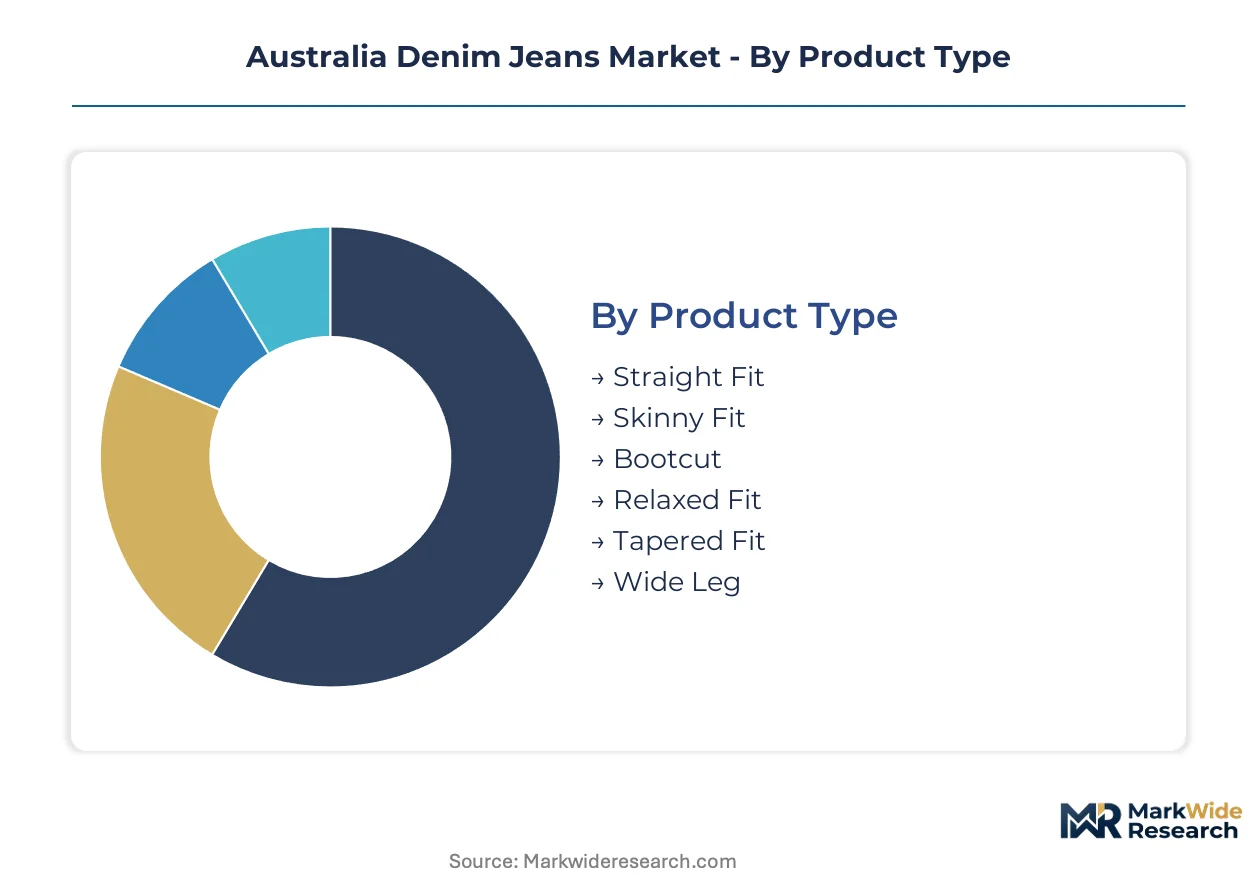
Denim segmentation in Australia reflects divergent paths between volume-driven mass retail and premium artisanal channels. Fabric provenance and fit specialization now determine margin architecture more than brand heritage alone.
Product Type:
Volume concentrates in fitted silhouettes while heritage cuts retain pricing power in specialty channels.
- Straight Fit:Classic leg profile with consistent width from hip to ankle, constructed from 12-14 ounce fabrics. Demand clusters among middle-aged buyers in suburban Melbourne retail precincts seeking versatile work-to-casual transition pieces.
- Skinny Fit:Tapered leg with reduced knee and ankle circumference, often incorporating elastane blends for recovery. Young adult consumers in Sydney's inner-urban postcodes drive unit volumes, prioritizing silhouette definition over long-term durability.
- Bootcut:Flared leg opening accommodating footwear stacks, traditionally constructed from rigid denim. Regional Queensland and Western Australia retain pockets of demand among agricultural and trades workers.
- Relaxed Fit:Generous seat and thigh dimensions with straight or tapered leg options. Plus-size and senior demographics in Adelaide and Perth suburban centers favor this category for comfort-driven purchase decisions.
- Tapered Fit:Roomier thigh transitioning to narrow ankle, bridging skinny and straight aesthetics. Melbourne's design-conscious young adults are migrating toward this hybrid silhouette as raw denim interest expands.
- Wide Leg:Dramatically expanded leg opening with high-rise waist positioning, typically in rigid 14+ ounce constructions. Boutique channels in Sydney's Paddington and Melbourne's Fitzroy are cultivating this retro-influenced segment.
Today's leader: Skinny Fit. Tomorrow's challenger: Tapered Fit.
Fabric Type:
Raw material certification tiers now separate premium positioning from commodity competition.
- Stretch Denim:Cotton-elastane blends enabling recovery and compression, dominating mass-market unit economics. Young adult female consumers in Sydney's eastern suburbs sustain demand despite sustainability concerns about synthetic fiber content.
- Organic Cotton:GOTS-certified fiber with restricted pesticide and water inputs, commanding 40-60% wholesale premiums. Victoria and New South Wales specialty retailers are expanding shelf space as ACCC greenwashing enforcement intensifies.
- Selvedge Denim:Shuttle-loomed fabric with self-finished edge, traditionally from Japanese or domestic narrow-width looms. Melbourne's selvedge enthusiasts drive small-batch production through direct-to-consumer channels.
- Raw Denim:Unwashed indigo-dyed fabric requiring break-in periods, prized for personalized fading patterns. Sydney's 25-34 male demographic is expanding this category through resale platform authentication.
- Recycled Denim:Mechanical or chemical processing of post-consumer cotton into new warp yarns, reducing virgin fiber dependence. ACCC product safety standards and emerging extended producer responsibility schemes are accelerating brand adoption.
Organic Cotton captures current margin premiums. Recycled Denim faces steepest expansion trajectory as compliance mandates harden.
Target Consumer:
Age-cohort purchasing patterns diverge sharply between digital-native and store-loyal segments.
- Teens:Price-sensitive demographic purchasing through fast-fashion online platforms and social commerce. Sydney and Melbourne secondary school catchments concentrate demand for trend-responsive skinny and wide-leg silhouettes.
- Young Adults:Primary volume driver across all channels, prioritizing sustainability credentials and fit experimentation. Inner-urban postcodes in Fitzroy, Newtown, and Surry Hills sustain premium denim boutique density.
- Middle-aged Adults:Quality-per-dollar focused, favoring straight and relaxed fits from established domestic manufacturers. Suburban shopping centers in Brisbane and Perth retain this cohort's loyalty.
- Seniors:Comfort and accessibility priorities driving relaxed fit and elastic-waist modifications. Regional Victoria and New South Wales towns with aging populations present underpenetrated distribution opportunities.
- Plus Size:Underserved segment demanding extended size runs with proportional pattern engineering. Online specialty retailers are capturing this demand as mainstream brands limit size range investments.
Young Adults anchor present revenue. Plus Size offers the most significant white-space expansion.
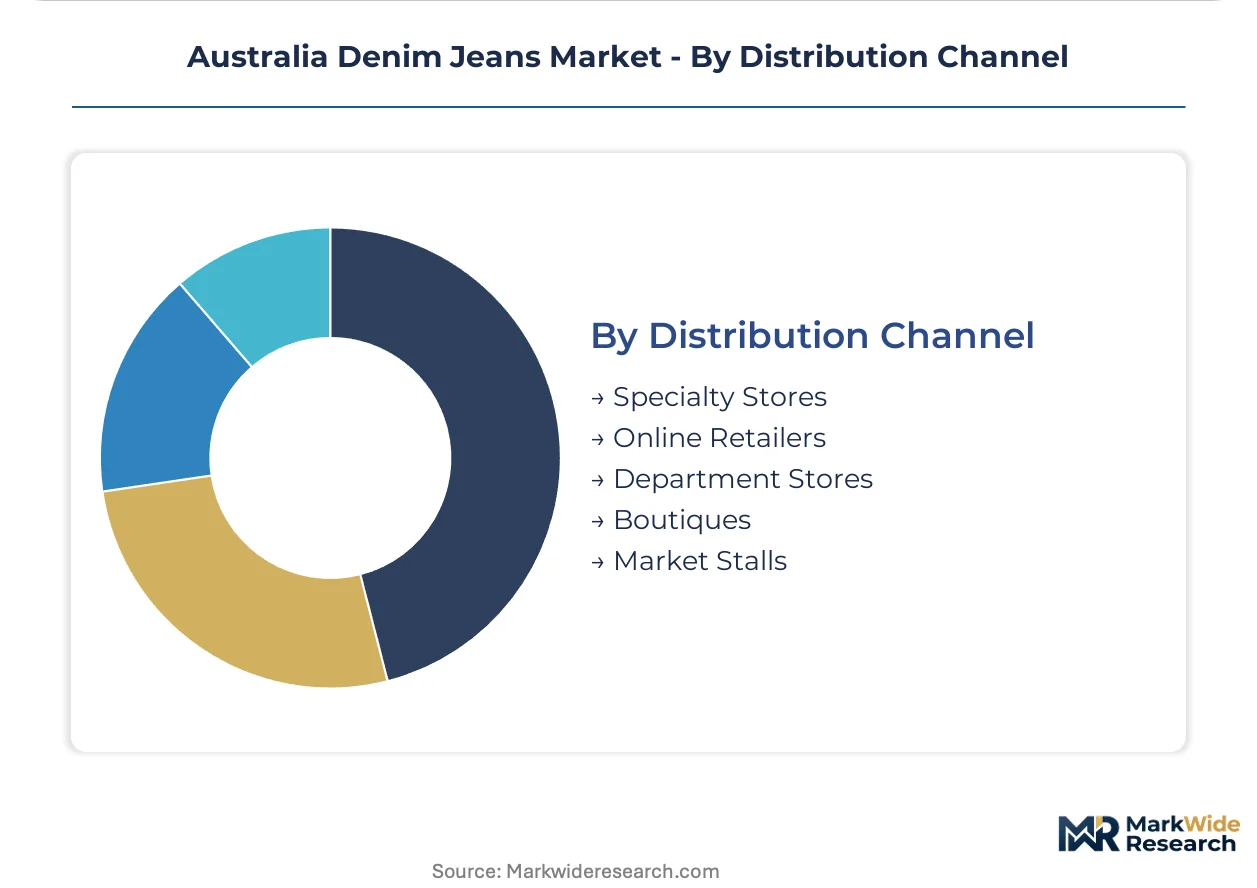
Distribution Channel:
Channel mix is compressing toward owned digital and curated physical experiences.
- Specialty Stores:Curated denim-focused retail with trained fit specialists and alteration services. Melbourne's Chapel Street and Sydney's Oxford Street clusters sustain this channel despite rent pressures.
- Online Retailers:Owned digital storefronts and multi-brand platforms capturing margin through direct consumer relationships. Virtual try-on investments are reducing fit-related return rates for Melbourne-based operators.
- Department Stores:Mid-market positioning with private label and licensed brand portfolios. Myer and David Jones are consolidating denim floor space as online penetration erodes foot traffic.
- Boutiques:Independent retailers emphasizing local designer discovery and experiential merchandising. Adelaide and Hobart are developing boutique density as Melbourne and Sydney saturate.
- Market Stalls:Seasonal and weekend trading at Melbourne's Queen Victoria Market and Sydney's Paddington Markets. Vintage and reworked denim specialists dominate this channel's value proposition.
Specialty Stores hold current premium positioning. Online Retailers are gaining share fastest through logistics infrastructure investments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Melbourne's cut-make-trim cluster anchors Australian denim manufacturing, concentrating garment finishing capacity and skilled pattern-making labor in Victoria while Sydney's retail density drives premium consumption patterns.
New South Wales
Sydney's Oxford Street and Paddington boutique corridors concentrate specialty denim retail, with inner-urban postcodes in Surry Hills and Newtown sustaining direct-to-consumer brand flagship density. Australian Competition and Consumer Commission consumer guarantee enforcement shapes warranty obligations for online retailers headquartered here. The state's logistics infrastructure supports same-day delivery networks that compress lead times for Melbourne-manufactured goods.
Victoria
Melbourne's Brunswick and Collingwood industrial zones host domestic cut-make-trim facilities serving premium selvedge and raw denim lines. Australian Made Campaign Limited certification timelines constrain product launch schedules for brands sourcing blended fiber compositions. The city's design education institutions feed specialized pattern-making expertise into local manufacturers, though aging craftsperson demographics threaten succession pipelines.
Queensland
Brisbane's suburban shopping centers sustain middle-aged consumer loyalty to straight and relaxed fit categories from established domestic manufacturers. The state's agricultural workforce retains demand for bootcut silhouettes in regional centers. Queensland's distance from Melbourne manufacturing clusters elevates freight costs and extends replenishment cycles for fast-turning fashion lines.
Western Australia
Perth's boutique retail density lags Sydney and Melbourne benchmarks, presenting first-mover positioning for sustainable direct-to-consumer denim brands. The state's isolation from eastern manufacturing centers has historically limited specialty denim access. Emerging local distribution partnerships are reducing delivery friction for Melbourne-based producers targeting Western Australian young adult consumers.
South Australia
Adelaide's suburban centers concentrate relaxed fit demand among senior demographics seeking comfort-driven purchase options. The city's developing boutique density in laneway retail precincts mirrors Melbourne's experiential merchandising models. South Australia's aging regional populations present underpenetrated distribution opportunities for extended size range specialists.
Australia Denim Jeans Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue sustainability differentiation and circular ownership models. The market structures around three tiers: heritage workwear specialists, premium selvedge artisans, and digital-native sustainability brands. Competitive moves concentrate on direct-to-consumer channel expansion and domestic manufacturing partnerships that compress lead times.
Within the premium artisan tier, Nobody Denim Online Pty Ltd. and Outland Denim exemplify positioning strategies built on transparent supply chain narratives. Among heritage-rooted specialists, R.M. Williams occupies a position bridging workwear authenticity with contemporary retail presence. Ksubi and Neuw represent the digital-native vector where brand communication prioritizes cultural relevance over manufacturing provenance claims.
| Leading Market Players |
|---|
| Godspeed |
| Neuw |
| Nobody Denim Online Pty Ltd. |
| Flux Denim |
| R.M. Williams |
| Outland Denim |
| Ksubi |
| Denimsmith |
| Rolla's |
| Others |
Pricing and Supply Chain Analysis
Organic cotton fiber costs originating from Australian irrigated acreage flow through selvedge denim pricing tiers, compressing margins for Melbourne-based cut-make-trim operators while elevating wholesale premiums for GOTS-certified lines sold through Sydney specialty retailers.
Pricing Analysis
Input-cost pass-through from constrained organic cotton supply is stratifying Australian denim across premium, standard, and economy tiers. Price differentiation rests on certification grade and domestic manufacturing provenance under Australian Made Campaign Limited rules. Pricing pressure stems from irrigation water allocation volatility in New South Wales and Victoria cotton belts. Young adult consumers in inner-urban postcodes show least price sensitivity for selvedge and raw denim, while teen fast-fashion buyers anchor the economy tier.
Supply Chain Analysis
Regional distribution centers in Melbourne's Brunswick industrial zone anchor hub-and-spoke patterns serving Sydney and Brisbane retail clusters. Manufacturing concentrates in Victoria, with raw cotton drawing from Queensland and New South Wales growers plus Japanese shuttle-loom imports for premium selvedge lines. Single-source vulnerability sits with Melbourne's concentrated garment finishing capacity. Distribution runs through direct-to-consumer digital storefronts bypassing traditional wholesale markups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Australian denim has entered late-cycle quality competition where young adult buyers in Sydney and Melbourne now prioritize transparent provenance over brand heritage alone.
For Market Incumbents: To counter circular ownership models displacing primary retail volume, Nobody Denim and Outland Denim should deepen selvedge pattern-making apprenticeships in Melbourne's design schools while securing extended producer responsibility pre-qualification for anticipated textile waste mandates. For New Entrants and Emerging Players: Enter via Perth's underpenetrated boutique retail corridor with sustainable credentials targeting Western Australia's isolation premium, or capture plus-size white space through online specialty channels with proportional pattern engineering absent from mainstream ranges. For Investors and Strategic Acquirers: Consolidation pressure builds where direct-to-consumer infrastructure and Australian Made certification timelines create acquisition targets among Melbourne-based cut-make-trim operators with established selvedge craftsmanship pipelines. Watch for laser finishing technology adoption rates as inflection signal for waterless production economics.| Strategic Initiative | Industry Significance |
|---|---|
| Direct-to-Consumer Channel Expansion | Bypasses wholesale markups for Melbourne brands selling selvedge lines to Sydney buyers. |
| Sustainability Repositioning | ACCC greenwashing enforcement rewards GOTS-certified organic cotton claims with shelf space. |
| Backward Integration into Cut-Make-Trim | Captures Melbourne garment finishing capacity before aging craftsperson demographics thin. |
| Premium Tier Introduction | Raw denim lines attract authentication premiums on peer-to-peer resale platforms. |
| Distribution Channel Expansion | Perth partnerships reduce delivery friction for Victoria-manufactured goods. |
Research Methodology
Coverage spans Victoria, New South Wales, Queensland, Western Australia, and South Australia, with primary inputs from each combining interviews with denim brand founders, cut-make-trim facility managers, specialty retail buyers, and Australian Made Campaign Limited certification officers alongside secondary validation from ACCC product safety filings, ABS trade data, and Cotton Australia production statistics through bottom-up and top-down triangulation.
Granularity-level modeling disaggregated volume and value across fit type, fabric certification tier, target consumer age cohort, and distribution channel throughout the forecast period. CAGRs derived from segment-level growth rate reconciliation with macroeconomic consumption indicators. Industry-specific inputs incorporated Australian organic cotton acreage constraints and laser finishing technology diffusion curves.
The model holds under stable ACCC enforcement intensity and organic cotton supply continuity; deviation in extended producer responsibility scheme timing or Melbourne labor availability would shift trajectory. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Apparel & Footwear
Sports Apparel Embellishment Market
Apparel & Footwear
Europe Headwear Market
Apparel & Footwear
Headwear Market
Apparel & Footwear
Women's Blazer Market
Apparel & Footwear
Womens Swimwear Market
Apparel & Footwear
Plus Size Clothing Market
Apparel & Footwear
Erotic Lingerie Market
Apparel & Footwear
France Denim Jeans Market
Apparel & Footwear
Men's Coats and Jackets Market
Apparel & Footwear
Women's Coats and Jackets Market
Apparel & Footwear
Fitness Apparel Market
Apparel & Footwear
Ethnic Wear Market
Apparel & Footwear
Global Swimwear (Swimsuit) Market
Apparel & Footwear
Outdoor Sports Apparel Market
Apparel & Footwear
Women's T-Shirts Market
Apparel & Footwear
Body Shaper Market