
 Cosmetic Palettes Market | 2026-2036
Cosmetic Palettes Market Size, Share, and Industry Trends Forecast 2026-2036
Cosmetic Palettes Market Outlook
Aftermarket refill and customization revenue is tilting margin pools away from one-time compact sales toward recurring consumable relationships. HCP Packaging leverages its manufacturing scale to dominate magnetic and refillable case formats for prestige brands. Lady Burd sustains R&D intensity in pressed-powder formulations that meet EU pigment restrictions. Columbia Cosmetics Manufacturing Inc. anchors North American private-label production with vertically integrated pressing and filling operations.
Cosmetic palettes are multi-pan assemblies of pressed powders, creams, or hybrid formulations housed in rigid or magnetic cases, typically containing two to thirty-five color wells arranged for coordinated application. These products serve commercial purposes ranging from consumer daily makeup to professional kit standardization where color consistency across batches determines artist reliability. Eyeshadow palettes occupy the largest value share due to repeat purchase frequency and trend-driven color cycling, while refillable case formats represent the fastest-growing packaging category as sustainability mandates reshape procurement patterns. Professional makeup application generates premium pricing power compared to retail consumer segments, though bridal makeup commands the highest per-unit spend within the end-user base.
FDA color additive regulations govern US market entry for cosmetic pigments, while REACH compliance in Europe restricts certain coal-tar dyes and heavy-metal contaminants in pressed formulations. China's SAMR enforces GB standards for cosmetic safety that foreign palette manufacturers must satisfy through local testing protocols. Stakeholders must monitor evolving state-level packaging extended producer responsibility laws and decide whether to absorb compliance costs or pass them through premium positioning.
Market Dynamics
Magnetic refillable case technology is restructuring procurement relationships, converting one-time compact purchases into recurring consumable revenue streams that reshape manufacturer margin architecture.
Growth Catalysts
- REACH pigment restrictions:EU ECHA enforcement of heavy-metal limits in pressed powders is accelerating R&D investment in compliant synthetic mica alternatives.
- Social media artistry education:Professional makeup artists on TikTok and Instagram are standardizing multi-pan kit configurations that drive premium palette adoption.
- Domestic brand expansion in China:SAMR-compliant local manufacturers are capturing premium eyeshadow share through vertically integrated formulation-to-retail operations.
Market Restraints
- Talc supply concentration:Dependence on limited US and Chinese talc sources creates input cost volatility for pressed-powder formulations.
- FDA color additive approval timelines:Pre-market notification requirements for new cosmetic pigments extend formulation-to-launch cycles by eighteen to thirty-six months.
- Aluminum case sourcing:Magnetic palette housing production concentrates in East Asian foundries, exposing brands to shipping cost fluctuations.
Strategic Opportunities
- Extended producer responsibility mandates:EU packaging waste directives are creating first-mover advantage for refillable case suppliers with closed-loop recovery systems.
- Bridal makeup kit standardization:Professional artists serving destination wedding markets in Italy and Greece are consolidating around twelve-to-eighteen pan configurations.
- Hybrid cream-powder formulations:Convergence of silicone elastomer technology with traditional pressing equipment is opening professional kit upgrade cycles.
Industry Challenges
- Pressing technician skill gaps:Precision powder compression for multi-texture palettes requires specialized operators that contract manufacturers struggle to retain.
- Cross-border formulation compliance:Simultaneous FDA, REACH, and SAMR certification creates testing cost burdens that smaller private-label clients cannot absorb.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cosmetic Palettes Market |
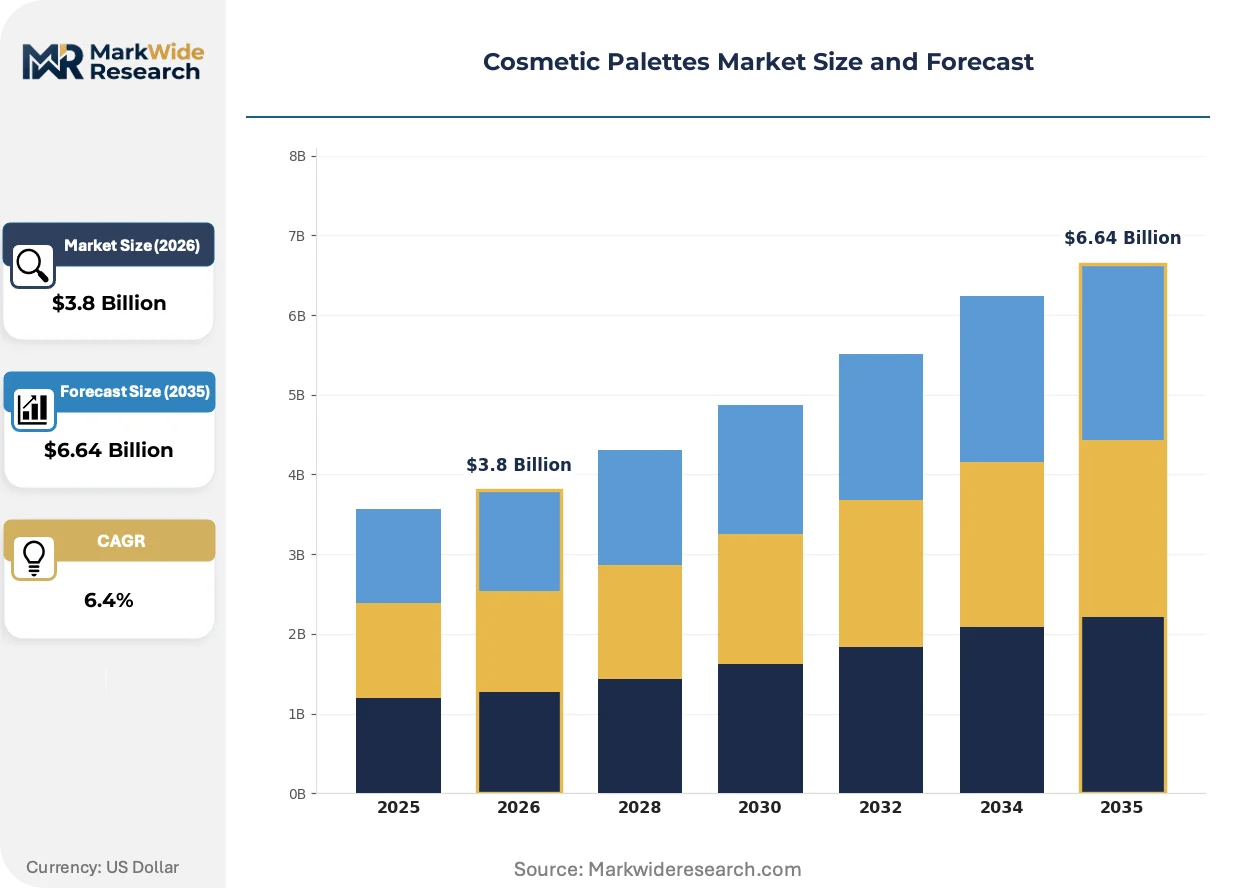
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Eyeshadow Palette, Blush Palette, Contour Palette, Lip Palette, Highlighter Palette Application: Daily Makeup, Professional Makeup, Bridal Makeup, Special Effects, Stage Makeup End User: Beauty Salons, Makeup Artists, Retail Consumers, Cosmetic Stores, Photo Studios Packaging Type: Compact Case, Magnetic Case, Refillable Case, Plastic Case, Wooden Case |
| Companies Covered | Lady Burd, MakeupPalettePro, HCP Packaging, Nardo's Natural, Columbia Cosmetics Manufacturing Inc., Libo Cosmetics, Trilogy Laboratories, Polliam, Mana Products, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cosmetic Palettes Market Strategic Shifts
Formulation chemistry and case engineering are converging to redefine product lifecycle economics, with sustainability mandates and professional workflow optimization driving parallel innovation tracks.
Biodegradable binder systems derived from plant-based polymers are replacing traditional petroleum-derived pressing agents in premium eyeshadow formulations. Professional kit suppliers in France and South Korea are adopting these materials at scale for artist-grade palettes. The shift is rendering obsolete conventional formulation stability testing protocols that assumed synthetic binder chemistry.
REACH Annex XVII restrictions on coal-tar dyes and nickel-release thresholds are forcing reformulation of classic color stories across European distribution channels. Manufacturers serving Germany and the Netherlands are retiring legacy pigment blends ahead of enforcement deadlines. Prestige brands with historical archives face the steepest compliance costs as they reconcile heritage shades with contemporary safety standards.
Direct-to-artist subscription models are replacing wholesale bulk purchasing for professional makeup kits. Independent artists in Los Angeles, London, and São Paulo are receiving monthly curated pan refills rather than seasonal palette replacements. This pattern is most pronounced among editorial and special-effects specialists who require rapid color cycling for project-based work.
Cosmetic Palettes Market Segmentation
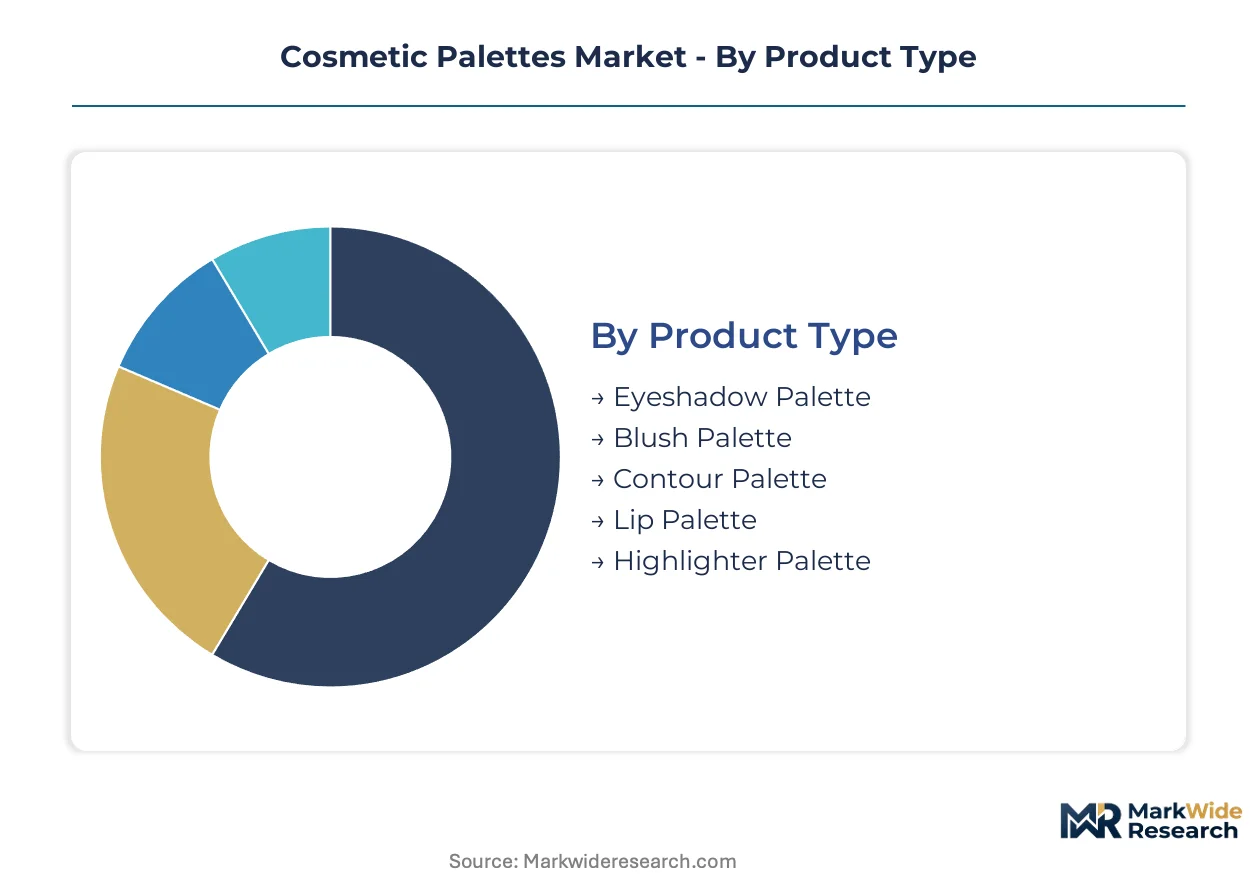
Segmentation in cosmetic palettes determines formulation complexity, packaging investment, and replenishment cadence. Each dimension carries distinct margin implications and regulatory exposure across professional and consumer channels.
Product Type:
After-sales intensity varies sharply by product type, with eyeshadow palettes generating the highest refill frequency and pan replacement revenue.
- Eyeshadow Palette:Multi-pan assemblies of pressed pigments, shimmers, and mattes arranged for coordinated eye looks. Demand concentrates among professional makeup artists in Los Angeles and Seoul who cycle colors seasonally for editorial and K-beauty content creation.
- Blush Palette:Coordinated cheek color wells ranging from two to six pans, often cream-powder hybrids. Bridal makeup specialists in Italy and Greece are standardizing around twelve-to-eighteen pan multi-product configurations that include dedicated blush sections.
- Contour Palette:Sculpting powders and creams in cool-toned gradients for facial dimension. Professional kit suppliers serving film and television production in the UK.
- Lip Palette:Cream and liquid formulations in pan or pot formats for custom color mixing. Editorial artists in Paris and New York.
- Highlighter Palette:Reflective powders and pressed glitters for luminosity effects. Social media content creators in São Paulo and Mumbai.
Eyeshadow palette holds the largest share; momentum sits with refillable highlighter configurations.
Application:
Cost tier stratification separates prestige professional applications from mass-market daily use, with bridal commanding premium per-unit economics.
- Daily Makeup:Consumer-grade palettes optimized for quick application and portability. Retail consumers in China and the US drive volume through e-commerce flash sales and influencer-curated bundles.
- Professional Makeup:Artist-grade formulations with batch-to-batch color consistency for kit reliability. Demand concentrates among editorial specialists in London and Los Angeles who require rapid color cycling for project-based work.
- Bridal Makeup:Premium palettes with extended wear and photography-optimized finishes. Destination wedding markets in Italy and Greece sustain the highest per-unit spend within the end-user base.
- Special Effects:Highly pigmented and prosthetic-compatible formulations for film and theater. SFX artists in Vancouver and Wellington.
- Stage Makeup:Heavy-coverage, sweat-resistant formulations for performance durability. Theater productions in New York and London's West End.
Professional makeup commands pricing power; bridal applications are climbing the fastest.
End User:
Customer type determines procurement channel, with beauty salons and makeup artists driving recurring consumable relationships versus one-time retail purchases.
- Beauty Salons:Service-oriented establishments requiring standardized palette configurations for staff consistency. Salons in South Korea and Japan.
- Makeup Artists:Independent professionals and agency-represented specialists with kit customization needs. Artists in São Paulo, London, and Los Angeles are adopting direct-to-artist subscription models for monthly curated pan refills.
- Retail Consumers:Individual purchasers influenced by social media trends and seasonal color cycles. Consumers in China and India.
- Cosmetic Stores:Specialty retailers with private-label and prestige brand assortments. Sephora and Ulta locations in the US.
- Photo Studios:Commercial photography and videography operations with high-throughput makeup demands. Studios in Mumbai and Bangkok.
Retail consumers generate the largest volume base; makeup artists show the steepest expansion trajectory.
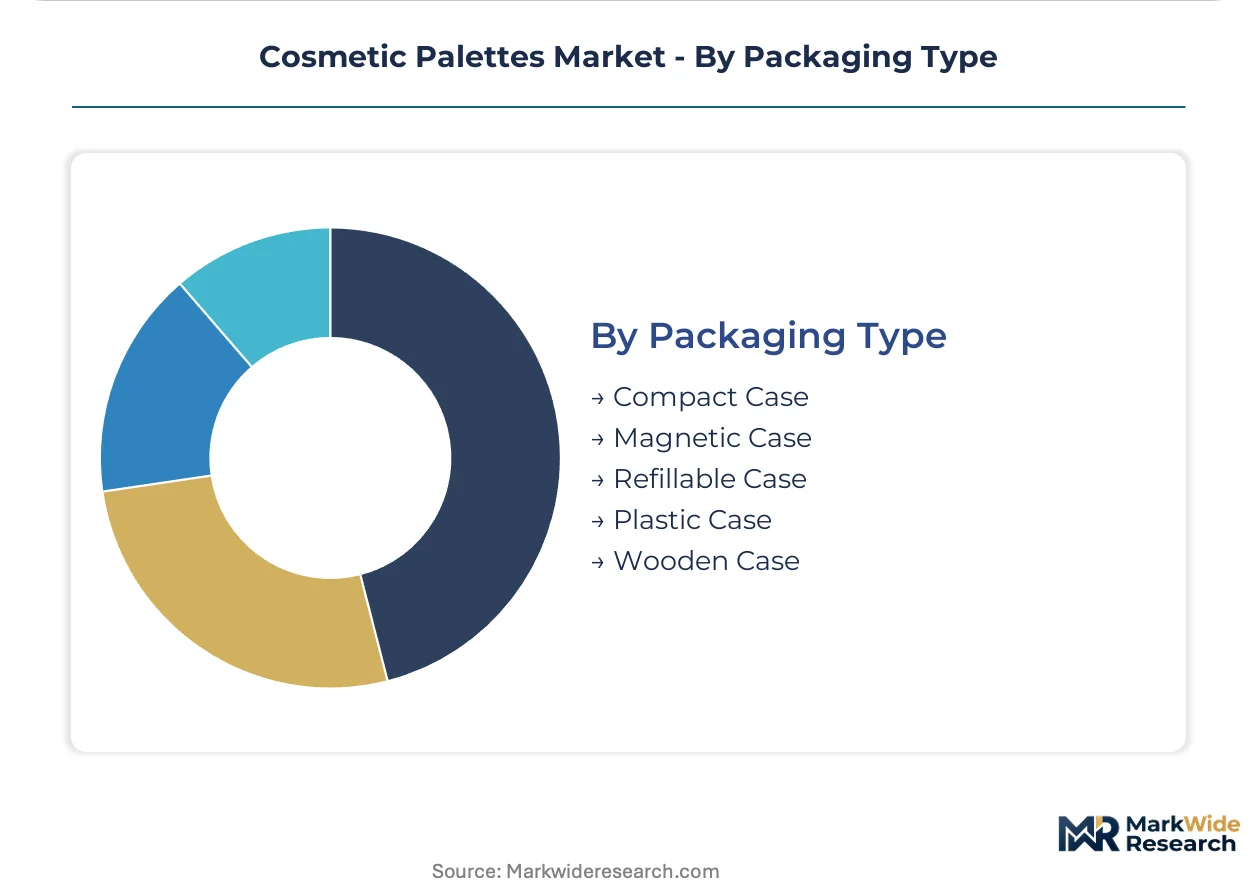
Packaging Type:
Supply concentration in East Asian foundries for magnetic and aluminum components creates procurement risk that brands address through multi-source qualification.
- Compact Case:Traditional hinged plastic or metal housings for fixed-pan configurations. Mass-market brands in the US and Brazil.
- Magnetic Case:Ferrous metal pans attach to magnetic bases for modular rearrangement. Professional kit suppliers in France and South Korea are adopting these formats at scale for artist-grade flexibility.
- Refillable Case:Durable outer shells designed for repeated pan insertion and removal. EU packaging waste directives are creating first-mover advantage for suppliers with closed-loop recovery systems serving Germany and the Netherlands.
- Plastic Case:Injection-molded ABS or PET housings for cost-sensitive segments. Drugstore brands in India and Southeast Asia.
- Wooden Case:Premium sustainable materials for luxury positioning. Niche artisanal producers in Scandinavia and Japan.
Compact case retains the largest installed base; refillable formats are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Professional makeup artists in South Korea and Italy deploy palettes as modular kit components, whereas retail consumers in India and Brazil treat them as seasonal fashion accessories with lower replenishment frequency.
United States
Bridal makeup specialists in Los Angeles and New York drive premium palette adoption for destination wedding content creation. FDA color additive regulations govern pigment approval timelines that extend formulation-to-launch cycles. HCP Packaging anchors magnetic case production for prestige brands through East Coast distribution hubs.
China
Domestic brands in Shanghai and Guangzhou expand premium eyeshadow offerings through vertically integrated formulation-to-retail operations. SAMR enforces GB standards for cosmetic safety that require local testing protocols for foreign manufacturers. The Yangtze River Delta concentrates private-label pressing and filling operations serving both domestic and export markets.
Germany
EU ECHA enforcement of REACH Annex XVII restrictions on coal-tar dyes accelerates R&D investment in compliant synthetic mica alternatives. Professional kit suppliers in Berlin and Hamburg are retiring legacy pigment blends ahead of enforcement deadlines. The Rhine-Ruhr region hosts closed-loop recovery systems for refillable case formats gaining first-mover advantage under packaging waste directives.
South Korea
K-beauty content creators in Seoul drive rapid color cycling for editorial and social media applications. MFDS cosmetic safety standards align with export requirements for adjacent Asian markets. The Seoul Capital Area concentrates biodegradable binder adoption at scale for artist-grade palette formulations.
Italy
Destination wedding markets in Tuscany and the Amalfi Coast sustain the highest per-unit spend for bridal makeup configurations. REACH compliance redirects formulation strategies away from nickel-release pigments in pressed powders. Milan anchors luxury packaging design studios serving heritage prestige brands reconciling archival color stories with contemporary safety standards.
Cosmetic Palettes Market Competitive Environment
Capability concentration sits with specialized formulation houses; scale advantage sits with integrated packaging suppliers. The vendor base stratifies across three tiers: magnetic case fabricators with East Asian manufacturing footprints, pressed-powder specialists with EU compliance expertise, and private-label manufacturers with vertically integrated pressing operations. Dominant competitive moves include backward integration into raw material sourcing and geographic expansion through distributor partnerships in high-growth Asian markets.
Within the packaging-specialist tier, HCP Packaging and Libo Cosmetics represent scale-driven manufacturing archetypes with East Asian production concentration. Lady Burd occupies a position exemplifying formulation-intensive players navigating EU pigment restrictions. Columbia Cosmetics Manufacturing Inc. anchors the private-label segment with North American pressing and filling capabilities.
| Leading Market Players |
|---|
| Lady Burd |
| MakeupPalettePro |
| HCP Packaging |
| Nardo's Natural |
| Columbia Cosmetics Manufacturing Inc. |
| Libo Cosmetics |
| Trilogy Laboratories |
| Polliam |
| Mana Products |
| Others |
Value Chain & Pricing Dynamics
The Yangtze River Delta concentrates private-label pressing and filling capacity that feeds downstream pricing power to prestige brands seeking compliant formulations. Contract manufacturers in Shanghai and Guangzhou leverage EU REACH certification investments to command premium positioning against uncertified competitors serving mass-market retailers.
Pricing Analysis
Long-term offtake contracts dominate procurement between major brands and magnetic case suppliers, insulating against aluminum price volatility while spot purchasing persists for specialty pigment batches. Three-tier pricing structure across premium artist-grade, standard professional, and economy consumer levels separates bridal kit suppliers from flash-sale retailers. Pricing pressure stems from talc supply concentration between US and Chinese sources, compressing margins for pressed-powder specialists. Retail consumers in India and Southeast Asia exhibit highest price sensitivity, whereas destination wedding artists in Italy absorb premium positioning without volume negotiation.
Supply Chain Analysis
Extended payment terms from South Korean and French professional kit suppliers to East Asian magnetic component foundries are restructuring working capital requirements across the tier. Raw material sourcing draws from Chinese synthetic mica operations, US talc deposits, and German binder chemistry specialists. Single-source vulnerability concentrates in aluminum case production at East Asian foundries exposed to shipping cost fluctuations. Distribution runs through vertically integrated domestic brands in China, specialized professional distributors in Europe, and e-commerce flash-sale platforms in Brazil and India.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Single-use disposable palettes represent a substitution threat that refillable format incumbents must neutralize through consumable revenue lock-in.
For Market Incumbents: Harden consumable relationships by embedding subscription-based pan refill programs that displace seasonal palette replacements. Secure captive supply of REACH-compliant synthetic mica through backward integration into raw material sourcing, insulating formulation costs from ECHA enforcement tightening. For New Entrants and Emerging Players: Pursue direct-to-artist subscription white space in São Paulo and Mumbai where editorial specialists require rapid color cycling without legacy distributor markups. Target biodegradable binder formulations for South Korean K-beauty content creators as the most penetrable sustainability segment, leveraging plant-based polymer positioning against petroleum-derived incumbents. For Investors and Strategic Acquirers: Long-term, this sits as a consumable-transition play because recurring pan refill economics displace one-time compact purchasing across professional and premium consumer segments. Acquisition candidates center on magnetic case fabricators with closed-loop recovery capabilities serving EU packaging waste directives. Monitor ECHA pigment restriction enforcement timelines as the signal for compliant formulation capacity scarcity inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Refillable Case Format Expansion | EU packaging waste directives reward closed-loop recovery systems with first-mover procurement advantage. |
| Biodegradable Binder Adoption | Plant-based polymer formulations meet South Korean MFDS standards while displacing petroleum-derived alternatives. |
| Direct-to-Artist Subscription Launch | Monthly curated pan refills capture editorial specialists in Los Angeles and London from wholesale distributors. |
| REACH Compliance Certification Investment | ECHA Annex XVII adherence unlocks premium positioning in German and Dutch professional channels. |
| Magnetic Component Multi-Source Qualification | East Asian foundry diversification reduces aluminum case exposure to shipping cost volatility. |
Study Parameters
Operator-level perspectives from pressed-powder formulation chemists, professional makeup kit suppliers, magnetic case procurement managers, and bridal salon owners anchored the qualitative base. Primary interviews triangulated against secondary sources including FDA color additive filings, ECHA REACH registration databases, SAMR GB standard compliance records, and customs trade data for talc and mica imports. Bottom-up palette volume estimates reconciled with top-down beauty market sizing across the analysis window.
Scenario-bracketing around regulatory enforcement intensity and sustainability mandate adoption shaped the analytical framework. Segmentation dimensions spanned product type, application tier, end-user procurement channel, packaging format, and regional regulatory cluster. CAGRs derived from fitted growth curves applied to professional artist population expansion and refillable format penetration rates, with inputs from social media content creator economy trajectories and EU extended producer responsibility implementation schedules.
Sensitivities concentrate around ECHA enforcement timelines for coal-tar dye restrictions, SAMR testing protocol changes for foreign manufacturers, and talc supply disruption events. Forecasts reflect documented assumptions regarding professional artist subscription adoption curves and magnetic case format share gains. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beauty & Personal Care
South Korea Dermocosmetics Market
Beauty & Personal Care
Europe Male Grooming Products Market
Beauty & Personal Care
Global Organic Hair Color Market
Beauty & Personal Care
Europe Professional Beauty Services Market
Beauty & Personal Care
Brazil Dermocosmetics Market
Beauty & Personal Care
Asia-Pacific Hair Removal Wax Market
Beauty & Personal Care
Over-Night Hair Treatment Products Market
Beauty & Personal Care
Middle East and Africa Bath and Shower Products Market
Beauty & Personal Care
North America Beauty Devices Market
Beauty & Personal Care
US Cosmetics Market
Beauty & Personal Care
Global Bath Bomb Market
Beauty & Personal Care
Beauty Fridge Market
Beauty & Personal Care
Makeup Egg Market
Beauty & Personal Care
US Natural Personal Care Market
Beauty & Personal Care
Beauty Pillowcases Market
Beauty & Personal Care
Italy Beauty and Personal Care Products Market