
 Europe Mineral Turpentine Market | 2026-2036
Europe Mineral Turpentine Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Mineral Turpentine Market Insights
Technical service contracts and reformulation support is hardening into a distinct revenue layer alongside commodity solvent sales. TotalEnergies leverages its integrated refining network to secure feedstock consistency across Northwestern Europe. DHC Solvent Chemie GmbH specializes in high-purity grades tailored to pharmaceutical and food-contact specifications. HCS Group anchors its position through dedicated storage and blending infrastructure at Rotterdam and Hamburg.
Mineral turpentine, also known as white spirit or petroleum spirits, comprises a refined hydrocarbon solvent blend typically spanning C7-C12 aliphatic and aromatic fractions with a distillation range of 150-200°C and flash point above 38°C; manufacturers produce it via catalytic reforming or straight-run distillation of crude oil fractions to serve primarily as a diluent in alkyd-based paints, varnishes, and industrial cleaning formulations. Industrial grade commands the largest volume share due to its penetration in construction and automotive refinishing, while pharmaceutical grade captures disproportionate margin owing to stringent purity certification and limited qualified supply. Paint thinner applications dominate absolute consumption, though adhesive solvent use is expanding fastest as packaging and tape manufacturers seek consistent evaporation profiles.
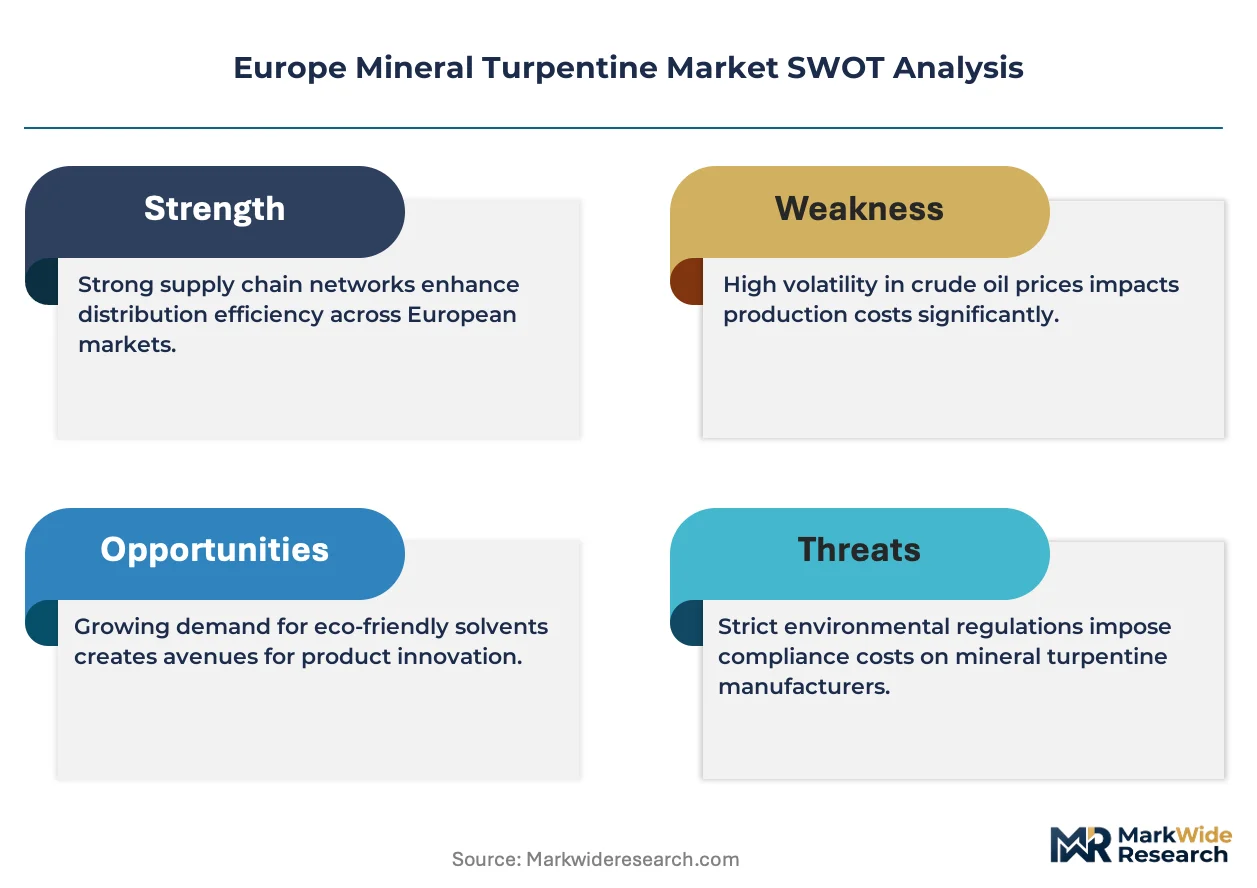
REACH registration requirements and the EU F-Gas Regulation's broader chemical management precedent shape product composition thresholds, with ECHA evaluations pushing suppliers toward reduced aromatic content and improved hazard communication. Germany's Federal Institute for Risk Assessment and France's ANSES coordinate national implementation, creating overlapping compliance obligations for cross-border suppliers. Buyers should monitor evolving substance restriction proposals under REACH sunset dates, as these will determine which reformulated grades retain market access.
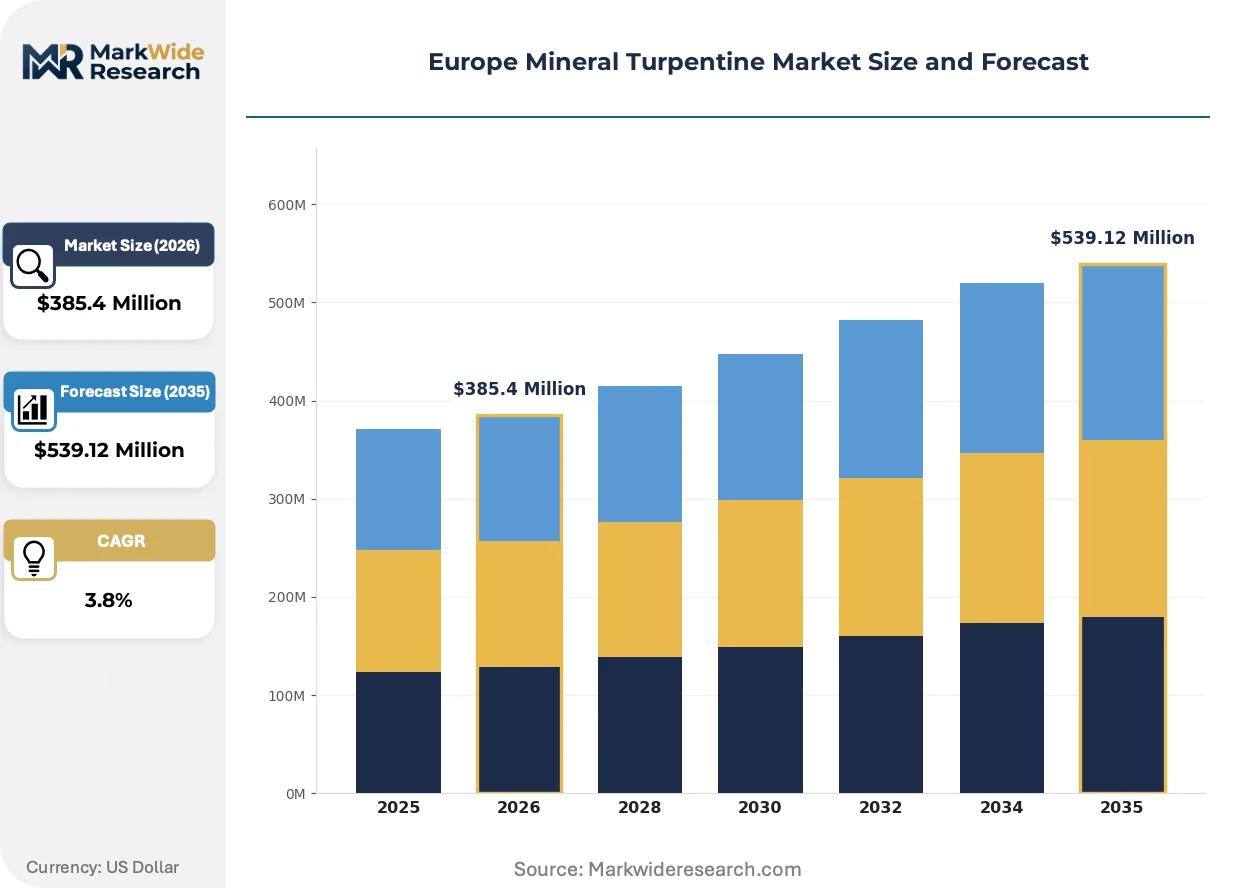
Market Dynamics
REACH sunset dates and the EU Green Deal's chemical sustainability mandates are forcing wholesale reformulation of mineral turpentine grades across Europe, compressing the window for conventional high-aromatic solvents while opening premium positioning for low-aromatic and dearomatized alternatives.
Growth Catalysts
- Construction sector recovery:Germany's residential and infrastructure build-out sustains paint thinner demand from professional decorators and industrial coating applicators.
- REACH registration deadlines:Compliance-driven grade upgrades push buyers toward registered, fully-documented supply chains with verified exposure scenarios.
- Adhesive tape manufacturing:Packaging producers in Italy and Poland specify mineral turpentine for controlled evaporation in pressure-sensitive adhesive formulations.
Market Restraints
- Crude oil feedstock volatility:Naphtha and kerosene price swings directly compress blending margins for European refiners.
- Substitution by aqueous systems:Water-borne coatings in automotive OEM plants displace solvent-borne alkyd formulations in Germany and France.
- ECHA authorization bottlenecks:Pending substance evaluations create regulatory uncertainty for C9-C12 aromatic fractions.
Strategic Opportunities
- Pharmaceutical-grade expansion:Eastern European generic drug manufacturers seek GMP-certified solvents for tablet coating and extraction processes.
- EU F-Gas Regulation precedent:Broader chemical phase-down frameworks create early-mover advantage for bio-based hydrocarbon alternatives.
- Technical service bundling:Reformulation support contracts attached to solvent supply deepen customer retention among mid-sized paint producers.
Industry Challenges
- Specialized toxicology expertise scarcity:REACH dossier preparation and exposure assessment require chemists with rare regulatory submission experience.
- Blending asset reconfiguration:Dearomatization units and molecular sieve investments strain capex budgets for independent distributors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Mineral Turpentine Market |
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $539.12 Million |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Commercial Grade, Industrial Grade, Pharmaceutical Grade, Food Grade Application: Paint Thinner, Solvent, Adhesive, Cleaning Agent End User: Manufacturing, Automotive, Construction, Pharmaceuticals Distribution Channel: Direct Sales, Online, Retail, Wholesale |
| Companies Covered | Shell, TotalEnergies, ExxonMobil, Cepsa, Neste, DHC Solvent Chemie GmbH, HCS Group, EURO-YSER, GSB Chemical, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Mineral Turpentine Market Trends and Innovations
Reformulation chemistry and regulatory compliance tooling are converging to redefine competitive advantage in European mineral turpentine supply, with technical service capabilities now separating premium suppliers from commodity traders.
Dearomatization via catalytic hydrogenation is electrifying the product hierarchy in industrial solvent markets. German automotive refinish shops and French furniture coaters are specifying sub-1% aromatic grades for worker safety compliance. This technology is compressing demand for conventional white spirit while electrifying margin structures for refiners with hydroprocessing capacity.
REACH sunset date scheduling is forcing anticipatory portfolio pruning across the supply base. ECHA's rolling evaluation of C9-C14 hydrocarbons triggers downstream reformulation costs for coating manufacturers. Germany's Federal Institute for Risk Assessment coordinates with ANSES in France to align national restrictions, creating synchronized compliance deadlines that favor pan-European suppliers with centralized regulatory affairs teams.
Buyers are consolidating solvent procurement through integrated chemical management contracts. Mid-sized paint producers in Italy and Spain are outsourcing inventory and formulation support to distributors with dedicated technical staff. This shift is most visible in Iberia, where construction chemical suppliers trade volume discounts for guaranteed supply security and on-site solvent recovery services.
Europe Mineral Turpentine Market Segmentation
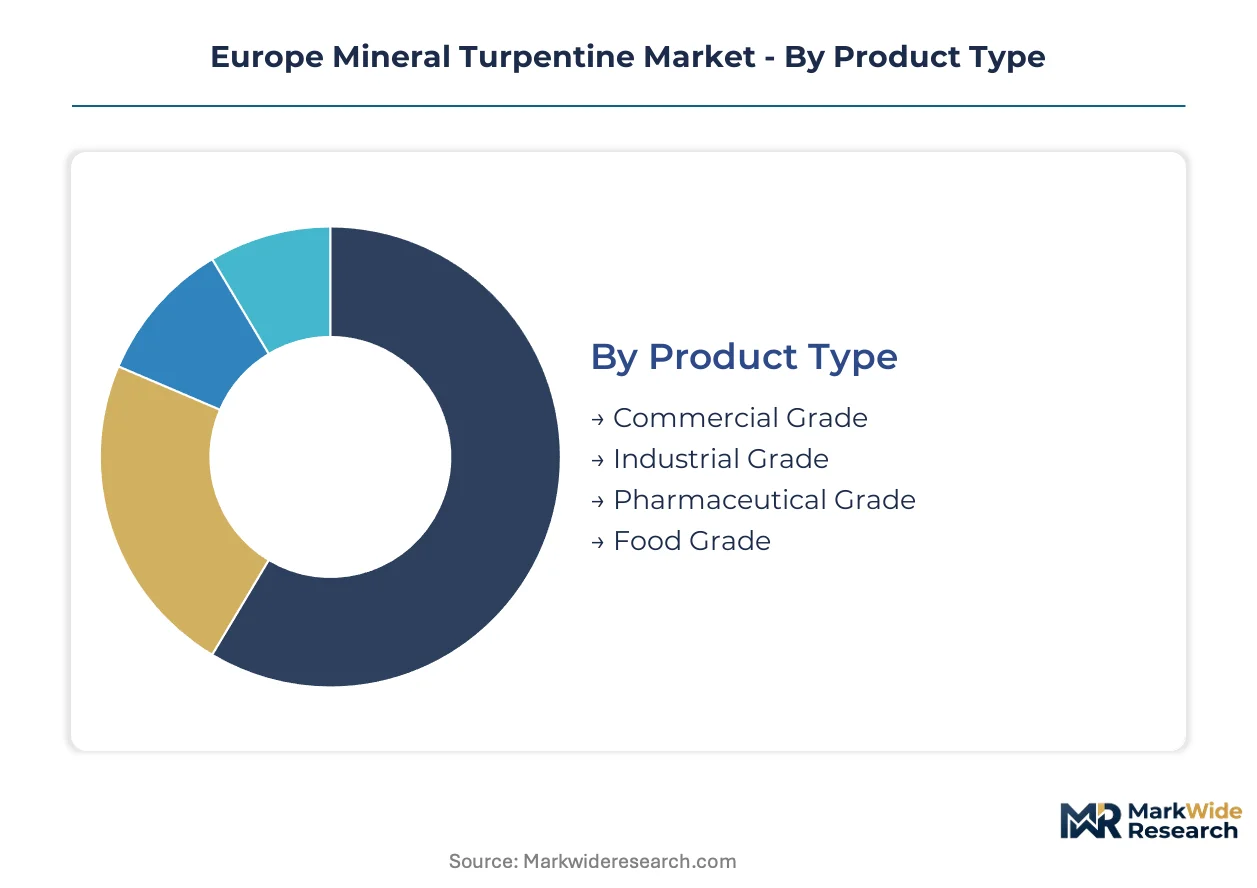
Segmentation in European mineral turpentine supply reveals how certification burdens, application chemistry, and channel economics partition the market into distinct competitive arenas. Buyers navigate trade-offs between regulatory compliance costs and performance specifications that vary sharply across grades and end-uses.
Product Type:
Certification intensity escalates from basic commercial grades through GMP-validated pharmaceutical and food-contact variants, with each tier demanding progressively stricter documentation under REACH and national food safety frameworks.
- Commercial Grade:Broad-cut hydrocarbon solvent with moderate aromatic content serves general-purpose thinning and cleaning across maintenance workshops. Italian furniture makers and Polish metal fabricators absorb steady volumes despite margin pressure from aqueous alternatives.
- Industrial Grade:Refined to tighter distillation ranges with controlled evaporation profiles, this specification dominates automotive refinishing and industrial coating lines in Germany's Ruhr corridor. REACH registration dossiers for this grade are now table stakes for supplier qualification.
- Pharmaceutical Grade:GMP-certified production with residual solvent testing per ICH Q3C guidelines.
- Food Grade:Meets EU 10/2011 plastic materials regulation for incidental food contact.
Industrial grade sits at the top of the volume ranking, with pharmaceutical grade climbing the fastest.
Application:
Application chemistry dictates solvent selection through evaporation rate matching, resin compatibility, and worker exposure limits that vary by formulation type.
- Paint Thinner:Alkyd resin dilution in decorative and protective coatings consumes the largest absolute volumes. German housing renovation cycles and French infrastructure maintenance sustain professional decorator demand despite water-borne substitution in OEM settings.
- Solvent:Carrier function in printing inks, agrochemical formulations, and chemical synthesis requires precise polarity tuning. Pharmaceutical extraction processes in Eastern Europe specify narrow-cut dearomatized grades for API manufacturing.
- Adhesive:Pressure-sensitive tape manufacturers in Italy and Poland specify controlled evaporation for consistent coating weights.
- Cleaning Agent:Degreasing and parts washing in metalworking shops faces substitution from aqueous and semi-aqueous systems.
Paint thinner commands the volume lead, though adhesive applications gain share fastest as packaging output expands.
End User:
End-user concentration patterns reflect regional industrial structure, with automotive and construction clusters driving geographic demand distribution.
- Manufacturing:General industrial processing spans metalworking, electronics, and consumer goods assembly. Batch chemical producers in the Netherlands and Belgium specify technical-grade solvents for reaction media and extraction.
- Automotive:OEM refinishing lines and aftermarket collision repair shops in Germany, France, and the UK specify low-aromatic grades for worker safety compliance. Tier-1 suppliers consolidate procurement through integrated chemical management contracts.
- Construction:Professional painting contractors and on-site maintenance crews in Spain and Italy drive seasonal demand fluctuations.
- Pharmaceuticals:Generic drug manufacturers in Poland, Hungary, and the Czech Republic source GMP-certified grades for tablet coating and API synthesis.
Manufacturing absorbs the largest volume, while pharmaceutical end-use expands most steeply on generic drug outsourcing trends.
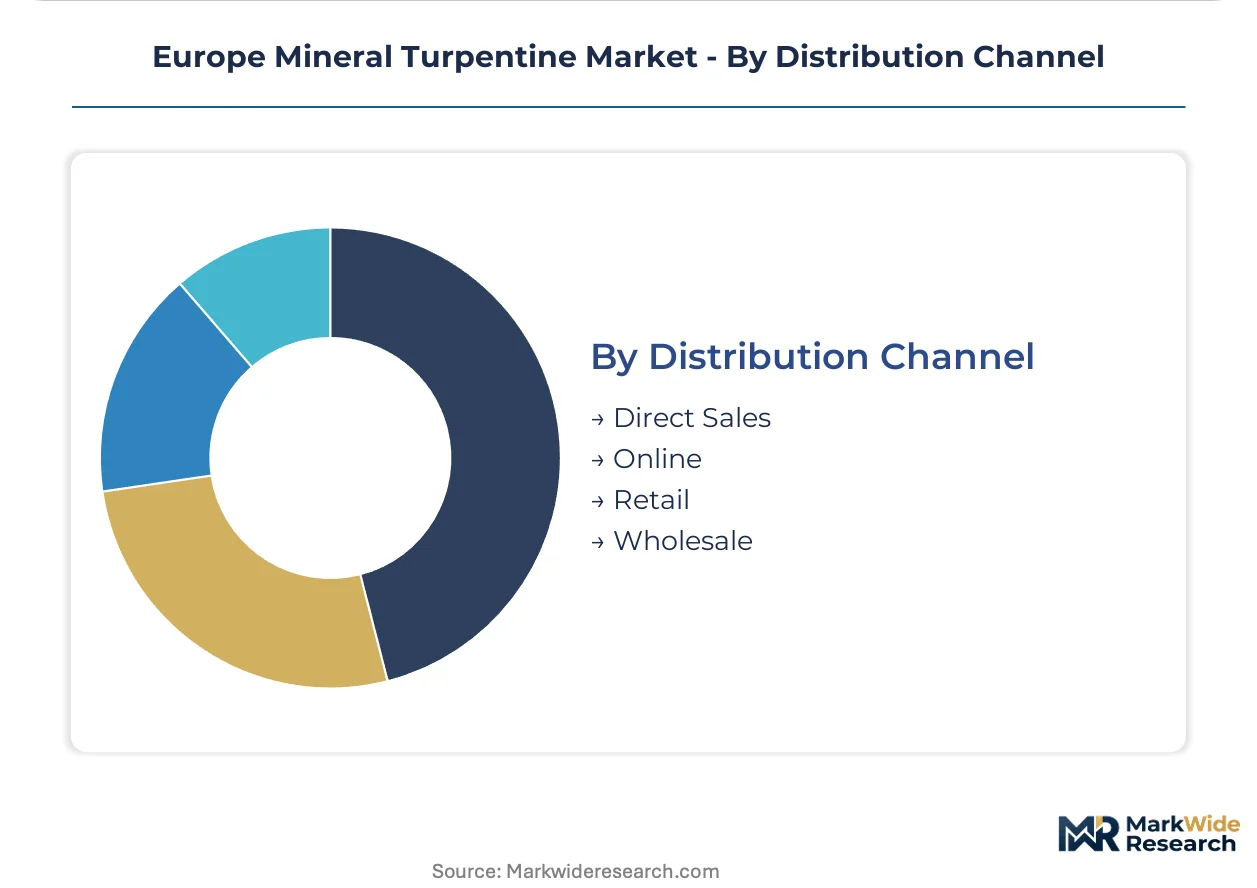
Distribution Channel:
Channel economics separate bulk commodity flows from value-added technical service relationships, with digital platforms emerging in standardized grade segments.
- Direct Sales:Refiner-to-manufacturer contracts secure volume commitments from large coating and adhesive producers. TotalEnergies and integrated distributors leverage dedicated tankage for just-in-time delivery to German automotive clusters.
- Online:E-procurement platforms gain traction in standardized commercial grades for small-batch maintenance shops. Digital channels remain marginal for certified pharmaceutical and food grades requiring documentation handoffs.
- Retail:Hardware and specialty chemical stores serve professional decorators and small contractors.
- Wholesale:Regional distributors blend bulk deliveries with inventory management for mid-sized industrial accounts.
Direct sales anchor volume flows, with online channels posting the steepest expansion trajectory among emerging procurement modes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's industrial corridor consumes substantially higher mineral turpentine volumes than France's fragmented coating sector, yet both face synchronized REACH compliance deadlines that reshape supplier qualification criteria.
Germany
Automotive OEM refinishing and construction chemical manufacturing absorb the region's largest solvent offtake. The Federal Institute for Risk Assessment coordinates with ECHA to enforce reduced aromatic content thresholds. The Ruhr industrial cluster hosts dedicated blending infrastructure serving tier-1 paint producers.
France
Furniture coating workshops and infrastructure maintenance crews sustain steady demand for low-aromatic thinners. ANSES aligns national restrictions with EU Green Deal chemical sustainability mandates. The Lyon-Auvergne-Rhône-Alpes corridor concentrates adhesive tape manufacturing specifying controlled evaporation grades.
Italy
Professional decorators and packaging adhesive producers drive seasonal consumption patterns. REACH registration dossiers determine supplier access to northern industrial zones. The Lombardy-Veneto manufacturing belt houses pressure-sensitive tape operations requiring precise solvent profiles.
Poland
Generic drug manufacturers source GMP-certified grades for tablet coating and API synthesis. ECHA substance evaluations create uncertainty for C9-C12 aromatic fraction imports. The Warsaw-Łódź pharmaceutical corridor attracts distributors with dedicated pharmaceutical-grade storage.
Netherlands
Batch chemical producers and refinery operations specify technical-grade solvents for reaction media. The EU F-Gas Regulation precedent shapes broader chemical phase-down frameworks. The Rotterdam port complex anchors storage and blending infrastructure for Northwestern European distribution.
Europe Mineral Turpentine Market Competitive Landscape
Top-tier vendors anchor integrated refining and distribution networks, while mid-scale specialists compete on certification depth and technical service bundling. The market structure reflects moderate consolidation around pan-European supply chains with regional blending assets. Strategic archetypes include integrated energy majors with captive feedstock, independent distributors with dedicated storage infrastructure, and specialty chemical firms with GMP-certified production. Dominant competitive moves encompass portfolio diversification into low-aromatic grades and geographic expansion through Rotterdam and Hamburg hub investments.
Within the integrated energy tier, Shell, TotalEnergies, and ExxonMobil represent archetypes of backward-controlled supply chains with hydroprocessing capacity for dearomatized production. These entities occupy positions where refinery integration secures feedstock consistency across Northwestern European demand centers. DHC Solvent Chemie GmbH and HCS Group exemplify the independent distribution archetype, anchoring market presence through dedicated tankage and blending infrastructure rather than captive crude supply.
| Leading Market Players |
|---|
| Shell |
| TotalEnergies |
| ExxonMobil |
| Cepsa |
| Neste |
| DHC Solvent Chemie GmbH |
| HCS Group |
| EURO-YSER |
| GSB Chemical |
| Others |
Pricing and Supply Chain Analysis
Naphtha price benchmarks on the Rotterdam spot market cascade through European mineral turpentine supply chains, compressing blending margins for independent distributors while integrated refiners capture arbitrage through captive feedstock access. Buyers face widening spreads between commercial-grade spot pricing and contract premiums for REACH-registered industrial grades.
Pricing Analysis
Capacity additions in the Netherlands and Germany are reshaping price floors for dearomatized grades as hydroprocessing investments outpace demand growth for conventional white spirit. Three-tier pricing structure across premium, standard, and economy levels stratifies by aromatic content and certification depth, with GMP-validated pharmaceutical grades commanding the widest premiums. Cost compression in industrial grades intensifies because aqueous coating substitution erodes volume commitments from automotive OEMs. Small-batch maintenance shops exhibit highest price sensitivity, while pharmaceutical manufacturers prioritize supply security over unit economics.
Supply Chain Analysis
Dual-sourcing requirements from German automotive and French furniture coaters mandate multi-supplier qualification, forcing distributors to maintain redundant inventory positions across Rotterdam and Hamburg hubs. Feedstock draws from Belgian refineries, German catalytic reformers, and Dutch straight-run distillation units. Supply chain risk centers on ECHA authorization bottlenecks for C9-C12 aromatic fractions, which could abruptly disqualify single-source suppliers. Distribution runs through integrated refiner-direct contracts for large coating producers, with wholesale distributors serving mid-tier industrial accounts through tankage and blending infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Europe mineral turpentine constitutes a late-cycle quality story as REACH sunset dates and EU Green Deal mandates concentrate procurement toward registered, low-aromatic supply chains with verified exposure scenarios.
For Market Incumbents: Deepen hydroprocessing capacity investments to secure dearomatized grade output before regulatory deadlines harden. Consolidate technical service teams around reformulation support contracts that attach to solvent supply agreements. Aqueous coating substitution in automotive OEM plants threatens volume erosion; backward integration into naphtha sourcing insulates margin compression from feedstock volatility. For New Entrants and Emerging Players: Regional distributors with dedicated pharmaceutical-grade storage represent the most penetrable channel partner type for Eastern European market entry. White-space targets include GMP-certified solvent supply to Polish and Hungarian generic drug manufacturers, plus on-site solvent recovery services for Iberian construction chemical suppliers. A technical service bundling approach differentiates against commodity traders lacking formulation chemistry expertise. For Investors and Strategic Acquirers: Asymmetric upside sits with independent distributors possessing Rotterdam or Hamburg tankage and established REACH dossier libraries. Five-to-ten year viability hinges on regulatory compliance asset depth rather than volume scale alone. Acquisition targets should demonstrate centralized regulatory affairs capabilities spanning ECHA, Germany's Federal Institute for Risk Assessment, and France's ANSES. The signal to watch is accelerated sunset date scheduling for C9-C14 hydrocarbon evaluations, which would trigger forced portfolio pruning across the supply base.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Naphtha Sourcing | Captive feedstock access insulates margin compression from Rotterdam spot price volatility. |
| Dearomatization Capacity Expansion | Hydroprocessing investments position suppliers ahead of EU Green Deal aromatic content mandates. |
| Technical Service Contract Bundling | Reformulation support deepens retention among mid-sized Italian and Spanish paint producers. |
| Pharmaceutical-Grade Certification Investment | GMP-validated production captures generic drug outsourcing trends in Poland and Hungary. |
| Rotterdam-Hamburg Hub Infrastructure | Dedicated tankage and blending assets secure supply security commitments from German automotive clusters. |
Research Methodology
Coverage spans Germany, France, Italy, Poland, and the Netherlands, with primary inputs from each market cluster combined with secondary validation. Interviews with refinery operations managers, procurement leads at coating manufacturers, distribution channel partners, and technical R&D directors informed supply-side dynamics. Secondary sources included customs and trade flow data, Cefic solvent market reports, ECHA registration dossiers, and SEC filings from integrated energy majors. Bottom-up grade-level volume estimates triangulated against top-down regional consumption benchmarks.
Granularity-level modeling distinguished commercial, industrial, pharmaceutical, and food-grade tiers across paint thinner, solvent, adhesive, and cleaning agent applications. End-user segmentation captured manufacturing, automotive, construction, and pharmaceutical demand patterns. CAGRs derived from regression analysis against construction output indices, automotive production data, and pharmaceutical manufacturing growth across the projection horizon. Forecast inputs incorporated REACH sunset date scheduling and EU Green Deal chemical sustainability mandate implementation timelines.
Revisions become necessary when ECHA authorization bottlenecks materialize for C9-C12 aromatic fractions or when crude oil feedstock volatility exceeds historical ranges. Forecasts reflect assumptions around regulatory compliance deadlines and substitution rates for aqueous coating systems. Deviation in German automotive OEM water-borne adoption timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Extracts
Bidens Pilosa Extract Market
Extracts
Eucommia Extract Market
Extracts
Orange Oil Market
Extracts
Cassia Extract Market
Extracts
Pectinase Market
Extracts
Histidine Market
Extracts
China Cedar Wood Oil Market
Extracts
Jalapeno Extract Market
Extracts
Cochineal Extract Market
Extracts
Black Fungus Extract Market
Extracts
Flower Extract Market
Extracts
Patchouli Oil Market
Extracts
Palmarosa Oil Market
Extracts
Global Rose Oils Market
Extracts
Herb and Spice Extracts Market
Extracts
Cassia Seed Extract Market