
 Alpha Ionone Market | 2026-2036
Alpha Ionone Market Size, Share, and Industry Trends Forecast 2026-2036
Alpha Ionone Market Analytics
Subscription-based technical support for aroma chemical customization is decoupling traditional bulk supply contracts from value-added service relationships. Symrise AG leverages its integrated R&D platform to anchor long-term partnerships with fragrance houses seeking tailored ionone profiles. Givaudan SA differentiates through biotechnology-derived routes that reduce batch-to-batch variability. BASF SE sustains manufacturing scale across multiple production sites, competing on volume reliability for global personal care brands.
Alpha ionone is a cyclic ketone aroma chemical with a violet-like odor profile, typically specified at minimum purity levels and characterized by specific gravity and refractive index parameters that determine its suitability for fine fragrance compounding. The compound serves as a foundational building block in perfumery, providing woody-floral notes that blend with ionone beta isomers in commercial formulations. Synthetic alpha ionone occupies the dominant volume position due to cost efficiency and supply consistency, while natural alpha ionone commands premium positioning in clean-label fragrance segments where botanical provenance drives purchasing decisions. Fractionated grades are gaining traction among pharmaceutical companies requiring controlled isomer ratios for active ingredient synthesis.
REACH registration requirements in the European Union and EPA chemical substance evaluations in the United States impose purity thresholds and environmental fate testing that elevate compliance costs for suppliers entering these jurisdictions. The International Fragrance Association standards further constrain permissible concentration levels in consumer products, directly influencing formulation economics across end-use categories. Stakeholders must monitor regulatory divergence between jurisdictions to anticipate reformulation mandates and reposition supply chain qualifications accordingly.
Market Dynamics
Synthetic biology platforms are compressing traditional petrochemical routes for alpha ionone production, forcing incumbent suppliers to requalify manufacturing assets while fragrance houses demand batch-to-batch consistency certificates that biotech-derived materials now routinely deliver.
Growth Catalysts
- REACH registration thresholds:EU fragrance compounders face mandatory purity documentation for ionone imports, creating compliant supplier preference effects that concentrate procurement among pre-registered chemical manufacturers.
- Fine perfumery formulation density:Grasse, France and Geneva, Switzerland host clustered R&D laboratories driving concentrated demand for high-grade alpha ionone with specified isomer ratios.
- Biocatalytic reduction processes:Engineered yeast strains now convert geraniol to alpha ionone with stereoselectivity that eliminates downstream fractional distillation steps.
Market Restraints
- Acetone-cyclohexanone feedstock volatility:Petrochemical input costs for synthetic alpha ionone swing with refinery output scheduling, compressing margin predictability for contract manufacturers.
- Isomer separation technical ceiling:Current distillation columns achieve practical purity limits around 98 percent, leaving residual beta ionone that constrains pharmaceutical-grade applications.
- Natural extraction yield constraints:Violet flower and raspberry botanical sources deliver sub-kilogram yields per hectare, pricing natural alpha ionone beyond mass-market fragrance accessibility.
Strategic Opportunities
- India specialty chemical manufacturing:BIS certification alignment and PLI scheme incentives for aroma chemical production attract contract manufacturing investment from European fragrance houses seeking supply diversification.
- Pharmaceutical isomer specification demand:Controlled alpha-to-beta ratios enable active ingredient synthesis for neurological therapeutic candidates, opening technical-grade supply contracts outside traditional perfumery.
- Direct-to-compounder digital platforms:Specialty chemical distributors launch specification-matching portals that bypass regional wholesale layers, capturing margin from fragmented buyer bases in mid-sized fragrance houses.
Industry Challenges
- Bioprocess scale-up engineering talent:Fermentation specialists with aroma chemical purification experience command premium compensation, constraining rapid capacity expansion for biotech-derived ionone facilities.
- Cross-jurisdictional registration synchronization:EPA chemical substance evaluations proceed on timelines decoupled from ECHA REACH dossier reviews, forcing dual-track compliance investments for suppliers serving both markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Alpha Ionone Market |
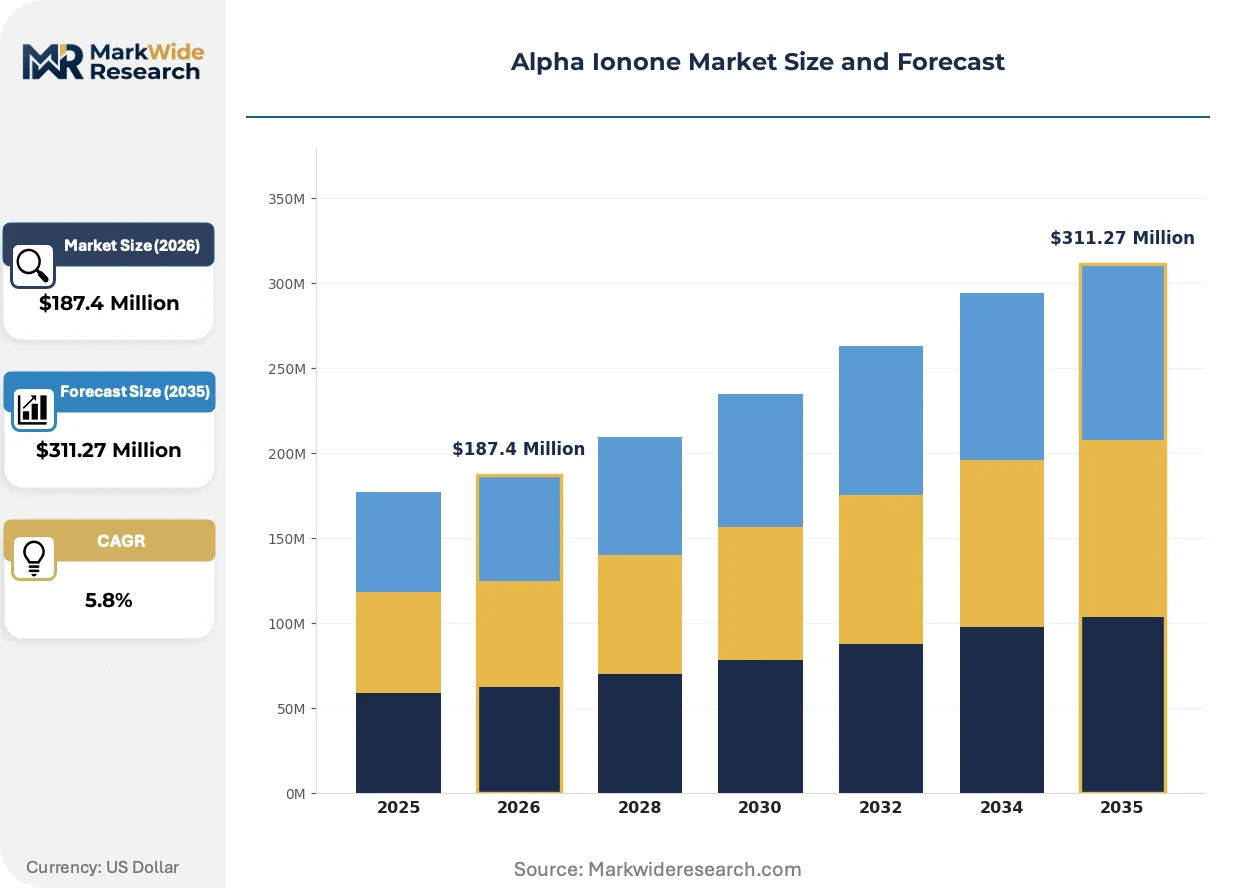
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Alpha Ionone, Synthetic Alpha Ionone, Fractionated Alpha Ionone, Isolated Alpha Ionone Application: Fragrances, Cosmetics, Food Flavoring, Pharmaceuticals Distribution Channel: Online Retail, Specialty Stores, Wholesale, Direct Sales End User: Food Industry, Personal Care, Household Products, Pharmaceutical Companies |
| Companies Covered | Symrise AG, International Flavors & Fragrances Inc., BASF SE, Sensient Technologies Corporation, Robertet Group, Firmenich SA, Takasago International Corporation, Axxence Aromatic GmbH, Givaudan SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Alpha Ionone Market Evolving Landscape
Continuous processing equipment and real-time analytical verification are replacing batch manufacturing paradigms in aroma chemical production, compressing quality assurance cycles while enabling just-in-time supply relationships with formulation laboratories.
Membrane-assisted pervaporation systems for isomer separation are absorbing capital investment from traditional fractional distillation infrastructure. European fragrance compounders in Germany and the Netherlands specify membrane-purified alpha ionone for woody-floral accords requiring precise odor thresholds. This absorption of separation technology is compressing energy intensity metrics that previously disadvantaged synthetic routes against natural extraction claims.
EPA chemical substance evaluations under the Toxic Substances Control Act now mandate environmental fate testing for ionone imports above volume thresholds, extending registration timelines by 18-24 months for new suppliers. This regulatory friction elevates incumbent advantage among pre-1979 inventory chemical manufacturers while forcing prospective entrants into joint submission consortia. Fine fragrance houses in the United States increasingly specify TSCA-compliant certificates of analysis, filtering supplier pools regardless of price competitiveness.
Subscription-based technical support contracts now unbundle aroma chemical supply from formulation advisory services, with fragrance houses paying annual retainers for customized ionone profile development. This service-layer separation displaces traditional volume-discount negotiations in North American procurement departments. Specialty distributors in New Jersey and California pilot outcome-based pricing models tied to finished fragrance stability performance rather than input chemical tonnage.
Alpha Ionone Market Segmentation
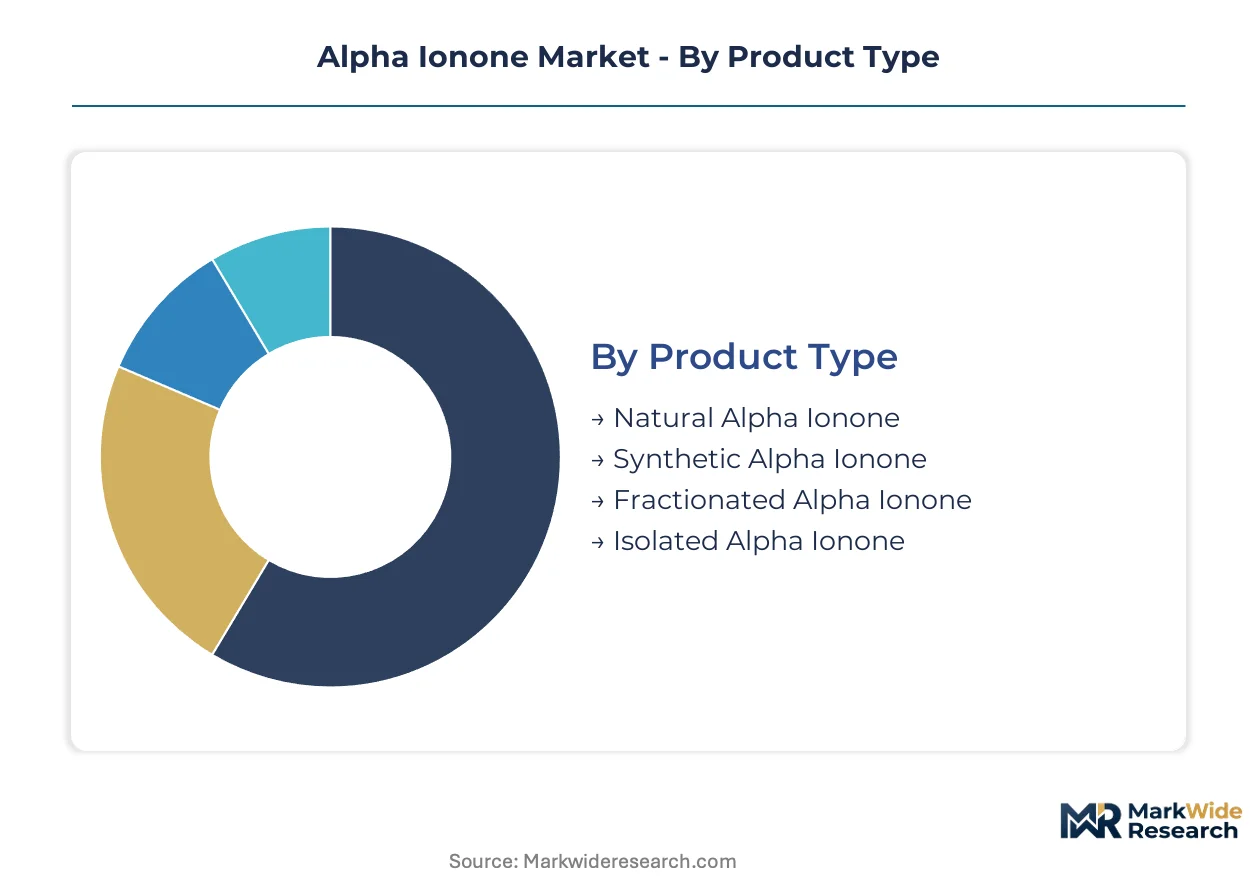
Alpha ionone procurement patterns diverge sharply across purity grades and end-use specifications. Formulation laboratories in France and Germany demand isomer-specific fractions that command technical premiums, while mass-market fragrance houses optimize for synthetic volume reliability.
Product Type:
Synthetic grades dominate tonnage, yet natural and fractionated variants capture margin through certification premiums and pharmaceutical precision requirements.
- Synthetic Alpha Ionone:Petrochemical-derived via acetone-cyclohexanone condensation routes, specified at minimum purity thresholds with defined specific gravity and refractive index parameters. Fragrance compounders in Geneva and Grasse specify synthetic grades for woody-floral accords where batch consistency outweighs botanical provenance. REACH pre-registration status among incumbent manufacturers creates procurement concentration effects that disadvantage new market entrants.
- Natural Alpha Ionone:Extracted from violet flowers and raspberry botanical sources at sub-kilogram yields per hectare, positioning this grade beyond mass-market accessibility. Clean-label fragrance segments in Switzerland and premium cosmetic lines in France absorb limited natural supply at price multiples that reflect agricultural yield constraints and extraction complexity.
- Fractionated Alpha Ionone:Membrane-assisted pervaporation achieves controlled alpha-to-beta isomer ratios for pharmaceutical synthesis applications.
- Isolated Alpha Ionone:Chromatographic separation delivers single-isomer purity for specialized therapeutic candidate development.
Today's leader: Synthetic Alpha Ionone. Tomorrow's challenger: Fractionated Alpha Ionone.
Application:
End-use concentration tracks regulatory jurisdiction clustering and formulation laboratory geography.
- Fragrances:Fine perfumery houses in Grasse and Geneva drive specification intensity for high-grade ionone with defined odor thresholds. IFRA concentration limits constrain formulation economics, directly influencing procurement volume decisions across European compounders.
- Pharmaceuticals:Controlled isomer ratios enable active ingredient synthesis for neurological therapeutic candidates, opening technical-grade supply contracts outside traditional perfumery channels. FDA and EMA purity documentation requirements elevate compliant supplier preference effects.
- Cosmetics:Personal care brands specify alpha ionone for violet-woody notes in skin and hair formulations.
- Food Flavoring:FSSAI and FDA flavor substance evaluations govern permissible applications in confectionery and beverage categories.
Fragrances anchor current procurement volumes. Pharmaceuticals are climbing the fastest as isomer-specific demand expands.
Distribution Channel:
Channel selection reflects buyer scale and specification complexity requirements.
- Direct Sales:Long-term supply contracts with embedded technical support dominate procurement for fragrance houses with dedicated formulation laboratories. Symrise AG and Givaudan SA anchor partnerships through integrated R&D platforms that unbundle chemical supply from advisory services.
- Wholesale:Regional distributors serve mid-sized compounders with standardized grade specifications and volume-discount structures.
- Specialty Stores:Small-batch procurement for independent perfumers and research institutions requiring custom isomer profiles.
- Online Retail:Specification-matching portals piloted by New Jersey and California distributors bypass traditional wholesale layers.
Direct Sales commands the premium tier. Online Retail is gaining share fastest through digital platform investments.
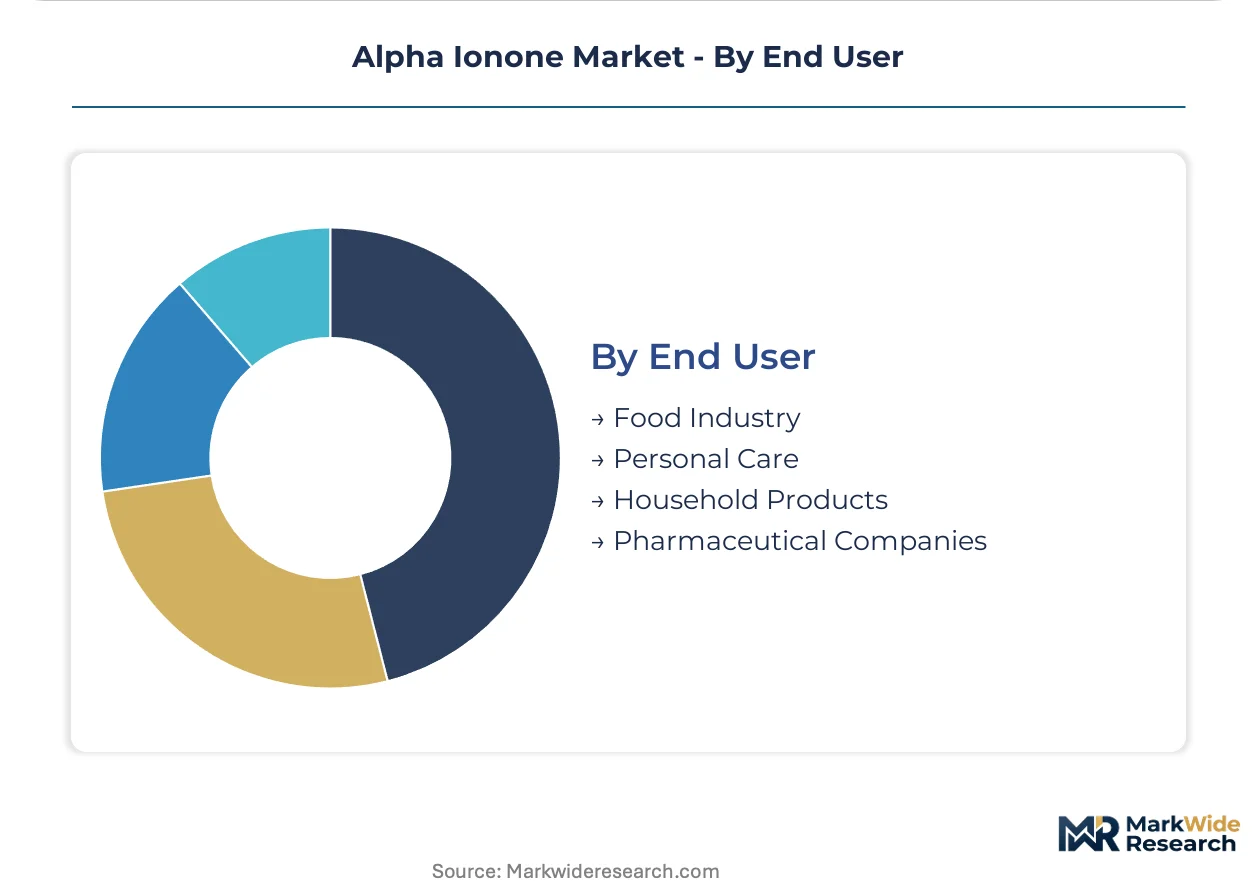
End User:
Customer type determines purity grade requirements and certification documentation intensity.
- Personal Care:Global personal care brands specify synthetic alpha ionone for volume reliability across multiple manufacturing sites. BASF SE sustains manufacturing scale that competes on supply security rather than customization depth.
- Pharmaceutical Companies:Controlled isomer ratios and batch-to-batch consistency certificates drive qualification timelines that favor pre-registered suppliers with established analytical protocols.
- Food Industry:Flavor houses in Germany and the United States concentrate demand for food-grade specifications with documented purity thresholds.
- Household Products:Mass-market fragrance applications for cleaning and air care products prioritize cost efficiency over isomer precision.
Personal Care leads procurement volumes. Pharmaceutical Companies represent the steepest expansion trajectory as neurological therapeutic pipelines mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
France concentrates fine perfumery demand while the United States anchors pharmaceutical-grade procurement, creating divergent specification intensity across Atlantic markets. Germany and Switzerland host precision chemical manufacturing that supplies both fragrance and therapeutic applications. India attracts contract manufacturing investment through scheme-based incentives and alignment with European certification standards.
France
Grasse-based formulation laboratories drive concentrated demand for high-grade alpha ionone with specified isomer ratios and defined odor thresholds. ANSM fragrance substance evaluations enforce documentation requirements that elevate compliant supplier preference effects among pre-registered chemical manufacturers. Geneva-proximate R&D clusters in neighboring Switzerland absorb fractionated grades for woody-floral accord development.
Germany
BASF SE sustains manufacturing scale across multiple production sites that compete on volume reliability for global personal care brands. REACH registration thresholds mandate purity documentation for ionone imports, creating procurement concentration among established chemical manufacturers. The ECHA dossier review timeline synchronizes with domestic formulation laboratory demand cycles in the Cologne-Düsseldorf corridor.
United States
FDA and EPA chemical substance evaluations under TSCA extend registration timelines for new ionone suppliers, elevating incumbent advantage among pre-1979 inventory chemical manufacturers. New Jersey and California distributors pilot specification-matching digital portals that bypass traditional wholesale layers. Fine fragrance houses increasingly specify TSCA-compliant certificates of analysis regardless of price competitiveness.
Switzerland
Clean-label fragrance segments absorb limited natural alpha ionone supply at price multiples reflecting agricultural yield constraints. Swissmedic therapeutic substance regulations intersect with fragrance chemical documentation for neurological pipeline applications. Basel-centered pharmaceutical R&D drives controlled isomer ratio demand that opens technical-grade supply contracts outside traditional perfumery channels.
India
BIS certification alignment and PLI scheme incentives for aroma chemical production attract European fragrance house contract manufacturing investment. CDSCO pharmaceutical substance evaluations create dual-track compliance requirements for suppliers serving both domestic and export markets. Maharashtra and Gujarat specialty chemical clusters absorb fermentation engineering talent for biocatalytic ionone production scale-up.
Alpha Ionone Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated fragrance houses commanding premium-tier relationships while volume suppliers compete on manufacturing scale. The supplier base concentrates around pre-registered chemical manufacturers with established REACH and TSCA compliance infrastructure. Three archetypes dominate: biotechnology-anchored innovators, petrochemical-scale incumbents, and natural-extraction specialists. Competitive moves center on fermentation capacity expansion and membrane separation technology licensing.
Within the integrated R&D tier, Symrise AG and Givaudan SA exemplify biotechnology-derived route development that reduces batch-to-batch variability. BASF SE occupies the scale-driven position across multiple production sites. These three represent divergent strategic anchors: service-layer unbundling, biocatalytic innovation, and manufacturing volume reliability.
| Leading Market Players |
|---|
| Symrise AG |
| International Flavors & Fragrances Inc. |
| BASF SE |
| Sensient Technologies Corporation |
| Robertet Group |
| Firmenich SA |
| Takasago International Corporation |
| Axxence Aromatic GmbH |
| Givaudan SA |
| Others |
Value Network & Pricing Analysis
Fragrance houses with dedicated formulation laboratories in Grasse and Geneva anchor procurement concentration that sustains premium pricing for isomer-specific grades while mass-market compounders negotiate synthetic volume contracts on cost efficiency metrics.
Pricing Analysis
Capacity additions in India and China are reshaping price floors for standard synthetic grades. Three-tier pricing structure across premium, standard, and economy levels separates membrane-purified pharmaceutical grades from commodity fragrance specifications and bulk industrial volumes. Cost compression in standard synthetic tiers intensifies because petrochemical feedstock volatility transfers margin pressure to contract manufacturers. Mass-market household product brands exhibit highest price sensitivity while pharmaceutical companies absorbing fractionated grades prioritize batch consistency over unit economics.
Supply Chain Analysis
Dual-sourcing mandates from European fragrance houses require simultaneous qualification of German and Indian suppliers for REACH-compliant grades. Manufacturing concentrates in Germany, India, and Switzerland with fermentation engineering talent shortages constraining biocatalytic capacity expansion. Feedstock dependencies center on acetone-cyclohexanone petrochemical streams, geraniol botanical extracts, and engineered yeast strain nutrient media. Single-source vulnerability persists for membrane separation equipment specialized to isomer purification. Distribution runs through direct technical partnerships for premium tiers and regional wholesale networks for standardized volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Alpha ionone functions as a stable compounder anchored by regulatory compliance requirements that perpetually refresh supplier qualification cycles and sustain incumbent advantage.
For Market Incumbents: Anchor manufacturing scale across multiple production sites to sustain volume reliability commitments against biotech-derived substitute materials threatening batch-to-batch consistency premiums. Invest in membrane separation technology licensing to defend margin position from fermentation-based entrants. Prioritize REACH and TSCA registration maintenance as regulatory leverage against unqualified competitors. For New Entrants and Emerging Players: The gap between pharmaceutical-grade fractionated pricing and commodity synthetic tiers offers white-space entry for biocatalytic specialists achieving stereoselective purity without downstream distillation. Target mid-sized fragrance houses in North America seeking supply diversification beyond established European suppliers. Deploy specification-matching digital platforms to bypass entrenched wholesale relationships and capture margin from fragmented buyer bases. For Investors and Strategic Acquirers: Integrated fragrance houses with captive aroma chemical production are the most active acquirer in this space, consolidating biotech fermentation capabilities to secure supply chain control. Long-term viability favors suppliers with dual-route manufacturing flexibility across petrochemical and biocatalytic platforms. Watch bioprocess scale-up engineering talent migration as the inflection signal for competitive positioning shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Biocatalytic Production Scale-Up | Engineered yeast strains eliminate fractional distillation steps that previously constrained pharmaceutical-grade yields. |
| Membrane Separation Technology Licensing | Pervaporation systems reduce energy intensity metrics that disadvantaged synthetic routes against natural extraction claims. |
| Backward Integration into Feedstock Supply | Captive geraniol cultivation secures botanical input streams for natural-grade positioning in clean-label segments. |
| Joint Regulatory Submission Consortia | Shared EPA and ECHA dossier costs reduce compliance barriers for prospective entrants into Atlantic markets. |
| Direct-to-Compounder Digital Platform Launch | Specification-matching portals capture margin from mid-sized fragrance houses bypassing traditional wholesale layers. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary discussions engaged fragrance compounders, pharmaceutical procurement leads, fermentation engineering directors, and specialty chemical distributors. Secondary validation drew from ECHA REACH dossiers, EPA TSCA filings, customs trade data, and IFRA concentration limit documentation. Bottom-up volume modeling triangulated against top-down market sizing across grade tiers and end-use applications.
Historical reference periods anchored projections across the analysis window with CAGRs derived from segment-level growth rate reconciliation. Segmentation dimensions included purity grade, isomer ratio specification, end-use industry, and regional regulatory cluster. Forecast inputs incorporated biocatalytic yield improvement trajectories, membrane separation technology adoption curves, and REACH registration timeline synchronization effects.
Caveats apply where feedstock cost volatility, bioprocess scale-up engineering shortages, or regulatory evaluation timeline extensions could materially shift the outlook. Deviation in fermentation capacity expansion rates would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flavor and Fragrance Chemicals
Aromatics Market
Flavor and Fragrance Chemicals
Middle East and Africa Deodorants Market
Flavor and Fragrance Chemicals
Global Bio Vanillin Market
Flavor and Fragrance Chemicals
Synthetic Cinnamaldehyde Market
Flavor and Fragrance Chemicals
Fragrance Fixatives Market
Flavor and Fragrance Chemicals
Synthetic Musk Market
Flavor and Fragrance Chemicals
Gel Air Fresheners Market
Flavor and Fragrance Chemicals
Tannic Acid Market
Flavor and Fragrance Chemicals
India Aroma Chemicals Market
Flavor and Fragrance Chemicals
Neryl Acetate Market
Flavor and Fragrance Chemicals
Sensory Modifiers Market
Flavor and Fragrance Chemicals
Peel Oil Market
Flavor and Fragrance Chemicals
Asia-Pacific Aroma Chemicals Market
Flavor and Fragrance Chemicals
Europe Flavors and Fragrances Market
Flavor and Fragrance Chemicals
Global Natural Cinnamic Aldehyde Market
Flavor and Fragrance Chemicals
4-Allylanisole Market