
 United States Cigarette Lighter Market | 2026-2036
United States Cigarette Lighter Market Size, Share, and Industry Trends Forecast 2026-2036
United States Cigarette Lighter Market Intelligence
Subscription-based flameless accessory services is restructuring how lighter brands monetize repeat engagement beyond the initial hardware sale. Zippo Manufacturing Company leverages its iconic metal refillable platform to sustain premium pricing through lifetime warranty programs. Société Bic S.A. anchors the mass-market disposable segment through gas station and convenience store channel dominance. Colibri differentiates in the specialty tier with precision-engineered torch mechanisms aimed at cigar aficionados.
A cigarette lighter is a portable ignition device typically employing piezoelectric spark generation or flint-wheel friction to produce flame from pressurized butane or naphtha fuel, with body construction ranging from injection-molded ABS plastic to brass and zinc alloys rated for thermal durability. Its primary commercial purpose spans tobacco ignition, culinary torch applications, and emergency fire-starting for outdoor recreation. Disposable plastic lighters dominate unit volume through gas station impulse purchases, while refillable metal variants command the margin pool due to replacement part ecosystems and collector aftermarket activity. Electronic arc lighters represent the fastest-growing product type as USB-rechargeable lithium-polymer cells displace fuel dependency in windproof applications.
The Consumer Product Safety Commission enforces child-resistance testing protocols under 16 CFR Part 1210, forcing redesign of ignition mechanisms and elevating compliance costs for imported units. California Proposition 65 labeling requirements for butane exposure warnings add state-level packaging complexity that shapes distributor inventory segmentation. The Pipeline and Hazardous Materials Safety Administration regulates lighter transportation classifications, constraining e-commerce fulfillment infrastructure for direct-to-consumer channels. Stakeholders must monitor evolving state-level flavored tobacco restrictions, as these policies indirectly compress lighter demand through smoking rate suppression in jurisdictions like Massachusetts and New York.
Market Dynamics
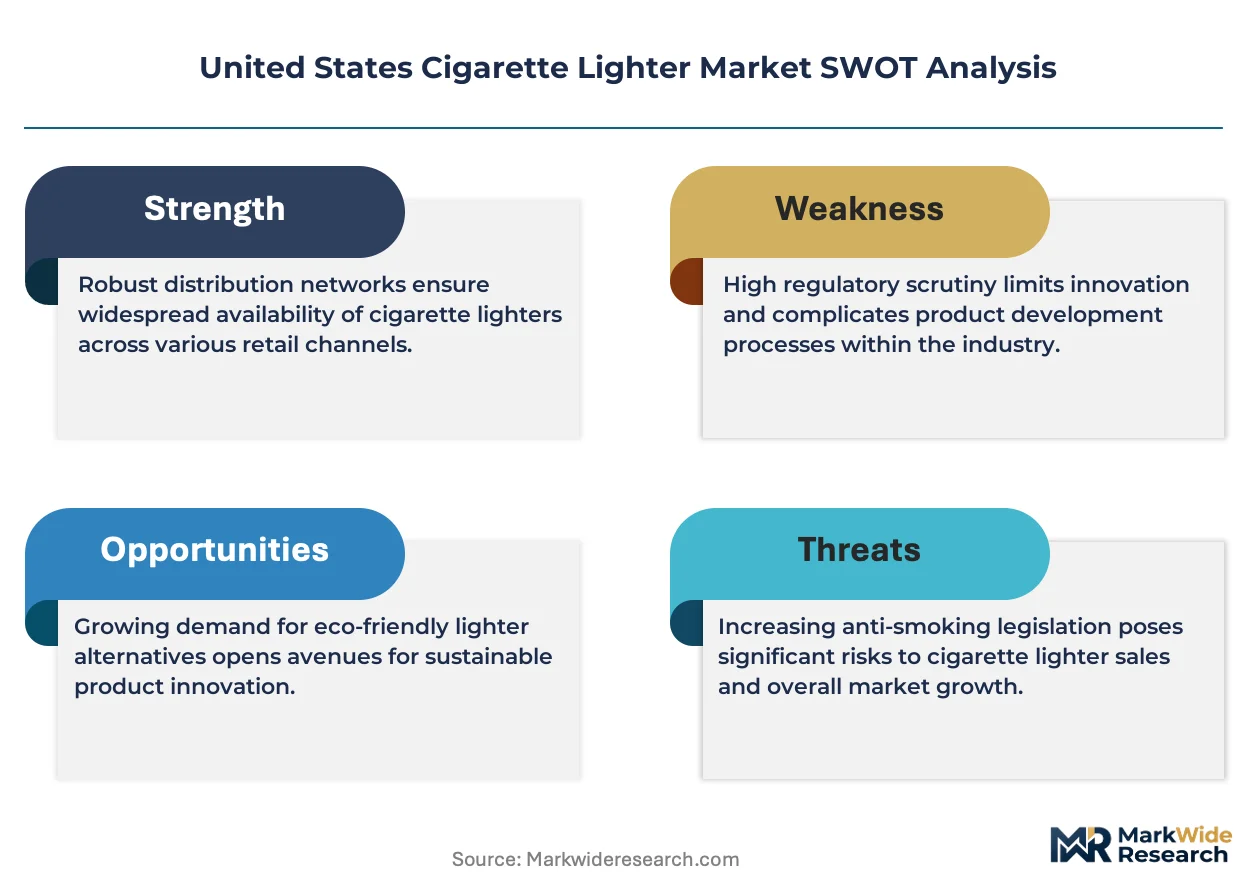
The Consumer Product Safety Commission's child-resistance mandate under 16 CFR Part 1210 is forcing comprehensive ignition mechanism redesign across domestic manufacturing and import channels, elevating compliance costs while compressing profit margins for low-cost disposable producers.
Growth Catalysts
- Outdoor recreation expansion:Camping participation rates in California and Texas drive demand for windproof and emergency fire-starting lighter variants.
- 16 CFR Part 1210 compliance:Child-resistance certification creates barrier-to-entry advantages for established domestic manufacturers with testing infrastructure.
- USB-rechargeable lithium-polymer cells:Electronic arc technology eliminates fuel dependency for outdoor enthusiasts prioritizing reliability.
Market Restraints
- Butane price volatility:Pressurized fuel costs fluctuate with petrochemical feedstock markets, squeezing margins on disposable plastic units.
- California Proposition 65 labeling:Butane exposure warning requirements add packaging complexity and inventory segmentation costs for national distributors.
- Flavored tobacco restrictions:Massachusetts and New York policies suppress smoking rates and indirectly compress lighter demand in affected jurisdictions.
Strategic Opportunities
- Subscription accessory services:Recurring revenue models for flameless accessories monetize engagement beyond initial hardware transactions.
- Collector aftermarket activity:Limited-edition metal refillable releases command premium pricing from enthusiast communities.
- Cigar aficionado precision tools:Torch mechanism specialization targets high-margin specialty retail channels.
Industry Challenges
- PHMSA transportation classification:Pipeline and Hazardous Materials Safety Administration regulations constrain e-commerce fulfillment infrastructure for direct-to-consumer channels.
- Ignition mechanism engineering:Child-resistance redesign demands specialized mechanical expertise scarce among mid-tier manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Cigarette Lighter Market |
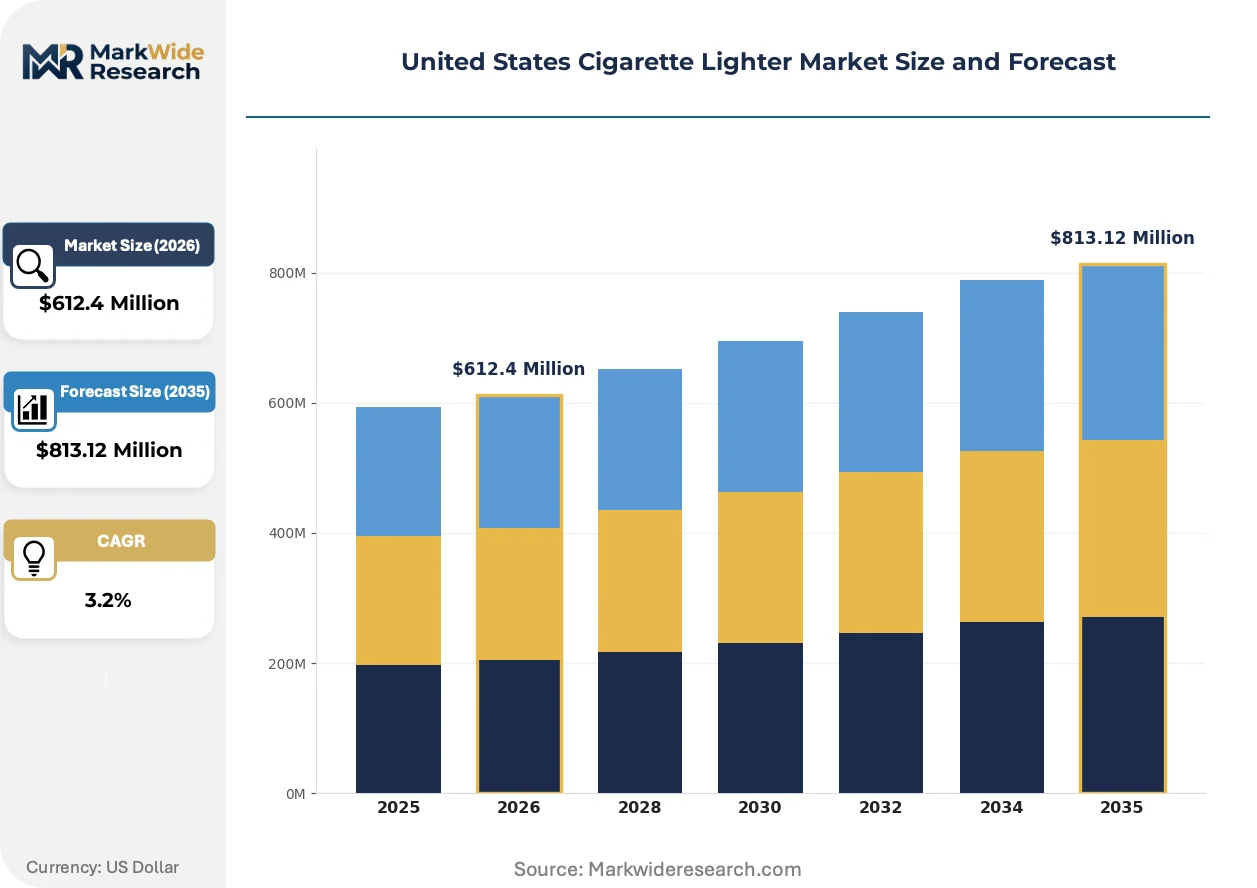
| Market Size in 2026 | $612.4 Million |
| Market Size in 2035 | $813.12 Million |
| CAGR (2026 – 2036) | 3.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Disposable, Refillable, Electronic, Specialty Material: Metal, Plastic, Glass, Wood Distribution Channel: Supermarkets, Convenience Stores, Online Retail, Gas Stations End User: Smokers, Campers, Outdoor Enthusiasts, Collectors |
| Companies Covered | Flamagas S.A., Colibri, Zippo Manufacturing Company, Dickson Concepts, Visol Products, Société Bic S.A, Tokai Co., Ltd., NingBo XINHAI Electric Co., LTD, Swedish Match Cricket, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Cigarette Lighter Market Strategic Shifts & Innovations
Product architecture and distribution channels are undergoing simultaneous transformation as fuel-based systems face regulatory pressure and electronic alternatives capture outdoor recreation segments.
Electronic arc ignition systems utilizing USB-rechargeable lithium-polymer cells is decentralizing fuel supply dependency for windproof applications. Outdoor enthusiasts and emergency preparedness buyers are adopting these units at accelerating rates through specialty retail and direct channels. This shift is decentralizing traditional gas station and convenience store distribution dominance while compressing butane supply chain relevance.
The Consumer Product Safety Commission's enforcement of 16 CFR Part 1210 child-resistance testing protocols is mandating ignition mechanism complexity increases. Domestic manufacturers with captive testing laboratories gain compliance timeline advantages over import-dependent competitors. Disposable plastic lighter segments face disproportionate cost pressure as redesign requirements intersect with thin margin structures.
Subscription-based flameless accessory services are unbundling hardware ownership from ongoing engagement. Camping and outdoor recreation buyers increasingly prefer curated accessory replenishment over transactional retail purchases. California and Texas demonstrate highest adoption density due to concentrated outdoor participation rates and direct-to-consumer logistics infrastructure maturity.
United States Cigarette Lighter Market Segmentation
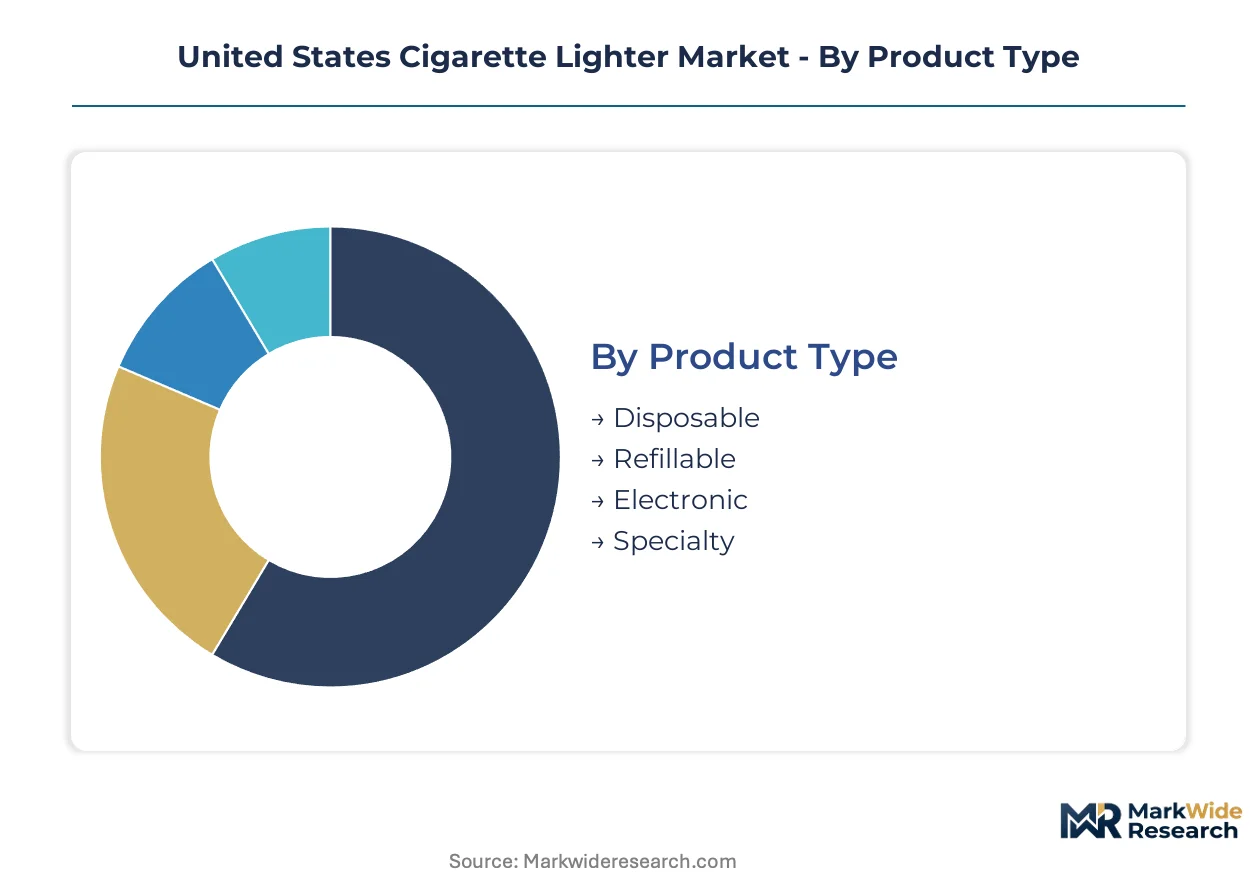
Product architecture and buyer behavior fragment across four distinct dimensions in the United States Cigarette Lighter Market. Each segmentation layer reveals divergent margin structures, compliance burdens, and channel dependencies that reshape competitive positioning.
Product Type:
Customization intensity spans from mass-produced single-use units to precision-engineered specialty tools with proprietary ignition systems.
- Disposable:Injection-molded ABS plastic bodies with piezoelectric ignition dominate unit volume through gas station impulse purchases. California and Texas absorb disproportionate flow due to elevated tobacco use rates and convenience store density. The Consumer Product Safety Commission's 16 CFR Part 1210 child-resistance mandate squeezes margins as redesign costs concentrate in this low-price tier.
- Electronic:USB-rechargeable lithium-polymer cells with arc-plasma ignition eliminate fuel dependency for windproof applications. Outdoor enthusiasts in California and Texas drive adoption through specialty retail and direct channels, displacing traditional butane supply chains.
- Refillable:Brass and zinc alloy construction supports lifetime warranty programs and replacement part ecosystems.
- Specialty:Precision torch mechanisms target cigar aficionados through high-margin specialty retail channels.
Most installed capacity flows through Disposable. Expansion is steepest in Electronic.
Material:
Cost tier stratification separates premium metal variants from commodity plastic units with divergent thermal durability ratings.
- Metal:Brass and zinc alloys rated for thermal durability command premium pricing through collector aftermarket activity and lifetime warranty programs. Refillable platform economics concentrate margin capture in this tier.
- Plastic:Injection-molded ABS dominates disposable production volumes with thin margins vulnerable to petrochemical feedstock volatility.
- Glass:Limited specialty applications in windproof casing designs for premium outdoor segments.
- Wood:Artisan and limited-edition collector releases targeting enthusiast communities.
Volume concentrates in Plastic. Value capture concentrates in Metal.
Distribution Channel:
Channel maturity separates established brick-and-mortar impulse infrastructure from emerging direct-to-consumer logistics constrained by hazardous materials regulations.
- Gas Stations:Impulse purchase dominance for disposable plastic units leverages tobacco adjacency and convenience positioning. California and Texas maintain highest outlet density.
- Convenience Stores:Similar impulse dynamics with extended operating hours capturing emergency replacement demand.
- Online Retail:Electronic arc lighter adoption accelerates through direct channels, though Pipeline and Hazardous Materials Safety Administration transportation classifications constrain fuel-based product fulfillment.
- Supermarkets:Mass-market presence with limited specialty or collector-tier penetration.
Transaction density peaks at Gas Stations. Margin expansion runs through Online Retail.
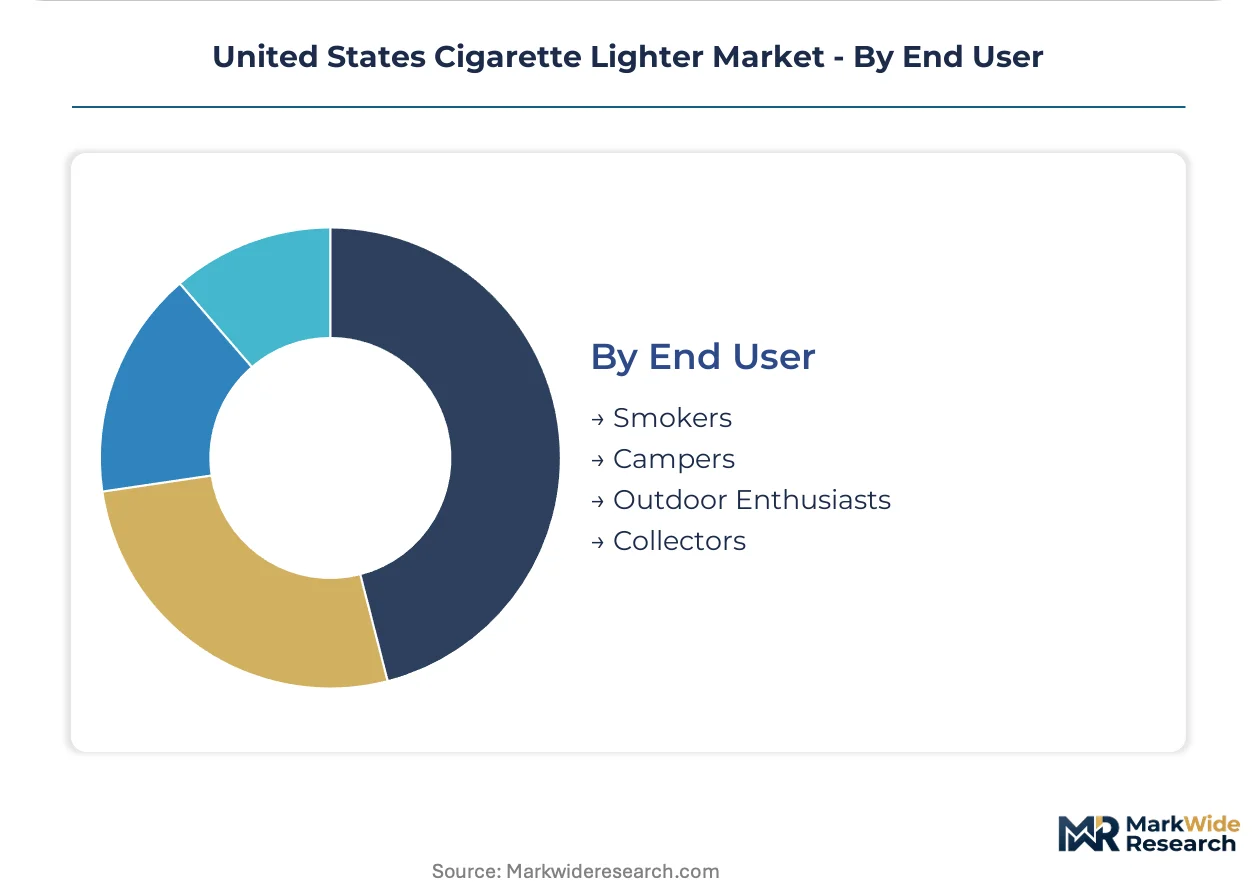
End User:
Application specificity ranges from habitual tobacco use to intermittent recreational and speculative collection behaviors.
- Smokers:Core demand driver with California and Texas concentration reflecting elevated tobacco use rates. Flavored tobacco restrictions in Massachusetts and New York indirectly compress this segment in affected jurisdictions.
- Outdoor Enthusiasts:Camping participation growth in California and Texas fuels demand for windproof and emergency fire-starting variants. Electronic arc technology gains fastest adoption here.
- Campers:Overlapping outdoor segment with specific emphasis on reliability and weather resistance.
- Collectors:Limited-edition metal refillable releases command premium pricing from enthusiast communities with active secondary market participation.
Volume anchors in Smokers. Value growth concentrates in Outdoor Enthusiasts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production migration patterns in the United States Cigarette Lighter Market reflect divergent state-level compliance burdens. Manufacturers with captive testing infrastructure concentrate in jurisdictions with lighter regulatory overlay, while import-dependent distributors face elevated child-resistance certification costs.
California
California absorbs disproportionate lighter flow through gas station and convenience store density. Proposition 65 butane exposure warning requirements add packaging complexity that shapes distributor inventory segmentation. Los Angeles and San Diego metropolitan clusters anchor outdoor recreation retail channels where electronic arc lighter adoption accelerates fastest.
Texas
Texas matches California in tobacco use rates and camping participation, driving parallel demand for disposable and windproof variants. The state lacks California's labeling mandates, creating arbitrage opportunities for national distributors routing inventory through Dallas-Fort Worth logistics hubs. Houston and Austin specialty retail corridors concentrate electronic lighter penetration.
New York
New York's flavored tobacco restrictions indirectly compress lighter demand through smoking rate suppression in metropolitan markets. The state's stringent fire safety codes elevate barrier-to-entry for disposable plastic imports. Buffalo and Rochester industrial zones host limited domestic assembly operations serving Northeast corridor distribution.
Florida
Florida's tourism economy sustains steady replacement demand through convenience retail along interstate corridors. The state operates under standard federal CPSC protocols without additive state-level chemical labeling. Miami and Orlando metropolitan areas concentrate cigar aficionado specialty retail where precision torch mechanisms command premium positioning.
Illinois
Illinois anchors Midwest distribution infrastructure with Chicago-based warehousing serving regional gas station and convenience store networks. The state's central location offsets elevated transportation classification costs under PHMSA regulations. Limited local manufacturing concentrates on refillable metal platform assembly for collector and warranty-service markets.
United States Cigarette Lighter Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments in the United States Cigarette Lighter Market. Disposable plastic production concentrates among high-volume OEM fabricators with thin margin tolerance, while refillable metal and specialty torch tiers sustain branded premium positioning. Three archetypes dominate: heritage manufacturers with lifetime warranty ecosystems, mass-market disposable specialists with convenience channel dominance, and precision-engineered specialty tool providers. Competitive moves center on ignition mechanism patent licensing and captive testing laboratory acquisition to compress CPSC compliance timelines.
Within the heritage branded tier, Zippo Manufacturing Company exemplifies lifetime warranty platform economics. Société Bic S.A. anchors mass-market disposable positioning through gas station and convenience store channel density. Colibri occupies the specialty precision-tool segment serving cigar enthusiast retail channels. These three represent divergent margin-capture strategies across the value chain.
| Leading Market Players |
|---|
| Flamagas S.A. |
| Colibri |
| Zippo Manufacturing Company |
| Dickson Concepts |
| Visol Products |
| Société Bic S.A |
| Tokai Co., Ltd. |
| NingBo XINHAI Electric Co., LTD |
| Swedish Match Cricket |
| Others |
Cost & Logistics Intelligence
Family-owned mid-cap manufacturers in Pennsylvania and Ohio anchor domestic refillable metal lighter production, connecting concentrated ownership structures to disciplined premium pricing and captive warranty-service networks that resist commodity erosion.
Pricing Analysis
Capacity additions in Mexico and Southeast Asia are reshaping price floors for disposable plastic tiers while premium metal segments maintain insulation. Three-tier pricing structure across premium, standard, and economy levels separates lifetime-warrantied brass collectibles from mid-grade refillables and commodity disposables. Price differentiation hinges on CPSC certification tier and thermal durability ratings. Cost compression in disposable segments is intensifying because 16 CFR Part 1210 compliance redesigns intersect with thin margins. Gas station impulse buyers demonstrate highest price sensitivity; cigar specialty purchasers show least.
Supply Chain Analysis
Domestic-content mandates under Buy American provisions for federal procurement are reshaping sourcing patterns for institutional and military-specification lighters. Manufacturing concentrates in China, Mexico, and domestic Pennsylvania-Ohio corridor facilities. Raw material dependencies span Taiwanese lithium-polymer cells, Saudi petrochemical feedstock for ABS resin, and Zambian copper for brass alloys. Single-source vulnerability sits with Chinese piezoelectric ignition component suppliers facing tariff exposure. Distribution runs through Dallas-Fort Worth and Chicago logistics hubs serving regional convenience store networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States Cigarette Lighter Market reads as a late-cycle quality story, with demand shifting toward precision-engineered torch mechanisms and USB-rechargeable electronic platforms that command sustainable margin premiums over commodity disposables.
For Market Incumbents: Acquire captive testing laboratory assets to compress CPSC 16 CFR Part 1210 certification timelines against import-dependent competitors. Secure exclusive channel placement in California specialty outdoor retail corridors where electronic arc adoption accelerates fastest. Backward integration into brass alloy casting insulates against Zambian copper price volatility threatening refillable platform economics. For New Entrants and Emerging Players: Direct-to-consumer subscription accessory services offer the most penetrable white-space target, with California and Texas outdoor enthusiasts demonstrating highest adoption density for curated flameless replenishment models. Bypass PHMSA-constrained fuel-based fulfillment by launching USB-rechargeable SKUs exclusively. Partner with camping gear influencers for authentic credibility transfer in specialty recreation segments. For Investors and Strategic Acquirers: Valuations sit cheapest among import-dependent disposable plastic specialists facing margin compression from compliance redesign costs. Long-term viability favors domestic manufacturers with captive testing infrastructure and collector aftermarket participation. Watch electronic arc lighter penetration rates in California specialty retail as the signal for inflection toward fuel-independent technology platforms.| Strategic Initiative | Industry Significance |
|---|---|
| CPSC Testing Laboratory Acquisition | Domestic manufacturers with captive 16 CFR Part 1210 certification capabilities compress compliance timelines against import competitors. |
| Subscription Accessory Service Launch | Recurring revenue models monetize camper engagement beyond initial hardware transactions in California and Texas corridors. |
| Electronic Arc Platform Expansion | USB-rechargeable lithium-polymer systems displace butane dependency for windproof outdoor applications. |
| Specialty Torch Mechanism Development | Precision-engineered ignition systems capture cigar aficionado demand through high-margin retail channels in Miami and Orlando. |
| Collector Limited-Edition Releases | Limited brass alloy runs activate enthusiast secondary markets and sustain premium pricing through scarcity economics. |
Research Approach
Direct dialogue with CPSC compliance officers, convenience store category managers, outdoor specialty retail buyers, and brass alloy procurement directors grounded qualitative findings in operational reality. Secondary validation drew from CPSC enforcement databases, PHMSA transportation classification rulings, California Proposition 65 regulatory filings, and camping participation surveys from the Outdoor Industry Association. Bottom-up demand modeling across product tiers triangulated against top-down macroeconomic indicators.
Segmented outputs across the projection horizon reflect discrete modeling of disposable, electronic, refillable, and specialty product architectures alongside material-grade stratification and channel-specific velocity patterns. CAGRs emerged from regression analysis against tobacco use rate trajectories, outdoor recreation participation indices, and electronic technology substitution curves. Input assumptions incorporated butane price volatility bands and state-level flavored tobacco restriction scenarios.
The model assumes a particular technology adoption path; alternative pathways for solid-state electronic ignition would alter the outlook if lithium-polymer cost curves steepen unexpectedly. Forecasts reflect documented assumptions around CPSC enforcement intensity and PHMSA regulatory stability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smoking Accessories
China Smoking Accessories Market
Smoking Accessories
Lighter Market
Smoking Accessories
Smoking Pipe Market
Smoking Accessories
Japan Smoking Accessories Market
Smoking Accessories
Pocket Flask Market
Smoking Accessories
UK Smoking Pipe Market
Smoking Accessories
China Smoking Pipe Market
Smoking Accessories
North America Smoking Pipe Market
Smoking Accessories
Pocket Lighter Market
Smoking Accessories
Smoking Accessories Market
Smoking Accessories
Global Blunt Wrap Market
Smoking Accessories
Hookah Products Market
Smoking Accessories
Electric Pocket Lighter Market
Smoking Accessories
Herb Grinder Market
Smoking Accessories
Ashtray Market
Smoking Accessories
Wearable Tailgating Keg Market