
 Wearable Tailgating Keg Market | 2026-2036
Wearable Tailgating Keg Market Size, Share, and Industry Trends Forecast 2026-2036
Wearable Tailgating Keg Market Insights
Domestic stainless steel fabrication capacity in the United States is expanding to serve portable beverage container demand. American Keg Company leverages its Pennsylvania-based metalworking heritage to sustain domestic production of welded cylindrical vessels. THIELMANN anchors European supply through its German engineering base, while Petainer competes with hybrid stainless-and-polymer designs that reduce shipping weight for remote tailgating locations.
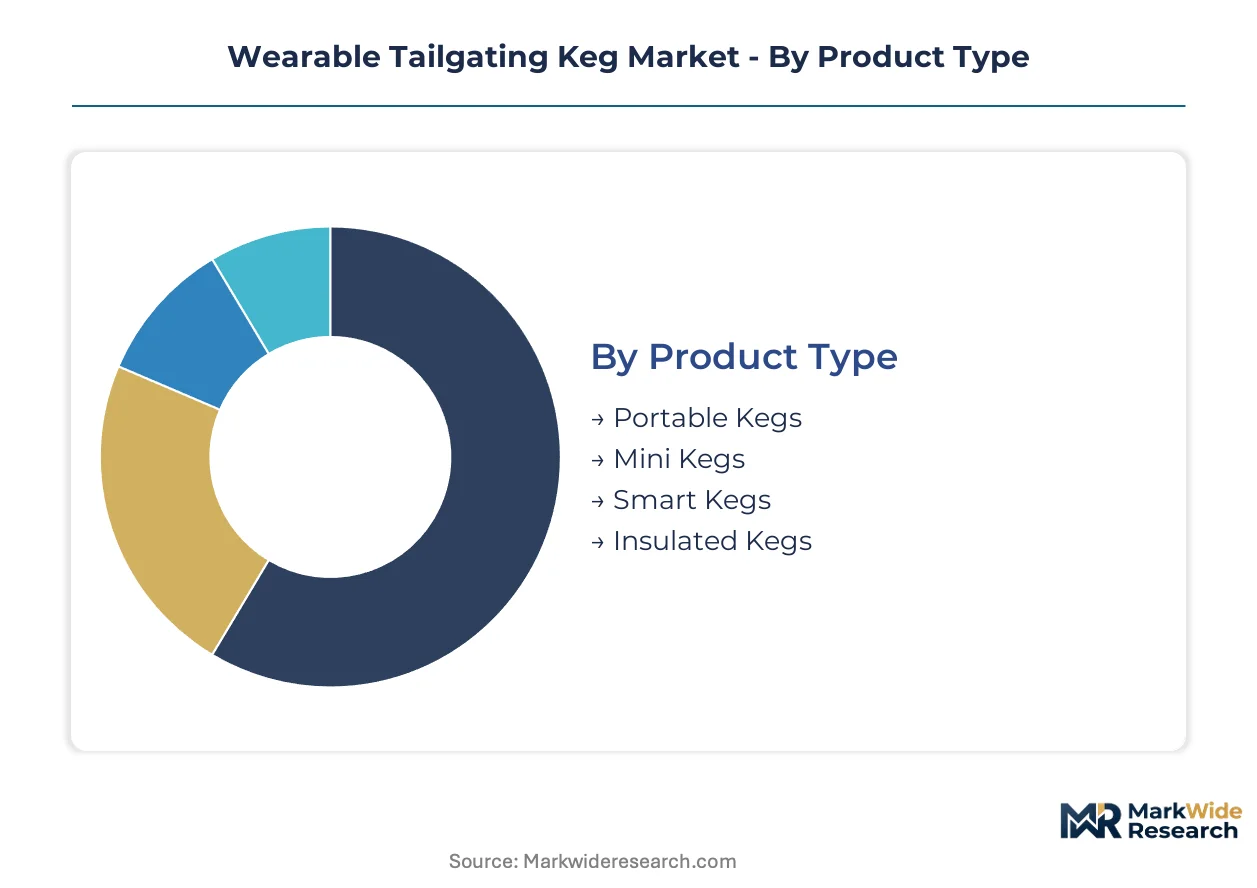
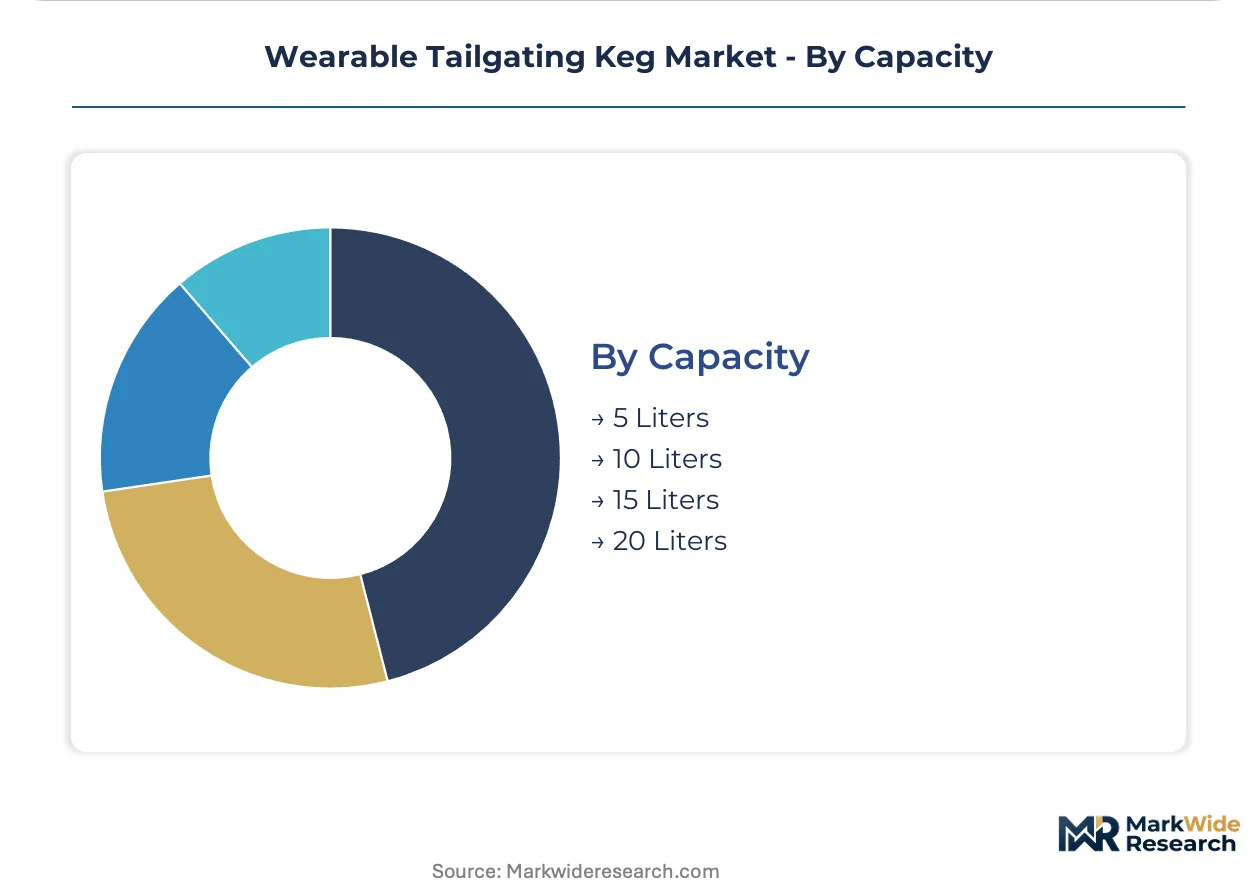
A wearable tailgating keg is a self-contained, manually portable beverage dispensing vessel engineered to maintain carbonation and thermal stability during outdoor social events, typically constructed with double-wall insulation and integrated tap mechanisms. Stainless steel variants dominate commercial-grade applications due to pressure tolerance and repeated sanitization cycles, while plastic and composite alternatives occupy price-sensitive recreational segments. Smart kegs with integrated chilling and monitoring functionality represent the fastest-growing product category, though insulated passive designs still command the largest volume share. Five-liter and ten-liter capacities lead consumer purchases, with twenty-liter units concentrating in rental and event-service channels.
FDA food-contact regulations govern interior surface coatings and sealing materials for all kegs distributed in the United States, while ISO 9001 quality management standards shape supplier qualification for European export markets. EPA guidelines on refrigerant systems influence electric chilling module designs in smart keg variants. Stakeholders must track evolving state-level container deposit legislation and stadium-specific alcohol policies that determine where portable dispensing systems gain event access.
Market Dynamics
Stadium alcohol policy liberalization across NCAA Division I conferences is reshaping where portable dispensing systems gain event access, forcing manufacturers to engineer rapid-cooling modules that satisfy venue security protocols while preserving beverage quality.
Growth Catalysts
- SEC and Big Ten conference tailgating expansions:Collegiate athletic departments in the United States are loosening parking-lot beverage restrictions, creating permitted zones for personal dispensing equipment that drives five- and ten-liter unit sales.
- FDA food-contact coating compliance:Interior surface material standards for beverage vessels are accelerating supplier qualification timelines, locking in certified manufacturers while excluding uncertified imports from legitimate distribution channels.
- Double-wall vacuum insulation:Thermal retention technology originally developed for commercial foodservice is migrating into consumer-grade tailgating equipment, extending ice-free cooling duration from four hours to eighteen hours.
Market Restraints
- 304-grade stainless steel price volatility:Nickel content fluctuations in austenitic steel alloys are compressing fabrication margins, forcing Pennsylvania and Ohio metalworkers to absorb cost spikes or pass through to price-sensitive recreational buyers.
- Chinese polymer component concentration:Polypropylene tap handles and silicone gasket supply chains cluster in Zhejiang province, exposing assemblers to tariff uncertainty and ocean freight rate spikes during peak tailgating season.
- Carbonation pressure tolerance ceilings:Passive insulated designs without active chilling cannot maintain dissolved CO2 levels above 2.5 volumes beyond six hours, limiting craft beer compatibility and ceding share to electric smart keg alternatives.
Strategic Opportunities
- Canadian prairie provinces:Saskatchewan and Manitoba lack established tailgating infrastructure despite comparable football culture, presenting first-mover positioning for rental-service models at Canadian Football League venues.
- Integrated IoT monitoring modules:Bluetooth-enabled temperature and pressure sensors combined with smartphone applications are creating subscription revenue streams from collegiate Greek life organizations managing shared equipment pools.
- EPA refrigerant transition timelines:Hydrofluorocarbon phase-down mandates are accelerating electric chilling module redesign around propane-based cooling systems, rewarding early engineering investment with regulatory compliance headroom.
Industry Challenges
- Welding technician scarcity:Orbital TIG welding certification for food-grade cylindrical vessels requires eighteen-month apprenticeship pipelines that Pennsylvania vocational programs cannot currently fill.
- Multi-jurisdiction alcohol transport permits:Cross-state collegiate rivalry game attendance requires manufacturers to navigate fifty distinct open-container statutes, complicating direct-to-consumer shipping logistics.
- Smart keg firmware update cycles:Connected chilling units demand ongoing cybersecurity patching that strains technical support capacity at mid-tier assemblers without captive software engineering teams.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wearable Tailgating Keg Market |
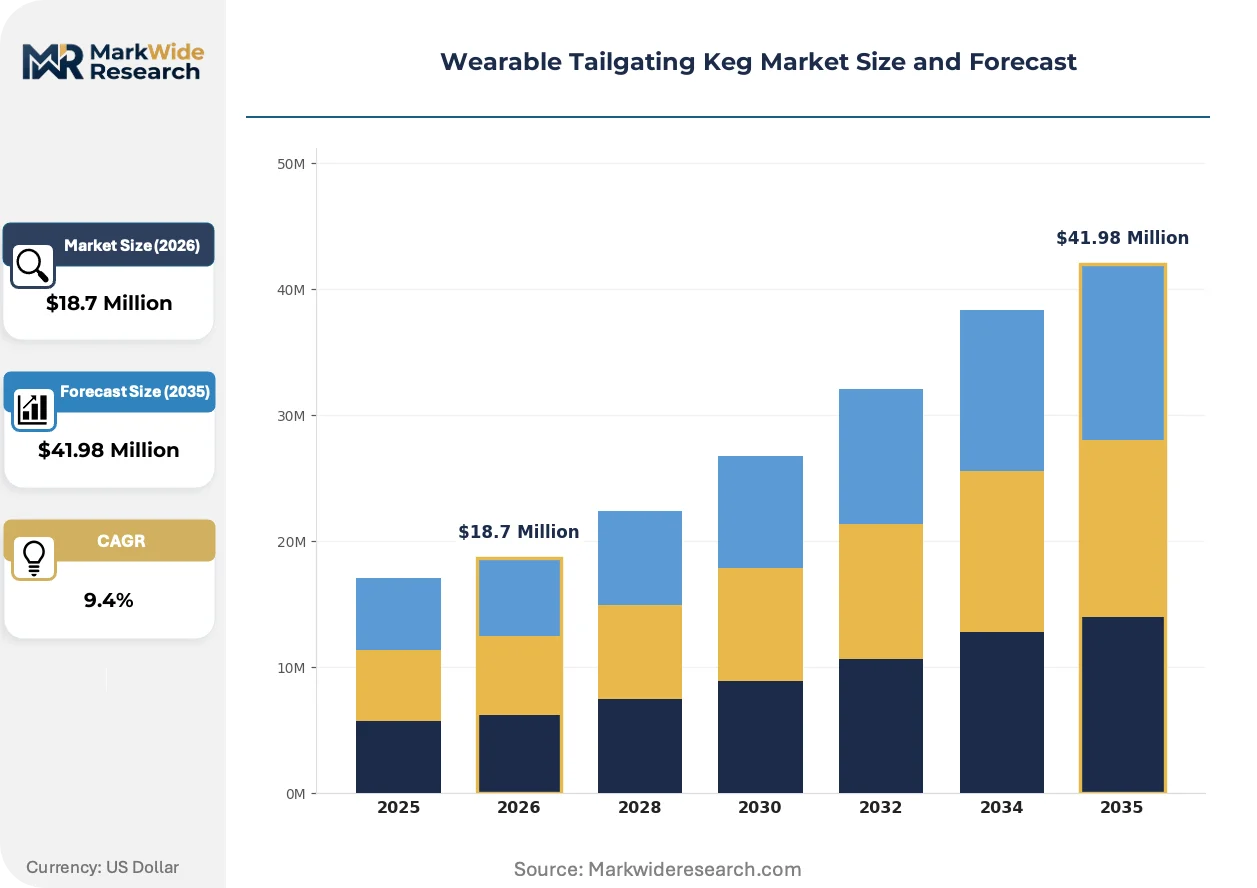
| Market Size in 2026 | $18.7 Million |
| Market Size in 2035 | $41.98 Million |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Kegs, Mini Kegs, Smart Kegs, Insulated Kegs Material: Stainless Steel, Plastic, Aluminum, Composite Functionality: Chilling, Dispensing, Carbonation, Monitoring Capacity: 5 Liters, 10 Liters, 15 Liters, 20 Liters |
| Companies Covered | American Keg Company, Dolium, Thirstburst, Schaefer Container Systems, Blefa GmbH, Odditymall, Petainer, THIELMANN – The Container Company, Wyndham, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wearable Tailgating Keg Market Trends and Innovations
Active chilling technology is compressing the performance gap between rental-grade equipment and consumer purchases, while regulatory pressure on refrigerant chemistry is forcing module redesign ahead of hardware replacement cycles.
Electrochemical solid-state cooling chips are overtaking thermoelectric Peltier elements in premium smart keg designs. Collegiate athletic department procurement offices are specifying solid-state modules for field-level hospitality suites. This thermal management approach is overtaking compressor-based alternatives in weight-constrained applications where vibration and noise restrictions apply.
EPA hydrofluorocarbon phase-down regulations under the American Innovation and Manufacturing Act are mandating refrigerant chemistry transitions by 2028. Chilling module suppliers must redesign heat exchange systems around A2L-classified propane blends. Electric smart keg manufacturers serving the United States market are accelerating qualification testing to secure EPA SNAP approvals ahead of import deadline constraints.
Subscription-based equipment pooling is displacing individual ownership among urban alumni chapters. Chicago and Detroit metropolitan area fan clubs are contracting with regional event rental services for guaranteed game-day availability. This procurement model compression is most visible in Great Lakes cities where apartment-dwelling millennials lack storage capacity for seasonal tailgating equipment.
Wearable Tailgating Keg Market Segmentation
Wearable tailgating keg purchasing decisions split sharply between passive insulation and active technology investments. Material certification requirements and stadium security protocols further complicate how manufacturers align production with fan behavior across collegiate and professional venues.
Product Type:
Volume leadership sits with passive insulated designs, while premium growth concentrates in connected dispensing systems with embedded chilling.
- Insulated Kegs:Double-wall vacuum construction with eighteen-hour thermal retention dominates Southeastern and Midwestern college football corridors. Passive designs satisfy stadium security protocols that restrict powered equipment, preserving market position despite functional limitations.
- Smart Kegs:Electrochemical solid-state cooling modules and Bluetooth-enabled pressure monitoring are expanding most quickly among Greek life organizations and urban alumni chapters. Subscription pooling models favor connected units with firmware-updatable dispensing controls.
- Portable Kegs:Entry-level welded cylindrical vessels target price-sensitive recreational buyers in Texas and Florida tailgating circuits.
- Mini Kegs:Sub-five-liter formats concentrate in Canadian Football League venues and apartment-dwelling millennial segments lacking storage capacity.
Today's leader: Insulated Kegs. Tomorrow's challenger: Smart Kegs.
Material:
Cost tier stratification separates certified food-grade metalworkers from polymer assemblers exposed to tariff volatility.
- Stainless Steel:304-grade austenitic alloys dominate commercial-grade applications requiring repeated sanitization cycles. Pennsylvania and Ohio fabrication clusters supply FDA-compliant interior surface coatings for legitimate United States distribution channels.
- Plastic:Polypropylene tap handles and silicone gasket assemblies reduce shipping weight for remote tailgating locations. Zhejiang province supply concentration exposes assemblers to ocean freight rate spikes during peak season.
- Aluminum:Lightweight spun vessels target weight-constrained hiking and festival applications outside traditional football venues.
- Composite:Hybrid stainless-and-polymer designs balance thermal performance with transport economics for rental-service fleet operators.
Certification requirements favor Stainless Steel for repeat-use commercial applications. Weight sensitivity elevates Plastic for single-event remote deployment.
Functionality:
Application context determines whether fans prioritize thermal stability, dispensing precision, or carbonation preservation.
- Chilling:Active electrochemical modules satisfy NCAA Division I hospitality suite procurement specifications. EPA hydrofluorocarbon phase-down mandates are forcing propane-based cooling system redesign ahead of hardware replacement cycles.
- Carbonation:Pressure tolerance above 2.5 volumes distinguishes craft beer compatibility from mass-market lager suitability. Passive designs without active chilling surrender share to electric alternatives for hop-forward styles.
- Dispensing:Integrated tap mechanisms with flow control dominate individual ownership models across Texas and Oklahoma.
- Monitoring:IoT temperature and pressure sensors enable subscription revenue from shared equipment pools in Chicago and Detroit metropolitan areas.
Chilling commands premium pricing in institutional procurement. Carbonation retention determines craft beer market access.
Capacity:
Customer type segmentation separates individual purchasers from rental-service fleet operators with divergent storage and transport constraints.
- 5 Liters:Compact formats dominate urban alumni chapter subscriptions and apartment-dwelling millennial segments. Limited volume suits single-game attendance without residual storage burden.
- 10 Liters:Mid-range capacity balances portability with group serving economics for SEC and Big Ten conference permitted tailgating zones.
- 15 Liters:Intermediate formats concentrate in Canadian prairie provinces lacking established tailgating infrastructure.
- 20 Liters:Rental and event-service channels favor maximum volume per transport trip for guaranteed game-day availability contracts.
Five- and ten-liter units capture individual purchase volume. Twenty-liter formats anchor rental-service economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping production geography as FDA food-contact certification costs in the United States push polymer component sourcing toward Asian manufacturing clusters, while European metalworking heritage sustains premium stainless fabrication against low-cost import pressure.
United States
SEC and Big Ten conference tailgating expansions drive five- and ten-liter unit demand across permitted parking-lot zones. FDA interior surface coating standards lock in Pennsylvania and Ohio fabrication clusters while excluding uncertified imports. Pittsburgh-area metalworkers leverage legacy cylindrical vessel expertise to supply collegiate athletic department procurement offices.
Germany
Engineering-intensive hospitality suite specifications at Bundesliga venues accelerate solid-state cooling module adoption. REACH chemical compliance and CE marking requirements shape supplier qualification for cross-border European distribution. THIELMANN anchors industrial-scale production from its Neunkirchen engineering base serving rental-service fleet operators.
China
Zhejiang province concentration in polypropylene tap handles and silicone gasket assemblies exposes assemblers to tariff volatility during peak North American tailgating season. GB standards for food-contact plastics govern export-oriented manufacturing while domestic demand remains minimal. Ningbo and Wenzhou polymer processors dominate component supply for global brand assemblers.
Canada
Saskatchewan and Manitoba present first-mover positioning for rental-service models at Canadian Football League venues lacking established tailgating infrastructure. Health Canada food-contact material regulations align closely with FDA standards, easing cross-border equipment deployment. Prairie province football culture mirrors American collegiate intensity without equivalent portable dispensing penetration.
United Kingdom
Premier League hospitality culture sustains premium insulated vessel demand for stadium-adjacent social events. Post-Brexit UKCA marking requirements diverge from CE standards, complicating continental supplier access. Midlands manufacturing heritage supports niche metalworking capacity for specialty beverage container fabrication.
Wearable Tailgating Keg Market Competitive Landscape
United States producers anchor one tier with FDA-certified domestic fabrication; German specialists hold premium engineering positioning through solid-state thermal management. The vendor base splits between consolidated metalworking heritage players and fragmented polymer assemblers exposed to supply chain volatility. Three archetypes dominate: certified stainless fabricators, hybrid composite designers, and smart keg technology integrators. Capacity expansion and refrigerant chemistry redesign constitute the dominant competitive moves ahead of EPA phase-down deadlines.
Among Pennsylvania-based metalworkers, American Keg Company exemplifies domestic cylindrical vessel heritage sustained through welded fabrication expertise. THIELMANN – The Container Company occupies the industrial-scale engineering tier with its Neunkirchen engineering base serving cross-border European demand. Petainer represents hybrid composite positioning that balances stainless thermal performance with polymer weight reduction for remote deployment logistics.
| Leading Market Players |
|---|
| American Keg Company |
| Dolium |
| Thirstburst |
| Schaefer Container Systems |
| Blefa GmbH |
| Odditymall |
| Petainer |
| THIELMANN – The Container Company |
| Wyndham |
| Others |
Pricing and Supply Chain Analysis
Certification-grade divergence between FDA-compliant stainless fabricators and uncertified polymer assemblers splits pricing power along material and regulatory lines, with Pennsylvania metalworkers commanding sustained premiums while Zhejiang-dependent component suppliers absorb tariff volatility through margin compression.
Pricing Analysis
Distributor markups on smart keg chilling modules run 35-45 points above passive insulated vessels, reflecting electrochemical solid-state technology premiums and embedded IoT firmware value. Price differentiation rests on FDA food-contact certification tier and EPA SNAP refrigerant approval status. Cost compression in entry-level welded cylindrical segments is intensifying as Chinese polymer component tariffs squeeze Ohio and Texas assemblers. Rental-service fleet operators show lowest price sensitivity due to guaranteed availability contracts, while individual recreational buyers in Florida and Texas circuits exhibit acute elasticity.
Supply Chain Analysis
Direct-to-OEM channels handle collegiate athletic department procurement for NCAA Division I hospitality suites, while distributor networks serve individual tailgating consumers through sporting goods retailers. Raw material dependencies center on 304-grade austenitic stainless from Pennsylvania and Ohio fabrication clusters, polypropylene tap handles from Zhejiang province, and silicone gasket assemblies from Ningbo processors. Supply chain risk concentrates in single-source vulnerability for electrochemical cooling chips and ocean freight rate spikes during peak Southeastern conference season. Distribution runs through regional event rental services for urban alumni chapter subscription pools.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The wearable tailgating keg market compounds steadily as collegiate athletic departments institutionalize permitted parking-lot beverage zones, creating recurring equipment refresh cycles tied to stadium infrastructure investments.
For Market Incumbents: Deploy refrigerant chemistry redesign ahead of EPA hydrofluorocarbon phase-down deadlines to secure SNAP approval headroom. Deepen backward integration into 304-grade stainless supply through captive Pennsylvania metalworking capacity, insulating against nickel price volatility that threatens fabrication margins. Counter emerging smart keg technology integrators by accelerating solid-state cooling module qualification for field-level hospitality suite specifications.
For New Entrants and Emerging Players: Capture Saskatchewan and Manitoba Canadian Football League venues through rental-service fleet deployment, exploiting first-mover absence of established tailgating infrastructure. Target apartment-dwelling millennial segments in Great Lakes metropolitan areas with five-liter mini keg subscription pooling models, leveraging storage constraints as procurement mode catalyst. Lead with Bluetooth-enabled equipment tracking as differentiated service layer for Greek life organization shared equipment pools.
For Investors and Strategic Acquirers: Consolidation pressure builds where orbital TIG welding certification scarcity constrains Pennsylvania vocational pipeline output, favoring acquisition of established FDA-certified fabricators over greenfield capacity. Frame long-term viability around recurring revenue from subscription-based equipment pooling and firmware-update service contracts. Monitor EPA refrigerant transition timeline adherence as inflection indicator for smart keg technology integrators' regulatory compliance positioning.
| Strategic Initiative | Industry Significance |
|---|---|
| Refrigerant Chemistry Redesign | EPA SNAP approval for propane-based cooling systems secures regulatory compliance headroom ahead of phase-down mandates. |
| Orbital TIG Welding Capacity Expansion | Pennsylvania vocational program partnerships address eighteen-month certification pipelines constraining FDA-compliant vessel output. |
| IoT Module Integration | Bluetooth-enabled pressure monitoring creates subscription revenue streams from collegiate Greek life equipment pools. |
| Canadian Prairie Rental Deployment | Saskatchewan and Manitoba CFL venues lack established tailgating infrastructure, presenting first-mover positioning. |
| Hybrid Composite Design Development | Stainless-and-polymer configurations balance thermal performance with shipping weight reduction for remote deployment. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with keg fabrication plant managers, collegiate athletic department procurement officers, event rental service operators, and polymer component sourcing leads with secondary validation through FDA food-contact material filings, EPA SNAP refrigerant approval databases, SEC 10-K disclosures from metalworking specialists, and customs trade records for 304-grade stainless imports. Bottom-up unit shipment estimates across five-liter, ten-liter, and twenty-liter capacity tiers triangulated against top-down collegiate football attendance and permitted tailgating zone expansion metrics.
Segment-weighting approaches modeled passive insulated, smart keg, portable, and mini keg product categories alongside stainless steel, plastic, aluminum, and composite material tiers, with functionality splits across chilling, carbonation, dispensing, and monitoring dimensions. CAGRs were derived from fitted growth curves across the projection horizon, incorporating SEC and Big Ten conference policy liberalization timelines, EPA hydrofluorocarbon phase-down schedules, and nickel alloy price volatility bands as industry-specific forecast inputs.
Tariff regime shifts, refrigerant chemistry transition delays, and welding technician pipeline constraints are the dominant revision risks to modeled outputs. Forecasts reflect documented assumptions regarding collegiate alcohol policy trajectory and stadium security protocol evolution. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smoking Accessories
Latin America Cigarette Lighter Market
Smoking Accessories
Pocket Lighter Market
Smoking Accessories
Smoking Accessories Market
Smoking Accessories
Ashtray Market
Smoking Accessories
Lighter Market
Smoking Accessories
Hookah Products Market
Smoking Accessories
China Smoking Accessories Market
Smoking Accessories
Global Blunt Wrap Market
Smoking Accessories
Smart E-Cigarettes Market
Smoking Accessories
UK Smoking Pipe Market
Smoking Accessories
Smoking Pipe Market
Smoking Accessories
US Smoking Pipe Market
Smoking Accessories
United States Cigarette Lighter Market
Smoking Accessories
Pod Vape Market
Smoking Accessories
Electric Pocket Lighter Market
Smoking Accessories
Japan Smoking Accessories Market