
 Travel Pouches Market | 2026-2036
Travel Pouches Market Size, Share, and Industry Trends Forecast 2026-2036
Travel Pouches Market Outlook
ISO 9001 quality management certification is unwinding competitive barriers for new entrants seeking shelf space at major retailers. Samsonite International S.A. leverages its vertically integrated manufacturing footprint across Asia to sustain cost advantages in nylon-based pouches. Tumi Holdings, Inc. anchors its positioning through full-grain leather toiletry bags that command premium placement in airport duty-free networks. Victorinox Swiss Army differentiates via Swiss-engineered zip closure systems that compete on durability testing standards.
Travel pouches denote compartmentalized textile containers engineered to organize garments, footwear, and toiletries within larger luggage assemblies, typically fabricated from denier-rated nylon or polyester with reinforced seam taping to achieve water resistance thresholds. Compression bags utilize one-way valve membranes to evacuate air volume, reducing packed bulk by measurable ratios for space-constrained travelers. Packing cubes dominate material throughput among product type segments due to universal airline carry-on dimension restrictions, while leather toiletry bags capture disproportionate margin pools through artisanal construction and brand licensing. Business travelers represent the fastest-growing end user cohort as hybrid work policies extend bleisure trip frequencies across corporate travel budgets.
FDA oversight of antimicrobial textile claims in the United States and REACH chemical restrictions administered by ECHA in Europe collectively constrain material formulation choices for manufacturers serving cross-border distribution. The EU Green Deal's extended producer responsibility frameworks for synthetic textiles are forcing reformulation toward recycled polyester feedstocks in export-oriented production facilities. Stakeholders must monitor evolving state-level packaging waste legislation in California and New York that threatens to reclassify single-use travel accessories under broader plastic reduction mandates.
Market Dynamics
Compression valve engineering and ECHA REACH chemical restrictions are restructuring material sourcing economics for travel pouch manufacturers serving cross-border distribution networks.
Growth Catalysts
- Hybrid work policies:Bleisure trip frequencies among corporate travelers are expanding demand for organized luggage solutions that accommodate both professional and leisure contents.
- EU Green Deal extended producer responsibility:Mandates for synthetic textile recycling are accelerating reformulation toward recycled polyester feedstocks in export-oriented production.
- Airline carry-on dimension enforcement:Universal restrictions at major carriers are elevating packing cube penetration as travelers optimize volume within strict linear inch limits.
Market Restraints
- Petrochemical feedstock volatility:Nylon and polyester resin prices fluctuate with crude oil derivatives, compressing margin stability for denier-rated fabric producers.
- Antimicrobial claim compliance:FDA oversight in the United States requires registration and substantiation for treated textiles, extending product development timelines.
- Leather supply concentration:Full-grain hide sourcing clusters in Italian and Argentinian tanneries create geographic vulnerability for premium toiletry bag manufacturers.
Strategic Opportunities
- Direct-to-consumer channel expansion:Premium luggage retailers are ceding shelf space to brand-owned digital storefronts that capture full margin on compression bag sales.
- California and New York packaging waste legislation:Proposed reclassification of single-use travel accessories creates first-mover advantage for reusable, modular pouch systems.
- Smart textile integration:RFID-enabled tracking layers converging with traditional nylon laminates are opening asset-recovery applications for high-value business travel segments.
Industry Challenges
- ISO 9001 certification backlog:Quality management system audits face scheduling delays at accredited bodies, slowing new entrant access to major retail distribution.
- Seam taping equipment retrofitting:Water resistance threshold upgrades require capital deployment into ultrasonic welding and hot-melt adhesive application lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Travel Pouches Market |
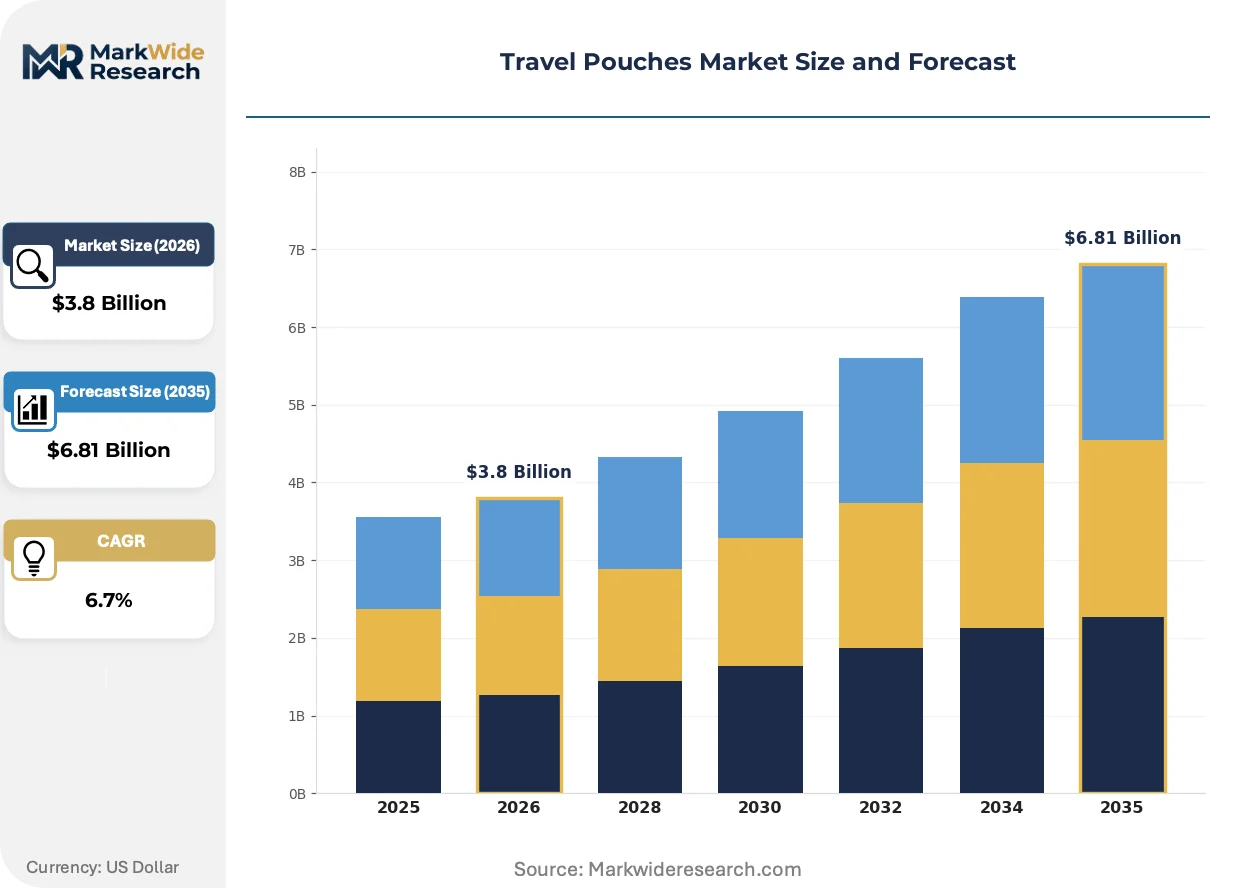
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Compression Bags, Packing Cubes, Toiletry Bags, Shoe Bags Material: Nylon, Polyester, Canvas, Leather End User: Frequent Travelers, Tourists, Business Travelers, Backpackers Closure Type: Zip Closure, Roll Top, Drawstring, Magnetic Closure |
| Companies Covered | Samsonite International S.A., Tumi Holdings, Inc., Travelpro International Inc., Delsey S.A., Briggs & Riley Travelware, Victorinox Swiss Army, American Tourister, Eagle Creek, Herschel Supply Co., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Travel Pouches Market Strategic Shifts
Material science advances and regulatory chemical frameworks are fragmenting traditional nylon-polyester dominance while digitization reshapes how travelers discover and purchase organization accessories.
One-way valve membrane technology is decomposing the bulk-volume tradeoff that previously constrained packing efficiency. Frequent flyers operating on space-constrained itineraries are adopting compression bags at accelerated rates. This displacement of conventional ziplock-style storage is compressing the addressable market for non-specialized alternatives.
REACH chemical restrictions administered by ECHA are eliminating certain phthalate plasticizers and flame retardants from textile formulations. Manufacturers serving European distribution must reformulate coating adhesives and dye carriers to maintain market access. Recycled polyester feedstocks are gaining share as compliant alternatives in export-oriented Asian production facilities.
Business travelers are consolidating purchasing authority through corporate travel management platforms rather than individual retail selection. Procurement via contracted suppliers with pre-negotiated amenity kits is displacing open-market acquisition for toiletry and organization products. This concentration is most visible in United States technology and consulting sectors where hybrid work policies extend trip frequencies.
Travel Pouches Market Segmentation
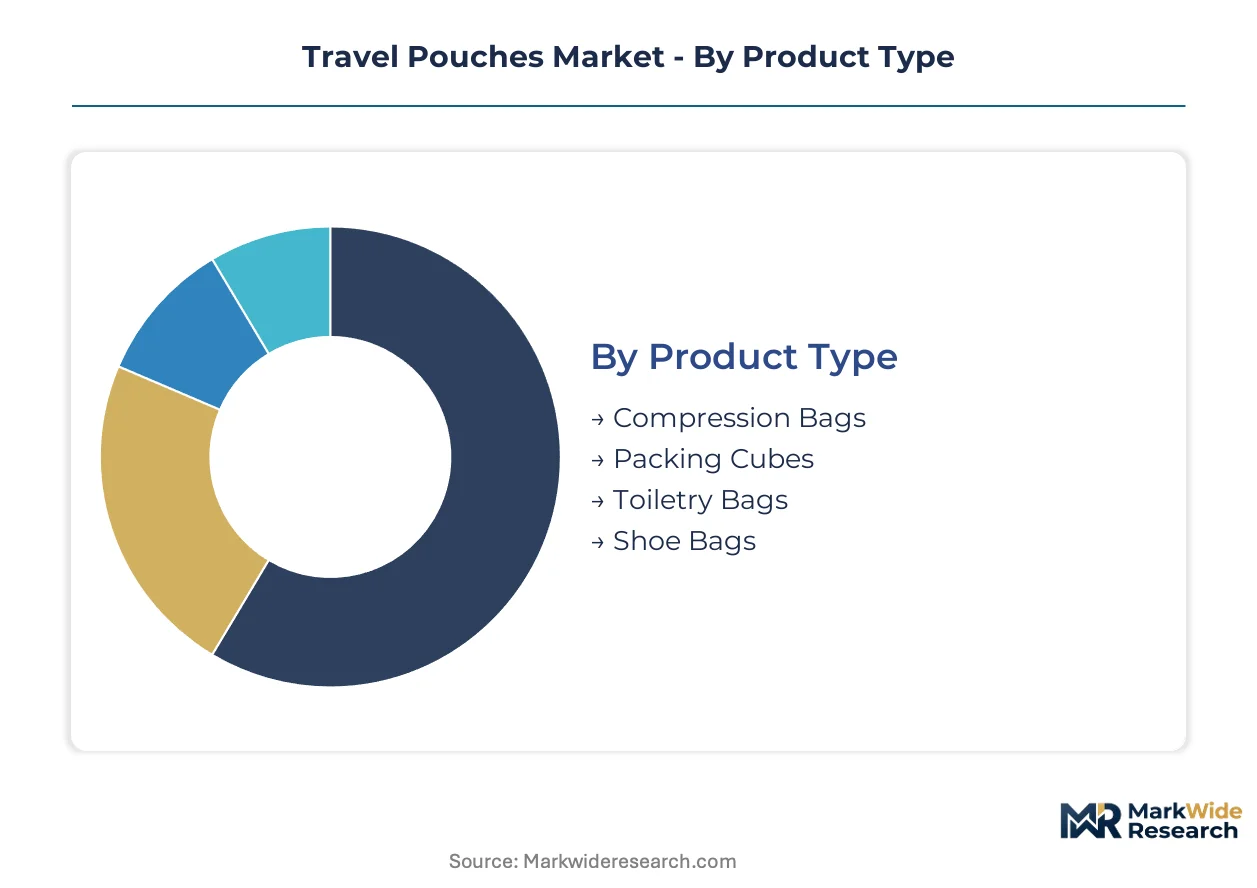
Travel pouch manufacturers align production configurations with distinct channel economics. Compression bags and packing cubes flow through mass-market retail and direct-to-consumer platforms, while leather toiletry bags concentrate in premium luggage boutiques and airport duty-free networks. Segmentation discipline determines margin capture and inventory velocity across these divergent distribution paths.
Product Type:
Channel mix splits sharply between utilitarian volume products and artisanal premium lines. Mass retailers anchor throughput for space-optimizing formats, whereas specialty luggage stores curate full-grain leather assortments.
- Compression Bags:One-way valve membranes evacuate air volume to reduce packed bulk by measurable ratios for space-constrained travelers. Demand concentrates among frequent flyers operating on tight linear-inch limits at United States legacy carriers, driven by universal carry-on enforcement tightening at Delta Air Lines and American Airlines hubs.
- Packing Cubes:Compartmentalized textile containers engineered with denier-rated nylon and reinforced seam taping achieve water resistance thresholds. Volume clusters in United States direct-to-consumer channels where hybrid work policies extend bleisure trip frequencies across corporate travel budgets.
- Toiletry Bags:Artisanal construction with full-grain hide sourcing from Italian and Argentinian tanneries commands premium placement in airport duty-free networks.
- Shoe Bags:Lightweight polyester or nylon enclosures protect footwear from garment contamination in checked luggage assemblies.
Packing cubes dominate installed base. Compression bags are where expansion concentrates.
Material:
Cost tier stratification separates commodity synthetics from heritage natural materials. Recycled feedstock reformulation is reshaping mid-tier positioning as ECHA REACH restrictions eliminate legacy chemical treatments.
- Nylon:Denier-rated synthetic with superior tear strength and abrasion resistance for high-frequency use cases. Samsonite International S.A. leverages vertically integrated manufacturing across Asia to sustain cost advantages in this material tier.
- Polyester:Lower unit cost with adequate durability for casual travel applications. EU Green Deal extended producer responsibility mandates are accelerating reformulation toward recycled polyester feedstocks in export-oriented Asian production facilities.
- Canvas:Woven cotton construction appeals to heritage aesthetic preferences in boutique retail channels.
- Leather:Full-grain hide delivers tactile premium differentiation and extended service life for business traveler segments.
Nylon anchors volume throughput. Recycled polyester is climbing the fastest.
End User:
Application context determines feature prioritization and price elasticity. Corporate procurement platforms are consolidating purchasing authority away from individual retail selection.
- Frequent Travelers:High-rotation users prioritize durability testing standards and compression efficiency. This segment concentrates in United States metropolitan corridors with hub airport proximity.
- Business Travelers:Hybrid work policies extend bleisure trip frequencies across technology and consulting sector travel budgets. Procurement via contracted suppliers with pre-negotiated amenity kits is displacing open-market acquisition.
- Tourists:Price-sensitive occasional users favor basic organizational utility over specialized performance features.
- Backpackers:Weight-minimizing users demand ultralight construction with multi-function flexibility.
Frequent travelers dominate installed base. Business travelers are gaining share fastest.
Closure Type:
Engineering specifications differentiate durability claims and water resistance performance. Swiss-engineered systems compete on testing standards that exceed mass-market alternatives.
- Zip Closure:Swiss-engineered zip systems from Victorinox Swiss Army compete on durability testing standards with reinforced slider mechanisms. Demand concentrates in premium channels where failure tolerance approaches zero.
- Roll Top:Waterproof sealing without mechanical complexity suits marine and adventure travel applications.
- Drawstring:Minimalist cord closure reduces weight and manufacturing cost for entry-level price tiers.
- Magnetic Closure:Rapid-access convenience appeals to business traveler segments prioritizing checkpoint efficiency.
Zip closure dominates installed base. Roll top is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Frequent flyers in the United States drive premium compression bag adoption through corporate travel budgets. Business travelers in Germany and the United Kingdom anchor European demand for organized luggage solutions. Asian manufacturing clusters supply denier-rated nylon to export markets under tightening chemical compliance regimes.
United States
Hybrid work policies extend bleisure trip frequencies across technology and consulting sector travel budgets. FDA oversight of antimicrobial textile claims requires registration and substantiation for treated travel pouches. Chicago and Dallas metropolitan corridors concentrate frequent flyer demand near Delta Air Lines and American Airlines hub operations.
Germany
Corporate procurement platforms consolidate purchasing authority for organized luggage solutions among business traveler segments. ECHA REACH chemical restrictions eliminate certain phthalate plasticizers from textile formulations used in travel accessories. Bavaria-based manufacturing facilities reformulate coating adhesives to maintain European market access under tightened compliance.
China
Export-oriented production facilities serve United States and European demand for packing cubes and compression bags. MEE-administered environmental standards push synthetic textile producers toward recycled feedstock adoption. Yangtze River Delta manufacturing clusters integrate ultrasonic welding equipment to achieve water resistance thresholds for international buyers.
United Kingdom
Airline carry-on dimension enforcement at London Heathrow and Gatwick elevates packing cube penetration among space-constrained travelers. EU Green Deal extended producer responsibility frameworks affect synthetic textile imports despite post-Brexit regulatory divergence. London metropolitan business travelers drive demand for premium leather toiletry bags through contracted amenity kit suppliers.
Japan
METI quality standards shape durability expectations for zip closure systems in premium travel pouch segments. Business travelers in Tokyo and Osaka prioritize Swiss-engineered durability testing standards for high-frequency use cases. Kanto region retail channels curate organized luggage assortments targeting bleisure trip frequencies among corporate segments.
Travel Pouches Market Competitive Environment
Player mix skews toward vertically integrated luggage conglomerates with captive nylon manufacturing capacity. Market structure concentrates around three to five dominant holding companies controlling premium airport duty-free placement. Two strategic archetypes prevail: heritage European leather artisans and Asian-scale synthetic fabricators. Competitive moves center on direct-to-consumer channel expansion and ECHA-compliant material reformulation to defend European market access.
Among Switzerland-based engineered goods specialists, Victorinox Swiss Army exemplifies durability-focused positioning through mechanical closure systems. Samsonite International S.A. and Tumi Holdings, Inc. occupy positions within the premium luggage conglomerate tier, representing contrasting geographic manufacturing footprints. These three companies anchor the competitive landscape across synthetic and natural material segments without exhaustive market coverage.
| Leading Market Players |
|---|
| Samsonite International S.A. |
| Tumi Holdings, Inc. |
| Travelpro International Inc. |
| Delsey S.A. |
| Briggs & Riley Travelware |
| Victorinox Swiss Army |
| American Tourister |
| Eagle Creek |
| Herschel Supply Co. |
| Others |
Value Chain & Pricing Dynamics
Denier-rated nylon capacity utilization across Yangtze River Delta clusters shapes both supply concentration and price floors for compression bag manufacturers. Petrochemical feedstock volatility compresses margin stability while ISO 9001 certification requirements erect barriers that protect incumbent pricing power against unqualified entrants.
Pricing Analysis
Cost-plus contracts with crude oil derivative indexation dominate raw material procurement for polyester and nylon resin suppliers. Three-tier pricing structure across premium, standard, and economy levels separates full-grain leather toiletry bags from denier-rated nylon packing cubes and entry-level polyester shoe bags. Pricing pressure stems from REACH-compliant reformulation costs that manufacturers absorb to maintain European market access. Tourist segments exhibit highest price sensitivity while business travelers purchasing through corporate procurement platforms show lowest elasticity.
Supply Chain Analysis
Just-in-time inventory strategies prevail among United States direct-to-consumer brands while Asian export manufacturers maintain strategic stockpiles of denier-rated nylon to buffer against petrochemical price spikes. Supply concentrates in China, Vietnam, and Bangladesh for synthetic textile fabrication with Italian and Argentinian tanneries anchoring full-grain leather sourcing. Raw material dependencies include crude oil derivatives for nylon polymerization, recycled PET flake for polyester reformulation, and chrome-tanned hides for premium toiletry construction. Single-source vulnerability clusters in Italian tannery districts for full-grain leather. Distribution runs through premium luggage retailers, airport duty-free networks, and brand-owned digital storefronts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Compression bag maintenance subscriptions and replacement valve membrane programs represent faster-expanding recurring revenue layers than hardware unit sales alone. Service-attach economics favor manufacturers who embed RFID-enabled tracking and warranty extension programs into initial purchases.
For Market Incumbents: Secure ECHA-compliant material formulations through backward integration into recycled polyester feedstock production or long-term offtake agreements with Yangtze River Delta suppliers. ISO 9001 certification backlogs at accredited bodies threaten new entrant shelf space access at major retailers; incumbents should deepen auditor relationships to accelerate competitor exclusion. Capacity addition in Vietnam offers tariff diversification against potential United States trade action on Chinese synthetic textiles. For New Entrants and Emerging Players: ISO 9001 fast-track programs through specialized consultancy partnerships compress quality management system deployment timelines from eighteen to nine months. White-space targets include RFID-enabled compression bags for high-value business travel segments and modular pouch systems compliant with proposed California packaging waste legislation. Direct-to-consumer launch with subscription-based organization kit replenishment captures full margin while bypassing incumbent retail gatekeepers. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors manufacturers with captive nylon polymerization capacity and established ECHA REACH compliance infrastructure. Long-term viability across the five-to-ten year window hinges on extended producer responsibility adaptation and smart textile integration capabilities. Acquisition target archetype: mid-scale Asian manufacturers with ultrasonic welding equipment and existing recycled polyester feedstock relationships. Signal to watch: California and New York legislative progression on single-use travel accessory reclassification.| Strategic Initiative | Industry Significance |
|---|---|
| Direct-to-Consumer Channel Expansion | Brand-owned digital storefronts capture full margin on compression bag sales while reducing retailer dependency. |
| Recycled Polyester Feedstock Transition | EU Green Deal extended producer responsibility mandates force reformulation to maintain European market access. |
| RFID-Enabled Smart Textile Integration | Asset-recovery applications open high-value business traveler segments with subscription-based tracking services. |
| ISO 9001 Certification Investment | Quality management system credentials unlock shelf space at major United States premium luggage retailers. |
| Ultrasonic Welding Equipment Retrofit | Water resistance threshold upgrades meet durability testing standards for frequent flyer replacement cycles. |
Study Parameters
A standing panel of luggage category buyers, textile procurement directors, airline amenity kit managers, and corporate travel platform executives provided ongoing calibration across the study period. Primary interviews with these stakeholders combined with secondary validation from customs records, SEC 10-K filings of listed luggage conglomerates, and ECHA REACH substance restriction updates. Bottom-up unit shipment modeling triangulated against top-down value estimates derived from retail audit data and duty-free network sales disclosures.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Analytical framework modeled product type, material grade, end-user segment, and closure mechanism dimensions with geographic regulatory cluster overlays. CAGRs derived from regression analysis of historical shipment trajectories adjusted for airline carry-on enforcement intensity and hybrid work policy penetration. Industry-specific forecast inputs included petrochemical price index correlations and ISO 9001 certification audit queue lengths.
Decision-makers should treat outputs as directional under base assumptions of stable airline dimension enforcement and continued REACH chemical restriction tightening; material deviation would warrant model refresh. Forecasts reflect these documented assumptions with acknowledged sensitivity to crude oil derivative volatility and state-level packaging waste legislative progression. Revision becomes warranted when California or New York reclassification thresholds for single-use travel accessories cross implementation stages.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Travel Accessories
Snowboard Bags Market
Travel Accessories
Pet Travel Accessories Market
Travel Accessories
Travel Accessories Market
Travel Accessories
Smart Luggage Market
Travel Accessories
Pet Travel Bags Market
Travel Accessories
UK Travel Accessories Market
Travel Accessories
Italy Travel Accessories Market
Travel Accessories
Amenity Kits Market
Travel Accessories
Ergonomic Backpack for Children Market
Travel Accessories
Backpack Systems Market
Travel Accessories
India Travel Accessories Market