
 Snowboard Bags Market | 2026-2036
Snowboard Bags Market Size, Share, and Industry Trends Forecast 2026-2036
Snowboard Bags Market Analytics
Buyer fragmentation across destination ski resorts and independent rental shops is repositioning procurement power toward regional equipment distributors. Dakine leverages its deep channel relationships with North American mountain resorts to sustain volume commitments. Burton anchors its position through vertical control over bag design and snowboard ecosystem bundling. Salomon competes by extending its alpine heritage into protective travel accessories for European ski circuits.
Snowboard bags are protective transport enclosures engineered with padded compartments, reinforced base panels, and weather-resistant closures to shield decks, bindings, and boots from impact and moisture during transit. Most premium constructions integrate 600D–1680D nylon or ballistic polyester with closed-cell EVA foam padding to absorb shock while maintaining sub–3 kg carry weights for airline portability. Soft bags dominate unit sales due to their foldable storage and lower price positioning, while wheeled variants capture disproportionate margin pools among frequent flyers and professional athletes. The amateur segment generates the highest absolute volumes, though professional-grade padded configurations with reinforced hard bases command superior per-unit profitability.
FDA guidelines on textile labeling and the EPA's emerging frameworks for recycled content claims shape material sourcing disclosures for US-bound products. REACH chemical restrictions and the EU Green Deal's circular economy mandates compel European suppliers to phase out virgin PVC coatings and document recycled nylon traceability. Stakeholders must monitor evolving airline dimensional restrictions and carbon accounting rules to anticipate which bag configurations and material certifications will secure retail placement.
Market Dynamics
Resort rental procurement consolidation is compressing margins for independent bag manufacturers while elevating volume commitments from regional equipment distributors serving Niseko, Hakuba, and North American mountain clusters.
Growth Catalysts
- REACH chemical restrictions:European mandates on virgin PVC coatings are accelerating supplier migration toward recycled nylon traceability systems, opening certified material premiums.
- Japan inbound tourism:Niseko and Hakuba valley operators are bulk-purchasing protective transport gear for international visitors, concentrating demand in Hokkaido and Nagano prefectures.
- Bio-based EVA foam:Closed-cell padding derived from plant feedstocks is displacing petroleum-based alternatives in premium wheeled configurations.
Market Restraints
- Ballistic polyester supply:1680D fabric production concentrates among Taiwanese and South Korean textile mills, exposing bag assemblers to input volatility.
- Airline dimensional enforcement:FAA guidance on carry-on size limits is compressing allowable bag geometries, forcing design compromises for wheeled variants.
- Hard-shell substitution:ABS and polycarbonate luggage with internal padding systems are capturing frequent-flyer segments from soft snowboard bags.
Strategic Opportunities
- EU Green Deal circular mandates:Documentation requirements for recycled content are creating certification premiums for bags with verified post-consumer nylon.
- Direct-to-resort distribution:Bypassing traditional retail through exclusive rental program contracts is opening recurring revenue streams.
- Smart tracking integration:RFID and Bluetooth beacon convergence is enabling loss-prevention features for high-value professional gear transport.
Industry Challenges
- Multi-standard compliance:Simultaneous EPA recycled content claims, REACH chemical documentation, and airline safety testing is stretching certification timelines.
- Specialized sewing automation:Complex curved seams for padded compartments require skilled operators that bag factories struggle to retain.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Snowboard Bags Market |
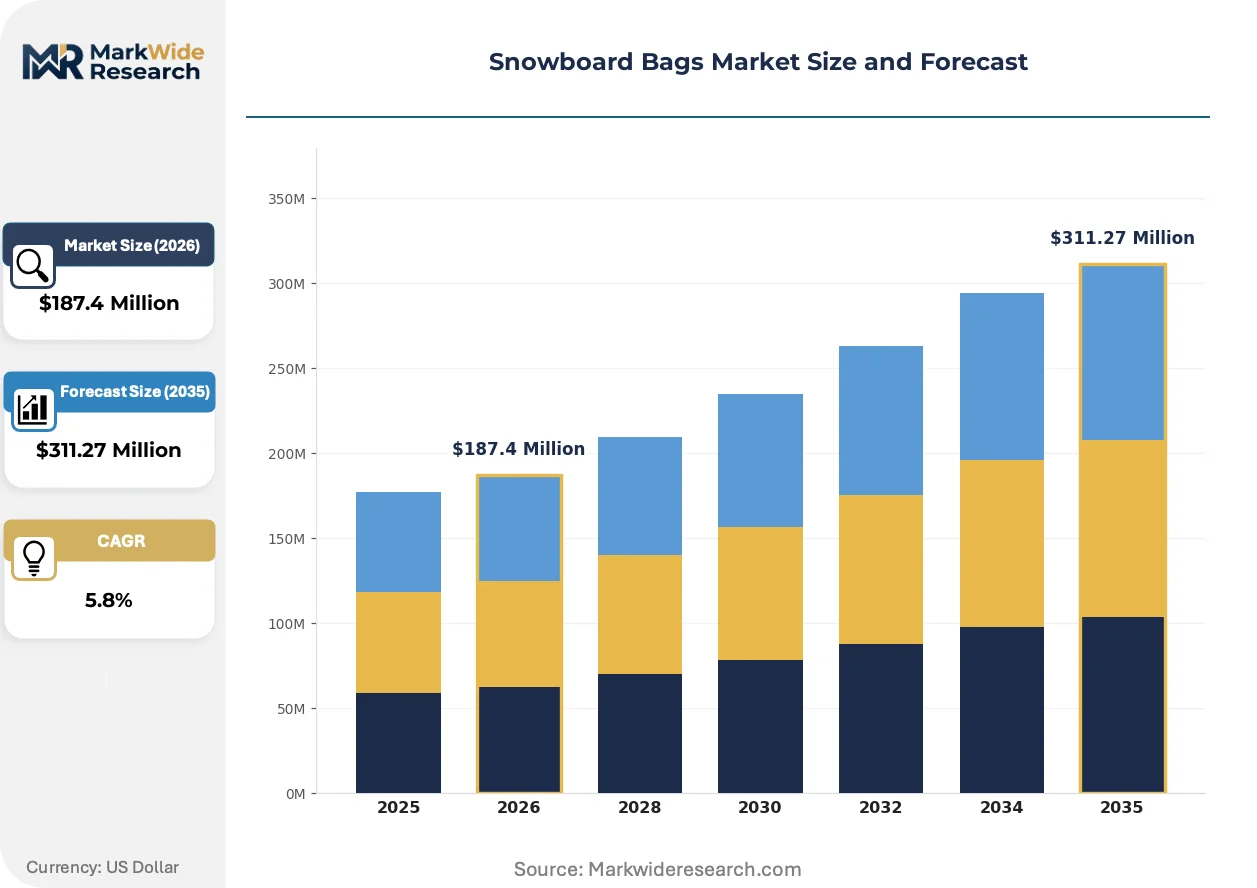
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Soft Bags, Hard Cases, Sling Bags, Wheeled Bags Material: Nylon, Polyester, Canvas, EVA Feature: Water-Resistant, Padded, Lightweight, Expandable End User: Amateurs, Professionals, Rentals, Tourists |
| Companies Covered | Dakine, Burton, Evo, Mammut, Black Diamond, Ortovox, Patagonia, Salomon, Transpack, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Snowboard Bags Market Evolving Landscape
Material science advances and regulatory disclosure requirements are compressing product development cycles while fragmenting competitive advantage between certification holders and cost-optimized assemblers.
Modular compartment systems with removable padded inserts are consolidating around standardized deck-width configurations. Japanese rental operators are adopting these systems fastest, demanding interchangeable boot and binding storage that reduces bag inventory SKUs. This standardization is consolidating procurement power toward distributors who can guarantee cross-brand compatibility.
REACH and RoHS compliance in Europe is forcing coating suppliers to phase out phthalate-based PVC treatments by 2026. Bag manufacturers serving EU markets are accelerating water-based polyurethane and silicone-treated nylon validation. Premium wheeled variants with documented chemical compliance are capturing shelf space in German and Austrian specialty retailers.
Buyer concentration among destination resort procurement teams is shortening vendor evaluation cycles. Independent rental shops in Colorado and Utah are consolidating purchases through regional equipment distributors rather than direct manufacturer relationships. This channel shift is most visible in North America, where distributor-exclusive product lines are displacing open-catalog configurations.
Snowboard Bags Market Segmentation
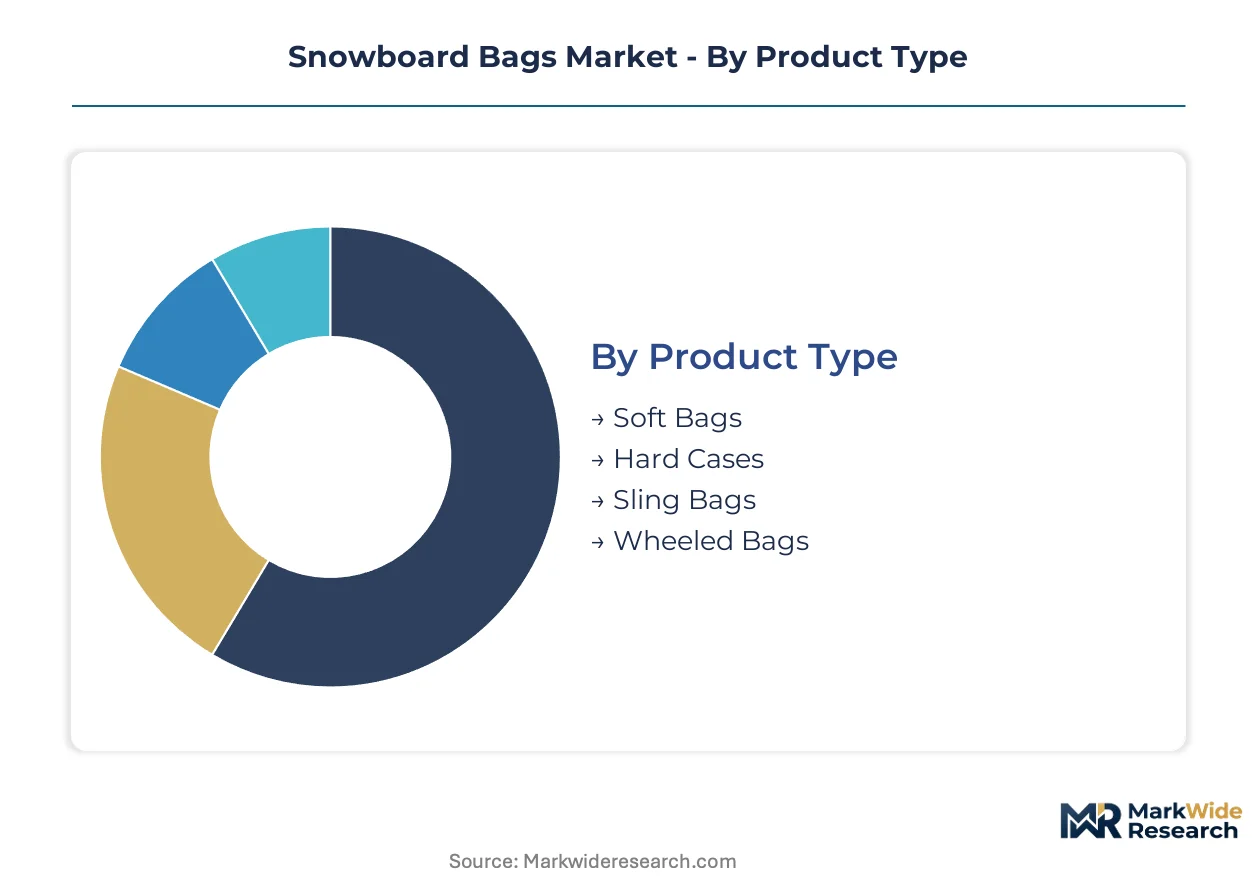
Product configuration choices in snowboard bags directly determine procurement patterns among destination resorts and airline-dependent travelers. Material certifications and dimensional compliance now filter which segments capture shelf space in regulated markets.
Product Type:
Manufacturing capacity for wheeled and hard-case variants concentrates among Taiwanese and South Korean assemblers with ballistic nylon integration capabilities.
- Soft Bags:Foldable constructions using 600D–1680D nylon or ballistic polyester dominate unit sales through lower price positioning and compact storage. Demand concentrates among amateur riders and domestic travelers in Colorado and Utah who prioritize vehicle trunk flexibility over airline check-in protection.
- Wheeled Bags:Reinforced base panels with integrated casters and telescoping handles capture disproportionate margin pools among frequent flyers and professional athletes. Japanese inbound tourism operators in Niseko and Hakuba bulk-purchase these configurations for international visitor equipment services.
- Hard Cases:ABS or polycarbonate shells with internal padding systems serve professional athletes and gear collectors requiring maximum impact resistance.
- Sling Bags:Single-strap compact designs target day-trippers and urban commuters with minimal storage requirements.
Today's leader: Soft Bags. Tomorrow's challenger: Wheeled Bags.
Material:
Cost tier differentiation separates virgin petroleum-based inputs from certified recycled alternatives commanding certification premiums.
- Nylon:1680D ballistic constructions dominate premium wheeled configurations with tear resistance and weatherproofing. REACH and RoHS compliance mandates in Europe are accelerating water-based polyurethane coating validation for EU-bound inventory.
- Polyester:Recycled post-consumer variants with documented traceability systems capture shelf space in German and Austrian specialty retailers under EU Green Deal circular mandates.
- Canvas:Heavy-duty cotton blends appeal to sustainability-focused consumers prioritizing biodegradability over weight optimization.
- EVA:Bio-based closed-cell foam padding derived from plant feedstocks displaces petroleum-based alternatives in premium configurations.
Current volume anchor: Nylon. Fastest certification climb: Recycled Polyester.
Feature:
Application requirements from resort rental programs prioritize modular interchangeability over single-purpose designs.
- Padded:Multi-layer EVA foam compartments with reinforced stitching protect decks and bindings during commercial transit. Japanese rental operators demand standardized padded inserts that reduce inventory SKU complexity across multiple board widths.
- Water-Resistant:Silicone-treated nylon and heat-sealed seams prevent moisture damage in snow-laden environments. European distributors prioritize documented chemical compliance for coatings under REACH phthalate restrictions.
- Lightweight:Sub–3 kg constructions target airline carry-on compliance where FAA dimensional guidance compresses allowable geometries.
- Expandable:Zippered volume adjustment accommodates varying gear loads from single-day to multi-week trips.
Procurement priority: Padded. Regulatory driver: Water-Resistant.
End User:
Customer type fragmentation repositions volume commitments toward consolidated rental procurement and away from dispersed individual purchases.
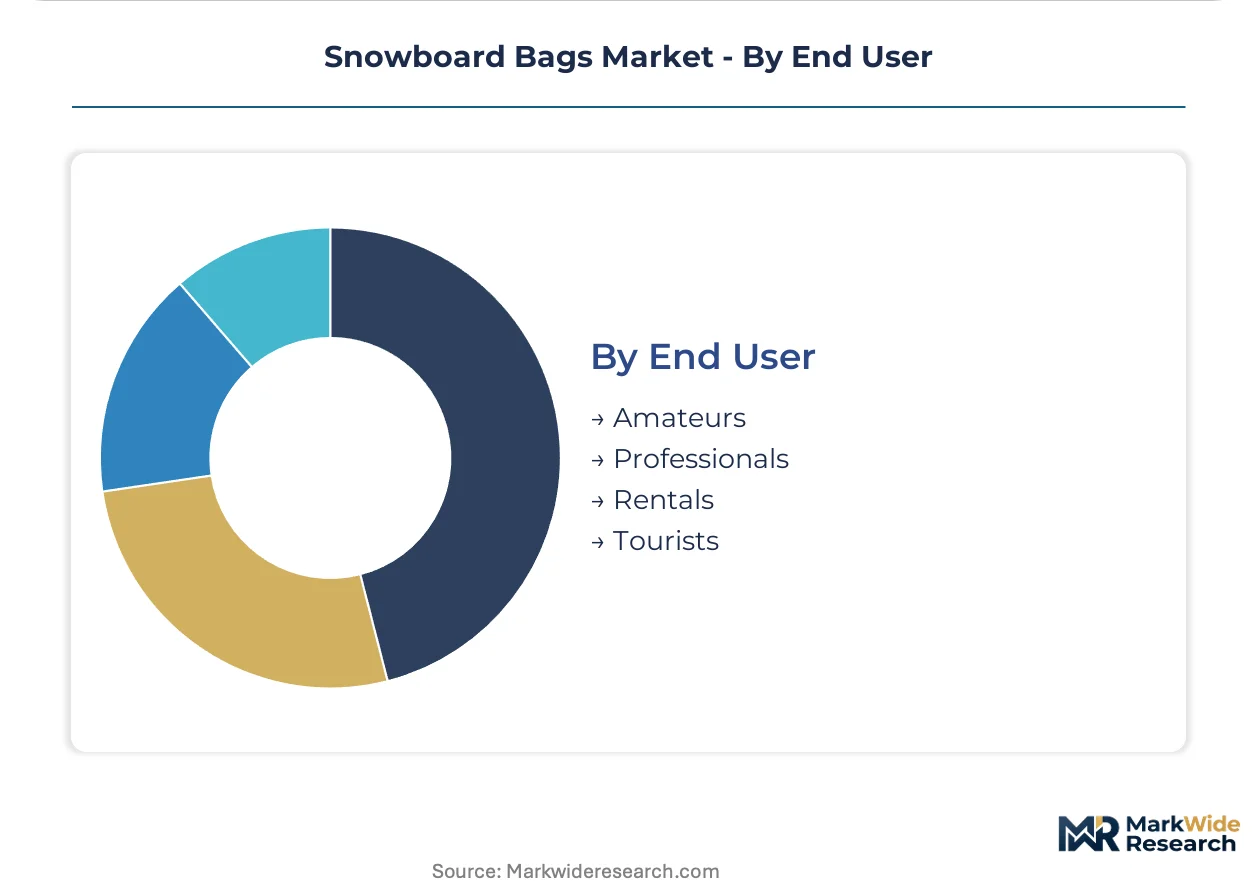
- Amateurs:Recreational riders generate highest absolute volumes through price-sensitive soft bag purchases at mass retail. North American mountain resort rental programs are consolidating amateur-grade procurement through regional equipment distributors rather than direct manufacturer relationships.
- Tourists:Inbound visitors to Japanese ski destinations drive bulk protective transport gear orders from Niseko and Hakuba valley operators.
- Professionals:Athletes and sponsored riders command premium per-unit profitability through hard-case and reinforced wheeled configurations with custom branding.
- Rentals:Resort and independent shop operators prioritize durability and standardized compatibility over aesthetic differentiation.
Volume foundation: Amateurs. Margin expansion: Tourists.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized sewing technicians and textile engineers cluster around Taiwanese and South Korean manufacturing hubs, anchoring global production capacity for ballistic nylon constructions.
United States
Colorado and Utah mountain resort operators drive bulk procurement through regional equipment distributors serving rental programs. EPA frameworks on recycled content claims shape material sourcing disclosures for domestic-bound inventory. Denver-based distributors consolidate purchasing power away from direct manufacturer relationships.
Japan
Niseko and Hakuba valley operators generate concentrated demand for wheeled protective transport gear serving inbound international tourists. METI standards on product safety influence quality specifications for rental program procurement. Hokkaido prefecture rental networks standardize on modular padded inserts to reduce inventory complexity.
Germany
REACH chemical restrictions and EU Green Deal circular mandates compel suppliers to phase out virgin PVC coatings and document recycled nylon traceability. Bavarian specialty retailers prioritize documented chemical compliance for premium wheeled configurations. Munich equipment distributors capture shelf space through certified material premiums.
Canada
British Columbia and Alberta destination resorts invest in guest equipment services, expanding protective transport procurement. Health Canada textile labeling requirements align with EPA disclosure frameworks for cross-border inventory. Whistler and Banff rental clusters concentrate demand among regional distributor networks.
South Korea
Ballistic polyester production concentrates among textile mills supplying bag assemblers with 1680D fabric inputs. MFDS product safety standards intersect with export market requirements for US and EU-bound inventory. Seoul metropolitan area manufacturing clusters face input volatility from petroleum-based material price swings.
Snowboard Bags Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. The vendor base separates into three strategic archetypes: heritage outdoor brands with alpine ecosystem bundling, dedicated bag manufacturers with deep channel relationships, and vertically integrated snowboard specialists controlling design-to-retail workflows. Dominant competitive moves include exclusive rental program contracts and certified material traceability investments.
Within the heritage outdoor tier, Mammut and Ortovox represent European alpine heritage extension into protective travel accessories. Dakine occupies a position exemplifying deep channel relationships with North American mountain resorts. Burton anchors the vertically integrated specialist archetype through in-house control over bag design and snowboard ecosystem bundling.
| Leading Market Players |
|---|
| Dakine |
| Burton |
| Evo |
| Mammut |
| Black Diamond |
| Ortovox |
| Patagonia |
| Salomon |
| Transpack |
| Others |
Value Network & Pricing Analysis
Resort rental procurement consolidation across Niseko, Hakuba, and Colorado mountain clusters anchors pricing power with regional equipment distributors who negotiate volume-based contract structures. This buyer concentration compresses margins for independent assemblers while rewarding certified material premiums through recurring program commitments.
Pricing Analysis
Bundled rental program contracts versus unbundled retail purchases split pricing models across the market. Three-tier pricing structure across premium wheeled, standard soft, and economy sling configurations segments buyer tiers. Price differentiation hinges on REACH compliance documentation and recycled nylon traceability certification. Cost compression in amateur-grade soft bags intensifies as distributor-exclusive lines displace open-catalog alternatives. Rental operators show lowest price sensitivity due to durability requirements, while individual amateurs drive aggressive cost benchmarking.
Supply Chain Analysis
Single-source vulnerability sits with Taiwanese and South Korean textile mills controlling 1680D ballistic polyester production. Manufacturing draws from petroleum-based nylon feedstocks, bio-based EVA foam alternatives, and water-based polyurethane coating systems. Tariff exposure on Taiwanese fabric inputs threatens margin stability for bag assemblers. Distribution runs through regional equipment distributors serving mountain resort clusters rather than direct manufacturer relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
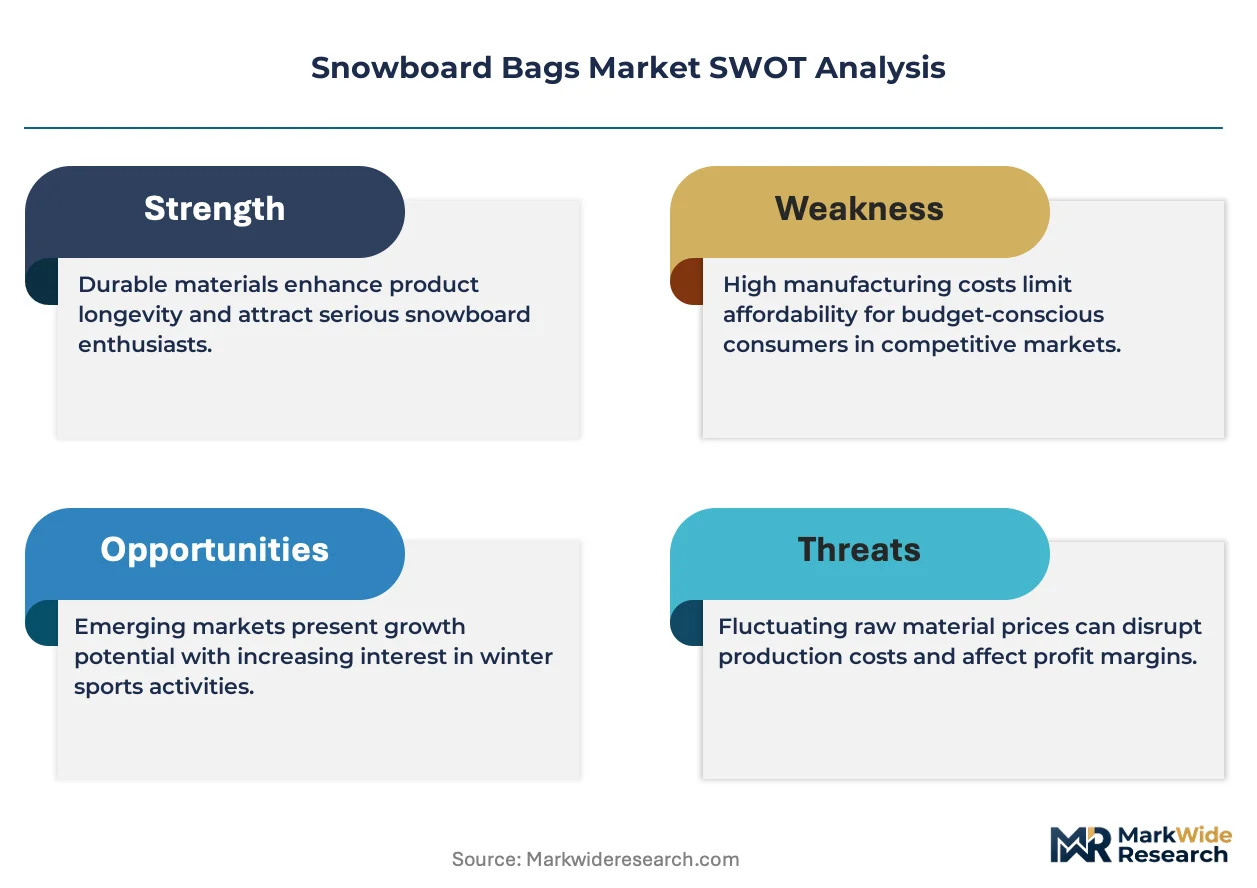
This market offers margin expansion through bio-based material substitution and certified premium tier capture, with REACH compliance investments unlocking pricing power in European specialty retail.
For Market Incumbents: Hedge against hard-shell luggage substitution by deepening rental program exclusivity and accelerating smart tracking integration for professional configurations. Lock in multi-year ballistic nylon supply agreements with Taiwanese mills before input volatility escalates. Prioritize backward integration into bio-based EVA foam padding production to capture certified material premiums. For New Entrants and Emerging Players: Begin with modular padded insert standardization for Japanese inbound tourism operators, where procurement consolidation creates vendor entry points. Target German and Austrian specialty retailers with documented REACH compliance as the most penetrable premium channel. Pursue direct-to-resort distribution contracts bypassing traditional retail markup structures. For Investors and Strategic Acquirers: Heritage outdoor brands with alpine ecosystem bundling are the most active acquirer in this space, seeking bag specialists to complete protective gear portfolios. Five-to-ten year viability favors vertically integrated players controlling design-to-retail workflows. Watch airline dimensional enforcement tightening as the inflection signal for wheeled variant demand compression.| Strategic Initiative | Industry Significance |
|---|---|
| Certified Material Traceability Investment | REACH and EU Green Deal documentation unlocks shelf space in German specialty retail. |
| Direct-to-Resort Distribution Bypass | Exclusive rental program contracts with Niseko operators secure recurring revenue streams. |
| Smart Tracking Integration | RFID and Bluetooth convergence addresses loss prevention for high-value professional gear transport. |
| Bio-Based Padding Transition | Plant-derived EVA foam displaces petroleum alternatives in premium wheeled configurations. |
| Regional Distributor Consolidation | Denver-based networks concentrate purchasing power away from direct manufacturer relationships. |
Research Methodology
Bottom-up resort rental procurement modeling reconciled against top-down textile mill capacity tracking forms the analytical core of this study. Primary interviews with equipment distributor procurement leads, resort rental program managers, Taiwanese textile mill operators, and European specialty retail buyers combined with secondary validation from customs trade records, EPA recycled content disclosure frameworks, and ECHA REACH registration databases. Triangulation across these sources anchored volume and value estimates.
Input-output matrices mapped raw material flows from South Korean and Taiwanese fabric mills through bag assemblers to regional distributor networks across the projection horizon. Segmentation dimensions included product configuration, material certification tier, end-user type, and geographic procurement cluster. CAGRs derived from slope-log analysis of documented procurement commitments and capacity expansion announcements. Forecast inputs incorporated airline dimensional guidance evolution and METI product safety standard revisions.
Caveats apply where FAA carry-on restriction tightening or ballistic polyester supply disruption could materially shift the outlook. Forecasts reflect assumptions about inbound tourism recovery trajectories and REACH enforcement consistency. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Travel Accessories
India Travel Accessories Market
Travel Accessories
Pet Travel Bags Market
Travel Accessories
Backpack Systems Market
Travel Accessories
Smart Luggage Market
Travel Accessories
Ergonomic Backpack for Children Market
Travel Accessories
Amenity Kits Market
Travel Accessories
Travel Accessories Market
Travel Accessories
Italy Travel Accessories Market
Travel Accessories
Travel Pouches Market
Travel Accessories
Pet Travel Accessories Market
Travel Accessories
UK Travel Accessories Market