
 UK Travel Accessories Market | 2026-2036
UK Travel Accessories Market Size, Share, and Industry Trends Forecast 2026-2036
UK Travel Accessories Market Insights
Recycled polycarbonate is expanding its share in hard-shell luggage production, displacing virgin ABS across mid-tier and premium price bands. Samsonite International S.A. leverages its vertical manufacturing footprint to control resin sourcing costs. Antler Ltd. anchors its domestic positioning through British design heritage and localized assembly. Travel Blue Ltd. competes on airport retail exclusivity, securing high-margin placement in Heathrow and Gatwick terminals.
UK travel accessories encompass luggage, organizers, pillows, passport holders, and portable chargers designed for mobility, protection, and convenience during transit; hard-shell variants typically employ polycarbonate or polypropylene shells with aluminum telescopic handles and TSA-compliant locking mechanisms. Luggage dominates absolute revenue due to replacement cycles and airline size enforcement, while portable chargers represent the fastest-expanding category as USB-C Power Delivery standards converge with passenger device dependency. Online retailers capture volume leadership through subscription bundling and return flexibility, though airport kiosks retain premium pricing power on impulse purchases.
The UK's Plastic Packaging Tax and extended producer responsibility frameworks under the Environment Agency shape material compliance costs for domestic manufacturers and importers alike. REACH regulations administered by the Health and Safety Executive restrict phthalate content in soft-touch luggage components and synthetic leather passport holders. Trading Standards enforces product safety marking under UKCA post-Brexit transition, creating certification friction for EU-sourced inventory. Stakeholders must monitor evolving customs documentation requirements and carbon border adjustment mechanisms to preserve margin structure and market access continuity.
Market Dynamics
The UK's Plastic Packaging Tax is compressing virgin resin demand across luggage supply chains, forcing manufacturers to requalify polycarbonate grades and absorb compliance costs through specification changes rather than price increases.
Growth Catalysts
- Business travel recovery:Corporate route expansion from London City and Heathrow Terminal 5 is accelerating replacement cycles for premium hard-shell luggage with integrated charging ports.
- REACH phthalate restrictions:Soft-touch component reformulation is opening specification windows for bio-based polyurethane alternatives in passport holders and travel organizers.
- USB-C Power Delivery convergence:Universal charging standards are collapsing adapter SKU proliferation, enabling accessory bundling strategies at airport retail.
Market Restraints
- Resin price volatility:Virgin polycarbonate feedstock costs tied to benzene derivatives create margin compression for mid-tier hard-shell producers without captive resin sourcing.
- UKCA marking friction:Post-Brexit conformity assessment duplication delays EU-sourced inventory clearance at Dover and Felixstowe ports.
- Aluminum telescopic handle supply:Extrusion capacity concentration in China's Zhejiang province exposes British assemblers to shipping rate spikes and extended lead times.
Strategic Opportunities
- Scottish Highlands tourism corridor:Underdeveloped airport retail presence at Inverness and Aberdeen creates first-mover positioning for adventure-focused luggage lines.
- Extended Producer Responsibility frameworks:Defra's packaging waste reforms incentivize take-back programs and closed-loop polycarbonate recovery systems.
- RFID-integrated security:Convergence of near-field communication with biometric passport standards is enabling premium tiering through trackable luggage tags.
Industry Challenges
- Polymer chemist talent scarcity:Formulation expertise for recycled-content polycarbonate blends concentrates with legacy automotive suppliers, constraining rapid material transitions.
- Multi-standard certification timelines:Simultaneous UKCA, CE, and FAA lithium battery transport approvals extend product launch windows by four to six months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UK Travel Accessories Market |
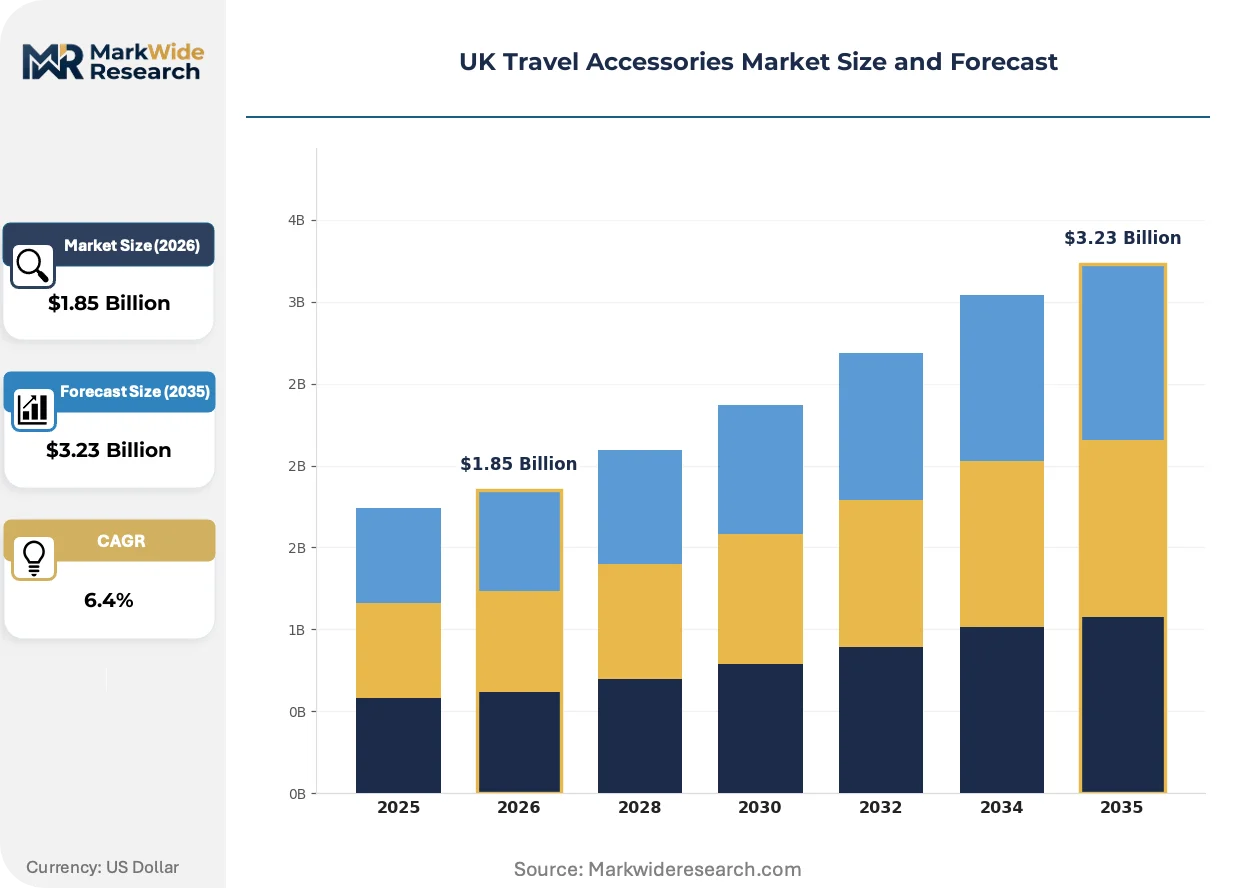
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Luggage, Travel Organizers, Travel Pillows, Passport Holders, Portable Chargers, Others Distribution Channel: Online Retailers, Specialty Stores, Department Stores, Airport Kiosks, Travel Agencies, Direct Sales Customer Type: Business Travelers, Leisure Tourists, Backpackers, Students, Senior Citizens, Families Application: Short-Term Trips, Long-Term Vacations, Adventure Travel, Corporate Travel, Commuting, Study Abroad |
| Companies Covered | Samsonite International S.A., Rimowa GmbH, Delsey, Antler Ltd., Design Go Ltd., Travel Blue Ltd., Victorinox AG, Tumi Holdings Inc., Briggs & Riley Travelware, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UK Travel Accessories Market Trends and Innovations
Material science advances and charging technology standardization are compressing product development cycles while regulatory compliance costs reshape competitive positioning across British manufacturing and import channels.
Recycled polycarbonate with post-consumer content certification is integrating into hard-shell luggage platforms as a structural differentiator. Premium business travelers now specify minimum recycled content thresholds in corporate travel procurement policies. This specification shift is integrating sustainability credentials into pricing power rather than treating them as optional premiums.
The Environment Agency's extended producer responsibility enforcement is tightening documentation requirements for synthetic leather components in passport holders and travel wallets. Manufacturers must now trace phthalate content through three-tier supply chains to demonstrate REACH compliance. Soft-touch luggage categories face the steepest reformulation costs as existing compound libraries fail new migration test standards.
Airport retail exclusivity contracts are fragmenting as online direct-to-consumer channels capture replacement purchases outside travel occasions. British consumers now research luggage specifications through comparison platforms before entering departure terminals. This behavior shift concentrates impulse premium capture within Heathrow Terminal 5 and Gatwick North terminals while eroding margin in regional airports.
UK Travel Accessories Market Segmentation
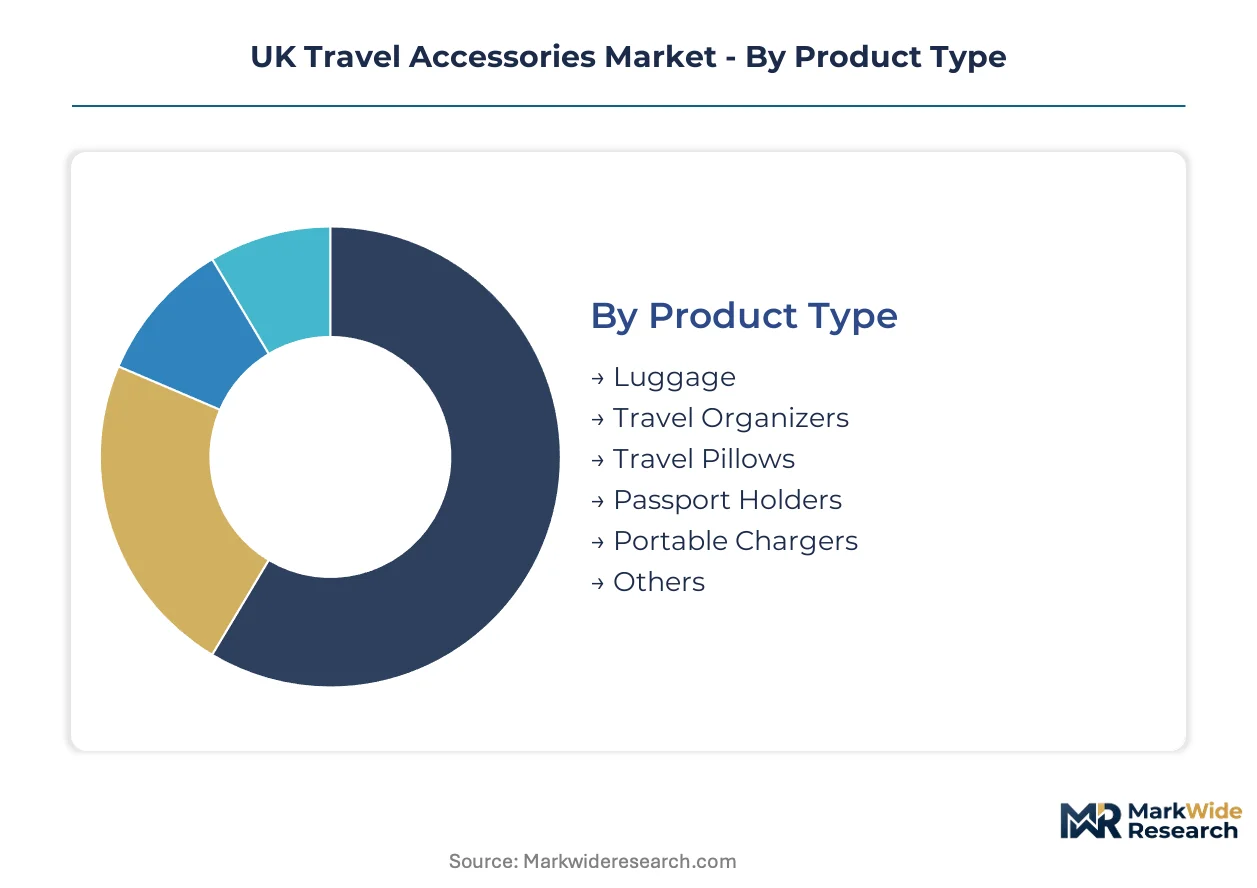
Travel accessories in the UK fragment across four intersecting dimensions that determine procurement channels, margin structure, and material specifications. Understanding these splits reveals where recycled polycarbonate adoption concentrates and where airport retail retains pricing power against online erosion.
Product Type:
Buyers prioritize protection-to-weight ratios and charging integration when selecting accessories for Heathrow and Gatwick departures.
- Luggage:Hard-shell variants employ polycarbonate or polypropylene shells with aluminum telescopic handles and TSA-compliant locking mechanisms. Corporate travel procurement policies now specify minimum recycled content thresholds for cabin and checked baggage across Greater London and the South East corridor.
- Portable Chargers:USB-C Power Delivery standards converge with passenger device dependency. Business travelers driving adoption through replacement cycles tied to airline route expansion from London City and Heathrow Terminal 5.
- Travel Organizers:Compression cubes and garment folders target leisure tourists seeking cabin-baggage optimization.
- Travel Pillows:Memory foam and inflatable variants serve long-haul passengers on transatlantic routes.
- Passport Holders:Synthetic leather and RFID-blocking materials face REACH phthalate restrictions requiring three-tier supply chain documentation.
- Others:Luggage tags, packing cubes, and toiletry kits round out the accessory ecosystem.
Luggage leads on scale; portable chargers lead on momentum.
Distribution Channel:
Channel selection in the UK hinges on purchase timing relative to departure and return flexibility requirements.
- Online Retailers:Subscription bundling and return flexibility capture volume leadership. British consumers research specifications through comparison platforms before entering departure terminals, eroding regional airport margins.
- Airport Kiosks:Exclusivity contracts at Heathrow and Gatwick terminals retain premium pricing power on impulse purchases. Travel Blue Ltd. and similar operators secure high-margin placement through terminal-specific agreements.
- Specialty Stores:Luggage specialists in Greater London offer fitting services and warranty support.
- Department Stores:John Lewis and Selfridges anchor mid-tier positioning through seasonal promotions.
- Travel Agencies:Package tour bundling creates accessory attachment opportunities.
- Direct Sales:Manufacturer websites bypass retail markups for brand-loyal repeat purchasers.
Online retailers dominate volume throughput; airport kiosks defend margin capture.
Customer Type:
Travel frequency and expense account access determine willingness to pay for integrated charging and recycled-content certification.
- Business Travelers:Corporate route expansion accelerates replacement cycles for premium hard-shell luggage with integrated charging ports. Procurement policies increasingly embed sustainability credentials as baseline requirements rather than optional premiums.
- Leisure Tourists:Price-sensitive segment driving demand for mid-tier recycled polycarbonate alternatives to virgin ABS.
- Backpackers:Lightweight durability priorities favor soft-shell construction over hard-shell protection.
- Students:Study abroad programs create seasonal demand spikes for entry-level luggage sets.
- Senior Citizens:Ergonomic handle systems and four-wheel spinner configurations address mobility considerations.
- Families:Multi-piece luggage sets and child-specific accessories concentrate purchase decisions around school holiday periods.
Business travelers anchor premium tier demand; leisure tourists scale recycled material adoption.
Application:
Trip duration and destination risk profile dictate protection level and power autonomy requirements.
- Corporate Travel:Short-haul European routes and long-haul intercontinental segments drive differentiated luggage specifications. Integrated charging ports and TSA-compliant locks dominate procurement checklists.
- Adventure Travel:Scottish Highlands tourism corridor creates first-mover positioning for durable hard-shell lines at underdeveloped Inverness and Aberdeen airport retail.
- Short-Term Trips:Cabin-baggage optimization prioritizes lightweight polycarbonate shells.
- Long-Term Vacations:Extended itineraries demand larger checked luggage with reinforced corner protection.
- Commuting:Daily rail and air commuters drive demand for compact organizers and portable chargers.
- Study Abroad:Semester-length programs create replacement cycle concentration in summer months.
Corporate travel concentrates premium spend; adventure travel offers geographic expansion opportunity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Greater London and the South East corridor concentrate UK travel accessories demand through Heathrow and Gatwick passenger volumes. Corporate procurement policies and airport retail placement drive premium-tier concentration in this cluster. Regional disparities emerge as Scottish and Northern English markets develop distinct channel preferences.
London and South East
Heathrow Terminal 5 and Gatwick North terminals anchor premium luggage sales through airport exclusivity contracts. The Environment Agency's extended producer responsibility frameworks shape material compliance documentation for synthetic leather passport holders sold through these channels. Travel Blue Ltd. secures high-margin placement in this corridor, leveraging impulse purchase behavior among business travelers.
Midlands
Manufacturing assembly for hard-shell luggage concentrates around Birmingham and Leicester industrial zones. Trading Standards enforces UKCA marking requirements on EU-sourced components entering through Dover and Felixstowe, creating certification friction for regional assemblers. Samsonite International S.A. maintains distribution hubs in this zone to serve central England retail networks.
Scotland
The Scottish Highlands tourism corridor generates adventure-focused demand for durable hard-shell lines at underdeveloped Inverness and Aberdeen airport retail. Defra's packaging waste reforms incentivize closed-loop polycarbonate recovery systems in Edinburgh and Glasgow urban centers. Antler Ltd. positions British design heritage to capture first-mover advantage in this underpenetrated geography.
North England
Manchester and Leeds metropolitan areas drive mid-tier recycled polycarbonate adoption among price-sensitive leisure tourists. REACH phthalate restrictions administered by the Health and Safety Executive force reformulation of soft-touch luggage components distributed through regional department stores. Online retailers capture volume leadership here through subscription bundling and return flexibility.
Wales
Cardiff and Swansea urban clusters support specialty luggage retailers offering fitting services and warranty support. The UK's Plastic Packaging Tax compresses virgin resin demand across supply chains serving Welsh distributors. Regional airport retail at Cardiff Airport remains marginal compared to English counterparts, concentrating purchases in city-center channels.
UK Travel Accessories Market Competitive Landscape
Global majors compete with regional champions across material sourcing, airport retail placement, and sustainability certification dimensions. The vendor base stratifies into three tiers: vertically integrated multinationals controlling resin supply chains, heritage-positioned domestic assemblers, and airport retail specialists securing terminal exclusivity. Two strategic archetypes dominate: scale-driven manufacturers leveraging captive polycarbonate sourcing, and design-led regional players emphasizing localized assembly. Competitive moves concentrate on backward integration into resin qualification and geographic expansion into underdeveloped Scottish airport retail.
Within the heritage-domestic tier, Antler Ltd. anchors British design positioning through localized assembly and domestic brand equity. Travel Blue Ltd. exemplifies the airport-retail specialist archetype, securing high-margin terminal placement at Heathrow and Gatwick. Samsonite International S.A. occupies the scale-driven multinational position, leveraging vertical manufacturing footprints to control resin sourcing costs across price bands.
| Leading Market Players |
|---|
| Samsonite International S.A. |
| Rimowa GmbH |
| Delsey |
| Antler Ltd. |
| Design Go Ltd. |
| Travel Blue Ltd. |
| Victorinox AG |
| Tumi Holdings Inc. |
| Briggs & Riley Travelware |
| Others |
Pricing and Supply Chain Analysis
Corporate travel procurement programs in Greater London and the South East corridor concentrate purchasing power for premium hard-shell luggage, anchoring a three-tier pricing structure across premium, standard, and economy levels that reflects recycled content certification tiers and airport retail placement exclusivity.
Pricing Analysis
Input-cost pass-through from virgin polycarbonate feedstock volatility compresses margins for mid-tier assemblers without captive resin sourcing. Pricing stratifies across premium, standard, and economy tiers based on recycled content certification thresholds and integrated charging port specifications. Cost compression in the standard tier intensifies because leisure tourists research specifications online before purchase, eroding airport kiosk premiums outside Heathrow Terminal 5 and Gatwick North. Business travelers demonstrate lowest price sensitivity, while students and backpackers anchor economy tier volume.
Supply Chain Analysis
Single-source vulnerability sits with China's Zhejiang province for aluminum telescopic handle extrusion, exposing British assemblers to shipping rate spikes and extended lead times. Raw material sourcing draws from Saudi Arabia for virgin polycarbonate feedstock, Belgium for specialty polymer additives, and domestic UK facilities for recycled-content resin qualification. Tariff exposure on EU-sourced components creates clearance friction at Dover and Felixstowe ports under UKCA marking requirements. Distribution runs through Birmingham and Leicester assembly hubs serving online retailers and airport kiosk operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in UK travel accessories rests on recycled polycarbonate adoption curves and premium-tier charging integration, with cost-down drivers from closed-loop recovery systems and specification consolidation around USB-C Power Delivery standards.
For Market Incumbents: Acquire polymer formulation expertise from legacy automotive suppliers to accelerate recycled-content polycarbonate blend qualification. Secure long-term airport retail exclusivity contracts at Inverness and Aberdeen before competitor entry. Counter the threat of direct-to-consumer channel erosion by embedding subscription bundling capabilities alongside physical retail presence.
For New Entrants and Emerging Players: RFID-integrated luggage tags with biometric passport convergence offer technology-first positioning against established hard-shell manufacturers. The Scottish Highlands tourism corridor presents the most penetrable geography, with underdeveloped airport retail and adventure-focused demand. A go-to-market angle through Edinburgh and Glasgow closed-loop recovery partnerships addresses Defra's extended producer responsibility incentives.
For Investors and Strategic Acquirers: Luggage specialists with captive airport kiosk networks are the most active acquirer in this space, seeking brand portfolios to fill distribution gaps. The acquisition target archetype combines British design heritage with localized assembly capabilities and UKCA certification infrastructure. Watch for inflection in corporate travel procurement policies embedding minimum recycled content thresholds as baseline requirements rather than optional premiums.
| Strategic Initiative | Industry Significance |
|---|---|
| Recycled Polycarbonate Integration | Post-consumer content certification from the Environment Agency unlocks premium pricing power in corporate procurement. |
| Airport Retail Expansion | First-mover placement at Inverness and Aberdeen captures adventure travel demand before competitor saturation. |
| USB-C Power Delivery Bundling | Universal charging standards collapse adapter SKU proliferation and enable margin-rich accessory packaging. |
| Closed-Loop Recovery Systems | Defra's packaging waste reforms incentivize take-back programs that reduce virgin resin cost exposure. |
| RFID Security Tiering | Near-field communication convergence with biometric passport standards enables trackable luggage tag premiums. |
Research Methodology
Coverage spans Greater London, the South East corridor, Midlands assembly zones, Scottish urban centers, and North England metropolitan areas, with primary inputs from each. The analysis combines structured interviews with polymer procurement leads at luggage manufacturers, airport retail operators at Heathrow and Gatwick, category buyers at John Lewis and Selfridges, and compliance officers at the Environment Agency and Health and Safety Executive. Secondary validation draws from UK customs records, Trading Standards enforcement data, SEC filings of listed luggage multinationals, and Defra packaging waste reporting. Bottom-up segment sizing triangulates against top-down passenger volume and replacement cycle estimates.
Granularity-level modeling operates at product type, distribution channel, customer archetype, and application dimensions, with additional disaggregation by recycled content certification tier and charging port specification. Volume and value outputs across the analysis window derive from passenger traffic projections, corporate travel recovery patterns, and material substitution elasticities. CAGRs are computed from annualized growth paths adjusted for regulatory phase-in timelines and procurement policy adoption curves. Forecast inputs include airline route expansion from London City and Heathrow Terminal 5, REACH phthalate restriction enforcement schedules, and USB-C standardization momentum.
The model holds under stable regulatory enforcement and continued corporate travel normalization; deviation in resin price volatility, customs clearance disruptions, or polymer chemist labor scarcity would shift trajectory bounds. Forecasts reflect documented assumptions about substitution rates and certification adoption timelines. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Travel Accessories
Ergonomic Backpack for Children Market
Travel Accessories
Travel Accessories Market
Travel Accessories
Snowboard Bags Market
Travel Accessories
Amenity Kits Market
Travel Accessories
Pet Travel Accessories Market
Travel Accessories
Travel Pouches Market
Travel Accessories
India Travel Accessories Market
Travel Accessories
Smart Luggage Market
Travel Accessories
Italy Travel Accessories Market
Travel Accessories
Backpack Systems Market
Travel Accessories
Pet Travel Bags Market