
 Backpack Systems Market | 2026-2036
Backpack Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Backpack Systems Market Outlook
Recycled polyester is expanding its share in backpack construction as brands respond to supply-chain cost volatility and consumer sustainability preferences. Osprey leverages closed-loop manufacturing partnerships to secure certified recycled inputs across its technical pack lines. Deuter sustains European production scale through in-house assembly facilities in Germany and Vietnam. Patagonia differentiates via transparent sourcing standards that command premium positioning in specialty retail channels.
Backpack systems are load-bearing enclosures engineered from woven textiles, foams, and hardware to distribute weight across the shoulders, hips, and sternum, typically incorporating adjustable torso lengths, framed back panels, and weather-resistant coatings for protection in transit. Their primary purpose spans civilian recreation, professional military operations, and daily commuter transport of electronics and personal goods. Hiking packs occupy the largest value pool due to technical complexity and replacement cycles tied to seasonal outdoor participation. Tactical packs represent the fastest-growing product type as defense modernization programs specify modular load-bearing platforms compatible with body armor systems. Daypacks remain a mature, high-volume segment where margin compression from private-label competition constrains branded pricing power.
The European Chemicals Agency enforces REACH substance restrictions on textile treatments and dyes used in backpack manufacturing, compelling suppliers to reformulate water-repellent coatings. The U.S. Federal Trade Commission monitors environmental marketing claims under Green Guides, penalizing vague recycled-content assertions that lack substantiation. Military procurement through NATO standardization agreements further dictates interoperability requirements for tactical pack dimensions and attachment interfaces. Stakeholders must monitor evolving extended-producer-responsibility frameworks in the European Union and California that will mandate textile collection infrastructure and recycled-content minimums.
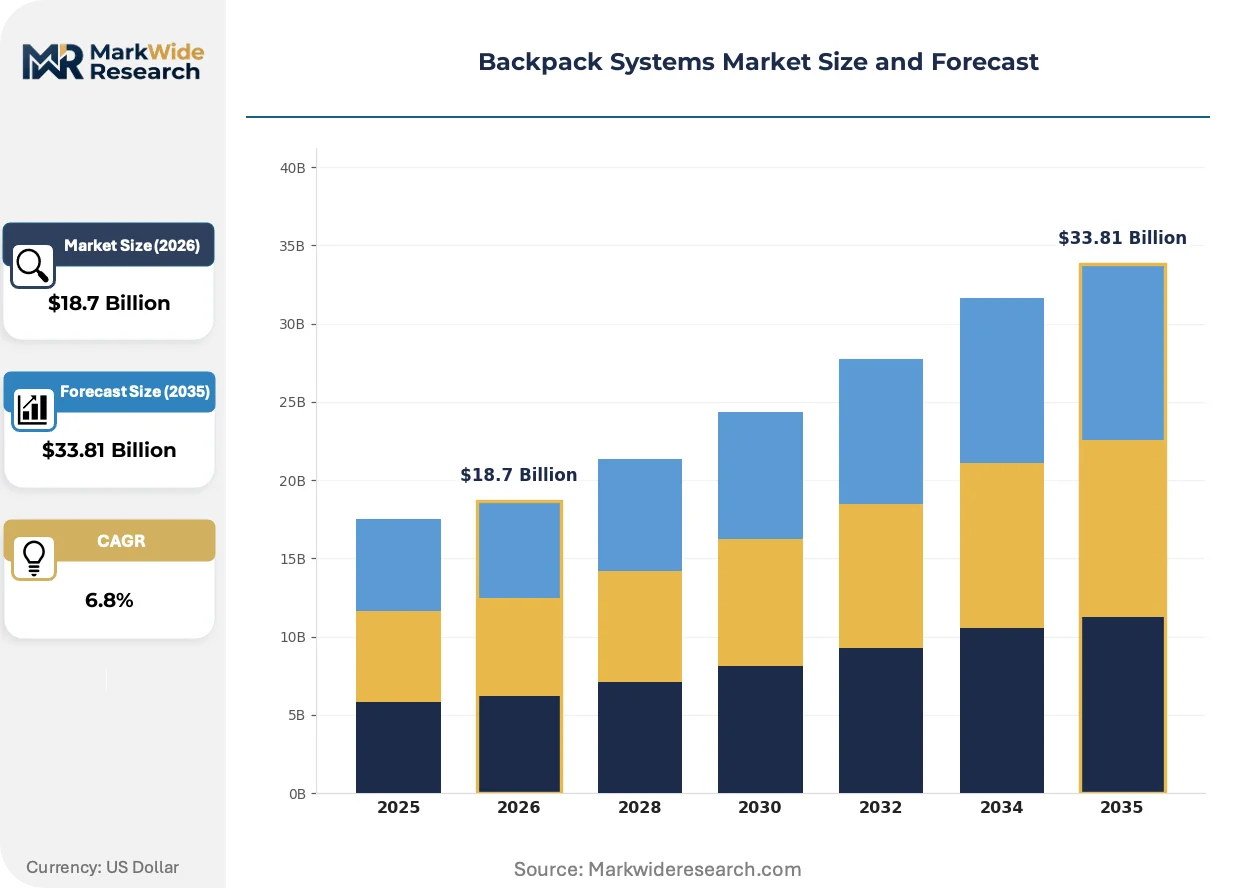
Market Dynamics
Recycled ocean-bound polyester is compressing virgin nylon margins across mid-tier backpack suppliers, forcing reformulation of water-repellent coatings to meet ECHA REACH substance restrictions while NATO military procurement specifications accelerate modular platform standardization.
Growth Catalysts
- REACH substance restrictions:The European Chemicals Agency mandates reformulated textile treatments, compelling suppliers to develop compliant water-repellent coatings that open premium positioning for certified sustainable packs.
- NATO standardization agreements:Military procurement programs specify modular load-bearing platforms compatible with body armor systems, driving interoperability requirements across tactical pack dimensions and attachment interfaces.
- Outdoor recreation participation:Federal defense spending and civilian outdoor activity in the United States sustain dual commercial and institutional demand channels for technical load-bearing equipment.
Market Restraints
- Input cost volatility:Recycled ocean-bound polyester from Repreve alters cost structures unpredictably as virgin nylon faces displacement pressure, squeezing margin predictability for mid-tier suppliers.
- Supply concentration risk:Premium daypack production relies on limited certified recycled input streams, creating bottleneck vulnerability when closed-loop manufacturing partnerships face capacity constraints.
- Technical limitation:Modular MOLLE-compatible designs require precision hardware integration that exceeds small-scale supplier capability, limiting vendor pool expansion.
Strategic Opportunities
- Extended-producer-responsibility frameworks:The European Union and California will mandate textile collection infrastructure and recycled-content minimums, creating first-mover advantage for compliant suppliers.
- Defense modernization programs:Tactical packs represent the fastest-growing product type as military specifications evolve, rewarding suppliers with NATO certification and modular platform expertise.
- Specialty retail channel expansion:Transparent sourcing standards command premium positioning in specialty retail, displacing mass-market distribution for technical pack lines with verified supply chain documentation.
Industry Challenges
- Certification timeline compression:FTC Green Guides enforcement penalizes vague recycled-content assertions, requiring substantiation infrastructure that extends product development cycles.
- Skill gap in closed-loop manufacturing:Technical expertise for certified recycled input integration remains scarce, constraining production scale-up for sustainable pack lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Backpack Systems Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Daypacks, Hydration Packs, Hiking Packs, Tactical Packs End User: Outdoor Enthusiasts, Military Personnel, Students, Travelers Material: Nylon, Polyester, Canvas, Leather Size: Small, Medium, Large, Extra Large |
| Companies Covered | NIKE, Samsonite, Osprey, VF Corporation, Adidas, The North Face, Herschel Supply Co., Deuter, Patagonia, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Backpack Systems Market Strategic Shifts
Material substitution and regulatory compliance are converging to reshape competitive positioning across the backpack value chain, with sustainability verification becoming a technical capability rather than a marketing overlay.
Recycled ocean-bound polyester is decentralizing virgin nylon's historical dominance in technical pack construction. Premium daypack manufacturers are adopting certified recycled inputs at accelerated rates to hedge against petroleum-based polymer volatility. This material shift is decentralizing supply chain control from petrochemical conglomerates toward specialized recycling processors with ocean plastic collection partnerships.
ECHA REACH substance restrictions on textile treatments and dyes are compelling coating reformulation across European supply chains. Industrial consequence includes elevated R&D expenditure for compliant water-repellent chemistries that maintain performance parity. Hiking pack segments face the steepest compliance burden as technical weatherproofing specifications conflict with restricted substance lists, driving supplier consolidation toward larger formulators with regulatory affairs capacity.
Buyer concentration in institutional channels is compressing switching cycles for tactical load-bearing equipment. Defense procurement offices are consolidating vendor pools around NATO-certified suppliers with demonstrated modular platform interoperability. This pattern is most visible in the United States, where federal defense spending and outdoor recreation participation create dual-channel demand that rewards suppliers with both military certification and consumer brand recognition.
Backpack Systems Market Segmentation
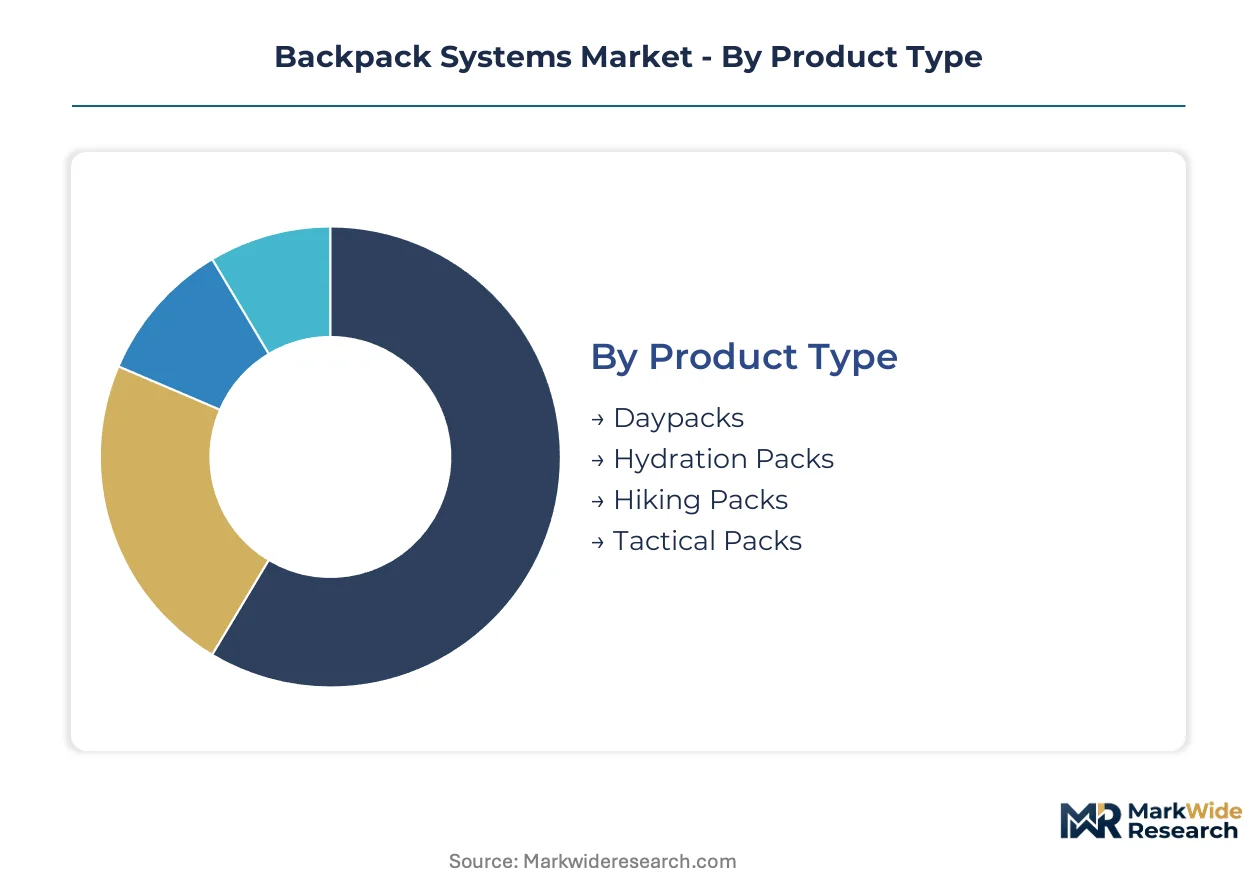
Backpack systems fragment across four distinct dimensions that dictate manufacturing complexity, margin structure, and channel strategy. Product type and end-user concentration determine capital allocation priorities, while material selection and size tiering shape supplier positioning against regulatory and cost pressures.
Product Type:
Capital intensity escalates with technical specification depth, framed back panel engineering, and modular hardware integration requirements.
- Hiking Packs:Technical load-bearing enclosures incorporate adjustable torso lengths, internal frame systems, and weather-resistant coatings for multi-day expeditions. Demand concentrates in the United States where federal land access and seasonal outdoor participation sustain replacement cycles tied to gear wear rates.
- Tactical Packs:Modular MOLLE-compatible platforms engineered for body armor system interoperability feature precision attachment interfaces and ballistic-rated textiles. NATO military procurement programs across member states specify these designs, accelerating vendor consolidation around certified suppliers with defense contract experience.
- Daypacks:Mature high-volume category serving commuter electronics transport and daily personal goods carriage.
- Hydration Packs:Specialized reservoirs with integrated drinking systems for endurance athletics and tactical field operations.
Most installed capacity flows through Hiking Packs. Expansion is steepest in Tactical Packs.
End User:
Customer type determines price elasticity, certification burden, and channel access requirements across institutional and commercial markets.
- Military Personnel:Institutional buyers mandate NATO standardization agreement compliance, modular platform interoperability, and documented supply chain provenance. Procurement offices in the United States and European member states consolidate vendor pools around certified suppliers, compressing switching cycles and elevating entry barriers for uncertified competitors.
- Outdoor Enthusiasts:Recreation participants prioritize technical weatherproofing, weight-to-capacity ratios, and seasonal replacement timing. United States demand anchors this segment through federal land access programs and outdoor industry association membership growth.
- Students:Price-sensitive volume segment with limited technical specification requirements and high private-label penetration.
- Travelers:Carry-on compatibility and security features drive purchase decisions in airport-adjacent retail channels.
Revenue concentration tilts toward Military Personnel. Outdoor Enthusiasts deliver the highest margin per unit.
Material:
Input cost volatility and regulatory compliance burden vary sharply across petroleum-based and recycled feedstock streams.
- Recycled Polyester:Ocean-bound polymer from specialized recycling processors displaces virgin nylon in premium daypack lines. ECHA REACH substance restrictions on textile treatments compel coating reformulation, rewarding suppliers with closed-loop manufacturing partnerships and certified input documentation.
- Nylon:Historical technical pack standard facing margin compression from petroleum price volatility and sustainability-driven brand switching.
- Canvas:Natural fiber alternative with limited weatherproofing performance constraining application to fashion-oriented and heritage-positioned lines.
- Leather:Premium positioning material with restricted application in technical load-bearing equipment due to weight and maintenance requirements.
Supply bottleneck risk concentrates in Recycled Polyester. Nylon retains the largest installed production base.
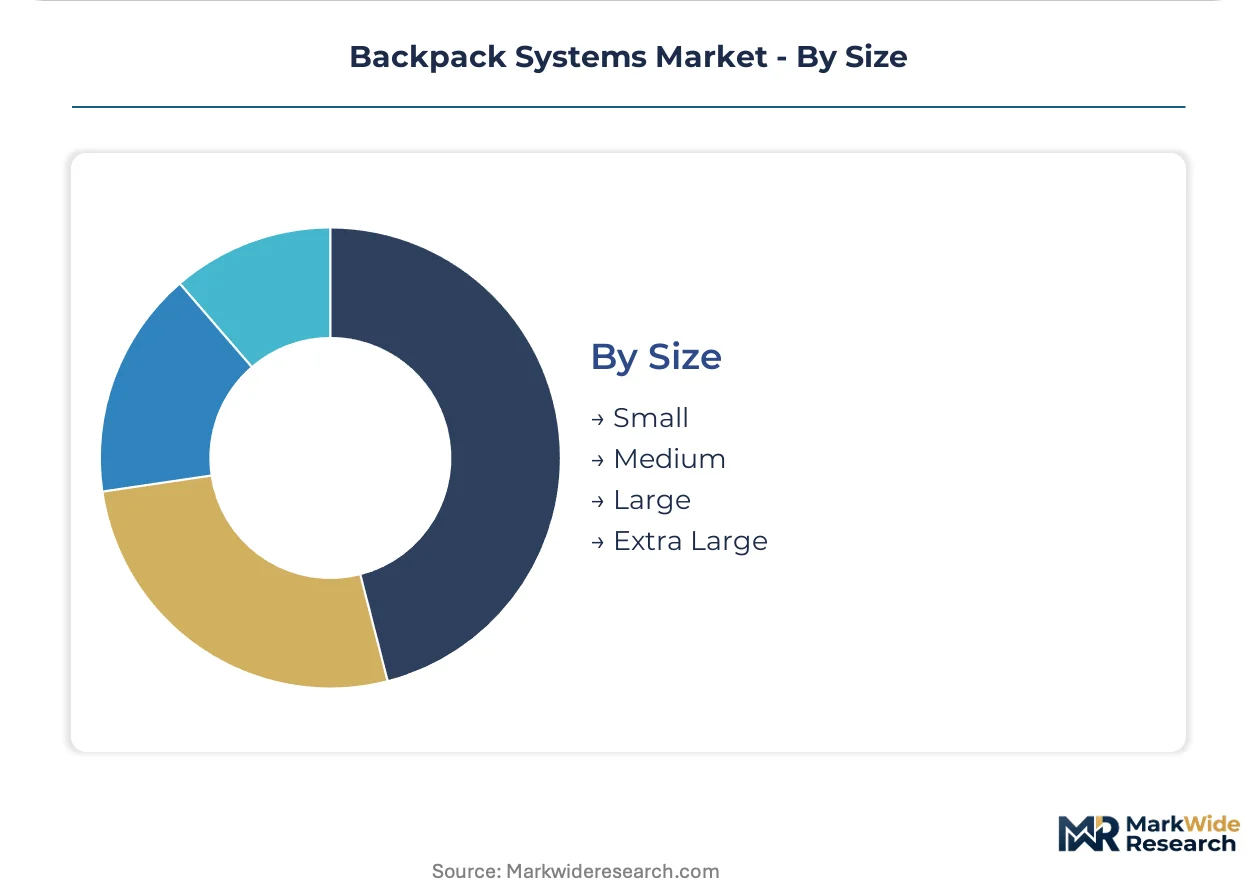
Size:
Capacity tiering aligns with trip duration, load weight distribution engineering, and retail shelf space economics.
- Large:Extended expedition capacity requiring sophisticated hip belt load transfer systems and frame suspension engineering. Technical complexity sustains premium pricing in specialty retail channels where staff expertise justifies higher transaction values.
- Medium:Versatile overnight-to-weekend capacity capturing the highest unit volumes across civilian recreation markets.
- Small:Day-trip and commuter-focused capacity with compressed margins from mass-market competition.
- Extra Large:Specialized expedition and military deployment capacity with limited production scale and concentrated supplier expertise.
Medium size dominates unit shipments. Large size commands the highest average selling price.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Colorado's outdoor recreation corridor anchors technical backpack manufacturing through concentrated specialty retail distribution and federal land management partnerships that sustain seasonal demand cycles for expedition-grade load-bearing equipment.
United States
Defense modernization programs and civilian outdoor participation sustain dual-channel demand for modular tactical platforms and technical hiking packs. The FTC enforces Green Guides standards on recycled-content marketing claims, compelling substantiation infrastructure. Colorado's Front Range hosts concentrated design offices and specialty retail headquarters serving Rocky Mountain recreation markets.
Germany
European military procurement through NATO standardization agreements drives specifications for MOLLE-compatible load-bearing systems. ECHA REACH substance restrictions mandate reformulated water-repellent coatings across textile treatments. Bavaria maintains in-house assembly facilities that sustain European production scale for technical pack lines.
Vietnam
Contract manufacturing capacity serves mid-tier suppliers seeking cost-competitive production for global brand licensing. The country's Ministry of Industry and Trade administers textile export standards that align with EU market access requirements. Ho Chi Minh City industrial zones concentrate cut-and-sew operations for international outdoor equipment orders.
China
Domestic outdoor recreation participation expands alongside manufacturing scale for synthetic textile components and precision hardware integration. SAMR oversees product safety standards for consumer goods including load-bearing equipment. Guangdong Province clusters polymer processing and molded frame component suppliers serving regional pack assembly.
Japan
Technical mountaineering culture sustains premium demand for lightweight frame systems and weatherproofing performance. METI promotes sustainable manufacturing standards that influence supplier certification requirements for recycled material documentation. Osaka-Kobe industrial corridors host specialized textile coating formulators serving domestic outdoor equipment brands.
Backpack Systems Market Competitive Environment
Global majors compete with regional champions across material certification and defense contract access, producing a tiered structure where premium positioning depends on transparent supply chain documentation and NATO interoperability credentials. Three archetypes dominate: vertically integrated European manufacturers with in-house assembly, brand licensors relying on Asian contract manufacturing, and specialty outdoor equipment houses with concentrated technical expertise. Competitive moves center on closed-loop manufacturing partnerships for certified recycled inputs and strategic positioning for extended-producer-responsibility compliance in the European Union and California.
Within the specialty outdoor equipment tier, Osprey and Deuter exemplify technical pack specialists with differentiated geographic production strategies, while Patagonia occupies a position defined by transparent sourcing standards that command premium retail placement. These three companies represent alternative pathways to sustainability verification—closed-loop partnerships, European in-house assembly, and supply chain transparency—each anchoring distinct competitive positioning against mid-tier suppliers facing margin compression from recycled input cost volatility.
| Leading Market Players |
|---|
| NIKE |
| Samsonite |
| Osprey |
| VF Corporation |
| Adidas |
| The North Face |
| Herschel Supply Co. |
| Deuter |
| Patagonia |
| Others |
Value Chain & Pricing Dynamics
NATO standardization agreements for modular load-bearing platforms are compressing vendor pools around certified suppliers, forcing uncertified mid-tier manufacturers to absorb reformulation costs for REACH-compliant coatings or exit tactical segments entirely. This procurement consolidation cascades into civilian channels where specialty retailers demand equivalent transparency documentation, elevating pricing power for suppliers with closed-loop manufacturing partnerships.
Pricing Analysis
Input-cost pass-through from recycled ocean-bound polyester volatility is stratifying pricing across three performance tiers. Premium-mid-economy pricing differentiation hinges on certified recycled-content documentation and NATO interoperability credentials, with technical hiking packs commanding the widest spreads. Cost compression in mid-tier daypacks is intensifying because private-label competition constrains branded pricing power. Military procurement offices exhibit the lowest price sensitivity, while student and commuter segments face acute margin pressure from mass-market alternatives.
Supply Chain Analysis
Recycled polyester supply rests on specialized ocean plastic collection partnerships concentrated in Southeast Asian coastal zones, with secondary processing clusters in Germany and Vietnam. Woven textile production draws from Vietnamese cut-and-sew facilities and Chinese polymer processing hubs, while precision MOLLE hardware fabrication centers on Guangdong Province. Single-source vulnerability concentrates in certified recycled input streams where closed-loop manufacturing partnerships face capacity constraints. Distribution runs through Colorado-based specialty retail headquarters serving Rocky Mountain recreation markets and defense procurement offices consolidating vendor pools.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The backpack systems market functions as a geographic-arbitrage play where European REACH compliance costs and Asian manufacturing scale differentials create margin optimization opportunities for suppliers with dual-hemisphere production footprints.
For Market Incumbents: Extend NATO certification maintenance into adjacent civilian tactical lines to capture defense procurement spillover demand. Deepen backward integration into certified recycled polyester streams to hedge against Repreve supply bottlenecks and ECHA coating reformulation requirements.
For New Entrants and Emerging Players: Enter via modular component specialization for MOLLE-compatible attachment systems, where technical precision requirements exceed small-scale supplier capability. Target the hydration pack segment for endurance athletics, where performance specifications are less stringent than military interoperability standards and direct-to-consumer channels reduce retail gatekeeper dependence.
For Investors and Strategic Acquirers: Asymmetric upside sits with European in-house assembly specialists with demonstrated ECHA compliance infrastructure and existing defense contract relationships. Five-to-ten year viability favors suppliers with verified closed-loop manufacturing partnerships as extended-producer-responsibility mandates expand. Watch California textile collection infrastructure rollout timing as an inflection indicator for recycled-content minimum compliance costs.
| Strategic Initiative | Industry Significance |
|---|---|
| Closed-Loop Manufacturing Partnership | Secures certified recycled polyester inputs from Repreve, insulating against virgin nylon volatility. |
| NATO Standardization Certification | Unlocks defense procurement channels across member states with interoperability requirements. |
| REACH-Compliant Coating Reformulation | Maintains European market access under ECHA substance restrictions on textile treatments. |
| Specialty Retail Channel Expansion | Displaces mass-market distribution through transparent sourcing documentation at Colorado headquarters. |
| Extended-Producer-Responsibility Preparation | Positions for EU and California textile collection mandates with first-mover compliance infrastructure. |
Study Parameters
Coverage spans North America, Europe, and Asia-Pacific manufacturing corridors, with primary inputs from each region combined with secondary validation. Interviews with product development directors at technical pack specialists, procurement officers at defense contractors, specialty retail category buyers, and textile coating formulators were triangulated against customs records, outdoor industry association participation data, and SEC filings from publicly traded parent companies. Bottom-up unit shipment estimates and top-down value reconciliation anchored the analytical framework.
Granularity-level modeling captured product type, end-user concentration, material feedstock, and capacity tier dimensions across the projection horizon. CAGRs were derived from segmented growth rate reconciliation with macroeconomic demand drivers. Forecast inputs incorporated seasonal outdoor participation indices, federal defense appropriations trajectories, and ECHA regulatory timeline assumptions.
Inputs from defense procurement databases and recycled material certification registries were available through the study window; gaps in proprietary military specification evolution introduce uncertainty bands around tactical pack demand projections. Forecasts reflect documented assumptions regarding NATO standardization agreement adoption rates and extended-producer-responsibility implementation sequencing. A small set of triggers—including ECHA substance restriction expansion, California textile collection infrastructure deployment, and Repreve processing capacity announcements—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Travel Accessories
Snowboard Bags Market
Travel Accessories
Smart Luggage Market
Travel Accessories
Travel Accessories Market
Travel Accessories
Pet Travel Bags Market
Travel Accessories
Amenity Kits Market
Travel Accessories
Pet Travel Accessories Market
Travel Accessories
Ergonomic Backpack for Children Market
Travel Accessories
UK Travel Accessories Market
Travel Accessories
Italy Travel Accessories Market
Travel Accessories
Travel Pouches Market
Travel Accessories
India Travel Accessories Market