
 Ergonomic Backpack for Children Market | 2026-2036
Ergonomic Backpack for Children Market Size, Share, and Industry Trends Forecast 2026-2036
Ergonomic Backpack for Children Market Insights
Premium orthopedic-grade certification is bifurcating the competitive landscape as parents prioritize spinal health validation over basic utility. JanSport leverages its institutional procurement relationships to sustain volume in North American school districts. Osprey differentiates through technical load-distribution engineering originally developed for adult outdoor packs. BLUEFAIRY specializes in lightweight eco-friendly constructions that occupy the sustainable premium niche in European markets.
An ergonomic backpack for children is a load-bearing container engineered with padded adjustable straps, lumbar support panels, and weight-distribution frames typically manufactured through thermoformed EVA foam molding and reinforced polyester weaving to minimize spinal compression during developmental years. The school segment dominates institutional procurement channels where district-level bulk purchasing concentrates volume, while the eco-friendly material tier captures margin expansion as regulatory pressure on virgin synthetics intensifies across OECD markets. Online retail channels are accelerating direct-to-consumer access, though specialty stores retain consultative influence for first-time buyers seeking fitting guidance.
The US Consumer Product Safety Commission enforces flammability and mechanical safety standards that govern strap integrity and small-component testing, while the EU Green Deal's textile sustainability framework is forcing reformulation of synthetic fabrics toward recycled content thresholds. China's GB standards for student supplies mandate load-bearing limits and dimensional specifications that manufacturers must satisfy for domestic market access. Stakeholders should monitor evolving chemical disclosure requirements under REACH and emerging state-level extended producer responsibility laws in California and New York that will reshape material sourcing decisions and compliance costs.
Market Dynamics
EU Green Deal textile sustainability mandates are forcing reformulation of virgin polyester toward recycled content thresholds, compressing margin structures for manufacturers dependent on conventional synthetic supply chains while opening premium positioning for compliant producers.
Growth Catalysts
- REACH chemical disclosure expansion:Stricter substance-of-very-high-concern listings under ECHA oversight are accelerating R&D investment in bio-based foam alternatives and water-based adhesives.
- Elementary school institutional procurement:District-level bulk purchasing programs in US public education systems are standardizing orthopedic-grade specifications across thousands of schools simultaneously.
- Guangdong manufacturing cluster concentration:Integrated EVA foam molding and textile weaving capabilities within single industrial zones are compressing production lead times and enabling rapid prototype-to-scale transitions.
Market Restraints
- Recycled polyester feedstock volatility:Post-consumer PET bottle supply fluctuations and rPET pricing premiums are squeezing gross margins for eco-tier product lines.
- Single-region foam chemical dependency:Specialty isocyanate formulations for high-rebound EVA cores concentrate among three East Asian chemical conglomerates, creating input concentration risk.
- California SB 54 EPR compliance friction:Extended producer responsibility timelines for textile waste are forcing premature packaging and take-back infrastructure investments ahead of revenue recovery mechanisms.
Strategic Opportunities
- India organized retail penetration:Modern trade and e-commerce platform expansion in tier-2 cities is creating first-mover advantage for brands establishing orthopedic fitting consultation infrastructure.
- Load-sensor IoT convergence:Integration of pressure-mapping films with smartphone applications is enabling real-time posture feedback subscriptions for health-conscious parents.
- EU Green Deal circular design mandates:Upcoming durability and repairability scoring requirements will reward modular frame architectures and replaceable component systems.
Industry Challenges
- Biomechanical certification talent scarcity:Pediatric orthopedic validation protocols require specialized kinesiology expertise that outpaces current university program output.
- Multi-jurisdiction testing redundancy:Separate flammability, mechanical, and chemical compliance sequences for US CPSC, EU REACH, and China GB standards extend product launch timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ergonomic Backpack for Children Market |
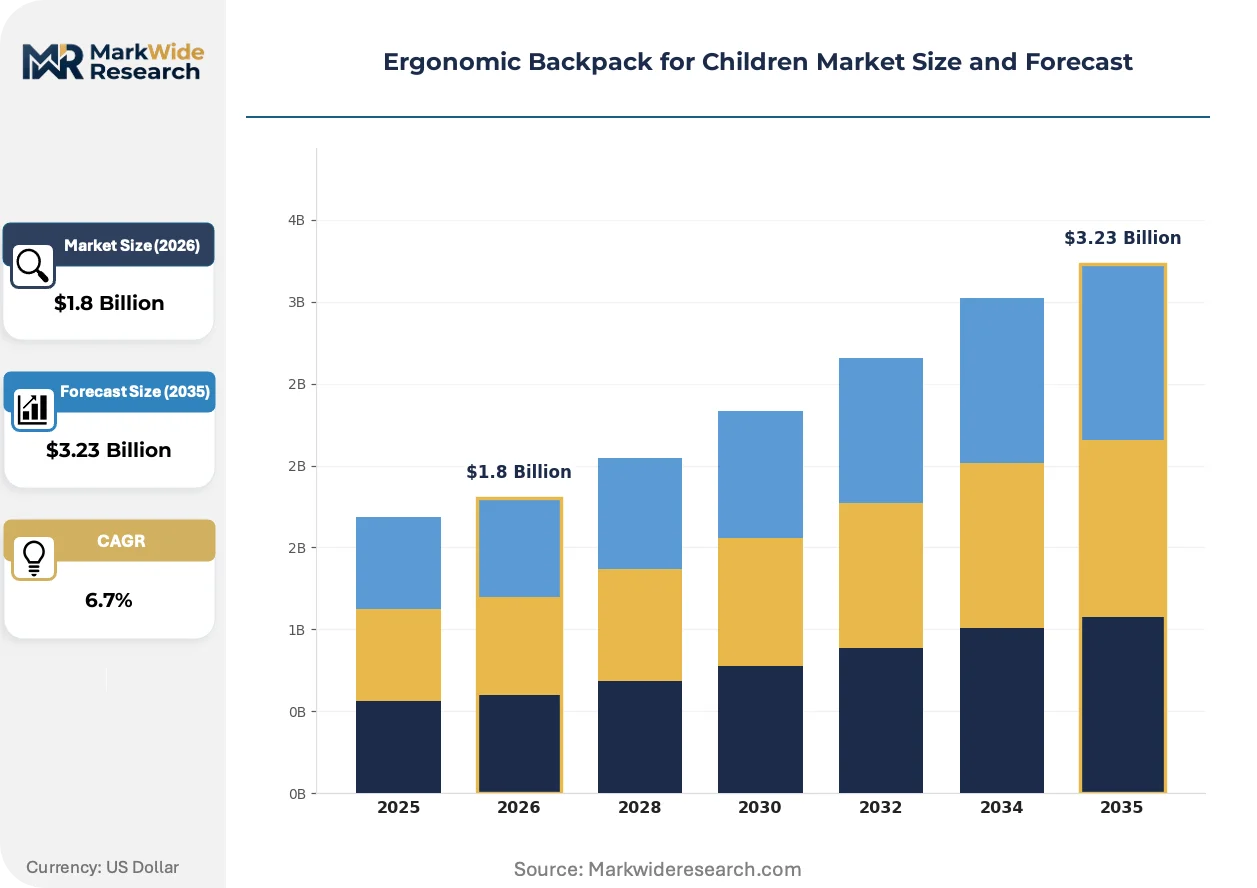
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Daily Use, Travel, Sports, School Material: Nylon, Polyester, Canvas, Eco-friendly Feature: Water-resistant, Lightweight, Adjustable Straps, Safety Reflectors Distribution Channel: Online Retail, Specialty Stores, Department Stores, Wholesale |
| Companies Covered | Bentgo, Simple Modern, VASCHY, Skip Hop, JanSport, BLUEFAIRY, J World New York, Jeune Premier, Osprey, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ergonomic Backpack for Children Market Trends and Innovations
Material science advances and regulatory chemistry restrictions are converging to reshape competitive differentiation, with sustainability verification and biomechanical validation replacing basic functional claims as primary purchase determinants.
Plant-derived TPU films and algae-based foam cores are fragmenting the mid-market material hierarchy. European specialty retailers are prioritizing these bio-alternatives for their premium private-label lines. This shift is fragmenting supplier relationships as petrochemical-dependent foam molders lose shelf-space access to biopolymer-certified competitors.
EU Green Deal textile sustainability framework implementation is mandating recycled content minimums and restricting microplastic shedding from synthetic fabrics. Apparel and accessories manufacturers must reformulate woven polyester toward mechanically recycled or bio-based feedstocks. The school backpack category faces accelerated compliance deadlines compared to fashion accessories due to higher abrasion and wash-frequency exposure profiles.
Parental purchasing behavior is rotating toward direct-to-consumer fitting tools that replace in-store consultation. Specialty retail foot traffic compression in North American suburban markets is forcing brands to deploy augmented reality sizing applications and video-based posture assessment. China domestic market adoption of live-stream commerce with real-time orthopedic Q&A is outpacing Western market development of equivalent trust-building mechanisms.
Ergonomic Backpack for Children Market Segmentation
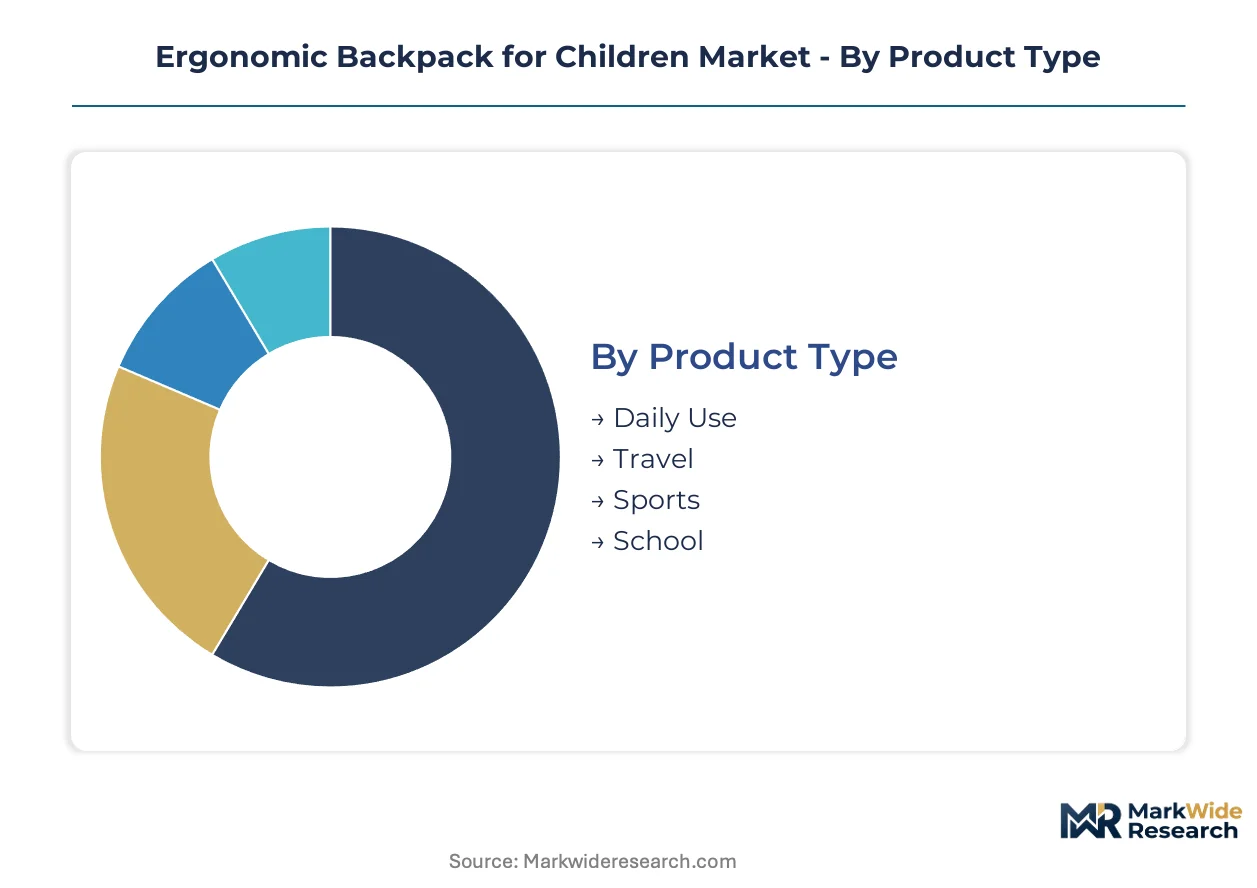
Ergonomic children's backpacks segment across functional use cases, material specifications, technical features, and channel access points. Each dimension carries distinct regulatory exposure and margin implications that shape manufacturer positioning strategies.
Product Type:
REACH chemical disclosure thresholds and CPSC mechanical safety standards apply differentially across use intensities, with daily-load specifications triggering stricter orthopedic validation protocols than occasional-use categories.
- School:Institutional procurement specifications mandate load-bearing limits and lumbar support panels engineered through thermoformed EVA foam molding. District-level bulk purchasing in US public education systems and China's GB-compliant domestic procurement channels concentrate volume for orthopedic-grade certification tiers.
- Daily Use:Urban parent demand for multi-purpose designs with modular compartment systems drives specification overlap between school and casual use cases, compressing pure-play positioning opportunities.
- Travel:Compact dimensions with reinforced grab handles and TSA-friendly laptop sleeves serve family vacation segments with shorter replacement cycles than academic-year products.
- Sports:Ventilated back panels and hydration-compatible designs target extracurricular activity segments with seasonal demand concentration and lower price elasticity than core academic segments.
Established volume favors School; emerging adoption favors Daily Use.
Material:
Cost tier stratification separates petrochemical-dependent supply chains from bio-based premium positioning, with EU Green Deal recycled content mandates compressing mid-market synthetic options.
- Eco-friendly:Plant-derived TPU films and algae-based foam cores command shelf-space priority in European specialty retail. Post-consumer PET bottle supply volatility and rPET pricing premiums constrain margin expansion despite regulatory tailwinds from EU textile sustainability frameworks.
- Polyester:Mechanically recycled woven constructions face accelerated compliance deadlines for microplastic shedding restrictions in high-abrasion school applications. Guangdong manufacturing clusters integrate textile weaving with EVA foam molding for rapid scale transitions.
- Nylon:High-tenacity ballistic weaves retain technical performance positioning for load-intensive applications with longer product lifecycles than standard polyester alternatives.
- Canvas:Natural fiber constructions occupy heritage aesthetic segments with limited orthopedic feature integration and declining share in certified ergonomic positioning.
Cost concentration sits with Polyester; premium expansion favors Eco-friendly.
Feature:
Customer type differentiation separates health-conscious parents seeking biomechanical validation from price-sensitive buyers prioritizing basic functional utility.
- Adjustable Straps:Padded sternum and waist belt configurations with sliding sternum straps enable torso-length customization across growth stages. Pediatric orthopedic fitting consultation infrastructure in India organized retail and North American specialty channels drives specification standardization.
- Lightweight:Frameless designs with minimal hardware target early elementary segments with strict load-to-body-weight ratio guidelines from school district wellness policies.
- Water-resistant:PU-coated fabrics and seam-taped constructions serve climate-variable regions with functional durability claims that substitute for premium material positioning.
- Safety Reflectors:Retroreflective tape integration addresses urban pedestrian visibility concerns with low incremental cost and mandatory specification in certain European municipal procurement frameworks.
Consultative channel influence concentrates on Adjustable Straps; direct-to-consumer conversion favors Lightweight.
Distribution Channel:
Geography of channel maturity determines where fitting guidance retains purchase influence versus where digital trust mechanisms displace physical consultation.
- Specialty Stores:In-store kinesiology expertise and posture assessment infrastructure sustain premium positioning in suburban North American markets experiencing foot traffic compression. Augmented reality sizing applications attempt to replicate consultative value for remote buyers.
- Online Retail:Live-stream commerce with real-time orthopedic Q&A in China domestic markets outpaces Western equivalent development, enabling direct-to-consumer access with trust-building mechanisms that bypass traditional retail markup structures.
- Department Stores:Seasonal promotional calendars and private-label consolidation pressure branded manufacturer shelf space in mid-tier price positioning.
- Wholesale:Institutional procurement relationships with school districts and corporate wellness programs concentrate volume with extended payment terms and specification compliance burdens.
Margin protection favors Specialty Stores; volume scaling favors Online Retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Guangdong manufacturing clusters anchor integrated EVA foam molding and textile weaving capabilities, compressing production lead times for scaled output. This supply-side concentration shapes competitive positioning across import-dependent markets while domestic demand fragmentation creates distinct procurement patterns.
United States
District-level bulk purchasing programs in public education systems concentrate volume for orthopedic-grade certification tiers. The US Consumer Product Safety Commission enforces flammability and mechanical safety standards governing strap integrity and small-component testing. California and New York state-level extended producer responsibility laws are reshaping material sourcing decisions and compliance cost structures for market entrants.
China
Rising parental health awareness converges with domestic manufacturing clusters to drive premium adoption curves. GB standards for student supplies mandate load-bearing limits and dimensional specifications that manufacturers must satisfy for domestic market access. Guangdong province's integrated industrial zones enable rapid prototype-to-scale transitions through captive EVA foam molding and polyester weaving capabilities.
Germany
Specialty retailers prioritize bio-alternative materials for premium private-label lines as EU Green Deal mandates accelerate compliance deadlines. ECHA oversight of substance-of-very-high-concern listings under REACH drives R&D investment in bio-based foam alternatives and water-based adhesives. Bavaria-based orthopedic consultation infrastructure sustains consultative channel influence for first-time buyers seeking fitting guidance.
India
Modern trade and e-commerce platform expansion in tier-2 cities creates first-mover advantage for brands establishing orthopedic fitting consultation infrastructure. BIS standards govern product safety specifications for imported and domestically manufactured student supplies. Maharashtra and Karnataka organized retail penetration is accelerating direct-to-consumer access with trust-building mechanisms that bypass traditional markup structures.
France
Municipal procurement frameworks in urban centers mandate retroreflective safety specifications for pedestrian visibility compliance. ANSM chemical disclosure requirements and EU Green Deal circular design mandates reward modular frame architectures and replaceable component systems. Île-de-France retail concentration sustains premium positioning for sustainable material tiers despite foot traffic compression in suburban markets.
Ergonomic Backpack for Children Market Competitive Landscape
Concentration sits with heritage outdoor equipment specialists and institutional procurement incumbents who control district-level relationship networks. The competitive landscape bifurcates between orthopedic-grade certification holders and volume-driven utility positioning. Three strategic archetypes dominate: technical load-distribution engineers, sustainable material premium specialists, and institutional procurement relationship managers. Competitive moves center on M&A for certification asset acquisition and backward integration into EVA foam molding capacity.
Among heritage outdoor equipment fabricators, Osprey and JanSport exemplify technical load-distribution and institutional relationship archetypes respectively. BLUEFAIRY occupies a position within the sustainable premium tier, anchoring bio-friendly construction positioning in European specialty retail channels. These three companies represent the dominant competitive vectors: technical engineering validation, procurement scale concentration, and regulatory-compliant material differentiation.
| Leading Market Players |
|---|
| Bentgo |
| Simple Modern |
| VASCHY |
| Skip Hop |
| JanSport |
| BLUEFAIRY |
| J World New York |
| Jeune Premier |
| Osprey |
| Others |
Pricing and Supply Chain Analysis
Recycled polyester feedstock substitution for virgin synthetics simultaneously shifts Guangdong manufacturing clusters toward rPET sourcing networks and compresses margin structures for mid-tier producers unable to pass material premiums to institutional buyers. This input transition concentrates pricing power among vertically integrated foam molders with captive textile weaving capabilities while fragmenting supplier relationships for petrochemical-dependent competitors.
Pricing Analysis
EU Green Deal textile sustainability mandates dictate the pricing tier structure across the European procurement landscape. Three-tier pricing structure across premium orthopedic-certified, standard institutional-grade, and economy utility levels separates products by certification depth and material provenance. Price differentiation hinges on REACH-compliant bio-based foam alternatives versus conventional EVA constructions, with volume scale driving standard-tier competitiveness. Cost compression in the recycled-content tier is intensifying because post-consumer PET bottle supply volatility prevents stable input costing. School district procurement officers demonstrate lowest price sensitivity due to wellness-policy mandates, while individual retail buyers in suburban North American markets exhibit highest elasticity.
Supply Chain Analysis
Just-in-time inventory strategies dominate downstream distribution while strategic stockpiling of specialty isocyanate formulations persists among three East Asian chemical conglomerates. Manufacturing gravity centers on China, Vietnam, and Bangladesh for textile weaving and cut-and-sew operations, with EVA foam molding concentrated in Guangdong province. Raw material dependencies include post-consumer PET flake for rPET yarn, toluene diisocyanate for high-rebound foam cores, and thermoplastic polyurethane films for bio-alternative laminates. Single-source vulnerability in isocyanate feedstocks creates input concentration risk for orthopedic-grade certification holders. Distribution runs through institutional procurement channels for school segment volume, with direct-to-consumer e-commerce capturing premium-tier margin expansion.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pediatric orthopedic validation expertise functions as the binding constraint across competitive tiers, with university kinesiology program output lagging certification demand from institutional procurement channels. This capability gap rewards early movers in biomechanical talent acquisition and testing infrastructure deployment.
For Market Incumbents: Consolidate district-level procurement relationships through exclusive multi-year supply agreements that embed orthopedic fitting consultation services. Acquire captive EVA foam molding capacity in Guangdong to compress lead times and defend margin position against rPET-dependent challengers. Prioritize backward integration into bio-based foam R&D partnerships as REACH chemical disclosure expansion accelerates.
For New Entrants and Emerging Players: Differentiate on load-sensor IoT convergence with smartphone-integrated posture feedback subscriptions, bypassing established consultative retail channels. Target tier-2 Indian cities through modern trade partnerships where orthopedic fitting infrastructure remains underdeveloped. Deploy live-stream commerce with real-time kinesiology Q&A to replicate trust-building mechanisms that displace specialty store influence.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed outdoor equipment specialists holding institutional procurement networks but lacking sustainable material certification. Long-term viability favors targets with modular frame architectures repairable under EU circular design mandates. Monitor California SB 54 EPR compliance friction as an inflection signal for packaging and take-back infrastructure valuations.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into EVA Foam Molding | Captive Guangdong production capacity compresses lead times for orthopedic-grade certification holders. |
| Bio-Based Material Certification Investment | REACH-compliant algae-foam alternatives secure shelf-space access in European specialty retail channels. |
| Load-Sensor IoT Platform Development | Real-time posture feedback subscriptions bypass physical consultation dependency in direct-to-consumer channels. |
| Institutional Procurement Relationship Expansion | District-level bulk purchasing agreements in US public education systems concentrate volume with extended terms. |
| Modular Frame Architecture Redesign | Replaceable component systems satisfy upcoming EU durability and repairability scoring requirements. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of customs records, trade databases, and regulatory filings from ECHA, CPSC, and SAMR. Product development executives at heritage outdoor equipment fabricators, procurement leads at US school district cooperatives, orthopedic consultants in Bavaria and Maharashtra, and supply chain directors at Guangdong manufacturing clusters provided structured input. Secondary validation drew from REACH substance-of-very-high-concern listings, China GB standards documentation, and EU Green Deal textile sustainability framework implementation guidance. Bottom-up segment sizing triangulated against top-down macroeconomic indicators across the analysis window.
Segmentation dimensions modeled include functional use case intensity, material specification tier, technical feature integration, and channel access maturity across the projection horizon. CAGRs derived from regression analysis of historical procurement volume patterns and parental health awareness indices. Industry-specific forecast inputs incorporated rPET feedstock pricing volatility curves and institutional wellness policy adoption rates by US state education departments.
The analysis sits within stated boundaries; outcomes outside sustained EU Green Deal enforcement intensity or accelerated China domestic health awareness campaigns would require recalibration. Forecasts reflect documented assumptions regarding recycled polyester supply stabilization and isocyanate chemical input availability. Practitioners should keep alternative scenarios live as REACH chemical disclosure expansion timelines and California extended producer responsibility implementation evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Travel Accessories
Pet Travel Accessories Market
Travel Accessories
Italy Travel Accessories Market
Travel Accessories
Amenity Kits Market
Travel Accessories
Pet Travel Bags Market
Travel Accessories
Travel Pouches Market
Travel Accessories
UK Travel Accessories Market
Travel Accessories
Backpack Systems Market
Travel Accessories
Smart Luggage Market
Travel Accessories
Travel Accessories Market
Travel Accessories
Snowboard Bags Market
Travel Accessories
India Travel Accessories Market