
 Travel Accessories Market | 2026-2036
Travel Accessories Market Size, Share, and Industry Trends Forecast 2026-2036
Travel Accessories Market Analysis
REACH compliance is shifting the cost-of-entry calculus for European suppliers, forcing reformulation of dyes, coatings, and adhesives across luggage and travel accessory production. Samsonite Corporation leverages its vertically integrated manufacturing footprint to absorb these regulatory costs without margin erosion. Delsey S.A. competes through Paris-based design studios that specialize in lightweight polycarbonate shell engineering. VIP Industries Ltd. dominates South Asian price tiers with Mumbai-centered production that sustains volume throughput across nylon and polyester lines.
Travel accessories encompass portable goods engineered for transit efficiency, typically constructed from woven synthetics, tanned hides, or molded polymers with specified denier ratings, tensile strength thresholds, and weatherproofing treatments designed to protect personal effects during movement. The luggage category anchors revenue due to replacement cycles tied to airline damage claims and durability expectations, while packing cubes represent the fastest-expanding segment as organization-focused travelers seek modular compression systems. Leather as a material commands premium positioning in business travel wallets and passport holders, though silicone is displacing conventional rubber in collapsible travel bottle and container applications.
FDA guidelines on antimicrobial surface claims influence U.S.-bound accessory marketing, while ECHA substance restrictions govern chemical inputs for EU-imported goods, and BIS certification requirements shape India's formal retail channel access for hard-sided luggage. Stakeholders must monitor evolving cabin baggage dimension rules from IATA member carriers, as these dimensional standards directly dictate form-factor R&D priorities and SKU rationalization across manufacturer portfolios.
Market Dynamics
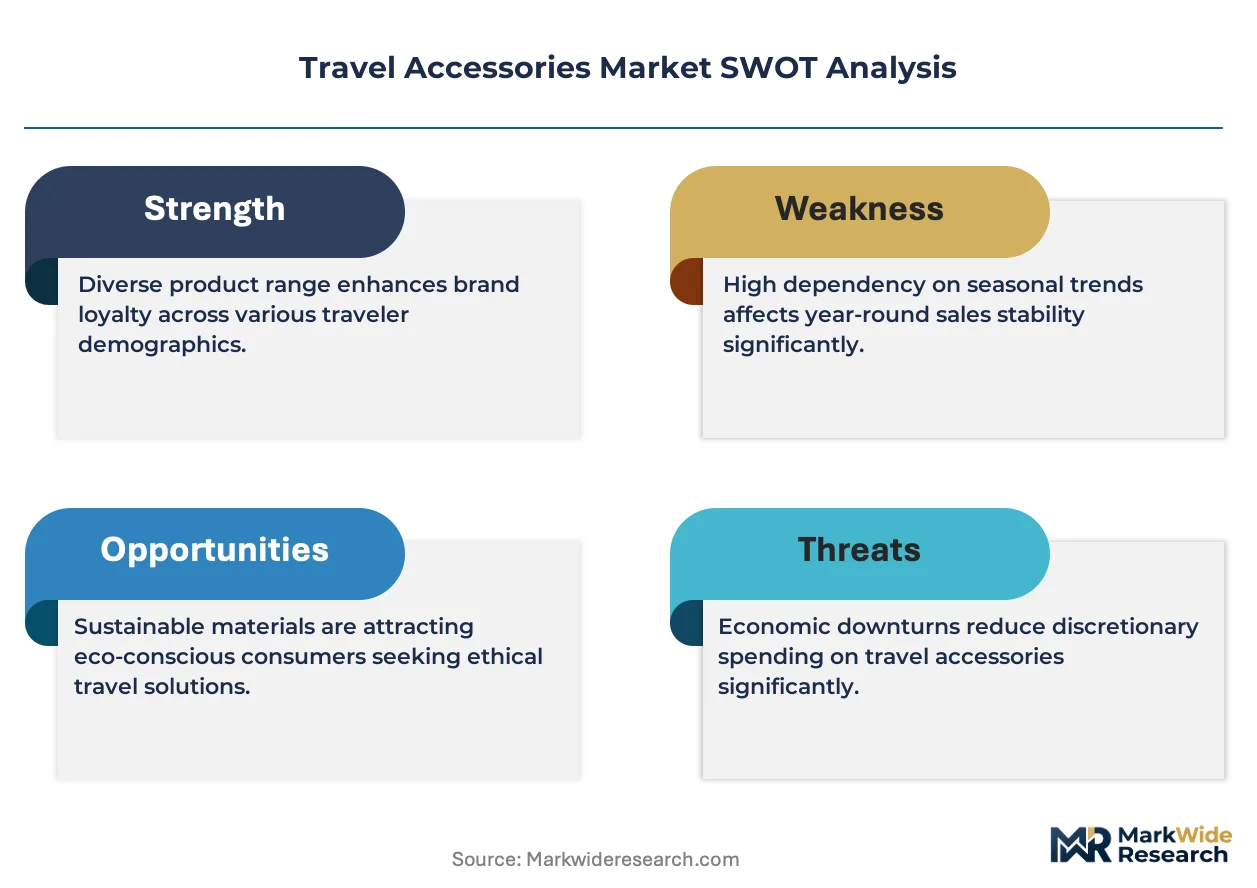
REACH compliance and the EU Green Deal are forcing wholesale reformulation of dyes, coatings, and adhesives across luggage manufacturing, compressing margins for suppliers lacking vertically integrated production or captive chemical processing capabilities.
Growth Catalysts
- Business Travel Procurement:Multinational firms are expanding premium luggage and organizational accessory programs, creating stable demand for polycarbonate hard-shell and leather wallet categories.
- REACH-Driven Material Innovation:ECHA substance restrictions are accelerating adoption of recycled nylon and bio-based leather substitutes among EU-bound manufacturers.
- Airline Connectivity Density:Hub cities with concentrated flight networks, particularly Frankfurt and Munich, concentrate affluent outbound travel demographics and drive replacement cycles.
Market Restraints
- Petrochemical Input Volatility:Polycarbonate and nylon 6,6 resin prices fluctuate with crude oil derivatives, compressing margin predictability for molded hard-shell producers.
- Regulatory Compliance Costs:REACH registration and BIS certification requirements create fixed-cost barriers that disproportionately burden small-batch manufacturers.
- Silicone Substitution:Collapsible travel bottles and containers are displacing conventional rubber and TPE formulations, eroding established material supplier relationships.
Strategic Opportunities
- Modular Compression Systems:Packing cubes represent underpenetrated white space as organization-focused travelers seek SKU-expandable accessories beyond traditional luggage.
- Antimicrobial Surface Claims:FDA guidelines create compliant marketing differentiation for U.S.-bound accessories with verified silver-ion or copper-infused treatments.
- Cabin Baggage Rule Convergence:IATA member carriers' evolving dimensional standards enable form-factor R&D specialization for carry-on optimized portfolios.
Industry Challenges
- Lightweight Engineering Talent Scarcity:Polycarbonate shell structural optimization requires specialized polymer engineers concentrated in Paris and Milan design studios.
- SKU Rationalization Complexity:Airline-specific cabin dimension variations force portfolio fragmentation that strains inventory management and forecasting systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Travel Accessories Market |
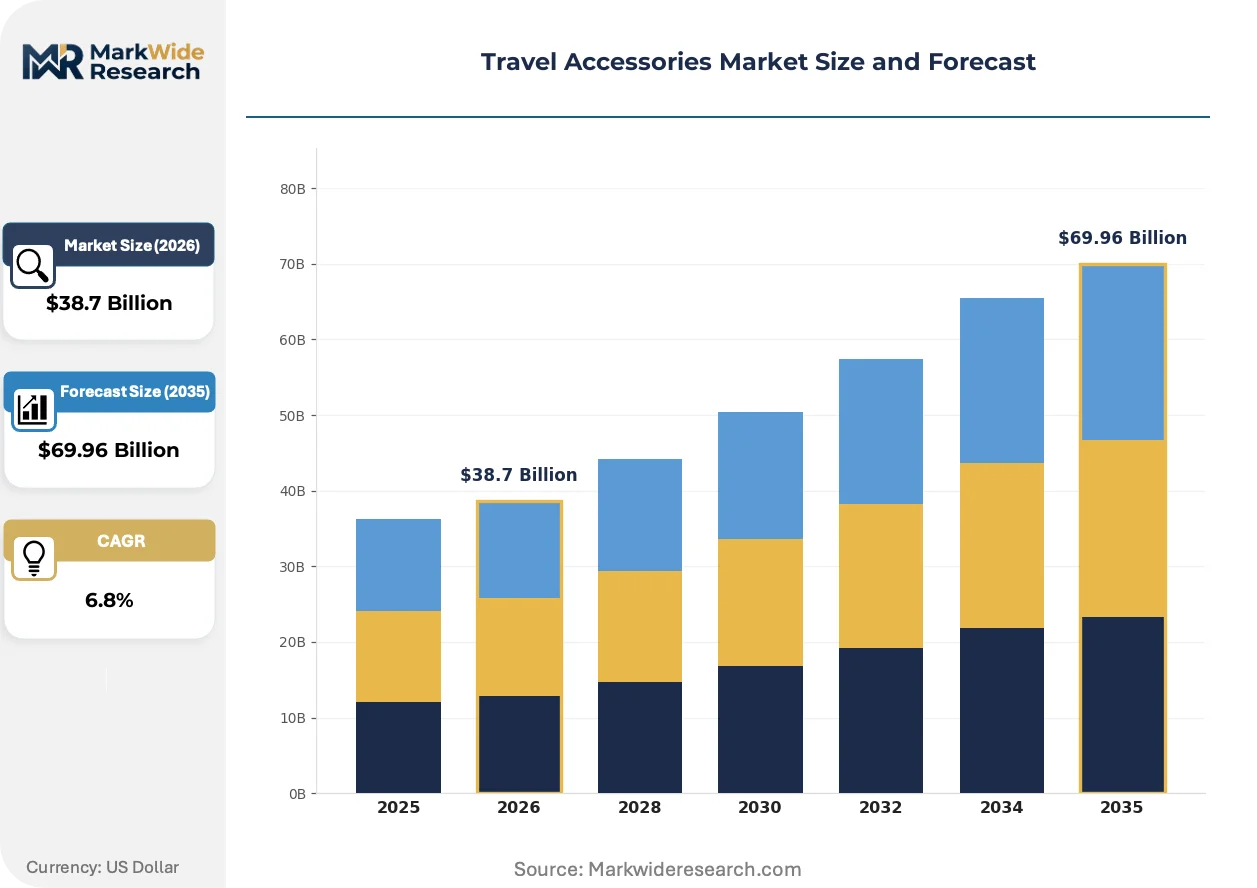
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $69.96 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Luggage, Travel Pillows, Passport Holders, Packing Cubes Material: Nylon, Leather, Polyester, Silicone Use Case: Business Travel, Leisure Travel, Backpacking, Family Trips Customer Type: Frequent Travelers, Occasional Tourists, Travel Enthusiasts, Corporates |
| Companies Covered | VIP Industries Ltd., Delsey S.A., Samsonite Corporation, Travelpro International Inc., Briggs & Riley Travelware, Rimowa GmbH, VF Corporation, LVMH Group, Tumi Holdings, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Travel Accessories Market Emerging Trajectories
Material science convergence with regulatory chemistry constraints is redefining performance benchmarks across synthetic and natural material categories, while distribution models adapt to direct-to-traveler channels.
Recycled ocean-bound nylon is integrating tensile strength specifications comparable to virgin polymer at reduced carbon intensity. Premium luggage manufacturers in Germany and Italy are adopting these inputs fastest, compressing the sustainability premium that previously separated mass-market from luxury positioning. The technology is integrating closed-loop supply chain traceability as a standard procurement requirement rather than optional certification.
EU Green Deal implementation timelines are tightening embodied carbon disclosure obligations for imported consumer goods. ECHA substance restrictions now govern not only finished articles but chemical inputs across tier-two suppliers, forcing reformulation of adhesives and weatherproofing treatments. Hard-sided luggage bound for EU retail channels bears the highest compliance burden, with manufacturers consolidating supplier audits to reduce verification redundancy.
Direct-to-consumer configuration tools are displacing traditional retail assortment models for organizational accessories. Travelers in Germany and the United States are designing modular packing systems through brand-owned platforms, bypassing department store buyers who previously curated SKU mixes. This channel shift concentrates demand data with manufacturers, enabling demand-signal responsive production scheduling that reduces finished goods inventory exposure.
Travel Accessories Market Segmentation
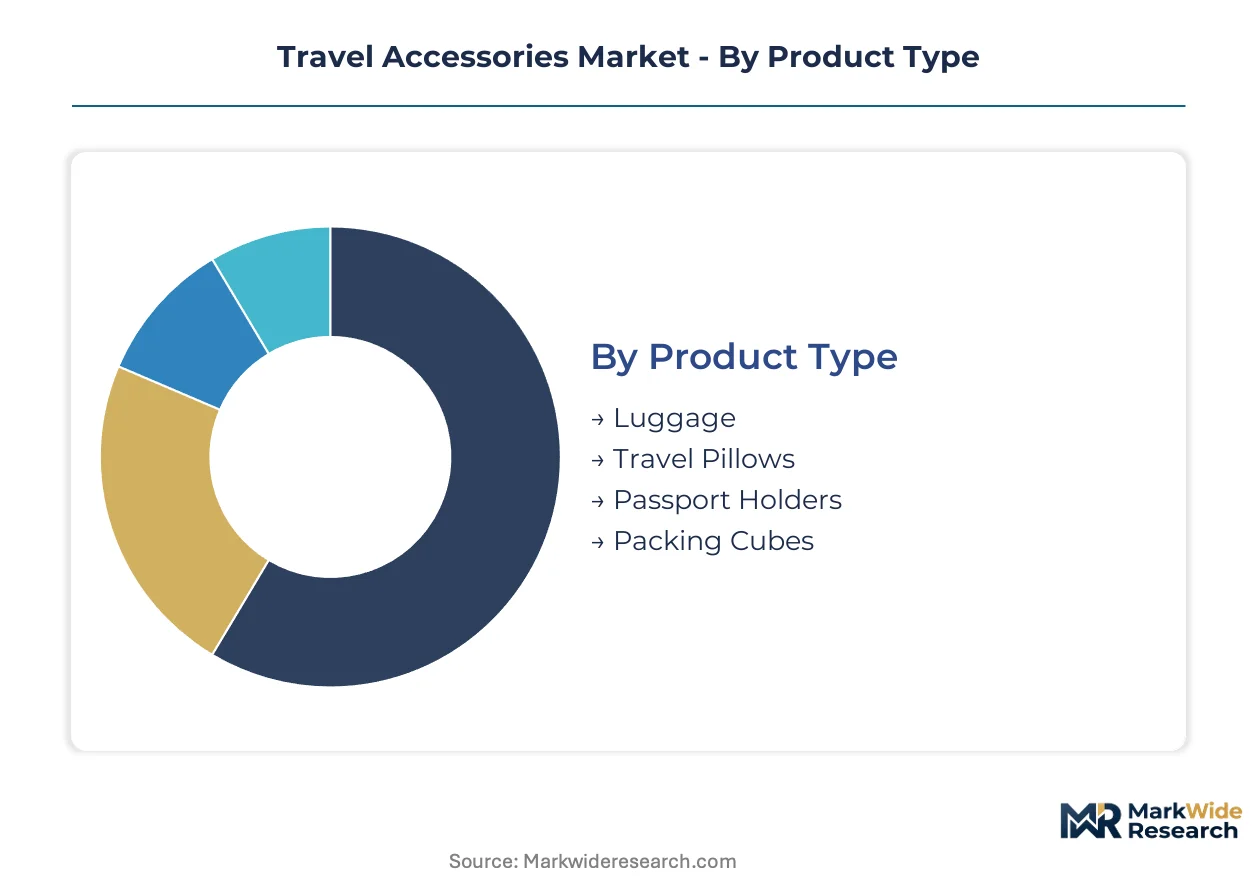
Travel accessories fragment across functional purpose, material chemistry, and behavioral intensity. Procurement patterns diverge sharply between replacement-driven luggage purchases and impulse-driven organizational accessories. Understanding these splits enables targeted portfolio allocation across manufacturing and distribution investments.
Product Type:
Volume concentrates in hard-shell and soft-sided luggage, while premium pricing power sits with modular organizational systems.
- Luggage:Hard-shell polycarbonate and soft-sided ballistic nylon constructions dominate airline check-in and carry-on applications. Replacement cycles accelerate in Germany and the United States where hub connectivity density drives damage claims and durability expectations. REACH-compliant coatings now penetrate even mid-tier ABS formulations.
- Packing Cubes:Compression-grade mesh and ripstop nylon systems enable modular organization within larger luggage volumes. Demand is climbing fastest among business travelers in Frankfurt and Munich who prioritize efficient cabin baggage compliance. Direct-to-consumer configuration tools bypass traditional retail curation for this segment.
- Travel Pillows:Memory foam and inflatable designs target neck support during long-haul transit.
- Passport Holders:Leather and synthetic wallet formats concentrate RFID-blocking features for security-conscious travelers.
Mature deployment sits with luggage. Newer deployment is concentrated in packing cubes.
Material:
Cost tiers separate petrochemical-derived synthetics from tanned hide and bio-based substitutes, with regulatory chemistry forcing reformulation at the premium end.
- Nylon:Recycled ocean-bound and virgin polymer grades specify tensile strength thresholds and denier ratings for abrasion resistance. German and Italian manufacturers absorb these inputs fastest, compressing the sustainability premium that previously separated mass-market from luxury positioning. Closed-loop traceability is now standard procurement requirement.
- Leather:Full-grain and corrected-grain hides command positioning in business travel wallets and passport holders. Tanneries in Italy face ECHA substance restrictions on chromium tanning agents, accelerating vegetable-tanned and bio-based leather substitute adoption for EU-bound production.
- Polyester:Lower-denier woven and non-woven constructions serve price-sensitive luggage linings and promotional travel accessories.
- Silicone:Food-grade platinum-cured formulations displace conventional rubber and TPE in collapsible travel bottles and containers, eroding established material supplier relationships.
Established supply chains anchor polyester. Reformulation investment is concentrating in nylon and leather.
Use Case:
Application intensity determines durability specifications and replacement frequency, with business travel sustaining premium pricing through corporate procurement programs.
- Business Travel:Polycarbonate hard-shell luggage and leather accessory categories dominate multinational firm procurement. Stable demand concentrates in Frankfurt, Munich, and Paris where dense airline connectivity supports affluent outbound demographics. IATA cabin baggage dimension rules directly dictate form-factor R&D priorities for this segment.
- Leisure Travel:Seasonal purchase patterns concentrate in department store and online channels, with price elasticity higher than business segments.
- Backpacking:Ultralight nylon and ripstop constructions prioritize weight minimization over durability for extended multi-destination itineraries.
- Family Trips:Volume-oriented luggage sets and organizational accessories serve multi-person travel requirements with color-coded differentiation features.
Procurement stability sits with business travel. Volume expansion is climbing fastest in leisure travel.
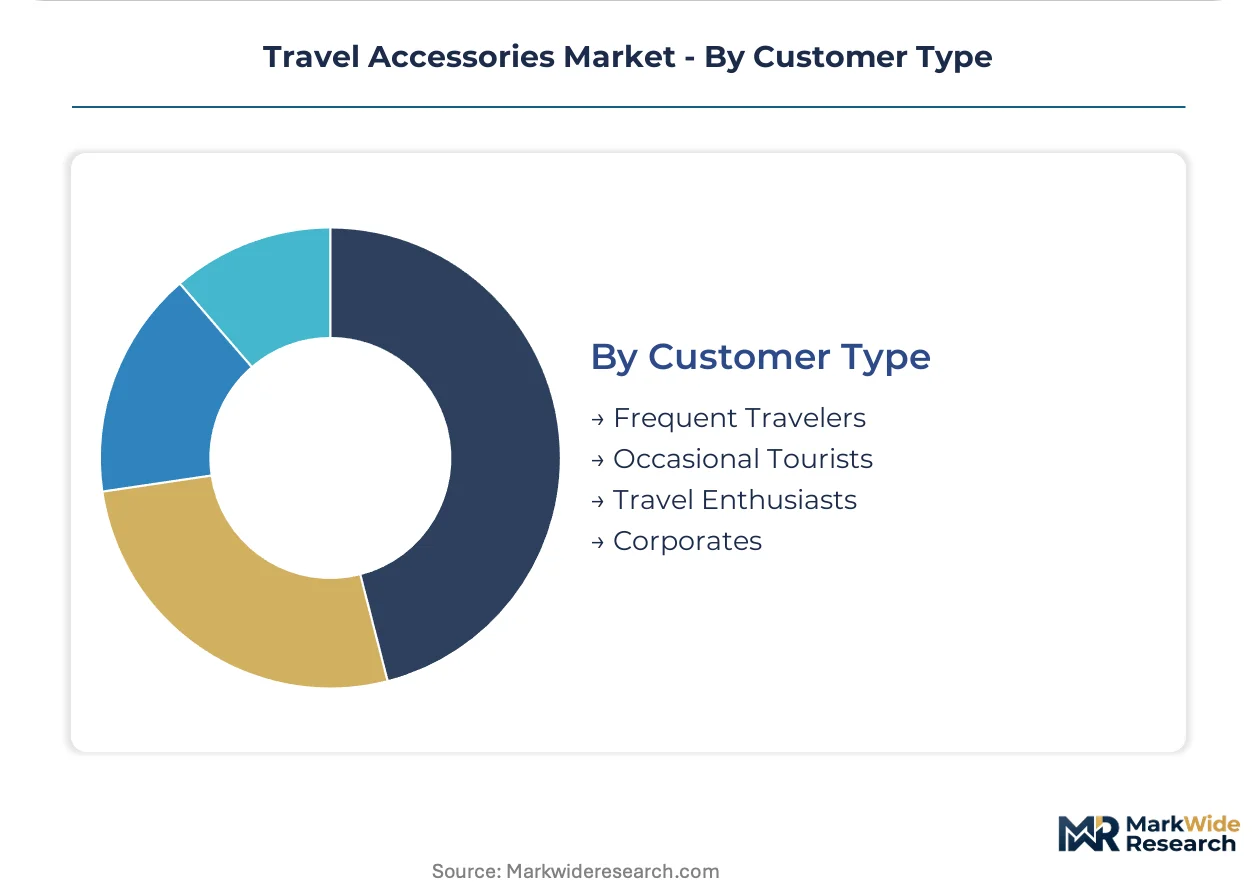
Customer Type:
Behavioral segmentation separates replacement-driven habitual purchasers from specification-sensitive corporate buyers and aspirational newcomers.
- Frequent Travelers:High-mileage individuals prioritize durability certifications and warranty terms over initial purchase price. Replacement cycles tie directly to airline damage claims and durability expectations in Germany and the United States.
- Occasional Tourists:Price-sensitive segment concentrates in seasonal promotional purchasing and entry-level nylon and polyester constructions.
- Travel Enthusiasts:Early adopters of modular packing systems and antimicrobial surface treatments drive SKU expansion in organizational accessories.
- Corporates:Centralized procurement programs at multinational firms create stable demand for premium luggage and leather wallet categories with standardized specifications across employee tiers.
Volume concentration sits with occasional tourists. Premium pricing power is expanding most quickly with corporates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Vietnam and Bangladesh are attracting luggage assembly operations through tariff exemptions and streamlined customs procedures. These zones concentrate cut-and-sew capacity for soft-sided nylon and polyester lines serving European and North American retail channels. Manufacturing migration is reshaping supplier networks across the travel accessories value chain.
United States
Corporate procurement programs at technology and consulting firms sustain premium luggage demand through centralized purchasing agreements. FDA guidelines on antimicrobial surface claims shape marketing strategies for U.S.-bound accessories with verified treatments. Los Angeles and New York City concentrate design studios and direct-to-consumer brand headquarters serving affluent business travelers.
Germany
Frankfurt and Munich function as hub cities where dense airline connectivity accelerates replacement cycles for damaged luggage. EU Green Deal implementation timelines tighten embodied carbon disclosure obligations for imported consumer goods. Bavaria hosts specialized polycarbonate shell engineering facilities serving premium hard-sided luggage production.
China
Yangtze River Delta manufacturing clusters supply molded polymer components and woven synthetic fabrics at scale for global luggage brands. GB standards and MIIT regulations govern product safety certifications for domestic retail distribution. Guangdong Province concentrates assembly operations for collapsible silicone travel containers displacing conventional rubber formulations.
India
Mumbai-centered production sustains volume throughput across nylon and polyester lines for price-sensitive South Asian markets. BIS certification requirements shape formal retail channel access for hard-sided luggage and organizational accessories. Maharashtra's industrial corridors host integrated textile and molding operations serving domestic and export demand.
Italy
Tanneries in Tuscany face ECHA substance restrictions on chromium tanning agents, accelerating vegetable-tanned leather adoption. REACH compliance costs compress margins for small-batch manufacturers lacking captive chemical processing. Milan design studios specialize in lightweight structural optimization for premium luggage shells.
Travel Accessories Market Vendor Landscape
European producers anchor the premium tier through design-forward engineering and regulatory compliance capabilities; Asian fabricators hold volume positions through integrated textile and molding operations. The vendor base separates into three functional layers: multinational brand houses with captive retail distribution, mid-scale specialists with regional manufacturing depth, and contract assemblers serving private-label programs. Two competitive moves dominate current positioning: backward integration into recycled nylon supply chains to absorb ECHA-driven material cost shifts, and direct-to-consumer platform investments that bypass traditional wholesale markups.
Within the multinational brand house tier, Samsonite Corporation and Delsey S.A. exemplify divergent geographic strategies. Samsonite leverages vertically integrated manufacturing footprints to absorb regulatory compliance costs without margin compression. Delsey occupies a position centered on Paris-based design capabilities in lightweight polycarbonate engineering. VIP Industries Ltd. anchors the mid-scale specialist layer through Mumbai-centered production sustaining volume throughput across synthetic material lines. These three enterprises represent distinct archetypes: global brand ownership with manufacturing control, design-led European positioning, and emerging market scale specialization.
| Leading Market Players |
|---|
| VIP Industries Ltd. |
| Delsey S.A. |
| Samsonite Corporation |
| Travelpro International Inc. |
| Briggs & Riley Travelware |
| Rimowa GmbH |
| VF Corporation |
| LVMH Group |
| Tumi Holdings, Inc. |
| Others |
Supply Flow & Price Mechanics
Recycled ocean-bound nylon feedstock flows from specialized polymer reclaimers through three distinct pricing tiers before reaching finished luggage SKUs, with virgin-grade alternatives commanding premiums that compress as REACH-compliant sourcing becomes baseline rather than differentiator.
Pricing Analysis
Short lead-time premiums separate spot inventory from contract-scheduled production across polycarbonate hard-shell and modular packing cube categories. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and after-sales warranty bundling. Pricing pressure stems from petrochemical input volatility that erodes margin predictability for molded hard-shell producers. Occasional tourists exhibit highest price sensitivity, while corporate procurement programs absorb premium positioning with minimal elasticity.
Supply Chain Analysis
Regional distribution centers in Germany, Vietnam, and Bangladesh orchestrate hub-and-spoke patterns that consolidate cut-and-sew capacity for soft-sided lines and molded component flows for hard-shell production. Raw material dependencies center on polycarbonate resin, ballistic nylon yarn, and chromium-tanned leather hides. Single-source vulnerability concentrates in Italian tanneries facing ECHA substance restrictions. Distribution runs through direct-to-consumer platforms that displace traditional wholesale markups for organizational accessories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The travel accessories sector sits in a material-transition phase as silicone formulations displace conventional rubber and TPE in collapsible container applications, forcing legacy suppliers to reformulate or cede share.
For Market Incumbents: Cement backward integration into recycled nylon supply chains to absorb ECHA-driven material cost shifts without margin compression. Prioritize captive chemical processing capabilities that neutralize REACH compliance burdens falling heaviest on small-batch competitors. Channel control through direct-to-consumer platforms defends against wholesale buyer consolidation.
For New Entrants and Emerging Players: The mid-tier price gap between polycarbonate hard-shell luggage and entry-level polyester constructions offers white-space entry for hybrid material formulations. Target modular packing cube segments where direct-to-consumer configuration tools bypass established retail gatekeepers. Pursue antimicrobial surface certification as compliant marketing differentiation for U.S.-bound accessories.
For Investors and Strategic Acquirers: Consolidation of supplier audits among EU-bound manufacturers is the leading indicator that margin compression is selecting for vertically integrated mid-cap specialists with captive chemical processing. Long-term viability favors enterprises controlling closed-loop traceability infrastructure. Watch for IATA cabin baggage rule convergence as signal for form-factor R&D specialization opportunities.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Recycled Nylon | Captive supply of ocean-bound polymer neutralizes ECHA substance restriction cost shocks for EU-bound production. |
| Direct-to-Consumer Platform Launch | Brand-owned configuration tools concentrate demand data and bypass department store buyer markups in Germany and the United States. |
| Antimicrobial Surface Certification | FDA-compliant silver-ion treatments create marketing differentiation for U.S.-bound accessories with verified claims. |
| Lightweight Structural Optimization R&D | Paris and Milan design studio talent concentrates polycarbonate shell engineering capabilities for premium positioning. |
| Closed-Loop Traceability Investment | Standard procurement requirements now demand supply chain visibility that separates mass-market from luxury tier positioning. |
Methodological Framework
Independent corroboration across luggage manufacturer procurement directors, airline baggage handling operations managers, and retail category buyers underwrites the qualitative findings in this study. Primary fieldwork with polymer engineers at Milan and Bavaria design studios, tannery technical directors in Tuscany, and special economic zone operations heads in Vietnam and Bangladesh combined with secondary validation from customs trade records, IATA operational bulletins, and ECHA substance restriction databases. Bottom-up SKU-level demand modeling and top-down macroeconomic triangulation anchored volume and value estimates.
Rate-of-change decomposition across the analysis window separated replacement-cycle-driven luggage demand from impulse-purchased organizational accessories. Segmentation dimensions modeled include product type, material chemistry, use case intensity, and customer behavioral archetype. CAGRs derived from trend extrapolation of airline connectivity density, regulatory implementation timelines, and material substitution curves. Forecast inputs incorporated REACH compliance cost pass-through assumptions and petrochemical price volatility bands.
Inputs from ECHA regulatory filings and IATA member carrier operational updates were available through the study window; gaps in real-time airline damage claim data introduce uncertainty bands around replacement frequency assumptions. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Travel Accessories
Italy Travel Accessories Market
Travel Accessories
Snowboard Bags Market
Travel Accessories
Amenity Kits Market
Travel Accessories
Smart Luggage Market
Travel Accessories
UK Travel Accessories Market
Travel Accessories
Backpack Systems Market
Travel Accessories
Pet Travel Bags Market
Travel Accessories
Pet Travel Accessories Market
Travel Accessories
Ergonomic Backpack for Children Market
Travel Accessories
Travel Pouches Market
Travel Accessories
India Travel Accessories Market