
 Amenity Kits Market | 2026-2036
Amenity Kits Market Size, Share, and Industry Trends Forecast 2026-2036
Amenity Kits Market Analysis
Buyer concentration among full-service carriers is expanding as Gulf and Asian airlines consolidate procurement through long-term vendor partnerships. InflightDirect leverages direct sales channels to sustain contracts with flag carriers across the Middle East. W.K. Thomas anchors European supply through manufacturing scale in hospitality amenity production. Aire Inflight differentiates via product specialization in luxury cabin configurations for premium routes.
Amenity kits are pre-assembled collections of personal care items, sleep accessories, and convenience products supplied to passengers in premium travel segments, typically packaged in branded pouches or cases with specifications for weight under 200 grams and dimensions fitting seat-back pockets. Their primary commercial purpose is to enhance passenger satisfaction scores and support airline brand positioning in competitive long-haul markets. Eco-friendly kits are gaining structural prominence as REACH and ECHA frameworks tighten material compliance requirements across European aerospace procurement. Travel kits retain volume leadership across distribution channels, though luxury kits command disproportionate margin pools in first-class and business-class deployments. Biodegradable materials are displacing conventional plastic compositions fastest in cruise line and hospitality segments where sustainability reporting pressures intensify.
The EU Green Deal and REACH frameworks in Europe, alongside FAA cabin safety standards in the United States, collectively shape material specifications and flammability testing protocols for inflight amenity contents. EMA and ECHA oversight of cosmetic ingredient safety further constrains formulation choices for skincare items included in premium kits. Stakeholders must monitor regulatory divergence between EU chemical restrictions and emerging biodegradability mandates in Asian aviation authorities to align product development roadmaps with compliance timelines.
Market Dynamics
REACH regulations and the EU Green Deal are compressing material specifications across European aviation procurement, forcing suppliers to requalify formulations and packaging substrates ahead of compliance deadlines. This regulatory pressure cascades through supply chains as airlines consolidate vendor lists to reduce certification burden.
Growth Catalysts
- Biodegradable substrate mandates:ECHA frameworks in Europe are phasing out petroleum-based plastics in cabin consumables, creating replacement demand for compostable alternatives in premium kit packaging.
- Hub carrier premiumization:Gulf airlines are retrofitting wide-body fleets with lie-flat business and first-class seats, expanding addressable passenger volumes for luxury amenity deployments.
- Cruise line sustainability reporting:Major hospitality operators are adopting biodegradable kit formats to meet Scope 3 emissions disclosure requirements under CSRD-aligned frameworks.
Market Restraints
- Raw material concentration:Specialty biopolymer supply for compliant pouches concentrates among German and Dutch chemical producers, exposing kit assemblers to input bottlenecks.
- Certification timeline friction:FAA flammability testing protocols for new textile substrates extend product qualification cycles by 8-14 months versus conventional materials.
- Airline procurement consolidation:Long-term vendor partnerships at Emirates, Qatar Airways, and Etihad reduce contract turnover frequency for mid-tier suppliers.
Strategic Opportunities
- Saudi aviation expansion:Saudia and Riyadh Air fleet growth under Vision 2030 creates greenfield demand for premium cabin suppliers without incumbent lock-in.
- Modular kit architecture:Configurable pouch systems allowing airlines to swap skincare, sleep, and wellness components by route length and passenger demographics.
- EU taxonomy-aligned procurement:Airlines qualifying for Green Deal transition financing must demonstrate sustainable supply chain practices, favoring certified biodegradable kit vendors.
Industry Challenges
- Cosmetic formulation compliance:EMA oversight of ingredient safety requires reformulation of moisturizers and cleansers to exclude restricted preservatives, complicating SKU management.
- Seat-back dimensional constraints:Evolving premium seat designs from Collins Aerospace and Safran reduce standardized pocket volumes, forcing custom kit dimensioning per airline configuration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Amenity Kits Market |
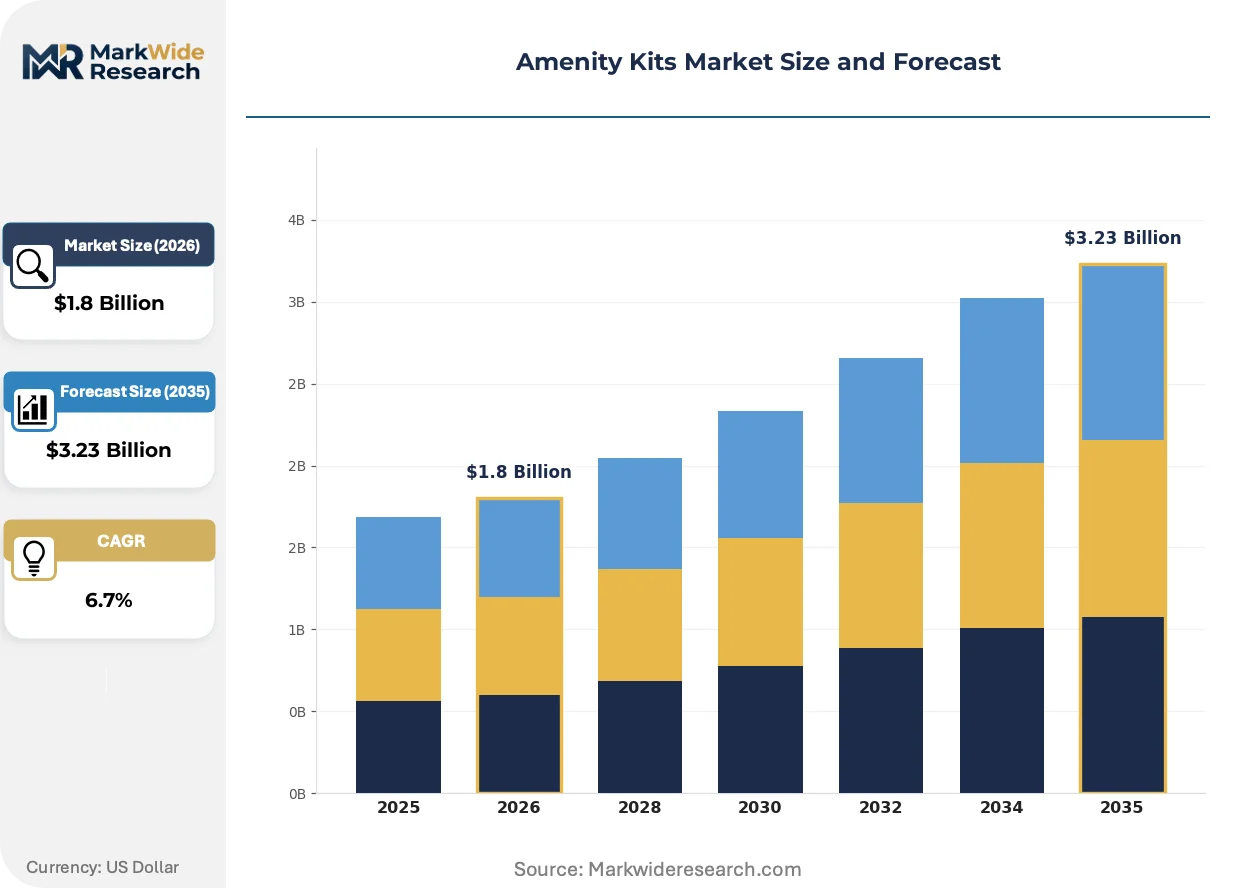
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Travel Kits, Luxury Kits, Eco-Friendly Kits, Customized Kits End User: Aerospace, Hospitality, Cruise Lines, Corporate Sector Material: Plastic, Biodegradable, Cotton, Nylon Distribution Channel: Online Retail, Brick-and-Mortar, Wholesale, Direct Sales |
| Companies Covered | Clip Ltd, InflightDirect, 4Inflight, Zibo Rainbow, AVID, Aire Inflight, W.K. Thomas, Orvec International Limited, AMKO, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Amenity Kits Market Emerging Trajectories
Material science advances and procurement digitization are restructuring how amenity kits are specified, sourced, and deployed across aviation and hospitality verticals. Three developments are altering competitive positioning.
Plant-based leather alternatives derived from agricultural waste streams are modularizing kit pouch construction. Lufthansa and Air France-KLM are piloting mycelium and pineapple-fiber cases on select long-haul routes. This substrate transition is compressing traditional synthetic leather supply contracts while opening formulation partnerships between airlines and biomaterial startups.
REACH Annex XVII restrictions on microplastics are tightening enforcement timelines for cosmetic rinse-off products included in premium kits. ECHA guidance now requires biodegradable certification for exfoliating beads and glitter components. European full-service carriers are responding by removing non-compliant items entirely or substituting with mineral-based alternatives ahead of 2027 deadlines.
Direct airline-vendor digital procurement platforms are displacing traditional hospitality distributors for recurring kit contracts. Emirates and Singapore Airlines now manage specification changes, quality audits, and replenishment scheduling through proprietary supplier portals. This channel shift is most advanced in the Middle East, where hub carriers have invested in procurement technology infrastructure to reduce administrative overhead on high-volume consumables.
Amenity Kits Market Segmentation
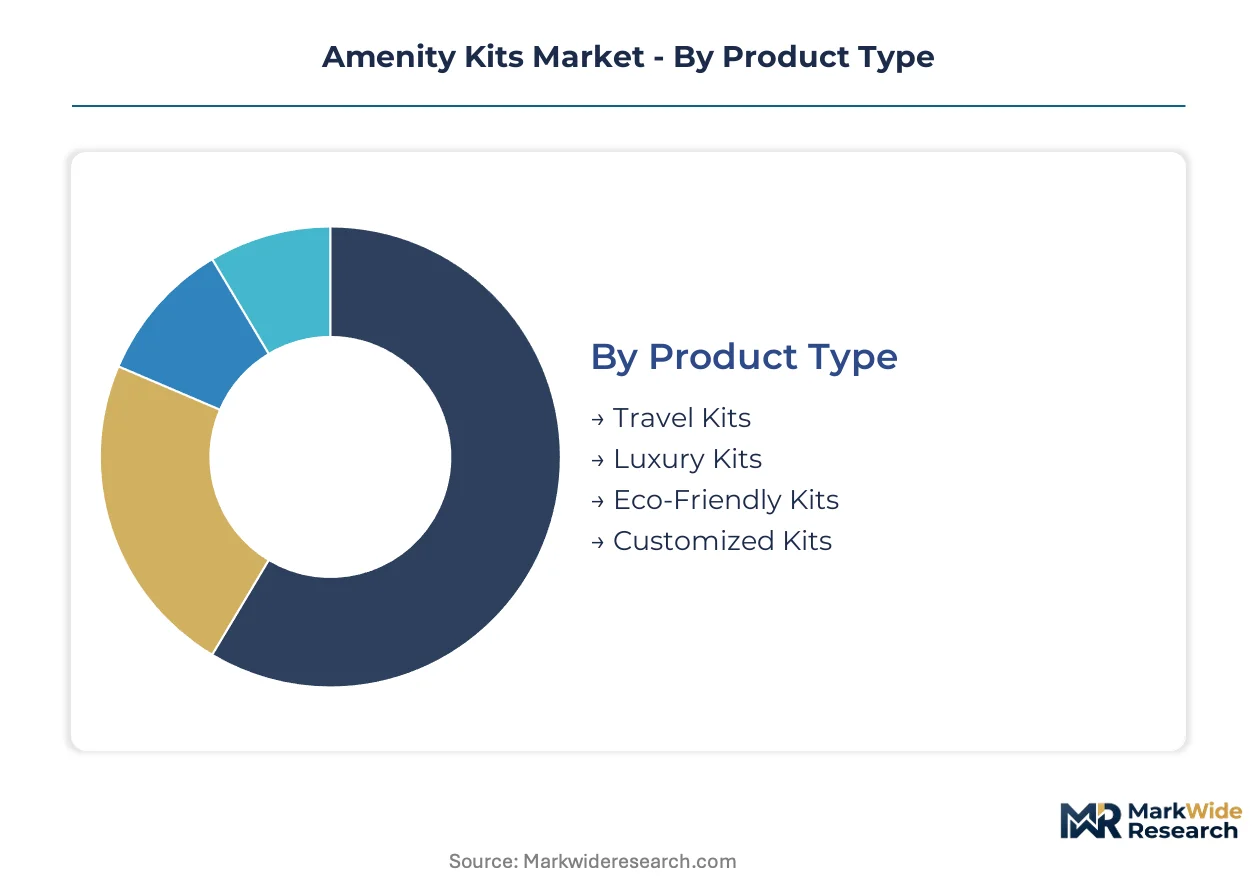
Amenity kit suppliers face divergent specification requirements across aviation, hospitality, and cruise verticals. Segmentation reveals where material compliance costs concentrate versus where customization premiums justify higher unit economics.
Product Type:
Travel kits function as standalone consumables distributed per passenger, while luxury and eco-friendly variants embed deeper into airline brand architecture and regulatory compliance systems.
- Travel Kits:Standardized assemblies containing dental kits, eye masks, and earplugs in synthetic pouches. Demand concentrates in Asia-Pacific full-service carriers retrofitting narrow-body fleets for regional routes where passenger volume offsets thinner margins.
- Luxury Kits:Curated collections featuring branded skincare, premium textiles, and collectible cases exceeding 150 grams. Emirates and Qatar Airways deploy these on ultra-long-haul segments where passenger experience differentiation drives yield management.
- Eco-Friendly Kits:Compostable pouches and refillable containers meeting ECHA biodegradability thresholds.
- Customized Kits:Route-specific configurations swapping contents by flight duration or destination.
Travel kits lead volumes today; eco-friendly kits are gaining share fastest as REACH enforcement tightens.
End User:
Cost tiers separate capital-intensive aerospace procurement from hospitality's volume-driven replenishment cycles.
- Aerospace:Long-term vendor contracts with technical qualification requirements for flammability testing and weight restrictions. Airlines in the United Arab Emirates and Saudi Arabia anchor demand through fleet expansion programs.
- Hospitality:Bulk purchasing of standardized kits for guest room replenishment with minimal customization.
- Cruise Lines:Sustainability reporting pressures under CSRD-aligned frameworks drive biodegradable kit adoption faster than aviation.
- Corporate Sector:Branded kits for executive travel programs and client gifting with logo customization requirements.
Aerospace dominates revenue concentration; cruise lines show the steepest expansion trajectory on sustainability mandates.
Material:
Supply concentration in German and Dutch biopolymer producers shapes procurement risk profiles across material categories.
- Plastic:Petroleum-based pouches and containers facing phase-out under EU Green Deal timelines. Legacy contracts at budget carriers sustain residual demand.
- Biodegradable:Polylactic acid and mycelium-derived substrates certified under industrial composting standards. REACH Annex XVII restrictions on microplastics accelerate substitution rates.
- Cotton:Organic textile pouches favored by European carriers for tactile premium positioning.
- Nylon:Durable synthetic fabrics retained for crew kits and reusable case applications.
Plastic still accounts for the largest installed base; biodegradable alternatives are climbing the fastest on regulatory pressure.
Distribution Channel:
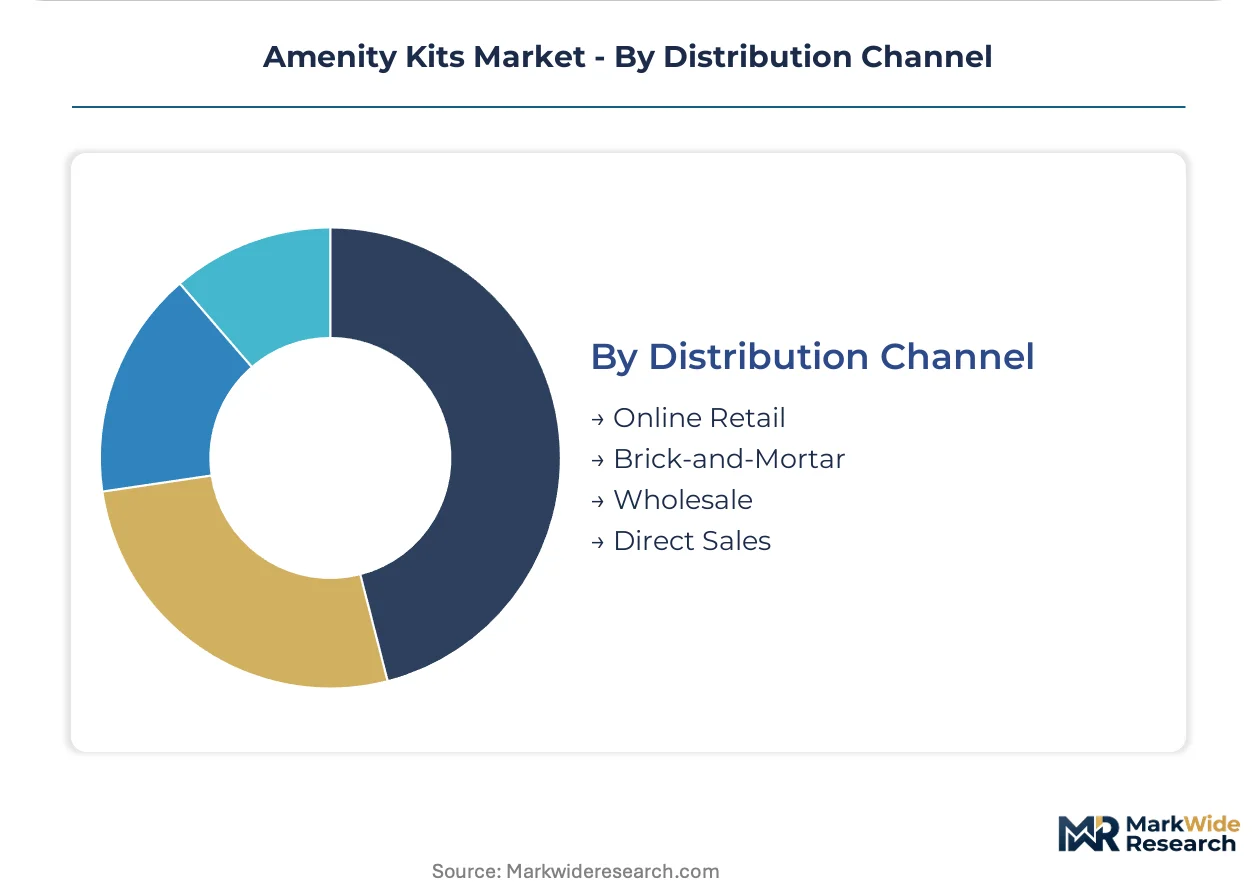
Customer type segmentation separates institutional procurement from fragmented retail and individual purchasing patterns.
- Online Retail:Direct-to-consumer sales of branded surplus and travel accessory bundles. Growth concentrates in post-pandemic leisure travel recovery segments.
- Brick-and-Mortar:Airport duty-free and hospitality supply showrooms serving last-minute procurement needs.
- Wholesale:Distributor-mediated bulk sales to mid-tier hotel chains and regional airlines without direct vendor relationships.
- Direct Sales:Airline proprietary portals managing specification changes, quality audits, and replenishment scheduling without intermediary markup.
Direct sales channels are expanding most quickly as Emirates and Singapore Airlines invest in procurement technology infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States and Germany diverge sharply in amenity kit procurement intensity, with American carriers prioritizing cost-standardized assemblies while German airlines accelerate biodegradable material transitions under REACH pressure. This regulatory asymmetry fragments supplier qualification requirements across transatlantic routes.
United States
Delta Air Lines and United Airlines drive demand for lightweight, standardized kits on domestic and transcontinental routes. FAA flammability testing protocols govern textile substrate approvals, extending qualification cycles for innovative materials. Manufacturing clusters concentrate in Georgia and North Carolina, where textile converters supply nylon and cotton pouch assemblies to airline procurement hubs in Atlanta.
Germany
Lufthansa Group mandates REACH-compliant biodegradable pouches across European short-haul and long-haul fleets. ECHA restrictions on microplastics in cosmetic components force reformulation of skincare items by 2027. Industrial activity clusters in North Rhine-Westphalia, where chemical producers supply polylactic acid substrates to kit assemblers serving Frankfurt and Munich hub operations.
United Arab Emirates
Emirates and Etihad Airways anchor premium cabin retrofit programs, expanding luxury kit deployments on A380 and 777 fleets. MOHAP cosmetic safety standards align with EMA frameworks for ingredient transparency. Dubai International Airport's free zone hosts consolidation warehouses where vendors stage customized kit configurations for rapid fleet replenishment.
Saudi Arabia
Saudia and Riyadh Air fleet expansion under Vision 2030 creates greenfield procurement opportunities without incumbent vendor lock-in. SFDA regulates cosmetic contents for passenger kits on international routes. Jeddah and Riyadh emerge as procurement coordination centers, with Red Sea tourism projects extending kit demand into hospitality verticals.
Japan
ANA and JAL maintain stringent weight restrictions under METI energy efficiency guidelines for cabin consumables. JIS standards govern textile durability and chemical content in premium kit assemblies. Osaka-based manufacturers specialize in compact, multi-functional pouch designs optimized for narrow-body premium cabin seat-back constraints.
Amenity Kits Market Vendor Landscape
Middle Eastern producers anchor the premium tier through direct airline partnerships; European specialists hold compliance-driven positions in biodegradable material transitions. Market structure concentrates around long-term vendor contracts at Gulf carriers, compressing turnover frequency for mid-tier entrants. Three archetypes dominate: direct-sales integrators serving flag carriers, manufacturing-scale suppliers anchoring hospitality volume, and product specialists targeting luxury cabin configurations. Consolidation proceeds through strategic partnerships rather than acquisition, as airlines reduce vendor lists to streamline certification burden.
Within the direct-sales integrator tier, InflightDirect and Aire Inflight exemplify positioning through airline portal relationships and premium route specialization respectively. W.K. Thomas occupies a manufacturing-scale position anchored in European hospitality supply. These three entities represent divergent competitive vectors: procurement technology integration, luxury cabin product depth, and production volume efficiency.
| Leading Market Players |
|---|
| Clip Ltd |
| InflightDirect |
| 4Inflight |
| Zibo Rainbow |
| AVID |
| Aire Inflight |
| W.K. Thomas |
| Orvec International Limited |
| AMKO |
| Others |
Supply Flow & Price Mechanics
Polylactic acid resin price indices from German chemical producers cascade through three-tier pricing structures across premium, standard, and economy levels in the Amenity Kits Market. REACH compliance costs concentrate in biodegradable substrate tiers while petroleum-based legacy materials face margin compression from regulatory phase-out timelines.
Pricing Analysis
Capacity additions in Saudi Arabia are reshaping price floors for premium cabin configurations as Vision 2030 fleet expansion creates greenfield procurement without incumbent vendor lock-in. Pricing stratifies across premium, standard, and economy tiers based on certification grade under ECHA biodegradability thresholds and customization level for airline-specific branding. Cost compression in standard travel kits is intensifying because Asian carriers are consolidating procurement through long-term vendor partnerships. Budget carriers exhibit highest price sensitivity while Gulf flag carriers prioritize passenger experience differentiation over unit cost.
Supply Chain Analysis
Skilled textile assembly labor availability in Bangladesh and Vietnam shapes pouch manufacturing economics for mid-tier kit suppliers serving hospitality volume contracts. Raw material sourcing draws from German polylactic acid producers, Dutch mycelium substrate specialists, and Chinese nylon converters for crew kit applications. Single-source vulnerability concentrates in European biopolymer supply where REACH Annex XVII restrictions outpace alternative certification capacity. Distribution runs through direct airline vendor portals in the Middle East and wholesale distributor networks for regional hotel chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
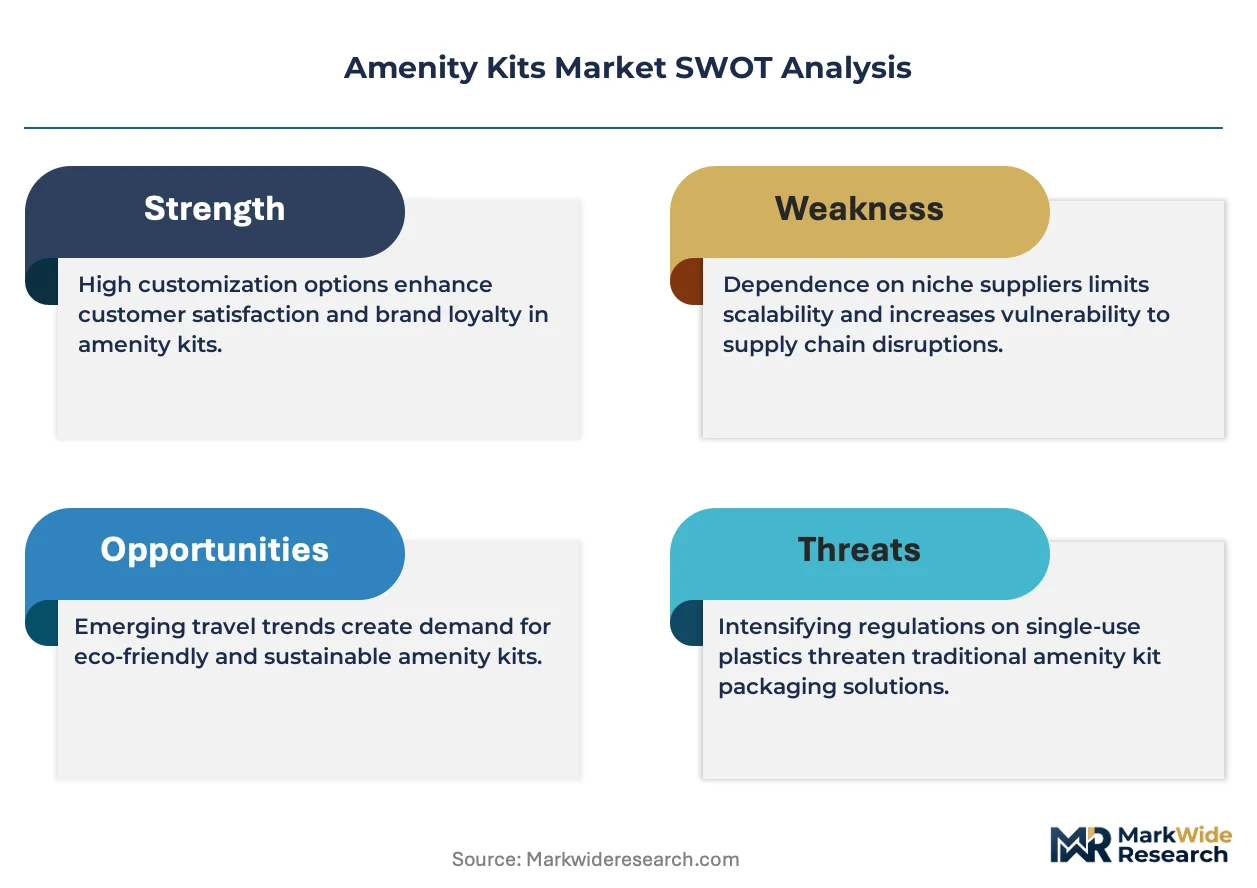
The Amenity Kits Market represents a late-cycle quality story as Gulf carriers retrofit wide-body fleets with lie-flat premium cabins, shifting procurement specifications toward weight-optimized luxury configurations with branded collectible cases.
For Market Incumbents: Acquire specialized biomaterial formulation capabilities to defend against REACH-driven substrate substitution timelines. Consolidate vendor qualification relationships with Emirates, Qatar Airways, and Etihad before Saudi aviation expansion creates alternative supplier pathways. ECHA microplastic restrictions threaten skincare item portfolios requiring rapid reformulation investment.
For New Entrants and Emerging Players: Modular kit architecture enabling route-specific component swapping offers entry into mid-tier carrier contracts without full qualification burden. Target Saudi Arabia's greenfield procurement environment where Riyadh Air and Saudia lack incumbent vendor lock-in. Deploy direct digital procurement platforms to bypass traditional hospitality distributor markups.
For Investors and Strategic Acquirers: Asymmetric upside sits with European biodegradable substrate specialists holding ECHA-certified compostable pouch production. Long-term viability hinges on regulatory enforcement continuity across EU Green Deal implementation phases. Monitor FAA flammability testing protocol revisions as signal for innovative textile substrate adoption inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Biomaterial Certification Investment | ECHA-compliant compostable substrates unlock EU airline procurement under REACH Annex XVII timelines. |
| Direct Airline Portal Integration | Emirates and Singapore Airlines proprietary supplier systems reduce administrative overhead on high-volume replenishment. |
| Saudi Market Entry Partnership | Vision 2030 fleet expansion at Saudia and Riyadh Air creates vendor relationships without legacy contract encumbrance. |
| Modular Kit Architecture Development | Configurable pouch systems allow airlines to customize contents by flight duration and passenger demographics. |
| Cosmetic Formulation Reformulation | EMA oversight of restricted preservatives requires SKU redesign ahead of 2027 compliance deadlines. |
Methodological Framework
Bottom-up airline procurement modeling reconciled against top-down biopolymer supply tracking forms the analytical core of this study. Primary interviews with airline procurement directors, amenity kit product managers, hospitality supply chain executives, and ECHA regulatory compliance officers combined with secondary validation from customs trade data, REACH Annex XVII filings, airline sustainability reports, and hospitality procurement databases. Triangulation between passenger volume forecasts and material substitution rates anchors volume projections.
Input-output matrices map polylactic acid substrate availability against premium cabin retrofit schedules across the analysis window. Segmentation dimensions modeled include kit type, end-use vertical, material substrate, and distribution channel complexity. CAGRs derive from weighted average of airline fleet expansion trajectories and regulatory compliance timeline enforcement. Forecast inputs incorporate ECHA biodegradability certification adoption curves and FAA flammability testing protocol revision schedules.
The model holds under sustained REACH enforcement and Gulf carrier premiumization investment; deviation in biopolymer supply bottlenecks or Saudi procurement timeline acceleration would shift trajectory assumptions. Forecasts reflect documented assumptions about regulatory continuity and airline passenger experience differentiation priorities. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Travel Accessories
Smart Luggage Market
Travel Accessories
Ergonomic Backpack for Children Market
Travel Accessories
Pet Travel Bags Market
Travel Accessories
Italy Travel Accessories Market
Travel Accessories
India Travel Accessories Market
Travel Accessories
Backpack Systems Market
Travel Accessories
Pet Travel Accessories Market
Travel Accessories
UK Travel Accessories Market
Travel Accessories
Travel Pouches Market
Travel Accessories
Snowboard Bags Market
Travel Accessories
Travel Accessories Market