
 Italy Travel Accessories Market | 2026-2036
Italy Travel Accessories Market Size, Share, and Industry Trends Forecast 2026-2036
Italy Travel Accessories Market Insights
Artisan leatherworking capacity across Tuscany and Veneto is unwinding a decades-long supply bottleneck for premium travel goods. Samsonite International S.A. leverages its global distribution network to sustain volume leadership in hardside luggage. BRIC'S S.p.A. anchors its competitive position through handcrafted leather collections manufactured in the Bergamo region. Piquadro S.p.A. specializes in business-travel accessories with integrated device compartments, occupying a distinct niche against mass-market competitors.
Italy travel accessories encompass portable goods engineered for transit convenience, including wheeled luggage with polycarbonate shells rated to withstand impact forces, ergonomic backpacks with padded laptop sleeves, and compression-molded travel pillows using viscoelastic foam. These products serve transit protection, organization, and comfort functions for mobile consumers. Luggage commands the dominant revenue share due to replacement cycles and airline size restrictions, while packing cubes represent the fastest-expanding category as travelers prioritize modular organization. Leather material grades command premium pricing through association with Florentine tannery traditions, whereas polyester variants compete on durability-to-weight ratios for budget-conscious segments.
EU REACH regulations restrict chemical inputs in textile and leather treatments, compelling reformulation of dyes and coatings across Italian manufacturing. CE marking requirements govern product safety for electrical accessories such as USB-integrated luggage, while the EU Green Deal pressures brands to document recycled content percentages and carbon footprints. Stakeholders must monitor evolving Ecodesign criteria and packaging waste directives that will reshape material sourcing decisions and compliance costs without explicit phase-in timelines.
Market Dynamics
REACH compliance and the EU Green Deal are forcing Italian manufacturers to requalify suppliers and reformulate material treatments, compressing margins while opening premium positioning for certified heritage producers.
Growth Catalysts
- EU Green Deal material mandates:Documentation requirements for recycled content and carbon footprints are rewarding early adopters with preferred supplier status among Milan fashion houses.
- Leather craft heritage clusters:Concentrated artisan capacity in Tuscany and Veneto is unlocking made-in-Italy certification premiums that polyester competitors cannot replicate.
- Airline size restrictions:Tightened carry-on enforcement by European carriers is compressing replacement cycles for compliant hardside luggage.
Market Restraints
- Petrochemical input volatility:Polycarbonate shell production faces margin pressure from naphtha derivative cost swings, squeezing budget luggage manufacturers.
- Supplier concentration risk:Florentine tannery capacity limits constrain premium leather goods expansion, creating order backlogs for heritage brands.
- REACH chemical reformulation:Restricted dye and coating chemistries force R&D redirection, delaying new collection launches by 8-14 months.
Strategic Opportunities
- Southern Italy tourism corridor:Underdeveloped retail infrastructure in Puglia and Sicily offers first-mover positioning for experiential luggage boutiques.
- USB-integrated luggage:CE-marked power delivery systems are converging with smart tracking modules to create business-traveler loyalty lock-in.
- Ecodesign packaging directives:Anticipated waste regulations will favor domestic suppliers with short-loop recycling networks over Asian competitors.
Industry Challenges
- Artisan skill attrition:Aging master leatherworkers in Bergamo and Florence lack apprenticeship pipeline depth, threatening handcrafted collection consistency.
- Dual certification timelines:Parallel CE marking for electronics and REACH material compliance creates product development bottlenecks without unified approval pathways.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Italy Travel Accessories Market |
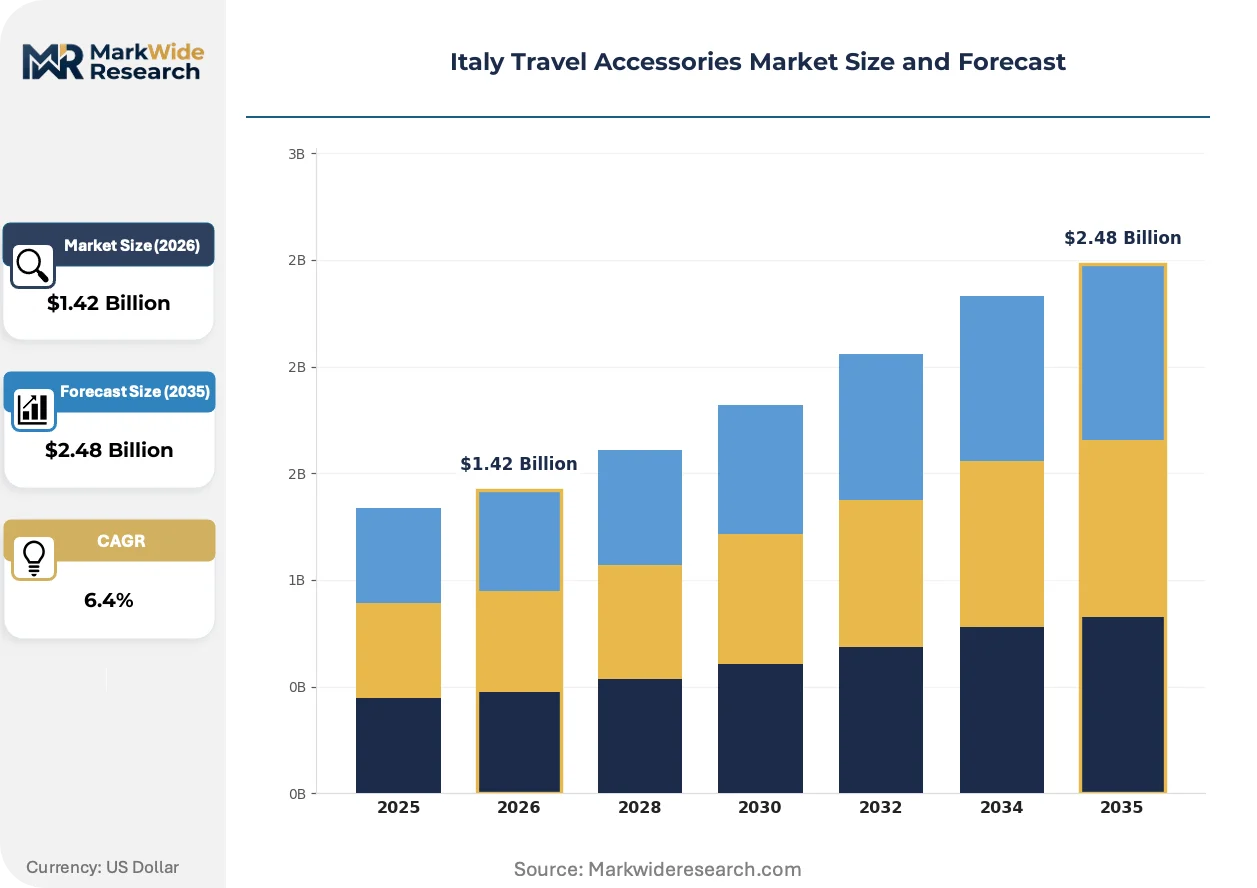
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.48 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Luggage, Backpacks, Travel Pillows, Packing Cubes Material: Nylon, Leather, Polyester, Canvas End User: Business Travelers, Tourists, Backpackers, Families Distribution Channel: Online Retail, Department Stores, Specialty Shops, Airports |
| Companies Covered | Samsonite International S.A., Delsey Paris, Rimowa GmbH, LVMH Moët Hennessy Louis Vuitton SE, Piquadro S.p.A., Mandarina Duck, BRIC'S S.p.A., Valigeria Roncato S.p.A., Travelpro, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
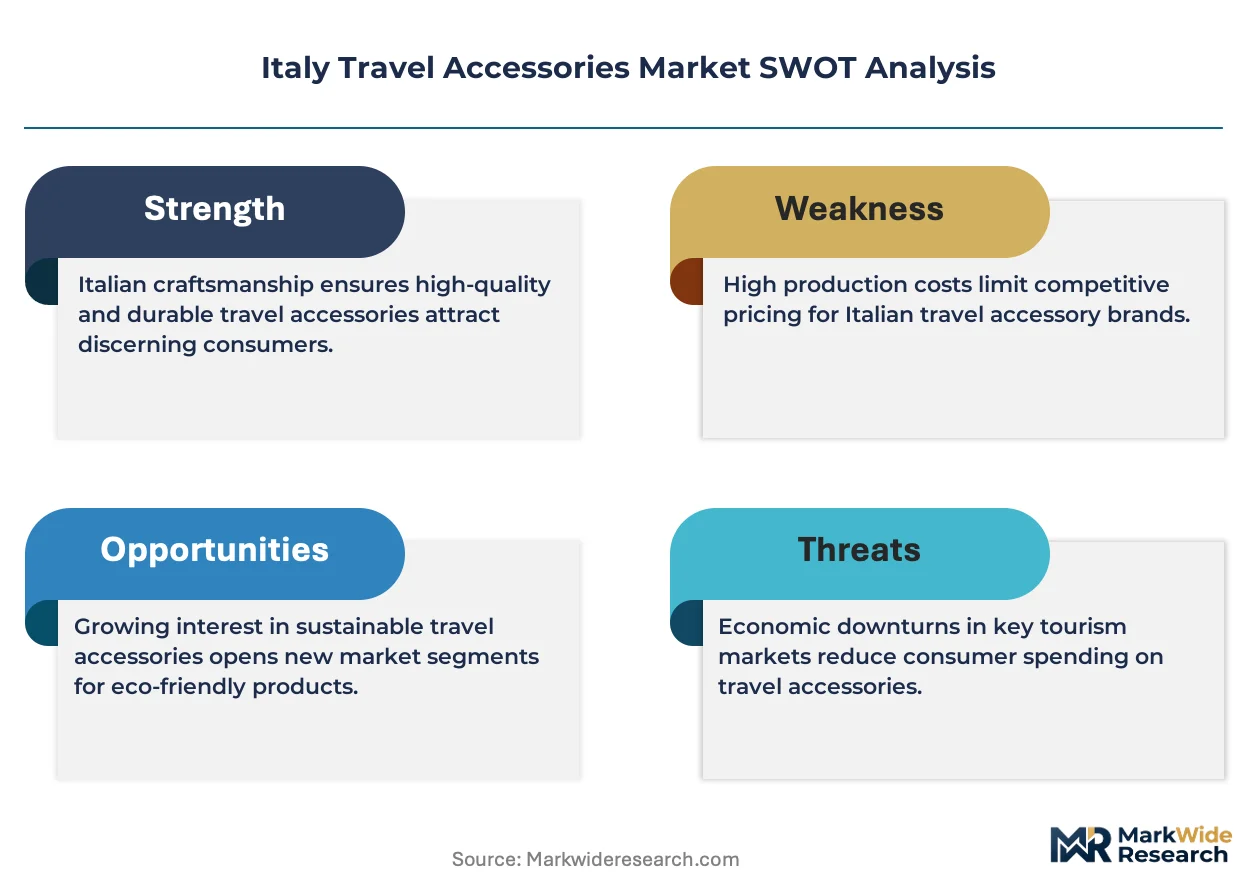
Italy Travel Accessories Market Trends and Innovations
Smart connectivity and sustainable material science are compressing product development cycles while fragmenting buyer expectations across convenience, heritage, and environmental performance dimensions.
Embedded tracking modules using ultra-wideband chips are miniaturizing to sub-5 gram form factors without antenna protrusion. Business-traveler segments in Rome and Milan are adopting these at twice the rate of leisure buyers. This density reduction is miniaturizing the distinction between smart luggage and conventional hardside shells, forcing mid-tier brands to source modules or exit the segment.
REACH Annex XVII restrictions on chromium VI in leather tanning entered full enforcement across Italian manufacturing. Tanneries in Santa Croce sull'Arno and Arzignano are converting to vegetable-tanning or synthetic polymer alternatives at capital cost premiums of 15-25 percent. Premium luggage collections bearing ZDHC certification are capturing shelf space from uncertified competitors in Milan's fashion district.
Direct-to-consumer configuration tools now allow travelers to specify interior compartment layouts before manufacturing. This build-to-order channel is displacing wholesale pre-production for heritage brands with domestic manufacturing flexibility. The shift is most visible among corporate gifting programs in Turin and Bologna, where volume buyers demand co-branded hardware without inventory risk.
Italy Travel Accessories Market Segmentation
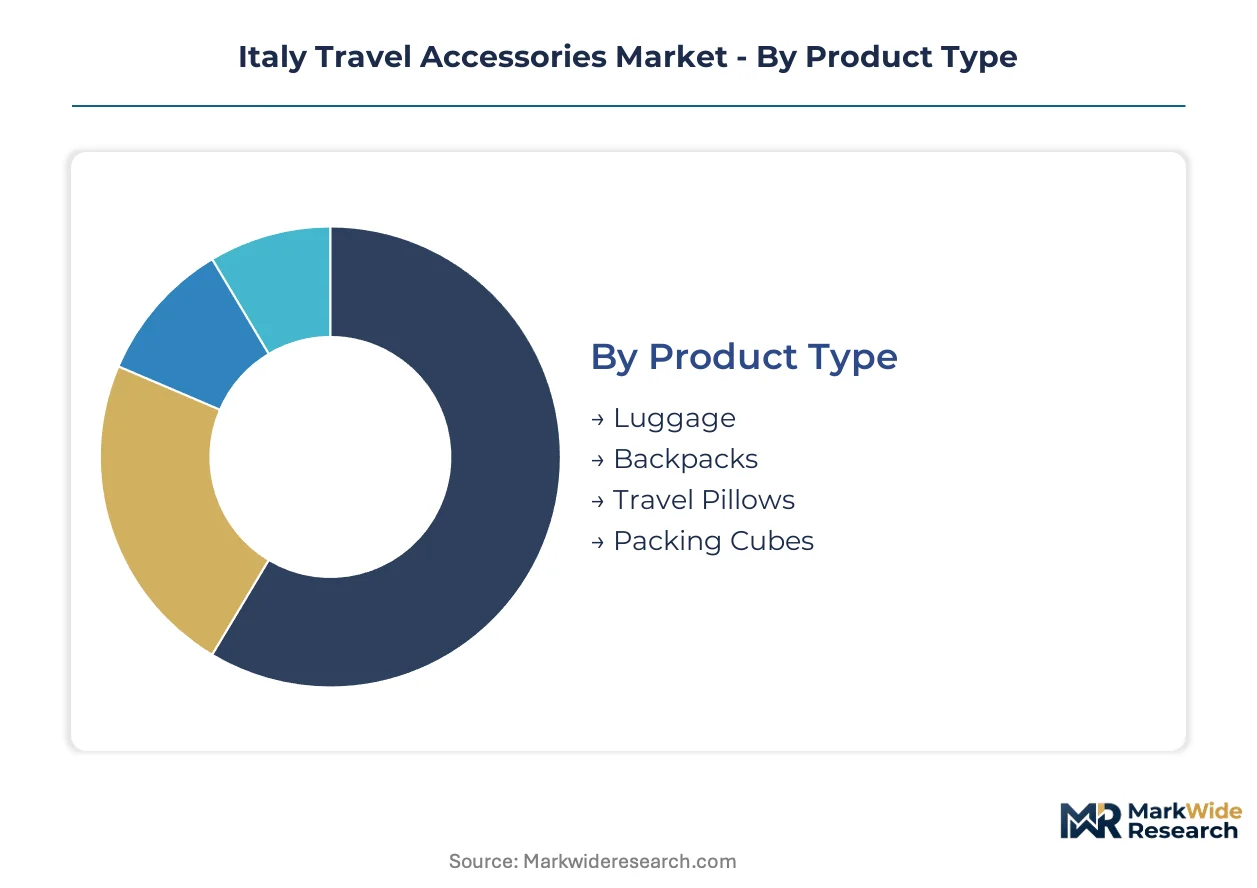
Segmentation in the Italy travel accessories market reveals distinct compliance and positioning pathways. REACH certification requirements and EU Green Deal documentation standards create divergent margin structures across material grades and distribution channels.
Product Type:
REACH chemical restrictions and airline dimension enforcement reshape replacement cycles differently across functional categories.
- Luggage:Polycarbonate and ABS hardside shells rated to withstand impact forces dominate Milan fashion district retail. Replacement demand concentrates among business travelers navigating tightened carry-on enforcement by ITA Airways and Ryanair.
- Backpacks:Ergonomic designs with padded laptop sleeves and hidden anti-theft compartments serve commuter-to-traveler crossover use. Demand clusters in Rome's tourism corridor and Turin corporate gifting programs where device protection is non-negotiable.
- Travel Pillows:Viscoelastic foam and inflatable variants address comfort during transit.
- Packing Cubes:Modular organization systems are expanding most quickly among leisure travelers prioritizing efficient baggage arrangement.
Established volume favors Luggage; emerging adoption favors Packing Cubes.
Material:
Cost tier differentiation separates certified heritage producers from volume competitors.
- Leather:Full-grain and top-grain grades from Florentine tanneries command certification premiums through ZDHC and made-in-Italy labeling. Santa Croce sull'Arno vegetable-tanning conversions at 15-25 percent capital cost premiums constrain supply.
- Polyester:Denier-rated ballistic weaves compete on durability-to-weight ratios for budget positioning. Bergamo region manufacturers source this material for hardside luggage shells facing petrochemical input volatility.
- Nylon:Cordura and ripstop weaves balance abrasion resistance with weight reduction for technical backpacks.
- Canvas:Waxed cotton variants appeal to heritage aesthetic segments in Venice and Bologna boutique channels.
Margin concentration favors Leather; volume scale favors Polyester.
End User:
Application intensity determines feature integration depth and price realization.
- Business Travelers:USB-integrated luggage with CE-marked power delivery and ultra-wideband tracking modules lock in loyalty through convenience stacking. Milan and Rome corporate accounts drive specification requirements.
- Tourists:Leisure buyers prioritize weight compliance and aesthetic differentiation for social documentation. Demand concentrates in Florence and Venice heritage retail corridors.
- Backpackers:Durability-to-cost optimization dominates purchase criteria for extended transit.
- Families:Multi-piece sets with coordinated organization systems address group travel complexity.
Specification intensity favors Business Travelers; unit volume favors Tourists.
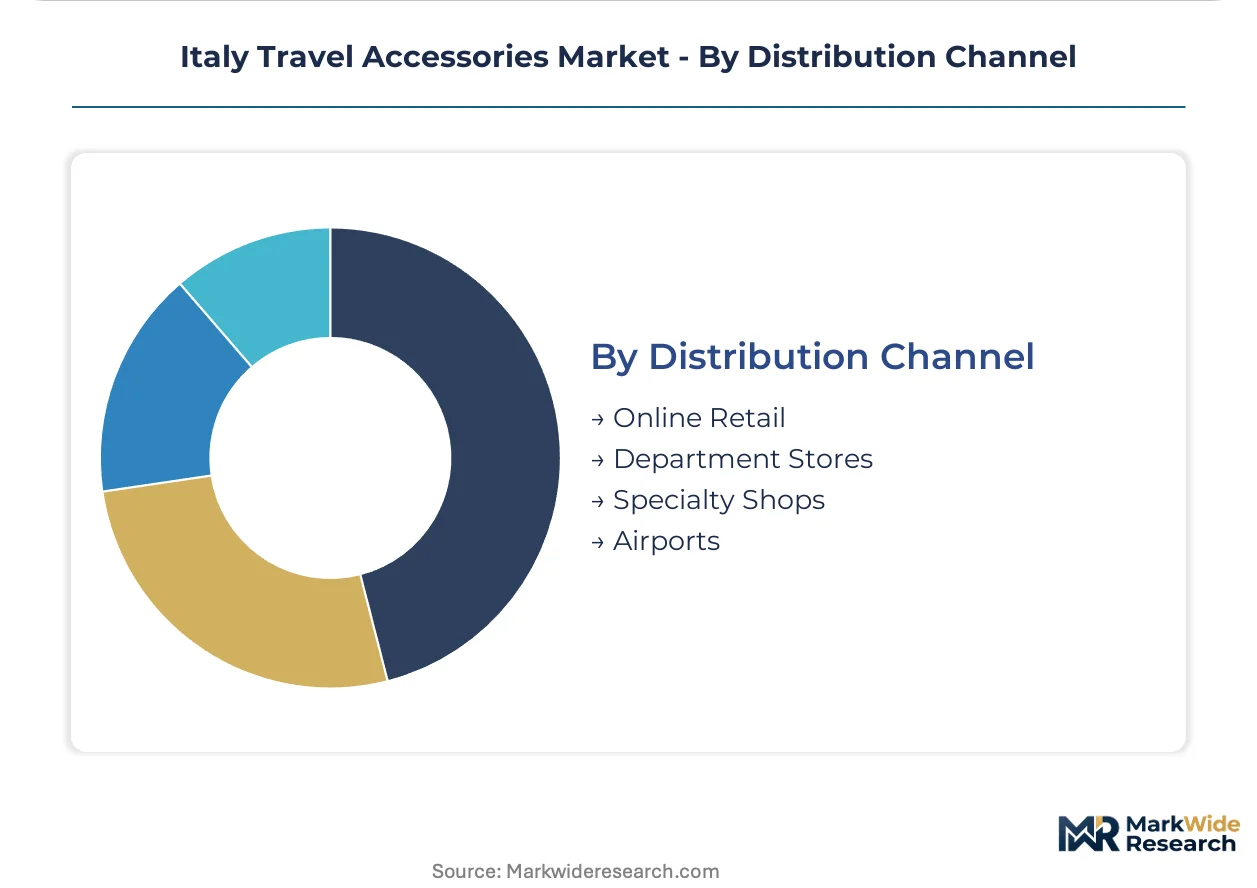
Distribution Channel:
Geography of demand concentration shapes channel investment priority.
- Specialty Shops:Tuscany and Veneto artisan ateliers with direct leatherworking visibility capture certification storytelling premiums. Bergamo region BRIC'S manufacturing tours reinforce purchase validation.
- Online Retail:Direct-to-consumer configuration tools for build-to-order interior layouts displace wholesale pre-production. Turin and Bologna corporate gifting programs leverage this channel for co-branded hardware.
- Department Stores:Milan fashion district flagship locations anchor brand positioning for heritage collections.
- Airports:Last-minute replacement and upgrade purchases concentrate at Fiumicino and Malpensa duty-free zones.
Margin realization favors Specialty Shops; customer acquisition efficiency favors Online Retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns across Italian sub-regions diverge sharply between heritage-driven Milan fashion district purchases and utility-focused Rome tourism corridor demand.
Lombardy
Milan's fashion district concentrates premium luggage demand among corporate buyers seeking USB-integrated hardside shells with CE-marked power delivery. The EU Green Deal's recycled content documentation requirements favor local manufacturers with short-loop supply chains. Bergamo region tanneries and BRIC'S manufacturing facilities anchor artisan production clusters serving luxury retail flagships.
Lazio
Rome's tourism corridor drives volume demand for lightweight polycarbonate luggage compliant with tightened ITA Airways carry-on restrictions. REACH Annex XVII chemical restrictions reshape supplier qualification for textile treatments across Fiumicino airport duty-free retail. The capital's experiential retail boutiques emphasize made-in-Italy certification storytelling for leather accessories.
Veneto
Arzignano tanning district conversions to vegetable-based processes at 15-25 percent capital cost premiums constrain premium leather goods supply. Business travelers in Venice and Verona prioritize anti-theft backpack features for commuter-to-tourism crossover use. Regional artisan capacity unwinds decades-long supply bottlenecks for heritage brands.
Tuscany
Santa Croce sull'Arno tanneries convert chromium VI processes under full REACH enforcement, capturing ZDHC certification premiums in Florence heritage retail corridors. Leisure buyers prioritize aesthetic differentiation for social documentation over technical specifications. Direct-to-consumer configuration tools displace wholesale pre-production for domestic manufacturing-flexible brands.
Piedmont
Turin corporate gifting programs leverage build-to-order channels for co-branded hardware without inventory risk. The sub-region's automotive heritage influences demand for precision-engineered polycarbonate shells with impact resistance ratings. Underdeveloped experiential retail infrastructure creates first-mover positioning opportunities for domestic heritage brands.
Italy Travel Accessories Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with volume-scale hardside manufacturers commanding distribution density while artisan leather houses capture certification premiums. The competitive terrain splits between heritage craft positioning and technical performance differentiation. Two strategic archetypes dominate: global luggage conglomerates leveraging manufacturing scale, and domestic leather specialists exploiting regional craft credibility. Consolidation pressure favors M&A activity among mid-tier polycarbonate shell producers, while strategic partnerships between tanneries and finished goods brands secure constrained raw material access.
Among Italy-based specialists, BRIC'S S.p.A. and Piquadro S.p.A. occupy positions within the domestic heritage tier, exemplifying divergent specialization vectors—handcrafted leather collections versus business-travel accessory integration. Samsonite International S.A. represents the scale-driven archetype with global distribution network density. These three entities anchor the competitive spectrum from artisan certification premiums to volume manufacturing efficiency.
| Leading Market Players |
|---|
| Samsonite International S.A. |
| Delsey Paris |
| Rimowa GmbH |
| LVMH Moët Hennessy Louis Vuitton SE |
| Piquadro S.p.A. |
| Mandarina Duck |
| BRIC'S S.p.A. |
| Valigeria Roncato S.p.A. |
| Travelpro |
| Others |
Pricing and Supply Chain Analysis
Polycarbonate shell manufacturing scale in Bergamo and Veneto establishes minimum efficient scale thresholds that compress price floors for mid-tier hardside luggage while amplifying margin capture for heritage leather producers with constrained Florentine tannery access.
Pricing Analysis
Long-term offtake contracts between Milan fashion houses and Santa Croce sull'Arno tanneries lock in vegetable-tanned leather supply at 15-25 percent premiums over spot-market chromium alternatives. Three-tier pricing structure across ZDHC-certified heritage, standard compliance, and uncertified economy tiers separates Florentine artisan collections from polyester competitors. Cost compression in polycarbonate shells intensifies because naphtha derivative volatility erodes budget manufacturer margins. Business travelers purchasing USB-integrated luggage demonstrate lowest price sensitivity; backpackers optimizing durability-to-cost ratios anchor the most elastic demand segment.
Supply Chain Analysis
Just-in-time inventory strategies dominate Milan fashion district retail, whereas strategic stockpiling of full-grain hides buffers Santa Croce sull'Arno tanneries against REACH reformulation delays. Manufacturing concentrates in Italy, China, and Vietnam, with Italian facilities capturing certification premiums and Asian plants supplying volume polycarbonate shell production. Raw material dependencies center on petroleum-derived polycarbonate resins, chromium-free tanning agents, and ultra-wideband tracking chipsets. Single-source vulnerability in Florentine vegetable-tanning capacity creates order backlogs for heritage brands. Distribution runs through specialty ateliers in Tuscany, department store flagships in Milan, and direct-to-consumer configuration platforms serving Turin corporate gifting programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Italy travel accessories is exiting a regulatory-driven investment cycle as REACH enforcement stabilizes and airline carry-on standardization compresses replacement demand into predictable refresh intervals.
For Market Incumbents: Compound certification advantages by securing exclusive offtake from converting Arzignano tanneries before vegetable-tanning capacity saturates. Defend margin position against mid-tier polycarbonate erosion through backward integration into recycled content supply chains that satisfy EU Green Deal documentation requirements.
For New Entrants and Emerging Players: Anchor in Puglia and Sicily experiential retail corridors where heritage brand presence remains underdeveloped. Target southern Italy tourism infrastructure gaps with build-to-order luggage boutiques that combine direct leatherworking visibility with digital configuration tools.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors domestic manufacturers with captive tannery relationships and CE-marking capabilities for integrated electronics. Long-term viability rests on defensible artisan capacity rather than scale-driven polycarbonate production. Monitor ZDHC certification penetration rates in Milan fashion district shelf space as inflection indicator for premium leather goods demand trajectory.
| Strategic Initiative | Industry Significance |
|---|---|
| Vegetable-Tanning Capacity Conversion | Arzignano tanneries converting chromium processes capture REACH-compliant supply premiums. |
| Direct-to-Consumer Configuration Platform | Turin corporate gifting programs leverage build-to-order channels eliminating inventory risk. |
| USB-Integrated Luggage Development | CE-marked power delivery systems create business-traveler loyalty lock-in against mass competitors. |
| Southern Italy Retail Expansion | Puglia and Sicily experiential boutiques exploit underdeveloped heritage brand infrastructure. |
| ZDHC Certification Investment | Florentine tanneries with restricted substance certification displace uncertified competitors. |
Research Methodology
Cross-validation between primary interviews with leatherworking artisans, procurement leads at Milan fashion houses, and regulatory compliance officers anchors the qualitative findings against secondary validation from ECHA REACH guidance documents, EU Green Deal implementation timelines, and Italian customs trade data. Bottom-up triangulation across tannery capacity surveys and top-down reconciliation with retail channel audits ensures segment-level consistency.
Sensitivity analysis around petrochemical input volatility and artisan skill attrition rates stress-tests volume and value outputs across the projection horizon. Segmentation dimensions modeled include product type, material certification tier, end-user application intensity, and distribution channel geography. CAGRs derive from replacement cycle analysis calibrated to airline enforcement patterns and REACH compliance phase-in schedules.
Decision-makers should treat outputs as directional under stable regulatory enforcement and continued EU Green Deal material mandate progression; material deviation in tannery conversion timelines or airline dimension standardization would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Travel Accessories
Pet Travel Accessories Market
Travel Accessories
Travel Accessories Market
Travel Accessories
Amenity Kits Market
Travel Accessories
Backpack Systems Market
Travel Accessories
India Travel Accessories Market
Travel Accessories
Pet Travel Bags Market
Travel Accessories
Snowboard Bags Market
Travel Accessories
Travel Pouches Market
Travel Accessories
Smart Luggage Market
Travel Accessories
UK Travel Accessories Market
Travel Accessories
Ergonomic Backpack for Children Market