
 Retail Ready Packaging (RRP) Market | 2026-2036
Retail Ready Packaging (RRP) Market Size, Share, and Industry Trends Forecast 2026-2036
Retail Ready Packaging (RRP) Market Analytics
The EU Packaging and Packaging Waste Regulation is repositioning compliance costs for RRP suppliers entering European retail channels. Smurfit Kappa leverages its integrated corrugated network across 35 countries to preempt fiber sourcing constraints. Mondi Group anchors its competitive stance through specialty kraft paper innovations that reduce plastic dependency in shelf-ready trays. WestRock sustains North American market presence via automated converting capacity tied to club-store pallet display contracts.
Retail ready packaging denotes secondary packaging engineered for direct shelf placement without repacking, typically constructed from corrugated fiberboard with die-cut perforations for easy opening and barcode visibility. The format eliminates labor-intensive stocking steps between warehouse arrival and consumer-facing display. Corrugated fiberboard dominates material selection due to crush resistance and printability, though biodegradable materials are gaining traction as grocers face Scope 3 emissions scrutiny. Display units command premium positioning in club and convenience channels where floor-space productivity determines category access. E-commerce platforms represent the fastest-growing end-user segment as unboxing experience becomes a retention variable.
EMA and ECHA frameworks in Europe govern chemical migration limits from packaging into food contact surfaces, while EPA guidelines in the United States shape recycled content thresholds for fiber-based RRP. REACH compliance costs are filtering smaller converters from multinational retail supply chains. Stakeholders must track evolving extended producer responsibility schemes that transfer end-of-life collection costs from municipalities to brand owners and their packaging partners.
Market Dynamics
Supermarket labor cost compression is the dominant structural force reshaping retail ready packaging demand, as automated shelf-stocking systems and direct-to-display logistics eliminate intermediate handling steps between distribution centers and consumer-facing aisles.
Growth Catalysts
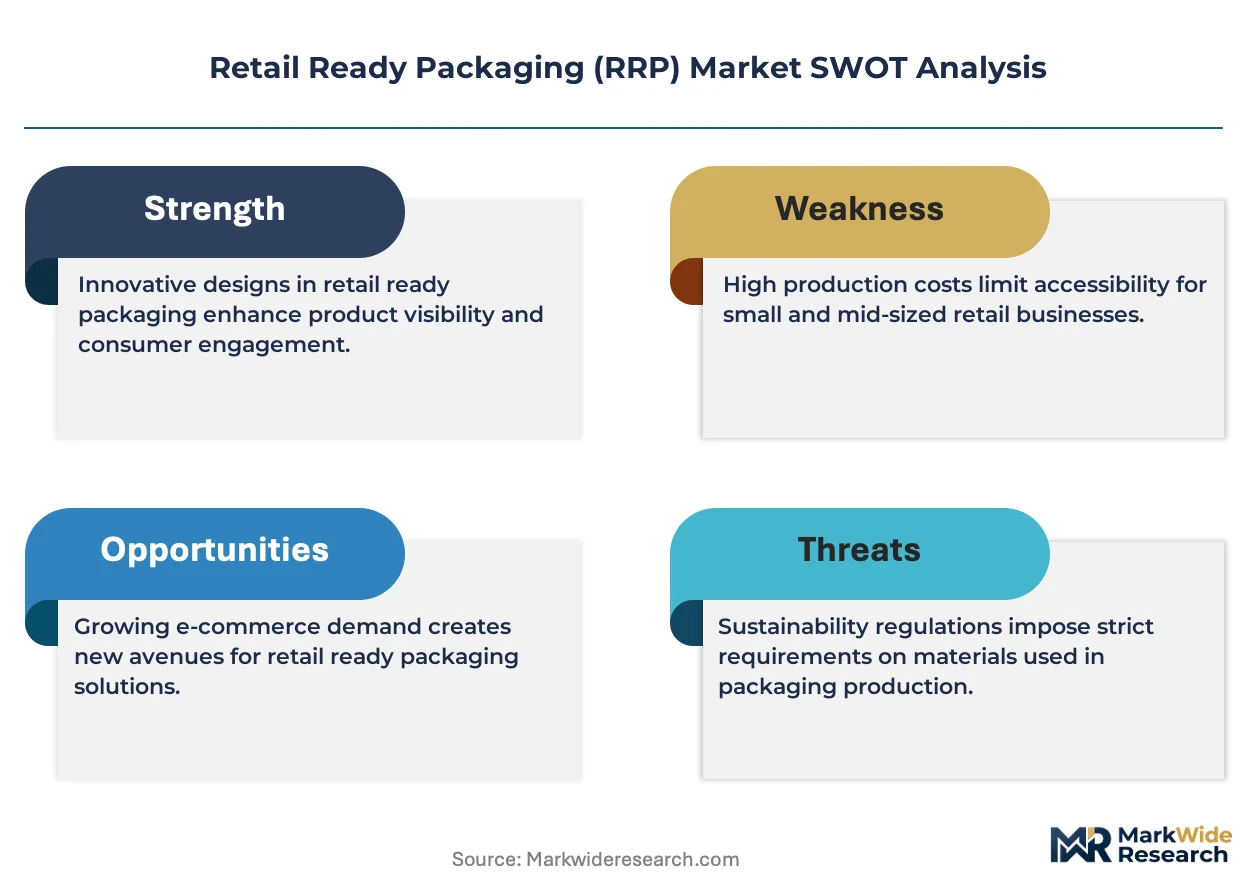
- EU Packaging and Packaging Waste Regulation:Recyclability mandates are forcing brand owners to specify fiber-based RRP formats, expanding addressable demand for compliant converters across German, French, and Italian retail channels.
- Corrugated fiberboard automation:High-speed die-cutting and inline printing systems are reducing per-unit conversion costs, enabling mid-sized grocers to adopt shelf-ready formats previously limited to multinational chains.
- Discounter format standardization:Aldi and Lidl procurement specifications in Germany are creating template economies that cascade through European private-label supply chains.
Market Restraints
- OCC price volatility:Old corrugated container input costs swing with Chinese import policies for recovered fiber, compressing converter margins during supply tightness.
- REACH compliance burden:ECHA chemical migration testing requirements for food-contact RRP are filtering smaller converters from multinational retail supply chains.
- Rigid plastic substitution:Reusable crates in fresh produce loops are capturing volume from single-use corrugated trays in closed-loop retailer systems.
Strategic Opportunities
- E-commerce unboxing experience:Direct-to-consumer brands are specifying tear-strip RRP formats that transition from protective shipper to display-ready presentation, opening channel diversification for corrugated specialists.
- Biodegradable barrier coatings:Water-based and PLA-lined fiberboards are penetrating fresh protein segments previously reserved for plastic, enabled by EFSA-approved contact surface innovations.
- Extended producer responsibility schemes:French and Italian EPR fee structures are favoring mono-material fiber designs over multi-substrate alternatives, creating regulatory tailwinds for integrated paperboard producers.
Industry Challenges
- Die-cut precision tolerances:Perforation consistency for clean tear-open functionality demands tooling investments that strain smaller converting operations.
- Multi-retailer format fragmentation:Incompatible tray dimensions across Tesco, Carrefour, and Rewe specifications force SKU proliferation and inventory complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Retail Ready Packaging (RRP) Market |
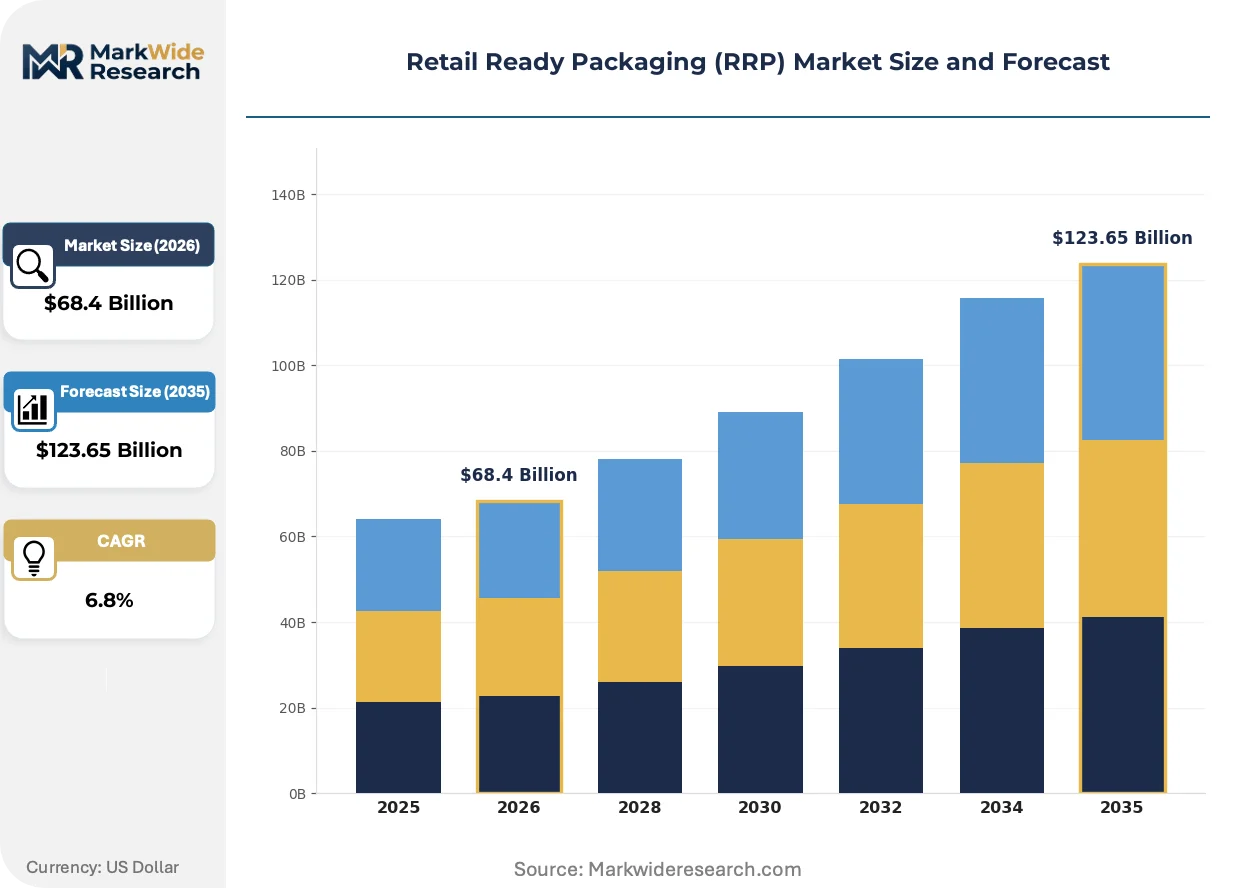
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $123.65 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cardboard Boxes, Plastic Trays, Display Units, Pallet Displays End User: Grocery Stores, Convenience Stores, E-commerce Platforms, Specialty Retailers Material: Corrugated Fiberboard, Rigid Plastic, Recycled Paper, Biodegradable Materials Packaging Format: Single Packs, Multi-packs, Stackable Units, Shrink-wrapped Packs |
| Companies Covered | Smurfit Kappa, Mondi Group, WestRock, Packaging Corporation of America, Amcor, International Paper, DS Smith, Graphic Packaging, Georgia-Pacific, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Retail Ready Packaging (RRP) Market Evolving Landscape
Digital printing integration and smart packaging interfaces are compressing design-to-shelf timelines while enabling batch-level customization previously uneconomical at RRP scale.
Water-based flexographic printing with inline quality inspection is rewriting the economics of short-run RRP production. Mid-market beverage brands are adopting digitally printed shelf-ready cases for seasonal promotions with two-week turnaround requirements. This capability is compressing minimum order quantities from truckload to pallet quantities, fragmenting converter customer bases toward higher-touch, lower-volume relationships.
REACH SVHC candidate list expansion is tightening chemical disclosure obligations for RRP suppliers serving European food retail. The regulation is forcing reformulation of optical brighteners and sizing agents in white-top linerboard. Fresh produce tray manufacturers are responding with third-party certified fiber sourcing and migrated substance testing protocols to retain listing status with EDEKA and Mercadona.
Club-store buyers are consolidating supplier relationships around full-display pallet program capabilities, displacing transactional tray-only vendors. Costco and Sam's Club procurement teams are specifying integrated pallet display systems with pre-assembled risers and side-shrouds. This concentration is visible most acutely in North American warehouse club channels, where category captains now control secondary packaging specification authority previously held by brand marketing teams.
Retail Ready Packaging (RRP) Market Segmentation
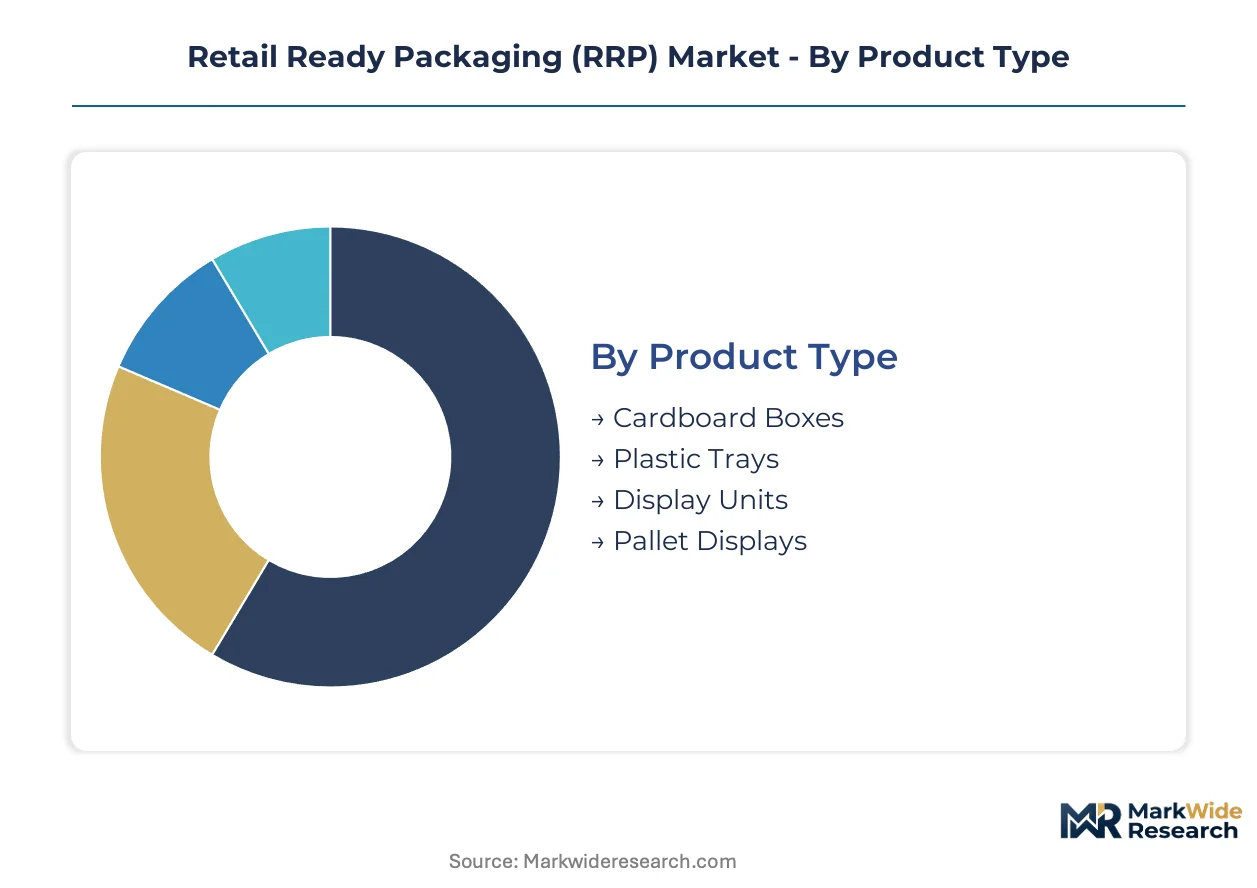
Segmentation in the RRP market tracks how shelf-ready formats align with distinct supply chain configurations and retail operational models. Each dimension—product construction, retail channel, material substrate, and pack configuration—carries specific tooling investments and compliance obligations that reshape converter specialization.
Product Type:
Supply concentration in high-speed converting equipment favors formats with standardized die specifications and repeat volume profiles.
- Cardboard Boxes:Die-cut corrugated cases with tear-strip perforations and barcode windows dominate mainstream grocery adoption. German discounters Aldi and Lidl specify uniform tray depths that cascade through private-label supply chains, locking in template economies for integrated fiberboard producers.
- Display Units:Floor-standing or counter-top corrugated structures with pre-assembled risers command premium positioning in club-store channels. Costco and Sam's Club procurement teams now specify integrated pallet programs that displace transactional tray-only vendors, concentrating supplier relationships around full-display capabilities.
- Plastic Trays:Thermoformed PET or PP formats with snap-lock features serve fresh produce segments requiring moisture resistance.
- Pallet Displays:Full-pallet shipper displays with branded side shrouds target warehouse club and mass merchandiser channels.
Cardboard boxes absorb the bulk of installed capacity; display units are expanding most quickly.
End User:
Channel-specific labor models and space productivity metrics determine format specifications and order frequency patterns.
- Grocery Stores:Traditional supermarkets specify shelf-ready trays that eliminate backroom unpacking labor. Automated shelf-stocking system rollouts at chains like Carrefour and Tesco are tightening dimensional tolerances and barcode placement requirements.
- E-commerce Platforms:Direct-to-consumer brands specify tear-strip RRP formats that transition from protective shipper to display-ready presentation. Unboxing experience engineering is opening channel diversification for corrugated specialists serving retention-focused online retailers.
- Convenience Stores:Limited backroom space drives demand for compact, high-turnover pack configurations.
- Specialty Retailers:Premium positioning requirements favor custom-printed, small-batch formats with seasonal flexibility.
Grocery stores anchor volume demand; e-commerce platforms are climbing the fastest.
Material:
Regulatory pressure on end-of-life recovery is rebalancing material selection toward fiber-dominated, mono-material constructions.
- Corrugated Fiberboard:Multi-layer paperboard with crush-resistant flute profiles remains the default substrate for dry grocery and beverage applications. EU Packaging and Packaging Waste Regulation recyclability mandates are forcing brand owners to specify fiber-based formats, expanding addressable demand for compliant converters.
- Biodegradable Materials:PLA-lined and water-based barrier-coated fiberboards are penetrating fresh protein segments previously reserved for plastic. EFSA-approved contact surface innovations are enabling substitution in EDEKA and Mercadona supply chains.
- Rigid Plastic:Reusable crates in closed-loop retailer systems are capturing volume from single-use alternatives in fresh produce loops.
- Recycled Paper:Post-consumer fiber content meets retailer sustainability scorecard requirements but faces strength limitations in high-humidity environments.
Corrugated fiberboard commands the dominant share of material throughput; biodegradable materials are gaining share fastest.
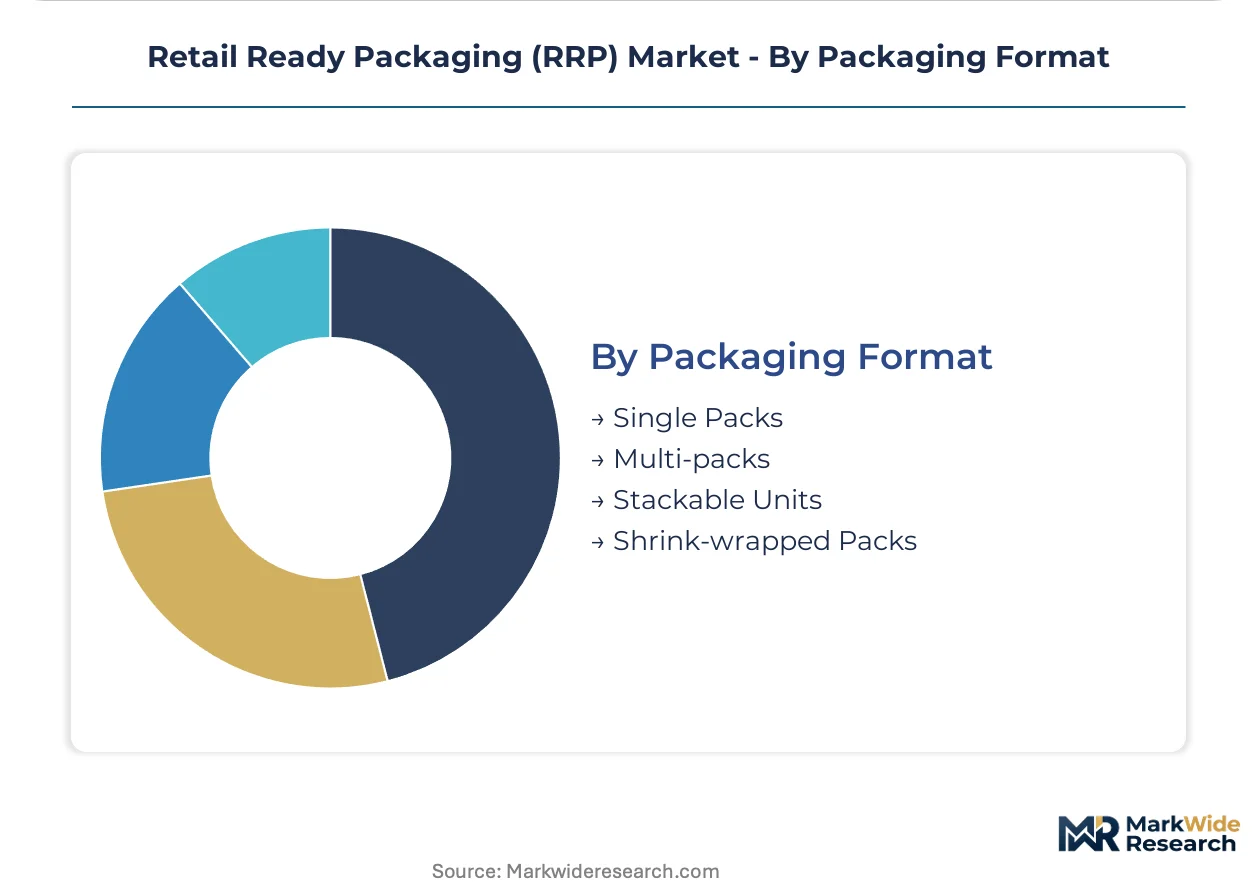
Packaging Format:
Retail shelf dimensions and replenishment velocity determine whether formats prioritize cube efficiency or promotional visibility.
- Multi-packs:Bundled configurations with common tear-open features serve high-velocity categories where shelf-ready stocking speed outweighs individual unit handling. Club-store pallet display contracts typically specify multi-pack foundations with pre-printed shrouds.
- Stackable Units:Interlocking tray designs with crush-resistant corners maximize vertical shelf utilization in space-constrained convenience and urban grocery formats.
- Single Packs:Individual unit presentation dominates premium and specialty retail channels with lower velocity requirements.
- Shrink-wrapped Packs:Film-secured bundles offer tamper evidence and moisture protection for beverage and household chemical applications.
Multi-packs absorb the bulk of production volume; stackable units are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Free trade zones in the Pearl River Delta and Yangtze River Delta concentrate corrugated converting capacity serving export-oriented manufacturing clusters.
Germany
Aldi and Lidl procurement mandates for standardized tray formats cascade through European private-label supply chains. The EU Packaging and Packaging Waste Regulation recyclability requirements filter non-compliant converters from retail channels. The Rhine-Ruhr industrial corridor hosts integrated fiberboard producers supplying discounter networks across the continent.
United States
Costco and Sam's Club pallet display contracts concentrate supplier relationships around integrated full-program capabilities. EPA recycled content thresholds shape fiber sourcing specifications for corrugated RRP serving club-store channels. The Chicago-Milwaukee corridor anchors automated converting capacity tied to mass merchandiser replenishment systems.
China
E-commerce platform demand for unboxing-optimized tear-strip formats drives specialty corrugated innovation. MEE dual carbon goals and provincial emissions trading schemes pressure converters toward renewable energy sourcing. The Shenzhen-Dongguan manufacturing belt supplies fiberboard display units for cross-border direct-to-consumer brands.
France
Extended producer responsibility fee structures favor mono-material fiber designs over multi-substrate alternatives. ECHA REACH chemical migration limits force reformulation of optical brighteners in food-contact linerboard. The Île-de-France logistics hub concentrates RRP specification authority for Carrefour and Auchan centralized procurement.
India
Modern trade expansion in urban centers drives shelf-ready tray adoption among domestic FMCG brands. FSSAI food-contact packaging regulations and BIS quality standards shape converter compliance investments. The Mumbai-Pune industrial corridor hosts emerging corrugated specialists serving Reliance Retail and D-Mart replenishment networks.
Retail Ready Packaging (RRP) Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered supply positions. The market structure shows consolidation at the integrated producer level alongside fragmentation among regional converting operations. Three archetypes dominate: multinational fiberboard integrators with captive pulp supply, specialty packaging converters with digital print capabilities, and rigid plastic tray manufacturers defending fresh produce applications. Competitive moves center on backward integration into recycled fiber sourcing and strategic partnerships with retail category captains.
Among Ireland-based integrated producers, Smurfit Kappa occupies a position exemplifying geographic diversification across European retail channels. Mondi Group and WestRock represent the scale-driven tier, with the former anchoring specialty kraft paper innovation and the latter exemplifying North American club-store contract concentration. These three entities sit within the multinational integrator archetype that commands specification authority with centralized retail procurement teams.
| Leading Market Players |
|---|
| Smurfit Kappa |
| Mondi Group |
| WestRock |
| Packaging Corporation of America |
| Amcor |
| International Paper |
| DS Smith |
| Graphic Packaging |
| Georgia-Pacific |
| Others |
Value Network & Pricing Analysis
OCC price volatility cascades through converter margin structures, with Old corrugated container input costs swinging between spot-market premiums and contract discounts based on Chinese import policies for recovered fiber. This raw-material-driven pricing tiering separates integrated producers with captive pulp supply from transactional converters exposed to spot-market OCC indices.
Pricing Analysis
Short lead-time premiums command substantial markups in the RRP market, with two-week turnaround seasonal promotions from mid-market beverage brands pricing at standard contract multiples above truckload-quantity baseline orders. Three-tier pricing structure across premium, standard, and economy levels stratifies by customization depth and volume scale, with club-store pallet display programs anchoring the premium tier. Pricing pressure stems from automated die-cutting capacity expansion compressing per-unit conversion economics in high-volume tray segments. Small-format convenience store buyers exhibit highest price sensitivity due to limited backroom space forcing compact SKU configurations, while Costco and Sam's Club procurement teams prioritize full-program integration over unit cost minimization.
Supply Chain Analysis
Container freight rates from Shanghai to Rotterdam and trans-Pacific lanes to Long Beach directly shape landed costs for corrugated machinery imports and specialty kraft paper feedstocks. Supply concentrates in Germany's Rhine-Ruhr industrial corridor, China's Shenzhen-Dongguan manufacturing belt, and the Chicago-Milwaukee corridor anchoring North American automated converting. Raw material dependencies center on OCC recovered fiber, unbleached kraft pulp, and water-based barrier coating chemistries. Single-source vulnerability runs through Chinese OCC export licensing policies that disrupted converter input costs during prior supply tightness. Distribution runs through centralized retail procurement hubs in Île-de-France for Carrefour and Auchan, with discounter networks in Germany mandating direct-to-DC supplier relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around integrated producers as REACH compliance costs and die-cut precision tooling investments filter smaller converters from multinational retail supply chains.
For Market Incumbents: Deepen backward integration into recycled fiber sourcing to insulate margin structures from Chinese OCC import policy swings. Expand automated converting capacity in the Chicago-Milwaukee corridor to capture Costco and Sam's Club pallet display contract consolidation. Invest in EFSA-approved biodegradable barrier coating R&D to defend fresh protein tray share against rigid plastic substitution in closed-loop retailer systems. For New Entrants and Emerging Players: Launch via digital print-enabled short-run production serving e-commerce direct-to-consumer brands with unboxing-optimized tear-strip formats. Target India's Mumbai-Pune industrial corridor where Reliance Retail and D-Mart replenishment networks are modernizing tray specifications without incumbent supplier lock-in. Pursue seasonal promotion contracts with mid-market beverage brands requiring two-week turnaround capabilities that strain legacy converter workflows. For Investors and Strategic Acquirers: Aldi and Lidl standardized tray format mandates cascading through European private-label supply chains is the leading indicator that template economies will concentrate specification authority among integrated producers with cross-border corrugated networks. Position acquisition screening toward mid-sized German and French converters with ECHA REACH compliance infrastructure and existing EDEKA or Mercadona listing status. Monitor extended producer responsibility fee structure implementations in France and Italy as signals of regulatory tailwinds favoring mono-material fiber designs.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Recycled Fiber Sourcing | Captive OCC supply insulates converters from Chinese import policy volatility and margin compression. |
| Digital Print Capability Expansion | Short-run seasonal promotion contracts with beverage brands fragment customer bases toward higher-touch relationships. |
| EFSA-Approved Biodegradable Barrier Coating Development | Fresh protein tray substitution opens segments previously reserved for plastic in EDEKA and Mercadona supply chains. |
| Automated Die-Cutting Capacity Addition | High-speed inline printing systems reduce per-unit costs enabling mid-sized grocer adoption of shelf-ready formats. |
| Club-Store Pallet Display Program Integration | Full-program capabilities with pre-assembled risers displace transactional tray-only vendors at Costco and Sam's Club. |
Research Methodology
Independent corroboration across procurement directors at Aldi and Lidl, corrugated plant managers in the Rhine-Ruhr corridor, and ECHA regulatory affairs specialists underwrites the qualitative findings in this analysis. Primary interviews with category buyers at Carrefour and Tesco, technical R&D directors at integrated fiberboard producers, and aftermarket service heads at die-cutting equipment manufacturers combined with secondary validation from EU Packaging and Packaging Waste Regulation compliance filings, SEC 10-K disclosures of listed packaging conglomerates, and trade data on OCC recovered fiber flows. Bottom-up volume modeling across product type and end-user segments triangulated against top-down macroeconomic drivers of supermarket labor cost compression.
Comparable-period anchoring to historical adoption curves of automated shelf-stocking system rollouts established the forecast window's baseline trajectory. The analytical framework segments by product construction, retail channel, material substrate, and pack configuration across the projection horizon, with CAGRs derived from elasticity modeling of discounter format standardization penetration rates. Industry-specific forecast inputs incorporated EPR fee structure implementation timelines in France and Italy and e-commerce unboxing experience investment intensity from direct-to-consumer brands.
OCC price volatility swings, REACH SVHC candidate list expansion pacing, and rigid plastic crate adoption rates in fresh produce closed loops are the dominant revision risks to modeled outputs. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Retail Packaging
Retail E Commerce Packaging Market
Retail Packaging
Club Store Packaging Market
Retail Packaging
Retail Ready Trays Market
Retail Packaging
Table Tent Market
Retail Packaging
Floor POP Display Market
Retail Packaging
Retail Bags Market
Retail Packaging
Free Standing Display Units Market
Retail Packaging
Global Shoe Packaging Market
Retail Packaging
Black Friday Packaging Market