
 Black Friday Packaging Market | 2026-2036
Black Friday Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Black Friday Packaging Market Outlook
Skilled flexographic press operators is collapsing across European corrugated plants, tightening peak-season capacity just as e-commerce order surges strain converter networks. WestRock sustains its position through captive containerboard supply and high-throughput box plants near Atlanta and Memphis. DS Smith differentiates via circular-design services and lightweight flute optimization for apparel shippers. Mondi Group anchors Central European demand with integrated kraft paper and corrugated operations spanning Austria and Poland.
Black Friday packaging denotes short-run, high-velocity protective and promotional formats engineered for single-transit durability and unboxing impact, typically constructed from recycled-content corrugated board, flexible polyethylene films, or padded paper mailers with burst strengths calibrated to 200-350 kPa. Its primary commercial purpose is to minimize dimensional weight shipping penalties while preserving brand presentation during the November-December fulfillment crush. Corrugated boxes dominate absolute volume as the workhorse of e-commerce parcel movement, yet padded envelopes and paper wraps claim the fastest expansion as fashion and cosmetics retailers seek to cut void fill and dimensional weight charges. Custom-size formats capture disproportionate margin pools by reducing material waste and freight costs for high-SKU-count merchants.
The EU Packaging and Packaging Waste Regulation mandates minimum recycled content thresholds and extended producer responsibility fees, pushing converters toward verified fiber sourcing and mono-material designs that simplify post-consumer sorting. The US EPA Sustainable Materials Management program and state-level extended producer responsibility laws in California and Oregon add compliance layers for cross-border shippers. Stakeholders must monitor whether recycled pulp cost premiums compress box margins faster than brand owners accept price pass-throughs for certified sustainable formats.
Market Dynamics
E-commerce order velocity is compressing converter lead times while the EU Packaging and Packaging Waste Regulation forces simultaneous material redesign, creating a capacity-design tension that defines current market structure.
Growth Catalysts
- Extended Producer Responsibility mandates:The EU Packaging and Packaging Waste Regulation mandates minimum recycled content thresholds, pushing brand owners toward certified sustainable formats and creating premium pricing pools for verified fiber sourcing.
- Dimensional weight optimization:Fashion and cosmetics retailers are driving demand for custom-size corrugated and padded paper mailers that reduce void fill and freight penalties across high-SKU fulfillment networks.
- German logistics concentration:Amazon fulfillment centers and Zalando logistics hubs anchor peak-season volume, concentrating converter investment in automated box plants near these demand nodes.
Market Restraints
- Recycled pulp cost volatility:Post-consumer fiber premiums compress box margins faster than brand owners accept price pass-throughs for certified sustainable formats.
- Skilled operator scarcity:Flexographic press operator pipelines are collapsing across European corrugated plants, tightening peak-season capacity just as e-commerce surges strain converter networks.
- Mono-material performance limitations:Simplified post-consumer sorting requirements under EU regulations constrain barrier properties and puncture resistance in single-substrate designs.
Strategic Opportunities
- Lightweight flute optimization:Apparel shippers in Germany and Poland are adopting micro-flute and nano-flute constructions that cut material weight without sacrificing stack strength.
- California EPR alignment:State-level extended producer responsibility laws create compliance service opportunities for cross-border shippers serving US West Coast e-commerce corridors.
- Circular-design service bundling:Packaging-as-a-service models that integrate recovery logistics with format design are capturing multi-year contracts from omnichannel retailers.
Industry Challenges
- Flexographic talent pipeline collapse:European technical institutes have shuttered specialized print programs, leaving converters dependent on aging workforces during November-December demand spikes.
- Certification timeline compression:FSC and PEFC chain-of-custody verification cannot match the velocity of Black Friday product launches, forcing expedited audits that strain accreditation bodies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Black Friday Packaging Market |
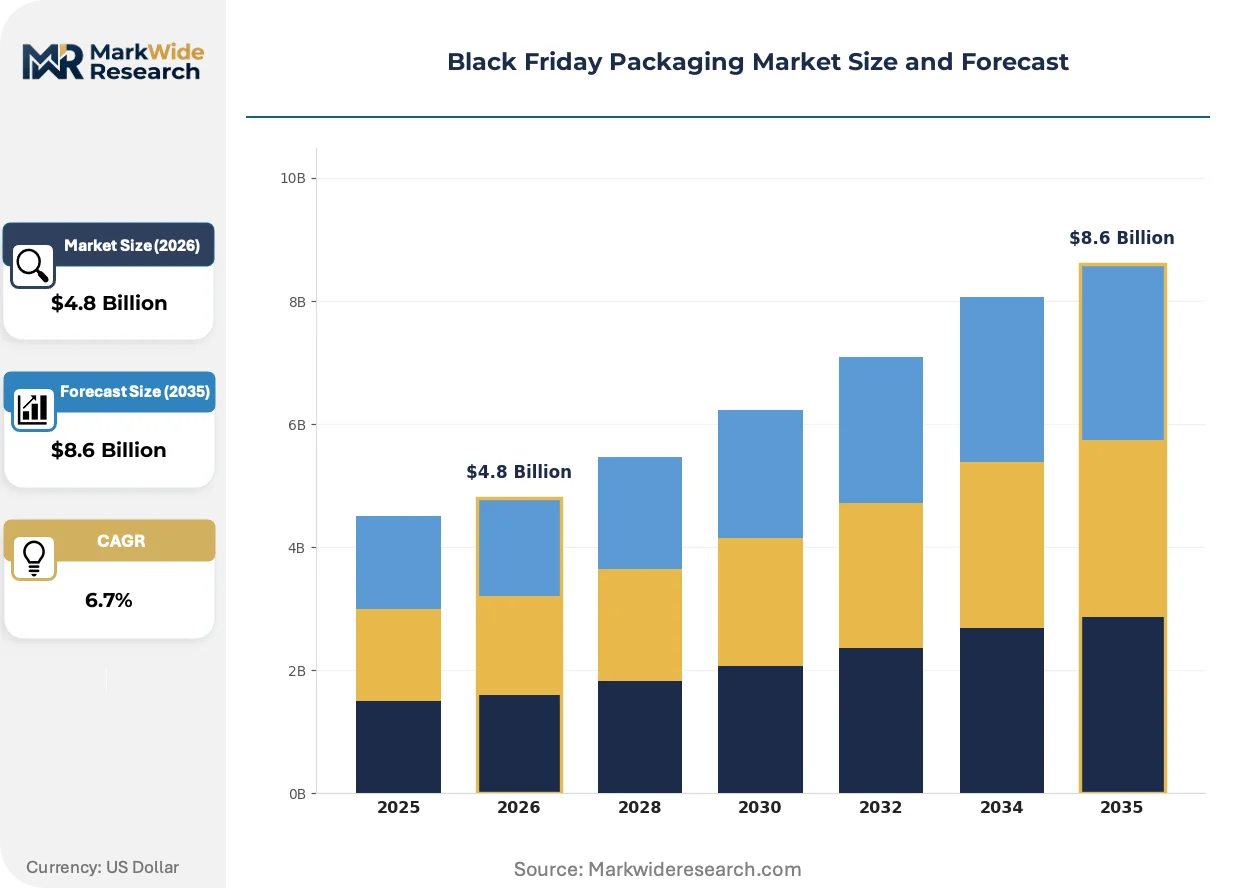
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Boxes, Bags, Envelopes, Wraps Material: Paper, Plastic, Glass, Metal End User: E-Commerce, Retail, Wholesale, Consumer Goods Size: Small, Medium, Large, Custom |
| Companies Covered | Smurfit Kappa, WestRock, DS Smith, Mondi Group, International Paper, Pratt Industries, Amcor, Packaging Corporation of America, Sealed Air, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Black Friday Packaging Market Strategic Shifts
Active material substitution and regulatory compliance automation are converging to reshape how protective formats are engineered, sourced, and recovered across peak-season fulfillment cycles.
Padded paper mailers with burst strengths calibrated to 200-350 kPa are supplanting polyethylene bubble wraps in cosmetics and accessory shipments. Zalando and similar fashion platforms are scaling these formats fastest, eliminating plastic separation steps for consumers while meeting EU mono-material mandates. This shift is compressing demand for multi-layer flexible films and redirecting converter capex toward kraft paper lamination lines.
The EU Packaging and Packaging Waste Regulation tightens material recovery targets across member states, forcing converters to deploy spectroscopic sorting verification and blockchain fiber tracing. German corrugated plants are retrofitting lines with near-infrared detection systems to validate recycled content claims in real time. Apparel shippers with German distribution nodes face the steepest compliance ramps and are pre-qualifying suppliers based on verified post-consumer fiber percentages.
Merchant procurement of protective formats is consolidating around integrated design-to-recovery contracts that bundle format optimization with reverse logistics. Omnichannel retailers are displacing spot-market box purchasing with multi-season agreements that lock in capacity and material certification. This pattern is most visible in Poland and Austria, where Mondi Group's integrated kraft paper and corrugated operations enable closed-loop service models for Central European e-commerce platforms.
Black Friday Packaging Market Segmentation
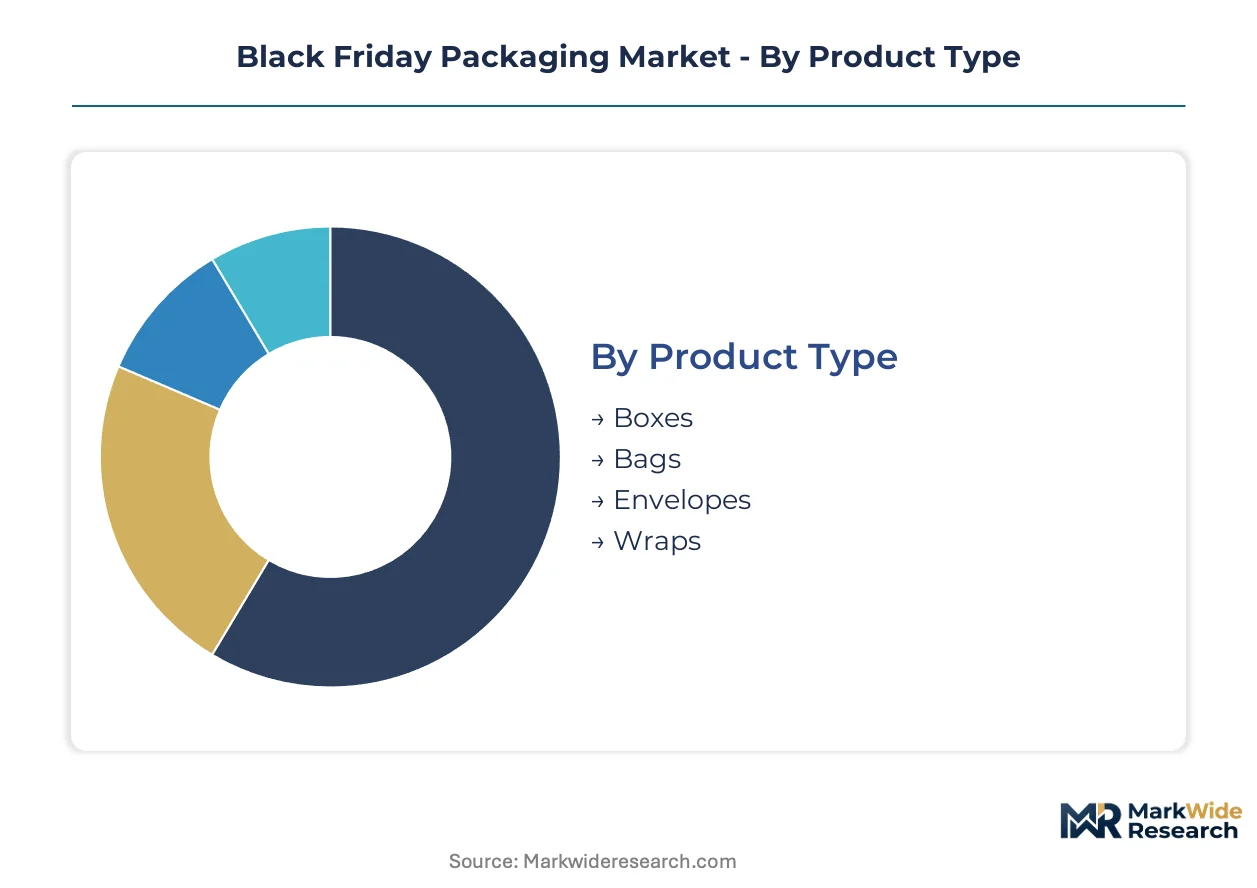
Black Friday packaging procurement patterns diverge sharply across product formats, material substrates, and fulfillment channel requirements. E-commerce velocity and EU regulatory mandates reshape how converters prioritize capacity allocation across these segment boundaries.
Product Type:
Domestic German fulfillment networks favor rigid protective formats, while cross-border e-commerce corridors drive flexible format uptake for dimensional weight savings.
- Boxes:Recycled-content corrugated constructions dominate absolute volume, with burst strengths calibrated to 200-350 kPa for single-transit durability. Amazon fulfillment centers and Zalando logistics hubs in Germany anchor peak-season demand for this segment, though flexographic press operator scarcity tightens converter capacity during November-December surges.
- Envelopes:Padded paper mailers are displacing polyethylene bubble wraps fastest in cosmetics and accessory shipments, eliminating plastic separation steps for consumers while meeting EU mono-material mandates. Fashion platforms are scaling these formats most aggressively across German and Polish distribution nodes.
- Bags:Flexible polyethylene and kraft paper variants serve mid-weight apparel shipments with lower void fill requirements than rigid alternatives.
- Wraps:Protective paper and tissue formats protect fragile goods within outer containers, common in premium cosmetics unboxing experiences.
Boxes command the established base. The steepest expansion runs through Envelopes.
Material:
Cost tiers separate virgin fiber premiums from post-consumer recycled grades, with certification complexity adding margin pressure at the top end.
- Paper:Kraft paper and corrugated board variants carry FSC and PEFC chain-of-custody requirements that outpace accreditation body capacity during Black Friday launch cycles. German corrugated plants are retrofitting lines with near-infrared detection systems to validate recycled content claims in real time.
- Plastic:Flexible polyethylene films face demand compression as EU Packaging and Packaging Waste Regulation mandates tighten material recovery targets and push converters toward mono-material designs that simplify post-consumer sorting.
- Glass:Premium cosmetic and fragrance applications require protective outer packaging with high puncture resistance, typically nested within corrugated inserts.
- Metal:Tin and aluminum containers serve luxury gift sets with high unboxing impact, though weight penalties limit e-commerce scalability.
Paper represents the volume anchor. Plastic is losing share fastest to fiber-based substitutes.
End User:
Application intensity varies by fulfillment velocity, with pure-play digital merchants driving format innovation ahead of brick-and-click retailers.
- E-Commerce:Pure-play digital merchants and omnichannel platforms generate the sharpest format customization demands, with high-SKU-count apparel shippers in Germany and Poland adopting micro-flute and nano-flute constructions that cut material weight without sacrificing stack strength.
- Retail:Store-based fulfillment networks prioritize shelf-ready packaging with promotional print surfaces for in-store display.
- Wholesale:Bulk shipment consolidation favors standard-size corrugated formats with minimal customization for B2B palletization.
- Consumer Goods:Brand owners across cosmetics and electronics balance unboxing impact with dimensional weight optimization for direct-to-consumer channels.
E-Commerce concentrates the most visible innovation investment. Wholesale maintains the most standardized procurement patterns.
Size:
Customer type separates high-volume merchants with dedicated format optimization programs from spot-market purchasers.
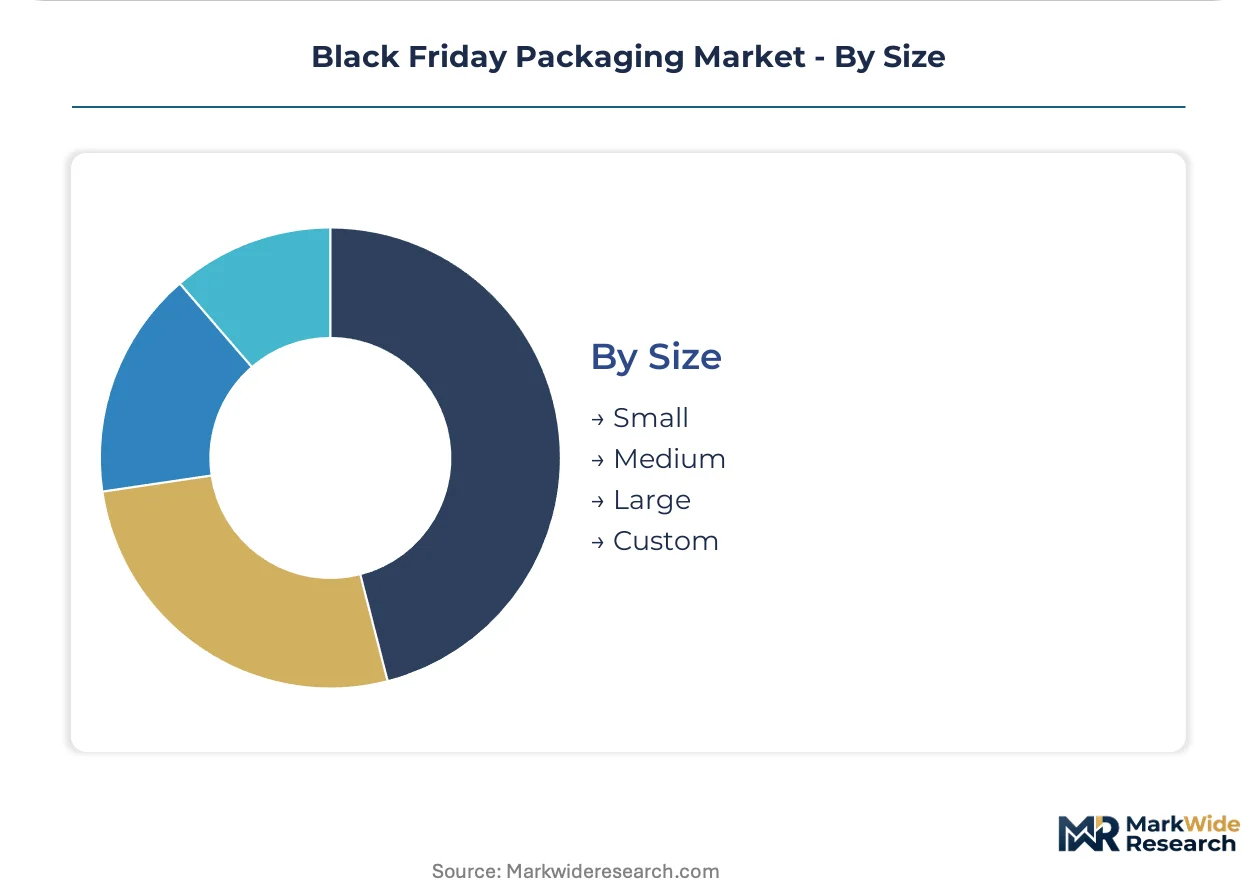
- Custom:Tailored dimensions reduce void fill and freight penalties for high-SKU-count merchants, capturing disproportionate margin pools through material waste reduction. Mondi Group's integrated operations in Austria and Poland enable closed-loop service models that bundle format design with recovery logistics.
- Small:Standardized formats serve accessory and cosmetics shipments with high velocity and low customization requirements.
- Medium:Mid-size apparel and footwear shipments dominate order volume across German logistics hubs.
- Large:Bulky goods and multi-item orders require reinforced flute constructions and edge protection systems.
Custom formats capture the premium pricing tier. Small sizes move the highest unit volumes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German e-commerce corridors deploy rigid corrugated formats at density levels unmatched elsewhere, while US West Coast merchants favor lightweight padded mailers to offset dimensional weight penalties across Pacific shipping lanes.
Germany
Amazon fulfillment centers and Zalando logistics hubs anchor peak-season corrugated consumption, with micro-flute optimization spreading rapidly among apparel shippers. The EU Packaging and Packaging Waste Regulation mandates minimum recycled content thresholds that push converters toward verified fiber sourcing. Automated box plants near Leipzig and Dortmund are retrofitting lines with near-infrared detection systems to validate post-consumer fiber percentages in real time.
United States
California and Oregon state-level extended producer responsibility laws create compliance complexity for cross-border shippers serving West Coast e-commerce corridors. The EPA Sustainable Materials Management program adds federal oversight layers to state mandates. High-throughput box plants near Atlanta and Memphis sustain captive containerboard supply chains that buffer peak-season demand surges.
Poland
Central European e-commerce platforms concentrate procurement through integrated design-to-recovery contracts that bundle format optimization with reverse logistics. EU Packaging and Packaging Waste Regulation recovery targets force rapid certification timelines for corrugated suppliers. Mondi Group's integrated kraft paper and corrugated operations span Kraków and Warsaw, enabling closed-loop service models for regional omnichannel retailers.
United Kingdom
Fashion and cosmetics retailers drive padded paper mailer adoption fastest among British pure-play digital merchants seeking to eliminate plastic separation steps for consumers. Extended producer responsibility frameworks align with EU regulatory direction despite post-Brexit divergence. Corrugated converters near Birmingham and Manchester face flexographic press operator scarcity that tightens November-December capacity.
France
Luxury cosmetics and fragrance brands demand protective outer packaging with high puncture resistance nested within corrugated inserts for premium unboxing experiences. ANSM and CNIL oversight adds compliance layers to packaging material selection for consumer-facing goods. Paris-region fulfillment networks prioritize shelf-ready formats with promotional print surfaces that bridge e-commerce and retail display requirements.
Black Friday Packaging Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with scale advantages concentrated among containerboard producers that control upstream pulp supply. The market structure rewards backward integration into virgin and recycled fiber streams, while lightweight flute optimization and circular-design service bundling represent the dominant competitive vectors. Strategic archetypes include captive-supply integrated players, circular-service specialists, and regional scale operators. Competitive moves center on M&A consolidation of corrugated assets and capacity expansion near German logistics nodes.
Among integrated European operators, Smurfit Kappa and DS Smith exemplify the circular-design specialist archetype, with service bundling that extends beyond format supply into recovery logistics. WestRock anchors the North American tier through high-throughput manufacturing concentration near Atlanta and Memphis. These three represent the strategic positioning that converters must match to secure multi-year contracts from omnichannel retailers seeking capacity locks and material certification guarantees.
| Leading Market Players |
|---|
| Smurfit Kappa |
| WestRock |
| DS Smith |
| Mondi Group |
| International Paper |
| Pratt Industries |
| Amcor |
| Packaging Corporation of America |
| Sealed Air |
| Others |
Value Chain & Pricing Dynamics
High-throughput box plant utilization rates near German logistics nodes create scale economies that compress unit costs while simultaneously elevating price floors for custom-format corrugated during peak-season demand surges. Containerboard producers with captive pulp supply wield asymmetric pricing power over spot-market converters facing recycled fiber cost volatility and flexographic operator scarcity.
Pricing Analysis
Long-term offtake contracts dominate procurement between omnichannel retailers and integrated converters, with spot-market purchasing confined to smaller merchants lacking volume scale. Price differentiation rests on FSC chain-of-custody certification tiers and dimensional weight optimization services, with certified sustainable formats commanding premiums that brand owners resist absorbing. Cost compression in recycled-content grades is intensifying because post-consumer fiber premiums outpace box margin recovery, though high-SKU-count apparel shippers show least price sensitivity due to freight penalty avoidance.
Supply Chain Analysis
Germany and Poland anchor European corrugated production, with integrated kraft paper and box plant operations concentrated near Leipzig, Dortmund, and Kraków. Raw material flows draw from Swedish and Finnish virgin fiber streams alongside post-consumer recovered paper collections across Central Europe. Single-source vulnerability concentrates in flexographic press operator pipelines that European technical institutes have shuttered. Distribution runs through Amazon fulfillment centers and Zalando logistics hubs that pre-qualify suppliers based on real-time recycled content verification.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Black Friday packaging sits in early-cycle expansion as EU Packaging and Packaging Waste Regulation mandates force material redesign across e-commerce fulfillment networks, accelerating adoption of mono-material formats and circular-design service bundling.
For Market Incumbents: Shield margin pools by deepening backward integration into post-consumer fiber collection networks and deploying near-infrared detection systems for real-time recycled content validation. Prioritize capacity addition near German logistics nodes to lock in multi-year contracts from omnichannel retailers seeking capacity guarantees, while countering flexographic talent pipeline collapse through automated press retrofit programs. For New Entrants and Emerging Players: FSC fast-track certification services represent the most penetrable white-space opportunity, as accreditation body capacity cannot match Black Friday product launch velocity. Target mid-size Polish and Austrian e-commerce platforms with design-to-recovery contracts that bundle format optimization with reverse logistics, leveraging the EU regulatory compliance gap that incumbent converters fill too slowly. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors circular-design specialists with integrated kraft paper and corrugated operations over pure-play box converters lacking upstream fiber control. Long-term viability over the coming decade hinges on verified post-consumer fiber percentages and real-time sorting verification capabilities. The signal to watch is expedited audit queue lengths at FSC and PEFC accreditation bodies as proxy for certification bottleneck intensity.| Strategic Initiative | Industry Significance |
|---|---|
| Lightweight Flute Optimization | Micro-flute and nano-flute constructions cut material weight for German apparel shippers without sacrificing stack strength. |
| Near-Infrared Detection Deployment | Real-time recycled content validation satisfies EU Packaging and Packaging Waste Regulation mandates for German corrugated plants. |
| Design-to-Recovery Contract Bundling | Integrated service models capture multi-year agreements from Polish and Austrian omnichannel retailers seeking closed-loop logistics. |
| Flexographic Automation Retrofit | Press automation offsets skilled operator scarcity that threatens November-December capacity at European box plants. |
| Post-Consumer Fiber Integration | Backward integration into recovered paper collection networks secures supply and buffers margin against pulp cost volatility. |
Study Parameters
Desk research of EU regulatory filings, trade association capacity surveys, and containerboard producer sustainability disclosures preceded structured interviews with corrugated plant managers, e-commerce procurement leads at German logistics platforms, flexographic press operators, and circular-design service directors. Primary fieldwork combined with secondary validation across customs data for packaging material flows and SEC filings for integrated producers enabled bottom-up and top-down triangulation of market sizing.
Variance decomposition across product format, material substrate, end-use channel, and geographic fulfillment node shaped the analytical framework over the projection horizon. CAGRs were derived from segment-level growth rate reconciliation against aggregate market expansion, with inputs including e-commerce order velocity indices, recycled pulp cost spreads, and flexographic capacity utilization surveys.
Decision-makers should treat outputs as directional under base assumptions of sustained EU regulatory enforcement and e-commerce penetration growth; material deviation in either driver would warrant model refresh. Recalibration cycles align with material shifts in accreditation body capacity, post-consumer fiber collection economics, and peak-season labor availability.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Retail Packaging
Table Tent Market
Retail Packaging
Retail Ready Packaging (RRP) Market
Retail Packaging
Retail Bags Market
Retail Packaging
Global Shoe Packaging Market
Retail Packaging
Retail E Commerce Packaging Market
Retail Packaging
Retail Ready Trays Market
Retail Packaging
Floor POP Display Market
Retail Packaging
Free Standing Display Units Market
Retail Packaging
Club Store Packaging Market