
 Retail Ready Trays Market | 2026-2036
Retail Ready Trays Market Size, Share, and Industry Trends Forecast 2026-2036
Retail Ready Trays Market Analytics
Packaging engineering talent shortages across European corrugated board mills is unwinding capacity expansion timelines for retail-ready formats. Smurfit Kappa leverages its integrated containerboard network to control fiber supply for tray substrates. WestRock Company anchors North American production through high-volume folding carton facilities optimized for club-store specifications. Mondi Group differentiates via lightweight kraftliner grades that reduce per-unit shipping weights for grocery distributors.
Retail ready trays are pre-formed, shelf-display packaging units engineered from corrugated fiberboard, solid bleached sulfate, or thermoformed polymers with precise die-cut dimensions and tear-away perforations for immediate product presentation without secondary handling. Cardboard variants dominate volume due to cost parity and established recycling streams, while biodegradable segments attract reformulation investment as retailers phase out petroleum-based plastics. Thermal packaging types lead margin pools where insulated tray walls protect chilled meat and dairy through distribution, and display-friendly design features command premium positioning in supermarket produce departments where visual merchandising directly influences purchase decisions.
The EU Packaging and Packaging Waste Regulation and FDA food-contact substance notifications shape material selection and barrier coating approvals for trays contacting fresh proteins and ready-to-eat meals. REACH compliance for adhesives and printing inks restricts certain chemical formulations, pushing converters toward water-based alternatives. Stakeholders must monitor evolving extended producer responsibility frameworks that will shift end-of-life collection costs toward brand owners and tray manufacturers.
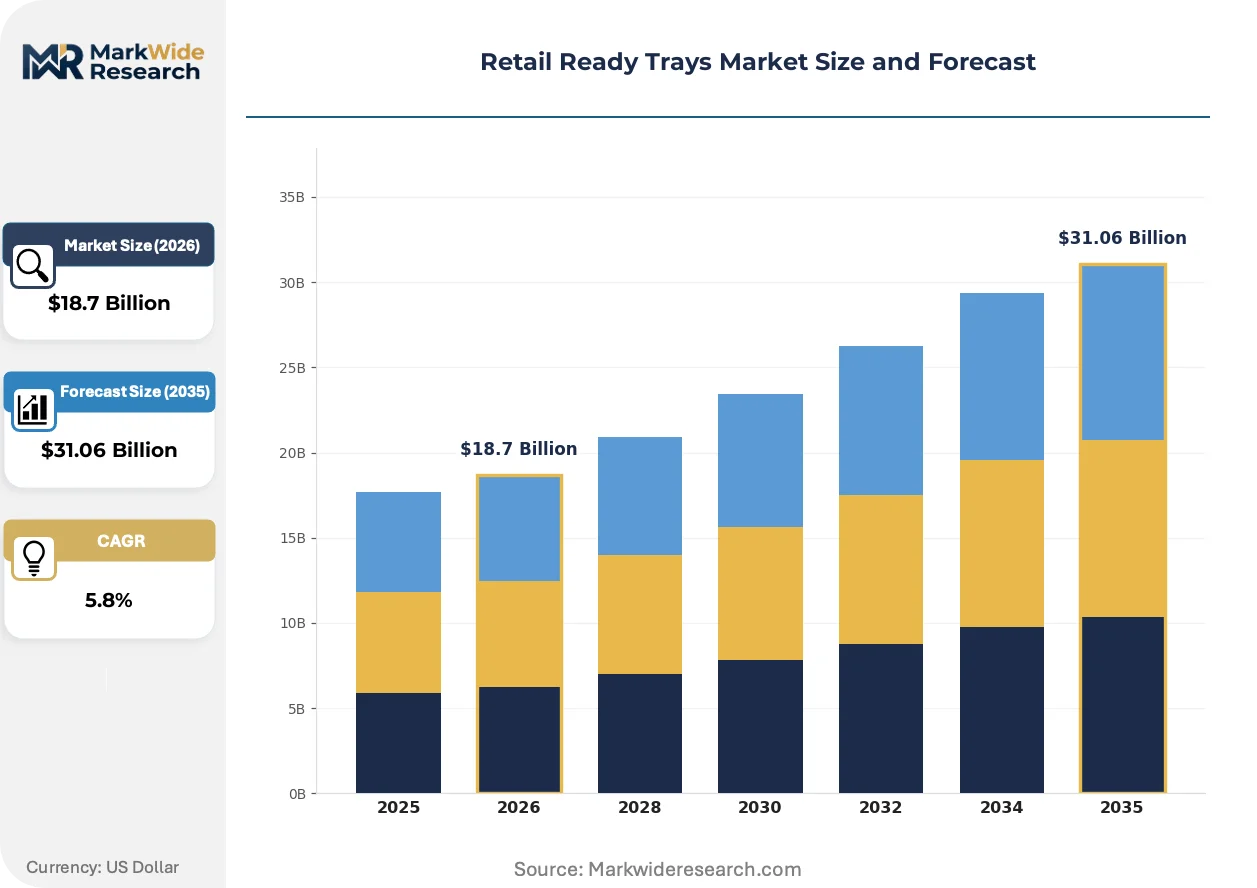
Market Dynamics
The EU Packaging and Packaging Waste Regulation is compressing design cycles for retail-ready trays as converters race to certify fiber-based alternatives before petroleum-plastic phase-out deadlines hit supermarket procurement calendars.
Growth Catalysts
- Automated Stocking Mandates:German retail chains now require standardized tray dimensions for robotic shelf-replenishment systems, forcing format convergence across supplier bases.
- REACH-Driven Material Reformulation:ECHA restrictions on solvent-based adhesives are accelerating water-based bonding technology adoption in corrugated tray manufacturing.
- Chilled Protein Distribution:Thermal-insulated tray walls with integrated barrier coatings are capturing expanded placement in supermarket meat and dairy departments.
Market Restraints
- Old Corrugated Container (OCC) Price Volatility:Recycled fiber input costs swing with municipal collection rates, squeezing converter margins on lightweight kraftliner grades.
- Tooling Concentration Risk:Precision die-cut perforation equipment for tear-away features concentrates among a handful of German and Italian machinery suppliers.
- Polymer Substitution Ceiling:Thermoformed PET trays retain moisture-barrier superiority for wet produce, limiting fiber-based penetration in berry and grape packaging.
Strategic Opportunities
- Poland and Czech Republic Modern Trade Expansion:Discount grocery chains in these markets are adopting Western European shelf-ready standards, opening tray specification windows.
- E-Commerce Grocery Lockers:Last-mile chilled fulfillment networks need collapsible, returnable tray formats that bridge retail display and home delivery.
- Extended Producer Responsibility (EPR) Credits:France's Citeo eco-modulation scheme rewards fiber-based packaging with lower fee schedules than plastic equivalents.
Industry Challenges
- Packaging Engineering Talent Scarcity:European corrugated board mills face 18-month recruitment timelines for structural designers fluent in automated stocking tolerances.
- FDA Food-Contact Notification Delays:Novel barrier coatings for protein trays face 12-18 month approval timelines, freezing product launch schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Retail Ready Trays Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $31.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Plastic, Cardboard, Wood, Biodegradable End User: Supermarkets, Convenience Stores, Wholesalers, Food Service Packaging Type: Thermal, Ventilated, Standard, Customizable Design Feature: Stackable, Reusable, Display Friendly, Lightweight |
| Companies Covered | Smurfit Kappa, WestRock Company, DS Smith, International Paper, Delkor Systems, Evolution Group, Lawrence Paper Company, Mondi Group, Green Bay Packaging, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Retail Ready Trays Market Evolving Landscape
Material science breakthroughs and regulatory phase-outs are converging to redraw competitive boundaries between fiber-based and polymer tray technologies across European grocery supply chains.
Water-based barrier coatings with oxygen-scavenging functionality are supplanting polyethylene extrusion layers in corrugated produce trays. Dutch and Belgian supermarket groups are piloting these formats for cut-vegetable applications. The shift is compressing capital recovery timelines for extrusion-lamination equipment while opening specification windows for integrated pulp-and-paper producers.
France's AGEC anti-waste law and its enforcement through DGCCRF inspections are mandating recyclability labeling and plastic reduction trajectories for all packaged goods. Tray converters must now submit third-party sorting protocol certifications to retain shelf placement. The chilled ready-meal segment is responding fastest, with reformulation investment flowing toward solid bleached sulfate substrates.
Buying desks at major retail groups are consolidating supplier rosters from twelve to four approved tray vendors per category. Centralized procurement in Germany and the Netherlands favors converters with in-house structural design studios and rapid prototyping capabilities. The squeeze is most visible in standardized produce trays where price transparency through e-sourcing platforms has collapsed supplier margins to single-digit percentages.
Retail Ready Trays Market Segmentation
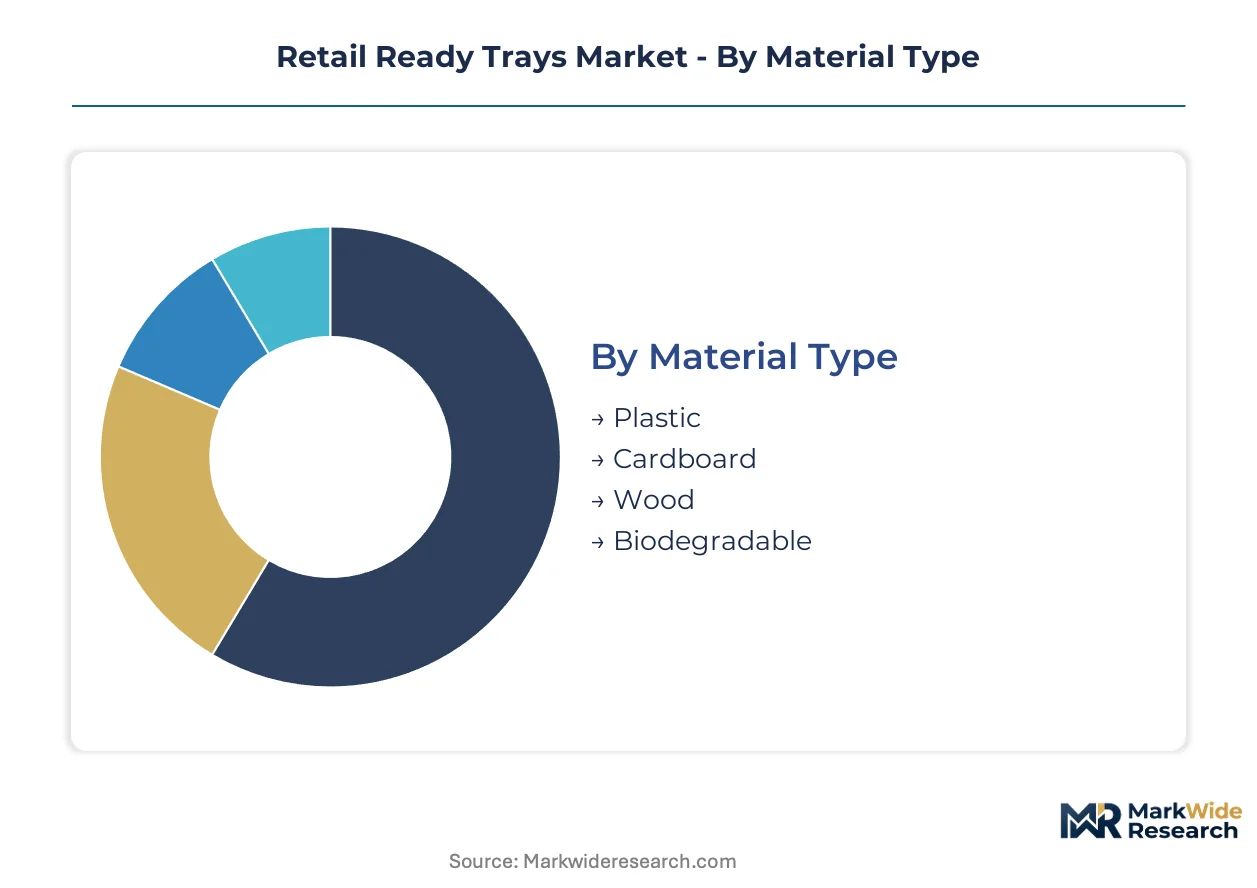
Retail ready trays serve divergent operational requirements across grocery supply chains, from automated stocking systems demanding dimensional precision to chilled distribution networks requiring thermal performance. Material selection and design configuration directly determine placement in high-velocity supermarket categories versus specialized food service applications.
Material Type:
Margin pools concentrate in barrier-coated fiber grades that satisfy EU Packaging and Packaging Waste Regulation compliance timelines while maintaining cost parity with legacy plastics.
- Plastic:Thermoformed PET and polypropylene variants retain moisture-barrier superiority for wet produce applications. German berry distributors specify these formats where fiber-based alternatives face technical ceilings, though petroleum-plastic phase-out deadlines are compressing procurement windows.
- Cardboard:Corrugated fiberboard dominates volume through established recycling infrastructure and cost efficiency. Smurfit Kappa and Mondi Group anchor European supply with integrated containerboard networks controlling fiber input costs for standardized supermarket formats.
- Wood:Pallet-compatible wooden trays serve bulk produce handling in wholesale channels where returnable logistics reduce per-trip packaging expenditure. Limited adoption in automated retail environments due to weight and dimensional inconsistency.
- Biodegradable:Molded pulp and PLA compounds attract reformulation investment as French AGEC law mandates plastic reduction trajectories. Pilot deployments in Dutch cut-vegetable applications test commercial viability against fiber-based alternatives.
The dominant share belongs to Cardboard, while Biodegradable is closing the gap fastest.
End User:
Procurement authority concentrates in centralized buying desks that consolidate supplier rosters and collapse margins through e-sourcing transparency.
- Supermarkets:German retail chains mandate standardized tray dimensions for robotic shelf-replenishment systems, forcing format convergence across supplier bases. Tear-away perforations and display-ready graphics command premium positioning in produce departments where visual merchandising drives purchase decisions.
- Convenience Stores:Smaller format requirements favor collapsible and lightweight configurations for limited backroom storage. Polish and Czech Republic discount chains are adopting Western European shelf-ready standards, opening specification windows for tray converters.
- Wholesalers:Volume-driven procurement prioritizes stackability and pallet efficiency over display aesthetics. Wooden and heavy-duty corrugated formats dominate this channel where returnable logistics reduce per-unit packaging costs.
- Food Service:Chilled ready-meal distributors require thermal-insulated tray walls with integrated barrier coatings for protein protection. FDA food-contact notification delays for novel coatings freeze product launch schedules in this segment.
Supermarkets command the largest volume position, though Food Service is expanding most quickly as chilled distribution networks proliferate.
Packaging Type:
Functional differentiation separates commodity formats from value-added designs that protect product integrity through temperature-variable supply chains.
- Thermal:Insulated tray walls with integrated barrier coatings capture expanded placement in supermarket meat and dairy departments. These formats lead margin pools where chilled protein distribution demands precise temperature control through last-mile fulfillment.
- Ventilated:Perforated designs enable respiration for fresh produce applications, extending shelf life in berry and grape packaging where moisture management is critical. Limited penetration in automated stocking systems due to structural inconsistency.
- Standard:Basic corrugated configurations serve high-volume, low-margin categories where cost minimization overrides functional specialization. Price transparency through e-sourcing platforms has collapsed supplier margins to single-digit percentages.
- Customizable:Rapid prototyping capabilities and in-house structural design studios differentiate converters serving centralized procurement in Germany and the Netherlands. These formats bridge retail display and e-commerce grocery locker requirements.
Thermal formats hold the premium position, while Customizable is gaining share fastest as retail buying desks consolidate supplier relationships.
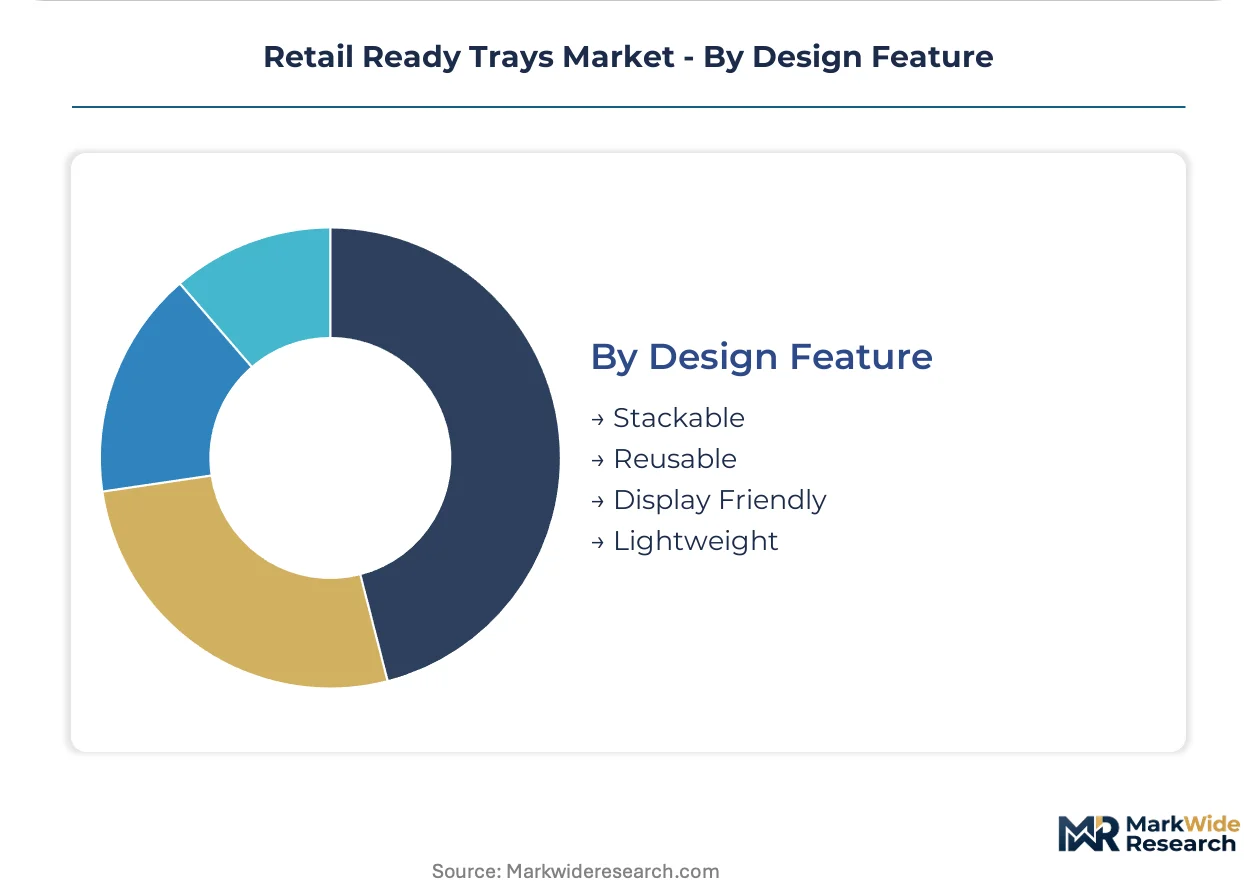
Design Feature:
Engineering priorities reflect tension between operational efficiency in distribution networks and merchandising effectiveness at point of sale.
- Stackable:Precision die-cut dimensions enable dense palletization and automated handling in high-volume distribution centers. Tooling concentration among German and Italian machinery suppliers creates supply risk for converters expanding capacity.
- Reusable:Collapsible formats serve e-commerce grocery lockers and returnable logistics networks where circular packaging models reduce regulatory exposure under extended producer responsibility frameworks. France's Citeo eco-modulation scheme rewards these designs with lower fee schedules.
- Display Friendly:Tear-away perforations and graphic-ready surfaces command premium positioning in supermarket produce departments. These features directly influence purchase decisions where visual merchandising replaces secondary handling.
- Lightweight:Mondi Group's kraftliner grades reduce per-unit shipping weights for grocery distributors, cutting freight expenditure in high-volume categories. OCC price volatility squeezes converter margins on these specifications.
Display Friendly dominates shelf placement, while Reusable is climbing the fastest as EPR frameworks shift end-of-life costs toward brand owners.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ECHA restrictions on solvent-based adhesives and the EU Packaging and Packaging Waste Regulation are compressing design cycles across European retail-ready tray supply chains, with German retail chains mandating standardized formats for automated stocking systems.
Germany
Robotic shelf-replenishment systems at Aldi and Lidl mandate precise tray dimensions, forcing format convergence across corrugated suppliers. The country's national packaging regulator enforces strict recyclability protocols under extended producer responsibility frameworks. The Rhine-Ruhr industrial corridor hosts precision die-cut perforation equipment suppliers that dominate tear-away feature tooling.
France
DGCCRF inspections under the AGEC anti-waste law mandate plastic reduction trajectories for packaged goods, accelerating fiber-based tray adoption. The Citeo eco-modulation scheme rewards fiber packaging with lower fee schedules than plastic equivalents. The Île-de-France region concentrates chilled ready-meal distributors reformulating toward solid bleached sulfate substrates.
Netherlands
Dutch supermarket groups pilot water-based barrier coatings with oxygen-scavenging functionality for cut-vegetable applications. The country's environmental agency enforces stringent sorting protocol certifications for shelf placement retention. Rotterdam-Antwerp port logistics clusters handle imported kraftliner grades for lightweight tray production.
Poland
Discount grocery chains modernize toward Western European shelf-ready standards, opening specification windows for tray converters. The national environmental inspectorate aligns enforcement with EU Packaging and Packaging Waste Regulation compliance timelines. The Warsaw-Łódź manufacturing belt attracts capacity expansion from integrated containerboard producers.
United States
FDA food-contact notification delays for novel barrier coatings freeze protein tray product launch schedules across chilled distribution networks. The agency's 12-18 month approval timelines create regulatory friction for reformulation investment. High-volume folding carton facilities in the Southeast and Midwest anchor North American production optimized for club-store specifications.
Retail Ready Trays Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the retail-ready trays market. Integrated pulp-and-paper producers control fiber input costs and captive supply chains, while specialized converters compete on rapid prototyping and structural design capabilities. The competitive terrain separates into three strategic archetypes: integrated containerboard networks, precision die-cut specialists, and barrier-coating innovators. Dominant competitive moves include backward integration into containerboard production and geographic expansion into Central European modern trade markets.
Among Ireland-based integrated producers, Smurfit Kappa exemplifies the containerboard network archetype through upstream control over fiber supply. Georgia-headquartered WestRock Company occupies a position at the scale-driven end of North American production. Austrian Mondi Group represents lightweight kraftliner specialization that reduces per-unit shipping weights for grocery distributors.
| Leading Market Players |
|---|
| Smurfit Kappa |
| WestRock Company |
| DS Smith |
| International Paper |
| Delkor Systems |
| Evolution Group |
| Lawrence Paper Company |
| Mondi Group |
| Green Bay Packaging |
| Others |
Value Network & Pricing Analysis
Long-term offtake contracts between German retail chains and integrated containerboard producers lock in fiber supply access while compressing price visibility for spot-market buyers. These arrangements concentrate purchasing power among Aldi and Lidl procurement desks, squeezing margin buffers for converters without captive pulp supply.
Pricing Analysis
German tray specifications command 15-20% premiums over Polish and Czech Republic equivalents due to precision die-cut tolerances for robotic stocking systems. Three-tier pricing structure across premium thermal-insulated, standard corrugated, and economy lightweight grades separates converters by barrier-coating certification and structural design capability. Cost compression in standard formats is intensifying because e-sourcing platforms collapsed supplier margins to single-digit percentages. Discount grocery chains in Central Europe exhibit highest price sensitivity, while chilled ready-meal distributors prioritize thermal performance over unit cost.
Supply Chain Analysis
Strategic stockpiling of Old Corrugated Container bales dominates inventory strategy among Rhine-Ruhr industrial corridor mills, buffering against municipal collection rate volatility. Supply concentrates in Germany, Poland, and the Netherlands, with integrated producers drawing from captive Scandinavian kraftliner sources. Raw material dependencies center on OCC fiber streams, water-based adhesive formulations, and precision perforation tooling from Italian machinery suppliers. Single-source vulnerability concentrates in tear-away feature die-cut equipment, where German and Italian vendors control 80% of installed base. Distribution runs through centralized retail procurement hubs in Düsseldorf and Rotterdam before last-mile deployment to automated distribution centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Retail ready trays function as a platform economy where standardized dimensions enable interoperability across robotic stocking systems, creating winner-take-most dynamics for format owners. This interoperability shift rewards early movers who capture specification authority with German retail chains.
For Market Incumbents: Fortify upstream fiber control through backward integration into containerboard production or long-term Scandinavian kraftliner offtakes. Incumbent converters must lock in rapid prototyping capabilities and in-house structural design studios to defend against buying desk consolidation that collapses approved vendor rosters from twelve to four per category. Capacity addition in Poland and Czech Republic manufacturing belts captures modern trade expansion while insulating margin exposure to German price compression. For New Entrants and Emerging Players: E-commerce grocery locker formats represent a service-layer gap where incumbents under-serve collapsible, returnable tray requirements bridging retail display and home delivery. New entrants should target Polish discount chain specifications as the most penetrable geography, where Western European shelf-ready standards are newly mandated but local converter capacity lags demand. A direct-to-retailer technical sales model bypasses entrenched distributor relationships blocking specification access. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors precision die-cut specialists with barrier-coating innovation pipelines over commodity corrugated producers. Long-term viability across the analysis window hinges on regulatory compliance timing rather than volume scale, positioning integrated pulp-and-paper networks with water-based coating R&D as preferred acquisition targets. The signal to watch is FDA food-contact notification approval velocity for novel oxygen-scavenging formulations, which unlocks chilled protein segment expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Barrier Coating R&D Investment | FDA notification approvals for oxygen-scavenging formulations unlock chilled ready-meal placement. |
| Precision Die-Cut Capacity Expansion | Robotic stocking mandates at Aldi and Lidl require dimensional tolerances unattainable by generalist converters. |
| Central European Manufacturing Footprint | Polish and Czech Republic modern trade adoption creates specification windows before local capacity saturates. |
| Water-Based Adhesive Transition | ECHA REACH compliance eliminates solvent-based bonding alternatives, favoring early reformulation adopters. |
| Extended Producer Responsibility Positioning | France's Citeo eco-modulation scheme rewards fiber-based formats with lower fee schedules than plastics. |
Research Methodology
A spread of perspectives from corrugated plant managers, retail category buyers, packaging structural designers, and barrier-coating R&D directors converged on the working assumptions around format standardization timelines. Primary interviews with these stakeholders combined with secondary validation from EU Packaging and Packaging Waste Regulation filings, ECHA REACH restriction updates, and retail procurement database tracking. Customs records of kraftliner grade imports and containerboard mill capacity announcements provided supply-side triangulation against bottom-up demand estimates from supermarket automated stocking deployment schedules.
Segmentation dimensions modeled include material type, end-user channel, packaging functionality, and design feature configuration across the projection horizon. CAGRs were derived from installed base growth of robotic shelf-replenishment systems, plastic phase-out deadline enforcement patterns, and chilled distribution network expansion trajectories. Industry-specific forecast inputs incorporated EPR fee schedule differentials and FDA food-contact notification approval pipelines.
Underlying assumptions cover regulatory enforcement consistency, fiber input cost stability, and automated stocking technology adoption curves, with deviation risk concentrated in OCC price volatility and precision tooling supply bottlenecks. Revision becomes warranted when EU member state transposition timelines for packaging waste regulations diverge materially from harmonized schedules.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Retail Packaging
Black Friday Packaging Market
Retail Packaging
Club Store Packaging Market
Retail Packaging
Table Tent Market
Retail Packaging
Retail E Commerce Packaging Market
Retail Packaging
Floor POP Display Market
Retail Packaging
Global Shoe Packaging Market
Retail Packaging
Free Standing Display Units Market
Retail Packaging
Retail Ready Packaging (RRP) Market
Retail Packaging
Retail Bags Market