
 Global Shoe Packaging Market | 2026-2036
Global Shoe Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Global Shoe Packaging Market Outlook
Premium-grade rigid box specifications is unwinding cost structures across the shoe packaging value chain as brands trade up from corrugated alternatives. Smurfit Kappa leverages its European containerboard network to supply coated kraft solutions for luxury footwear houses. Mondi Group anchors its position through integrated pulp-to-box operations in Central Europe. Elevate Packaging specializes in compostable films that replace petroleum-based windows in retail shoe boxes.
Shoe packaging denotes engineered enclosures—typically folding cartons, rigid set-up boxes, or flexible pouches fabricated from paperboard, polyethylene terephthalate, or polylactic acid blends—designed to protect footwear from compression, moisture, and contamination during distribution while serving as a retail presentation surface. Corrugated fiberboard dominates volume production due to its crush resistance and printability, though biodegradable substrates gain traction where landfill diversion mandates apply. Boxes capture the largest value share within packaging type segments, yet biodegradable material formulations expand fastest as regulatory deadlines for recyclability approach. E-commerce end users drive structural demand for ship-ready formats that eliminate secondary overboxing, compressing margin pools toward dual-use retail-shipping designs.
The US EPA guides recycled content thresholds for paper-based packaging through Comprehensive Procurement Guidelines, while the EU Packaging and Packaging Waste Regulation imposes extended producer responsibility fees that alter material selection economics. China's SAMR enforces GB standards for food-contact-grade adhesives that also constrain footwear packaging chemistry where cross-contamination risks exist. Stakeholders must monitor how divergent recyclability certification schemes across California, Germany, and Japan fragment compliance architecture and force regional SKU proliferation.
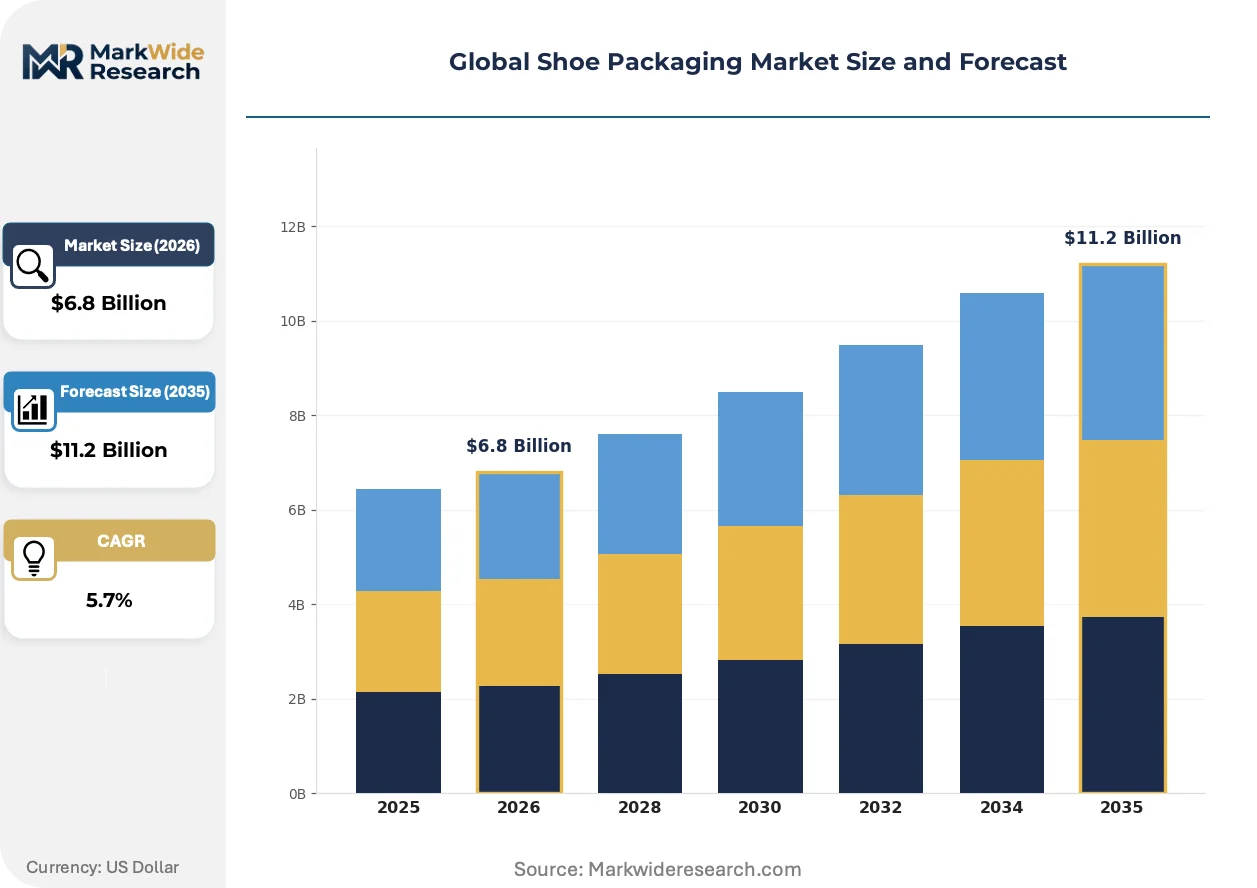
Market Dynamics
The EU Packaging and Packaging Waste Regulation is compressing material selection windows across European supply chains, forcing converters to recertify substrates ahead of 2030 recyclability deadlines while athletic brands simultaneously spec rigid magnetic-closure boxes that carry 40-60% cost premiums over corrugated alternatives.
Growth Catalysts
- Extended Producer Responsibility mandates:The EU Packaging and Packaging Waste Regulation imposes modulated fees that reward recycled content, pulling converters toward certified post-consumer paperboard streams.
- E-commerce ship-ready formats:Direct-to-consumer footwear volumes demand dual-use retail-shipping designs that eliminate secondary overboxing, collapsing two packaging tiers into one bill of materials.
- Biodegradable window films:Polylactic acid and cellulose-based transparent substrates replace petroleum-derived PVC and PET in luxury shoe box windows where landfill diversion mandates apply.
Market Restraints
- Pulp price volatility:Northern bleached softwood kraft pulp contracts swing on energy costs and Nordic mill outages, compressing converter margins on fixed-price annual supply agreements.
- Adhesive chemistry constraints:China's SAMR enforces GB standards for food-contact-grade adhesives that constrain footwear packaging formulations where cross-contamination risks trigger conservative compliance interpretations.
- Recyclability certification fragmentation:Divergent schemes across California's SB 54, Germany's Dual System, and Japan's Container and Packaging Recycling Law force regional SKU proliferation that dilutes scale economies.
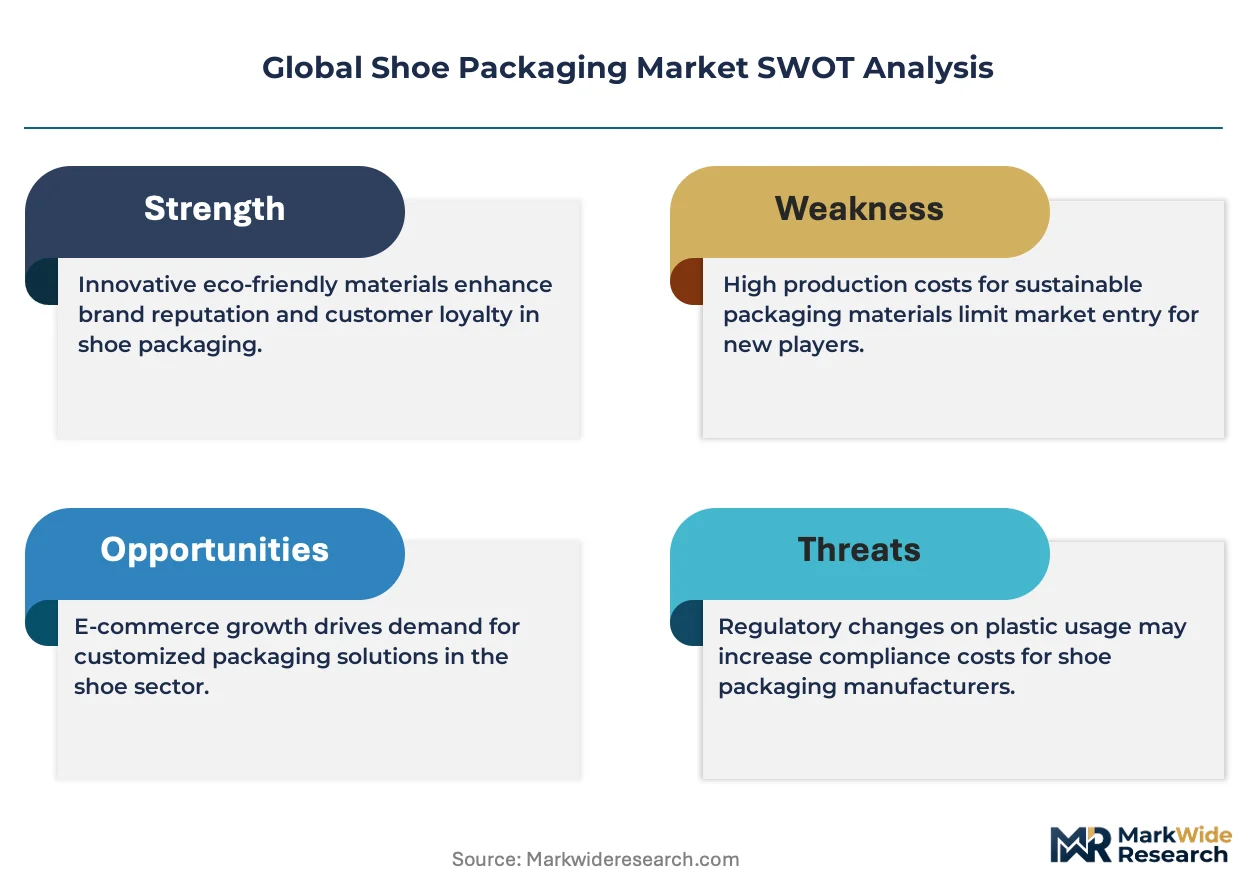
Strategic Opportunities
- Underpenetrated Indian formal footwear:Bata India and Metro Brands are expanding retail footprints, creating demand for printed folding cartons that domestic converters currently underserve with imported substrates.
- Magnetic closure automation:Precision tape-application equipment from Italian and German suppliers enables mid-tier brands to access premium unboxing mechanics previously reserved for luxury houses.
- Carbon border adjustment alignment:The EU Carbon Border Adjustment Mechanism creates competitive openings for packaging producers with verified low-carbon pulp sourcing to displace Asian competitors on European soil.
Industry Challenges
- Structural engineering talent scarcity:Packaging schools graduate fewer specialists in rigid box mechanics than converters require for athletic brand specifications, forcing in-house training programs.
- Legacy ERP integration with traceability platforms:Batch-level recycled content verification demands data architecture upgrades that many mid-tier converters have deferred.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Shoe Packaging Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Packaging Type: Boxes, Bags, Wraps, Inserts Material: Cardboard, Plastic, Biodegradable, Metal End User: Retailers, E-commerce, Wholesalers, Manufacturers Design: Custom, Standard, Eco-Friendly, Luxury |
| Companies Covered | WestRock, Smurfit Kappa, Mondi Group, DS Smith, International Paper, Stora Enso, Elevate Packaging, Packman Packaging, Great Little Box Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Shoe Packaging Market Strategic Shifts
Material science breakthroughs and regulatory chemistry constraints are actively rewiring substrate hierarchies across footwear packaging, compressing adoption cycles for bio-based alternatives while digital print technologies collapse minimum order quantities.
Polylactic acid blended with thermoplastic starch is decomposing the petroleum-based window film monopoly in premium shoe packaging. Luxury athletic brands including On Running and Allbirds specify these transparent substrates for seasonal limited editions. The technology is decomposing the traditional PVC/PET supply base by enabling home-compostable claims that satisfy California SB 54 and EU Single-Use Plastics Directive interpretations.
REACH Annex XVII restrictions on per- and polyfluoroalkyl substances are eliminating grease-resistant coatings from paperboard intended for European markets. Converters must validate alternative barrier technologies—siliconized papers and clay coatings—through migration testing protocols. Athletic footwear with outdoor positioning faces the steepest reformulation path as mud-resistant box exteriors lose their fluorochemical treatments.
Brand-led packaging-as-content strategies are collapsing the traditional wholesale-retail specification split. Nike and Adidas now brief single designs for both DTC unboxing videos and wholesale floor display, eliminating the parallel SKU structures that previously separated channels. This consolidation is most visible in North American and Western European markets where influencer marketing budgets exceed traditional point-of-sale material allocations.
Global Shoe Packaging Market Segmentation
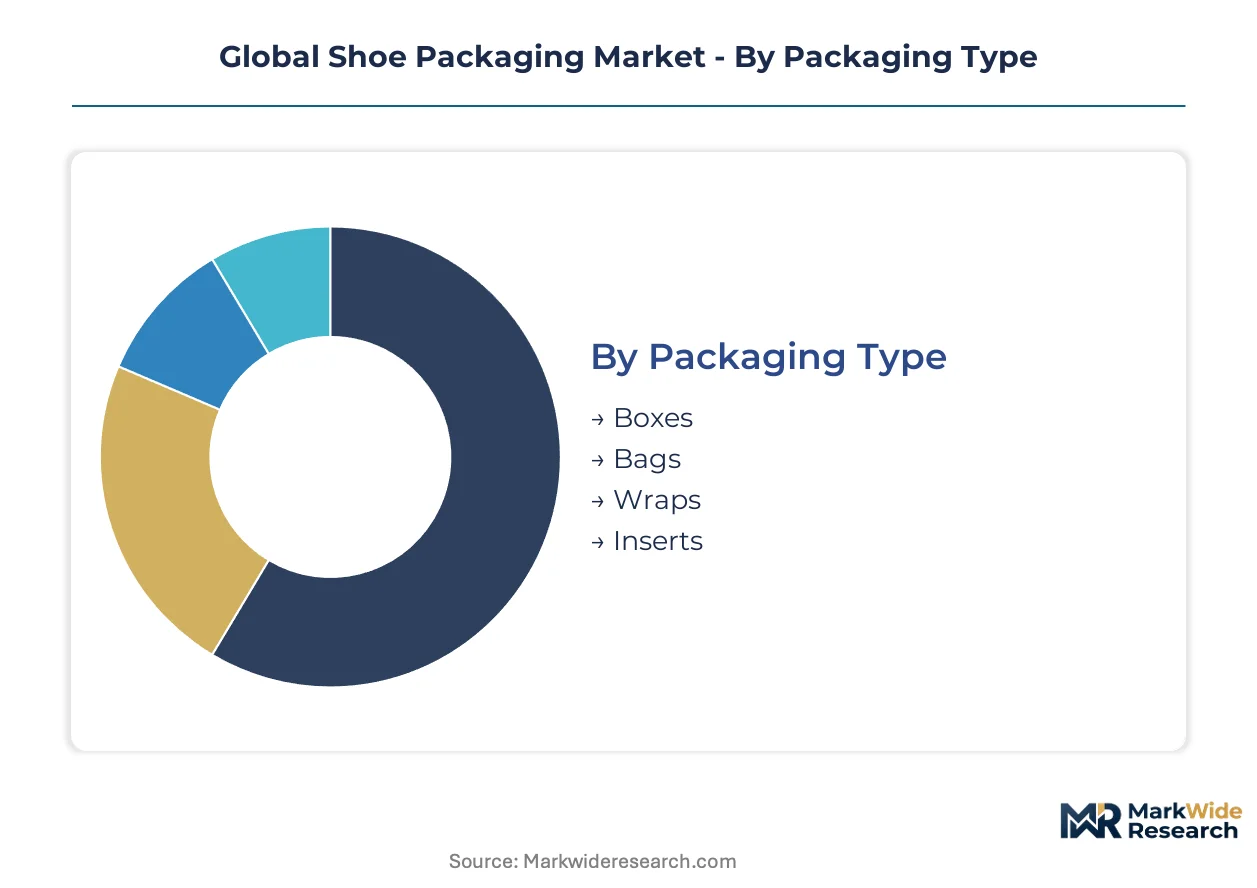
Shoe packaging procurement flows through distinct channel hierarchies that reshape specification requirements. Athletic brands source rigid magnetic-closure boxes for flagship retail while e-commerce operators compress dual-use retail-shipping designs into unified material bills.
Packaging Type:
Channel mix determines structural specifications: wholesale floors demand presentation-grade rigidity while direct-to-consumer shipments prioritize crush resistance and dimensional efficiency.
- Boxes:Rigid set-up constructions with recycled paperboard cores dominate premium athletic brand specifications. Wholesale retail channels in Germany and Japan pull magnetic-closure designs from European converters. E-commerce penetration is collapsing traditional retail-wholesale SKU splits into unified ship-ready formats.
- Bags:Non-woven polypropylene and cotton drawstring enclosures serve value-tier footwear distribution. Indian formal footwear retailers source printed folding cartons from domestic converters with imported substrates. Biodegradable alternatives gain regulatory traction where EU Packaging and Packaging Waste Regulation fees apply.
- Wraps:Tissue and kraft paper layers protect against scuffing during bulk transport.
- Inserts:Molded pulp and corrugated fiberboard structures prevent compression damage in stacked containers.
By volume, Boxes leads. By growth pace, Inserts is ahead as ship-ready specifications demand integrated protection.
Material:
Cost tier stratification separates commodity procurement from certified sustainable streams that command measurable premiums.
- Cardboard:Coated unbleached kraft and solid bleached sulfate grades anchor volume production. Smurfit Kappa's European containerboard network supplies luxury footwear houses with calibrated stiffness specifications. Pulp price volatility on Nordic mill outages compresses converter margins under annual fixed-price agreements.
- Biodegradable:Polylactic acid blended with thermoplastic starch decomposes petroleum-based window film monopolies. On Running and Allbirds specify these transparent substrates for seasonal limited editions. California SB 54 and EU Single-Use Plastics Directive interpretations accelerate adoption.
- Plastic:Polyethylene terephthalate and polyvinyl chloride retain share in moisture barrier applications.
- Metal:Tinplate and aluminum closures serve collectible and gift-box positioning in luxury segments.
By volume, Cardboard leads. By growth pace, Biodegradable is expanding most quickly as regulatory deadlines approach.
End User:
Customer type determines order quantity thresholds and customization depth, with manufacturers pulling standard formats while retailers demand printed differentiation.
- E-commerce:Direct-to-consumer volumes demand dual-use retail-shipping designs that eliminate secondary overboxing. Nike and Adidas brief single specifications for both unboxing videos and wholesale floor display. North American and Western European markets show the clearest channel consolidation.
- Retailers:Department stores and specialty footwear chains require presentation-grade finishing with seasonal graphic rotations. Bata India and Metro Brands are expanding retail footprints, creating demand that domestic Indian converters currently underserve.
- Wholesalers:Bulk distribution channels prioritize unit cost over aesthetic specification.
- Manufacturers:Factory-direct procurement of standard corrugated formats for initial product protection.
By volume, Retailers leads. By growth pace, E-commerce is climbing the fastest as influencer marketing budgets redirect point-of-sale material allocations.
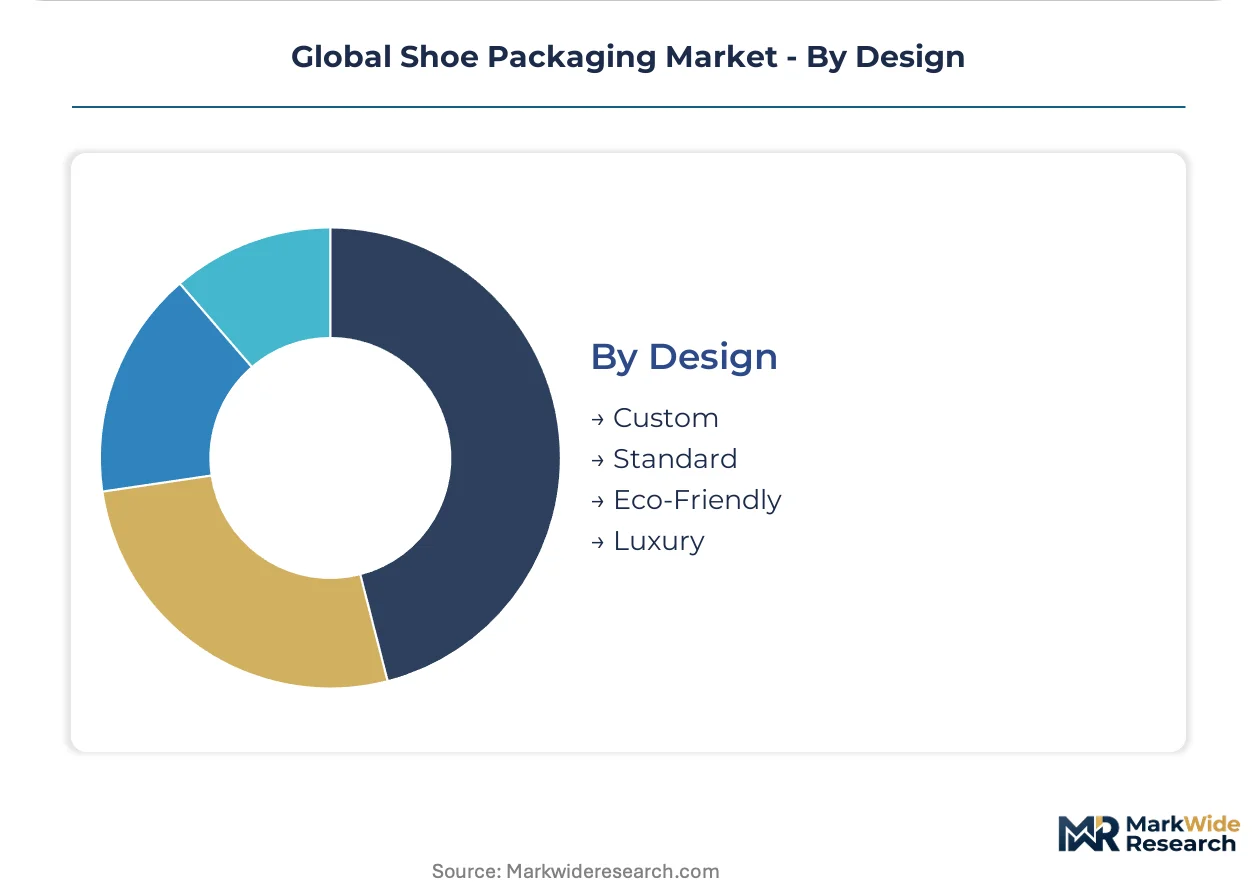
Design:
Application context separates utilitarian protection from content-capture strategies that feed social media distribution.
- Custom:Brand-specific dimensional engineering accommodates sole geometries and accessory compartments. Precision tape-application equipment from Italian and German suppliers enables mid-tier brands to access premium unboxing mechanics. Magnetic closure automation is displacing hand-finished luxury production.
- Eco-Friendly:Home-compostable claims require substrate validation through migration testing protocols. REACH Annex XVII restrictions on per- and polyfluoroalkyl substances eliminate grease-resistant coatings from European-market paperboard. Clay coatings and siliconized papers serve as barrier alternatives.
- Standard:Generic folding carton specifications serve undifferentiated volume production.
- Luxury:Rigid constructions with foil stamping and embossed logos target gift and collectible positioning.
By volume, Standard leads. By growth pace, Eco-Friendly is gaining share fastest as modulated fees reward recycled content verification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Footwear manufacturing clusters in China, Vietnam, and Indonesia pull packaging procurement toward Southeast Asian production corridors. European converters face recertification deadlines under tightened material compliance rules. North American brands demand ship-ready formats that collapse retail-shipping tiers.
China
GB standards enforced by SAMR constrain adhesive chemistry in export-bound packaging. The Yangtze River Delta concentration of footwear factories generates pull-through demand for coated kraft specifications. Zhejiang and Guangdong provinces host integrated pulp-to-box operations serving premium athletic brand contracts.
Germany
Dual System fees under the EU Packaging and Packaging Waste Regulation alter material selection economics for converters. REACH Annex XVII restrictions on per- and polyfluoroalkyl substances eliminate grease-resistant coatings from paperboard formulations. The North Rhine-Westphalia packaging belt supplies magnetic-closure rigid boxes to luxury footwear houses.
United States
EPA Comprehensive Procurement Guidelines guide recycled content thresholds for paper-based packaging. California SB 54 recyclability certification requirements fragment compliance architecture against federal standards. The Pacific Northwest pulp and paper corridor supplies containerboard to West Coast footwear distribution hubs.
Vietnam
Footwear export growth from Ho Chi Minh City and Binh Duong industrial zones drives demand for corrugated ship-ready formats. Domestic converters import coated substrates from regional suppliers to meet athletic brand specifications. The government pushes packaging localization to reduce import dependency.
India
Bata India and Metro Brands expand retail footprints, creating demand that domestic converters underserve with imported substrates. BIS standards govern paperboard quality specifications for formal footwear packaging. Maharashtra and Gujarat industrial corridors attract investment in folding carton capacity.
Global Shoe Packaging Market Competitive Environment
Concentration sits with integrated European containerboard networks and specialized biodegradable film producers. The market structure shows tiered competition between multinational paperboard conglomerates, regional rigid box specialists, and emerging compostable substrate innovators. Two strategic archetypes dominate: integrated pulp-to-box operators leveraging captive fiber supply, and precision converters deploying automated magnetic-closure equipment. Competitive moves center on recycled content certification acquisition and dual-use retail-shipping format development.
Among integrated paperboard suppliers, Smurfit Kappa and Mondi Group exemplify the European containerboard archetype with calibrated stiffness specifications for luxury footwear houses. Elevate Packaging occupies a position within the biodegradable specialization tier, representing compostable film alternatives to petroleum-based window substrates. These three companies anchor the competitive map across distinct capability vectors—integrated fiber supply, continental distribution density, and material science innovation—without overlapping positioning.
| Leading Market Players |
|---|
| WestRock |
| Smurfit Kappa |
| Mondi Group |
| DS Smith |
| International Paper |
| Stora Enso |
| Elevate Packaging |
| Packman Packaging |
| Great Little Box Company |
| Others |
Value Chain & Pricing Dynamics
EU Packaging and Packaging Waste Regulation modulated fees gate both substrate qualification and price differentiation simultaneously, forcing converters to absorb certification costs while athletic brands extract premiums for magnetic-closure rigid boxes. Cost compression in corrugated tiers intensifies because pulp contract volatility on Nordic mill outages squeezes fixed-price annual agreements.
Pricing Analysis
EU Packaging and Packaging Waste Regulation dictates the pricing tier structure across European supply chains, segmenting procurement into certified post-consumer paperboard streams versus virgin fiber alternatives. Three-tier pricing structure across premium, standard, and economy levels separates rigid magnetic-closure specifications from coated folding cartons and unprinted corrugated bulk formats. Pricing pressure stems from e-commerce brands collapsing retail-shipping tiers into single-format bills of materials. Wholesalers exhibit highest price sensitivity due to volume procurement and minimal customization requirements, while luxury athletic houses accept substantial premiums for unboxing mechanics.
Supply Chain Analysis
Port congestion on Asia-Europe trade lanes elevates inbound logistics costs for coated kraft substrates imported to Southeast Asian footwear manufacturing clusters. Supply concentrates in China, Vietnam, and Indonesia, drawing from Northern bleached softwood kraft pulp contracts, polylactic acid resin streams, and magnetic closure hardware from Italian equipment suppliers. Single-source vulnerability sits with Nordic pulp mills supplying stiffness-calibrated grades to luxury footwear houses. Distribution runs through converter networks anchored in Zhejiang and Guangdong provinces, with European rigid box specialists serving German and Japanese retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized talent in rigid box structural engineering has become the constraining asset, with packaging schools graduating fewer specialists than converters require for athletic brand specifications. This capability gap widens as magnetic-closure automation demands precision mechanics expertise.
For Market Incumbents: Shield margin pools by securing captive pulp supply through backward integration into Nordic fiber streams or long-term offtake agreements with bleached kraft mills. Accelerate ERP upgrades for batch-level recycled content verification before EU recertification deadlines fragment compliance architecture further. For New Entrants and Emerging Players: Anchor in Indian formal footwear packaging, where Bata India and Metro Brands expand retail footprints faster than domestic converters can deploy folding carton capacity with imported substrates. Target magnetic-closure automation services for mid-tier athletic brands seeking premium unboxing mechanics without hand-finished production costs. For Investors and Strategic Acquirers: EU Packaging and Packaging Waste Regulation 2030 recyclability deadlines reshape the acquisition landscape toward converters with verified low-carbon pulp sourcing and integrated pulp-to-box operations. Long-term viability favors targets with dual-use retail-shipping format capabilities and established certification relationships. Watch for divergence between California SB 54 and EU recyclability standards as the signal for regional SKU proliferation risk.| Strategic Initiative | Industry Significance |
|---|---|
| Recycled Content Certification Investment | EU modulated fees reward post-consumer paperboard streams, altering material economics for converters. |
| Magnetic Closure Automation Deployment | Italian and German precision equipment enables mid-tier brands to access premium unboxing mechanics. |
| Dual-Use Retail-Shipping Format Development | Nike and Adidas brief single designs for DTC unboxing videos and wholesale floor display. |
| Low-Carbon Pulp Sourcing Verification | EU Carbon Border Adjustment Mechanism creates openings to displace Asian competitors on European soil. |
| Compostable Window Film Scale-Up | Polylactic acid blends from Elevate Packaging replace petroleum-based substrates for California and EU compliance. |
Study Parameters
A spread of perspectives from packaging converters, brand sustainability officers, pulp procurement managers, and rigid box structural engineers converged on the working assumptions underlying this analysis. Primary fieldwork combined with secondary validation from customs trade records, SEC filings of integrated paperboard suppliers, EPA Comprehensive Procurement Guidelines documentation, and EU Packaging and Packaging Waste Regulation impact assessments. Bottom-up volume modeling triangulated against top-down value estimates across substrate tiers and end-use channels.
Segmentation dimensions modeled include packaging type, material formulation, end-user channel, and design specification across the projection horizon. CAGRs derived from elasticity-adjusted demand curves incorporating e-commerce penetration rates, regulatory fee schedules, and pulp price volatility indices. Industry-specific inputs encompass magnetic-closure equipment deployment timelines and biodegradable film migration testing protocols.
Underlying assumptions cover sustained EU regulatory enforcement, stable Asia-Europe containerized freight rates, and continued athletic brand preference for rigid presentation formats, with deviation risk concentrated in pulp mill outage frequency and divergent recyclability certification schemes. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Retail Packaging
Retail E Commerce Packaging Market
Retail Packaging
Retail Ready Trays Market
Retail Packaging
Retail Ready Packaging (RRP) Market
Retail Packaging
Floor POP Display Market
Retail Packaging
Retail Bags Market
Retail Packaging
Club Store Packaging Market
Retail Packaging
Black Friday Packaging Market
Retail Packaging
Table Tent Market
Retail Packaging
Free Standing Display Units Market