
 Table Tent Market | 2026-2036
Table Tent Market Size, Share, and Industry Trends Forecast 2026-2036
Table Tent Market Insights
Digital print-on-demand integration is reconfiguring how table tent manufacturers manage short-run customization and just-in-time fulfillment. Deflecto LLC leverages extensive North American distribution infrastructure to sustain rapid turnaround capabilities for hospitality clients. Azar Displays anchors its position through deep product specialization in acrylic and PVC fabrication. Displays2go competes aggressively on catalog breadth, controlling online channel traffic for standard-format table tents.
A table tent is a freestanding, folded or molded display piece, typically constructed from cardstock, acrylic, PVC, or paperboard with die-cut or scored fold lines, designed to rest upright on flat surfaces for point-of-sale messaging, menu presentation, or promotional communication in hospitality and retail environments. Cardstock and acrylic material types dominate current volume, with acrylic commanding stronger margin pools in hotel and event segments where durability and aesthetic weight justify premium positioning. Custom size configurations and seasonal design customization represent the fastest-expanding demand categories, driven by restaurants and cafes seeking campaign-specific refresh cycles rather than static displays.
FDA guidelines on food-contact surface materials shape substrate selection for table tents deployed in US restaurant settings, while EPA standards on vinyl chloride emissions influence PVC manufacturing processes and facility compliance costs. The EU Green Deal and REACH chemical restrictions are redirecting European procurement toward recyclable paper and certified cardstock alternatives. Stakeholders must monitor how fragmented municipal recycling codes across multiple jurisdictions will reshape material specifications and supplier qualification requirements.
Market Dynamics
Digital print-on-demand integration is reconfiguring table tent procurement from bulk seasonal orders to campaign-specific, short-run fulfillment cycles. This shift compresses lead times and fragments supplier relationships across hospitality and retail channels.
Growth Catalysts
- QR-code menu integration:United States restaurants are expanding table tent deployment to bridge physical tabletop presence with digital ordering platforms and loyalty program enrollment.
- REACH chemical restrictions:European manufacturers are accelerating substrate innovation toward recyclable cardstock alternatives to preempt compliance deadlines and secure hospitality chain contracts.
- Acrylic fabrication specialization:German hotel and event segments are driving premium positioning for durable, aesthetically weighted displays with seasonal design refresh capabilities.
Market Restraints
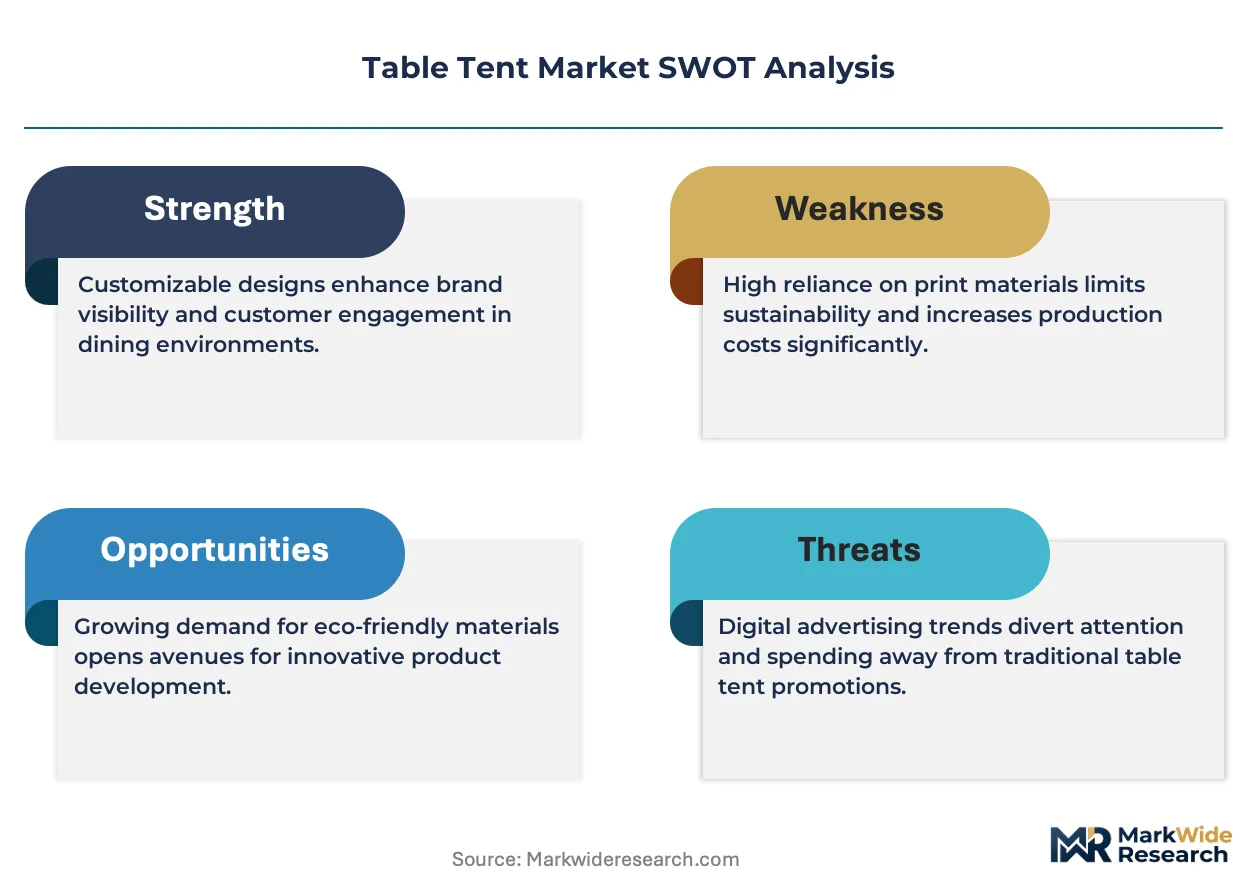
- Pulp and resin input volatility:Cardstock and acrylic raw material costs fluctuate with energy prices and forestry supply constraints, squeezing mid-tier manufacturer margins.
- Chinese acrylic substrate concentration:Premium display supply chains rely heavily on concentrated Asian petrochemical processing, exposing buyers to geopolitical freight disruption.
- Vinyl chloride emission standards:EPA facility compliance requirements elevate capital expenditure thresholds for PVC-based table tent production in domestic manufacturing.
Strategic Opportunities
- India hospitality expansion:Underpenetrated restaurant and cafe sectors in tier-2 Indian cities present white space for cardstock table tent standard-format penetration.
- EU Green Deal procurement mandates:Public sector hospitality and institutional catering contracts are prioritizing certified recyclable substrates, creating preferential supplier qualification pathways.
- Near-field communication convergence:Integration of NFC chips with traditional cardstock structures is enabling tap-to-order functionality without full digital display replacement.
Industry Challenges
- Short-run digital workflow reconfiguration:Traditional die-cutting and scoring equipment requires capital-intensive retrofitting to accommodate variable-data, on-demand production schedules.
- Fragmented municipal recycling code alignment:Suppliers must navigate incompatible substrate certification requirements across multiple North American and European jurisdictions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Table Tent Market |
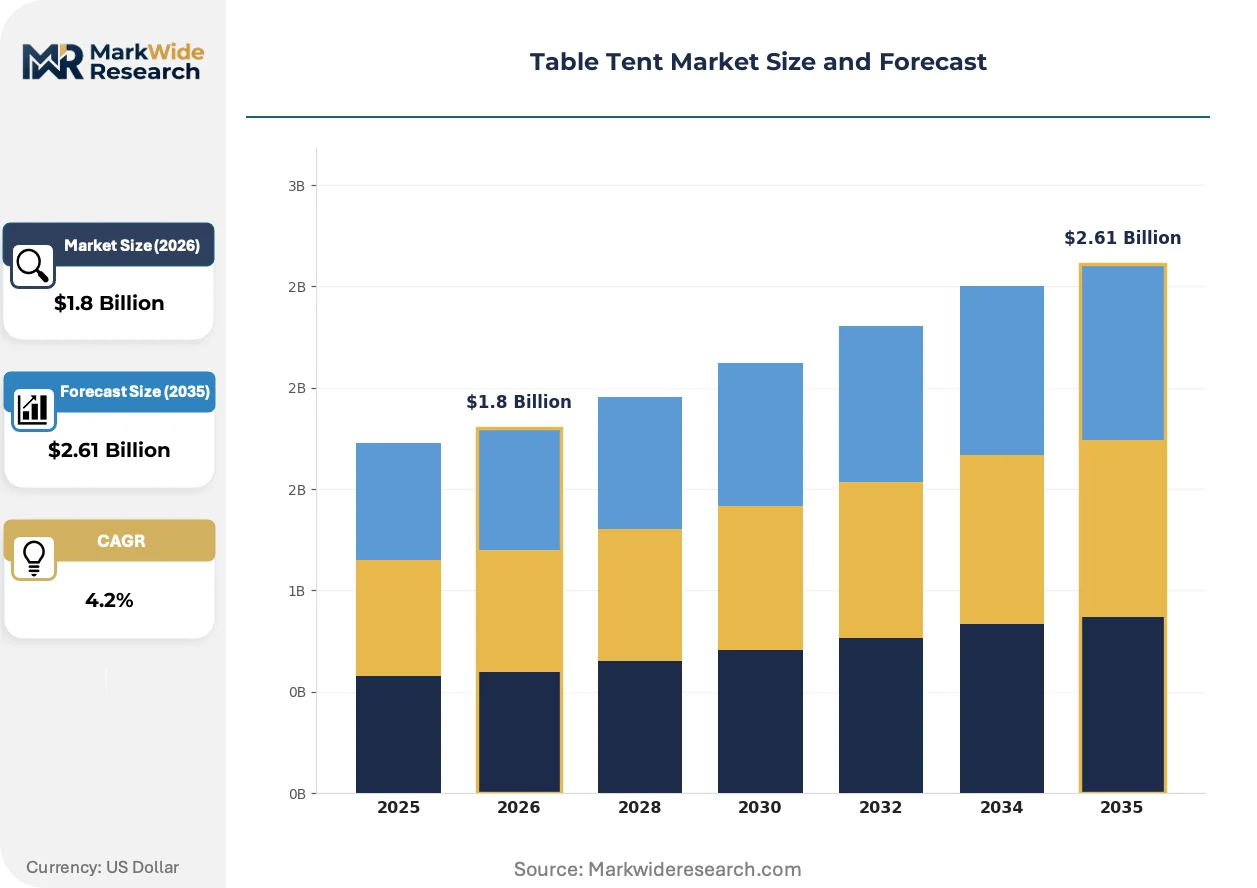
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.61 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: PVC, Cardstock, Acrylic, Paper Size: A4, A5, Square, Custom End User: Restaurants, Hotels, Events, Cafes Design Customization: No Customization, Standard Design, Personalized, Seasonal Themes |
| Companies Covered | Deflecto LLC, Azar Displays, Displays2go, Vispronet, AdirOffice, SourceOne, MyBinding, ShopPOPdisplays, Plastic Products Mfg, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Table Tent Market Trends and Innovations
Table tent production is pivoting from static, high-volume manufacturing to agile, data-driven fulfillment systems. Three convergent forces are reshaping competitive positioning: substrate virtualization, regulatory material redirection, and compressed procurement cycles.
Near-field communication (NFC) chip embedding is virtualizing the functional boundary between physical cardstock displays and digital transaction interfaces. Quick-service restaurant chains in the United States are piloting tap-to-pay and tap-to-menu capabilities in laminated cardstock tents. This convergence is virtualizing the traditional role of table tents as purely visual carriers, compressing the distinction between analog signage and interactive point-of-sale infrastructure.
The EU's Packaging and Packaging Waste Regulation is mandating extended producer responsibility frameworks for single-use display materials. European manufacturers must now document recyclability pathways and reduce virgin plastic content in acrylic and PVC substrates. German hospitality chains are responding by specifying FSC-certified cardstock and bio-based acrylic alternatives in procurement tenders, shifting supplier qualification criteria toward circular economy credentials.
Restaurant procurement departments are compressing refresh cycles from annual to quarterly campaign rotations. This behavioral shift fragments order volumes and elevates premium pricing for rapid-turnaround digital print services. United States hospitality groups are unbundling design, production, and fulfillment across multiple specialized vendors rather than consolidating with single-source suppliers, redistributing margin capture across the value chain.
Table Tent Market Segmentation
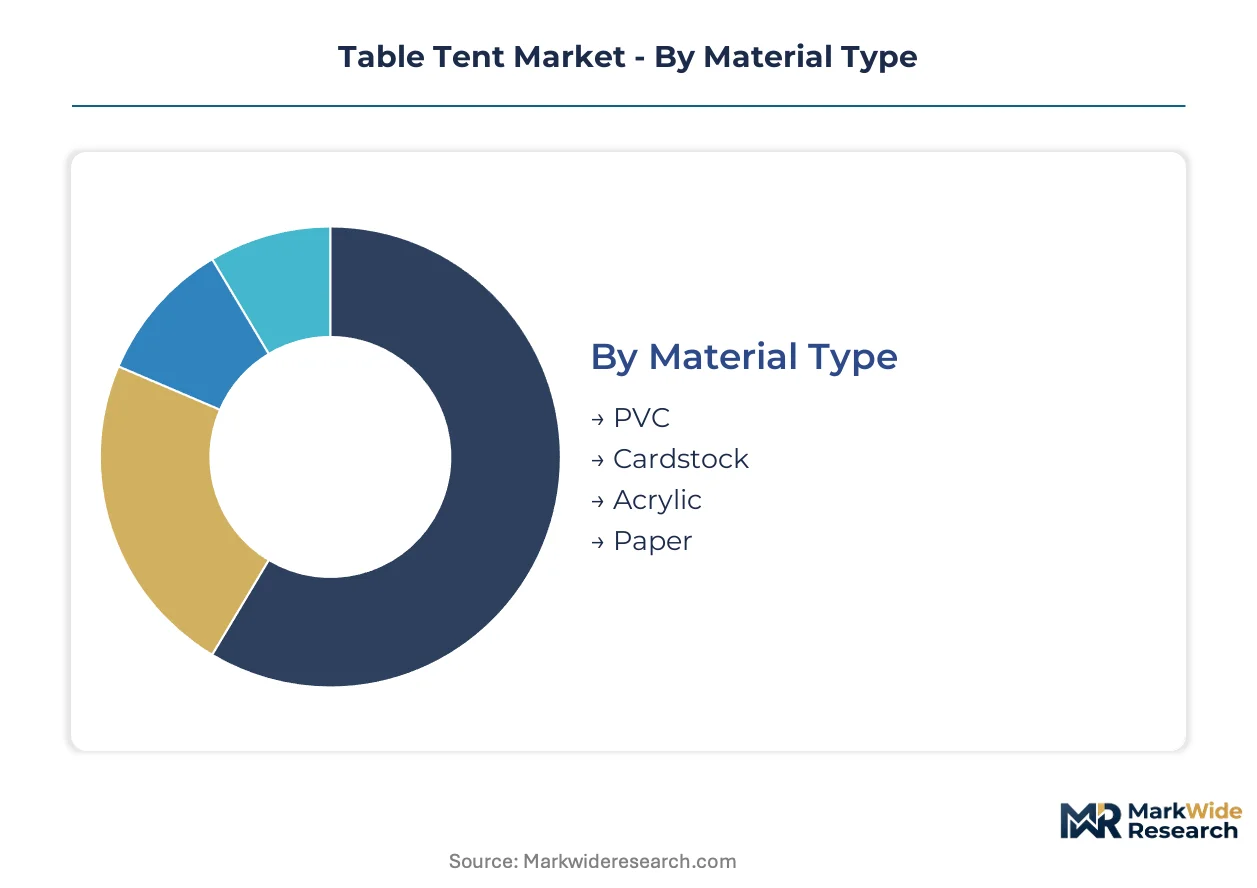
Table tent procurement patterns diverge sharply across material grades, format specifications, and end-use durability requirements. Understanding these segment boundaries enables suppliers to align substrate capabilities with specific hospitality workflows and campaign refresh cycles.
Material Type:
Cost tier stratification separates commodity substrates from engineered display materials with divergent margin structures.
- Cardstock:Folded paperboard with clay-coated or uncoated finishes, typically 12-24 pt thickness, supports single-use promotional cycles and QR-code integration. United States quick-service restaurants favor laminated cardstock for quarterly menu refreshes driven by digital ordering platform updates.
- Acrylic:Cast or extruded polymethyl methacrylate sheets, 2-5mm gauge, deliver optical clarity and impact resistance for premium positioning. German hotel chains specify acrylic for lobby and banquet displays where seasonal design customization justifies extended service life and aesthetic weight.
- PVC:Rigid vinyl extrusions offer weather resistance and dimensional stability for outdoor patio deployments.
- Paper:Lightweight uncoated or lightweight coated stocks serve ultra-short promotional windows and event-specific messaging.
Cardstock commands the established base. The steepest expansion runs through acrylic.
Size:
Application context determines format selection, with hospitality workflows dictating visibility distance and tabletop footprint constraints.
- Custom:Die-cut or digitally cut dimensions outside standard ISO formats enable brand-specific silhouettes and multi-panel configurations. United States casual dining chains deploy custom sizes for loyalty program enrollment displays sized to specific condiment caddy integrations.
- A5:Half-letter format balances messaging surface with minimal table intrusion for cafe and bistro settings.
- A4:Full-letter dimensions accommodate extensive menu listings and multi-language hospitality requirements.
- Square:Symmetrical formats suit social media campaign aesthetics and Instagram-optimized visual presentation.
A5 and A4 formats dominate current volume. Custom configurations are climbing the fastest as campaign-specific procurement fragments standard-format consolidation.
End User:
Customer type segmentation reveals divergent durability expectations and refresh cycle behaviors across hospitality subsectors.
- Restaurants:Full-service and quick-service operators deploy table tents for menu highlighting, upsell promotion, and digital platform bridging. United States restaurant procurement departments are compressing refresh cycles from annual to quarterly rotations as loyalty program enrollment and QR-code menu integration accelerate.
- Events:Temporary deployments for conferences, weddings, and corporate functions prioritize rapid production turnaround over extended durability.
- Hotels:Concierge, in-room dining, and banquet applications specify premium substrates with seasonal design customization capabilities.
- Cafes:High-turnover beverage-focused operations favor lightweight cardstock for frequent promotional rotation.
Restaurants anchor current demand concentration. Events and hotel segments are gaining share fastest through experience-economy expansion.
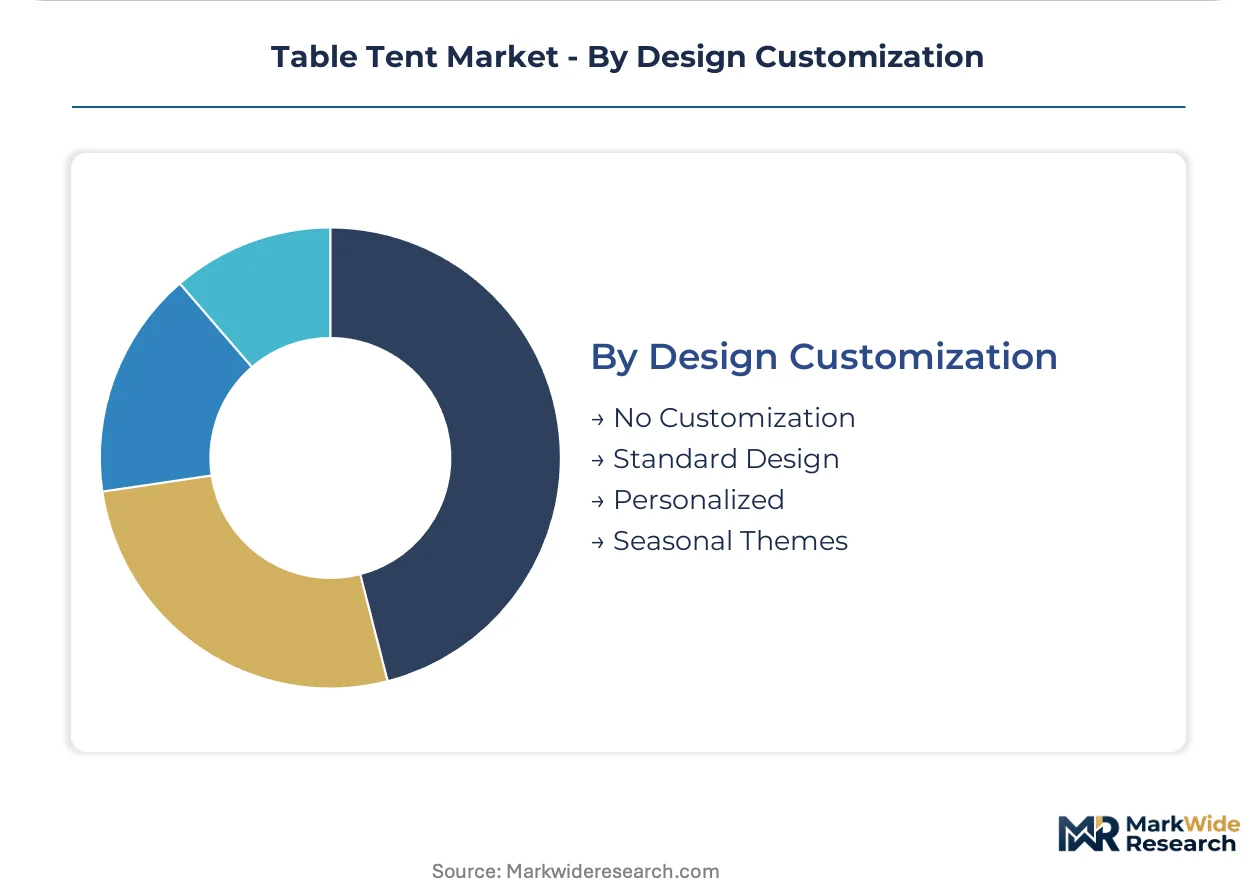
Design Customization:
Volume and maturity gradients separate static catalog offerings from agile, data-driven fulfillment systems.
- Seasonal Themes:Pre-designed template libraries with holiday, sporting event, and cultural calendar alignment enable rapid deployment without bespoke creative investment. German hospitality chains specify seasonal theme packages with acrylic substrate pairings for Oktoberfest, Christmas market, and summer terrace campaigns.
- Personalized:Variable-data printing incorporates specific venue names, localized pricing, or guest-specific messaging for franchise and multi-location operators.
- Standard Design:Catalog templates with limited color or logo substitution serve cost-sensitive procurement with minimal lead time.
- No Customization:Blank or generic pre-printed units for emergency replenishment or ultra-budget deployments.
Standard design captures the volume base. Seasonal themes and personalized tiers are expanding most quickly as digital print-on-demand integration reconfigures procurement workflows.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Restaurant procurement departments in the United States anchor buyer concentration, with German hospitality chains and Indian cafe operators expanding procurement volumes for campaign-specific display refresh cycles.
United States
Quick-service restaurant chains drive cardstock table tent procurement for QR-code menu integration and loyalty program enrollment displays. FDA guidelines on food-contact surface materials constrain substrate selection for tabletop deployments. Chicago and Dallas hospitality clusters concentrate demand for laminated cardstock with quarterly refresh cycles tied to digital platform updates.
Germany
Hotel and event segments specify premium acrylic displays with seasonal design customization for Oktoberfest and Christmas market campaigns. EU Green Deal procurement mandates redirect hospitality contracts toward FSC-certified cardstock and bio-based acrylic alternatives. Munich and Frankfurt procurement offices lead specification trends for durable, aesthetically weighted banquet displays.
India
Tier-2 city cafe and restaurant sectors present underpenetrated demand for standard-format cardstock table tents with rapid production turnaround. BIS certification requirements for imported display materials shape supplier qualification pathways. Bangalore and Hyderabad hospitality clusters are expanding procurement for promotional rotation in high-turnover beverage-focused operations.
China
Acrylic substrate manufacturing concentrates petrochemical processing capacity for premium display supply chains serving export markets. MEE environmental compliance standards elevate facility investment thresholds for PMMA extrusion operations. Guangdong and Zhejiang industrial zones dominate cast acrylic sheet production for hospitality display applications.
United Kingdom
Pub and casual dining chains deploy custom-size table tents for condiment caddy integration and localized loyalty program messaging. REACH chemical restrictions influence substrate selection toward recyclable paperboard alternatives. London and Manchester procurement departments are compressing refresh cycles from annual to quarterly campaign rotations.
Table Tent Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented procurement relationships. The vendor base separates into catalog-breadth operators, substrate-specialist fabricators, and digital-fulfillment integrators. Three strategic archetypes dominate: North American distribution-heavy incumbents, European premium-substrate specialists, and agile short-run digital printers. Competitive moves concentrate on geographic footprint expansion and digital workflow retrofitting for variable-data production.
Among North American incumbents, Deflecto LLC and Displays2go occupy positions spanning distribution infrastructure and online channel control. Azar Displays exemplifies the substrate-specialist archetype through acrylic and PVC fabrication concentration. These three companies represent the competitive tension between scale-driven catalog operators and material-specific fabrication expertise.
| Leading Market Players |
|---|
| Deflecto LLC |
| Azar Displays |
| Displays2go |
| Vispronet |
| AdirOffice |
| SourceOne |
| MyBinding |
| ShopPOPdisplays |
| Plastic Products Mfg |
| Others |
Pricing and Supply Chain Analysis
Chinese acrylic substrate manufacturing concentrates upstream petrochemical processing capacity, anchoring margin capture in cast polymethyl methacrylate sheet production while downstream hospitality buyers in Germany and the United States absorb freight and tariff pass-through volatility.
Pricing Analysis
Cost-plus contracts with pulp and resin indexation dominate cardstock and acrylic procurement between North American hospitality chains and mid-tier manufacturers. Price differentiation rests on FSC certification tier and volume scale, with premium acrylic displays commanding wider spreads due to German hotel segment durability requirements. Cost compression in laminated cardstock intensifies as quick-service restaurants unbundle design and production across multiple vendors. United States quick-service operators exhibit highest price sensitivity, while German hotel procurement departments prioritize aesthetic weight over unit cost.
Supply Chain Analysis
Upstream feedstock supply draws from concentrated acrylic sheet production in Guangdong and Zhejiang provinces, FSC-certified pulp sourcing from Scandinavian forestry operations, and vinyl chloride resin processing along the US Gulf Coast. Raw material dependencies center on polymethyl methacrylate monomer, clay-coated paperboard, and extruded PVC substrates. Single-source vulnerability in Chinese acrylic manufacturing exposes premium display supply chains to geopolitical freight disruption. Distribution runs through North American hospitality supply distributors, European print-on-demand fulfillment networks, and direct-to-hotel procurement offices in Munich and Frankfurt.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Digital display substitution threatens physical table tent incumbents as quick-service restaurants pilot full-screen tabletop interfaces; defense requires embedding interactive functionality into traditional substrates rather than ceding surface territory to screens.
For Market Incumbents: Harden substrate innovation pipelines against NFC-enabled cardstock convergence by acquiring digital print-on-demand capabilities with variable-data workflow integration. Deflecto LLC and Azar Displays should deepen backward integration into FSC-certified pulp supply to preempt EU Green Deal procurement mandate disqualification. Channel control through hospitality supply distributor exclusivity agreements remains critical as restaurant procurement departments fragment vendor relationships. For New Entrants and Emerging Players: Tier-2 Indian cities with underpenetrated cafe sectors represent the most penetrable entry point for standard-format cardstock table tent manufacturing with rapid-turnaround positioning. Bangalore and Hyderabad hospitality clusters lack dedicated local production capacity for quarterly promotional refresh cycles. A go-to-market angle anchored on BIS certification assistance and Hindi-language design template libraries differentiates against import-dependent incumbents. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed North American distribution-heavy players carrying legacy die-cutting equipment requiring capital-intensive digital workflow retrofitting. Long-term viability across the analysis window favors substrate-specialist fabricators with acrylic and bio-based material R&D pipelines over catalog-breadth operators facing margin compression. The signal to watch is hospitality chain consolidation into centralized procurement platforms that disintermediate fragmented supplier relationships.| Strategic Initiative | Industry Significance |
|---|---|
| NFC Chip Integration | Enables tap-to-order functionality in laminated cardstock for US quick-service chains. |
| FSC Certification Investment | Secures preferential supplier qualification under EU Green Deal procurement mandates. |
| Digital Print-on-Demand Acquisition | Compresses turnaround times for quarterly campaign refresh cycles in hospitality. |
| Backward Integration into Pulp Supply | Reduces exposure to Scandinavian forestry supply constraints and energy price volatility. |
| India Manufacturing Footprint | Captures tier-2 city cafe demand with localized BIS-compliant production capacity. |
Research Methodology
A standing panel of hospitality procurement directors, digital print production managers, substrate R&D specialists, and FSC certification auditors provided ongoing calibration across primary interview rounds. Secondary validation drew from EPA vinyl chloride emission filings, EU Packaging and Packaging Waste Regulation documentation, customs trade data for acrylic sheet imports, and hospitality supply distributor inventory disclosures. Bottom-up demand modeling across restaurant, hotel, cafe, and event segments triangulated against top-down market sizing from substrate production capacity estimates.
Scenario-bracketing around pulp and resin price volatility, REACH chemical restriction implementation timelines, and NFC adoption curves in quick-service restaurants shaped the analytical framework. Segmentation dimensions modeled included material type, size configuration, end-use durability requirements, and design customization tier across the projection horizon. CAGRs derived from segment-level volume trajectories weighted by substrate-specific margin structures, with acrylic fabrication specialization and digital print-on-demand penetration serving as primary forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in energy prices, freight rates, or hospitality sector employment would shift the trajectory. Cross-checking against hospitality capital expenditure surveys and restaurant same-store sales benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Retail Packaging
Global Shoe Packaging Market
Retail Packaging
Retail Ready Trays Market
Retail Packaging
Club Store Packaging Market
Retail Packaging
Floor POP Display Market
Retail Packaging
Retail Bags Market
Retail Packaging
Retail Ready Packaging (RRP) Market
Retail Packaging
Retail E Commerce Packaging Market
Retail Packaging
Free Standing Display Units Market
Retail Packaging
Black Friday Packaging Market