
 Free Standing Display Units Market | 2026-2036
Free Standing Display Units Market Size, Share, and Industry Trends Forecast 2026-2036
Free Standing Display Units Market Analysis
Lightweight corrugated engineering is reconfiguring how free standing display units achieve structural integrity without metal hardware. Smurfit Kappa leverages integrated paper-based supply chains to control substrate costs across European retail networks. DS Smith anchors its position through closed-loop recycling systems that recover display fiber from supermarket backrooms. Sonoco Products Company competes via proprietary tube and core technologies that extend into temporary point-of-purchase structures.
Free standing display units are self-supporting merchandising structures, typically fabricated from corrugated fiberboard, folded sheet metal, extruded plastics, or engineered wood composites, designed to present products at floor level without wall attachment or fixture dependency. Cardboard displays dominate volume due to low per-unit cost and high printability for seasonal campaigns, while metal displays command margin pools in permanent retail installations where load-bearing capacity and theft resistance matter. Temporary installations represent the fastest-growing segment as brands prioritize event-based activation over fixed capital expenditure, and modular designs are gaining share by enabling component reuse across multiple retail formats.
The EPA governs volatile organic compound emissions from coatings applied to metal and wooden displays in the United States, while REACH restricts hazardous substances in European-sourced substrates and adhesives. China's GB standards set dimensional tolerances and load-testing protocols for domestic manufacturing export certification. Stakeholders must monitor how extended producer responsibility frameworks in the EU and pending state-level packaging legislation in California reshape material specifications and end-of-life recovery obligations.
Market Dynamics
Retail format modernization and the EU Green Deal's extended producer responsibility frameworks are compressing replacement cycles while forcing substrate transitions toward recyclable corrugated fiberboard and reduced-VOC coatings across European and North American networks.
Growth Catalysts
- REACH Compliance Mandates:European manufacturers accelerate cardboard display adoption to meet hazardous substance restrictions in substrates and adhesives, eliminating legacy plastic-heavy formats from supermarket chains.
- Trade Show Infrastructure Investment:China and Germany expand convention center capacity, driving demand for modular temporary displays that deploy rapidly across exhibition floors.
- Corrugated Engineering Advances:Lightweight structural fiberboard now achieves load-bearing parity with metal at one-third weight, enabling freight cost reductions for seasonal promotional campaigns.
Market Restraints
- Old-Growth Pulp Supply Concentration:Nordic and Canadian fiber suppliers control premium kraft linerboard grades, exposing converters to input volatility when forestry harvest quotas tighten.
- Permanent Metal Display Substitution:High-theft retail environments in urban centers retain preference for steel fixtures despite higher capital intensity, limiting cardboard penetration in electronics and spirits categories.
- EPA VOC Enforcement:Coating compliance costs for wooden and metal display manufacturers in the United States compress margins on small-batch custom orders.
Strategic Opportunities
- India Modern Trade Expansion:Organized retail penetration in tier-two cities creates first-mover advantage for corrugated display suppliers establishing local converting partnerships.
- Digital Print Convergence:Inline inkjet systems enable lot-size-one customization, allowing brands to localize messaging without plate changeover delays or minimum order thresholds.
- California EPR Legislation:Pending state-level packaging recovery mandates will compel supermarket chains to source displays with certified recyclable content, favoring suppliers with closed-loop fiber systems.
Industry Challenges
- Structural Engineering Talent Scarcity:Packaging design programs emphasize graphic rather than load-bearing engineering, leaving display manufacturers competing for finite corrugated mechanics specialists.
- Legacy Fixture Integration Friction:Modular cardboard systems require adapter hardware to interface with existing supermarket slotwall and gondola infrastructure, complicating rollout timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Free Standing Display Units Market |
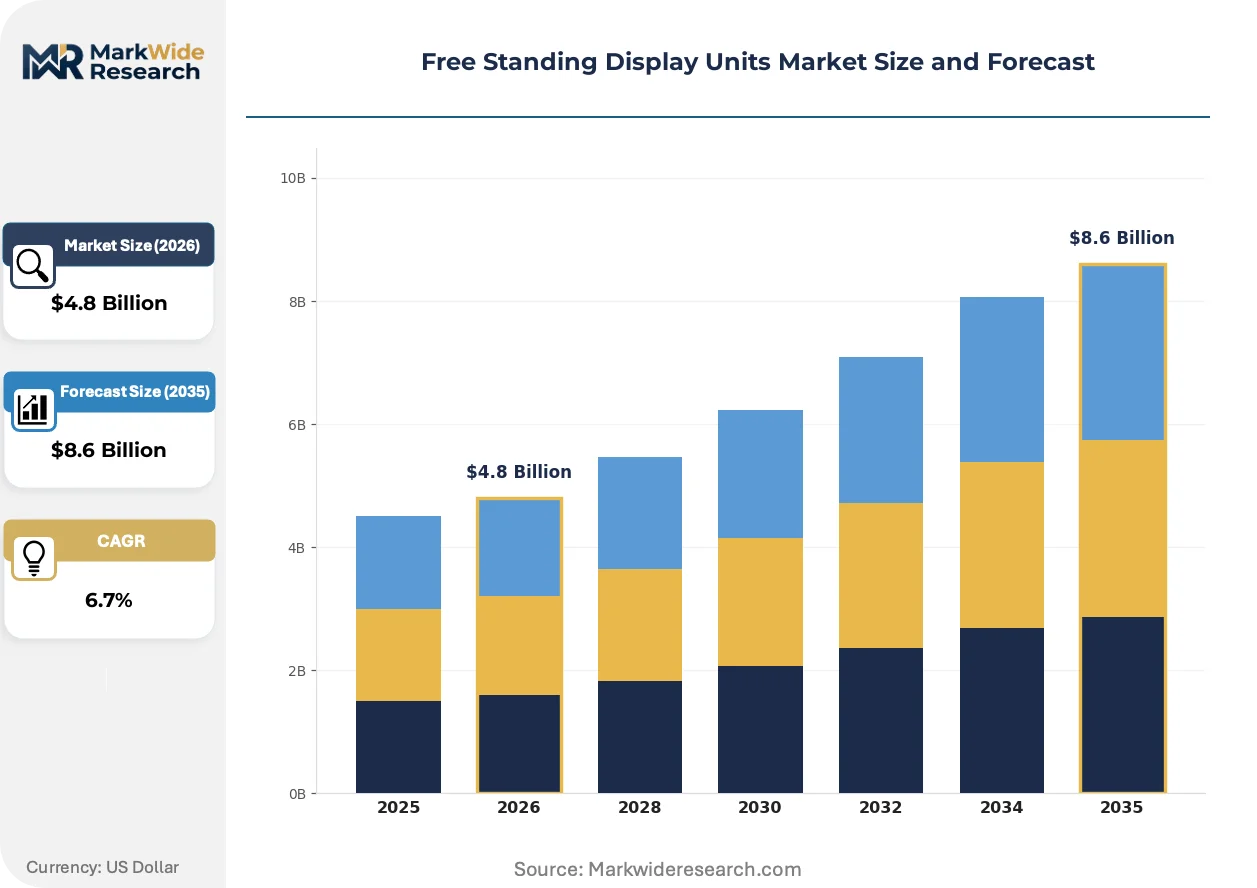
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
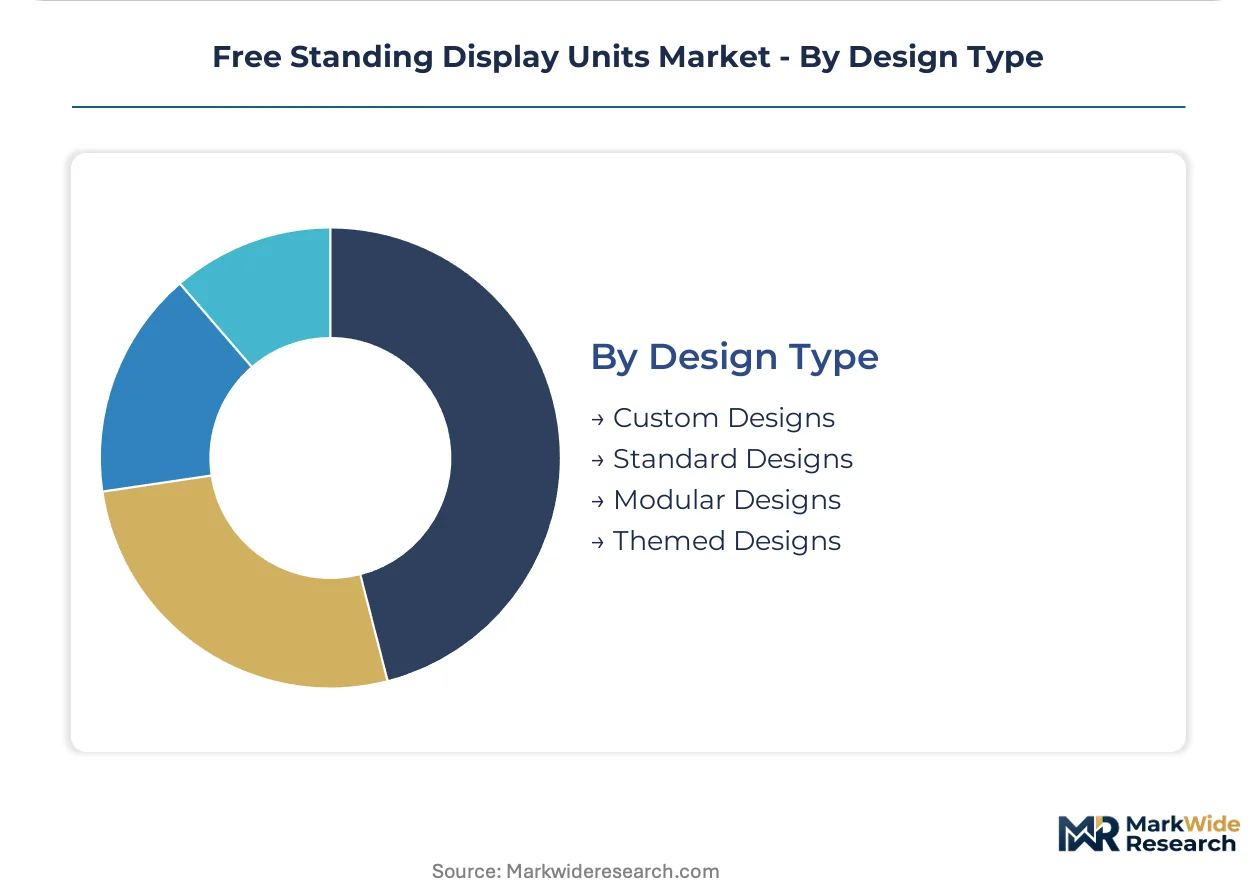
| Segmentation | Product Type: Cardboard Displays, Metal Displays, Wooden Displays, Plastic Displays End User: Retail Stores, Trade Shows, Supermarkets, Showrooms Installation Type: Permanent, Semi-Permanent, Temporary, Mobile Design Type: Custom Designs, Standard Designs, Modular Designs, Themed Designs |
| Companies Covered | WestRock, Simpson Group, DS Smith, Great Northern Corporation, FFP, Smurfit Kappa, Sonoco Products Company, International Paper, KSF Global, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Free Standing Display Units Market Emerging Trajectories
Material science breakthroughs and regulatory pressure on end-of-life recovery are converging to reshape how temporary merchandising structures achieve both visual impact and circularity compliance.
Corrugated fiberboard is hybridizing with polymer-reinforced edge profiles to create displays that withstand 90-day retail cycles without structural degradation. Mass-market grocers in Germany and the United States deploy these hybrid formats for center-store promotions previously reserved for metal fixtures. The technology is compressing the performance gap between temporary cardboard and permanent steel, enabling capital expenditure reallocation toward campaign frequency rather than fixture durability.
The EU Green Deal's packaging and packaging waste regulation revision tightens recyclability definitions and mandates minimum recycled content thresholds. European converters must redesign multi-material displays to enable fiber recovery without contamination from plastic laminates or metallic inks. Supermarket private-label programs in France and the Netherlands now specify mono-material corrugated constructions, disqualifying legacy formats from category captaincy bids.
Event-based activation contracts are displacing annual fixture procurement agreements as brand marketing budgets pivot toward experiential and pop-up retail. Beverage and cosmetics companies in China and the United States now lease display systems for 30-90 day campaigns rather than purchasing permanent installations. This consumption-pattern shift favors suppliers with rapid design-to-delivery capabilities and national logistics networks over asset-heavy manufacturers optimized for long production runs.
Free Standing Display Units Market Segmentation

Segmentation in free standing display units reveals how substrate selection, installation duration, and design complexity map to distinct service requirements and margin structures. Each dimension carries implications for logistics intensity, coating compliance, and end-of-life recovery obligations.
Product Type:
After-sales service intensity varies sharply across substrates, with metal displays requiring field repair capabilities and cardboard formats demanding rapid replacement logistics rather than maintenance.
- Cardboard Displays:Engineered from corrugated fiberboard with high-resolution lithographic or flexographic printing surfaces. Demand concentrates in German and United States supermarket chains executing frequent seasonal rotations, where lightweight construction enables single-person installation and disposal logistics. REACH compliance on adhesive formulations and the EU Green Deal's extended producer responsibility frameworks accelerate substitution away from plastic-laminated alternatives.
- Metal Displays:Fabricated from folded steel or aluminum with powder-coated or electroplated finishes. Urban retail environments in high-theft categories—electronics, spirits, cosmetics—retain preference for steel fixtures despite capital intensity, as load-bearing capacity and theft resistance justify permanent installation economics. EPA VOC enforcement on coating applications compresses margin on small-batch custom orders.
- Wooden Displays:Constructed from engineered composites or solid timber with low-VOC finishes. Boutique furniture and premium spirits showrooms specify these formats for tactile warmth.
- Plastic Displays:Injection-molded or thermoformed polymers with high durability for wet environments. Limited adoption persists in beverage cooler surrounds where moisture resistance trumps recyclability mandates.
By volume, Cardboard Displays leads. By growth pace, Metal Displays is ahead as urban retail hardens security requirements.
End User:
Procurement patterns diverge between capital-expenditure-driven permanent installations and operating-expense-driven campaign activations, reshaping supplier relationship structures.
- Supermarkets:Center-store and end-cap merchandising programs rotate displays on 30-90 day cycles. German chains now specify mono-material corrugated constructions to meet private-label sustainability requirements.
- Trade Shows:Convention center deployments in China and Germany demand rapid assembly systems with tool-free installation. Modular tube-and-core technologies from specialized suppliers dominate this segment.
- Retail Stores:Department and specialty formats balance fixture permanence against campaign flexibility. Adapter hardware requirements for slotwall integration complicate cardboard system rollouts.
- Showrooms:Automotive and furniture displays emphasize extended durability with premium surface finishes. Wooden and metal formats retain preference here.
Supermarkets generate highest unit volume. Trade Shows exhibits steepest expansion trajectory as experiential marketing budgets displace annual fixture procurement.
Installation Type:
Duration-based classification determines depreciation treatment, logistics configuration, and design-for-disassembly requirements across customer portfolios.
- Temporary:30-90 day campaign structures with single-use or limited-reuse specifications. Event-based activation contracts now displace annual procurement agreements in beverage and cosmetics sectors.
- Permanent:Multi-year installations with capital depreciation and field maintenance obligations. Electronics and spirits categories in urban United States locations retain steel fixture preference.
- Semi-Permanent:6-12 month seasonal programs with component reuse across multiple campaigns. Hybrid corrugated-polymer edge profiles enable 90-day structural integrity without metal hardware.
- Mobile:Castor-mounted or collapsible units for pop-up retail and roadshow deployment. Logistics networks with rapid design-to-delivery capabilities capture this expanding segment.
Temporary installations lead by volume growth. Permanent installations retain highest per-unit value concentration.
Design Type:
Engineering complexity tiers separate commodity converters from specialists capable of structural load-bearing optimization and rapid customization.
- Modular Designs:Component-based systems enabling reconfiguration across retail formats without complete replacement. Closed-loop fiber recovery systems from integrated suppliers align with supermarket sustainability specifications.
- Custom Designs:Bespoke geometries for brand-specific campaign activations. Digital print convergence enables lot-size-one localization without plate changeover delays.
- Standard Designs:Catalog formats with minimal engineering overhead and rapid fulfillment. Volume converters compete on substrate cost control and national logistics coverage.
- Themed Designs:Seasonal or promotional constructions with high graphic complexity and limited reuse potential. Short production runs strain coating compliance economics for small-batch manufacturers.
Standard Designs dominate unit shipments. Modular Designs is gaining share fastest as capital expenditure reallocation favors component reuse over fixture durability.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Supermarket chains and trade show operators in Germany, China, and the United States drive the majority of procurement volume for free standing display units. These buyers prioritize modular cardboard formats for seasonal rotations and steel fixtures for high-theft categories. Regulatory pressure on recyclability and VOC emissions is compressing replacement cycles across all three markets.
Germany
Rewe and Edeka specify mono-material corrugated constructions for private-label sustainability programs. The EU Green Deal's extended producer responsibility frameworks mandate minimum recycled content thresholds for packaging waste regulation compliance. Display converters in the Rhine-Ruhr cluster engineer closed-loop fiber recovery systems to meet supermarket chain specifications.
United States
Walmart and Target rotate center-store displays on 30-90 day cycles to maximize aisle conversion rates. EPA enforcement on volatile organic compound emissions from metal and wooden display coatings compresses margins for small-batch custom manufacturers. Chicago-area fabricators supply corrugated formats to Midwestern grocery networks while California's pending EPR legislation drives recyclable content certification demand.
China
Convention center expansions in Shanghai and Guangzhou accelerate demand for modular temporary displays with tool-free assembly. GB standards set dimensional tolerances and load-testing protocols for domestic manufacturing export certification. Shenzhen-based suppliers leverage rapid design-to-delivery capabilities to capture beverage and cosmetics brand activation contracts.
France
Carrefour and Intermarché disqualify multi-material displays from category captaincy bids under tightened recyclability definitions. REACH restrictions on hazardous substances in substrates and adhesives eliminate legacy plastic-heavy formats from supermarket chains. Lyon-area converters specialize in hybrid corrugated-polymer edge profiles for 90-day retail cycles.
India
Reliance Retail and D-Mart expand organized retail penetration in tier-two cities, creating first-mover opportunities for corrugated display suppliers. The country's national packaging regulator enforces quality control orders on paper and paperboard products. Mumbai and Ahmedabad converting partnerships establish local production capacity to serve modern trade expansion.
Free Standing Display Units Market Vendor Landscape
Channel-controlling players compete with product-specialist players across tiered supply structures. Integrated paper and packaging conglomerates dominate substrate cost control through captive fiber supply chains. Specialist display engineering firms capture premium margins in temporary activation and modular system design. Competitive moves center on closed-loop recycling infrastructure investments and digital print capability acquisitions.
Among Irish and UK-based paper and packaging conglomerates, Smurfit Kappa and DS Smith occupy positions anchored in integrated European fiber networks. Smurfit Kappa exemplifies the channel-controlling archetype through paper-based supply chain integration. DS Smith represents closed-loop recycling system specialization with supermarket backroom fiber recovery. Sonoco Products Company, a US-based packaging corporation, anchors the tube and core technology extension into temporary point-of-purchase structures. These three players illustrate how geographic concentration of fiber supply and recycling infrastructure shapes competitive positioning.
| Leading Market Players |
|---|
| WestRock |
| Simpson Group |
| DS Smith |
| Great Northern Corporation |
| FFP |
| Smurfit Kappa |
| Sonoco Products Company |
| International Paper |
| KSF Global |
| Others |
Supply Flow & Price Mechanics
Rhine-Ruhr corrugated converters anchor European supply capacity, with captive kraft linerboard mills from integrated paper groups feeding downstream display manufacturers. Their fiber cost pass-through mechanisms determine pricing power across supermarket private-label programs in Germany and France.
Pricing Analysis
Cost-plus contracts with old-growth pulp indexation dominate procurement between Nordic fiber suppliers and European converters. Price differentiation rests on certification grade—FSC chain-of-custody commands premium positioning—and volume scale, with national retail chains extracting favorable terms against regional grocers. Cost compression in custom cardboard formats is intensifying because REACH-compliant adhesive formulations add 8-12% to substrate costs. Supermarket chains exhibit highest price sensitivity, while boutique spirits brands tolerate premium positioning for wooden displays with tactile finishes.
Supply Chain Analysis
Contract manufacturing concentrates with Smurfit Kappa's integrated European mills, DS Smith's closed-loop recycling facilities, and Sonoco's tube-and-core foundries serving North American networks. Raw material dependencies center on Canadian and Nordic kraft linerboard, South American eucalyptus pulp for premium grades, and water-based coatings from German specialty chemical suppliers. Single-source vulnerability runs through Nordic old-growth fiber harvest quotas, which tighten unpredictably under forestry stewardship protocols. Distribution runs through supermarket category captaincy programs, direct-to-brand logistics for trade show activations, and third-party merchandising service providers handling field installation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through Walmart and Target's consolidated procurement functions, which now mandate closed-loop fiber recovery specifications across North American supplier bases. Rewe and Edeka's private-label sustainability requirements in Germany mirror this consolidation pattern.
For Market Incumbents: Pre-empt margin erosion by securing captive linerboard supply through backward integration into Scandinavian pulp assets or long-term offtake agreements with Canadian suppliers. Counter modular cardboard substitution threats in high-theft categories by developing hybrid corrugated-polymer edge profiles that achieve 90-day structural parity with steel. Certification investment in EU Green Deal compliance separates defendable premium positioning from commodity converter exposure. For New Entrants and Emerging Players: Build out rapid design-to-delivery capabilities targeting India's tier-two modern trade expansion, where Reliance Retail and D-Mart procurement functions remain fragmented and receptive to local converting partnerships. Digital print convergence enables lot-size-one localization without plate economics, creating entry wedge against legacy high-volume competitors. White-space concentration sits with 30-90 day beverage and cosmetics activation contracts in China and the United States. For Investors and Strategic Acquirers: Carve-out targets emerge from paper and packaging conglomerates divesting non-core display engineering units to focus on containerboard scale. Long-term viability favors suppliers with closed-loop fiber infrastructure and supermarket backroom recovery relationships over asset-light design houses. Watch for California EPR legislation implementation as inflection signal—certified recyclable content mandates will disqualify multi-material competitors and reshape category captaincy economics.| Strategic Initiative | Industry Significance |
|---|---|
| Closed-Loop Fiber Recovery Investment | Aligns with EU Green Deal extended producer responsibility mandates across Rewe and Edeka networks. |
| Digital Print Capability Acquisition | Enables lot-size-one campaign localization for beverage brands pivoting to event-based activation. |
| Hybrid Corrugated-Polymer Engineering | Compresses performance gap between temporary cardboard and permanent steel in center-store merchandising. |
| India Local Converting Partnership | Captures modern trade expansion in tier-two cities ahead of consolidated procurement function maturation. |
| REACH-Compliant Adhesive Verticalization | Defends margin position against regulatory cost pass-through in European substrate formulations. |
Methodological Framework
Cross-validation between primary interviews with retail category managers, corrugated packaging engineers, and sustainability procurement leads anchors the qualitative findings against secondary validation from EPA coating enforcement records, EU EPR framework documentation, and supermarket private-label specification sheets. Bottom-up triangulation aggregates converter capacity and fiber input costs; top-down calibration cross-checks against trade show infrastructure investment disclosures and retail format modernization capex patterns.
Calibration against historical replacement cycle data and regulatory implementation timelines shapes the projection framework across substrate type, installation duration, and end-user segment dimensions. CAGRs derive from elasticity modeling of supermarket display rotation frequency against fiber cost trajectories and REACH compliance cost pass-through assumptions. Corrugated engineering advances and digital print adoption curves serve as industry-specific forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive moves by integrated paper conglomerates into closed-loop recycling infrastructure would shift outcomes beyond modeled parameters. Quarterly review of Nordic forestry harvest quota announcements, California EPR rulemaking progress, and India modern trade penetration rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Retail Packaging
Retail Bags Market
Retail Packaging
Retail Ready Packaging (RRP) Market
Retail Packaging
Retail Ready Trays Market
Retail Packaging
Table Tent Market
Retail Packaging
Retail E Commerce Packaging Market
Retail Packaging
Black Friday Packaging Market
Retail Packaging
Global Shoe Packaging Market
Retail Packaging
Floor POP Display Market
Retail Packaging
Club Store Packaging Market