
 Global Metal Bellows Market | 2026-2036
Global Metal Bellows Market Size, Share, and Industry Trends Forecast 2026-2036
Global Metal Bellows Market Outlook
Modular sensor-and-bellow assemblies is pivoting procurement patterns across aerospace and semiconductor equipment buyers. BOA Group leverages deep hydroforming expertise to anchor European nuclear and chemical plant retrofits. Witzenmann Group sustains dominance in automotive exhaust flex assemblies through captive tube-making capacity. Technetics Group differentiates via electron-beam welding specialization for satellite propulsion lines.
Metal bellows are precision-engineered elastic vessels formed from thin-walled metal tubes through hydroforming, roll-forming, or edge-welded diaphragm stacking, designed to absorb thermal expansion, vibration, and pressure differentials in sealed fluid systems. Stainless steel variants occupy the volume core due to cost-efficient corrosion resistance across HVAC and industrial process lines. Titanium bellows represent the fastest-growing product category, driven by weight-critical aerospace and medical oxygen system applications. Oil and gas applications command premium margin pools, particularly in subsea riser tensioner systems where fatigue life specifications exceed twenty years.
The EPA enforces leak detection and repair standards that mandate welded bellows seals in volatile organic compound service, tightening specification thresholds for American refineries. EMA medical device regulations and REACH substance restrictions in Europe are redirecting material qualification pathways toward nickel-cobalt alloys with full batch traceability. Japan's METI energy efficiency codes for industrial boilers are expanding replacement demand for high-cycle bellows in steam conditioning stations. Stakeholders must monitor evolving hydrogen infrastructure codes, as embrittlement-resistant alloys will determine qualification status for high-pressure fueling and pipeline compressor seals.
Market Dynamics
Aerospace OEMs are consolidating supplier bases around electron-beam welded titanium bellows for next-generation propulsion architectures, compressing qualification timelines and concentrating procurement among certified precision metalformers.
Growth Catalysts
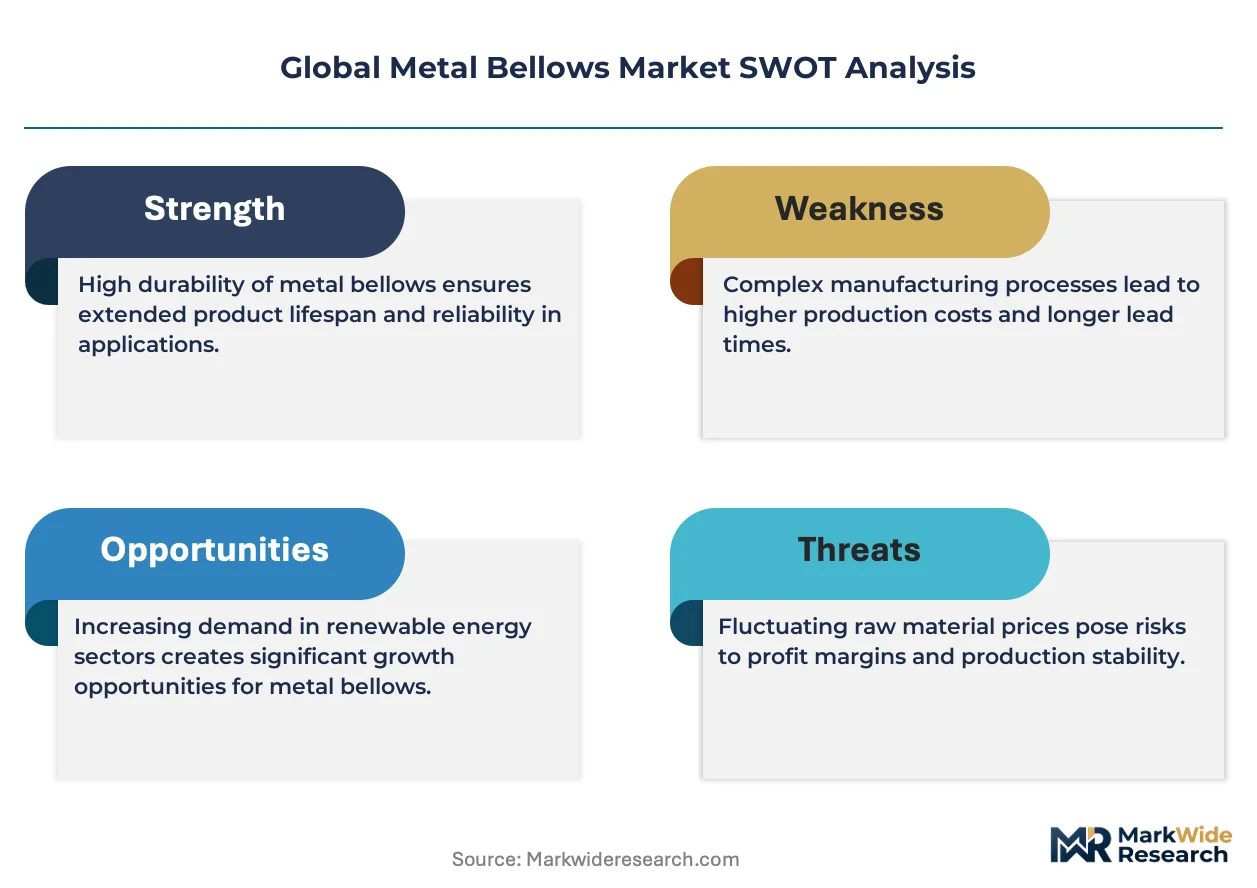
- EU F-Gas Regulation:Phase-down of hydrofluorocarbon-based sealing systems is mandating welded metal bellows in refrigeration compressors and heat pump circuits across European HVAC retrofit programs.
- Titanium hydroforming:Weight reduction imperatives in satellite propulsion and medical oxygen delivery are accelerating adoption of thin-wall titanium bellows with fatigue cycles exceeding ten million operations.
- German nuclear fleet:Extended reactor lifespans and primary circuit maintenance cycles are generating replacement demand for Inconel bellows in steam generator tube bundles and pressurizer surge lines.
Market Restraints
- Nickel price volatility:Inconel and Hastelloy feedstock costs fluctuate with London Metal Exchange nickel contract movements, compressing margins on long-lead nuclear and subsea contracts with fixed pricing terms.
- Japanese specialty steel concentration:Ultra-thin strip production for edge-welded diaphragm bellows clusters among three integrated mills in Nagoya and Kobe, creating single-source vulnerability for precision thickness grades below 0.1 millimeter.
- Polymer bellow substitution:Perfluoroelastomer and PTFE convoluted seals are capturing low-pressure HVAC and chemical transfer applications where temperature excursions remain below 200 degrees Celsius.
Strategic Opportunities
- Hydrogen infrastructure codes:Draft ISO 19880 and regional standards for 700-bar fueling stations are creating first-mover qualification pathways for embrittlement-resistant nickel-cobalt alloy bellows in compressor seals and dispenser hoses.
- Semiconductor equipment retrofit:Legacy CVD and etch tool installed bases in Taiwan and South Korea require bellows replacement for ultra-high vacuum compatibility, opening aftermarket service contracts independent of OEM channel control.
- Modular sensor integration:Bellows-and-transducer assemblies for pressure and temperature feedback are penetrating aerospace health monitoring systems, bundling hardware with predictive maintenance software subscriptions.
Industry Challenges
- Electron-beam welding certification:Aerospace and nuclear end-users require ASME Section IX and AWS D17.1 qualified welders with radiographic inspection clearances, constraining production scaling for new market entrants.
- REACH substance documentation:Full batch traceability for nickel, cobalt, and chromium alloys demands ERP system upgrades and third-party audit investments that disproportionately burden mid-tier metalformers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Metal Bellows Market |
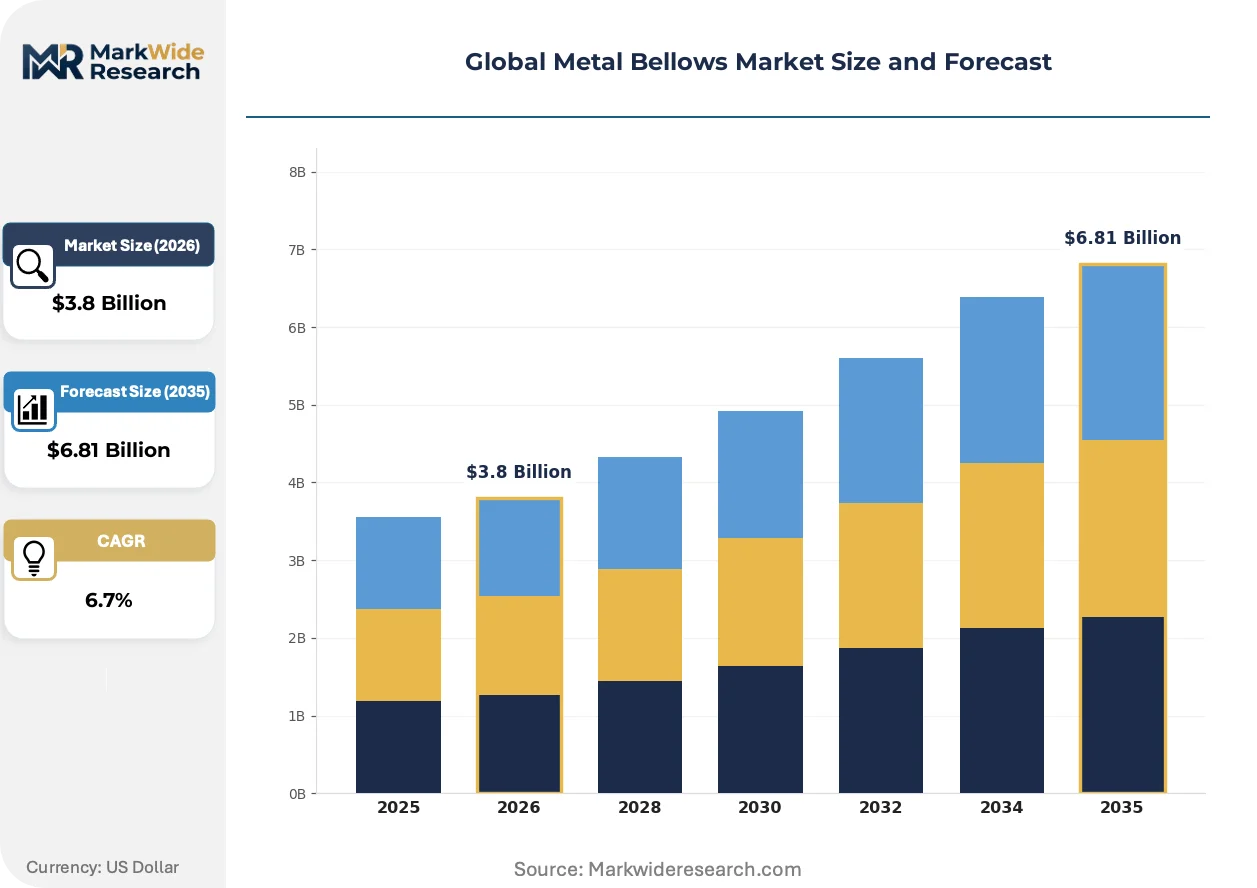
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stainless Steel, Inconel, Monel, Titanium Application: Aerospace, Automotive, HVAC, Oil & Gas End User: Manufacturers, Distributors, Contractors, Engineers Installation Type: Onshore, Offshore, Indoor, Outdoor |
| Companies Covered | BOA Group, Technetics Group, Witzenmann Group, Servometer, KSM Corporation, Senior Flexonics, EagleBurgmann, Meggitt PLC, MW Industries, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Metal Bellows Market Strategic Shifts
Additive manufacturing of bellows mandrels and conformal cooling channels is compressing prototype lead times from months to weeks, enabling geometry optimization previously constrained by conventional toolmaking economics.
Roll-formed titanium bellows with plasma-arc welded seams is overtaking hydroformed stainless steel variants in satellite propulsion lines, with SpaceX and Airbus Defence procurement teams specifying the lighter alloy for constellation deployment missions where kilogram savings translate directly to launch cost reductions.
EPA leak detection and repair standards for volatile organic compound service are tightening welded bellows seal specifications across American refinery fluid catalytic cracking units, forcing material upgrades from 316L stainless steel to Alloy 625 for sour gas resistance and extending supplier qualification cycles by twelve to eighteen months.
Direct sourcing from precision metalformers is displacing distributor channels for semiconductor and aerospace OEMs, with procurement teams in Dresden, Austin, and Yokohama establishing vendor-managed inventory programs that transfer forecasting risk to bellows manufacturers while securing volume commitments and technical collaboration access.
Global Metal Bellows Market Segmentation
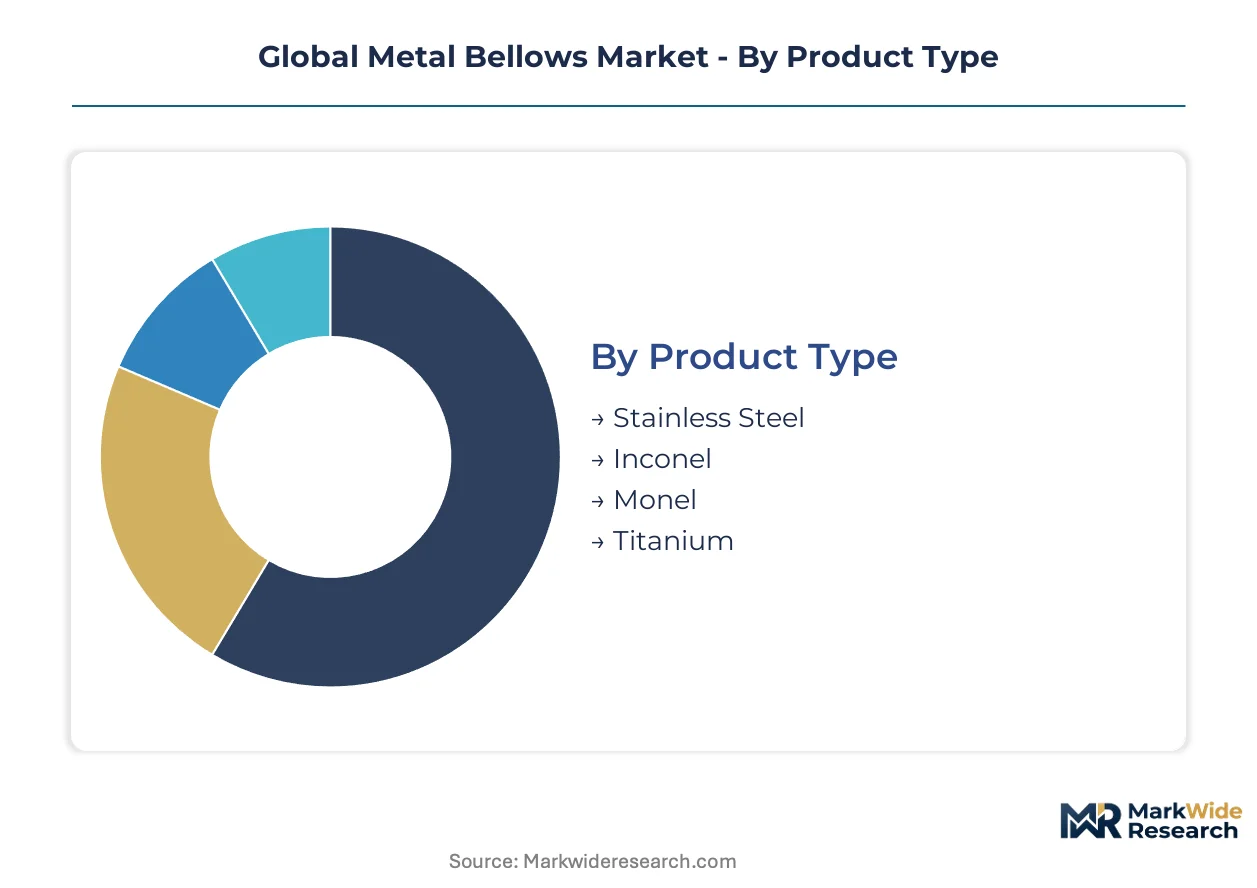
Metal bellows procurement varies sharply by technical specification, with aerospace and nuclear buyers demanding electron-beam welded titanium while HVAC contractors prioritize cost-optimized stainless steel. Segmentation reveals where margin pools concentrate and which alloy grades command qualification premiums.
Product Type:
Customization intensity spans from commodity stainless steel to mission-critical titanium, with alloy selection directly determining fatigue life, corrosion resistance, and regulatory compliance pathways.
- Stainless Steel:Austenitic 316L and 304 grades dominate volume through hydroformed exhaust flex joints and industrial process lines. German HVAC retrofit programs and American refinery leak detection mandates sustain replacement demand for welded 316L seals in volatile organic compound service.
- Titanium:Thin-wall Ti-6Al-4V bellows with plasma-arc welded seams absorb thermal expansion in satellite propulsion lines and medical oxygen systems. SpaceX and Airbus Defence procurement teams specify this alloy for constellation missions where kilogram savings reduce launch costs.
- Inconel:Nickel-chromium superalloy withstands pressurized water reactor steam generator environments. Extended German nuclear fleet lifespans generate replacement cycles for Inconel 625 and 718 grades in pressurizer surge lines.
- Monel:Copper-nickel alloy resists seawater corrosion in subsea riser tensioner systems. Offshore Brazil and Gulf of Mexico developments specify Monel K-500 for fatigue life exceeding twenty-year design specifications.
Leading the category by volume: Stainless Steel. Expanding most quickly: Titanium.
Application:
End-use differentiation separates specification-heavy sectors with ASME welding mandates from price-sensitive markets vulnerable to polymer substitution.
- Aerospace:Satellite propulsion, aircraft engine bleed air systems, and launch vehicle fuel lines require electron-beam welded titanium with radiographic inspection clearances. AS9100 certification barriers concentrate procurement among qualified precision metalformers.
- Automotive:Exhaust flex assemblies and EGR cooler bellows sustain Witzenmann Group dominance through captive tube-making capacity. European OEMs specify hydroformed stainless steel for thermal expansion absorption in turbocharged powertrains.
- HVAC:Refrigeration compressor seals and heat pump circuits face EU F-Gas Regulation phase-down of hydrofluorocarbon-based alternatives. Welded metal bellows capture retrofit demand across European building stock renovation programs.
- Oil & Gas:Subsea riser tensioners, wellhead connectors, and refinery fluid catalytic cracking units command premium margins. EPA leak detection standards force Alloy 625 upgrades for sour gas resistance in American downstream facilities.
Margin concentration peaks in Oil & Gas. Fastest qualification timeline compression: Aerospace.
End User:
Channel structure shifts from distributor intermediation toward direct vendor-managed inventory programs as technical collaboration requirements intensify.
- Manufacturers:Aerospace OEMs and semiconductor equipment builders consolidate supplier bases around electron-beam welding specialists. Dresden and Yokohama procurement teams transfer forecasting risk to bellows producers through VMI arrangements.
- Distributors:Industrial maintenance supply houses face displacement in aerospace and semiconductor channels while retaining HVAC contractor relationships. Price transparency pressures compress margins on standard stainless steel grades.
- Contractors:Nuclear plant maintenance specialists and subsea installation firms specify Inconel and Monel for replacement cycles. Long-lead contracts with fixed pricing expose margin volatility to London Metal Exchange nickel movements.
- Engineers:EPC firms and design consultancies influence material selection through piping stress analysis and fatigue life modeling. Early engagement determines alloy qualification pathways before procurement release.
Procurement authority concentrates with Manufacturers. Channel disruption accelerates fastest among Distributors.
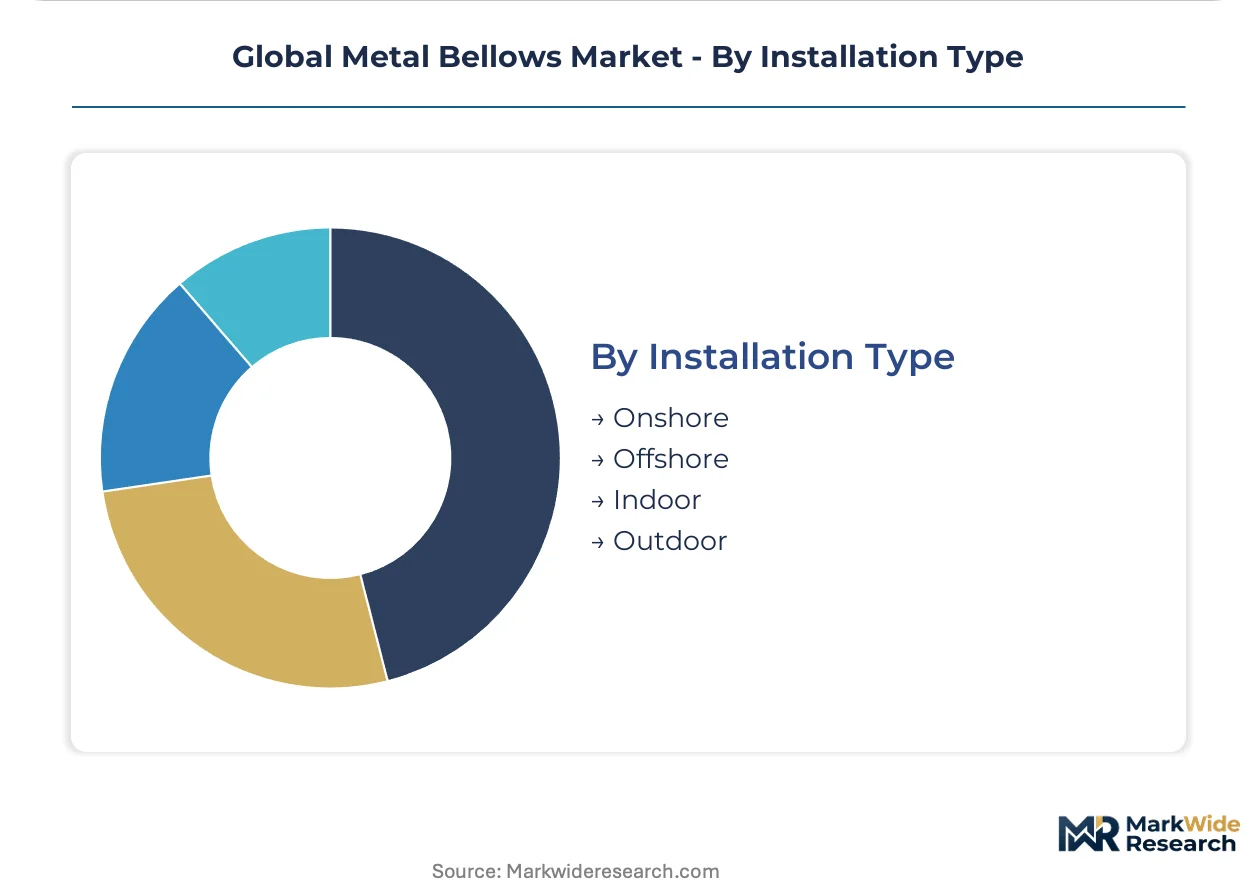
Installation Type:
Environmental exposure severity dictates alloy grade and welding specification, with offshore and outdoor installations demanding corrosion-resistant superalloys.
- Onshore:Refinery process lines and power plant steam conditioning stations accommodate hydroformed stainless steel with periodic inspection protocols. Japanese METI energy efficiency codes expand replacement demand for high-cycle bellows in industrial boilers.
- Offshore:Subsea production systems and floating platform risers require Monel and Inconel grades with twenty-year fatigue specifications. Deepwater Brazil pre-salt developments sustain premium pricing for embrittlement-resistant alloys.
- Indoor:Semiconductor cleanrooms and medical gas systems prioritize titanium for ultra-high vacuum compatibility and weight reduction. Taiwan and South Korea legacy CVD tool retrofits open aftermarket service contracts.
- Outdoor:Pipeline compressor seals and hydrogen fueling station dispensers face emerging ISO 19880 standards for 700-bar service. Embrittlement-resistant nickel-cobalt alloys determine qualification status for first-mover infrastructure deployments.
Specification intensity peaks in Offshore. Regulatory tailwinds strengthen fastest for Outdoor hydrogen applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in precision manufacturing corridors concentrate metal bellows fabrication across Germany, Japan, and the United States. Demand clusters around nuclear maintenance cycles, semiconductor equipment retrofits, and aerospace propulsion programs.
United States
EPA leak detection mandates for volatile organic compound service drive welded bellows procurement in refinery fluid catalytic cracking units. The Agency enforces material upgrades from 316L stainless steel to Alloy 625 for sour gas resistance. Houston-Gulf Coast petrochemical complexes sustain premium contract volumes for fatigue-resistant superalloys.
Germany
Extended nuclear reactor lifespans generate replacement cycles for Inconel bellows in steam generator tube bundles. The EU F-Gas Regulation accelerates welded metal bellows adoption in refrigeration compressors and heat pump circuits. Ruhr industrial clusters anchor European HVAC retrofit demand through BOA Group hydroforming operations.
Japan
METI energy efficiency codes for industrial boilers expand replacement demand for high-cycle bellows in steam conditioning stations. Ultra-thin strip production for edge-welded diaphragm bellows concentrates among Nagoya and Kobe integrated mills. Yokohama procurement teams establish vendor-managed inventory programs transferring forecasting risk to manufacturers.
China
Dual carbon goals and hydrogen infrastructure development create qualification pathways for embrittlement-resistant alloys in high-pressure fueling applications. National standards under MIIT guidance shape material specifications for pipeline compressor seals. Yangtze River Delta precision metalforming clusters serve domestic semiconductor equipment builders.
South Korea
Legacy CVD and etch tool installed bases in semiconductor fabrication facilities require bellows replacement for ultra-high vacuum compatibility. National industrial policy supports captive supply chain development for critical vacuum components. Seoul Capital Area equipment manufacturers consolidate direct sourcing relationships with certified precision metalformers.
Global Metal Bellows Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across electron-beam welding, hydroforming, and edge-welded diaphragm fabrication. The vendor base stratifies into three tiers: integrated mills with captive tube-making capacity, precision metalformers with ASME-certified welding operations, and regional fabricators serving maintenance supply channels. Dominant competitive moves include backward integration into ultra-thin strip production and strategic partnerships for modular sensor-and-bellow assemblies.
Among German fabricators, BOA Group and Witzenmann Group exemplify distinct archetypes within European nuclear and automotive exhaust supply chains. Technetics Group occupies a position among electron-beam welding specialists serving satellite propulsion applications. These three entities represent the geographic and technical diversification patterns visible across the competitive set.
| Leading Market Players |
|---|
| BOA Group |
| Technetics Group |
| Witzenmann Group |
| Servometer |
| KSM Corporation |
| Senior Flexonics |
| EagleBurgmann |
| Meggitt PLC |
| MW Industries, Inc. |
| Others |
Value Chain & Pricing Dynamics
Electron-beam welding certification requirements are compressing supplier bases while simultaneously inflating qualification premiums for aerospace and nuclear procurement teams. This production-method transition concentrates pricing power among ASME-certified metalformers with radiographic inspection clearances, while spot-market stainless steel variants face cost compression from polymer substitution threats.
Pricing Analysis
Lead-time premiums dominate contract negotiations, with expedited electron-beam welded titanium bellows commanding substantial markups over standard-cycle hydroformed alternatives. Three-tier pricing structure across mission-critical, industrial-grade, and commodity levels separates AS9100-certified aerospace suppliers from HVAC retrofit providers. Cost compression in stainless steel segments is intensifying because perfluoroelastomer seals capture sub-200°C applications. HVAC contractors exhibit highest price sensitivity, while satellite propulsion procurement teams prioritize fatigue-life guarantees over unit economics.
Supply Chain Analysis
Domestic-content mandates in China's MIIT-guided hydrogen infrastructure codes are redirecting sourcing toward Yangtze River Delta precision metalforming clusters. Ultra-thin strip production draws from Japanese Nagoya and Kobe integrated mills, German Ruhr hydroforming operations, and American Gulf Coast superalloy processors. Nickel-cobalt alloy feedstock, titanium sponge, and edge-welded diaphragm components anchor material dependencies. Single-source vulnerability concentrates in sub-0.1 millimeter thickness grades from Japanese specialty steel producers. Distribution runs through direct vendor-managed inventory programs for semiconductor and aerospace OEMs, with distributor channels retaining HVAC contractor relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Plasma-arc welded titanium bellows are displacing hydroformed stainless steel in satellite propulsion architectures, compressing qualification timelines and reshaping competitive positioning around weight-critical performance metrics.
For Market Incumbents: Anchor market position through backward integration into ultra-thin strip production and captive electron-beam welding capacity expansion. Polymer substitution threats in HVAC applications demand defensive certification investments in REACH-compliant nickel-cobalt alloys. Channel control through vendor-managed inventory programs with Dresden and Yokohama procurement teams secures volume commitments against emerging precision metalformers. For New Entrants and Emerging Players: Begin with semiconductor equipment retrofit services in Taiwan and South Korea, where legacy CVD tool bellows replacement escapes OEM channel lock-in. Hydrogen fueling station compressor seals under draft ISO 19880 standards offer penetrable qualification pathways for embrittlement-resistant alloy specialists. Go-to-market through predictive maintenance software bundling with sensor-integrated bellows assemblies differentiates against commodity suppliers. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to diversified industrial conglomerates seeking electron-beam welding capabilities. Long-term viability hinges on hydrogen infrastructure deployment velocity and nuclear fleet extension decisions. Watch for MIIT finalization of 700-bar compressor seal standards as inflection indicator for nickel-cobalt alloy demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ultra-Thin Strip Production | Captive supply of sub-0.1mm grades eliminates Japanese mill dependency for edge-welded diaphragm bellows. |
| Electron-Beam Welding Certification Investment | ASME Section IX and AWS D17.1 qualifications unlock aerospace and nuclear procurement channels. |
| Modular Sensor-and-Bellow Assembly Development | Pressure-transducer integration with predictive maintenance software creates recurring revenue streams. |
| Hydrogen Infrastructure Qualification Pathway | ISO 19880 compliance for 700-bar nickel-cobalt alloys secures first-mover compressor seal positioning. |
| Vendor-Managed Inventory Program Expansion | Forecasting risk transfer to manufacturers locks in volume commitments from Dresden semiconductor OEMs. |
Study Parameters
Trade association filings, customs and trade flow databases, and SEC 10-K disclosures formed the secondary backbone of this study. Primary interviews with aerospace procurement directors, nuclear plant maintenance specialists, semiconductor equipment engineers, and precision metalformer operations executives combined with secondary validation. Bottom-up and top-down triangulation cross-checked alloy-grade demand estimates against end-use installation data.
Bottom-up modeling aggregated product-type volumes across stainless steel, titanium, Inconel, and Monel grades, while top-down approaches validated against regional industrial output indicators. Segmentation dimensions spanned material alloy, application sector, end-user channel, and installation environment across the projection horizon. CAGRs derived from regression analysis of historical procurement patterns and regulatory-driven replacement cycle assumptions. Hydrogen infrastructure code development velocity and nuclear fleet extension decisions served as scenario-weighting inputs.
Underlying measurement precision varies by segment; aerospace and nuclear applications carry tighter precision than commodity HVAC estimates due to disclosed contract visibility. Forecasts reflect documented assumptions about regulatory implementation timelines and alloy substitution elasticities. Nickel price volatility, Japanese specialty steel supply disruptions, and polymer substitution acceleration constitute primary revision risks. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Metals
North America Metal Turned Precision Product Manufacturing Market
Specialty Metals
Case Hardening Steel Market
Specialty Metals
Specialty Metallic Pigments Market
Specialty Metals
Precision Stainless Steel Market
Specialty Metals
Metal Halide Market
Specialty Metals
Precious Metal Plating Market
Specialty Metals
Dysprosium Market
Specialty Metals
Europe Metal Precision Turned Product Manufacturing Market
Specialty Metals
Global Special Steel Market