
 Metal Halide Market | 2026-2036
Metal Halide Market Size, Share, and Industry Trends Forecast 2026-2036
Metal Halide Market Analytics
Multi-source procurement for arc tube ceramics and halide salts is pivoting toward vertically integrated supply chains as price volatility in rare earth elements disrupts spot purchasing. Philips leverages captive manufacturing of quartz arc tubes to buffer against tungsten and scandium iodide cost swings. Osram sustains long-term supply agreements with Chinese rare earth processors, while GE Current competes through regional lamp assembly hubs that shorten logistics lead times to North American industrial buyers.
Metal halide lamps generate light by passing an electric arc through a gaseous mixture of vaporized mercury and metal halide compounds, typically achieving color temperatures between 3000K and 6000K with luminous efficacy ranging from 75 to 100 lumens per watt. Their primary commercial purpose centers on high-intensity discharge illumination where color accuracy and beam penetration outweigh energy efficiency priorities. High-pressure metal halide systems anchor the installed base across aging sports stadium infrastructure, while compact variants are gaining fastest in retail environments where ceiling height constraints limit fixture size. The conventional technology segment remains structurally dominant by unit volume, though energy-efficient retrofit demand is reshaping margin pools toward premium phosphor-coated lamps.
The EPA's Toxic Substances Control Act governs mercury content thresholds in U.S. lamp imports, while the EU RoHS Directive restricts hazardous substance concentrations in electrical equipment sold across member states. China's GB standards for discharge lamp safety and efficiency testing create a fragmented compliance landscape that raises entry costs for smaller exporters. Stakeholders must monitor accelerating LED substitution rates in street lighting tenders, where municipal procurement criteria are tightening lumen-per-watt minimums beyond metal halide reach.
Market Dynamics
LED retrofits are compressing replacement cycles for metal halide installations across municipal and commercial infrastructure, forcing incumbent suppliers to defend aftermarket revenue through phosphor-coated premium SKUs and extended warranty programs.
Growth Catalysts
- Sports infrastructure modernization:Aging mercury vapor systems in North American stadiums face mandatory replacement under local energy efficiency ordinances, pulling metal halide demand through 2035.
- Ceramic arc tube chemistry advances:Polycrystalline alumina envelopes withstand higher thermal loads than quartz predecessors, extending lamp life in high-vibration industrial settings.
- EU F-Gas Regulation phase-down:Hydrofluorocarbon restrictions in lighting manufacturing are redirecting producer R&D toward halide salt formulations with lower global warming potential.
Market Restraints
- Rare earth element price volatility:Scandium and dysprosium iodide salts face supply concentration among Chinese processors, amplifying input cost unpredictability for arc tube producers.
- Mercury content thresholds:EPA Toxic Substances Control Act and EU RoHS Directive impose strict caps on lamp imports, raising compliance costs for smaller exporters without captive testing facilities.
- LED luminous efficacy gaps:Solid-state systems now exceed 150 lumens per watt in street lighting tenders, disqualifying metal halide from municipal procurement where lumen-per-watt minimums dominate scoring.
Strategic Opportunities
- Industrial retrofit cycles in China's eastern corridor:National energy intensity targets are shortening replacement intervals for factory floor lighting, creating volume concentration in Jiangsu and Zhejiang provinces.
- UV-C germicidal metal halide variants:Pandemic-era demand for high-intensity ultraviolet disinfection is opening adjacent revenue streams in healthcare and food processing facilities.
- Vertical farming spectrum optimization:Tunable ceramic metal halide systems with enhanced red-blue output are penetrating controlled-environment agriculture installations where photosynthetic photon flux density requirements exceed LED economics at scale.
Industry Challenges
- Arc tube ceramic engineering talent scarcity:Specialized knowledge in polycrystalline alumina sintering and halide salt dosing concentrates among aging workforces in Germany and Japan.
- Legacy ballast compatibility complexity:Electromagnetic and electronic ballast fragmentation across installed bases complicates SKU rationalization and inventory management for distributors.
- RoHS compliance testing timelines:Third-party certification delays for hazardous substance documentation extend new product introduction cycles by 4-6 months for EU-bound shipments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Metal Halide Market |
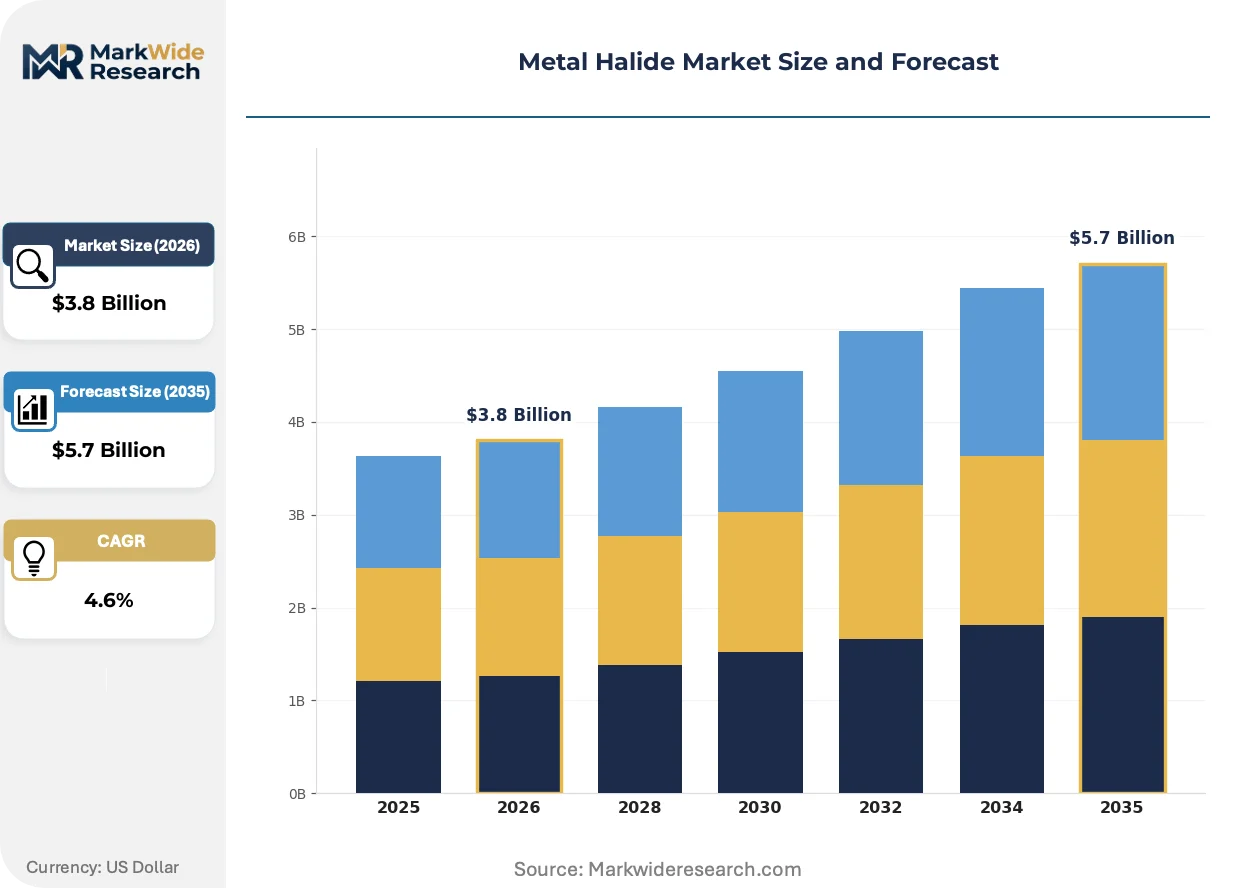
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: High-Pressure, Low-Pressure, Standard, Compact Application: Commercial Lighting, Sports Facilities, Street Lighting, Industrial Lighting Technology: LED, Conventional, Smart, Energy-Efficient End User: Retail, Hospitality, Transportation, Manufacturing |
| Companies Covered | Philips, Osram, GE Current, Acuity Brands Lighting, Eaton Corporation, Hubbell, HELLA GmbH, Generac Holdings, Atlas Copco, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Metal Halide Market Evolving Landscape
Metal halide technology is bifurcating between premium ceramic systems defending high-CRI applications and commodity quartz lamps facing accelerated substitution, with innovation concentrating in thermal management and spectral tuning rather than fundamental efficacy gains.
Ceramic metal halide arc tubes are expanding into high-bay industrial and retail environments where color rendering index requirements exceed 90 and thermal shock resistance proves critical. Food processors and automotive paint booths are adopting these systems fastest, displacing quartz alternatives within five-year replacement windows. The technology is expanding into applications previously reserved for tungsten-halogen and early LED generations, compressing mid-market pricing tiers.
China's GB standards for discharge lamp safety and efficiency testing are fragmenting compliance requirements for exporters, with mandatory salt spray testing and seismic simulation protocols added to 2024 implementation guidance. Manufacturers serving multiple geographies must maintain parallel certification tracks, elevating fixed costs for product development. European producers are responding by regionalizing lamp assembly to avoid cross-border retesting burdens.
Buyer consolidation among facility management conglomerates is centralizing procurement decisions for multi-site retail and logistics chains, squeezing distributor margins and favoring direct manufacturer relationships with national account pricing. Group purchasing organizations now aggregate lighting spend across hospitality and healthcare verticals, displacing traditional electrical wholesale channels. This concentration is most visible in North American big-box retail and German automotive supplier parks.
Metal Halide Market Segmentation
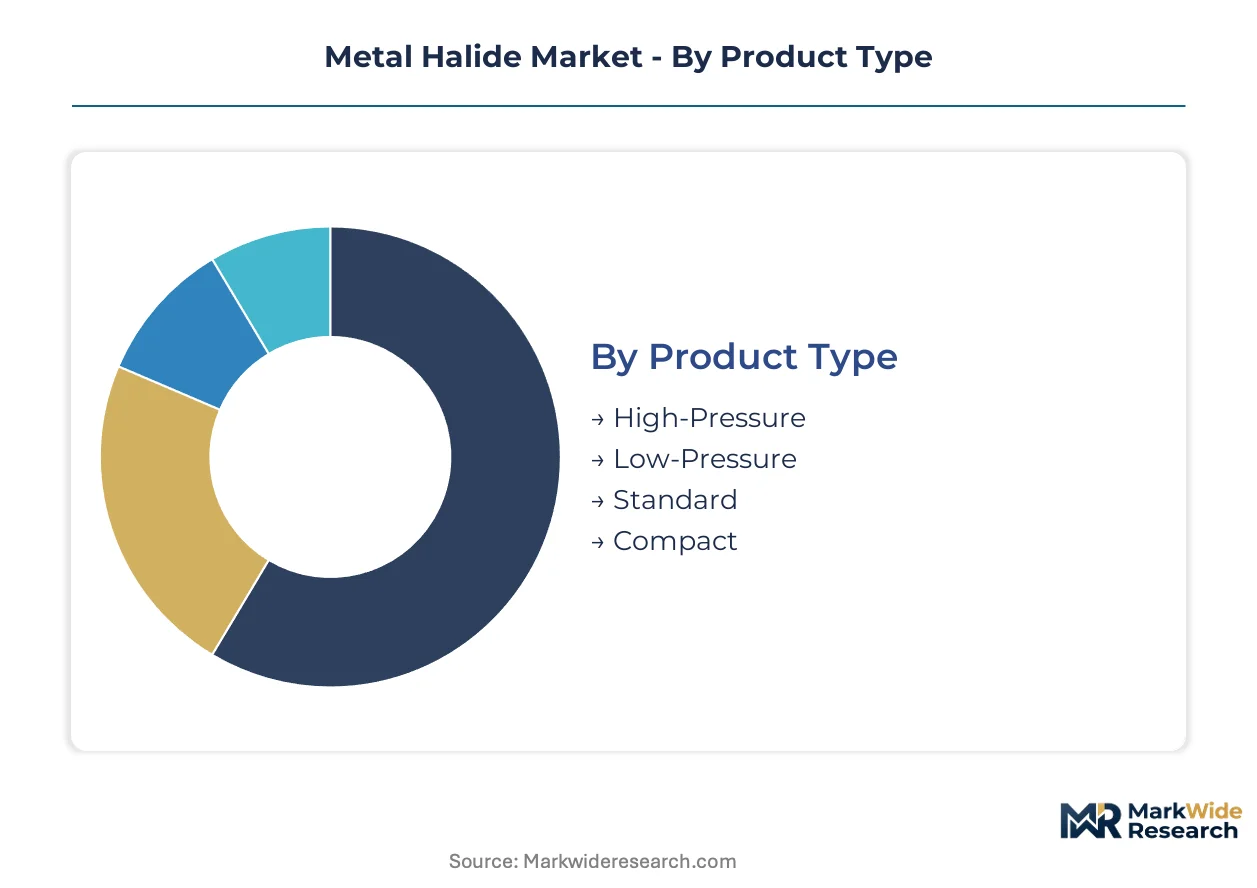
Metal halide lamp buyers exhibit sharply divergent priorities across technical specifications, regulatory exposure, and lifecycle economics. Understanding these fault lines enables suppliers to align R&D investment with segments where arc tube chemistry and thermal engineering command premium pricing power.
Product Type:
Cost tier separates buyers seeking extended lamp life in vibration-intensive environments from those prioritizing fixture compatibility in retrofit scenarios.
- High-Pressure:Polycrystalline alumina arc tubes withstand thermal cycling in foundries and forging operations where quartz envelopes fracture within months. Demand concentrates in Germany's automotive supplier parks and Japan's steel processing corridors, driven by RoHS compliance timelines that disqualify mercury vapor alternatives.
- Compact:Reduced envelope dimensions enable retrofit into existing downlight housings without structural modification. North American big-box retail chains specify these for ceiling height constraints below four meters, though LED substitution is compressing replacement cycle visibility.
- Low-Pressure:Lower thermal load operation suits climate-controlled commercial interiors with minimal vibration exposure.
- Standard:Commodity quartz construction dominates spot procurement for budget-constrained municipal tenders.
High-pressure systems lead volumes today; compact variants are gaining share fastest.
Application:
Volume concentration tracks infrastructure age and local energy ordinance stringency rather than new construction cycles.
- Sports Facilities:Color rendering index requirements above 90 and beam penetration specifications preserve metal halide dominance in North American stadium retrofits. Local efficiency ordinances in California and New York mandate mercury vapor phase-outs, pulling demand through lamp replacement windows.
- Industrial Lighting:Ceramic arc tube penetration is deepest in food processing and automotive paint booths where thermal shock resistance prevents contamination from envelope failure. China's Jiangsu and Zhejiang provinces are shortening factory floor retrofit intervals to meet national energy intensity targets.
- Commercial Lighting:Office and hospitality installations face accelerating LED displacement as lumen-per-watt economics improve.
- Street Lighting:Municipal procurement criteria now exclude metal halide from most North American and European tenders based on efficacy minimums.
Sports facilities anchor current revenue; industrial lighting is expanding most quickly.
Technology:
Maturity gradient separates legacy installed base defense from adjacent wavelength applications requiring spectral tunability.
- Conventional:Electromagnetic ballast compatibility and established distributor relationships sustain aftermarket revenue in aging North American infrastructure. Margin pools are compressing as LED retrofits accelerate, forcing suppliers toward phosphor-coated premium SKUs.
- Energy-Efficient:Ceramic metal halide variants with improved luminous efficacy target EU F-Gas Regulation compliance by reducing halide salt quantities with high global warming potential. German and Japanese producers concentrate polycrystalline alumina sintering expertise.
- LED:Solid-state substitution is cannibalizing metal halide across all application segments except high-CRI niche requirements.
- Smart:Connected fixture integration remains underdeveloped for arc discharge systems relative to solid-state competitors.
Conventional technology dominates installed base; energy-efficient variants show the steepest expansion trajectory.
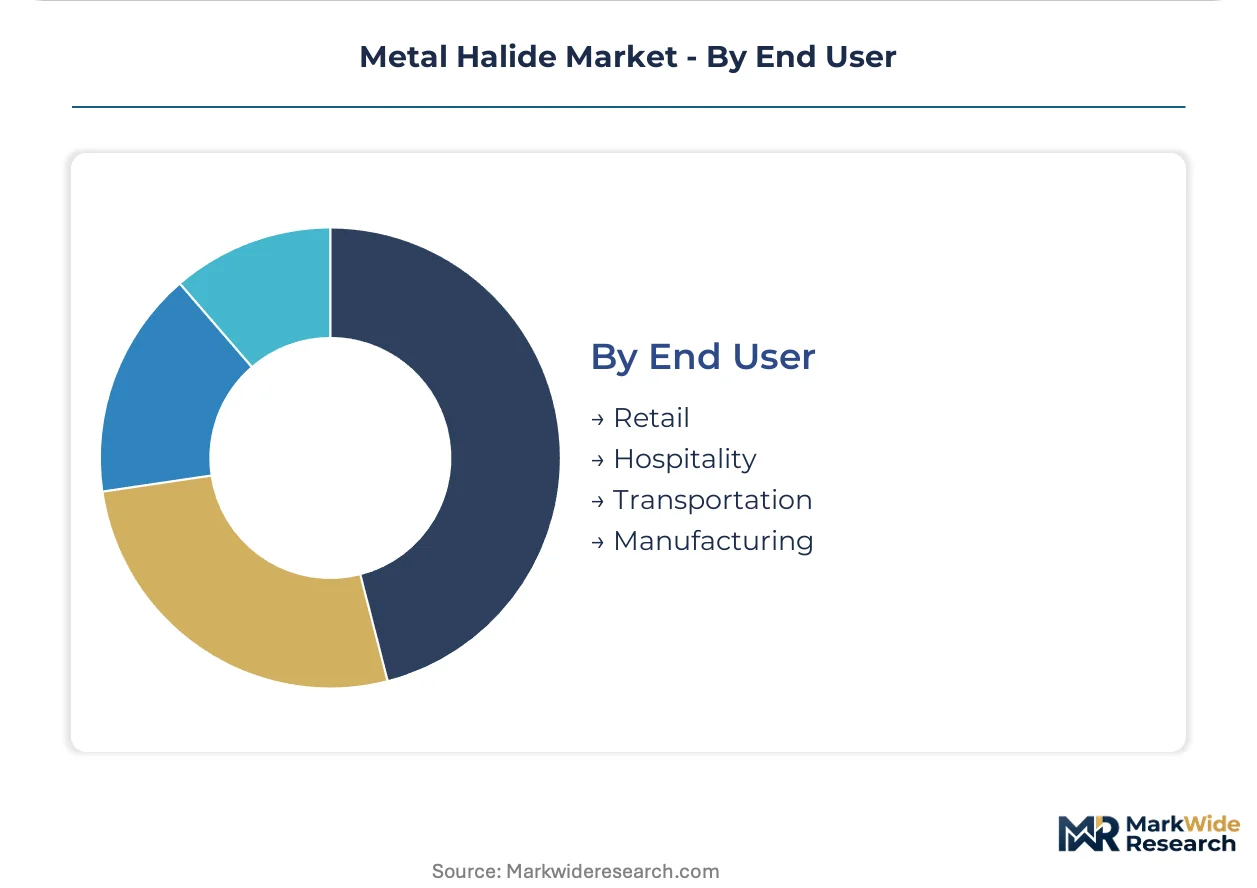
End User:
Procurement centralization among facility management conglomerates is reshaping channel economics across buyer categories.
- Manufacturing:Group purchasing organizations aggregate lighting spend across multi-site automotive and electronics production networks, squeezing distributor margins and favoring direct manufacturer relationships with national account pricing structures.
- Retail:Big-box chains specify ceramic metal halide for color-critical merchandise display while consolidating procurement decisions at headquarters level, displacing traditional electrical wholesale channels.
- Hospitality:Hotel operators prioritize lamp life and color consistency in lobby and ballroom applications with infrequent fixture access.
- Transportation:Airport and rail maintenance facilities face mixed incentives between metal halide beam penetration and LED maintenance reduction.
Manufacturing commands the largest share; retail procurement concentration is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's eastern manufacturing corridor concentrates the densest installed base of industrial metal halide systems, with Jiangsu and Zhejiang provinces driving replacement demand under national energy intensity mandates. Regional variation tracks regulatory phase-out timelines, rare earth processing proximity, and sports infrastructure age.
United States
Sports stadium retrofits in California and New York anchor demand as local efficiency ordinances mandate mercury vapor phase-outs. EPA Toxic Substances Control Act compliance costs filter smaller importers from the aftermarket. Dallas-Fort Worth and Los Angeles metropolitan areas concentrate the largest aging high-bay industrial installations.
Germany
Automotive supplier parks in Bavaria and Baden-Württemberg prioritize ceramic arc tube systems for paint booth color consistency under EU RoHS Directive timelines. EU F-Gas Regulation phase-downs redirect producer R&D toward alternative halide salt formulations. Frankfurt-Rhine-Main logistics hubs drive warehousing retrofit cycles.
China
Jiangsu province factory floors shorten replacement intervals to meet dual carbon goals and national energy intensity targets. GB standards for discharge lamp safety fragment compliance requirements for domestic versus export production. Zhejiang's Ningbo and Wenzhou lighting manufacturing clusters integrate rare earth processing with lamp assembly.
Japan
Steel processing corridors in Chubu and Kansai regions demand polycrystalline alumina arc tubes for thermal shock resistance in high-vibration environments. METI efficiency standards accelerate quartz-to-ceramic upgrades. Nagoya automotive production networks sustain group purchasing organization concentration.
India
Maharashtra and Gujarat industrial zones initiate metal halide retrofits as BIS standards tighten mercury content thresholds for import clearance. Central Electricity Authority guidelines push factory floor efficacy minimums. Mumbai-Pune manufacturing belt concentrates food processing demand for high-CRI illumination.
Metal Halide Market Competitive Landscape
Global majors compete with regional champions across arc tube chemistry and thermal engineering capabilities. The vendor base splits between vertically integrated lamp producers controlling rare earth salt supply and assembly-focused competitors sourcing components through spot markets. Three archetypes dominate: captive ceramic processors, electronics conglomerates with lighting divisions, and industrial equipment suppliers bundling illumination with power infrastructure. Competitive moves concentrate on backward integration into arc tube ceramics and regional assembly hub expansion to shorten logistics lead times.
Among diversified electronics conglomerates, Philips and Osram occupy positions defined by captive manufacturing capabilities and long-term rare earth supply agreements. GE Current exemplifies the industrial infrastructure bundling archetype. These three anchors represent distinct strategic postures: upstream control over arc tube materials, sustained processor relationships, and regional logistics optimization respectively.
| Leading Market Players |
|---|
| Philips |
| Osram |
| GE Current |
| Acuity Brands Lighting |
| Eaton Corporation |
| Hubbell |
| HELLA GmbH |
| Generac Holdings |
| Atlas Copco |
| Others |
Value Network & Pricing Analysis
Group purchasing organizations aggregating lighting spend across multi-site automotive and retail networks dictate contract-based long-term offtake pricing with volume-scaled discounts. This buyer concentration compresses spot-market premiums and forces suppliers toward captive arc tube production to defend margin pools.
Pricing Analysis
Rare earth salt cost pass-through dominates pricing dynamics, with scandium and dysprosium iodide volatility transmitted directly to ceramic arc tube premiums. Three-tier pricing structure across premium phosphor-coated, standard quartz, and economy retrofit levels separates buyers by certification grade and thermal performance specifications. Cost compression in commodity quartz tiers is intensifying because LED substitution accelerates in municipal street lighting tenders. Municipal procurement teams exhibit highest price sensitivity, while food processors and automotive paint booths prioritize color rendering index consistency over unit economics.
Supply Chain Analysis
Direct-to-industrial channels handle high-volume factory floor demand, while electrical wholesale distributors serve fragmented retrofit replacement markets. Polycrystalline alumina arc tube production concentrates in Germany, Japan, and China's Jiangsu province, with rare earth halide salt processing anchored in Chinese Inner Mongolia and Ganzhou clusters. The supply chain draws from tungsten electrode suppliers in Austria, quartz envelope manufacturers in the United States, and ceramic powder specialists in Japan. Single-source vulnerability in scandium iodide refining creates exposure to export license restrictions. Distribution runs through regional assembly hubs in Dallas-Fort Worth, Frankfurt-Rhine-Main, and Ningbo to shorten logistics lead times to industrial buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The metal halide market functions as a stable compounder, with sports infrastructure modernization and industrial retrofit cycles providing predictable replacement revenue streams despite LED encroachment.
For Market Incumbents: Acquire specialized polycrystalline alumina sintering capabilities in Germany or Japan to lock in ceramic arc tube engineering talent. Secure long-term offtake agreements with Chinese rare earth processors before EU F-Gas Regulation phase-downs redirect competitor sourcing. Channel control through direct national account relationships with facility management conglomerates defends aftermarket revenue against distributor margin compression. For New Entrants and Emerging Players: Begin with UV-C germicidal metal halide variants for healthcare and food processing facilities, where pandemic-era disinfection protocols sustain premium pricing. Target vertical farming installations in China's eastern corridor, where tunable spectrum systems exceed LED economics at scale for photosynthetic photon flux density requirements. A technical sales force emphasizing spectral engineering consultation differentiates against commodity lamp assemblers. For Investors and Strategic Acquirers: Industrial equipment suppliers bundling illumination with power infrastructure are the most active acquirer in this space, seeking captive arc tube supply to complement existing electrical distribution networks. Acquisition candidates include regional lamp assemblers with established GB standards certification for China domestic production and export clearance. Watch municipal procurement criteria in California and New York for lumen-per-watt threshold adjustments that could accelerate or delay mercury vapor phase-out timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Arc Tube Ceramics | Captive polycrystalline alumina production buffers Philips and Osram against rare earth cost swings. |
| Regional Assembly Hub Expansion | GE Current's Dallas-Fort Worth facility shortens logistics lead times to North American industrial buyers. |
| UV-C Germicidal Variant Development | Pandemic-era healthcare disinfection protocols open adjacent revenue streams beyond general illumination. |
| Long-term Rare Earth Supply Agreement | Osram's sustained processor relationships in China secure scandium iodide access despite export concentration. |
| Phosphor-Coated Premium SKU Introduction | Extended lamp life warranties defend aftermarket revenue against accelerating LED substitution rates. |
Research Methodology
Multiple input streams — technical interviews with arc tube ceramics engineers, procurement discussions with facility management conglomerates, and regulatory filings with EPA and EU ECHA — were reconciled against trade data and industry association disclosures. Primary fieldwork captured perspectives from plant engineers at German automotive supplier parks, maintenance directors in Japan's steel processing corridors, and lighting specification consultants for North American stadium retrofits. Secondary validation drew from EPA Toxic Substances Control Act guidance documents, EU RoHS Directive implementation notices, China's GB standards discharge lamp testing protocols, and customs records tracking rare earth salt imports. Bottom-up unit economics and top-down market sizing were cross-referenced to establish volume and value estimates.
Historical shipment data was cross-referenced against expert panel assessments of replacement cycle timing and regulatory phase-out schedules. The forecast framework models product type segmentation across high-pressure, compact, low-pressure, and standard variants; application splits across sports facilities, industrial lighting, commercial installations, and street infrastructure; technology tiers separating conventional electromagnetic ballast systems from energy-efficient ceramic alternatives; and end-user concentration among manufacturing, retail, hospitality, and transportation verticals. CAGRs were derived from regression analysis of retrofit interval compression and substitution elasticity parameters. Industry-specific inputs include EU F-Gas Regulation halide salt restriction timelines and China's national energy intensity target enforcement trajectories across the analysis window.
Several conditions sit outside the modeled scope, including unannounced breakthroughs in solid-state lighting economics, abrupt rare earth export restrictions, and municipal procurement criteria revisions that could accelerate LED mandates beyond current ordinance timelines. Forecasts reflect assumptions about ceramic arc tube adoption rates and phosphor-coated premium SKU penetration that warrant periodic reassessment. Periodic stress-testing of base assumptions against actual retrofit cycle data and regulatory implementation pacing is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Metals
Europe Metal Precision Turned Product Manufacturing Market
Specialty Metals
North America Metal Turned Precision Product Manufacturing Market
Specialty Metals
Specialty Metallic Pigments Market
Specialty Metals
Precision Stainless Steel Market
Specialty Metals
Dysprosium Market
Specialty Metals
Precious Metal Plating Market
Specialty Metals
Global Special Steel Market
Specialty Metals
Global Metal Bellows Market
Specialty Metals
Case Hardening Steel Market