
 North America Metal Turned Precision Product Manufacturing Market | 2026-2036
North America Metal Turned Precision Product Manufacturing Market Size, Share, and Industry Trends Forecast 2026-2036
North America Metal Turned Precision Product Manufacturing Market Insights
Equipment leasing and asset-light machining networks is fragmenting competitive control across North America. Melling Tool Co sustains vertical integration from raw bar stock to finished automotive fasteners. Kamatics Corporation specializes in aerospace-grade bushing and bearing assemblies for defense platforms. Cox Manufacturing Company anchors high-volume Swiss turning capacity for medical device OEMs.
Metal turned precision product manufacturing encompasses the subtractive fabrication of cylindrical components via single-point cutting on lathes or CNC turning centers, typically holding tolerances of ±0.0005 inches or tighter for critical-fit applications. The process produces screws, bolts, bushings, and washers that serve as mechanical interfaces, load-bearing elements, and vibration-dampening interfaces across industrial equipment. Stainless steel and alloy steel material grades dominate structural aerospace and automotive applications where fatigue resistance governs specification. Turning technology leads machining method selection for true cylindrical geometries, while EDM complements extreme-hardness or internal-feature requirements in medical device and electronics end uses.
FAA airworthiness directives and NHTSA safety standards mandate material certification and traceability for flight-critical and automotive turned components sold in the United States. EPA metalworking effluent guidelines restrict coolant chemistry and chip handling practices, pushing shops toward closed-loop filtration investments. Health Canada and PMRA parallel requirements in Ontario and Quebec tighten cross-border supply chain compliance. Stakeholders must weigh captive machining capacity against outsourced precision networks as regulatory audit scope widens.
Market Dynamics
Equipment leasing and asset-light machining networks is fragmenting competitive control across North America, eroding the pricing power of vertically integrated incumbents while enabling smaller Swiss-turning specialists to capture aerospace and medical device contracts through distributed capacity models.
Growth Catalysts
- Aerospace OEM expansion in Mexico:Flight-critical turned component orders from Mexican aerospace manufacturing clusters are pulling precision capacity southward, creating cross-border supply chain density.
- NHTSA safety standards:Material certification and traceability mandates for automotive fasteners are locking out uncertified suppliers and consolidating qualified vendor pools.
- Closed-loop coolant systems:EPA metalworking effluent guidelines are forcing capital upgrades that favor larger shops with environmental compliance infrastructure.
Market Restraints
- Alloy steel price volatility:Nickel and molybdenum input cost swings compress margin predictability for long-diameter bar stock programs.
- Great Lakes corridor concentration:Michigan-Ohio-Ontario supply clustering creates weather and logistics vulnerability for just-in-time automotive supply chains.
- Additive manufacturing substitution:Metal 3D printing for complex internal geometries is capturing prototype and low-volume work from five-axis turning centers.
Strategic Opportunities
- Quebec precision medical corridor:Health Canada device licensing harmonization with FDA pathways is attracting Swiss-turning investment for orthopedic implant components.
- EV powertrain hardware:Electric vehicle battery tray fasteners and motor shaft couplings represent specification-white-space for turned alloy steel grades.
- Digital thread integration:Convergence of machine tool IoT sensors with ERP quality modules is enabling predictive tolerance drift correction.
Industry Challenges
- CNC programming talent scarcity:Multi-axis Swiss turning and live-tooling CAM expertise gaps constrain shop-floor expansion in Ontario and Michigan.
- FAA airworthiness certification timelines:Material lot traceability and first-article inspection protocols extend new supplier qualification cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Metal Turned Precision Product Manufacturing Market |
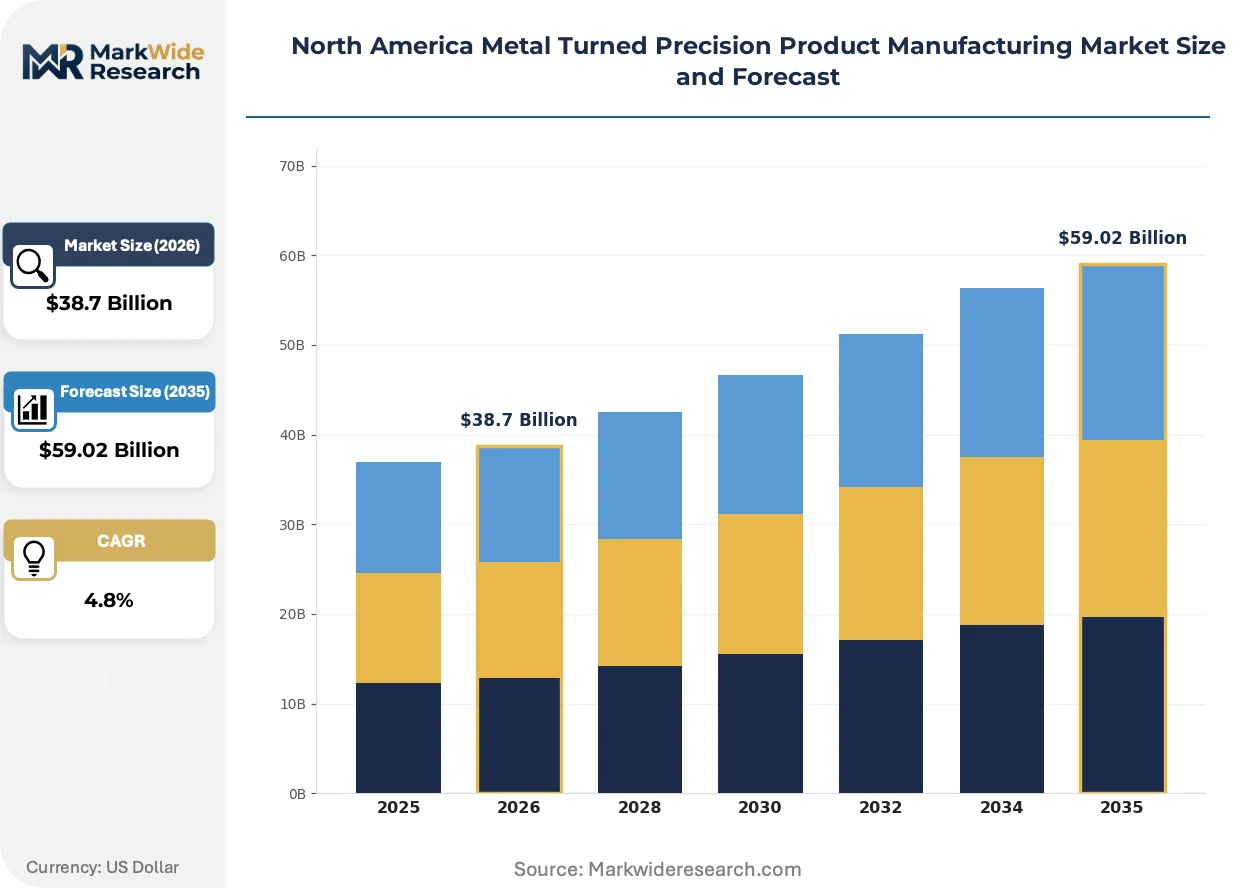
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $59.02 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Screws, Bolts, Bushings, Washers Machining Technology: Turning, Milling, Grinding, EDM Material: Aluminum, Brass, Stainless Steel, Alloy Steel End User: Aerospace, Automotive, Electronics, Medical Devices |
| Companies Covered | Premier Farnell Corp, Melling Tool Co, Kamatics Corporation, Sorenson Engineering Inc, Cox Manufacturing Company, Creed-Monarch Inc, Camcraft Inc, M & W Industries Inc, Greystone of Lincoln Inc, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Metal Turned Precision Product Manufacturing Market Trends and Innovations
Digital manufacturing infrastructure is compressing the distance between design iteration and production-ready turned components, collapsing traditional prototyping lead times while embedding quality assurance into machine control logic rather than post-process inspection.
Digital twin software for CNC turning centers is virtualizing machine behavior before metal cutting begins, allowing aerospace suppliers to validate tool paths and predict surface finish outcomes without scrapping titanium bar stock. Medical device OEMs in Minnesota and Massachusetts are adopting these platforms fastest, running virtual first-article inspections that compress FDA submission timelines. The technology is virtualizing traditional metrology workflows, displacing coordinate measuring machine bottlenecks with real-time spindle-load feedback loops.
EPA metalworking effluent guidelines are mandating zero-discharge coolant systems for facilities above defined throughput thresholds, forcing capital allocation toward vacuum distillation and membrane filtration. Shops in Ohio and Michigan are consolidating wet-machining capacity to centralized plants while satellite facilities transition to minimum-quantity lubrication. Automotive fastener manufacturers face the steepest compliance curves, as high-volume chip generation triggers the strictest discharge monitoring.
Consolidated supplier scorecards are compressing vendor lists across aerospace and medical device procurement functions, rewarding turned-component suppliers with embedded quality data and lot-level digital traceability. Distributors serving the Great Lakes automotive corridor are losing share to direct mill relationships as OEMs consolidate fastener spend with fewer qualified sources. The shift is most visible in Michigan, where Tier-1 suppliers now mandate machine-connectivity APIs as a condition of contract award.
North America Metal Turned Precision Product Manufacturing Market Segmentation
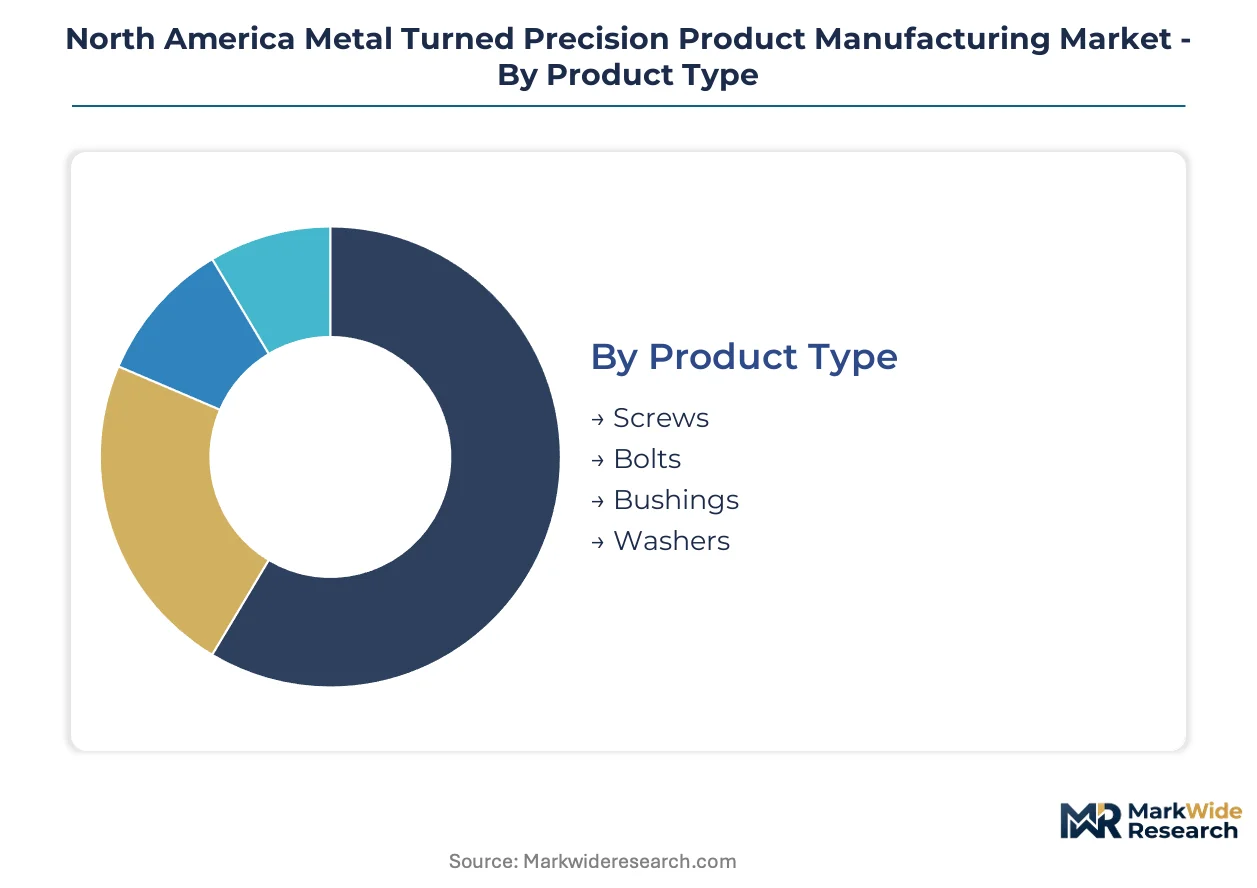
Precision turned components serve as mechanical interfaces across industrial equipment, with specification requirements varying sharply by end-use criticality. Segmentation reveals how cycle-time pressures and tolerance demands reshape supplier specialization across the continent.
Product Type:
Cycle times compress fastest for high-volume fastener categories, while custom bushing programs extend production horizons through extended qualification protocols.
- Screws:Thread-forming and thread-cutting variants dominate high-volume automotive assembly lines, with Michigan OEMs driving demand for metric and imperial standardization. Michigan-Ohio automotive corridors consume the highest screw volumes, though Mexican aerospace clusters are pulling precision socket-head capacity southward for flight-critical applications.
- Bolts:High-tensile alloy steel grades anchor structural aerospace and heavy-equipment applications where fatigue resistance governs specification. Ontario and Quebec defense contractors specify NAS and MS standard bolts with full material traceability, locking out uncertified suppliers from qualified vendor pools.
- Bushings:Self-lubricating and press-fit variants serve as vibration-dampening interfaces across rotating equipment.
- Washers:Flat, lock, and Belleville configurations distribute clamping loads in bolted assemblies.
Screws dominate installed base by unit volume. Bolts is where expansion concentrates for margin-accretive aerospace and defense contracts.
Machining Technology:
Cost tiers separate commodity turning from premium EDM work, with technology selection directly governing achievable tolerances and capital intensity.
- Turning:Single-point cutting on lathes and CNC turning centers produces true cylindrical geometries holding tolerances of ±0.0005 inches or tighter. The Great Lakes corridor concentrates Swiss-turning capacity for medical device and automotive fastener OEMs, with live-tooling investments enabling complex features without secondary operations.
- EDM:Wire and sinker configurations machine extreme-hardness materials and internal geometries inaccessible to conventional cutting tools. Minnesota and Massachusetts medical device manufacturers deploy EDM for titanium and cobalt-chrome implant components where surface integrity governs biocompatibility.
- Milling:Multi-axis machining centers produce prismatic features on turned blanks.
- Grinding:Cylindrical and centerless configurations achieve sub-micron finishes for bearing surfaces.
Turning dominates installed base across North American job shops. EDM is where expansion concentrates for orthopedic and aerospace superalloy work.
Material:
Application requirements dictate material selection, with corrosion resistance and strength-to-weight ratios driving specification divergence across end-use sectors.
- Stainless Steel:Austenitic and martensitic grades deliver corrosion resistance for medical device and food-processing equipment. Health Canada and FDA device licensing harmonization is attracting Swiss-turning investment to Quebec for orthopedic implant components requiring 316L and 17-4 PH specifications.
- Alloy Steel:Nickel and molybdenum grades provide fatigue resistance for flight-critical aerospace and automotive powertrain applications. EPA metalworking effluent guidelines force closed-loop coolant investments that favor larger Ohio and Michigan shops processing high-alloy bar stock.
- Aluminum:6061 and 7075 grades serve weight-sensitive aerospace and electronics applications.
- Brass:Free-machining alloys target electrical connectors and plumbing fittings.
Alloy steel dominates installed base for structural applications. Stainless steel is where expansion concentrates for medical device and corrosion-critical specifications.
End User:
Customer type governs procurement rigor, with aerospace and medical device OEMs imposing qualification barriers that commodity automotive suppliers rarely match.
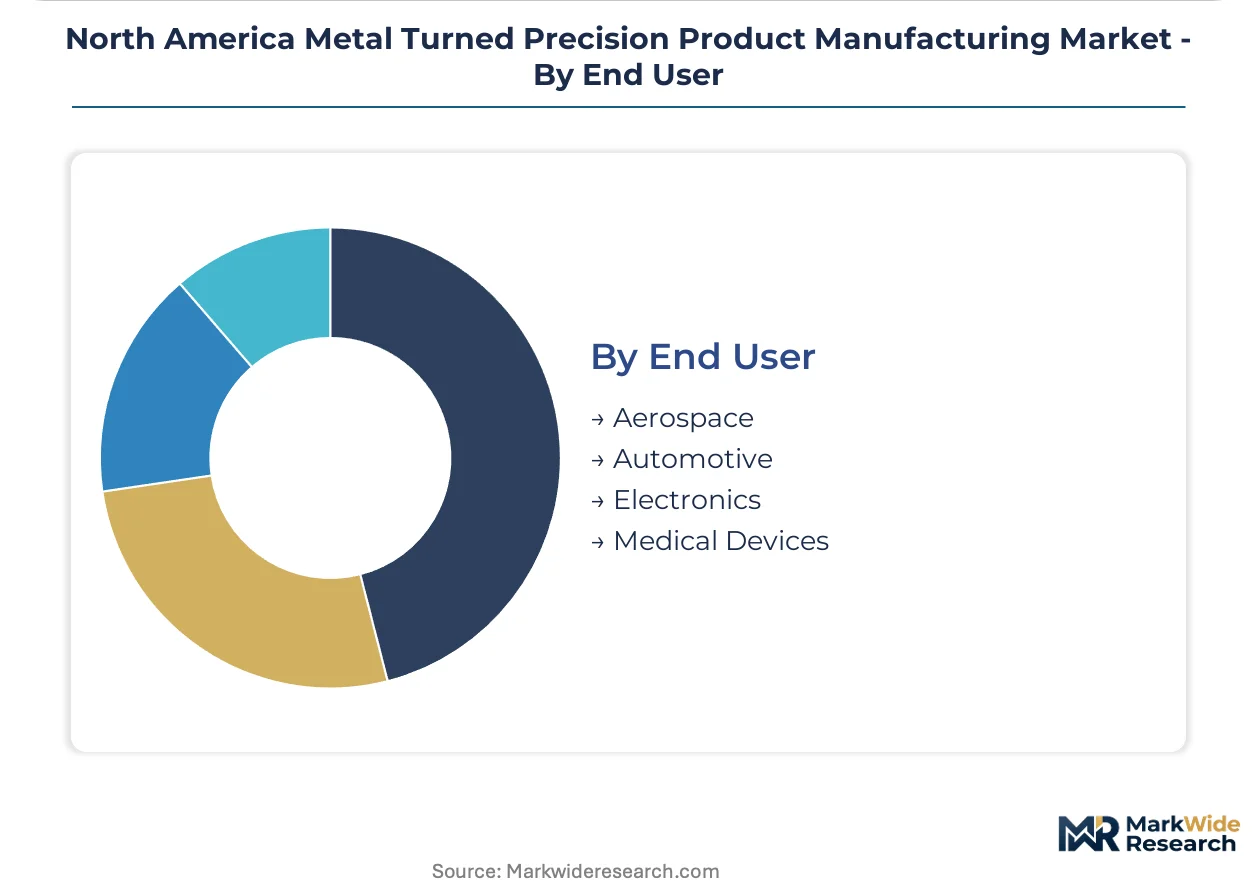
- Aerospace:Flight-critical turned components demand full material lot traceability and first-article inspection protocols per FAA airworthiness directives. Mexican aerospace manufacturing clusters are expanding orders for precision fasteners and bushing assemblies, creating cross-border supply chain density that pulls capacity from Texas and California.
- Automotive:NHTSA safety standards mandate material certification for structural fasteners, consolidating qualified vendor pools as uncertified suppliers face exclusion. EV powertrain hardware represents specification-white-space for battery tray fasteners and motor shaft couplings in alloy steel grades.
- Medical Devices:Orthopedic implants and surgical instruments require biocompatible surface finishes and FDA submission documentation.
- Electronics:Miniature turned connectors and heat sinks target precision form factors.
Automotive dominates installed base by production volume. Aerospace is where expansion concentrates for margin and long-term contract stability.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows across North America reveal concentrated precision manufacturing capacity in the Great Lakes corridor, with cross-border component shipments tightening supply chain interdependence among the three member economies.
United States
Michigan and Ohio automotive OEMs drive demand for high-tensile alloy steel fasteners, while Minnesota medical device manufacturers specify Swiss-turned orthopedic implants. FAA airworthiness directives mandate material lot traceability for flight-critical components sourced from domestic aerospace clusters. The Great Lakes manufacturing corridor anchors the continent's highest density of CNC turning capacity.
Canada
Ontario defense contractors specify NAS and MS standard bolts with full material certification, locking procurement to qualified vendor pools. Health Canada and PMRA parallel EPA requirements on metalworking effluent, pushing Ontario shops toward closed-loop coolant investments. Quebec's precision medical corridor attracts Swiss-turning specialists serving orthopedic implant OEMs with FDA-harmonized submission pathways.
Mexico
Querétaro and Baja California aerospace manufacturing clusters expand orders for flight-critical turned bushings and fasteners, pulling precision capacity southward from Texas and California. Mexican federal environmental standards under SEMARNET tighten coolant discharge monitoring for maquiladora machining operations. Nuevo León's industrial parks concentrate new Swiss-turning investments serving cross-border automotive supply chains.
North America Metal Turned Precision Product Manufacturing Market Competitive Landscape
On the supply side, the industry is fragmenting across asset-light machining networks and equipment leasing models, eroding pricing power for vertically integrated incumbents while enabling smaller Swiss-turning specialists to capture aerospace and medical contracts. Three archetypes dominate: captive automotive fastener divisions, independent precision job shops, and aerospace-certified specialty houses. Competitive moves concentrate on M&A consolidation of qualified supplier pools and geographic expansion toward Mexican aerospace clusters.
Among North American precision fabricators, Melling Tool Co, Kamatics Corporation, and Cox Manufacturing Company occupy distinct positions within this tiered structure. Melling Tool Co exemplifies backward-integrated control from raw bar stock through finished automotive fasteners. Kamatics Corporation represents the aerospace-defense specialty archetype with focused certification depth. Cox Manufacturing Company anchors high-volume Swiss-turning capacity serving medical device OEMs with embedded quality data systems.
| Leading Market Players |
|---|
| Premier Farnell Corp |
| Melling Tool Co |
| Kamatics Corporation |
| Sorenson Engineering Inc |
| Cox Manufacturing Company |
| Creed-Monarch Inc |
| Camcraft Inc |
| M & W Industries Inc |
| Greystone of Lincoln Inc |
| Others |
Pricing and Supply Chain Analysis
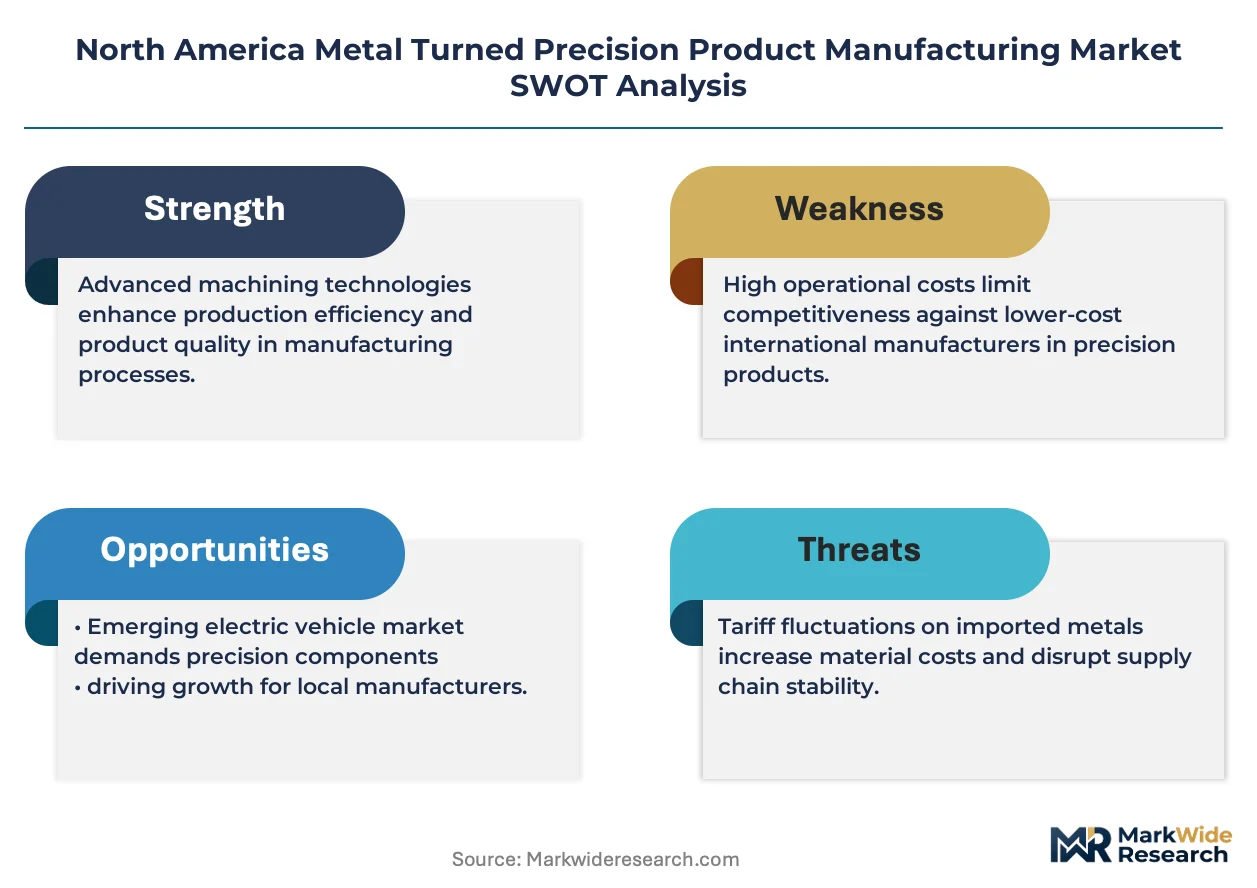
Great Lakes bar stock distributors anchor upstream concentration for North American precision turned components, feeding margin pools toward aerospace-certified specialty houses and Swiss-turning medical specialists rather than commodity automotive fastener producers. Nickel and molybdenum alloy steel pricing volatility compresses predictability for long-diameter programs, while EPA closed-loop coolant mandates favor capital-rich Ohio and Michigan shops with environmental infrastructure.
Pricing Analysis
Industrial OEM buyers anchor a contract-based long-term offtake structure with volume-tiered discounts and certification-grade premiums. Price differentiation separates FAA-certified aerospace lots from uncertified automotive commodity runs, with brand reputation and full material traceability commanding substantial uplifts. Cost compression in high-volume fastener tiers intensifies as Mexican maquiladora capacity pulls pricing southward. Tier-1 automotive procurement teams exhibit highest price sensitivity, while orthopedic implant OEMs prioritize lot-level digital traceability over unit cost.
Supply Chain Analysis
Alloy steel feedstock draws from US, Canadian, and Mexican mill sources, with specialty nickel grades tethered to single-source long-term agreements. Raw material dependencies center on nickel, molybdenum, and high-grade stainless bar stock, while cobalt-chrome superalloys feed orthopedic implant demand. Tariff exposure on cross-border Mexican shipments creates structural vulnerability for just-in-time aerospace supply chains. Distribution runs through direct mill relationships consolidating fastener spend, displacing traditional Great Lakes distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Digital manufacturing infrastructure is accelerating competitive disruption across North American precision turning, with EPA effluent mandates and FAA digital traceability requirements creating decisive capability gaps between connected and legacy shops.
For Market Incumbents: Pre-empt additive manufacturing substitution by embedding machine-connectivity APIs into contract terms before Tier-1 automotive procurement mandates universal adoption. Consolidate qualified supplier pools through targeted acquisition of Ontario and Quebec Swiss-turning specialists with Health Canada-FDA harmonized submission pathways. Defensive capacity addition in Nuevo León industrial parks secures proximity to expanding Mexican aerospace clusters.
For New Entrants and Emerging Players: Pursue EV powertrain hardware specification-white-space for battery tray fasteners and motor shaft couplings, where alloy steel grade standards remain unsettled. Quebec's precision medical corridor offers lowest barriers to entry given FDA-harmonized device licensing and converging orthopedic implant demand. Go-to-market positioning through embedded quality data and lot-level digital traceability bypasses established distributor relationships.
For Investors and Strategic Acquirers: Capital is best deployed toward aerospace-certified specialty houses with captive Swiss-turning capacity and existing FAA material lot traceability protocols, rather than undifferentiated commodity fastener producers facing Mexican pricing pressure. Long-term viability over the mid-term projection horizon favors shops with closed-loop coolant infrastructure already amortized. Watch for NHTSA safety standard expansion into EV-specific fastener categories as inflection signal for consolidation timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bar Stock Processing | Melling Tool Co's captive raw material control insulates margin from nickel price volatility. |
| Swiss-Turning Capacity Expansion | Cox Manufacturing anchors high-volume orthopedic implant supply with embedded quality data systems. |
| Cross-Border Mexican Aerospace Cluster Entry | Querétaro flight-critical component demand pulls precision capacity from Texas and California. |
| Closed-Loop Coolant Infrastructure Investment | EPA effluent guidelines force capital allocation favoring larger Ohio and Michigan shops. |
| Digital Thread Integration Partnership | Machine tool IoT sensor convergence with ERP modules enables predictive tolerance drift correction. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of regulatory filings, customs trade data, and industry association reports. Primary interviews engaged CNC programming specialists, Tier-1 automotive procurement directors, aerospace quality assurance leads, and medical device regulatory affairs managers across Michigan, Ohio, Ontario, and Quebec. Secondary validation drew from EPA metalworking effluent guideline dockets, FAA airworthiness directive archives, Health Canada device licensing databases, and SEC filings from publicly traded precision manufacturing parent entities. Bottom-up shop-level capacity assessments triangulate against top-down end-use demand segmentation.
Forecast inputs span machining technology adoption curves, material grade specification shifts, and regulatory compliance cost trajectories across the projection horizon. Segmentation dimensions model product type, machining technology tier, material specification, and end-use criticality with geographic production cluster overlay. CAGRs derive from installed base erosion rates for conventional turning centers versus Swiss-turning and EDM expansion in medical and aerospace superalloy applications. Alloy steel price volatility assumptions and EPA compliance capital requirements inform scenario-weighted outputs.
Macroeconomic conditions sit as an overlay; deviation in nickel and molybdenum commodity prices, cross-border tariff regimes, or automotive production schedules would shift the trajectory. Forecasts embed assumptions regarding FAA digital traceability mandate timing and Health Canada-FDA harmonization pace. Cross-checking against IHS Markit vehicle production data and Boeing-Airbus order backlogs is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Metals
Metal Halide Market
Specialty Metals
Precious Metal Plating Market
Specialty Metals
Europe Metal Precision Turned Product Manufacturing Market
Specialty Metals
Dysprosium Market
Specialty Metals
Global Metal Bellows Market
Specialty Metals
Specialty Metallic Pigments Market
Specialty Metals
Case Hardening Steel Market
Specialty Metals
Precision Stainless Steel Market
Specialty Metals
Global Special Steel Market