
 Specialty Metallic Pigments Market | 2026-2036
Specialty Metallic Pigments Market Size, Share, and Industry Trends Forecast 2026-2036
Specialty Metallic Pigments Market Outlook
Multi-source procurement is expanding across the specialty metallic pigments value chain as formulators reduce concentration risk. BASF SE leverages its integrated pigment and dispersion capabilities to sustain supply security for automotive coatings customers. Eckart GmbH anchors its position through captive aluminum flake production in Germany. Sun Chemical Corporation competes via specialized paste formulations for the packaging inks segment.
Specialty metallic pigments consist of thin, optically active metal flakes—predominantly aluminum, copper, bronze, or zinc—typically manufactured through ball milling or vacuum metallization to achieve controlled particle sizes between 5 and 150 micrometers, producing distinctive luster, hiding power, and angular color travel in finished goods. Aluminum pigments dominate volume due to their cost-performance ratio in automotive basecoats and industrial maintenance coatings, while copper and bronze pigments command premium positioning in decorative architectural finishes and luxury cosmetics where warmer metallic tones justify higher formulation spend. Powder and paste forms lead current consumption patterns, though flake geometries optimized for waterborne compatibility represent the fastest-growing technical sub-category as environmental compliance tightens across coatings formulations.
REACH registration requirements and the EU F-Gas Regulation constrain solvent-based carrier systems that traditionally suspend metallic flakes, redirecting R&D investment toward waterborne and UV-curable delivery platforms. EPA VOC rules under the Clean Air Act impose comparable reformulation pressures across US architectural and industrial coatings applications. FDA color additive specifications govern cosmetic-grade metallic pigments, creating a dual-track compliance burden for suppliers serving both industrial and personal care end users. Stakeholders must monitor evolving biobased resin compatibility standards and regional carbon border adjustments that could reshape raw material sourcing economics and finished product market access.
Market Dynamics
Waterborne carrier systems are displacing solvent-borne metallic pigment suspensions across automotive and industrial coatings, forcing reformulation investments that favor suppliers with captive flake production and dispersion expertise.
Growth Catalysts
- REACH VOC Thresholds:Tightening EU volatile organic compound limits under REACH and the F-Gas Regulation accelerate migration toward waterborne metallic pigment pastes in decorative and automotive refinish coatings.
- Automotive OEM Phase-Out:Major vehicle manufacturers are eliminating solvent-borne basecoats from new production lines, expanding addressable demand for compatible aluminum and effect pigment systems.
- China Manufacturing Corridors:Concentrated automotive refinish and consumer electronics production in Guangdong and Jiangsu provinces absorb premium metallic pigment volumes for domestic and export finished goods.
Market Restraints
- Aluminum Flake Supply Concentration:Captive vacuum metallization capacity concentrates among German and Chinese producers, creating input bottlenecks during raw metal price volatility.
- Waterborne Compatibility Limits:Surface-treated flake geometries required for stable waterborne dispersion raise unit manufacturing costs versus conventional solvent grades.
- Copper-Zinc Substitution Pressure:Warm-tone bronze and copper pigments face pricing pressure from coated mica and synthetic pearlescent alternatives in mid-tier cosmetic applications.
Strategic Opportunities
- UV-Curable Platform Expansion:Industrial wood and plastic coatings segments in Germany and Italy are adopting UV-curable metallic systems that bypass thermal drying constraints.
- India Automotive Refinish:Underpenetrated vehicle repair networks in Maharashtra and Tamil Nadu represent whitespace for effect pigment suppliers as domestic car parc ages.
- Biobased Resin Alignment:Emerging certification standards for renewable coating binders in France and the Netherlands favor metallic pigments with verified compatibility testing.
Industry Challenges
- Formulation Chemist Scarcity:Waterborne metallic system development requires specialized expertise in surface chemistry and stabilization that outpaces current technical training pipelines.
- Dual-Track Compliance Burden:Suppliers serving both FDA-governed cosmetics and EPA-regulated industrial coatings must maintain parallel quality systems and documentation.
- Legacy Equipment Retrofit Costs:Coatings manufacturers face capital demands for tank cleaning and application line modifications when switching from solvent to waterborne metallic bases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Specialty Metallic Pigments Market |
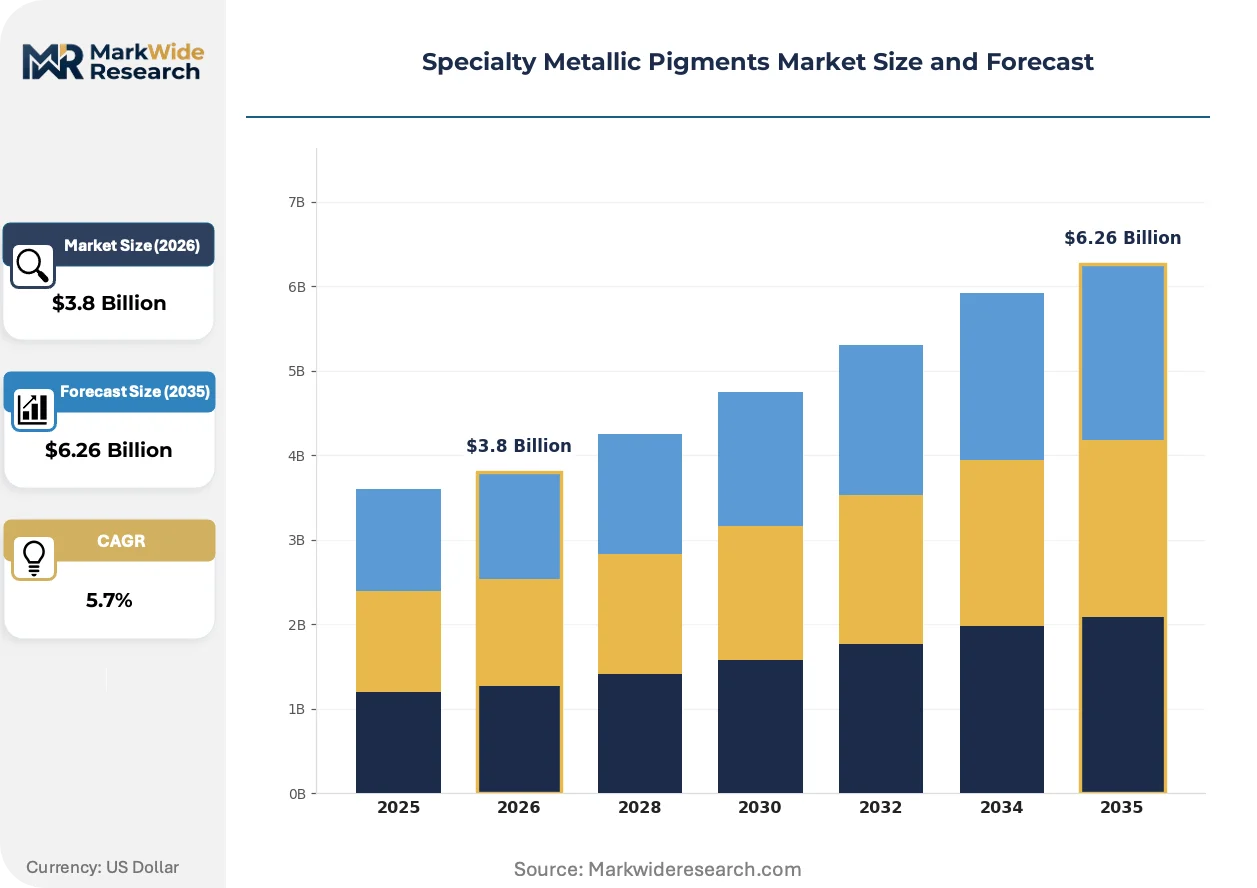
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aluminum Pigments, Copper Pigments, Bronze Pigments, Zinc Pigments Form: Powder, Paste, Flake, Pellet Application: Coatings, Plastics, Inks, Cosmetics End User: Automotive, Construction, Consumer Electronics, Toys |
| Companies Covered | BASF SE, Altana AG, Eckart GmbH, Sun Chemical Corporation, Toyal America, Sudarshan Chemical Industries, SCHLENK SE, Merck KGaA, Umicore, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Specialty Metallic Pigments Market Strategic Shifts
Particle engineering and carrier system innovation dominate competitive differentiation as environmental compliance tightens and end-users demand broader effect palettes with fewer process steps.
Vacuum metallization technology is consolidating control over high-luster aluminum flake production for automotive effect coatings. Tier-one coatings formulators in Germany and Japan are qualifying these grades for waterborne basecoats at accelerated timelines. The technology is consolidating supplier power toward integrated producers with captive PVD capacity, compressing margins for merchant ball-milled flake converters.
The EU F-Gas Regulation and EPA Clean Air Act VOC rules are forcing synchronous reformulation across Atlantic coatings markets. Solvent-borne metallic paste volumes face structural decline in architectural and industrial maintenance segments. Automotive OEMs in Michigan and Baden-Württemberg are responding with consolidated qualified supplier lists that favor partners with multi-continent waterborne validation data.
Coatings buyers are consolidating procurement around fewer pigment suppliers capable of dual regulatory compliance and technical service proximity. Regional formulators in Italy and Spain are displacing fragmented local distributors with direct mill relationships. This concentration is most visible in automotive refinish networks where single-source metallic pigment agreements now cover waterborne basecoat, clearcoat, and touch-up systems.
Specialty Metallic Pigments Market Segmentation
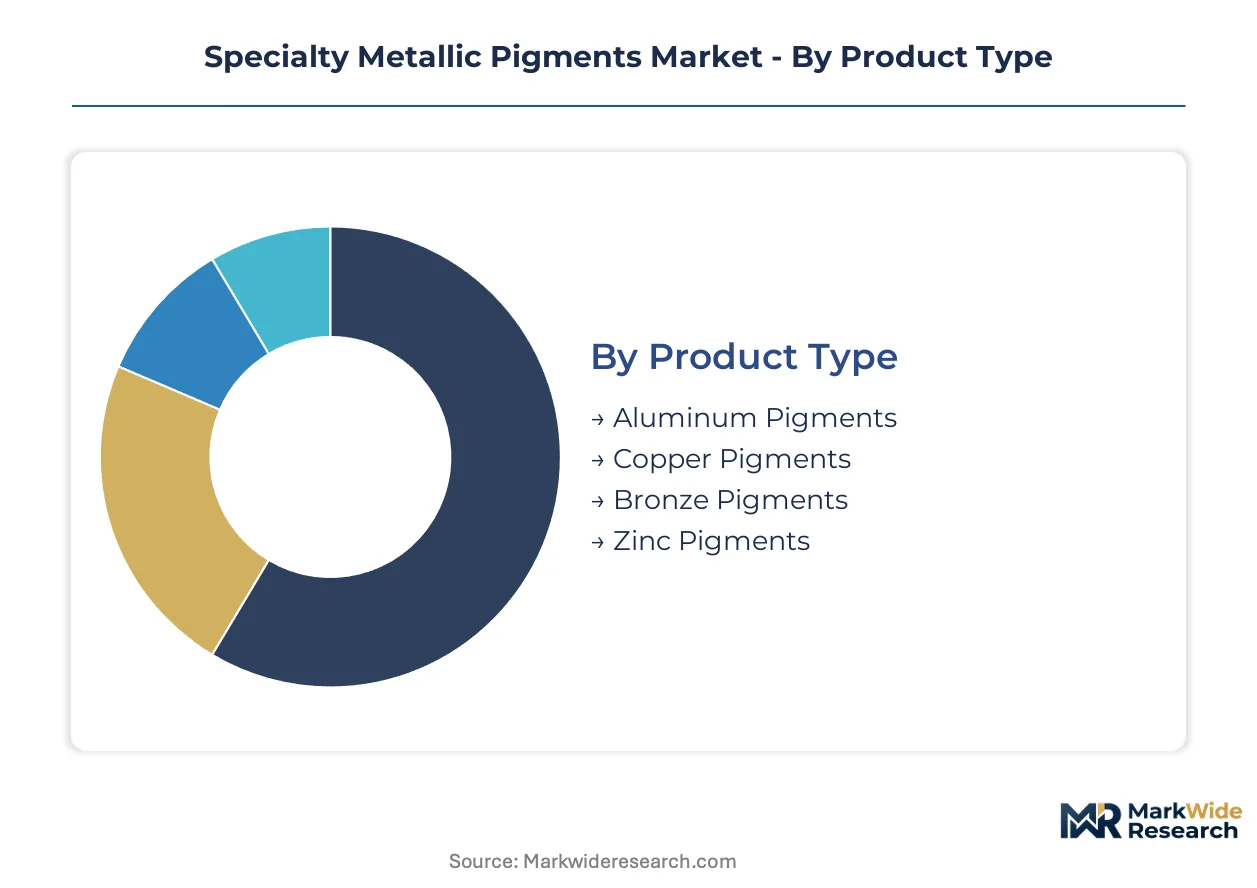
Specialty metallic pigments demand fragments across distinct technical specifications and end-use requirements. Each segment carries unique capital requirements and regulatory exposure that reshape supplier economics.
Product Type:
Capital intensity varies sharply across metal chemistries, with vacuum metallization and surface treatment infrastructure driving fixed cost structures.
- Aluminum Pigments:Ball-milled or PVD-produced flakes deliver silver metallic effects with controlled particle geometries between 5 and 150 micrometers. Automotive OEM basecoats in Michigan and Baden-Württemberg absorb the largest volumes as waterborne compatibility requirements intensify. REACH VOC thresholds and EPA Clean Air Act rules are accelerating reformulation toward surface-treated grades.
- Copper Pigments:Warm-tone metallic flakes command premium positioning in decorative architectural finishes and luxury cosmetics where color temperature justifies higher formulation spend. FDA color additive specifications create dual-track compliance burdens for suppliers serving personal care end users alongside industrial coatings customers.
- Bronze Pigments:Copper-zinc alloys produce intermediate gold-bronze effects for packaging inks and decorative coatings. Guangdong province manufacturing corridors concentrate demand for export-oriented consumer goods.
- Zinc Pigments:Lower-luster flakes serve corrosion-resistant industrial maintenance coatings and specific anticorrosive primer formulations.
Aluminum pigments absorb the bulk of installed capacity; copper pigments are expanding most quickly in cosmetic and architectural premium tiers.
Form:
Processing economics and end-use handling requirements determine form selection, with dispersion stability becoming the critical technical differentiator.
- Powder:Dry flake concentrates offer lowest transport costs and longest shelf stability for industrial coatings compounders with in-house dispersion capabilities. Powder dominates high-volume automotive refinish operations in China and Germany.
- Paste:Pre-dispersed metallic concentrates in solvent or waterborne carriers reduce manufacturing complexity for mid-tier coatings formulators. Paste forms lead current consumption patterns as environmental compliance tightens across coatings formulations.
- Flake:Optimized geometries for specific resin systems enable precise effect control in automotive effect coatings and luxury packaging.
- Pellet:Solid carrier systems simplify handling in plastics compounding operations, particularly for masterbatch producers serving consumer electronics housings.
Paste formulations carry the highest value-add; flake geometries optimized for waterborne compatibility are climbing the fastest.
Application:
Regulatory exposure and performance specifications create distinct margin profiles across downstream industries.
- Coatings:Automotive, architectural, and industrial maintenance formulations represent the largest addressable volume. EU F-Gas Regulation and EPA VOC rules are forcing synchronous reformulation across Atlantic markets.
- Plastics:Consumer electronics housings and automotive interior components drive demand for heat-stable metallic effects. Jiangsu province electronics manufacturing clusters absorb significant pellet and powder volumes.
- Inks:Packaging and commercial printing applications favor paste forms with rapid drying characteristics. Sun Chemical Corporation competes via specialized paste formulations for this segment.
- Cosmetics:FDA color additive specifications govern metallic pigment purity and particle size for eye and lip applications, creating certification barriers for industrial-grade suppliers.
Coatings applications dominate revenue; plastics compounding for electronics is gaining share fastest.
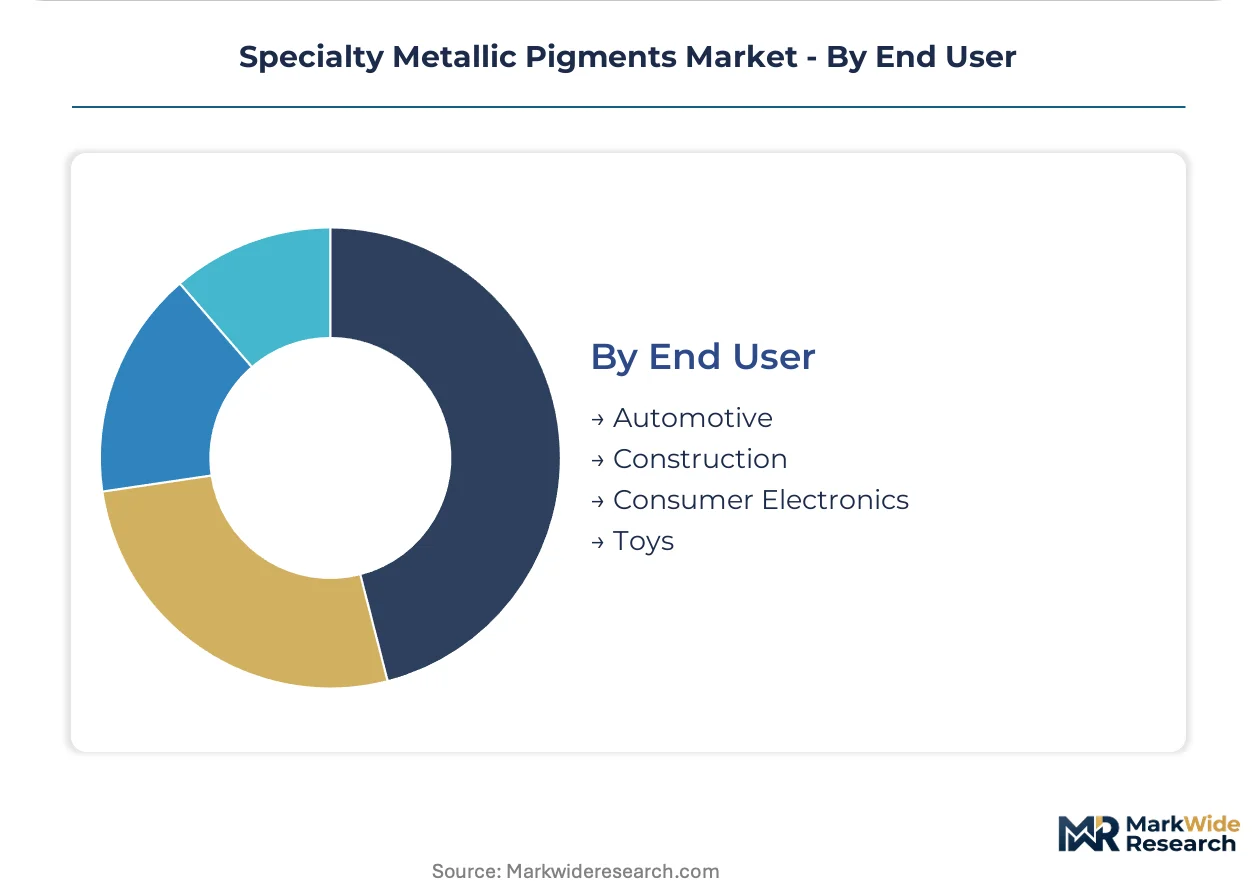
End User:
Customer consolidation and technical service requirements reshape supplier relationships across terminal markets.
- Automotive:OEM basecoat programs and refinish networks demand validated waterborne systems with consistent batch-to-batch color matching. Automotive OEMs represent the fastest-expanding buyer segment as solvent-borne phase-outs accelerate.
- Construction:Architectural coatings and decorative finishes concentrate demand in Germany, France, and Italy where REACH compliance tightens VOC thresholds for decorative coatings.
- Consumer Electronics:Smartphone and laptop housings require precision color control and electromagnetic compatibility. China concentrates demand through its domestic manufacturing corridors.
- Toys:Safety regulations including migration limits for soluble metals constrain pigment selection in children's products.
Automotive end users command the largest procurement volumes; consumer electronics is expanding most quickly in absolute terms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German vacuum metallization capacity anchors specialty metallic pigment supply security for automotive coatings customers across Europe and North America. Aluminum flake production concentrates in Baden-Württemberg and Bavaria, with captive PVD operations feeding waterborne basecoat qualification programs at OEM plants in Michigan and Shanghai.
United States
Automotive OEM basecoat programs in Michigan absorb premium aluminum pigment volumes as solvent-borne phase-outs accelerate. EPA Clean Air Act VOC rules under Title I force synchronous reformulation across architectural and industrial coatings applications. Coatings manufacturers in Ohio and Indiana face capital demands for tank cleaning and application line modifications when switching carrier systems.
Germany
REACH registration requirements and the EU F-Gas Regulation constrain solvent-based carrier systems that traditionally suspend metallic flakes. ECHA compliance timelines redirect R&D investment toward waterborne and UV-curable delivery platforms. Vacuum metallization clusters in Stuttgart and Mannheim consolidate control over high-luster aluminum flake production for automotive effect coatings.
China
Guangdong and Jiangsu province manufacturing corridors concentrate demand for domestic automotive refinish and consumer electronics applications. MEE enforcement of dual carbon goals tightens volatile organic compound thresholds for decorative coatings production. Electronics masterbatch compounders in Shenzhen absorb significant pellet and powder volumes for smartphone and laptop housings.
India
Underpenetrated vehicle repair networks in Maharashtra and Tamil Nadu represent whitespace for effect pigment suppliers as domestic car parc ages. BIS certification requirements for automotive coatings create compliance barriers for imported metallic paste formulations. Refinish distributors in Mumbai and Chennai are consolidating procurement around fewer pigment suppliers with technical service proximity.
Japan
Automotive interior component manufacturers in Aichi Prefecture drive demand for heat-stable metallic effects in plastics compounding. METI industrial standards govern flake geometry specifications for electromagnetic compatibility in consumer electronics. Coatings formulators in Nagoya are qualifying vacuum-metallized grades for waterborne basecoats at accelerated timelines.
Specialty Metallic Pigments Market Competitive Environment
Global majors compete with regional champions across waterborne validation capabilities and captive flake production infrastructure. The supplier base organizes into three tiers: integrated chemical conglomerates with multi-continent dispersion networks, mid-scale specialists with captive PVD or ball-milling assets, and regional distributors converting merchant flake into paste formulations. Consolidation pressures favor partners with dual regulatory compliance and documented biobased resin compatibility. Dominant competitive moves include backward integration into aluminum flake production and geographic expansion through direct mill relationships displacing fragmented local distributors.
Among Germany-based integrated producers, BASF SE and Eckart GmbH occupy positions anchored by captive aluminum flake production and automotive coatings validation data. BASF SE exemplifies the conglomerate archetype with combined pigment and dispersion capabilities, while Eckart GmbH represents specialist concentration in vacuum metallization technology. Sun Chemical Corporation sits within the regional champion tier, competing through specialized paste formulations for packaging inks segment customers. Altana AG and Merck KGaA demonstrate diversified materials science positioning across effect pigment portfolios.
| Leading Market Players |
|---|
| BASF SE |
| Altana AG |
| Eckart GmbH |
| Sun Chemical Corporation |
| Toyal America |
| Sudarshan Chemical Industries |
| SCHLENK SE |
| Merck KGaA |
| Umicore |
| Others |
Value Chain & Pricing Dynamics
Family-owned German vacuum metallization specialists anchor supply discipline through captive PVD capacity, translating aluminum flake scarcity into sustained premium pricing for automotive waterborne grades while resisting merchant-market commoditization.
Pricing Analysis
Technical service bundling separates premium pigment suppliers from commodity flake converters, with validation data and color-matching support included in long-term automotive contracts. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and waterborne compatibility testing depth. Cost compression in mid-tier paste formulations is intensifying because synthetic pearlescent alternatives erode bronze pigment positioning. Tier 1 automotive OEMs demonstrate lowest price sensitivity due to single-source qualification barriers, while regional refinish distributors in Southern Europe exhibit highest sensitivity to per-kilogram differentials.
Supply Chain Analysis
Skilled PVD technician availability constrains capacity expansion in Baden-Württemberg and Bavaria, limiting aluminum flake output growth despite automotive demand acceleration. Supply concentrates in Germany, China, and Japan, with raw material draws from primary aluminum smelters and copper cathode producers. Single-source vulnerability runs through vacuum metallization equipment suppliers serving the flake production base. Distribution runs through qualified coatings formulator networks with validated waterborne dispersion capabilities rather than open merchant channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure intensifies as REACH compliance costs and waterborne R&D requirements force sub-scale paste converters toward exit, favoring integrated producers with captive flake assets.
For Market Incumbents: Deploy backward integration into aluminum flake production to secure input supply against German and Chinese PVD capacity bottlenecks. Expand waterborne validation laboratories in Michigan and Shanghai to capture automotive OEM qualification timelines. Synthetic pearlescent substitution in mid-tier cosmetics threatens copper-bronze pigment margins, requiring accelerated effect pigment portfolio diversification. For New Entrants and Emerging Players: Direct-to-formulator digital platforms bypass fragmented distributor networks in India's underpenetrated Maharashtra and Tamil Nadu refinish markets. Target automotive electronics masterbatch compounders in Jiangsu province seeking electromagnetic-compatible metallic effects with lower minimum order quantities than incumbent suppliers require. Partner with regional coatings distributors for technical service proximity without capital-intensive mill investments. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale European paste converters with automotive validation data but strained working capital from raw material price volatility. Five-to-ten year viability hinges on waterborne platform transition completion and biobased resin compatibility certification. Monitor ECHA enforcement intensity against solvent-borne coating imports as inflection indicator for waterborne pigment demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aluminum Flake Production | Captive PVD capacity insulates BASF and Eckart from merchant supply bottlenecks during raw metal volatility. |
| Waterborne Validation Laboratory Expansion | Technical service proximity in Michigan accelerates automotive OEM qualification timelines against Japanese competitors. |
| Biobased Resin Compatibility Certification | French and Dutch renewable binder standards favor suppliers with verified testing documentation for premium positioning. |
| Direct Mill Relationships with Regional Formulators | Italian and Spanish coatings producers displace fragmented distributors to secure supply security and batch consistency. |
| UV-Curable Platform Development | German and Italian industrial wood coatings segments adopt metallic systems bypassing thermal drying constraints. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with coatings formulators, automotive OEM procurement officers, pigment plant managers, and distribution channel partners. SEC 10-K disclosures, ECHA REACH registration databases, Cefic sector reports, and import-export statistics provided demand-side validation. Bottom-up volume estimates from end-use consumption patterns reconciled with top-down supply capacity assessments across vacuum metallization and ball-milling installations.
Segment-level volume reconciliation against production capacity data shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include metal chemistry tier, carrier system format, end-use industry application, and regional regulatory cluster. CAGRs derived from regression analysis of historical consumption patterns against automotive production forecasts and coatings formulation mix shifts. Waterborne transition timelines and biobased resin adoption curves served as industry-specific demand drivers.
The model holds under stable REACH enforcement intensity and continued automotive solvent-borne phase-outs; deviation in ECHA regulatory acceleration or aluminum raw material supply disruption would shift volume trajectories. Forecasts reflect documented assumptions regarding waterborne compatibility adoption rates and OEM qualification timelines. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Metals
North America Metal Turned Precision Product Manufacturing Market
Specialty Metals
Precision Stainless Steel Market
Specialty Metals
Europe Metal Precision Turned Product Manufacturing Market
Specialty Metals
Dysprosium Market
Specialty Metals
Global Special Steel Market
Specialty Metals
Case Hardening Steel Market
Specialty Metals
Metal Halide Market
Specialty Metals
Global Metal Bellows Market
Specialty Metals
Precious Metal Plating Market