
 Global Special Steel Market | 2026-2036
Global Special Steel Market Size, Share, and Industry Trends Forecast 2026-2036
Global Special Steel Market Outlook
The capability gap between blast-furnace integrated mills and electric-arc furnace specialists is reorganizing competitive tiers in special steel. ArcelorMittal leverages its European flat-rolled research network to sustain premium automotive contracts. Nippon Steel Corporation anchors Japanese aerospace supply chains through proprietary vacuum arc remelting protocols. Tata Steel Limited competes across Southeast Asian construction markets with cost-optimized bar and wire rod configurations.
Special steel denotes alloyed, high-performance ferrous materials engineered for superior mechanical properties, corrosion resistance, or thermal stability through precise control of carbon, chromium, nickel, molybdenum, and vanadium content, typically produced via secondary refining, continuous casting, and thermomechanical processing to serve demanding load-bearing or extreme-environment applications. Stainless steel commands the widest margin pool due to chemical-process industry replacement cycles and medical device sterilization standards, while alloy steel extends fastest in power-train lightweighting programs where manganese-boron press-hardened grades displace conventional mild steel. Tool steel occupies a mature but defensible niche in die-casting and plastic injection molding where tungsten-carbide compatibility and red-hardness specifications limit supplier switches.
The US EPA enforces Maximum Achievable Control Technology standards for electric arc furnace particulate emissions, while the EU Green Deal's carbon border adjustment mechanism reshapes import competitiveness for Indian and Chinese exporters. Japan's METI coordinates national R&D consortia on hydrogen-direct-reduction steelmaking to preserve domestic special steel leadership. Stakeholders must monitor which regulatory jurisdictions first mandate scrap-traceability certification, as this will fragment raw-material sourcing economics across producer tiers.
Market Dynamics
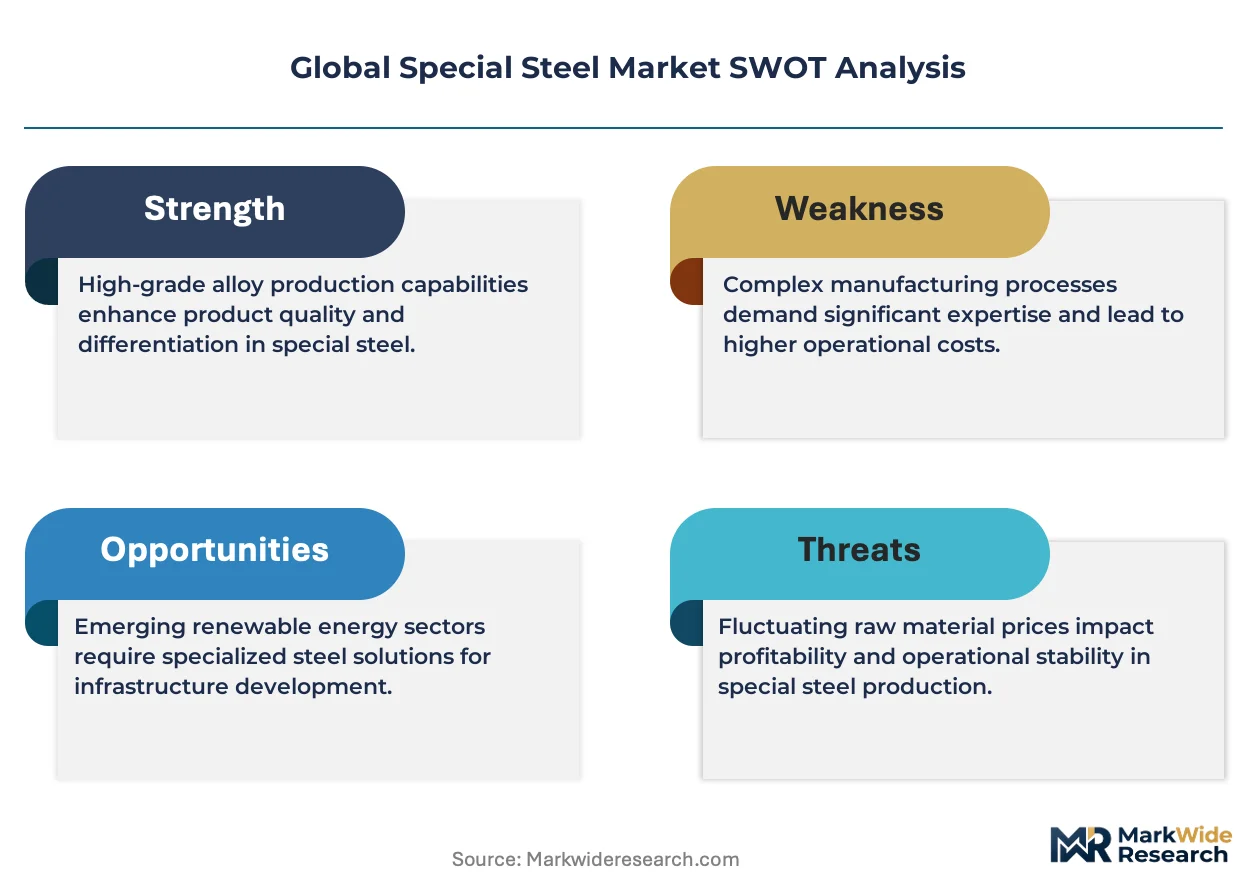
The capability gap between blast-furnace integrated mills and electric-arc furnace specialists is reorganizing competitive tiers in special steel, with hydrogen-direct-reduction pilots now determining which producers retain premium automotive and aerospace contracts.
Growth Catalysts
- Automotive lightweighting mandates:Power-train programs in Germany and Japan are expanding orders for manganese-boron press-hardened grades that displace conventional mild steel in chassis components.
- EU Green Deal carbon border adjustments:The mechanism is reshaping import competitiveness and accelerating scrap-traceability investments among Indian and Chinese exporters serving European chemical-process industries.
- Medical device sterilization standards:Stainless steel replacement cycles in surgical instrument manufacturing are widening margin pools for corrosion-resistant austenitic grades certified to ISO 13485 protocols.
Market Restraints
- Scrap supply concentration:Premium grades depend on consistent heavy-melting scrap flows concentrated in Turkey and the US Southeast, exposing melt shops to price volatility.
- US EPA Maximum Achievable Control Technology:Compliance costs for electric arc furnace particulate emissions are compressing returns at mid-scale producers without integrated environmental systems.
- Long-lead vacuum arc remelting capacity:Aerospace-grade billet production remains bottlenecked by limited VAR furnace availability, extending order fulfillment timelines.
Strategic Opportunities
- India's western industrial corridor:Demand clusters around Pune and Gujarat offer white-space expansion for cost-optimized bar and wire rod configurations serving construction equipment OEMs.
- Japan METI hydrogen steelmaking consortia:National R&D coordination preserves domestic special steel leadership and creates technology export potential for direct-reduction licensing.
- Additive manufacturing feedstock:Gas-atomized powder grades for laser powder bed fusion are opening premium niches beyond conventional wrought product lines.
Industry Challenges
- Vacuum metallurgy skill scarcity:Qualified technicians for ladle refining and degassing operations are retiring faster than apprenticeship pipelines replenish them.
- Dual certification timelines:Simultaneous compliance with China's GB carbon intensity standards and EU REACH substance restrictions extends product qualification cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Special Steel Market |
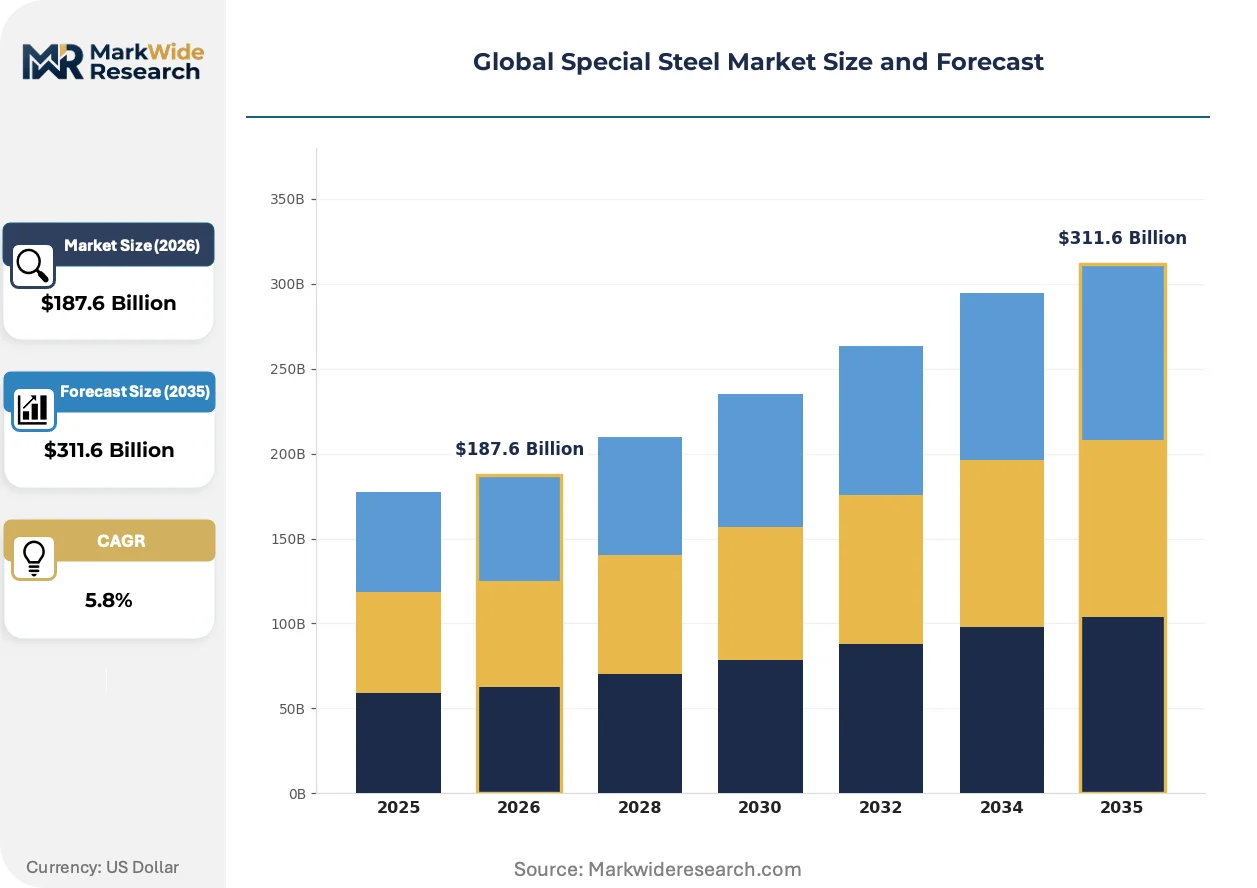
| Market Size in 2026 | $187.6 Billion |
| Market Size in 2035 | $311.6 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Alloy Steel, Carbon Steel, Stainless Steel, Tool Steel Application: Aerospace, Automotive, Construction, Energy End User: Manufacturers, Fabricators, Distributors, OEMs Form: Bars, Plates, Sheets, Tubes |
| Companies Covered | China Baowu Steel Group, ArcelorMittal, Nippon Steel Corporation, Baosteel Group, Pohang Iron and Steel Company, JFE Holdings Inc., Tata Steel Limited, Daido Steel, JSW Steel, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Special Steel Market Strategic Shifts
Digital twin deployment across continuous casting lines is compressing defect detection cycles and enabling real-time chemistry adjustments that were previously batch-dependent.
Hydrogen-based direct reduction is fragmenting the traditional coke-oven route for special steel feedstock. Automotive OEMs in Germany are qualifying HBI-derived billets for structural safety components ahead of 2030 supply agreements. This shift is compressing the premium attached to conventional blast-furnace integrated capacity.
The EU Green Deal's carbon border adjustment mechanism is forcing Indian exporters to implement third-party scrap-traceability certification. Chemical-process industry buyers are now mandating embodied-carbon documentation for stainless replacement orders. Producers without verified supply-chain data face exclusion from premium European tenders.
After-sales service unbundling is spreading among tool steel distributors. Die-casting shops in Japan now subscribe to red-hardness monitoring and reconditioning services separate from initial material purchases. This model is most visible in automotive stamping corridors where tooling uptime directly determines contract profitability.
Global Special Steel Market Segmentation
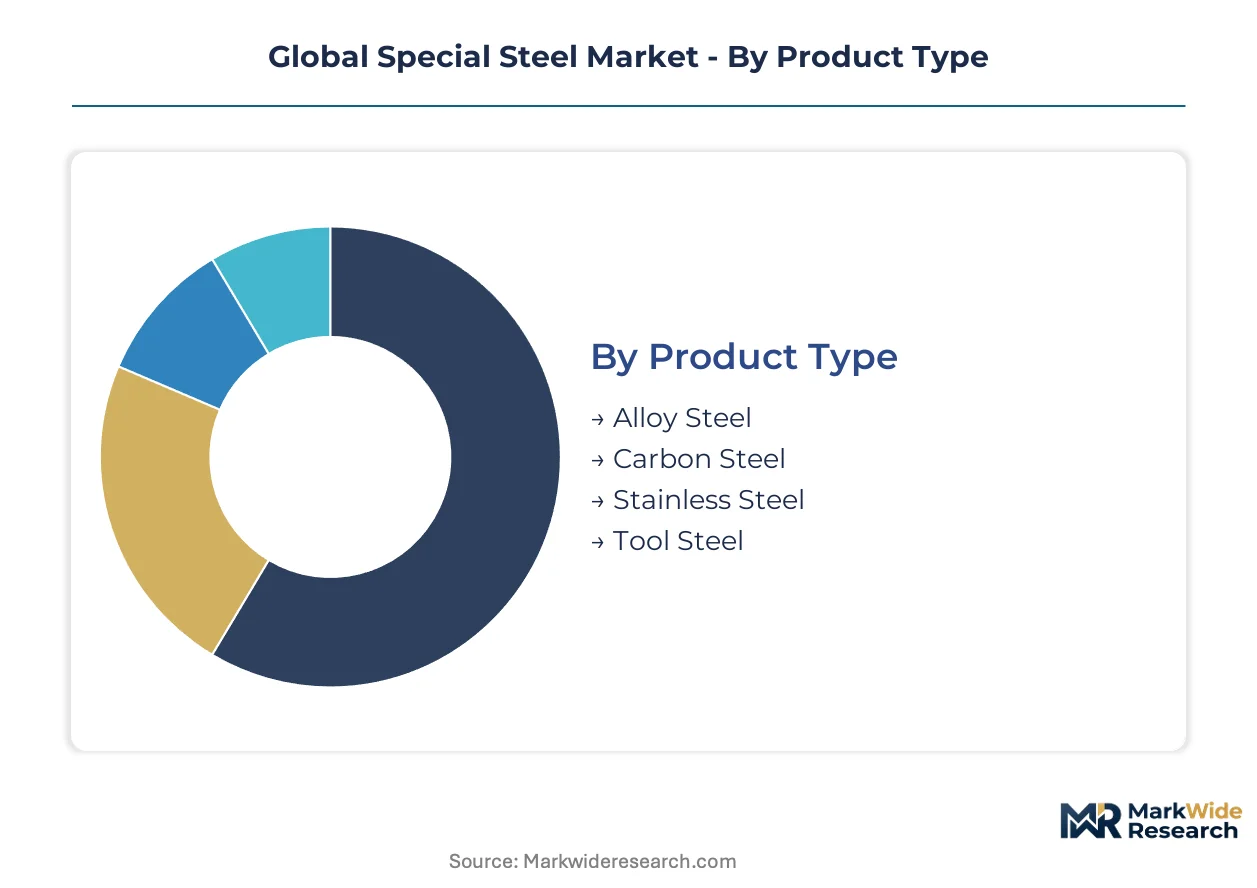
Special steel segmentation reveals how margin pools concentrate in corrosion-resistant grades and automotive-qualifying alloys, with form factor and supply chain position determining access to premium pricing tiers. Understanding these splits exposes where hydrogen-direct-reduction investments and vacuum metallurgy capabilities will reshape competitive boundaries.
Product Type:
Margin pools concentrate in corrosion-resistant and high-strength alloy formulations where specification certification creates supplier stickiness.
- Stainless Steel:Austenitic and duplex grades engineered with precise chromium-nickel-molybdenum ratios deliver sterilization-grade surfaces for surgical instrument manufacturing. Chemical-process industry replacement cycles in Germany and Japan sustain premium pricing for ISO 13485-certified material.
- Alloy Steel:Manganese-boron press-hardened grades enable chassis lightweighting through controlled thermomechanical processing. Power-train programs at German and Japanese automotive OEMs are displacing conventional mild steel in structural safety components.
- Tool Steel:Tungsten and vanadium-alloyed formulations maintain red-hardness for die-casting and plastic injection molding applications where tooling uptime determines contract profitability.
- Carbon Steel:Controlled-carbon grades serve construction equipment and general fabrication with cost-optimized bar and wire rod configurations competing across Southeast Asian markets.
The dominant share belongs to Stainless Steel, while Alloy Steel is closing the gap fastest through automotive lightweighting mandates.
Application:
Volume concentration tracks automotive and construction demand, but certification intensity and technical barriers concentrate profitability in aerospace and energy segments.
- Automotive:Structural safety components require press-hardened manganese-boron grades with precise crash-energy absorption properties. German OEM qualification of hydrogen-reduced billet feedstock is compressing premiums for conventional blast-furnace supply.
- Aerospace:Vacuum arc remelting protocols produce ultra-clean billet for turbine discs and landing gear with defect tolerances measured in parts per million. Japanese supply chains anchor this segment through proprietary VAR furnace operations.
- Construction:Bar and wire rod configurations serve equipment OEMs in India's western industrial corridor around Pune and Gujarat where cost-optimized specifications dominate procurement.
- Energy:Corrosion-resistant grades withstand sour gas environments and geothermal brine exposure, with EU carbon border adjustments now mandating embodied-carbon documentation for replacement orders.
Automotive commands the largest volume position, though Aerospace exhibits the steepest expansion trajectory as OEMs qualify new hydrogen-reduced feedstock sources.
End User:
Supply chain position determines margin capture, with OEM direct contracts commanding premium pricing over distributor-mediated flows.
- OEMs:Direct procurement of certified grades for automotive and aerospace production lines requires integrated technical service capabilities and long-term qualification timelines.
- Manufacturers:Tier suppliers process semi-finished forms into components, balancing specification compliance against scrap-yield economics.
- Fabricators:Job shops and structural steel processors prioritize form factor availability and delivery reliability over metallurgical customization.
- Distributors:Inventory positions in tool steel and stainless grades serve fragmented die-casting and medical device customers with unbundled after-sales monitoring services.
OEMs retain the dominant procurement value, while Distributors are gaining share fastest through service-model unbundling.
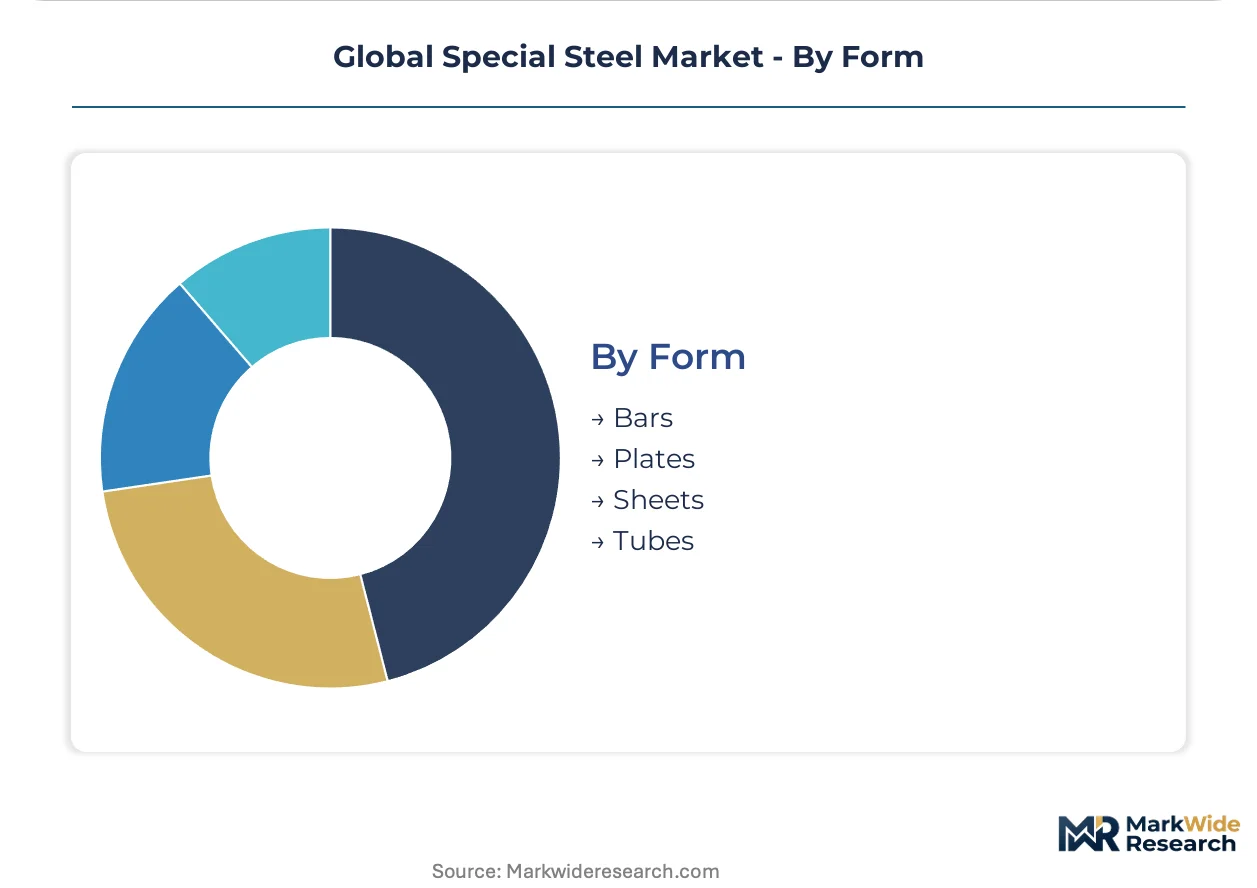
Form:
Continuous casting yield rates and thermomechanical processing intensity create cost tier differentiation across form factors.
- Plates:Heavy-gauge flat products serve pressure vessels and chemical-process equipment with thickness tolerances tied to welding procedure specifications.
- Sheets:Cold-rolled and coated surfaces enable automotive body-in-white stamping with surface quality grades determining paint adhesion performance.
- Bars:Long products in round, square, and hexagonal sections feed machining centers and construction reinforcement with straightness and decarburization limits.
- Tubes:Seamless and welded configurations deliver pressure containment for energy applications with hydrostatic test protocols verifying wall thickness consistency.
Plates hold the dominant position, while Sheets are climbing the fastest on automotive lightweighting program expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in India's western industrial corridor demonstrate acute price sensitivity for construction-grade bar and wire rod, while German automotive OEMs absorb substantial premiums for hydrogen-qualified billet feedstock in structural safety programs.
China
GB standards issued by MEE tighten melt-shop emissions intensity rules, forcing capacity consolidation among smaller electric-arc furnace operators. The Yangtze River Delta concentration around Shanghai sustains stainless output for chemical-process industry replacement cycles. Domestic producers face mounting pressure to implement scrap-traceability systems ahead of anticipated carbon border adjustments.
Germany
Automotive lightweighting mandates from KBA drive manganese-boron press-hardened grade procurement for chassis components. The EU Green Deal's carbon border adjustment mechanism reshapes import competitiveness for Indian and Chinese suppliers. The Ruhr industrial cluster anchors hydrogen-direct-reduction pilot programs qualifying HBI-derived billets for 2030 supply agreements.
Japan
METI coordinates national R&D consortia on hydrogen steelmaking to preserve domestic special steel leadership in aerospace supply chains. Vacuum arc remelting protocols from Nagoya-area producers maintain ultra-clean billet output for turbine disc applications. The Kanto region around Tokyo concentrates medical device sterilization-grade stainless certified to ISO 13485 protocols.
India
Construction equipment OEMs in Pune and Gujarat generate concentrated demand for cost-optimized bar and wire rod configurations. BIS certification requirements intersect with EU REACH substance restrictions, extending product qualification timelines for export-oriented producers. The western industrial corridor offers white-space expansion as infrastructure investment accelerates.
United States
EPA Maximum Achievable Control Technology standards compress returns at mid-scale electric arc furnace producers without integrated environmental systems. Heavy-melting scrap supply concentration in the Southeast exposes melt shops to price volatility. The Gulf Coast petrochemical corridor sustains stainless replacement demand with stringent embodied-carbon documentation requirements emerging from downstream buyers.
Global Special Steel Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with the capability gap between blast-furnace mills and electric-arc furnace operators reorganizing competitive boundaries. Hydrogen-direct-reduction pilots now determine which producers retain premium automotive and aerospace contracts. Three archetypes dominate: scale-driven integrated mills with European research networks, vacuum metallurgy specialists anchoring Japanese supply chains, and cost-optimized regional producers serving construction markets. Competitive moves concentrate on scrap-traceability certification investments and strategic partnerships for hydrogen feedstock qualification.
Among Asia-Pacific integrated producers, China Baowu Steel Group and Nippon Steel Corporation occupy positions reflecting scale and metallurgical specialization respectively. ArcelorMittal represents the European archetype leveraging flat-rolled research networks. These three exemplify how geographic origin and corporate structure correlate with strategic positioning across premium and volume tiers.
| Leading Market Players |
|---|
| China Baowu Steel Group |
| ArcelorMittal |
| Nippon Steel Corporation |
| Baosteel Group |
| Pohang Iron and Steel Company |
| JFE Holdings Inc. |
| Tata Steel Limited |
| Daido Steel |
| JSW Steel |
| Others |
Value Chain & Pricing Dynamics
Blast-furnace capacity utilization above 85 percent in the Ruhr cluster sustains premium pricing power for hydrogen-qualified billet, while electric-arc furnace melt shops in Turkey and the US Southeast face compressed margins from scrap volatility. Scale economies at integrated European mills create price floors that mid-scale VAR specialists cannot match without alloy surcharges.
Pricing Analysis
After-sales service revenue from red-hardness monitoring and reconditioning subscriptions now drives lifetime value for tool steel distributors serving Japanese die-casting shops. Three-tier pricing structure across aerospace-certified, automotive-qualified, and construction-grade specifications reflects certification intensity and vacuum metallurgy throughput costs. Pricing pressure stems from EU carbon border adjustments forcing scrap-traceability investments onto Indian and Chinese exporters. Chemical-process industry buyers in Germany exhibit lowest price sensitivity for ISO 13485-certified austenitic grades, while construction equipment OEMs in India's western corridor negotiate aggressively on bar and wire rod configurations.
Supply Chain Analysis
Turkey and the US Southeast anchor heavy-melting scrap supply for premium grade production, while China and India dominate cost-optimized bar and wire rod output for Southeast Asian construction markets. Manganese, chromium, and nickel feedstock draws from South African, Kazakh, and Indonesian mining operations. Single-source vulnerability concentrates in vacuum arc remelting furnace availability for aerospace billet production. Distribution runs through mill-direct contracts for automotive and aerospace OEMs, with distributor-mediated flows serving fragmented medical device and die-casting customers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity exists as hydrogen-direct-reduction qualification requirements split the supplier base between legacy integrated mills and emerging low-carbon specialists. Automotive OEM demand for embodied-carbon documentation creates niche entry points for traceability-certified producers.
For Market Incumbents: Consolidate hydrogen-direct-reduction pilot capacity in the Ruhr and Nagoya corridors before 2030 supply agreement deadlines lock in feedstock qualifications. Acquire scrap-traceability certification providers to preempt EU carbon border adjustment compliance costs. Backward integration into heavy-melting scrap collection networks in Turkey reduces exposure to price volatility from merchant market concentration.
For New Entrants and Emerging Players: Anchor in India's western industrial corridor around Pune and Gujarat with cost-optimized bar and wire rod configurations targeting construction equipment OEM procurement. Qualify gas-atomized powder grades for additive manufacturing feedstock to bypass conventional wrought product line capital intensity. Partner with Japanese METI consortia for hydrogen steelmaking technology licensing to accelerate premium automotive contract access.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among tool steel distributors unbundling after-sales monitoring services from initial material sales. Long-term viability over the projection horizon favors vacuum metallurgy specialists with proprietary VAR protocols and aerospace supply chain anchoring. Acquisition target archetype: mid-scale electric-arc furnace operators with integrated environmental systems and pending hydrogen-reduction retrofit permits. Signal to watch: first regulatory jurisdiction mandating scrap-traceability certification as fragmentation trigger for raw-material sourcing economics.
| Strategic Initiative | Industry Significance |
|---|---|
| Hydrogen-Direct-Reduction Capacity Buildout | Qualification by German KBA for 2030 automotive supply agreements locks in premium structural safety component contracts. |
| Scrap-Traceability Certification Investment | EU Green Deal carbon border adjustments exclude non-compliant Indian and Chinese exporters from chemical-process industry tenders. |
| Vacuum Arc Remelting Furnace Expansion | Japanese METI consortia preserve domestic aerospace leadership through ultra-clean billet output for turbine disc applications. |
| After-Sales Service Unbundling | Japanese die-casting shops subscribe to red-hardness monitoring separate from initial tool steel purchases, improving distributor margin stability. |
| India Western Corridor Manufacturing Footprint | Pune and Gujarat demand clusters offer white-space expansion for cost-optimized bar and wire rod serving construction equipment OEMs. |
Study Parameters
Cross-validation between executive interviews at ArcelorMittal, Nippon Steel Corporation, and Tata Steel Limited and secondary validation from SEC filings and EU ETS registry data anchors the qualitative findings. Primary discussions with melt shop managers, automotive Tier 1 procurement leads, aerospace quality engineers, and chemical-process industry buyers informed operational constraints and qualification timelines. Secondary sources include customs trade databases, China MEE GB standard filings, Japan METI R&D consortium disclosures, and BIS certification records. Bottom-up capacity utilization models and top-down demand segmentation triangulate volume estimates.
Sensitivity analysis across scrap price volatility scenarios, hydrogen-reduction capital cost ranges, and carbon border adjustment implementation timelines tests forecast robustness. Segmentation dimensions modeled include product type, application, end user, form factor, and regional production hub across the analysis window. CAGRs derive from regression against automotive lightweighting program expansion rates, chemical-process industry replacement cycle data, and medical device sterilization standard adoption curves. Forecast inputs incorporate electric-arc furnace capacity additions in India and hydrogen-direct-reduction pilot commissioning schedules in Germany and Japan.
Underlying assumptions cover sustained EU Green Deal enforcement, Chinese GB emissions intensity compliance, and automotive OEM 2030 hydrogen-qualified feedstock targets, with deviation risk concentrated in scrap supply disruptions from Turkish merchant market concentration and vacuum metallurgy technician retirement rates exceeding apprenticeship pipeline replenishment. Recalibration cycles align with material shifts in carbon border adjustment implementation scope and first regulatory jurisdiction scrap-traceability mandate timing.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Metals
Specialty Metallic Pigments Market
Specialty Metals
Dysprosium Market
Specialty Metals
Europe Metal Precision Turned Product Manufacturing Market
Specialty Metals
Case Hardening Steel Market
Specialty Metals
Metal Halide Market
Specialty Metals
Precision Stainless Steel Market
Specialty Metals
Global Metal Bellows Market
Specialty Metals
Precious Metal Plating Market
Specialty Metals
North America Metal Turned Precision Product Manufacturing Market