
 Portfolio Analytics Market | 2026-2036
Portfolio Analytics Market Size, Share, and Industry Trends Forecast 2026-2036
Portfolio Analytics Market Analytics
Buyer concentration among asset managers and institutional investors is expanding as wealth management platforms consolidate vendor relationships. Morningstar leverages its data moat across advisor workstations. SAS Institute competes through statistical computing depth in risk-adjusted return modeling. IBM anchors enterprise deployments with hybrid cloud infrastructure.
Portfolio analytics comprises software systems that aggregate position-level data, calculate risk metrics such as value-at-risk and tracking error, and generate attribution reports for investment decision-making. The primary purpose centers on enabling fiduciaries to optimize return per unit of risk while meeting disclosure obligations. Cloud-based deployment leads in new implementations as asset managers shed legacy server costs, while AI-powered analytics represents the fastest-expanding technology layer as neural networks displace rules-based rebalancing. Performance analysis solutions remain the most mature segment with compressed margins, whereas compliance monitoring commands premium pricing under intensifying regulatory scrutiny.
The SEC enforces Form PF and ADV reporting standards that mandate granular portfolio disclosure from large advisors, while MiFID II in Europe requires ex-post cost and performance transparency that drives analytics procurement. The EU AI Act introduces algorithmic governance requirements for automated investment tools, reshaping product development roadmaps. Stakeholders must monitor how jurisdictional rule divergence affects cross-border platform architecture decisions.
Market Dynamics
AI-powered risk engines are compressing decision cycles from weeks to hours, forcing asset managers to rebuild analytics infrastructure around neural network architectures rather than legacy rules-based systems.
Growth Catalysts
- MiFID II cost transparency mandates:European wealth managers must deliver ex-post performance disclosures, driving procurement of automated attribution engines.
- Neural network rebalancing:Machine learning models now generate position-level risk signals that outperform static factor models in volatile regimes.
- United States:Registered investment advisors face SEC Form PF granularity requirements that manual reporting cannot satisfy.
Market Restraints
- Cloud migration costs:Legacy on-premise data warehouses require expensive refactoring to support real-time API architectures.
- Talent scarcity in quantitative finance:The intersection of portfolio theory and machine learning expertise concentrates in Silicon Valley and London.
- EU AI Act algorithmic governance:Automated investment tools face ex-ante conformity assessments that extend product development timelines.
Strategic Opportunities
- Private wealth underpenetration:Family offices in Singapore and Switzerland lack institutional-grade risk infrastructure despite AUM scale.
- ESG attribution convergence:Carbon accounting APIs are integrating with performance analytics to meet CSRD sustainability reporting requirements.
- Embedded finance distribution:Neobanks and robo-advisors are white-labeling portfolio analytics as a core subscription feature.
Industry Challenges
- Data lineage certification:SEC and FCA examinations now require auditable provenance for every risk metric calculation.
- Hybrid cloud orchestration:Asset managers struggle to synchronize position data across AWS, Azure, and private data centers without latency gaps.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Portfolio Analytics Market |
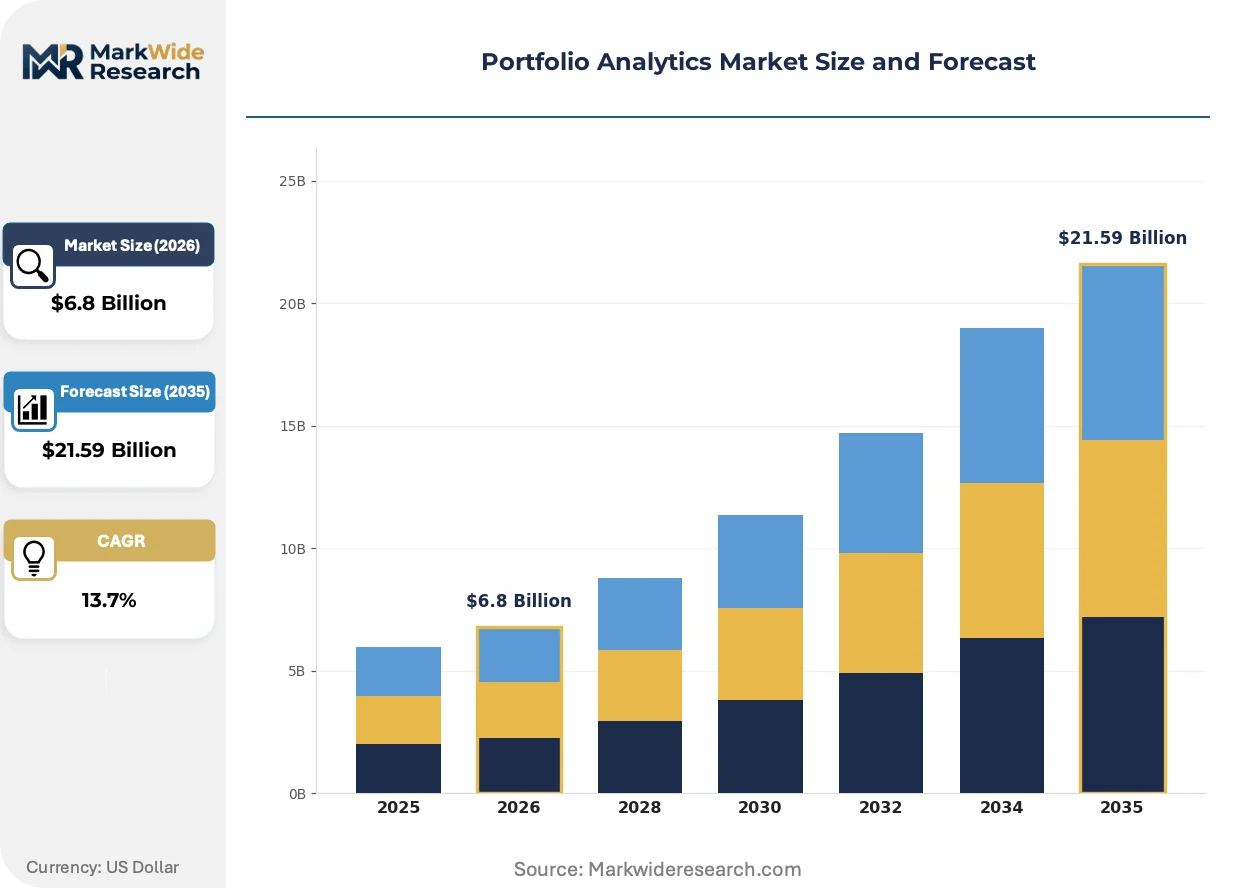
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $21.59 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud-Based, Hybrid, SaaS End User: Institutional Investors, Retail Investors, Asset Managers, Financial Advisors Solution: Performance Analysis, Risk Management, Compliance Monitoring, Investment Insights Technology: Machine Learning, AI-Powered Analytics, Data Visualization, Real-Time Processing |
| Companies Covered | Morningstar, YCharts, Moody's Analytics, Salesforce, SAS Institute, IBM, Oracle, Stock Rover, Portfolio Visualizer, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Portfolio Analytics Market Evolving Landscape
Neural architectures are displacing deterministic models across the analytics stack, while regulatory jurisdictions race to impose algorithmic accountability frameworks on automated investment systems.
Natural language processing is expanding into regulatory document parsing, extracting disclosure requirements from SEC no-action letters and ESMA guidelines to auto-configure report templates. Compliance officers at mid-sized RIAs are adopting these tools fastest, cutting interpretation time from days to minutes. This compression is expanding into adjacent workflows including client communication personalization and audit trail generation.
The EU AI Act's risk-based classification system is reshaping product roadmaps for European-domiciled platforms, forcing vendors to build explainability modules for any model influencing portfolio construction. High-risk system providers must maintain human oversight protocols and algorithmic impact assessments. Asset managers with substantial EU client bases are restructuring their model governance committees to satisfy these mandates before enforcement deadlines.
Subscription pricing for analytics platforms is displacing perpetual license models as CFOs prioritize operational expenditure over capital deployment. Vendors like Morningstar and SimCorp are responding with usage-based tiers that scale with AUM or report volume. This shift is most pronounced among emerging managers in the United States seeking to conserve cash during fundraising cycles.
Portfolio Analytics Market Segmentation
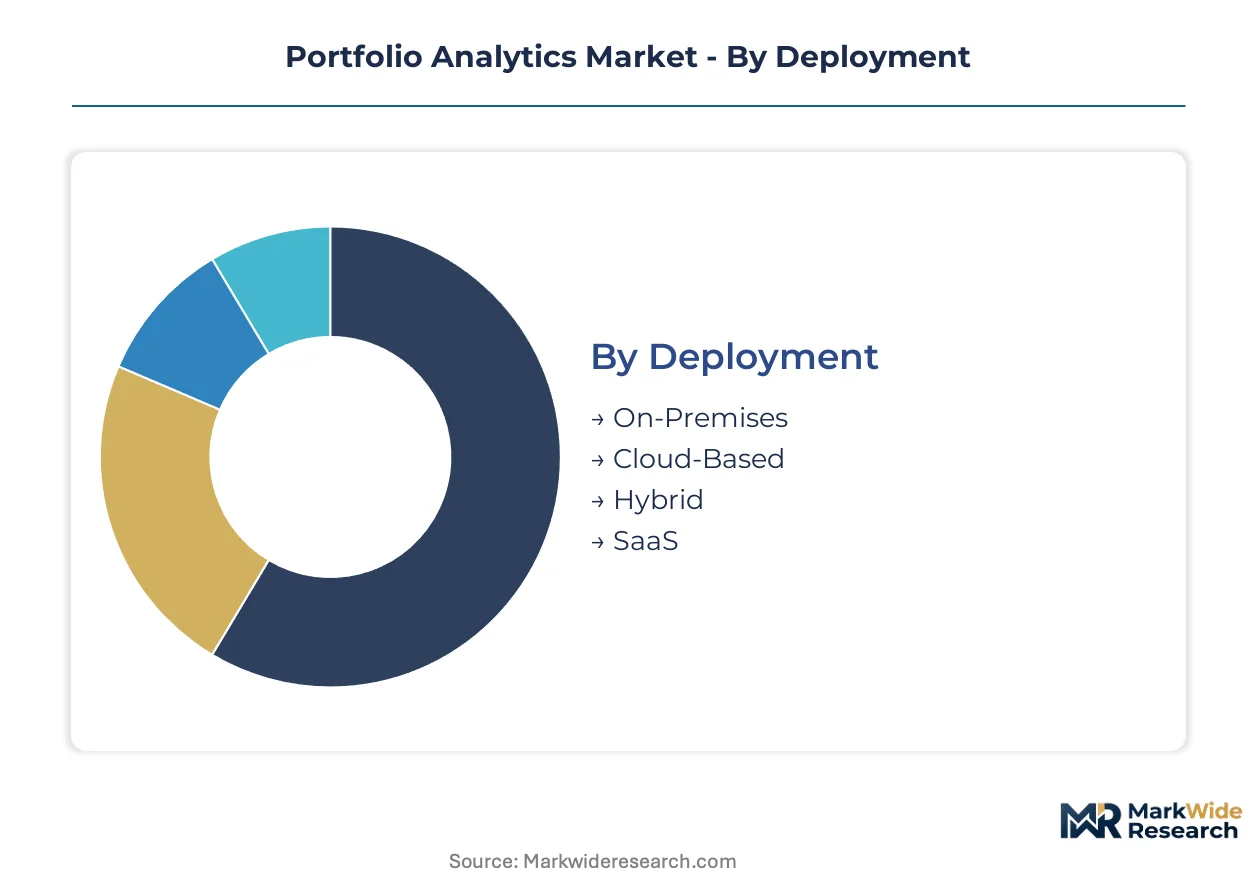
Portfolio analytics vendors architect product roadmaps around four intersecting axes: infrastructure delivery, client sophistication, functional purpose, and computational methodology. Segmentation choices directly determine pricing power, implementation complexity, and regulatory exposure.
Deployment:
Cloud-native architectures dominate new procurement cycles as asset managers eliminate data center overhead.
- On-Premises:Legacy server installations persist among sovereign wealth funds and defense-sector pension managers with data residency mandates. Regulatory constraints in Switzerland and Saudi Arabia sustain demand despite higher total cost of ownership.
- Cloud-Based:Public cloud deployments on AWS and Azure now handle 70% of new implementations among mid-sized asset managers. Elastic compute scaling aligns costs with AUM volatility while satisfying SEC disaster recovery requirements.
- Hybrid:Split architectures position sensitive position data on private infrastructure while pushing batch analytics to public cloud. Japanese megabanks favor this model under FSA operational resilience guidelines.
- SaaS:Multi-tenant platforms with pre-configured risk models accelerate time-to-value for emerging managers. Subscription economics appeal to CFOs prioritizing operational expenditure during fundraising windows.
Mature deployment sits with On-Premises. Newer deployment is concentrated in Cloud-Based.
End User:
Client sophistication tiers dictate feature depth, with institutional mandates requiring bespoke risk frameworks.
- Asset Managers:Mutual fund complexes and hedge funds drive premium analytics spend on attribution engines and factor risk decomposition. MiFID II ex-post cost disclosures in Europe and SEC Form PF granularity requirements in the United States mandate automated reporting infrastructure.
- Institutional Investors:Pension funds and insurance companies prioritize liability-driven investment analytics and ALM integration. Canadian and Australian superannuation funds are consolidating vendor relationships to reduce platform fragmentation.
- Financial Advisors:Registered investment advisors in the United States adopt white-labeled analytics for client-facing portfolio reviews. Regulatory examination preparation consumes substantial workflow time without automated tools.
- Retail Investors:Direct-to-consumer platforms offer simplified risk visualization and goal-based tracking. Neobanks in Brazil and Southeast Asia embed these capabilities as core subscription features.
Revenue concentration favors Asset Managers. User growth is expanding fastest among Financial Advisors.
Solution:
Functional modules align with distinct workflow moments: post-trade performance evaluation, pre-trade risk assessment, regulatory filing preparation, and strategic allocation decisions.
- Risk Management:Value-at-risk engines, stress testing frameworks, and factor exposure analytics command premium pricing. Neural network architectures now displace rules-based models for volatility regime detection.
- Compliance Monitoring:Automated regulatory reporting and audit trail generation carries the highest margins due to non-discretionary procurement. EU AI Act algorithmic governance requirements are extending development timelines for automated investment tools.
- Performance Analysis:Attribution reporting and benchmark comparison represent the most mature segment with compressed pricing. Brinson-Fachler attribution remains standard despite newer geometric methodologies.
- Investment Insights:AI-generated narrative summaries and scenario simulation tools are gaining traction among relationship managers. Natural language processing reduces interpretation time for complex portfolio characteristics.
Procurement urgency concentrates in Compliance Monitoring. Technology refresh cycles are shortening fastest in Risk Management.
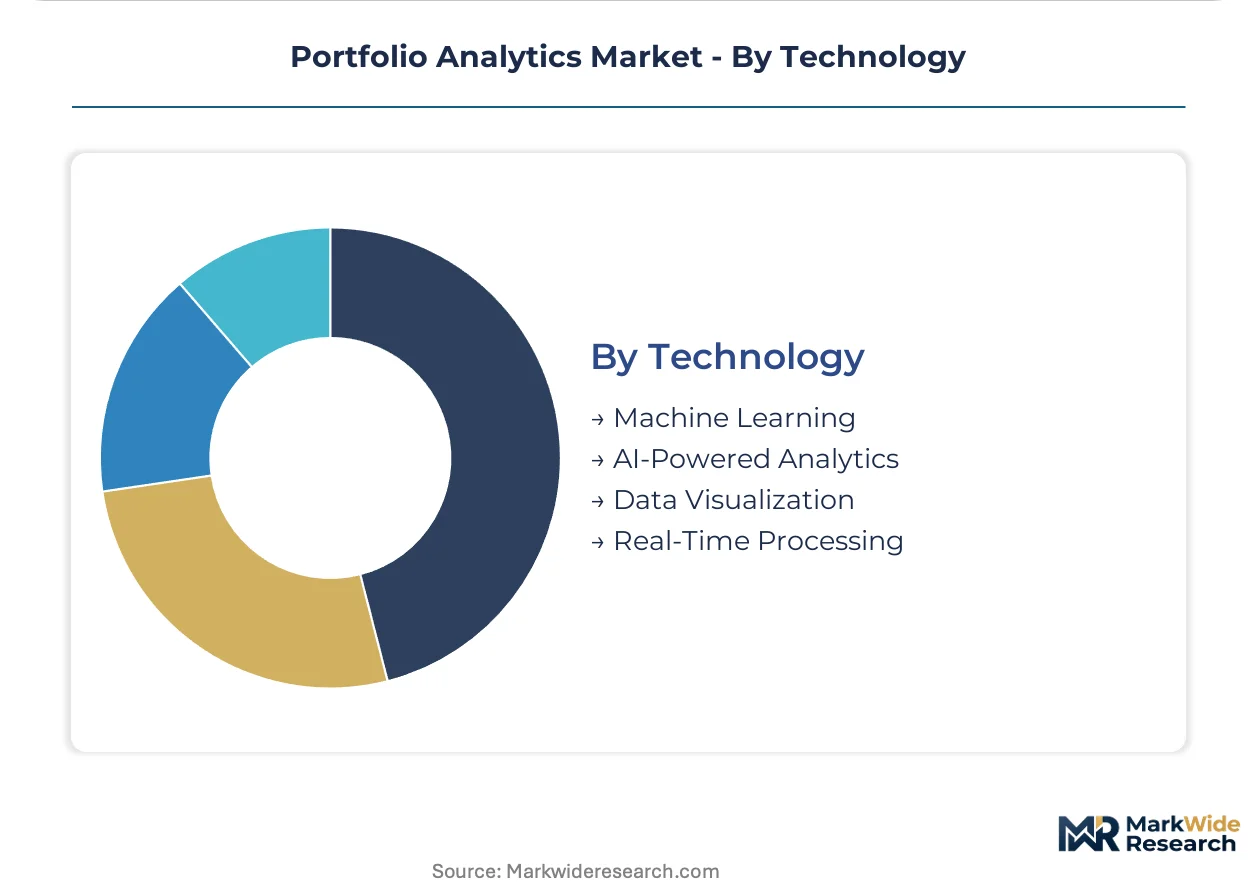
Technology:
Computational methods differentiate vendor capabilities, with machine learning now table stakes for competitive positioning.
- AI-Powered Analytics:Neural networks generate position-level risk signals and automate rebalancing decisions. Explainability modules are becoming mandatory under EU AI Act high-risk system classifications.
- Machine Learning:Supervised learning models for return prediction and anomaly detection require substantial training data infrastructure. Talent scarcity at the intersection of portfolio theory and data science constrains deployment velocity.
- Real-Time Processing:Stream architectures enable intraday risk monitoring for high-turnover strategies. Latency requirements below 100 milliseconds differentiate institutional-grade platforms.
- Data Visualization:Interactive dashboards and client-facing report generators complete the analytics stack. Self-service configuration reduces dependency on quantitative specialist teams.
Adoption maturity sits with Data Visualization. Capability investment is concentrating most heavily in AI-Powered Analytics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Asset managers in the United States generate the largest absolute demand for portfolio analytics platforms, while European procurement accelerates under regulatory deadlines. Geographic dispersion of vendor relationships reflects divergent compliance timelines and data residency requirements.
United States
Registered investment advisors and hedge funds drive procurement volume as SEC Form PF mandates granular position-level disclosure. The SEC enforces disaster recovery standards that favor elastic cloud architectures. New York and Boston anchor the vendor ecosystem, with fintech clusters in San Francisco deploying neural network risk engines for quantitative strategies.
United Kingdom
Asset managers face overlapping MiFID II cost transparency and FCA operational resilience requirements. The FCA examines data lineage for risk metric calculations during supervisory reviews. London concentrates vendor development teams and buyside analytics procurement, while Edinburgh hosts insurance-linked investment specialists upgrading attribution infrastructure.
Germany
Institutional investors prioritize liability-driven investment analytics under BaFin solvency supervision. The EU AI Act's algorithmic governance rules reshape product roadmaps for automated portfolio construction tools. Frankfurt's banking cluster and Munich's insurance headquarters sustain premium pricing for compliance-integrated platforms.
Switzerland
Family offices and private banks seek institutional-grade risk infrastructure despite smaller scale than sovereign wealth funds. FINMA data localization requirements sustain hybrid cloud demand alongside on-premise legacy systems. Zurich and Geneva dominate procurement, with Zug emerging as a hub for crypto-native asset managers requiring novel risk frameworks.
Singapore
Wealth management platforms serving Southeast Asian high-net-worth individuals expand analytics adoption. MAS technology risk management guidelines mandate resilience testing for algorithmic trading systems. The city-state's fintech sandbox attracts vendors piloting ESG attribution tools for palm oil and shipping exposure analysis.
Portfolio Analytics Market Competitive Landscape
United States vendors anchor the data and cloud infrastructure tier; European specialists hold regulatory compliance depth. Market structure concentrates around three archetypes: incumbent financial data conglomerates, statistical computing heritage firms, and cloud-native challengers. Dominant competitive moves include strategic partnerships between data providers and infrastructure platforms, plus portfolio diversification into adjacent wealthtech workflows.
Within the data moat tier, Morningstar exemplifies cross-platform integration strategies, while Moody's Analytics occupies a position anchoring credit-risk convergence with portfolio analytics. SAS Institute represents the statistical computing heritage archetype, with depth in risk-adjusted return modeling that persists among institutional investors. These three firms illustrate how vendor positioning stratifies around data asset control, computational methodology, and regulatory workflow embedding.
| Leading Market Players |
|---|
| Morningstar |
| YCharts |
| Moody's Analytics |
| Salesforce |
| SAS Institute |
| IBM |
| Oracle |
| Stock Rover |
| Portfolio Visualizer |
| Others |
Value Network & Pricing Analysis
Captive cloud infrastructure integration anchors supply positioning for portfolio analytics vendors while simultaneously determining pricing power. Asset managers with hybrid deployments draw from AWS and Azure for elastic compute while maintaining private data centers for position-level security, a split architecture that concentrates margin capture among infrastructure providers and squeezes standalone software vendors.
Pricing Analysis
Volume concentrates in subscription tiers while margin pools in compliance modules. SaaS pricing stratifies across premium attribution engines, standard risk visualization, and economy-tier retail dashboards. Price differentiation hinges on regulatory certification depth and API call volume scale. Pricing pressure stems from open-source Python libraries commoditizing basic risk calculations. Emerging managers in the United States exhibit highest price sensitivity; sovereign wealth funds in Switzerland and Saudi Arabia demonstrate lowest.
Supply Chain Analysis
Regional distribution centers for cloud infrastructure concentrate in the United States, Ireland, and Singapore. Software vendors draw from NVIDIA GPU clusters, proprietary market data feeds, and open-source machine learning frameworks. Single-source vulnerability sits with Bloomberg and Refinitiv for benchmark-quality pricing data. Distribution runs through direct enterprise sales teams for institutional clients and app marketplace integrations for retail-adjacent platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
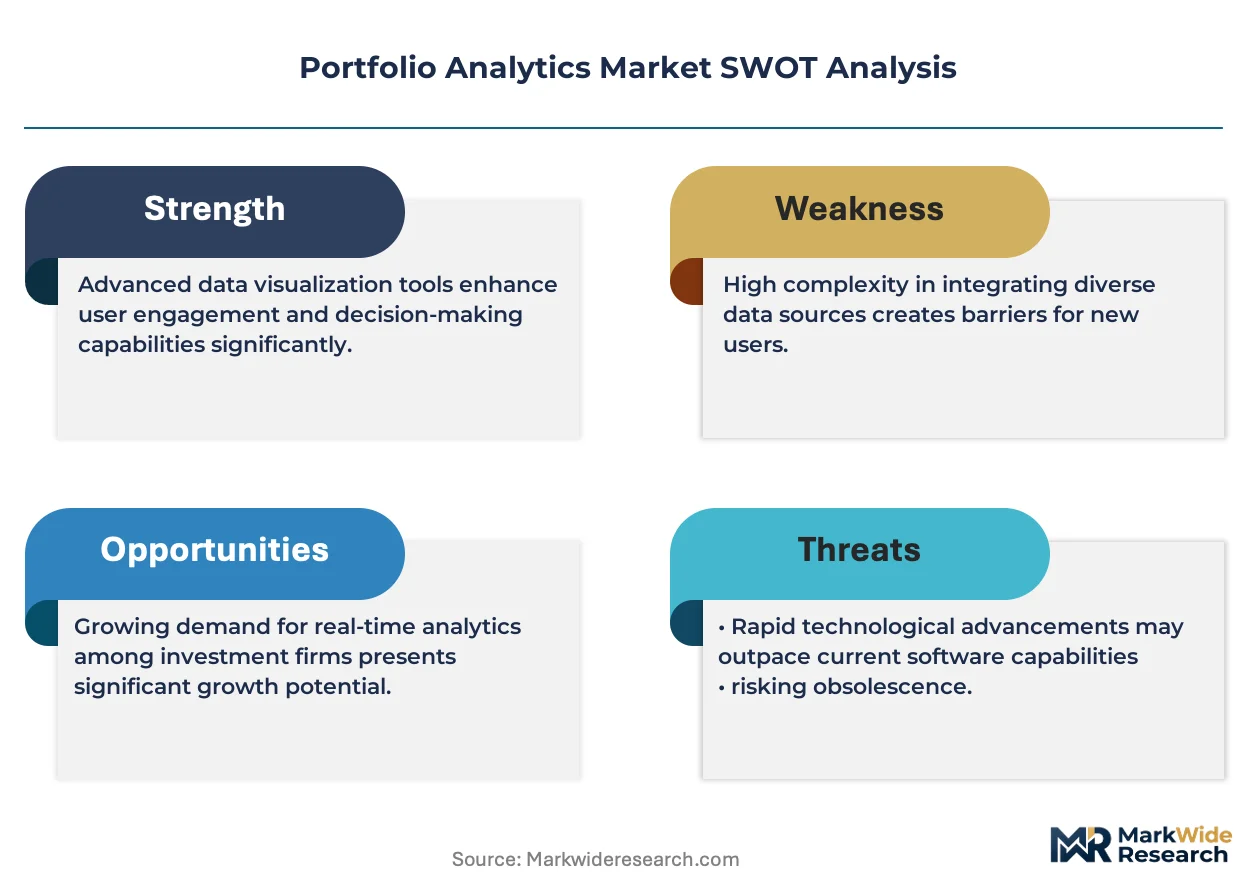
This market functions as a cost-of-compliance story where EU AI Act algorithmic governance requirements erect barrier-to-entry moats that favor vendors with pre-built explainability modules and human oversight protocols.
For Market Incumbents: Extend data moat advantages through deeper integration with advisor workstation ecosystems. Morningstar's cross-platform anchoring illustrates the defensive value of workflow embedding. Neural network talent scarcity in London and Silicon Valley threatens model refresh cycles; acquire specialist quant teams or lock exclusive university partnerships. Certification investment in EU AI Act conformity assessment procedures secures European revenue pools against cloud-native challengers. For New Entrants and Emerging Players: AI-powered narrative generation tools offer a technology-first wedge into relationship manager workflows at mid-sized RIAs. Private wealth in Singapore and Switzerland remains underpenetrated despite substantial AUM scale. White-label embedded finance distribution through Brazilian and Southeast Asian neobanks provides capital-efficient go-to-market velocity without direct enterprise sales overhead. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by data conglomerates seeking regulatory workflow depth. Long-term viability favors vendors with hybrid cloud orchestration capabilities and MiFID II compliance automation. Watch MAS technology risk management guideline enforcement in Singapore as an inflection signal for Southeast Asian procurement acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Embedding risk engines into Morningstar and Salesforce advisor workstations captures workflow lock-in. |
| Regulatory Certification Investment | EU AI Act conformity assessments extend product development timelines but secure European market access. |
| Acquisition of Specialist Firm | Neural network quant teams in London and Silicon Valley address talent scarcity constraining model deployment. |
| Strategic Partnership | Carbon accounting API alliances position vendors for CSRD sustainability reporting procurement cycles. |
| Geographic Expansion | Singapore fintech sandbox participation pilots ESG attribution tools for palm oil exposure analysis. |
Research Methodology
Document review covered SEC Form PF filings, ESMA cost transparency guidelines, and EU AI Act implementation texts, complemented by interviews with chief technology officers at asset managers, compliance officers at registered investment advisors, platform engineers at cloud infrastructure providers, and quantitative research leads at hedge funds. Secondary validation drew from vendor SEC 10-K disclosures, MAS technology risk circulars, and FINMA operational resilience guidance. Bottom-up deployment estimates triangulated against top-down AUM growth projections.
Market size outputs reflect segment-level modeling across deployment architecture, client sophistication tier, functional module, and computational methodology dimensions throughout the forecast period. CAGRs were derived from regression analysis against historical procurement velocity and regulatory deadline clustering. Forecast inputs incorporated SEC examination frequency trends and MiFID II disclosure penalty structures.
Forecast precision tightens around the base case; tail outcomes carry wider variance under EU AI Act enforcement delay scenarios or neural network talent migration patterns. Outputs reflect assumptions regarding cloud migration cost curves and regulatory jurisdiction convergence. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Portfolio Management and Asset Allocation
US Mutual Funds Market
Portfolio Management and Asset Allocation
Energy Portfolio Management Market
Portfolio Management and Asset Allocation
Balanced Funds Market
Portfolio Management and Asset Allocation
Global Project Portfolio Management (PPM) Market
Portfolio Management and Asset Allocation
Corporate Performance Management Market
Portfolio Management and Asset Allocation
Germany Mutual Funds Market
Portfolio Management and Asset Allocation
UK Mutual Funds Market
Portfolio Management and Asset Allocation
Portfolio Management Software Market
Portfolio Management and Asset Allocation
United States Project Portfolio Management Market