
 Germany Mutual Funds Market | 2026-2036
Germany Mutual Funds Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Mutual Funds Market Insights
Retail investors is reorganizing fund distribution dynamics across Germany as digital onboarding and robo-advisory platforms lower minimum investment thresholds. DWS Group leverages its scale advantage across passive and active strategies to sustain retail engagement through bundled banking channels. Union Investment anchors cooperative banking networks, while Flossbach von Storch specializes in concentrated equity approaches that attract performance-oriented HNWIs.
Germany mutual funds represent pooled investment vehicles regulated under the German Investment Code (KAGB) and EU UCITS directives, holding diversified portfolios of equities, bonds, or alternative assets with daily liquidity and professional management. Their primary purpose channels household and institutional savings into capital markets while offering risk diversification beyond direct security ownership. Equity strategies dominate asset flows among retail participants, whereas bond allocations retain structural importance for institutional liability matching. Balanced approaches are gaining traction as volatility-conscious investors seek blended exposure across growth and value orientations.
BaFin enforces KAGB disclosure standards and ESG integration requirements under the EU Sustainable Finance Disclosure Regulation, reshaping product design and marketing eligibility. The European Securities and Markets Authority coordinates stress-testing protocols that influence redemption liquidity management across German fund administrators. Stakeholders must monitor how evolving EU taxonomy alignment rules will reclassify eligible green assets and redirect distributor shelf space.
Market Dynamics
Retail investor migration toward digital distribution channels is compressing traditional bank-branch fund sales models across Germany, forcing asset managers to rebuild distribution economics around platform economics rather than relationship banking.
Growth Catalysts
- EU Green Deal taxonomy alignment:Sustainable fund classifications under SFDR Article 8 and 9 criteria are redirecting retail shelf space toward ESG-integrated products. This regulatory framework creates marketing eligibility advantages for compliant fund structures.
- Robo-advisory platform proliferation:Automated portfolio construction tools are lowering minimum investment thresholds from five-figure sums to sub-€500 entry points. Fintech-enabled distributors in Berlin and Munich are capturing first-time equity fund participants.
- Cooperative banking network infrastructure:Sparkassen and Volksbanken maintain embedded physical presence in smaller municipalities where digital-native competitors lack coverage. This geographic density sustains balanced fund distribution outside metropolitan cores.
Market Restraints
- Negative interest rate legacy on money market funds:Prolonged sub-zero policy rates from the European Central Bank have structurally compressed yield expectations for conservative retail segments. Many investors remain anchored to deposit-like return assumptions that equity funds cannot satisfy.
- BaFin liquidity stress-testing requirements:Enhanced redemption coverage mandates under ESMA-coordinated protocols have increased operational overhead for fund administrators. Smaller asset managers face disproportionate compliance cost burdens relative to AUM scale.
- Direct indexing technology substitution:Separately managed account platforms offering customized equity baskets are peeling away high-net-worth investors seeking tax-loss harvesting control. This bypasses mutual fund wrapper fees entirely.
Strategic Opportunities
- Eastern German state penetration:Saxony and Thuringia exhibit mutual fund ownership rates substantially below western Länder averages. Targeted financial literacy programs through employer-sponsored platforms could activate dormant household savings.
- Multi-asset target-date fund expansion:Automatic glide-path products addressing retirement savings gaps are underrepresented in German occupational pension schemes. Bundling through bAV (betriebliche Altersvorsorge) channels offers structural distribution access.
- CSRD-driven ESG data infrastructure:Corporate sustainability reporting mandates are improving underlying issuer disclosure quality. Fund managers with proprietary ESG scoring capabilities can differentiate active strategies through information advantage.
Industry Challenges
- Quantitative risk modeling talent scarcity:Derivatives structuring and alternative risk premia expertise remains concentrated among a handful of Frankfurt-based asset managers. Mid-tier firms struggle to recruit portfolio construction specialists capable of building non-correlated return streams.
- Legacy IT system integration friction:Migration from on-premise fund accounting platforms to cloud-native administration systems requires multi-year capital commitments. Operational continuity risks during transition periods deter technology modernization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Mutual Funds Market |
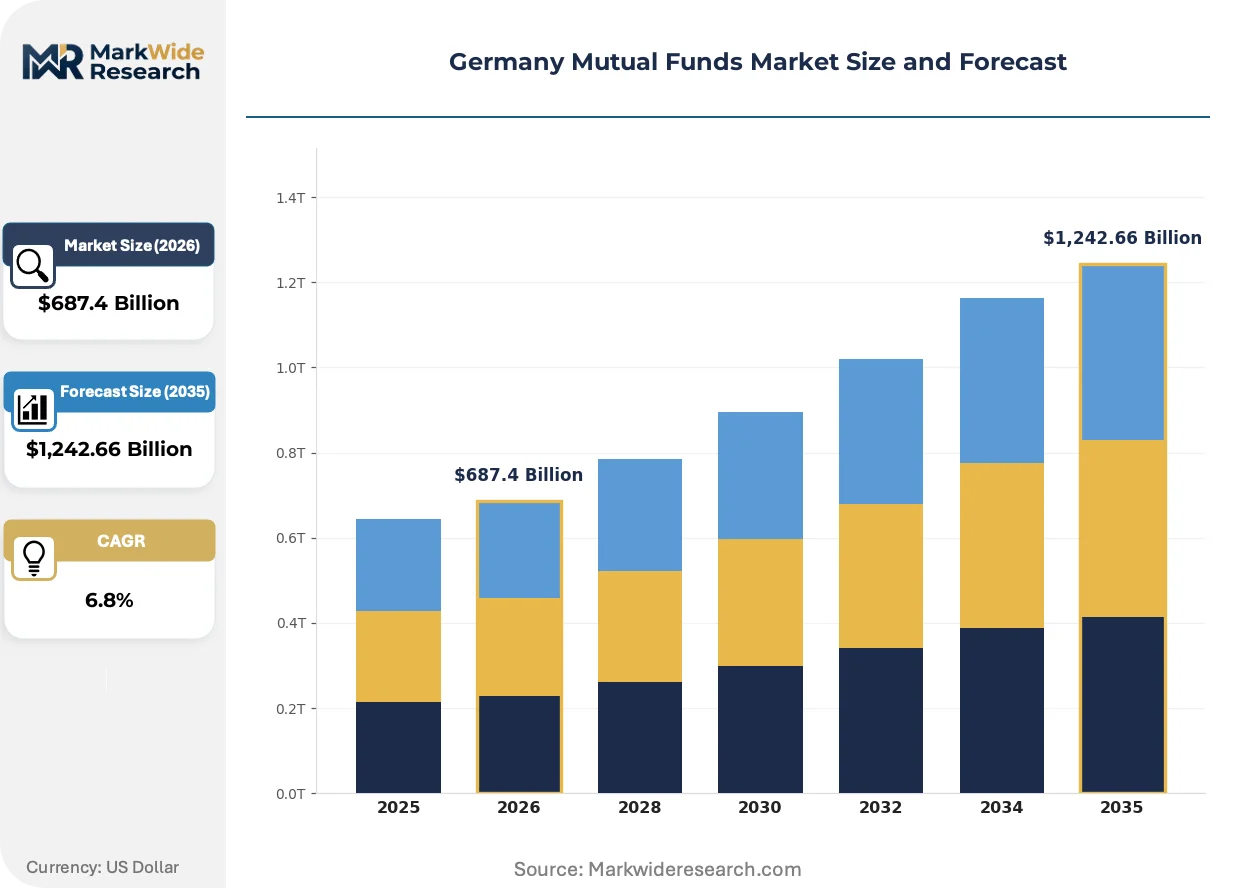
| Market Size in 2026 | $687.4 Billion |
| Market Size in 2035 | $1,242.66 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Investment Strategy: Growth, Value, Index, Balanced Fund Size: Small Cap, Mid Cap, Large Cap, Mega Cap Asset Class: Equities, Bonds, Real Estate, Commodities Investor Type: Retail Investors, Institutional Investors, HNWIs, Corporates |
| Companies Covered | Allianz Global Investors, DWS Group, Union Investment, DekaBank, Lupus alpha Asset Management, MEAG, Flossbach von Storch, Deutsche Invest Capital Partners, VanEck, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Mutual Funds Market Trends and Innovations
Fund distribution architecture is fragmenting across multiple channel types simultaneously, with no single model achieving dominance. This multiplicity forces asset managers to maintain parallel operational capabilities rather than optimizing around one pathway.
Blockchain-based fund tokenization is displacing traditional transfer agency record-keeping for selected alternative fund structures. Family offices and institutional allocators in Hamburg and Frankfurt are piloting digital share registry systems that compress settlement cycles from two days to near-instantaneous. This infrastructure compression reduces administrative drag but requires BaFin regulatory sandbox participation for legal validity.
The EU AI Act's risk classification framework for algorithmic decision-making is reshaping robo-advisory product design across German fund platforms. Automated recommendation engines now face mandatory human oversight requirements and explainability standards. Retail-facing distributors are reengineering client interface protocols to document intervention points where algorithmic suggestions are overridden.
Subscription-based financial advisory models are replacing commission-driven fund sales in affluent household segments. Independent fee-only planners in Munich and Düsseldorf are disintermediating bank-owned distribution channels by unbundling product recommendation from transaction execution. This shift concentrates fund selection authority with advisors who prioritize total expense ratio minimization over revenue-sharing arrangements.
Germany Mutual Funds Market Segmentation
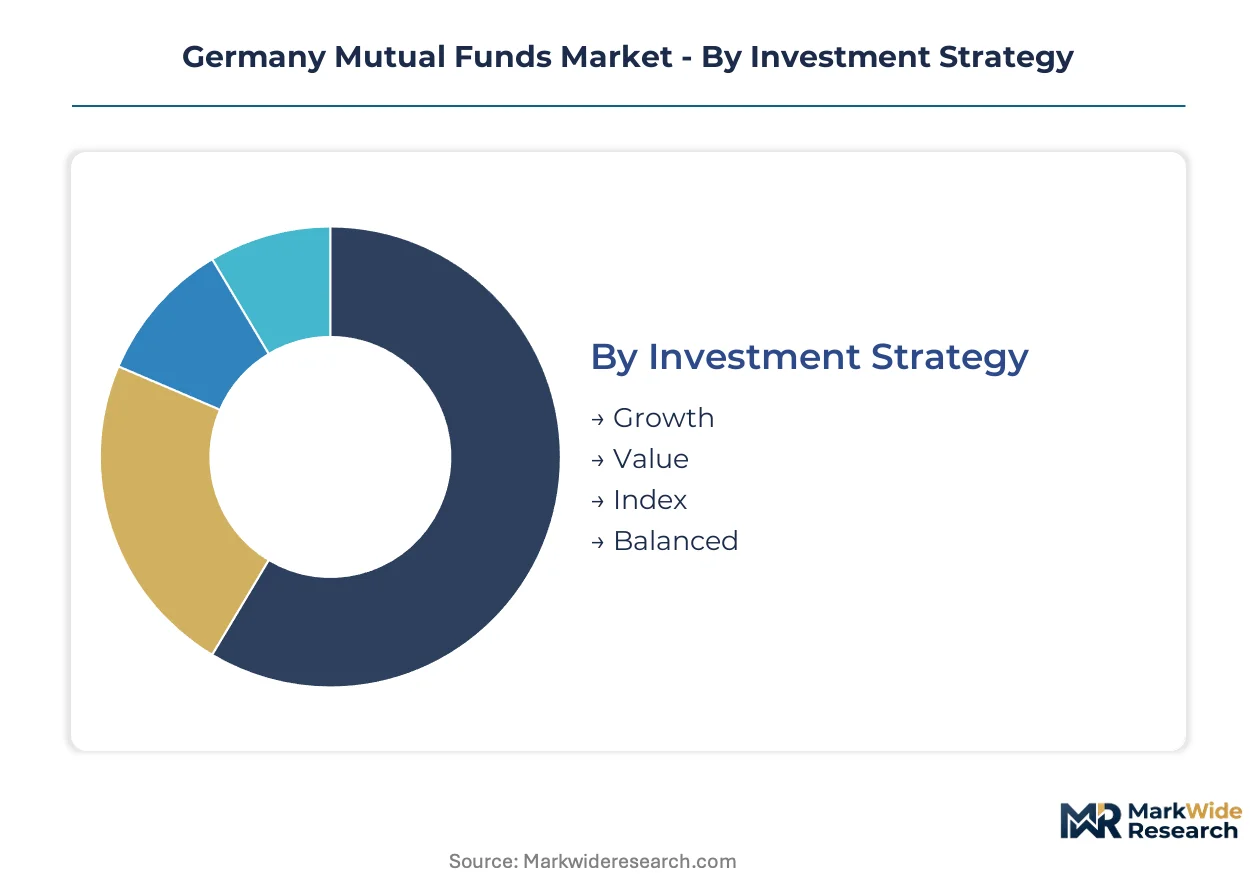
Investment strategy and asset class allocations determine fee structures and redemption patterns across German fund platforms. Fund size categories shape liquidity management requirements under BaFin stress-testing protocols. Investor type segmentation governs distribution channel economics and ESG disclosure intensity.
Investment Strategy:
Active management premiums concentrate in concentrated equity approaches, while passive vehicles compete on expense ratio minimization.
- Growth:Portfolio managers target companies with above-average earnings expansion, typically technology and healthcare issuers. Berlin-based robo-advisors channel millennial savers into growth-oriented UCITS funds as they build equity exposure for the first time.
- Value:These strategies emphasize undervalued equities with strong balance sheet characteristics and dividend yield support. Sparkassen cooperative networks distribute value funds to conservative retail clients in smaller municipalities where digital platforms have weaker penetration.
- Index:Passive replication of benchmark indices at minimal cost. DWS Group and BlackRock dominate shelf space through bundled banking relationships.
- Balanced:Blended equity-fixed income allocations for volatility-conscious investors. Demand is accelerating among pre-retirement households seeking glide-path stability.
Growth strategies hold installed capacity. Balanced is rotating up the share rankings.
Fund Size:
Large-cap vehicles capture the deepest liquidity pools, while mid-cap specialization commands performance fee premiums.
- Small Cap:Concentrated positions in sub-$2 billion market capitalization issuers. Flossbach von Storch attracts HNWI capital through specialized small-cap equity teams with concentrated research coverage.
- Mid Cap:The sweet spot between liquidity and alpha generation. Munich-based independent advisors favor mid-cap funds for clients seeking growth with manageable volatility profiles.
- Large Cap:Core holdings for institutional liability matching and retail core-satellite construction. Union Investment anchors cooperative distribution with large-cap equity and bond fund staples.
- Mega Cap:Direct indexing competition has compressed mutual fund wrapper demand at the largest capitalization tiers. Institutional investors increasingly bypass fund structures for separately managed accounts.
Large Cap holds installed capacity. Mid Cap is rotating up the share rankings.
Asset Class:
Fixed income retains structural importance for German insurance and pension fund liability matching, while real estate commands illiquidity premiums.
- Equities:Dominant asset class for retail participation through digital distribution platforms. Robo-advisory proliferation in Berlin and Munich has lowered minimum investment thresholds to sub-€500 entry points.
- Bonds:Government and corporate debt allocations serve institutional redemption coverage requirements. Negative interest rate legacy has compressed yield expectations and pushed conservative investors toward longer-duration strategies.
- Real Estate:Open-ended fund structures with quarterly liquidity windows. German Spezialfonds channel institutional capital into domestic commercial property exposure.
- Commodities:Inflation hedging and diversification vehicles, typically through swap-based replication. Retail uptake remains limited due to volatility and tax treatment complexity.
Bonds holds installed capacity. Real Estate is rotating up the share rankings.
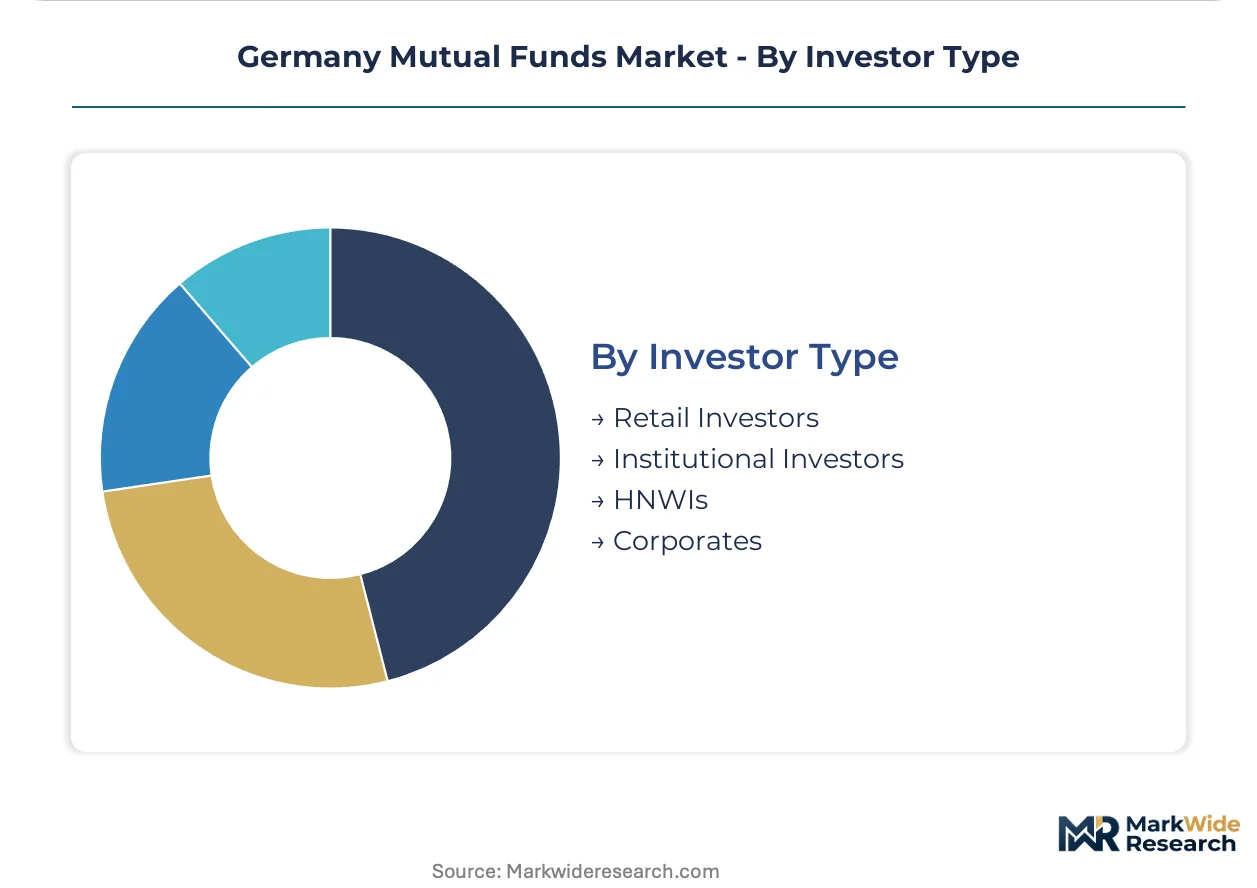
Investor Type:
Retail participation drives platform economics, while institutional mandates determine operational scale requirements.
- Retail Investors:Individual households accessing funds through bank branches, direct platforms, or robo-advisors. Digital onboarding has expanded participation among first-time equity investors in metropolitan hubs.
- Institutional Investors:Insurance companies, pension funds, and corporate treasuries with customized mandate structures. BaFin liquidity stress-testing requirements shape product design for this segment.
- HNWIs:High-net-worth individuals with capacity for segregated mandates and alternative fund access. Direct indexing technology is peeling away this segment from traditional mutual fund wrappers.
- Corporates:Treasury cash management and employee savings plan sponsorship. Betriebliche Altersvorsorge channels offer structural distribution access for target-date and balanced fund products.
Retail Investors holds installed capacity. Institutional Investors is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German fund managers export UCITS-compliant products across European distribution networks, with Luxembourg and Ireland serving as primary domiciliation jurisdictions for cross-border retail access.
Bavaria
Munich anchors southern Germany's wealth management concentration, with private banks and independent advisors driving balanced fund adoption among affluent pre-retirement households. BaFin's KAGB disclosure standards shape product registration protocols for distributors operating across this high-net-worth corridor. The city's fintech clusters are pioneering subscription-based advisory models that disintermediate traditional bank-owned channels.
North Rhine-Westphalia
The Düsseldorf-Cologne corridor concentrates institutional fund mandates from insurance groups and corporate pension schemes. The EU Green Deal taxonomy redirects shelf space toward SFDR Article 8 and 9 compliant structures through bAV occupational pension channels. DekaBank leverages cooperative banking infrastructure across this densely populated industrial belt.
Hesse
Frankfurt's asset management density creates quantitative risk modeling talent scarcity that constrains mid-tier firm expansion. ESMA-coordinated stress-testing protocols administered through BaFin influence liquidity management requirements for fund administrators headquartered in this regulatory capital. The city's derivatives structuring expertise concentrates among established players.
Berlin-Brandenburg
Berlin's robo-advisory proliferation captures first-time equity investors through sub-€500 minimum thresholds on digital platforms. The EU AI Act's risk classification framework mandates human oversight requirements for algorithmic recommendation engines deployed across these fintech-enabled distributors. Venture capital flows support platform economics experimentation outside traditional branch banking.
Hamburg
Family offices and institutional allocators in this northern port city pilot blockchain-based fund tokenization for alternative structures. BaFin regulatory sandbox participation enables digital share registry systems that compress settlement cycles. The cluster's maritime wealth origins sustain demand for real estate and infrastructure fund exposure.
Germany Mutual Funds Market Competitive Landscape
Player mix skews toward banking-affiliated asset managers with captive distribution networks. The competitive structure concentrates around three strategic archetypes: cooperative banking-integrated managers, independent boutiques with concentrated equity specializations, and global platform providers with passive scale advantages. M&A activity targets digital distribution capabilities, while portfolio diversification moves emphasize multi-asset target-date construction for retirement savings gaps.
Within the banking-affiliated tier, Allianz Global Investors and DWS Group exemplify scale-driven operators with bundled distribution access across retail and institutional channels. Union Investment anchors cooperative banking networks through Sparkassen and Volksbanken infrastructure. Independent specialists Flossbach von Storch occupy positions in concentrated equity approaches that attract performance-oriented high-net-worth investors seeking differentiated alpha generation outside standardized product frameworks.
| Leading Market Players |
|---|
| Allianz Global Investors |
| DWS Group |
| Union Investment |
| DekaBank |
| Lupus alpha Asset Management |
| MEAG |
| Flossbach von Storch |
| Deutsche Invest Capital Partners |
| VanEck |
| Others |
Pricing and Supply Chain Analysis
Long-term capacity reservation agreements between asset managers and fund administration platforms lock in distribution shelf space while providing fee visibility across multi-year horizons. These contractual structures align BaFin compliance cost allocations with platform technology investments, creating mutual dependency between pricing power and operational infrastructure.
Pricing Analysis
Next-generation robo-advisory platforms command fee premiums of 15-25 basis points above legacy branch-based distribution, while prior-generation telephone-sales models face compression toward zero-revenue sharing. The dominant pricing structure stratifies across active management premium tiers, passive index economy tiers, and hybrid advisory standard tiers. Price differentiation rests on ESG integration depth and digital onboarding sophistication. Cost compression in passive vehicles is intensifying because BlackRock and DWS Group leverage scale economies across bundled banking channels. Retail investors accessing funds through Sparkassen cooperative networks demonstrate lowest price sensitivity, while millennial first-time investors on Berlin-based fintech platforms exhibit highest sensitivity to total expense ratios.
Supply Chain Analysis
Inventory cycles for fund accounting software licenses and transfer agency services extend 12-18 months, creating capacity constraints during platform migration waves. Technology infrastructure concentrates in Germany, Ireland, and Luxembourg as UCITS domiciliation hubs. Raw material dependencies include cloud computing capacity from hyperscale providers, proprietary ESG data feeds from CSRD-compliant issuers, and compliance software modules from regulated vendors. Single-source vulnerability sits with legacy mainframe-dependent transfer agents facing BaFin-mandated stress-testing upgrades. Distribution runs through three parallel channels: cooperative banking networks, independent fee-only advisors, and direct-to-consumer digital platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Germany's mutual fund market represents early-cycle expansion driven by retail investor migration toward sub-€500 minimum digital entry points. Robo-advisory penetration in Berlin and Munich demonstrates untapped household savings activation across eastern Länder.
For Market Incumbents: Secure distribution exclusivity through technology co-development with cooperative banking networks before fintech platforms achieve comparable geographic density. Prioritize backward integration into proprietary ESG scoring infrastructure as CSRD disclosure mandates intensify data differentiation. Defend against direct indexing substitution by embedding tax-optimization features within mutual fund wrappers.
For New Entrants and Emerging Players: Differentiate on employer-sponsored betriebliche Altersvorsorge channel access, where automatic enrollment mechanics bypass customer acquisition cost barriers. Target Saxony and Thuringia financial literacy gaps through employer-platform partnerships. Penetrate the multi-asset target-date fund white space with glide-path products addressing retirement savings gaps. Lead with subscription-based advisory models that disintermediate revenue-sharing arrangements.
For Investors and Strategic Acquirers: Boutique asset managers with concentrated equity specializations and established HNWI relationships represent prime acquisition targets as direct indexing pressures traditional mutual fund economics. Long-term viability hinges on regulatory technology capabilities that automate SFDR Article 8 and 9 compliance workflows. Monitor blockchain-based fund tokenization pilots in Hamburg family offices as infrastructure modernization inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Robo-Advisory Platform Development | BaFin's KAGB disclosure requirements shape algorithmic recommendation engine design protocols. |
| ESG Data Infrastructure Investment | CSRD-driven issuer disclosure quality creates information advantage for active managers. |
| Cooperative Banking Network Integration | Sparkassen and Volksbanken geographic density sustains distribution outside metropolitan cores. |
| Multi-Asset Target-Date Fund Launch | Betriebliche Altersvorsorge channels offer structural access to retirement savings gaps. |
| Blockchain Tokenization Pilot | BaFin regulatory sandbox participation validates digital share registry compression. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with fund distribution executives, portfolio construction specialists, BaFin regulatory affairs leads, and cooperative banking network managers. Secondary validation drew from KAGB implementation guidance, ESMA stress-testing protocols, EU Sustainable Finance Disclosure Regulation technical standards, and Bundesbank household financial wealth surveys. Bottom-up asset flow modeling triangulated against top-down GDP-savings rate projections.
Across the analysis window, forecasts integrated investment strategy segmentation by active-passive orientation, fund size liquidity tiers, asset class allocation patterns, and investor type channel economics. CAGRs were derived from historical flow momentum adjusted for regulatory catalyst velocity and technology substitution curves. Modeled inputs included robo-advisory platform adoption curves, SFDR product reclassification timelines, and direct indexing competitive encroachment rates.
Material uncertainties — ECB interest rate trajectory shifts, EU taxonomy alignment rule revisions, and blockchain settlement infrastructure regulatory validation — sit outside the modeled envelope. Forecasts reflect assumptions about retail digital onboarding acceleration and institutional liability-matching demand stability. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Portfolio Management and Asset Allocation
Energy Portfolio Management Market
Portfolio Management and Asset Allocation
UK Mutual Funds Market
Portfolio Management and Asset Allocation
Portfolio Analytics Market
Portfolio Management and Asset Allocation
Corporate Performance Management Market
Portfolio Management and Asset Allocation
US Mutual Funds Market
Portfolio Management and Asset Allocation
Portfolio Management Software Market
Portfolio Management and Asset Allocation
United States Project Portfolio Management Market
Portfolio Management and Asset Allocation
Global Project Portfolio Management (PPM) Market
Portfolio Management and Asset Allocation
Balanced Funds Market