
 United States Project Portfolio Management Market | 2026-2036
United States Project Portfolio Management Market Size, Share, and Industry Trends Forecast 2026-2036
United States Project Portfolio Management Market Analytics
Mid-market professional services firms is bifurcating from traditional enterprise buyers as the fastest-growing procurement segment in United States Project Portfolio Management. Oracle Corporation leverages its integrated cloud infrastructure to anchor complex federal and defense portfolio deployments. Microsoft Corporation competes through native embedding within Office 365 and Azure ecosystems, reducing switching costs for existing enterprise customers. Planview Inc. specializes in resource management and strategic planning modules that differentiate its offering for manufacturing and aerospace verticals.
United States Project Portfolio Management encompasses software platforms that orchestrate multi-project selection, prioritization, and resource allocation across enterprise programs, typically integrating Gantt scheduling, capacity planning dashboards, and real-time financial tracking against capital expenditure budgets. Cloud-Based deployment now leads segment growth as FedRAMP-authorized SaaS offerings displace legacy on-premise installations in government and healthcare verticals, while Financial Management solution modules capture disproportionate margin pools due to embedded ROI analytics and compliance reporting functionality that large corporations prioritize during procurement cycles.
FedRAMP, NIST SP 800-53, and SEC cybersecurity disclosure rules collectively reshape vendor qualification and product architecture requirements for software providers serving regulated United States industries. FedRAMP authorization creates a two-tier market access structure where authorized vendors capture federal agency contracts while non-compliant suppliers remain restricted to commercial segments. Stakeholders must monitor evolving CMMC integration timelines and state-level data residency mandates that could fragment deployment architectures across California, Texas, and New York regulatory jurisdictions.
Market Dynamics
FedRAMP authorization requirements are compressing vendor qualification timelines while NIST cybersecurity frameworks force architectural redesigns across federal procurement channels, fundamentally restructuring competitive access to government portfolio management contracts.
Growth Catalysts
- FedRAMP Authorization Mandates:Federal agencies now require authorized SaaS platforms for infrastructure program oversight, creating compliant vendor preference in multi-billion dollar procurement pools.
- Defense Portfolio Modernization:Pentagon digital transformation initiatives drive demand for integrated resource allocation dashboards across weapons system development programs.
- California Enterprise Consolidation:Technology sector headquarters in Silicon Valley and San Francisco prioritize platform unification to reduce software sprawl across distributed engineering teams.
Market Restraints
- Specialized Talent Scarcity:Shortage of certified portfolio management professionals with federal compliance expertise limits implementation velocity for complex deployments.
- Legacy System Interoperability:Proprietary data formats in existing ERP installations create integration friction that extends deployment cycles by 40-60%.
- CMMC Timeline Uncertainty:Pending Cybersecurity Maturity Model Certification requirements introduce procurement hesitation among defense contractors awaiting final rule publication.
Strategic Opportunities
- Texas Energy Sector Expansion:Oil and gas majors in Houston are consolidating project oversight tools for capital-intensive exploration and renewable transition programs.
- Healthcare Vertical Penetration:Hospital systems in New York and Massachusetts seek FedRAMP-authorized platforms to manage facility construction and clinical system rollouts under HIPAA constraints.
- Artificial Intelligence Convergence:Machine learning modules for predictive resource allocation and risk scoring create differentiation for next-generation platform releases.
Industry Challenges
- Multi-Cloud Integration Complexity:Enterprises operating across AWS GovCloud, Azure Government, and on-premise environments face architectural fragmentation that complicates single-pane portfolio visibility.
- State Data Residency Fragmentation:Diverging requirements between California Consumer Privacy Act provisions and Texas data localization preferences force redundant deployment configurations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Project Portfolio Management Market |
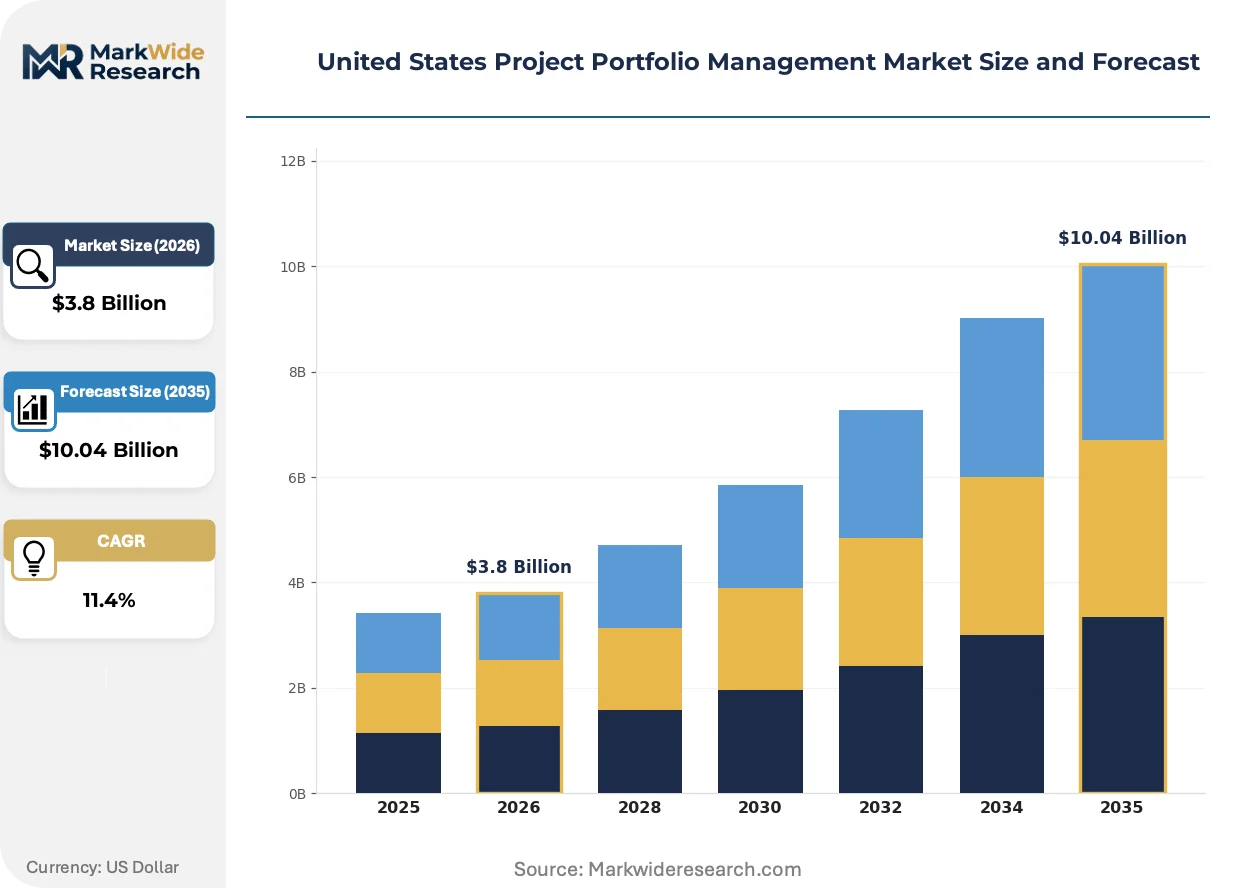
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Type: On-Premise, Cloud-Based, Hybrid, Managed Services Industry Vertical: IT, Construction, Healthcare, Financial Services End User: Small Enterprises, Medium Enterprises, Large Corporations, Government Agencies Solution Category: Project Management, Resource Management, Financial Management, Reporting Tools |
| Companies Covered | Oracle Corporation, ServiceNow Inc., Microsoft Corporation, Atlassian Corporation PLC, Smartsheet, SAP SE, Asana Inc., Planview Inc., Procore, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Project Portfolio Management Market Evolving Landscape
Cloud-native architectures are displacing legacy on-premise installations as federal security authorizations mature, while embedded analytics capabilities reshape how procurement committees evaluate platform investments.
Artificial intelligence for predictive portfolio risk scoring is bifurcating vendor competitive positioning. Early adopters in aerospace manufacturing deploy machine learning modules to forecast resource contention across concurrent programs. This capability compression is forcing traditional planning tool vendors toward partnership or acquisition strategies to maintain federal contract eligibility.
NIST SP 800-53 control implementations now mandate continuous monitoring architectures for all federal portfolio management deployments. Software providers must embed automated compliance reporting that feeds directly into agency security dashboards. Defense and civilian agencies in Virginia and Maryland procurement corridors are prioritizing platforms with pre-mapped control implementations over generic enterprise alternatives.
Subscription pricing for outcome-based portfolio oversight is displacing perpetual license models among mid-market professional services firms. Consulting partnerships in Chicago and Boston now bundle platform access with implementation support, unbundling traditional VAR relationships. This channel restructuring concentrates margin capture with vertically specialized advisors rather than broad technology distributors.
United States Project Portfolio Management Market Segmentation
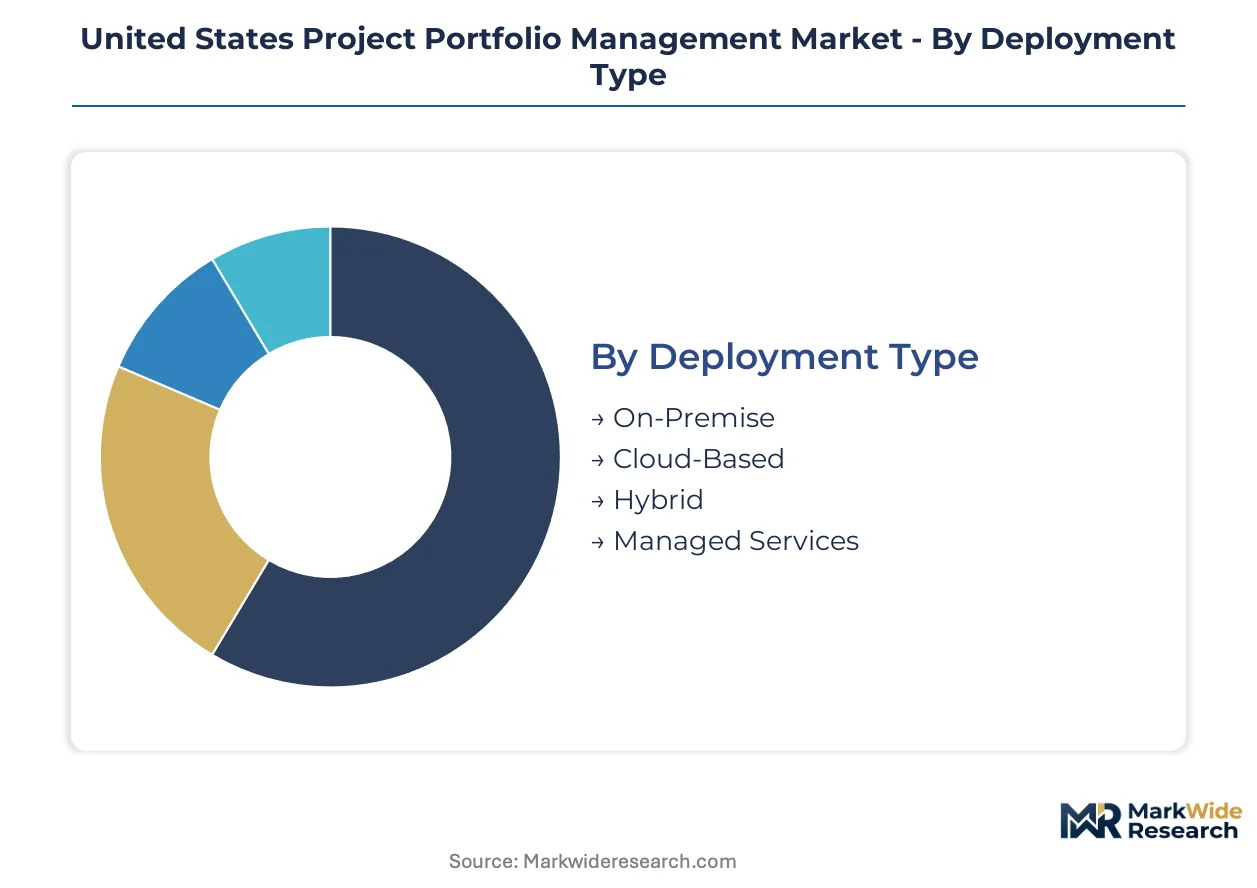
Portfolio management procurement patterns diverge sharply across deployment architectures and organizational scale. Federal compliance mandates and enterprise consolidation pressures create distinct segment trajectories that reshape vendor go-to-market strategies.
Deployment Type:
Domestic demand concentrates in federally authorized platforms, while export-oriented configurations serve multinational corporations with hybrid sovereignty requirements.
- Cloud-Based:FedRAMP-authorized SaaS architectures now anchor federal agency procurement, with continuous monitoring dashboards embedded per NIST SP 800-53. California and Texas healthcare systems drive commercial adoption for HIPAA-aligned facility construction oversight.
- On-Premise:Legacy installations persist in defense contractor environments awaiting CMMC finalization, with air-gapped configurations mandatory for classified program portfolios. Pentagon weapons system development programs sustain this segment through extended refresh cycles.
- Hybrid:Split architectures accommodate state-level data residency fragmentation between California Consumer Privacy Act and Texas localization preferences.
- Managed Services:Third-party operational control appeals to mid-market professional services firms lacking internal cybersecurity expertise.
On-Premise commands the established base. The steepest expansion runs through Cloud-Based.
Industry Vertical:
Cost-tier stratification separates capital-intensive infrastructure programs from recurring operational technology spend.
- IT:Silicon Valley engineering organizations prioritize platform unification across distributed agile teams. San Francisco headquarters drive consolidation to reduce software sprawl from acquired startup tool stacks.
- Construction:Gantt scheduling and resource leveling modules dominate mega-project oversight for federal infrastructure programs. New York metropolitan transit and energy transmission projects sustain specialized vendor ecosystems.
- Healthcare:Hospital construction and clinical system rollouts demand FedRAMP authorization under HIPAA constraints.
- Financial Services:SEC cybersecurity disclosure rules mandate audit trails for capital expenditure governance.
Construction retains the deepest incumbent footprint. Healthcare climbs the fastest on compliance tailwinds.
End User:
Customer-type stratification reveals bifurcation between compliance-driven public sector and efficiency-seeking private enterprise.
- Government Agencies:Federal portfolio governance tools manage multi-billion dollar infrastructure programs with NIST-mandated continuous monitoring. Virginia and Maryland procurement corridors prioritize pre-mapped control implementations.
- Large Corporations:Enterprise digital transformation initiatives in California, Texas, and New York drive platform consolidation across business units.
- Medium Enterprises:Subscription pricing for outcome-based oversight displaces perpetual licenses among Chicago and Boston consulting partnerships.
- Small Enterprises:Bundled implementation support from specialized advisors replaces traditional VAR relationships.
Large Corporations anchor current revenue. Government Agencies gain share fastest on federal modernization mandates.
Solution Category:
Margin pools concentrate where embedded analytics intersect regulatory reporting requirements.
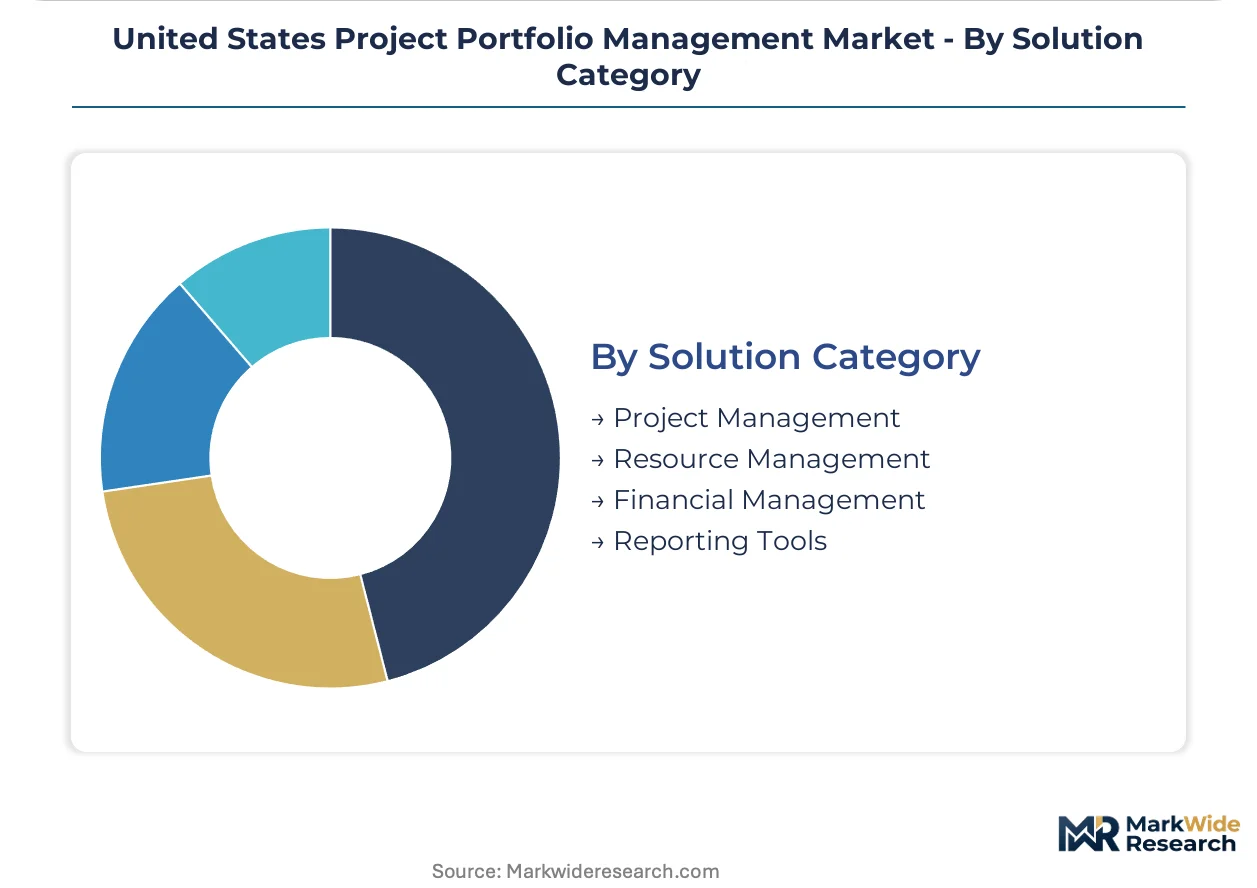
- Financial Management:ROI analytics and compliance reporting functionality capture disproportionate margin as procurement committees prioritize capital expenditure visibility. Real-time budget tracking against program baselines distinguishes premium offerings.
- Resource Management:Capacity planning dashboards differentiate platforms for manufacturing and aerospace verticals with concurrent program contention.
- Project Management:Core Gantt scheduling and milestone tracking faces commoditization pressure from adjacent productivity suites.
- Reporting Tools:Automated compliance feeds into agency security dashboards now table stakes for federal eligibility.
Project Management holds the broadest installed base. Financial Management expands most quickly on procurement committee prioritization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Enterprise buyers concentrate in coastal technology corridors and federal procurement hubs, with demand bifurcating between compliance-driven government agencies and efficiency-seeking private corporations. Federal modernization mandates and state-level data residency requirements reshape deployment architectures across sub-regional markets.
California
Silicon Valley technology headquarters and San Francisco enterprise campuses drive platform consolidation initiatives to reduce software sprawl across distributed engineering teams. The California Consumer Privacy Act imposes data residency constraints that complicate multi-cloud portfolio architectures. Los Angeles and San Diego aerospace contractors deploy resource management modules for concurrent weapons system development programs.
Texas
Houston energy majors consolidate project oversight tools for capital-intensive exploration portfolios and renewable transition investments. State data localization preferences create deployment friction with California-aligned privacy frameworks. Dallas-Fort Worth healthcare systems seek FedRAMP-authorized platforms for facility construction management under HIPAA constraints.
Virginia and Maryland
Pentagon procurement corridors and civilian agency headquarters anchor federal portfolio governance demand with NIST-mandated continuous monitoring requirements. FedRAMP authorization serves as gatekeeper for multi-billion dollar infrastructure program contracts. Northern Virginia defense contractors maintain air-gapped on-premise installations for classified program portfolios awaiting CMMC finalization.
New York
Metropolitan transit authorities and financial services headquarters prioritize financial management modules with embedded SEC cybersecurity disclosure compliance. Hospital construction and clinical system rollouts in New York City and Boston drive healthcare vertical penetration. Albany state agencies add procurement volume for infrastructure program oversight tools.
Illinois
Chicago consulting partnerships bundle subscription-based platform access with implementation support, displacing traditional VAR relationships for mid-market professional services firms. Manufacturing headquarters in Detroit and Cleveland extend demand for capacity planning dashboards across concurrent program contention. State procurement offices modernize legacy ERP integrations for capital expenditure visibility.
United States Project Portfolio Management Market Competitive Landscape
Player mix skews toward diversified enterprise software conglomerates with adjacent cloud infrastructure assets, creating tiered access patterns where federal authorization status determines contract eligibility. Market structure concentrates around vendors with pre-mapped NIST control implementations and FedRAMP authorization credentials. Strategic archetypes include integrated cloud infrastructure providers, specialized resource management platforms, and native productivity suite embedders. Dominant competitive moves encompass partnership strategies for AI capability acquisition and geographic expansion through vertically specialized consulting channels.
Within the integrated infrastructure tier, Oracle Corporation and Microsoft Corporation exemplify archetypes leveraging captive cloud ecosystems to reduce customer switching costs and anchor complex federal deployments. Planview Inc. occupies a position among specialized resource management providers, differentiating through strategic planning modules for manufacturing and aerospace verticals with concurrent program contention requirements. ServiceNow Inc. and SAP SE sit within the enterprise workflow consolidation segment, competing through platform unification value propositions across IT and business process domains.
| Leading Market Players |
|---|
| Oracle Corporation |
| ServiceNow Inc. |
| Microsoft Corporation |
| Atlassian Corporation PLC |
| Smartsheet |
| SAP SE |
| Asana Inc. |
| Planview Inc. |
| Procore |
| Others |
Value Network & Pricing Analysis
Capacity reservation agreements with FedRAMP-authorized cloud providers lock in multi-year supply access while capping price escalation for federal agency deployments. These contractual structures tether software procurement committees to pre-negotiated SaaS tiers, insulating program budgets from volatile infrastructure scaling costs across the analysis window.
Pricing Analysis
Cost-plus contracts with CPI indexation anchor enterprise SaaS procurement for federal portfolio management deployments. Three-tier pricing structure across premium, standard, and economy levels differentiates by FedRAMP authorization tier and embedded analytics depth. Pricing pressure stems from mid-market professional services firms consolidating vendor relationships to reduce software sprawl. Government agencies exhibit lowest price sensitivity due to compliance-mandated procurement timelines, while small enterprises face acute cost compression.
Supply Chain Analysis
Implementation lead times for FedRAMP-authorized platforms now stretch eighteen to twenty-four months, forcing procurement committees into advance capacity commitments. Software development concentrates in the United States, India, and Ireland, with cloud infrastructure anchoring in AWS GovCloud and Azure Government regions. The supply chain draws from specialized cybersecurity audit firms, compliance documentation specialists, and federal contracting advisors. Single-source vulnerability in FedRAMP authorization pathways creates bottleneck risk. Distribution runs through vertically specialized consulting partnerships rather than broad technology distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics in United States Project Portfolio Management hinge on interoperability with Office 365 and Azure ecosystems, where native embedding creates switching-cost moats that reshape competitive boundaries.
For Market Incumbents: Consolidate federal contract eligibility through accelerated FedRAMP authorization investments, locking out non-compliant challengers from Pentagon and civilian agency procurement corridors. Deepen captive cloud infrastructure control to reduce third-party dependency in multi-cloud deployments. CMMC timeline uncertainty threatens defense contractor revenue streams; pre-mapped NIST control implementations provide defensive differentiation.
For New Entrants and Emerging Players: Anchor in Texas energy sector consolidation, where Houston majors seek specialized resource management for capital-intensive exploration portfolios without entrenched vendor relationships. Target mid-market professional services firms in Chicago and Boston through subscription bundling with implementation support. FedRAMP authorization partnerships with established cloud providers accelerate market access.
For Investors and Strategic Acquirers: Capital is best deployed toward specialized resource management platforms with aerospace and manufacturing vertical depth, where concurrent program contention requirements sustain premium pricing. Long-term viability rests on AI capability integration for predictive risk scoring. Watch CMMC final rule publication as signal for defense contractor procurement acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
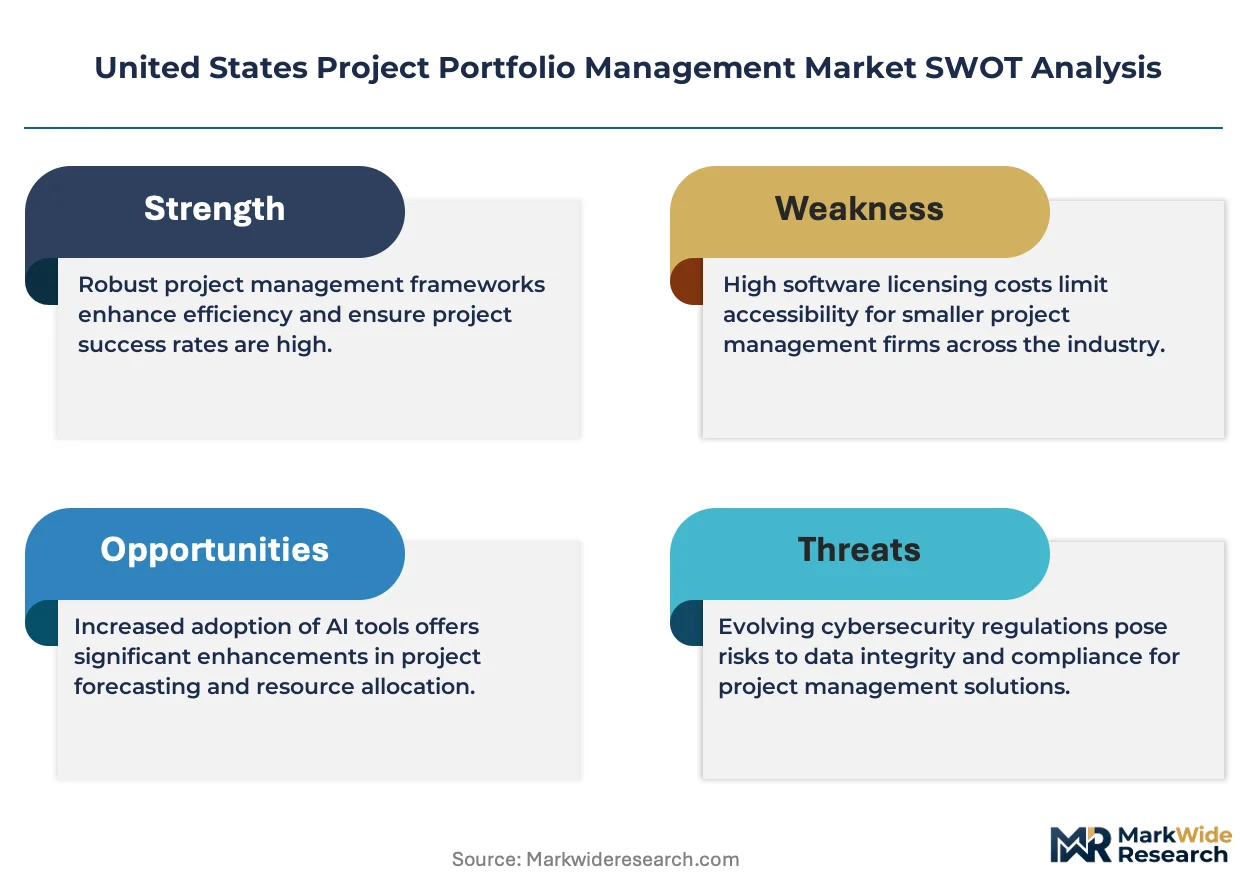
| FedRAMP Authorization Acceleration | Unlocks multi-billion dollar federal infrastructure program contracts for compliant vendors. |
| AI Capability Acquisition | Machine learning modules for predictive resource allocation differentiate next-generation platform releases. |
| Vertical Consulting Partnership | Chicago and Boston advisors bundle platform access, displacing traditional VAR relationships. |
| Multi-Cloud Architecture Unification | Single-pane visibility across AWS GovCloud and Azure Government reduces fragmentation. |
| State Data Residency Compliance | California CCPA and Texas localization preferences force redundant deployment configurations. |
Research Methodology
Cross-validation between primary interviews with federal procurement officers and secondary validation through FedRAMP authorization databases anchors the qualitative findings. The analysis incorporated discussions with platform engineers, IT procurement officers at healthcare systems, integration specialists, and compliance documentation advisors. Secondary sources encompassed SEC filings from enterprise software providers, hyperscaler capex disclosures, NIST SP 800-53 control mappings, and federal contracting databases. Bottom-up segment sizing triangulated against top-down market boundary definitions.
Sensitivity analysis around FedRAMP authorization timelines and CMMC implementation assumptions stress-tested projection robustness across the modeling period. The forecast framework modeled deployment type, organization scale, industry vertical, solution category, and regional adoption pattern. CAGRs derived from historical trajectory analysis and regulatory inflection timing. Key inputs included federal infrastructure program budget allocations and enterprise digital transformation spend patterns.
Decision-makers should treat outputs as directional under assumptions of sustained federal modernization mandates and stable cloud infrastructure pricing; material deviation would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Portfolio Management and Asset Allocation
Portfolio Analytics Market
Portfolio Management and Asset Allocation
US Mutual Funds Market
Portfolio Management and Asset Allocation
Balanced Funds Market
Portfolio Management and Asset Allocation
Corporate Performance Management Market
Portfolio Management and Asset Allocation
Global Project Portfolio Management (PPM) Market
Portfolio Management and Asset Allocation
Energy Portfolio Management Market
Portfolio Management and Asset Allocation
Germany Mutual Funds Market
Portfolio Management and Asset Allocation
UK Mutual Funds Market
Portfolio Management and Asset Allocation
Portfolio Management Software Market