
 Energy Portfolio Management Market | 2026-2036
Energy Portfolio Management Market Size, Share, and Industry Trends Forecast 2026-2036
Energy Portfolio Management Market Foresight
ISO 50001 energy management certification is reorganizing vendor qualification criteria across enterprise procurement cycles. Siemens leverages its digital grid software heritage to anchor large utility deployments in European markets. IBM competes through cloud-native analytics architectures that extend across multi-site corporate energy estates. Honeywell sustains channel control via building automation integration that positions energy portfolio tools within broader facility management contracts.
Energy portfolio management denotes the systematic coordination of generation assets, consumption profiles, and contractual positions across electricity, natural gas, and carbon markets through software platforms that process interval-meter data in 15-minute or hourly resolution for dispatch optimization and financial settlement. Cloud computing deployments now dominate new implementations as utilities abandon on-premise infrastructure, while machine learning modules represent the fastest-expanding technology layer as operators deploy predictive algorithms for price forecasting and renewable output estimation. Portfolio optimization services capture the deepest margin pools due to recurring advisory engagements tied to volatile power markets, whereas reporting solutions have matured into standardized SaaS offerings with compressed pricing.
FERC Order 2222 in the United States enables distributed resource aggregation, compelling software vendors to reconfigure platforms for bidirectional market participation. The EU Green Deal and CSRD mandate granular emissions disclosure, reshaping compliance management modules into mandatory procurement criteria for corporate energy buyers. Stakeholders must monitor how evolving carbon border adjustment mechanisms redefine the data granularity required for cross-border energy contracting and portfolio valuation.
Market Dynamics
Grid operators are abandoning legacy dispatch systems as 15-minute settlement intervals and renewable intermittency expose spreadsheet-based coordination to financial losses exceeding millions per balancing event. This structural pressure is compressing procurement cycles for integrated portfolio platforms.
Growth Catalysts
- FERC Order 2222:Distributed energy resource aggregation mandates in the United States are forcing utilities to deploy bidirectional market participation software for behind-the-meter assets.
- EU Green Deal carbon accountability:Granular emissions disclosure requirements are converting compliance management modules from optional add-ons to mandatory procurement criteria for corporate energy buyers.
- German coal phase-out timeline:Grid balancing complexity in this market is accelerating replacement of manual scheduling tools with automated dispatch optimization systems.
Market Restraints
- Cloud infrastructure concentration:Dominance of hyperscale providers creates single-point-of-failure risk for real-time portfolio operations dependent on continuous data pipeline availability.
- Cybersecurity certification costs:IEC 62443 compliance for critical energy infrastructure imposes six-figure validation expenses that exclude mid-market utilities from advanced platform tiers.
- Legacy SCADA integration friction:Proprietary protocols in existing control systems extend implementation timelines and inflate professional services margins for deployment vendors.
Strategic Opportunities
- Carbon border adjustment mechanisms:Emerging cross-border emissions accounting rules are creating demand for contract-level carbon tracing functionality in procurement modules.
- Machine learning price forecasting:Convergence of historical market data with weather satellite feeds enables predictive algorithms that reduce imbalance penalties for renewable-heavy portfolios.
- Industrial microgrids:Underpenetrated manufacturing estates in Spain and Italy present white space for on-site generation optimization bundled with grid services aggregation.
Industry Challenges
- Interconnection queue data scarcity:Opaque transmission upgrade timelines distort asset valuation models and force manual override of automated capacity expansion recommendations.
- ISO 50001 auditor shortage:Limited certification body capacity extends enterprise compliance timelines and delays software procurement approvals tied to management system mandates.
- Settlement system fragmentation:Non-standardized data formats across European power exchanges impose costly mapping layers that erode SaaS margin structures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Energy Portfolio Management Market |
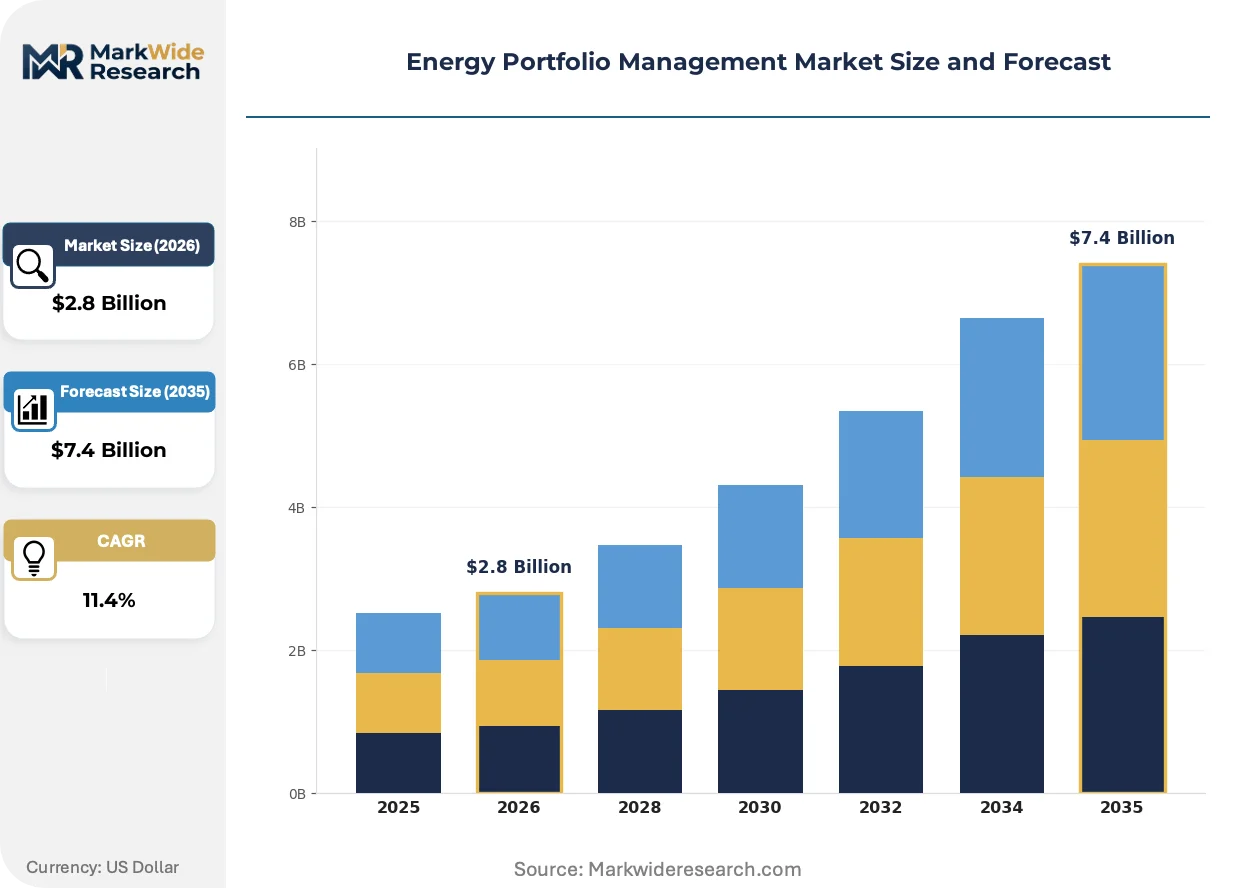
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $7.4 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Portfolio Optimization, Risk Management, Compliance Management, Reporting Solutions Technology: Big Data Analytics, Cloud Computing, Machine Learning, Internet of Things User Type: Utilities, Independent Power Producers, Asset Managers, Corporate Energy Buyers Application: Renewable Energy Management, Energy Trading, Demand Response, Carbon Management |
| Companies Covered | IBM, Honeywell, EnergyCAP, ABB, Johnson Controls, Schneider Electric, SAP, EnergyHub, Siemens, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Energy Portfolio Management Market Shifts & Advancements
Platform architectures are pivoting from retrospective reporting toward predictive orchestration as renewable penetration exposes the latency gaps in traditional dispatch workflows. This evolution favors vendors with native machine learning pipelines over legacy database-centric incumbents.
Digital twin modeling is supplanting static asset registers in utility control rooms. Transmission operators in Germany and Denmark are deploying physics-based simulations that mirror generator behavior at 15-minute resolution. This capability is compressing the competitive moat of established energy management vendors lacking real-time simulation engines.
The EU CSRD mandates scope 3 emissions disclosure for listed entities, forcing software vendors to reconfigure procurement modules for supplier-level carbon tracing. Corporate energy buyers in France and the Netherlands are prioritizing platforms with embedded emissions factor databases. This regulatory pressure is marginalizing point solutions lacking integrated sustainability reporting.
Subscription-based platform access is displacing perpetual license structures in utility procurement. Municipal cooperatives in Texas and community choice aggregators in California favor operational expenditure models that align software costs with realized balancing savings. This shift compresses upfront revenue recognition but extends customer lifetime value for vendors demonstrating measurable dispatch cost reductions.
Energy Portfolio Management Market Segmentation
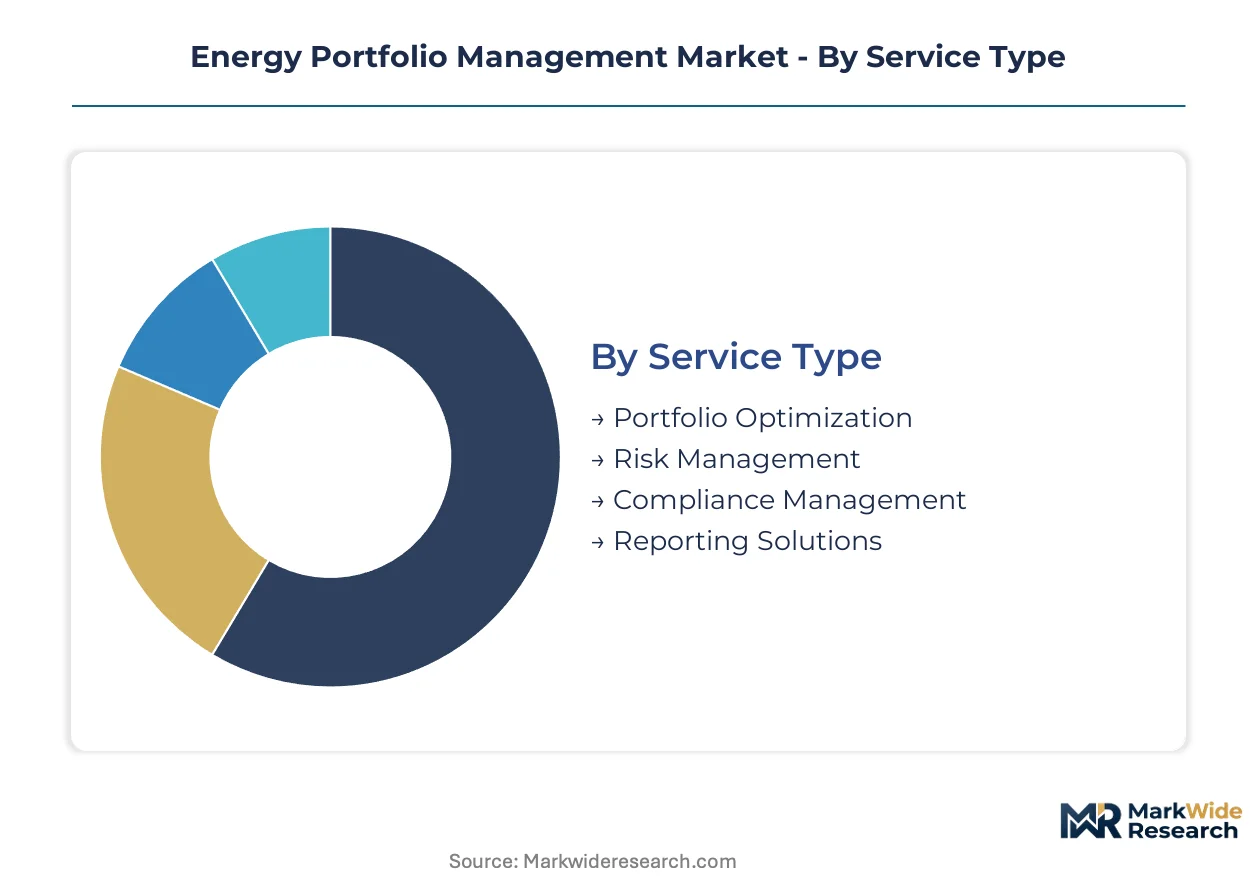
Energy portfolio management platforms serve heterogeneous operational requirements across generation dispatch, financial risk, and regulatory compliance. Segment boundaries reflect divergent technology maturity, procurement authority, and data granularity needs.
Service Type:
Portfolio Optimization dominates European utility procurement cycles, while Risk Management concentrates in North American independent power producer budgets. Compliance Management spreads across both regions as CSRD and FERC disclosure rules tighten.
- Portfolio Optimization:Advanced algorithms balance generation assets against contractual positions and market price signals in 15-minute dispatch intervals. German transmission operators and Danish grid companies deploy these modules to manage coal phase-out volatility and offshore wind intermittency.
- Risk Management:Hedging analytics quantify exposure across power, gas, and carbon price curves using Monte Carlo simulations. Texas municipal cooperatives and California community choice aggregators prioritize these tools following winter storm Uri and summer heat wave financial losses.
- Compliance Management:Automated emissions tracking and audit trail generation for EU Green Deal and F-Gas Regulation mandates.
- Reporting Solutions:Standardized SaaS dashboards for stakeholder disclosure and management reporting.
Portfolio Optimization commands the established base. The steepest expansion runs through Compliance Management.
Technology:
Cloud Computing deployments now outpace on-premise infrastructure across all customer tiers. Machine Learning represents the fastest-climbing investment layer as operators pursue predictive renewable output and price forecasting.
- Cloud Computing:Hyperscale infrastructure delivers elastic compute for interval-meter data processing and real-time dispatch optimization. French and Dutch corporate energy buyers favor multi-tenant architectures that eliminate capital expenditure approval cycles.
- Machine Learning:Neural networks trained on historical market data and satellite weather feeds predict imbalance penalties and optimize bid strategies. German utilities deploy these modules to reduce renewable curtailment costs and intraday trading losses.
- Big Data Analytics:Distributed processing of terabyte-scale meter and market datasets for pattern detection and anomaly identification.
- Internet of Things:Sensor networks for behind-the-meter asset monitoring and distributed resource aggregation.
Cloud Computing anchors current procurement volumes. Machine Learning is gaining share fastest as algorithmic performance differentiates vendor offerings.
User Type:
Utilities drive the deepest platform customization requirements, while Corporate Energy Buyers concentrate demand for integrated sustainability reporting. Independent Power Producers prioritize trading and optimization modules over compliance features.
- Utilities:Vertically integrated operators require end-to-end coordination of generation, transmission, and retail operations. Spain and Italy distribution system operators are expanding procurement for grid balancing platforms as renewable penetration climbs.
- Corporate Energy Buyers:Listed entities in France and the Netherlands procure bundled energy and carbon management suites to satisfy CSRD scope 3 disclosure mandates.
- Independent Power Producers:Merchant generators focused on market optimization and PPA structuring.
- Asset Managers:Financial investors managing diversified generation portfolios across multiple jurisdictions.
Utilities retain the largest installed base. Corporate Energy Buyers are expanding most quickly as regulatory disclosure obligations multiply.
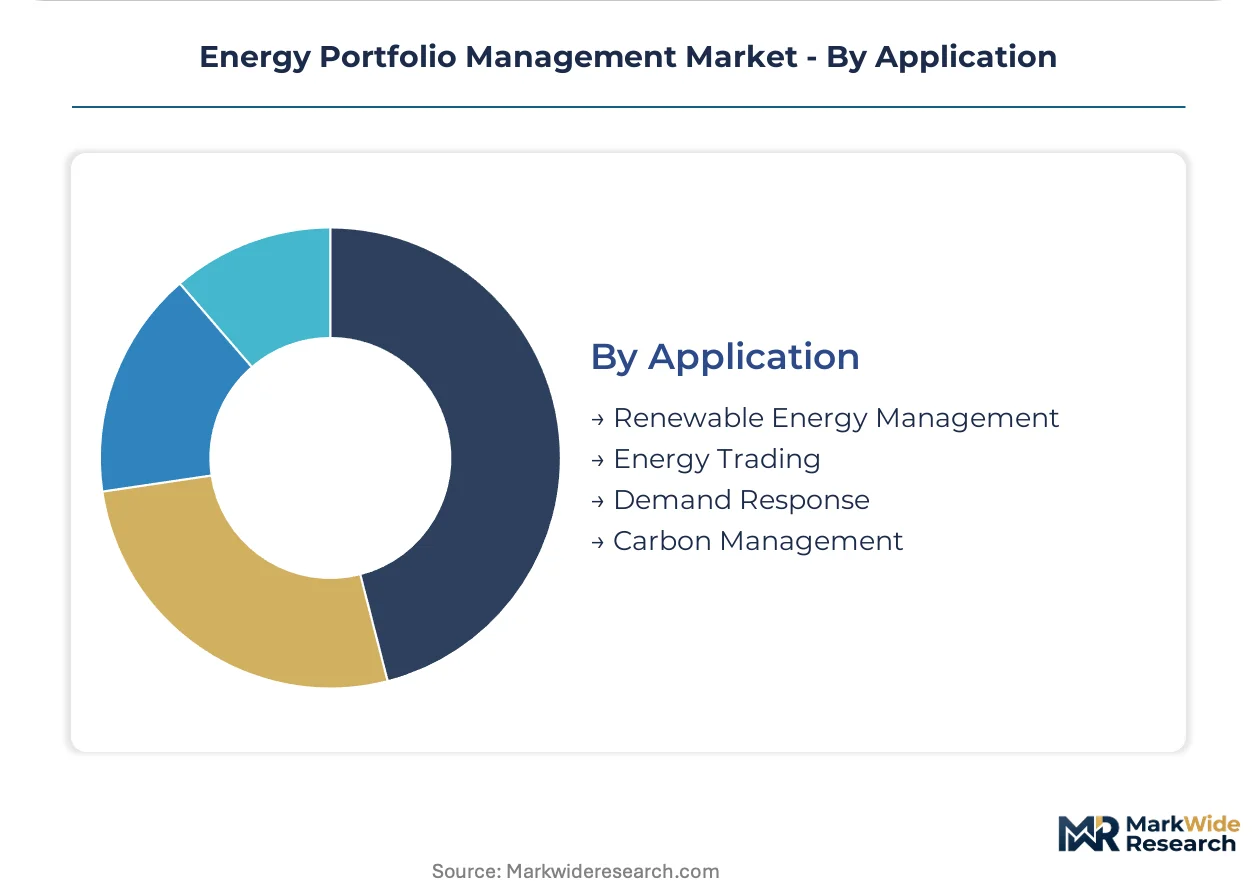
Application:
Renewable Energy Management absorbs the majority of new implementation resources as wind and solar penetration destabilizes traditional dispatch workflows. Carbon Management is emerging as a mandatory procurement category following EU emissions disclosure rules.
- Renewable Energy Management:Forecasting, curtailment optimization, and grid integration for variable generation assets. German and Danish operators deploy these capabilities at 15-minute resolution to manage offshore wind ramp events.
- Carbon Management:Contract-level emissions tracing and offset procurement for scope 1, 2, and 3 disclosure. French corporate buyers prioritize platforms with embedded emissions factor databases to satisfy CSRD mandates.
- Energy Trading:Bid strategy optimization and position management across intraday, day-ahead, and forward markets.
- Demand Response:Aggregation and dispatch of behind-the-meter flexible load for grid services revenue.
Renewable Energy Management holds the dominant share. Carbon Management is climbing the fastest as border adjustment mechanisms and disclosure rules tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU Green Deal and F-Gas Regulation are accelerating software procurement across Europe, while FERC Order 2222 is reshaping utility technology stacks in the United States. Grid balancing complexity and renewable intermittency are compressing implementation timelines in markets with aggressive coal phase-out schedules.
Germany
Transmission operators deploy 15-minute dispatch optimization to manage offshore wind ramp events and coal exit volatility. The national coal phase-out timeline forces grid operators to abandon manual scheduling tools. The North Sea wind corridor and industrial Rhineland cluster anchor platform deployments for balancing market participation.
United States
FERC Order 2222 mandates bidirectional market participation software for distributed resource aggregation. Texas municipal cooperatives and California community choice aggregators prioritize risk management modules following extreme weather financial losses. The ERCOT and CAISO market footprints concentrate procurement for imbalance penalty reduction.
France
Corporate energy buyers procure bundled energy and carbon management suites to satisfy CSRD scope 3 disclosure mandates. The EU CSRD emissions disclosure rules convert compliance modules from optional add-ons to mandatory procurement criteria. The Île-de-France corporate headquarters cluster drives SaaS subscription growth for multi-site energy estates.
Denmark
Grid companies deploy physics-based digital twin simulations at 15-minute resolution to mirror generator behavior. Offshore wind penetration destabilizes traditional dispatch workflows and compresses procurement cycles for predictive orchestration platforms. The Kattegat and Baltic Sea wind zones anchor real-time simulation engine deployments.
Netherlands
Corporate buyers favor multi-tenant cloud architectures that eliminate capital expenditure approval cycles. The EU Green Deal carbon accountability rules force upgrades from spreadsheet-based tracking to automated compliance systems. The Rotterdam industrial port complex and Amsterdam corporate headquarters drive integrated sustainability reporting demand.
Energy Portfolio Management Market Competitive Landscape
Player mix skews toward diversified industrial conglomerates with digital grid heritage, cloud-native software vendors, and building automation integrators. Siemens leverages its digital grid software heritage to anchor large utility deployments. IBM competes through cloud-native analytics architectures. Honeywell sustains channel control via building automation integration. Dominant competitive moves include strategic partnerships for SCADA integration and geographic expansion into underpenetrated Southern European markets.
Within the diversified industrial tier, Siemens and ABB represent archetypes with deep utility relationships and control system heritage. Among cloud-native specialists, IBM occupies a position exemplifying analytics-first architectures for multi-site corporate estates. Honeywell sits within the building automation integration archetype, positioning energy portfolio tools within broader facility management contracts. Johnson Controls and Schneider Electric exemplify the converged energy-facilities management positioning. EnergyHub and EnergyCAP anchor the pure-play SaaS segment focused on distributed resource aggregation and municipal cooperative procurement.
| Leading Market Players |
|---|
| IBM |
| Honeywell |
| EnergyCAP |
| ABB |
| Johnson Controls |
| Schneider Electric |
| SAP |
| EnergyHub |
| Siemens |
| Others |
Supply & Pricing Matrix
Hyperscale cloud infrastructure concentration in Germany and the Netherlands generates procurement leverage for enterprise energy buyers while compressing SaaS margins for software vendors serving municipal cooperatives. This scale dynamic simultaneously elevates price floors for IEC 62443-certified platforms and erodes differentiation for non-compliant entrants.
Pricing Analysis
Certification level creates the primary spread between premium and standard tiers, with IEC 62443-validated platforms commanding substantial premiums over uncertified alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects deployment complexity, with cloud-native SaaS subscriptions displacing perpetual licenses. Cost compression in the mid-market tier is intensifying because municipal cooperatives demand outcome-based pricing tied to realized balancing savings. Corporate energy buyers in France and the Netherlands exhibit lowest price sensitivity due to CSRD compliance deadlines, while Texas municipal cooperatives drive hardest bargain terms.
Supply Chain Analysis
Implementation timelines stretching eighteen to thirty-six months reflect the inventory of specialized integration engineers required for legacy SCADA protocol mapping. Software development concentrates in Germany, the United States, and France, with hyperscale cloud infrastructure drawing from Dublin, Frankfurt, and Amsterdam data center clusters. Critical dependencies include satellite weather data feeds, interval-meter hardware, and emissions factor databases. Single-source vulnerability runs through concentrated hyperscale cloud providers. Distribution runs through direct enterprise sales teams and systems integrator partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating as French and Dutch corporate energy buyers consolidate procurement decisions under centralized sustainability officers, fragmenting vendor access points. This shift elevates platform stickiness for incumbents while raising customer acquisition costs for challengers.
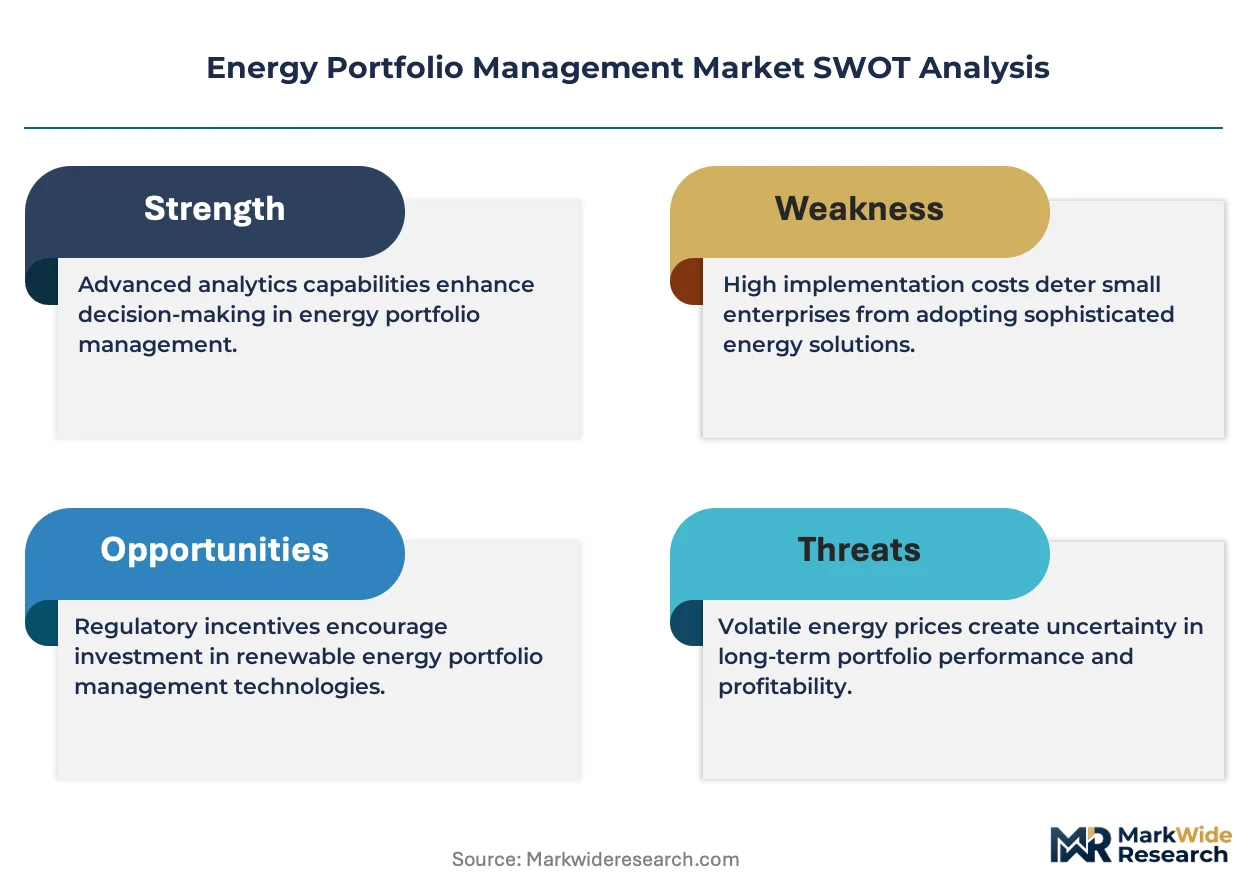
For Market Incumbents: Shield installed base relationships by embedding machine learning modules that increase switching costs through predictive algorithm training on proprietary customer datasets. Prioritize backward integration into satellite weather data feeds to secure raw material advantage for renewable forecasting. Defend against cloud-native challengers by accelerating ISO 50001 certification partnerships that extend compliance timelines and delay procurement approvals for unqualified vendors.
For New Entrants and Emerging Players: Mid-market municipal cooperatives in Spain and Italy represent the most penetrable white-space segment, where incumbent platforms over-serve with enterprise-grade complexity. Industrial microgrid optimization for manufacturing estates offers second entry vector, bundling on-site generation control with grid services aggregation. Lead generation through channel partnerships with building automation integrators bypasses direct competition against established utility sales forces.
For Investors and Strategic Acquirers: Cloud-native SaaS specialists with embedded carbon accounting modules present the highest-value acquisition archetype, as CSRD disclosure mandates convert compliance features from optional to mandatory procurement criteria. Long-term viability hinges on regulatory enforcement continuity across the EU Green Deal implementation window. Monitor carbon border adjustment mechanism finalization as inflection signal for contract-level tracing functionality demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Machine Learning Module Integration | Predictive algorithms trained on German offshore wind data reduce imbalance penalties for renewable-heavy portfolios. |
| IEC 62443 Certification Investment | Six-figure validation expenses create defensive moats excluding mid-market challengers from critical infrastructure procurement. |
| SCADA Protocol Partnership | Integration agreements with ABB and Siemens compress implementation timelines and capture professional services margin. |
| Carbon Accounting Database Licensing | Embedded emissions factor libraries satisfy French CSRD scope 3 mandates and differentiate against point solutions. |
| Southern European Geographic Expansion | Underpenetrated Spanish and Italian industrial microgrids offer white-space for bundled generation optimization platforms. |
Research Methodology
Desk research of FERC filings, EIA project databases, EU Green Deal implementation guidance, and IEA renewable integration reports preceded structured interviews with utility planning officers, IPP project developers, grid operators, and EPC contractors. Primary fieldwork across Germany, the United States, France, and Denmark validated secondary assumptions on procurement cycle compression and platform architecture preferences. Bottom-up triangulation of vendor revenue estimates against top-down market sizing anchored volume projections.
Variance decomposition across service type, technology layer, user archetype, and application domain shaped the analytical framework over the projection horizon. Modeled segmentation dimensions included deployment model, organization scale, regulatory framework complexity, and regional grid interconnection type. CAGRs were derived from logistic diffusion curves fitted to historical software procurement patterns, with inputs from renewable penetration trajectories and coal phase-out timelines.
Forecasts assume regulatory continuity in EU Green Deal implementation and FERC Order 2222 enforcement; material policy shifts would require re-modeling of distributed resource aggregation demand and carbon disclosure granularity requirements. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Portfolio Management and Asset Allocation
Balanced Funds Market
Portfolio Management and Asset Allocation
Portfolio Analytics Market
Portfolio Management and Asset Allocation
UK Mutual Funds Market
Portfolio Management and Asset Allocation
Portfolio Management Software Market
Portfolio Management and Asset Allocation
Global Project Portfolio Management (PPM) Market
Portfolio Management and Asset Allocation
United States Project Portfolio Management Market
Portfolio Management and Asset Allocation
Corporate Performance Management Market
Portfolio Management and Asset Allocation
Germany Mutual Funds Market
Portfolio Management and Asset Allocation
US Mutual Funds Market