
 UK Mutual Funds Market | 2026-2036
UK Mutual Funds Market Size, Share, and Industry Trends Forecast 2026-2036
UK Mutual Funds Market Insights
The gap between actively managed premium strategies and low-cost passive vehicles is restructuring how asset managers allocate resources across their product lines. Schroders leverages its multi-asset capabilities to sustain pricing power in specialist equity mandates. Baillie Gifford anchors its competitive edge through concentrated growth-oriented portfolios that differentiate from benchmark-hugging alternatives. Vanguard competes aggressively on cost, dominating the passive segment through scale-driven fee compression.
Mutual funds represent pooled investment vehicles that aggregate capital from multiple investors to purchase diversified portfolios of securities, operating under trust structures with daily net asset value calculations and regulated redemption terms. Their primary commercial purpose channels retail and institutional savings into liquid, professionally managed exposure across equities, fixed income, and multi-asset blends. Equity funds occupy the largest allocation share among UK investors, while passive management strategies capture the fastest expansion as fee sensitivity reshapes flows. Target date funds remain nascent but attract defined contribution pension schemes seeking glide-path automation.
The Financial Conduct Authority enforces the Consumer Duty framework, compelling fund distributors to demonstrate fair value and clear performance communication to retail clients. HMRC tax wrapper rules for ISAs and pensions shape product design and distribution channel economics across UK platforms. Stakeholders must monitor how the FCA's ongoing scrutiny of fund charges and greenwashing claims will recalibrate competitive positioning between active and passive providers.
Market Dynamics
The Financial Conduct Authority's Consumer Duty framework is compressing margins across fund distribution while simultaneously accelerating the shift toward passive vehicles and automated investment platforms.
Growth Catalysts
- Consumer Duty Implementation:The FCA's disclosure mandates are forcing distributors to rationalize fee structures, which paradoxically steers retail flows toward transparent, low-cost index products.
- Defined Contribution Pension Auto-Enrolment:Workplace pension schemes are channeling sustained monthly inflows into target-date and balanced fund strategies, creating sticky asset bases.
- Platform Technology:Direct-to-consumer investment apps are collapsing distribution layers, enabling retail investors to access institutional-grade fund menus without intermediary markups.
Market Restraints
- Active Management Fee Compression:The spread between passive and active expense ratios has narrowed to unsustainable levels for boutique equity specialists dependent on performance fees.
- Concentrated Platform Dependency:Hargreaves Lansdown and Interactive Investor collectively intermediate access for over half of UK direct retail fund assets, creating gatekeeper risk.
- Greenwashing Liability Exposure:The FCA's anti-greenwashing rule is forcing fund groups to retreat from loosely defined ESG classifications, constraining product launch velocity.
Strategic Opportunities
- Scotland's Asset Management Cluster:Edinburgh and Glasgow house concentrated compliance and fund administration talent pools at 15-20% cost discounts to London.
- Model Portfolio Services:Discretionary wealth managers are outsourcing fund selection to white-label multi-asset solutions, opening B2B distribution channels for specialist builders.
- Long-Term Asset Fund Structure:The FCA's LTAF authorization is unlocking illiquid private market exposure within tax-advantaged wrappers, bridging the gap between mutual fund liquidity and alternative return profiles.
Industry Challenges
- Smarter Consumer Duty Compliance:Fund boards must now document value assessments across product lifecycles, requiring investment in data infrastructure and governance personnel.
- Legacy System Integration:Established asset managers face friction unifying proprietary order management systems with third-party platform APIs for real-time NAV reporting.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UK Mutual Funds Market |
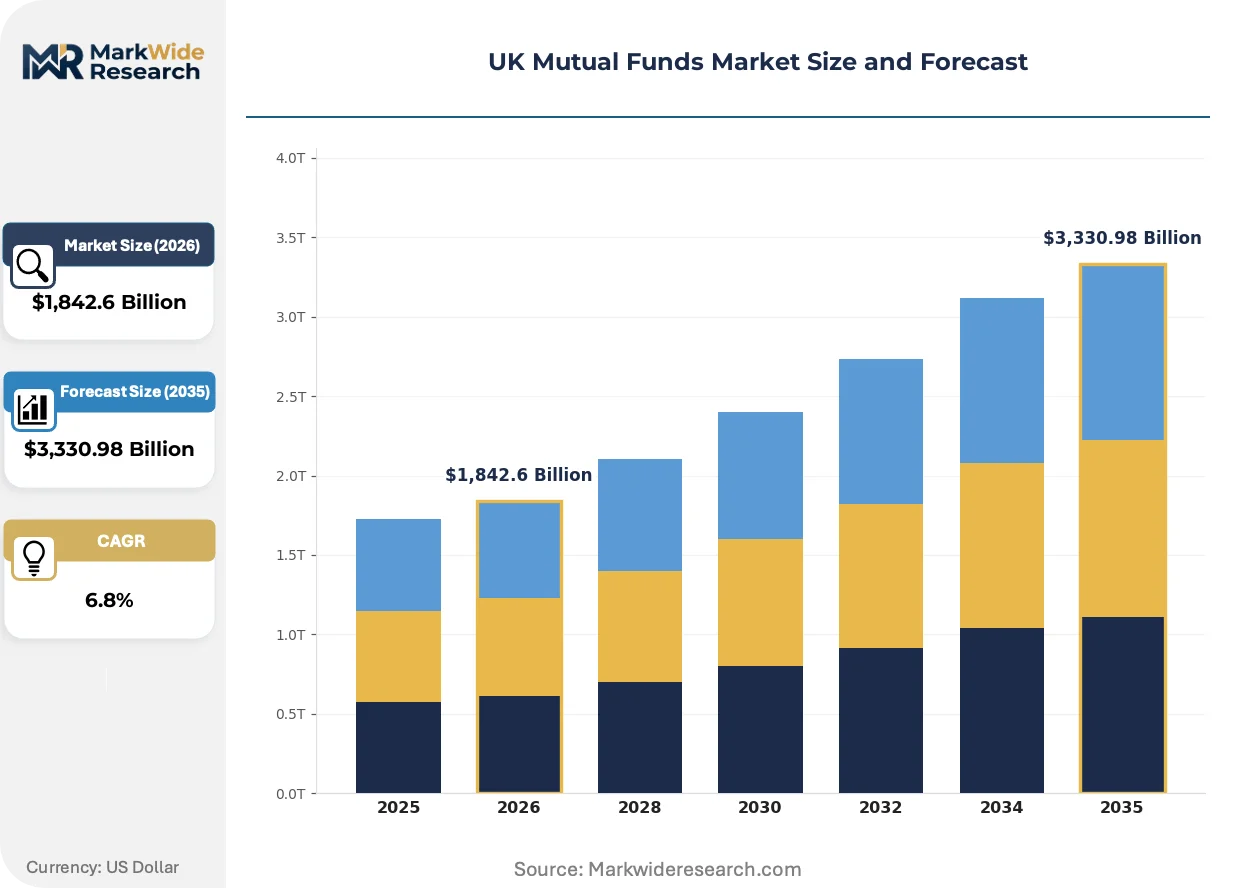
| Market Size in 2026 | $1,842.6 Billion |
| Market Size in 2035 | $3,330.98 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Fund Type: Equity Funds, Bond Funds, Balanced Funds, Money Market Funds Investor Type: Retail Investors, Institutional Investors, High-Net-Worth Individuals, Pension Funds Investment Strategy: Active Management, Passive Management, Index Funds, Target Date Funds Distribution Channel: Direct Sales, Financial Advisors, Online Platforms, Banks |
| Companies Covered | Schroders, Baillie Gifford, Fidelity International, M&G Investments, Invesco Perpetual, BNY Mellon Investment Management, Artemis Fund Managers, J.P. Morgan Asset Management, Vanguard, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UK Mutual Funds Market Trends and Innovations
Technology-driven disintermediation is collapsing traditional distribution economics while regulatory pressure on fee transparency accelerates product-line rationalization across active and passive strategies.
Artificial intelligence-powered portfolio analytics is converging with automated rebalancing engines to enable dynamic tax-loss harvesting at scale. WealthTech platforms serving mass-affluent investors are embedding these tools as standard features. This convergence is compressing the addressable market for traditional discretionary portfolio management services.
The FCA's Consumer Duty framework now mandates annual value assessments and explicit performance communication standards. Asset managers must demonstrate fair value across product lines or face distribution restrictions. Specialist equity houses are responding by consolidating overlapping fund ranges and sharpening investment process differentiation.
Retail investors are migrating toward fractional share ownership and direct indexing overlays, bypassing traditional fund wrappers entirely. Platform providers are capturing this behavior shift by offering separately managed account infrastructure at mutual-fund price points. This rotation is most visible among investors under 40 accessing products through mobile-first interfaces.
UK Mutual Funds Market Segmentation
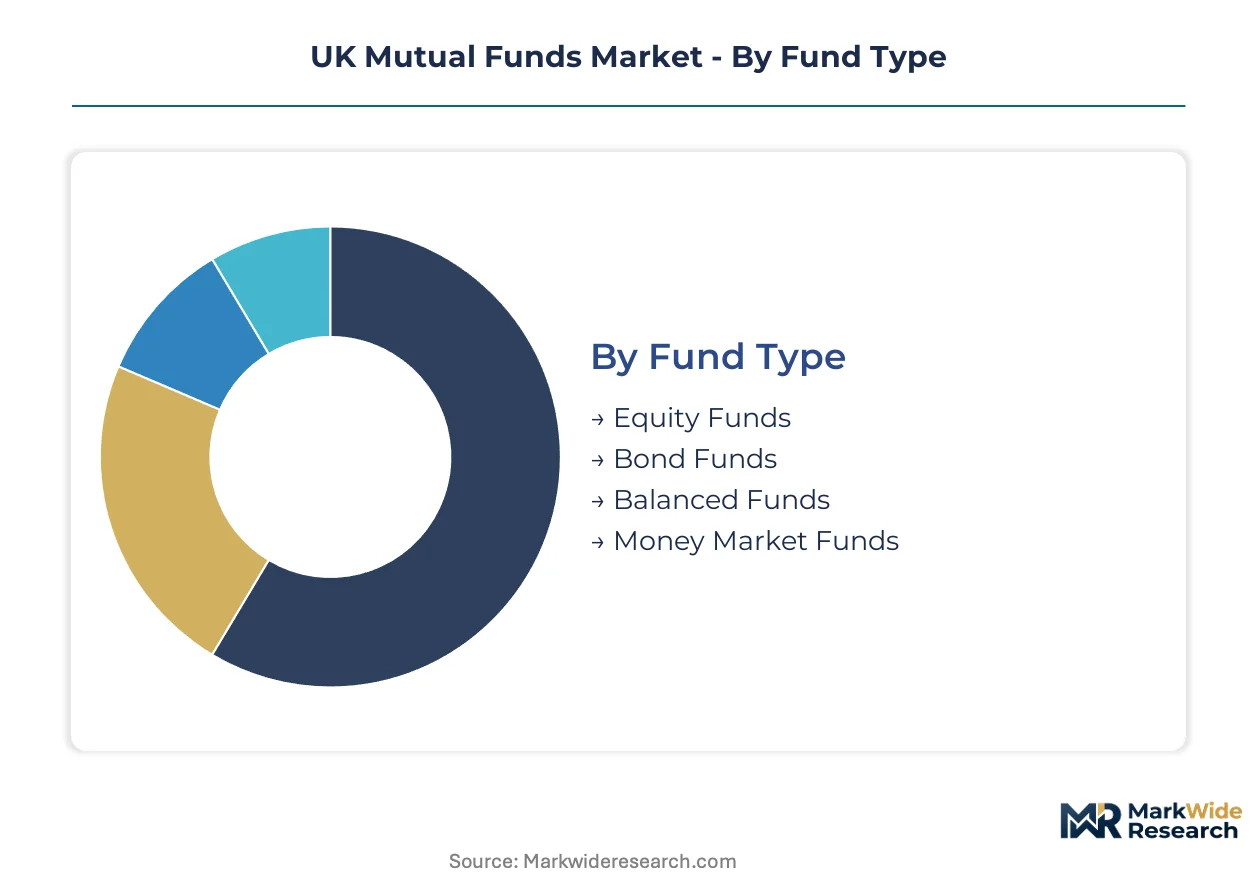
Segmentation in the UK mutual funds market determines how asset managers configure product lines, pricing tiers, and distribution partnerships. Each dimension—fund type, investor profile, strategy orientation, and channel access—creates distinct margin structures and regulatory obligations that shape competitive positioning.
Fund Type:
Asset allocation preferences among UK savers concentrate heavily in equity exposure, though fixed-income and hybrid vehicles retain defensive utility in volatile rate environments.
- Equity Funds:These vehicles channel capital into diversified share portfolios across UK, European, and global markets. Defined contribution pension schemes in London and the Southeast direct sustained monthly flows into UK equity income and global growth mandates, with the FCA's Consumer Duty rules now demanding clearer risk disclosures on volatility expectations.
- Bond Funds:Fixed-income vehicles invest across government gilts, investment-grade corporate debt, and strategic bond allocations. Liability-driven investment strategies at UK corporate pension funds are stabilizing demand for long-duration gilt funds despite yield curve uncertainty.
- Balanced Funds:Multi-asset vehicles blending equity and fixed-income exposure through static or dynamic allocation frameworks. Platform distributors favor these for risk-rated model portfolio construction.
- Money Market Funds:Short-term liquidity vehicles holding treasury bills, commercial paper, and certificates of deposit. Corporate treasurers utilize these for cash management during rate volatility.
Equity funds lead on scale; balanced funds lead on momentum as platform-driven risk profiling expands their intermediary adoption.
Investor Type:
Fee sensitivity and advice requirements diverge sharply across client segments, forcing distributors to maintain parallel service tiers.
- Retail Investors:Individual savers accessing funds through ISAs, SIPPs, and general investment accounts. Direct-to-consumer platforms in the UK are collapsing advisory layers, enabling self-directed investors to construct institutional-grade portfolios without intermediary markups.
- Institutional Investors:Corporate treasurers, insurance companies, and charity endowments deploying large-ticket mandates. These buyers negotiate bespoke fee schedules and demand granular reporting on environmental, social, and governance integration.
- High-Net-Worth Individuals:Affluent investors with portfolios typically exceeding one million pounds. Discretionary wealth managers serving this segment are outsourcing fund selection to white-label multi-asset solutions.
- Pension Funds:Defined benefit and defined contribution schemes managing retirement liabilities. Auto-enrolment legislation continues channeling mandatory employee contributions into default fund strategies.
Pension funds lead on scale; retail investors lead on momentum as platform technology democratizes access.
Investment Strategy:
Management style selection increasingly determines cost structure and performance benchmarking methodology.
- Active Management:Discretionary portfolio construction seeking alpha through security selection and tactical allocation. Specialist UK equity houses are consolidating overlapping fund ranges to sharpen investment process differentiation under FCA value assessment requirements.
- Passive Management:Rules-based replication of market indices at minimized cost. Scale-driven fee compression has narrowed expense ratios to single basis points for mainstream UK and global equity trackers.
- Index Funds:Mutual fund structures tracking specific benchmarks with daily NAV calculation. Platform technology enables fractional share ownership that bypasses traditional fund wrappers entirely.
- Target Date Funds:Glide-path vehicles adjusting equity-fixed income mix as retirement approaches. Defined contribution schemes are adopting these for default investment strategies.
Active management leads on scale; passive management leads on momentum as fee transparency accelerates product-line rationalization.
Distribution Channel:
Channel economics determine whether asset managers capture full management fees or surrender portions to intermediaries.
- Direct Sales:Asset manager relationships with institutional buyers bypassing platform layers. Large UK pension consultants intermediate these flows through fiduciary management mandates.
- Financial Advisors:Independent and restricted advisers providing personalized recommendations. The FCA's Consumer Duty framework now mandates annual value assessments that force advisers to document fair value across recommended fund ranges.
- Online Platforms:Direct-to-consumer investment apps offering fund supermarkets with comparison tools. Hargreaves Lansdown and Interactive Investor collectively intermediate access for over half of UK direct retail fund assets.
- Banks:High-street and private banking channels distributing proprietary and third-party funds. Legacy system integration challenges persist as established banks unify proprietary order management with third-party platform APIs.
Online platforms lead on scale; financial advisors lead on momentum as regulatory reform elevates advice quality.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Asset management talent concentrates disproportionately in London's Square Mile and Edinburgh's financial district, with compliance specialists and fund administrators clustering around these hubs at significant cost premiums to secondary locations.
London and the Southeast
Defined contribution pension schemes in the capital direct sustained monthly flows into UK equity income and global growth mandates. The Financial Conduct Authority's Consumer Duty rules demand clearer risk disclosures on volatility expectations from distributors headquartered here. The asset management cluster in the City of London and Canary Wharf channels capital into equity and balanced fund strategies for institutional and retail clients nationwide.
Scotland
Edinburgh and Glasgow house concentrated compliance and fund administration talent pools at fifteen to twenty percent cost discounts to London. HMRC tax wrapper rules for ISAs and pensions shape product design from Scottish-based fund groups serving UK-wide distribution. Baillie Gifford anchors the Edinburgh cluster with concentrated growth-oriented portfolios that differentiate from benchmark-hugging alternatives.
Midlands
Corporate treasurers in Birmingham and Nottingham utilize money market funds for cash management during rate volatility. The FCA's ongoing scrutiny of fund charges recalibrates competitive positioning for Midlands-based platforms serving mass-affluent investors. Discretionary wealth managers in the region are outsourcing fund selection to white-label multi-asset solutions.
North England
Retail investors through Manchester and Leeds-based platforms are expanding their participation in passively managed index funds. Auto-enrolment legislation continues channeling mandatory employee contributions into default fund strategies across workplace pension schemes in the region. Platform technology in these cities is collapsing distribution layers, enabling self-directed investors to construct institutional-grade portfolios.
Wales and Northern Ireland
Smaller fund administration operations in Cardiff and Belfast serve as back-office locations for London and Edinburgh-based asset managers. The FCA's anti-greenwashing rule is forcing fund groups to retreat from loosely defined ESG classifications, affecting product launch velocity from these jurisdictions. Compliance personnel in these locations support value assessment documentation across product lifecycles.
UK Mutual Funds Market Competitive Landscape
Top-tier vendors anchor the active-specialist segment, while scale-driven passive providers compress fee structures across the retail mass market. The UK mutual funds market exhibits tiered concentration, with a handful of multi-asset specialists commanding institutional mandates and platform distribution partnerships. Strategic archetypes separate into concentrated growth equity houses, diversified multi-asset managers, and cost-minimized index replication engines. Competitive moves center on product-line consolidation to satisfy FCA value assessments and technology partnerships to embed automated rebalancing capabilities.
Within the active-specialist tier, Schroders and Baillie Gifford occupy positions exemplifying contrasting approaches to sustained pricing power. Schroders leverages multi-asset capabilities across institutional and retail channels, while Baillie Gifford anchors its competitive edge through concentrated portfolio construction. Vanguard represents the scale-driven passive archetype, competing aggressively on cost through fee compression enabled by operational scale. These three firms illustrate how management style selection increasingly determines cost structure and performance benchmarking methodology across the UK market.
| Leading Market Players |
|---|
| Schroders |
| Baillie Gifford |
| Fidelity International |
| M&G Investments |
| Invesco Perpetual |
| BNY Mellon Investment Management |
| Artemis Fund Managers |
| J.P. Morgan Asset Management |
| Vanguard |
| Others |
Pricing and Supply Chain Analysis
Platform-driven direct indexing technology is collapsing traditional fund wrapper economics while simultaneously compressing distribution margins and concentrating supply-side power among scale infrastructure providers. This convergence redraws how asset managers calibrate fee structures against custody, administration, and compliance costs.
Pricing Analysis
The bundled-versus-unbundled service split now dominates UK mutual fund economics, with platform technology enabling investors to strip out advisory layers and access institutional-grade vehicles at retail price points. Price differentiation hinges on active management complexity versus passive replication efficiency, with specialist equity houses commanding premium tiers while index trackers compete on single-digit basis points. Pricing pressure intensifies downward as the FCA's Consumer Duty mandates force documented value assessments across product lifecycles. Retail investors accessing funds through direct-to-consumer platforms exhibit highest price sensitivity, whereas institutional pension consultants negotiate bespoke fee schedules with lowest elasticity.
Supply Chain Analysis
Domestic-content mandates under HMRC tax wrapper rules for ISAs and SIPPs are reshaping sourcing decisions, compelling fund administrators to maintain UK-domiciled custody and compliance infrastructure. Supply concentration centers on London's Square Mile for portfolio management talent, Edinburgh for fund administration at cost discounts, and Dublin for cross-border UCITS structuring. Raw material dependencies encompass equity research from broker-dealers, index licensing from benchmark providers, and custody services from global banks. Single-source vulnerability runs through concentrated platform gatekeepers Hargreaves Lansdown and Interactive Investor, which intermediate access for over half of UK direct retail fund assets. Distribution runs through vertically integrated platform ecosystems that capture investor relationships and data flows.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
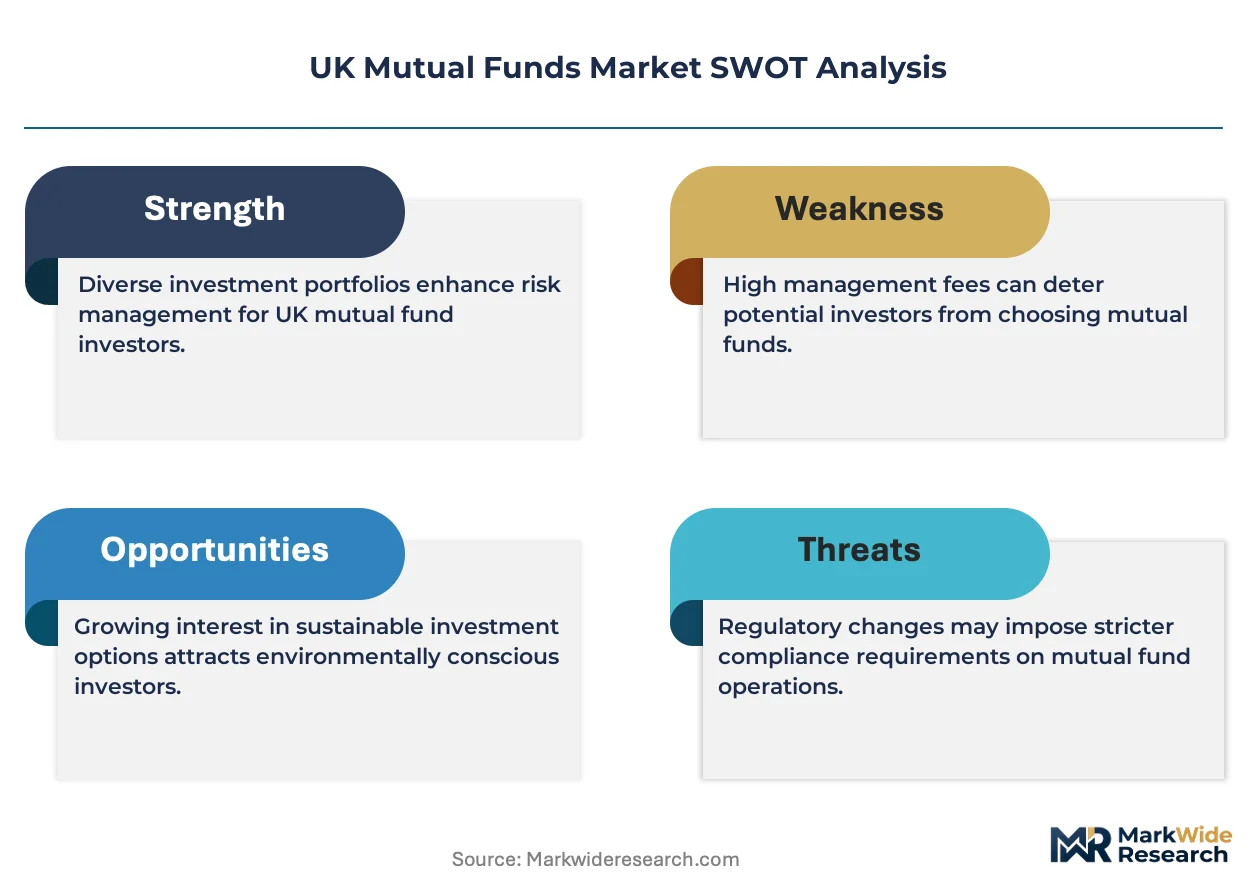
UK mutual funds present a margin-expansion narrative anchored in operational scale and automated infrastructure substitution for legacy distribution layers. Fee compression at the product level is offset by platform technology reducing intermediary capture.
For Market Incumbents: Cement pricing power through multi-asset capability consolidation and proprietary index licensing that differentiates from commodity passive offerings. Threats from fractional share ownership and direct indexing demand defensive investment in separately managed account infrastructure. Channel control through white-label model portfolio services represents the priority lever for retaining intermediary relationships.
For New Entrants and Emerging Players: Enter via Scotland's compliance and administration talent pools at fifteen to twenty percent cost discounts to London, targeting the nascent Long-Term Asset Fund structure for illiquid private market exposure. The most penetrable white-space sits in automated tax-loss harvesting tools for mass-affluent investors. A go-to-market angle through WealthTech platform partnerships bypasses traditional distribution gatekeepers.
For Investors and Strategic Acquirers: Valuations sit cheapest among boutique equity specialists facing unsustainable active-passive fee spreads. Long-term viability over a five-to-ten year window favors scale-driven passive providers and multi-asset consolidators over concentrated growth houses dependent on performance fees. The acquisition target archetype comprises Scotland-based fund administrators with compliance infrastructure and London platform technology assets. The signal to watch is FCA enforcement action on greenwashing claims that accelerates product-line rationalization.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Technology Integration | Embedding automated rebalancing engines collapses distribution layers and captures direct retail relationships. |
| Multi-Asset Capability Consolidation | Schroders leverages diversified mandates to sustain pricing power under FCA value assessment requirements. |
| Scotland Cost Arbitrage Expansion | Edinburgh and Glasgow compliance talent pools enable fifteen to twenty percent operational cost reductions. |
| Long-Term Asset Fund Authorization | FCA's LTAF structure unlocks illiquid private market exposure within tax-advantaged ISA and pension wrappers. |
| Direct Indexing Infrastructure Buildout | Separately managed account platforms capture investor migration away from traditional fund wrappers entirely. |
Research Methodology
Bottom-up pension scheme and retail platform modeling reconciled against top-down asset flow tracking forms the analytical core of this study. Primary interviews with fund board directors, platform technology officers, compliance consultants, and discretionary wealth managers combined with secondary validation from FCA regulatory filings, HMRC tax wrapper guidance, platform AUM disclosures, and industry association statistics. Triangulation across stakeholder perspectives and documentary sources ensures coverage of both disclosed metrics and operational realities.
Historical trendline analysis of net flows by fund category, management style, and distribution channel established baseline growth patterns across the projection horizon. Segmentation dimensions modeled encompass fund type, investor profile, investment strategy orientation, and channel access, with additional granularity on platform technology adoption rates. CAGRs were derived through regression analysis of flow trajectories adjusted for regulatory intervention effects. Forecast inputs include auto-enrolment contribution schedules, platform market share shifts, and FCA enforcement intensity indicators.
Inputs from FCA regulatory consultations and platform operator disclosures were available through the study window; gaps in real-time fund-level profitability data introduce uncertainty bands around margin compression estimates. Forecasts reflect assumptions on Consumer Duty compliance costs and technology substitution rates. Regulatory enforcement intensity, macroeconomic rate volatility, and platform consolidation outcomes represent specific risk factors that could revise projections. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Portfolio Management and Asset Allocation
United States Project Portfolio Management Market
Portfolio Management and Asset Allocation
Balanced Funds Market
Portfolio Management and Asset Allocation
Corporate Performance Management Market
Portfolio Management and Asset Allocation
Germany Mutual Funds Market
Portfolio Management and Asset Allocation
Portfolio Management Software Market
Portfolio Management and Asset Allocation
US Mutual Funds Market
Portfolio Management and Asset Allocation
Global Project Portfolio Management (PPM) Market
Portfolio Management and Asset Allocation
Portfolio Analytics Market
Portfolio Management and Asset Allocation
Energy Portfolio Management Market