
 Balanced Funds Market | 2026-2036
Balanced Funds Market Size, Share, and Industry Trends Forecast 2026-2036
Balanced Funds Market Outlook
Subscription-based model portfolio services is recalibrating how balanced funds reach end investors. Vanguard leverages its scale in index-based allocation products to dominate the direct-to-consumer channel. BlackRock sustains technology leadership through its Aladdin risk analytics platform that underpins institutional target-date construction. Fidelity differentiates via its hybrid robo-advisor offering that blends automated rebalancing with human advisor access.
Balanced funds are pooled investment vehicles maintaining fixed or flexible allocations across equity, fixed-income, and alternative asset classes, typically rebalancing to predetermined ratios such as 60/40 or tactical glide paths. Their primary purpose is to deliver risk-adjusted returns through diversification while simplifying asset allocation decisions for investors with moderate risk tolerance. Target-date funds lead the fund-type dimension as employer-sponsored retirement plans default participants into age-appropriate glide paths. Growth-oriented investment strategies are expanding fastest among younger retail cohorts seeking equity-heavy allocations within regulated wrappers. Financial advisors remain the dominant distribution channel for high-net-worth segments, though online platforms are capturing incremental flows from digitally native investors.
The SEC enforces liquidity risk management programs and swing pricing rules that directly affect how balanced funds manage redemption pressures and value illiquid holdings. The Department of Labor's fiduciary standards under ERISA influence which fund share classes qualify for inclusion in defined-contribution plan lineups. FINRA's suitability requirements shape advisor recommendations across conservative and aggressive allocation categories. Stakeholders must monitor how pending SEC reforms to fund naming conventions and ESG disclosure requirements will alter product positioning and competitive differentiation in hybrid fund categories.
Market Dynamics
The SEC's updated fund classification rules are compressing how asset managers structure hybrid portfolios, forcing simultaneous compliance with liquidity mandates and glide-path transparency requirements.
Growth Catalysts
- Target-date adoption in employer plans:Defined-contribution sponsors are defaulting participants into age-appropriate allocation vehicles, channeling steady inflows into balanced structures.
- Retail demand for retirement income:Aging demographics across developed economies are seeking simplified equity-debt combinations that reduce individual decision burden.
- Technology-enabled personalization:Risk analytics platforms now support customized glide-path construction at scale, lowering minimum thresholds for tailored solutions.
Market Restraints
- Fixed-income duration exposure:Central bank rate volatility compresses bond portfolio stability, eroding the traditional ballast function within 60/40 allocations.
- Fee compression pressure:Passive index proliferation drives management fee erosion, squeezing revenue available for active allocation research.
- Illiquid asset integration limits:Alternative allocations face redemption mismatch risks under SEC liquidity rule frameworks, constraining diversification depth.
Strategic Opportunities
- ESG-integrated allocation products:European Union Sustainable Finance Disclosure Regulation creates compliance-driven demand for climate-aware glide paths.
- Direct indexing overlay services:Separately managed account technology enables tax-loss harvesting within balanced wrappers, attracting high-net-worth segments.
- India's expanding mutual fund penetration:Regulatory reforms by SEBI and rising retail participation open underdeveloped markets for hybrid fund distribution.
Industry Challenges
- Cross-asset risk modeling complexity:Correlation breakdowns between equity and fixed-income during stress periods strain traditional portfolio construction methodologies.
- Advisor platform integration friction:Legacy custody systems require costly API development to support automated rebalancing and tax optimization features.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Balanced Funds Market |
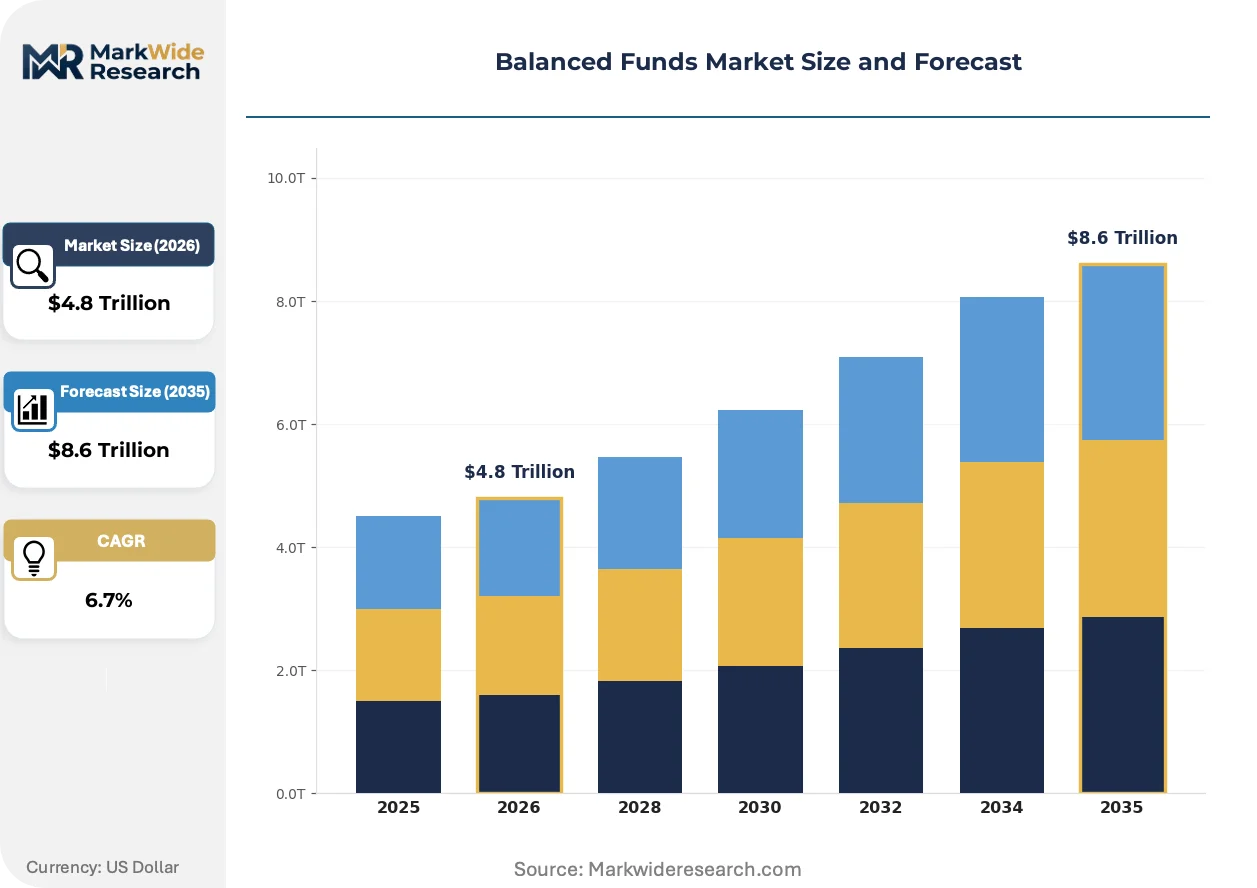
| Market Size in 2026 | $4.8 Trillion |
| Market Size in 2035 | $8.6 Trillion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Fund Type: Target Date, Life Cycle, Conservative Allocation, Aggressive Allocation Investment Strategy: Growth, Income, Value, Diversified Distribution Channel: Online, Financial Advisors, Banks, Direct Sales Customer Type: Retail Investors, High-Net-Worth Individuals, Institutional Investors, Family Offices |
| Companies Covered | Vanguard, T. Rowe Price, BlackRock, American Funds, Fidelity, PIMCO, Dodge & Cox, Schwab, Invesco, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Balanced Funds Market Strategic Shifts
Asset allocation technology is dissolving boundaries between institutional and retail portfolio construction, enabling sophisticated risk management at mass-market scale.
Unified risk analytics platforms are unifying equity, fixed-income, and alternative asset data into single-pane portfolio views. Institutional consultants and large defined-contribution recordkeepers are deploying these systems for real-time glide-path monitoring. This convergence is unifying previously siloed asset-class oversight, compressing the expertise gap between institutional and retail offerings.
SEC swing pricing reforms are forcing fund boards to implement formal liquidity classification frameworks for all holdings. The rules require daily liquidity bucketing and stress-testing against redemption scenarios. European-domiciled funds face parallel pressure from ESMA's liquidity stress-testing guidelines, driving convergence in operational infrastructure.
Digital-native investors are bypassing traditional advisor channels for direct-to-consumer allocation platforms. Robo-advisors and model marketplaces are capturing incremental flows from millennials seeking low-touch solutions. This channel rotation is most visible in the United States, where Vanguard and BlackRock direct platforms now compete with traditional wirehouse distribution.
Balanced Funds Market Segmentation
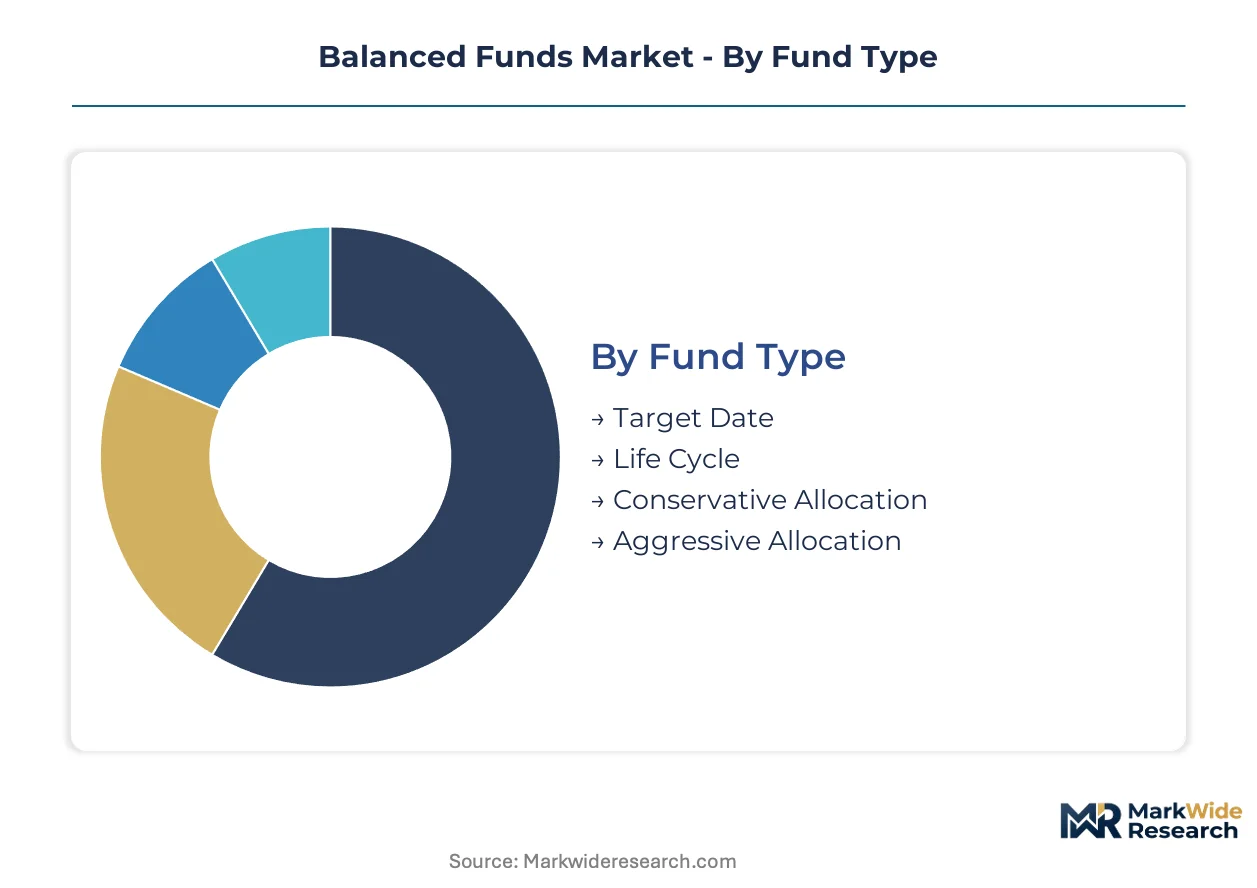
Balanced funds serve heterogeneous investor profiles requiring differentiated glide-path construction, fee structures, and distribution access. Segmentation reveals how product architecture aligns with retirement timelines, risk tolerance thresholds, and advisory relationships.
Fund Type:
Portfolio construction methodology determines rebalancing frequency, equity glide-path slope, and liquidity classification under SEC rule frameworks.
- Target Date:Automatic equity reduction along predetermined retirement-year glide paths. Employer-sponsored defined-contribution plans in the United States default participants into these vehicles, channeling payroll deduction flows into age-appropriate risk profiles.
- Life Cycle:Dynamic risk adjustment based on accumulated account balance rather than chronological age. Emerging demand concentrates among younger retail cohorts seeking equity-heavy allocations within tax-advantaged wrappers.
- Conservative Allocation:Fixed-income-majority portfolios emphasizing capital preservation.
- Aggressive Allocation:Equity-dominant structures targeting long-term appreciation.
Mature deployment sits with Target Date. Newer deployment is concentrated in Life Cycle.
Investment Strategy:
Return objectives and security selection philosophy shape fee structures, tracking error budgets, and alternative asset eligibility.
- Growth:Equity-centric positioning emphasizing capital appreciation over current income. Expanding most quickly among millennials in direct-to-consumer platforms seeking automated rebalancing at low cost basis.
- Income:Fixed-income and dividend-focused allocations targeting distribution yield. Demand concentrates among pre-retirees in the United States converting accumulation balances to sustainable withdrawal strategies.
- Value:Discounted security selection within traditional allocation frameworks.
- Diversified:Multi-factor exposure blending growth, income, and alternative sleeves.
Established book sits with Income. Steepest expansion trajectory belongs to Growth.
Distribution Channel:
Investor acquisition economics and service intensity vary dramatically across intermediated versus direct access models.
- Online:Digital-native platforms offering algorithmic allocation and tax-loss harvesting. Capturing incremental flows from digitally native investors bypassing traditional wirehouse relationships.
- Financial Advisors:Human-mediated guidance with holistic financial planning integration. Dominant channel for high-net-worth segments requiring estate coordination and concentrated position management.
- Banks:Deposit-gathering institutions cross-selling fund products to existing customers.
- Direct Sales:Manufacturer-owned platforms eliminating intermediary compensation layers.
Legacy volume concentrates with Financial Advisors. Emerging flow volume clusters in Online.
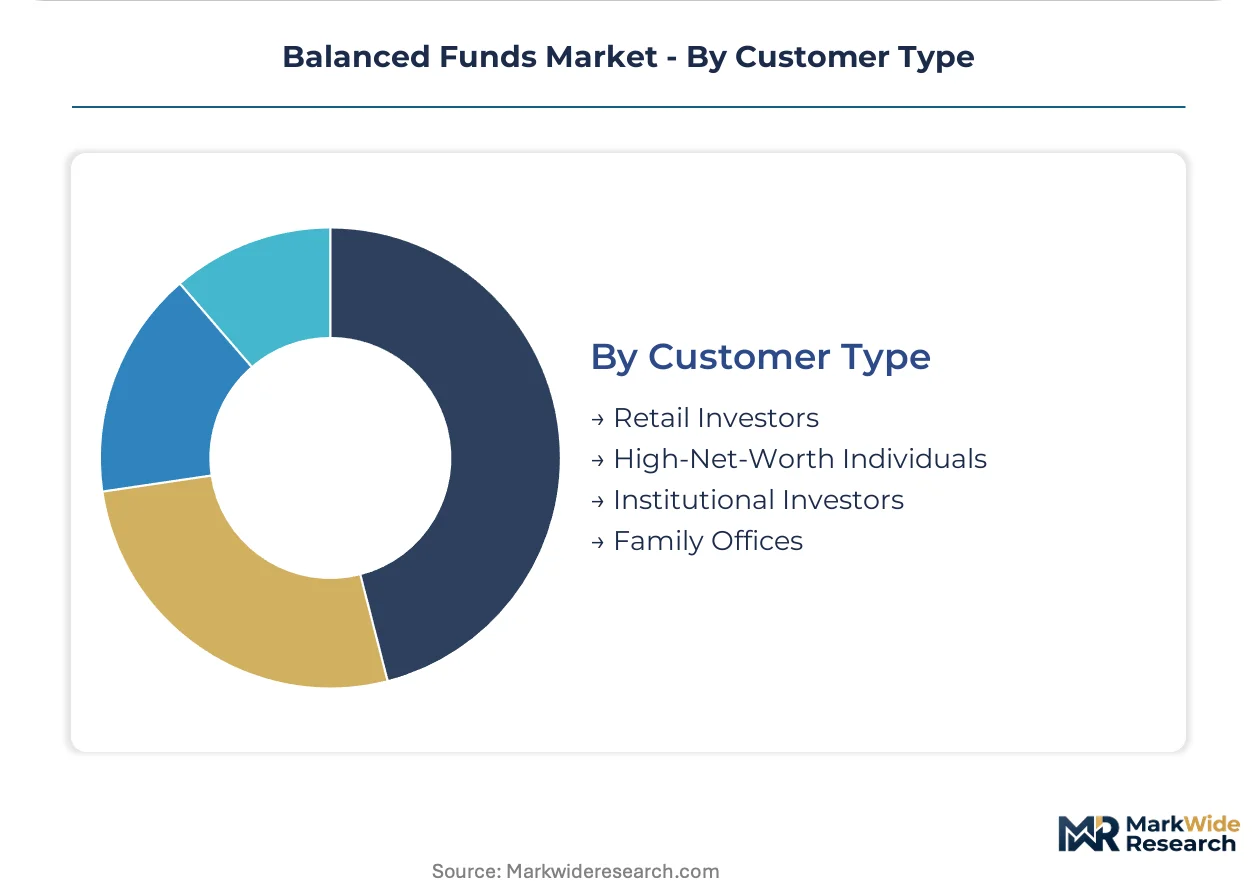
Customer Type:
Account size and governance structure dictate customization depth, share class eligibility, and reporting sophistication.
- Retail Investors:Mass-market participants investing through employer plans or individual accounts. The United States dominates this segment as target-date adoption expands across defined-contribution plan lineups.
- High-Net-Worth Individuals:Affluent households requiring separately managed account overlays and tax optimization. Demand concentrates for direct indexing integration within balanced wrappers.
- Institutional Investors:Pension funds and endowments with fiduciary oversight requirements.
- Family Offices:Multi-generational wealth vehicles seeking bespoke glide-path construction.
Institutional capital anchors the segment. Retail participation is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States generates the dominant share of balanced fund assets under management, while manufacturing of portfolio construction technology clusters in financial centers across multiple continents. Consumption concentrates in developed economies with mature defined-contribution retirement systems. Production of risk analytics platforms and fund administration services distributes across specialized financial hubs.
United States
Employer-sponsored 401(k) plans default participants into target-date vehicles, channeling steady payroll flows into balanced structures. The SEC enforces liquidity risk management programs and swing pricing rules that reshape how funds manage redemption pressures. Boston and New York host concentrated clusters of asset managers deploying Aladdin-style risk analytics for institutional glide-path construction.
United Kingdom
Auto-enrollment pension reforms expanded retail participation in multi-asset vehicles, particularly among younger cohorts seeking equity-heavy allocations. The Financial Conduct Authority's consumer duty rules mandate clearer fee disclosure and suitability assessments for advised sales. London's asset management district anchors European distribution of hybrid fund products, with recordkeepers deploying unified risk platforms for real-time monitoring.
Germany
Riester and Rürup pension reforms created tax-advantaged wrappers driving demand for lifecycle allocation products. BaFin's implementation of EU Sustainable Finance Disclosure Regulation forces climate-aware glide-path integration. Frankfurt's banking quarter hosts concentrated fund administration operations serving cross-border European distribution.
Japan
Government Pension Investment Fund reforms redirected institutional capital toward diversified multi-asset strategies, creating template effects for retail products. The Financial Services Agency's stewardship code pressures asset managers toward long-term balanced allocation frameworks. Tokyo's Marunouchi district clusters trust banks and asset managers developing target-date solutions for aging demographics.
Australia
Superannuation guarantee expansion channeled mandatory retirement contributions into diversified default options, with lifecycle strategies gaining traction. APRA's prudential standards govern liquidity management and stress-testing for superannuation funds holding hybrid portfolios. Sydney's financial district hosts concentrated fund administrator operations supporting automated rebalancing at mass-market scale.
Balanced Funds Market Competitive Environment
Capital-heavy asset managers with proprietary distribution compete with asset-light fintech platforms and index specialists. The market structure concentrates among three tiers: scale-driven index providers with direct-to-consumer platforms, active allocation specialists with advisor relationships, and hybrid robo-advisors blending automation with human guidance. Dominant competitive moves include strategic partnerships with defined-contribution recordkeepers and technology licensing of risk analytics infrastructure.
Within the scale-driven tier, Vanguard and BlackRock anchor opposite ends of the passive-active spectrum, with the former exemplifying direct-to-consumer index dominance and the latter representing institutional risk platform licensing. Fidelity occupies a hybrid position bridging automated rebalancing with human advisor access. T. Rowe Price exemplifies the active allocation specialist archetype with sustained advisor channel relationships.
| Leading Market Players |
|---|
| Vanguard |
| T. Rowe Price |
| BlackRock |
| American Funds |
| Fidelity |
| PIMCO |
| Dodge & Cox |
| Schwab |
| Invesco |
| Others |
Value Chain & Pricing Dynamics
Portfolio management talent concentration in Boston and New York widens pricing-tier spreads between mass-market index funds and bespoke institutional mandates, as labor-cost differentials between quantitative analysts and relationship managers feed into fee stratification across distribution channels.
Pricing Analysis
Margin tightening in active allocation tiers reflects passive index proliferation compressing management fees at the core. Three-tier pricing structure across premium, standard, and economy levels separates Aladdin-powered institutional mandates from direct-to-consumer robo-advisory wrappers and vanilla target-date funds. Price differentiation traces to technology licensing depth and advisor relationship intensity. Retail participants in employer-sponsored plans exhibit lowest price sensitivity; high-net-worth segments seeking direct indexing overlays demonstrate highest willingness to pay for customization.
Supply Chain Analysis
Risk analytics software supply rests on concentrated development clusters in Boston, New York, and London, where Aladdin-style platforms and competing portfolio construction engines draw from specialized quantitative research labor pools. Critical inputs include real-time market data feeds, cloud computing infrastructure, and regulatory compliance modules. Single-source vulnerability concentrates in benchmark index licensing from dominant providers. Distribution runs through defined-contribution recordkeepers, wirehouse advisor platforms, and direct-to-consumer digital channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asset managers face a vertical-integration race to capture risk analytics capabilities and distribution infrastructure, with proprietary Aladdin-style platforms and direct-to-consumer channels representing the decisive upstream and downstream levers shaping competitive economics.
For Market Incumbents: Extend technology licensing reach to smaller recordkeepers before fintech platforms commoditize portfolio construction tools. Deepen advisor platform integration through API development that automates rebalancing and tax-loss harvesting. Counter fee compression by embedding risk analytics as value-added services rather than standalone cost centers. For New Entrants and Emerging Players: Capture white-space in India's expanding mutual fund penetration where SEBI reforms and rising retail participation create underdeveloped hybrid fund distribution. Target digitally native investors seeking low-touch solutions through model marketplace positioning. Lead with ESG-integrated allocation products to differentiate in European markets facing SFDR compliance requirements. For Investors and Strategic Acquirers: Re-rating potential sits with asset-light fintech platforms possessing scalable risk analytics infrastructure given SEC swing pricing reforms forcing liquidity management upgrades across the industry. Long-term viability favors providers with captive distribution through employer plan recordkeeping relationships. Watch target-date fund flow velocity into retirement-aged cohorts as an inflection indicator for fee realization rates.| Strategic Initiative | Industry Significance |
|---|---|
| Risk Analytics Platform Licensing | Enables smaller asset managers to compete with Aladdin-powered institutional construction without captive R&D investment. |
| Direct-to-Consumer Channel Expansion | Vanguard and BlackRock direct platforms capture millennial flows bypassing traditional wirehouse relationships. |
| ESG Glide-Path Integration | SFDR compliance requirements in Europe force climate-aware allocation product development across fund lineups. |
| API Development for Advisor Platforms | Automated rebalancing and tax optimization features reduce legacy custody system friction for high-net-worth segments. |
| Target-Date Recordkeeping Partnerships | Employer plan default positioning channels steady payroll flows into age-appropriate balanced structures. |
Study Parameters
Multi-period observation of target-date fund flow patterns, fee compression trajectories, and regulatory implementation timelines anchored the trend analysis, supplemented by interviews with portfolio construction executives, defined-contribution recordkeeping officers, SEC compliance leads, and risk analytics platform engineers. Secondary validation drew from SEC fund disclosure databases, FINRA suitability guidance filings, Department of Labor ERISA advisory opinions, and European ESMA liquidity stress-testing guidelines. Bottom-up fund-level data triangulated against top-down asset manager revenue disclosures.
Input-output matrices modeled allocation flows across fund type, investment strategy, distribution channel, and customer type dimensions throughout the forecast period. CAGRs derived from regression analysis of historical flow velocity against demographic cohort transitions and regulatory implementation schedules. Industry-specific forecast inputs included 401(k) plan sponsor adoption curves for automatic enrollment features and glide-path equity reduction slopes by target retirement year.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to central bank rate trajectory shifts and correlation breakdowns between equity and fixed-income during stress periods. Assumptions reflect current SEC liquidity rule frameworks and ERISA fiduciary standards. A small set of triggers warrants ongoing watch: SEC reforms to fund naming conventions, ESG disclosure requirement finalization, and central bank quantitative tightening duration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Portfolio Management and Asset Allocation
US Mutual Funds Market
Portfolio Management and Asset Allocation
United States Project Portfolio Management Market
Portfolio Management and Asset Allocation
Portfolio Analytics Market
Portfolio Management and Asset Allocation
Global Project Portfolio Management (PPM) Market
Portfolio Management and Asset Allocation
Energy Portfolio Management Market
Portfolio Management and Asset Allocation
Corporate Performance Management Market
Portfolio Management and Asset Allocation
Germany Mutual Funds Market
Portfolio Management and Asset Allocation
UK Mutual Funds Market
Portfolio Management and Asset Allocation
Portfolio Management Software Market