
 Middle East and Africa Management Consulting Services Market | 2026-2036
Middle East and Africa Management Consulting Services Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Management Consulting Services Market Foresight
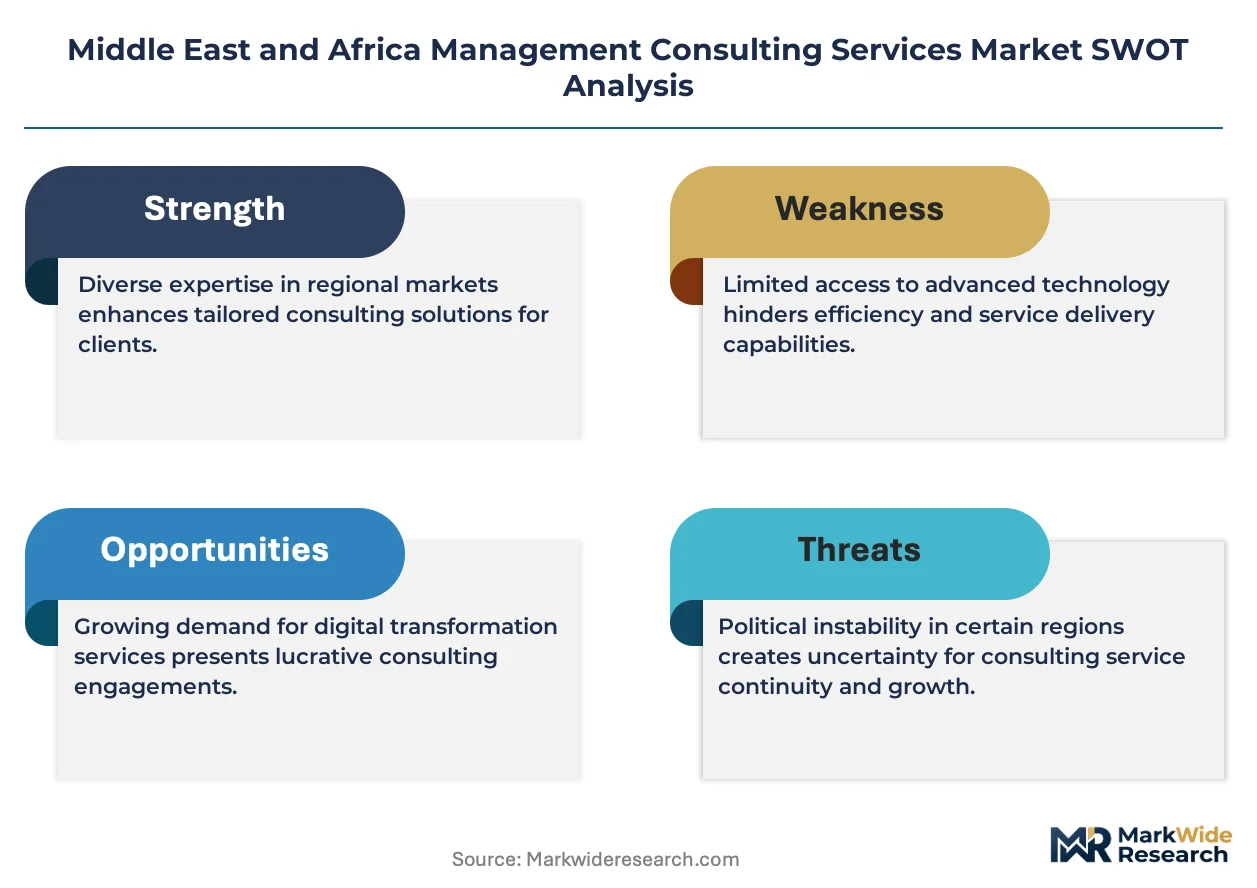
GDPR-aligned data governance requirements across African markets with EU trade exposure are repositioning compliance advisory as a mandatory cost of entry for international consultancies. McKinsey & Company leverages its Johannesburg hub to anchor public sector capability-building programs across Southern Africa. Deloitte Touche Tohmatsu Limited sustains competitive positioning through deep operational improvement benches in Riyadh and Lagos. Ernst & Young Global Limited differentiates via financial advisory specialization tied to sovereign wealth fund restructuring mandates.
Middle East and Africa management consulting services encompass structured advisory engagements delivered by professional services firms to improve organizational performance, spanning diagnostic assessment, strategy formulation, implementation support, and change management with defined deliverables, timelines, and knowledge transfer protocols. Operations improvement engagements deploy lean manufacturing methodologies, supply chain reconfiguration, and cost transformation programs to enhance asset productivity and working capital efficiency for industrial clients. Strategy Consulting commands premium fee structures among large enterprises navigating energy transition and diversification imperatives, while IT Advisory accelerates fastest as cloud migration and cybersecurity mandates reshape technology spending across financial services and telecommunications verticals. Public Sector clients represent an expanding margin pool as government modernization programs proliferate from Egypt to Kenya.
Saudi Arabia's National Transformation Program and South Africa's Public Finance Management Act create dual regulatory foundations shaping procurement transparency and local content requirements for advisory contracts. The UAE's Ministry of Finance circulars on federal entity restructuring, alongside Nigeria's SEC corporate governance codes, establish compliance benchmarks that filter market access for foreign consultancies. Stakeholders must monitor evolving local partnership mandates and emerging data residency rules that will determine operational licensing and talent deployment models across the region.
Market Dynamics
Sovereign wealth fund restructuring mandates across Gulf Cooperation Council states are compressing advisory procurement cycles and elevating technical specialization thresholds above generalist strategy offerings.
Growth Catalysts
- Vision 2030 Privatization Mandates:Saudi Arabia's regulatory framework compels state-owned enterprise restructuring, generating sustained demand for operational transformation advisory and governance redesign.
- GDPR-Aligned Data Governance:African markets with EU trade exposure are repositioning compliance advisory as mandatory cost of entry, forcing consultancies to build localized data residency capabilities.
- Cloud Migration Acceleration:Financial services and telecommunications verticals across the UAE are driving IT advisory expansion through cybersecurity mandates and legacy system replacement programs.
Market Restraints
- Local Content Requirements:South Africa's Public Finance Management Act and Nigeria's SEC corporate governance codes impose partnership mandates that restrict foreign consultancy operational licensing.
- Talent Deployment Friction:Emerging data residency rules across Kenya and Egypt complicate cross-border knowledge transfer and project staffing models for regional headquarters.
- Procurement Transparency Standards:Federal entity restructuring circulars from the UAE Ministry of Finance extend vendor qualification timelines and compress fee structures for public sector engagements.
Strategic Opportunities
- Kenya Public Sector Modernization:Government digital transformation programs outside traditional GCC hubs offer first-mover positioning for consultancies with established African operational footprints.
- Energy Transition Advisory:Large enterprises navigating diversification imperatives require integrated strategy support spanning carbon accounting, renewable project finance, and regulatory compliance.
- Capability-Building Program Models:Southern African public sector clients demonstrate appetite for embedded advisory structures that transfer operational skills rather than deliver static recommendations.
Industry Challenges
- Specialized Talent Scarcity:Deep benches in financial advisory and sovereign wealth fund restructuring remain concentrated in Riyadh and Johannesburg, constraining service expansion to secondary markets.
- Regulatory Fragmentation:Divergent compliance benchmarks across Egypt, Nigeria, and Kenya force consultancies to maintain multiple licensing frameworks and partnership structures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Management Consulting Services Market |
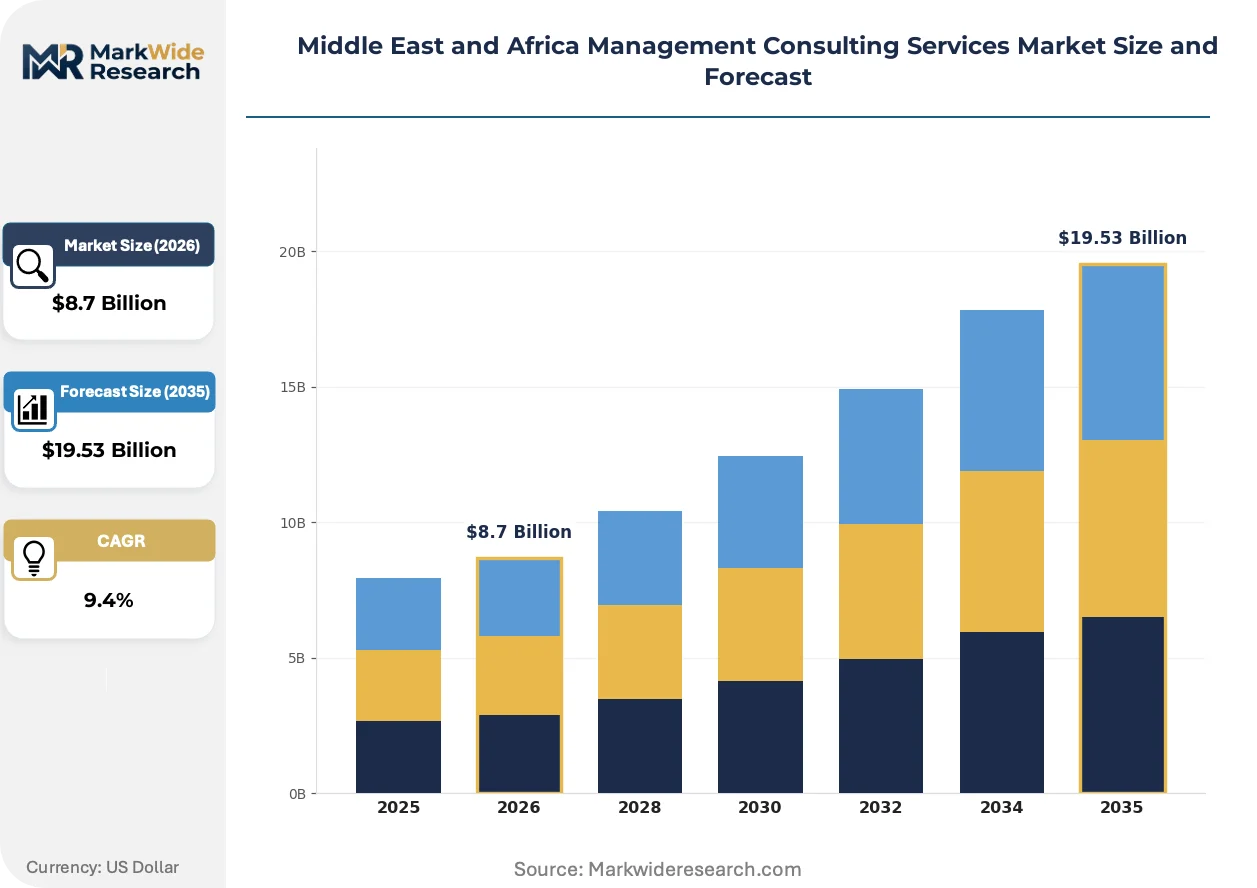
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Strategy Consulting, Operations Improvement, IT Advisory, Financial Advisory Industry Vertical: Healthcare, Manufacturing, Financial Services, Telecommunications Deployment Model: On-premises, Cloud-based, Hybrid, Remote Client Type: Large Enterprises, SMEs, Public Sector, Non-profits |
| Companies Covered | McKinsey & Company, Deloitte Touche Tohmatsu Limited, Ernst & Young Global Limited, Boston Consulting Group, Bain & Company, Accenture plc, PwC, KPMG, Arif Kitchlew Management Consultancy, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Management Consulting Services Market Shifts & Advancements
Advisory delivery models across the Middle East and Africa are fragmenting between premium strategy engagements and scaled implementation support, with technology platforms compressing traditional diagnostic phases.
Artificial intelligence-enabled diagnostic tools are unifying data extraction, pattern recognition, and scenario modeling into continuous advisory workflows. Large industrial clients in Saudi Arabia and the UAE are adopting these platforms to compress strategy development cycles from quarters to weeks. This unifying capability is collapsing the traditional boundary between diagnostic assessment and implementation support, forcing consultancies to restructure project staffing and knowledge transfer protocols.
Saudi Arabia's National Transformation Program regulatory framework is mandating standardized disclosure requirements for state-owned enterprise advisory contracts. Industrial clients must now document procurement transparency and local content ratios in restructuring engagements. Energy and infrastructure verticals are responding by embedding compliance specialists within project teams and pre-qualifying vendor partnerships.
Public sector buyers are consolidating advisory procurement through framework agreements rather than discrete project awards. Government modernization programs in Egypt and Kenya are shifting from individual ministry contracts to centralized professional services panels. This concentration is most visible in healthcare and education verticals, where federal entities now mandate multi-year capability-building structures over standalone strategy reports.
Middle East and Africa Management Consulting Services Market Segmentation
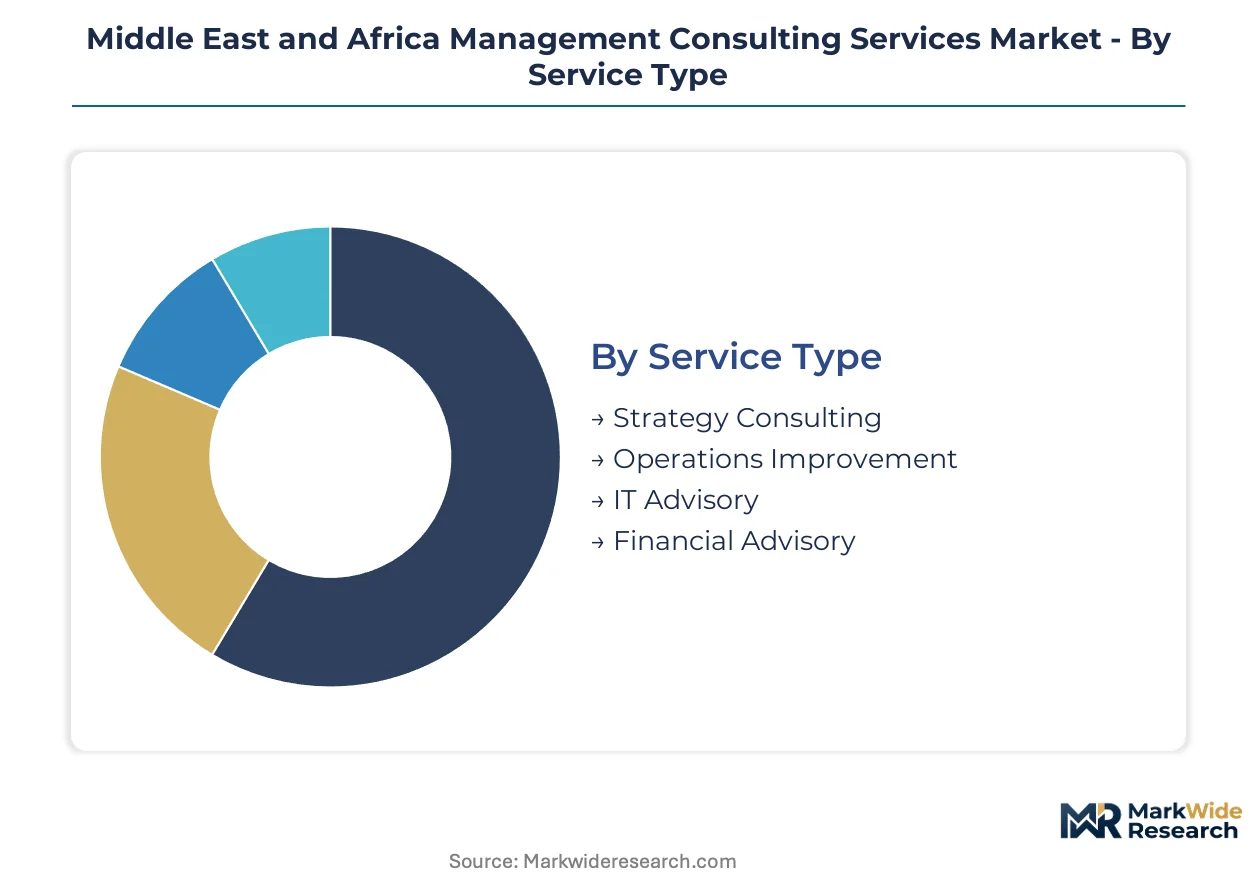
Segmentation in Middle East and Africa management consulting services reveals how procurement patterns diverge across client sophistication levels and regulatory exposure. Service buyers prioritize different capability bundles based on ownership structure, technology maturity, and compliance mandates.
Service Type:
Fee structures and engagement duration vary sharply by advisory depth, with buyers selecting service tiers based on strategic urgency and internal execution capacity.
- Strategy Consulting:Premium engagements spanning market entry, portfolio restructuring, and diversification roadmaps for energy and infrastructure conglomerates. Saudi Aramco and ADNOC transformation mandates concentrate demand in Riyadh and Abu Dhabi, with sovereign wealth fund restructuring elevating technical specialization thresholds above generalist offerings.
- IT Advisory:Cloud migration, cybersecurity architecture, and legacy system replacement programs for financial services and telecommunications verticals. Dubai Islamic Bank and Emirates NBD digital transformation roadmaps are compressing delivery timelines and forcing consultancies to embed technical implementation teams alongside strategy advisors.
- Operations Improvement:Lean manufacturing deployment and supply chain reconfiguration for industrial clients seeking asset productivity gains.
- Financial Advisory:Transaction support, valuation, and restructuring for privatization mandates and state-owned enterprise divestitures.
Strategy Consulting leads on scale; IT Advisory leads on momentum.
Industry Vertical:
Regulatory intensity and capital deployment cycles determine vertical prioritization, with compliance-heavy sectors commanding sustained advisory relationships.
- Financial Services:Basel III implementation, Islamic finance structuring, and digital banking transformation for UAE and Saudi Arabian banks. Central Bank of the UAE and Saudi Central Bank circulars on operational resilience and open banking are mandating multi-year advisory partnerships rather than discrete project awards.
- Telecommunications:5G rollout financing, spectrum auction strategy, and infrastructure sharing agreements for Etisalat and stc Group. Regulatory pressure from TRA UAE and CITC Saudi Arabia on network security and data localization is expanding compliance advisory scopes.
- Healthcare:Hospital privatization, health insurance integration, and clinical quality systems for GCC public health authorities.
- Manufacturing:Industrial diversification and export competitiveness programs for Saudi Arabian and Egyptian producers.
Financial Services captures the deepest advisory relationships; Telecommunications shows the steepest expansion trajectory.
Deployment Model:
Delivery configuration hinges on data sensitivity, talent mobility constraints, and client preference for embedded versus episodic support.
- Hybrid:Blended on-site and remote delivery combining relationship partner presence with distributed analyst teams. Kenya and Egypt public sector modernization programs are adopting hybrid structures to navigate emerging data residency rules while maintaining cross-border knowledge transfer.
- Cloud-based:Platform-enabled advisory leveraging AI diagnostic tools and continuous data feeds. Saudi Arabian industrial clients are compressing strategy development cycles from quarters to weeks through these unified workflows.
- On-premises:Fully embedded advisory with consultants resident at client facilities for sensitive restructuring mandates.
- Remote:Location-independent delivery for standardized diagnostic and benchmarking engagements.
Hybrid dominates current procurement; Cloud-based is gaining share fastest.
Client Type:
Budget authority and decision velocity separate client segments, with public sector procurement reform creating distinct competitive dynamics.
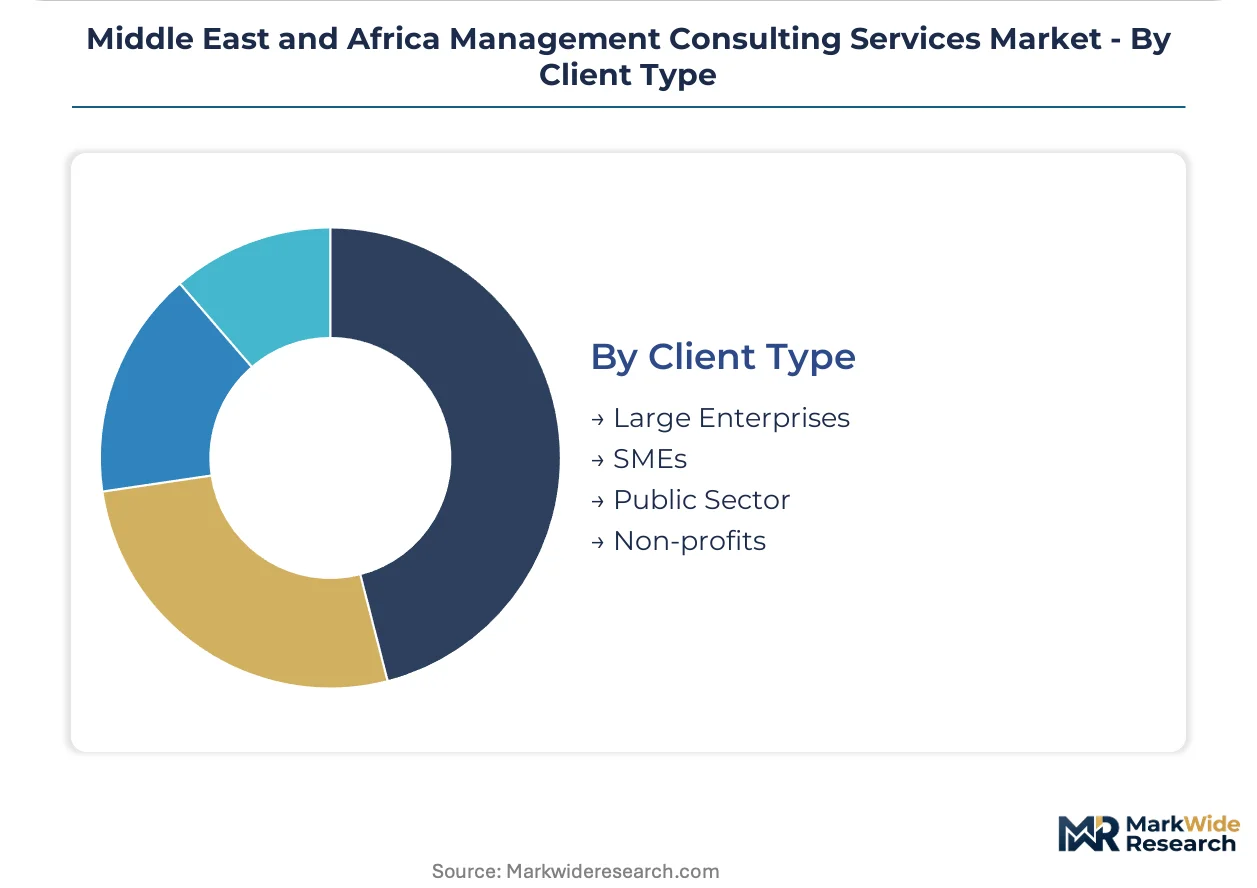
- Public Sector:Federal and ministry-level engagements for digital transformation, entity restructuring, and capability-building. UAE Ministry of Finance circulars on procurement transparency and South Africa's Public Finance Management Act are extending vendor qualification timelines while expanding contract values.
- Large Enterprises:Multi-year strategic partnerships with energy, banking, and industrial conglomerates navigating energy transition imperatives.
- SMEs:Modular advisory packages for family-owned businesses seeking operational discipline and succession planning.
- Non-profits:Governance and funding strategy support for development organizations and philanthropic foundations.
Public Sector leads on contract value concentration; Large Enterprises sustain the most predictable renewal rates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized consulting talent clusters in Riyadh, Dubai, and Johannesburg anchor advisory delivery across the region. These hubs concentrate expertise in sovereign wealth fund restructuring, digital transformation, and public sector capability-building that serves cross-border mandates.
Saudi Arabia
Vision 2030 privatization mandates and state-owned enterprise restructuring generate sustained demand for operational transformation advisory. The National Transformation Program regulatory framework standardizes disclosure requirements for advisory contracts. Riyadh anchors the deepest benches of financial advisory specialists serving GCC sovereign wealth fund mandates.
United Arab Emirates
Dubai and Abu Dhabi function as regional headquarters for international consultancies managing African expansion strategies. Ministry of Finance circulars on federal entity restructuring extend vendor qualification timelines while expanding contract values. The Dubai International Financial Centre concentrates IT advisory expertise for financial services digital transformation.
South Africa
The Public Finance Management Act imposes local content requirements and partnership mandates that filter market access for foreign consultancies. Johannesburg anchors McKinsey's public sector capability-building programs across Southern Africa. Cape Town's financial services cluster sustains demand for governance and risk advisory.
Egypt
Government modernization programs are shifting from individual ministry contracts to centralized professional services panels. Emerging data residency rules complicate cross-border knowledge transfer for regional headquarters. Cairo's healthcare and education verticals demonstrate appetite for multi-year capability-building structures.
Kenya
Public sector digital transformation programs outside traditional GCC hubs offer first-mover positioning for consultancies with established African footprints. Hybrid delivery structures navigate data residency constraints while maintaining cross-border staffing flexibility. Nairobi's emerging fintech cluster generates ancillary demand for regulatory compliance advisory.
Middle East and Africa Management Consulting Services Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across service tiers, creating a tiered market structure with distinct positioning vectors. The vendor base separates into global strategy houses, technology-integrated implementers, and regionally anchored specialists. Three strategic archetypes dominate: premium strategy advisors commanding restructuring mandates, operational improvement specialists embedded in industrial clients, and compliance-focused boutiques serving regulatory-intensive verticals. Competitive moves concentrate on local partnership formation and specialized talent acquisition rather than scale-based expansion.
Within the premium strategy tier, McKinsey & Company and Boston Consulting Group exemplify advisory models built around sovereign wealth fund mandates and energy transition roadmaps. Deloitte Touche Tohmatsu Limited and Ernst & Young Global Limited occupy positions bridging strategy formulation with implementation execution, leveraging operational benches in Riyadh and Lagos. Accenture plc anchors the technology-integrated vector, representing consultancies that embed technical implementation teams alongside traditional advisory functions.
| Leading Market Players |
|---|
| McKinsey & Company |
| Deloitte Touche Tohmatsu Limited |
| Ernst & Young Global Limited |
| Boston Consulting Group |
| Bain & Company |
| Accenture plc |
| PwC |
| KPMG |
| Arif Kitchlew Management Consultancy |
| Others |
Supply & Pricing Matrix
Talent cost inflation indices in Riyadh and Dubai cascade through consulting delivery models into three distinct pricing tiers, with premium strategy engagements absorbing partner-level rate premiums while implementation-heavy contracts compress margins through analyst bench scaling.
Pricing Analysis
Bundled service packages combining strategy formulation with implementation support command fee premiums over unbundled diagnostic-only engagements across Saudi Aramco and ADNOC transformation mandates. Project-based pricing dominates, with differentiation driven by partner seniority tier and certification depth in sovereign wealth fund restructuring. Cost compression in mid-market operational improvement is intensifying because Nigerian and South African local content mandates force foreign consultancies into revenue-sharing partnerships. Public sector clients exhibit highest price sensitivity due to procurement transparency circulars, while energy conglomerates show lowest sensitivity given energy transition urgency.
Supply Chain Analysis
Dual-sourcing requirements embedded in UAE Ministry of Finance circulars and South Africa's Public Finance Management Act mandate that public sector buyers qualify multiple consultancies for framework agreements, fragmenting contract concentration. Geographic supply concentrates in the United Arab Emirates, Saudi Arabia, and South Africa, where Riyadh, Dubai, and Johannesburg anchor specialized talent pools. Delivery draws from partner-level expertise, analyst bench capacity, and technology platform licenses. Single-source vulnerability persists in sovereign wealth fund financial advisory, where deep benches remain confined to Riyadh. Distribution runs through regional headquarters managing cross-border staffing to Kenya and Egypt.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market rests on capability-building program models that shift revenue from one-off strategy reports to multi-year embedded advisory, capturing recurring fees while reducing client acquisition costs.
For Market Incumbents: Extend sovereign wealth fund restructuring specialization into adjacent carbon accounting and renewable project finance to capture energy transition budgets. Deepen operational benches in Lagos and Nairobi before local content mandates harden. Partner pre-qualification requirements in Nigeria's SEC corporate governance codes threaten exclusive positioning.
For New Entrants and Emerging Players: Kenya's Public Finance Management Act alignment opens a window for consultancies with established African footprints to secure government digital transformation contracts outside GCC hub competition. Target healthcare and education verticals in Egypt where federal entities mandate multi-year capability-building structures. Lead with hybrid delivery models that navigate data residency constraints while offering cost advantages over fully embedded competitors.
For Investors and Strategic Acquirers: Asymmetric upside sits with technology-integrated advisory boutiques possessing AI-enabled diagnostic platforms and existing UAE financial services relationships. Long-term viability favors firms bridging strategy formulation with implementation execution rather than pure diagnostic players. Watch for sovereign wealth fund restructuring mandate volume as inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Local Partnership Formation | Satisfies South Africa's Public Finance Management Act local content requirements while unlocking Nigerian SEC-mandated vendor pre-qualification. |
| AI Diagnostic Platform Deployment | Compresses Saudi Aramco strategy development cycles from quarters to weeks, collapsing traditional diagnostic-implementation boundaries. |
| Capability-Building Program Expansion | Captures Egyptian healthcare and education vertical demand for multi-year embedded advisory over standalone strategy reports. |
| Sovereign Wealth Fund Specialization | Secures premium fee structures in Riyadh where GCC restructuring mandates concentrate technical specialization thresholds. |
| Hybrid Delivery Infrastructure | Enables Kenya and Egypt public sector engagement despite emerging data residency rules complicating cross-border staffing. |
Research Methodology
Coverage spans the Middle East and Africa, with primary inputs from each sub-region combining structured interviews with strategy partners, public sector procurement officers, sovereign wealth fund executives, and technology platform vendors alongside secondary validation. Secondary sources include UAE Ministry of Finance circulars, Saudi National Transformation Program disclosures, South African Public Finance Management Act guidance, SEC Nigeria corporate governance codes, and central bank operational resilience circulars. Bottom-up project pipeline tracking triangulates with top-down market sizing across service type, vertical, and client type dimensions.
Granularity-level modeling applies at service type, industry vertical, deployment model, and client type intersections, with additional segmentation by regulatory exposure tier. CAGRs derive from trend extrapolation of advisory procurement cycle compression and technology platform adoption curves. Forecast inputs include sovereign wealth fund restructuring mandate flow, cloud migration acceleration in UAE financial services, and public sector modernization program rollout velocity across Egypt and Kenya.
Revisions become necessary when local content mandates tighten beyond current partnership requirements, data residency rules extend to additional jurisdictions, or procurement transparency standards compress fee structures beyond modeled thresholds. Deviation in sovereign wealth fund restructuring volume would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Corporate Training and Talent Development
Asia-Pacific Corporate Training Market
Corporate Training and Talent Development
Europe Management Consulting Services Market
Corporate Training and Talent Development
Asia Pacific HR Professional Services Market
Corporate Training and Talent Development
Global Sales Training Market
Corporate Training and Talent Development
Integrated Talent Management Market
Corporate Training and Talent Development
Europe Executive Search (Headhunting) Market
Corporate Training and Talent Development
IT Training Market
Corporate Training and Talent Development
France Outplacement Services Market
Corporate Training and Talent Development
United States HR Professional Service Market
Corporate Training and Talent Development
Private Tutoring Market
Corporate Training and Talent Development
Educational Consulting and Training Market
Corporate Training and Talent Development
Canada Outplacement Services Market
Corporate Training and Talent Development
Executive Coaching Certification Market
Corporate Training and Talent Development
Asia Pacific Strategic Consulting Services Market
Corporate Training and Talent Development
Corporate Leadership Training Market
Corporate Training and Talent Development
Corporate Training Services Market