
 Private Tutoring Market | 2026-2036
Private Tutoring Market Size, Share, and Industry Trends Forecast 2026-2036
Private Tutoring Market Analysis
After-school assessment preparation revenue is reconfiguring how education companies allocate capital between physical centers and digital infrastructure. TAL Education Group leverages its established brand recognition in mathematics and science tutoring to maintain parent loyalty across tiered city markets. BYJU'S anchors its growth on animated content libraries and adaptive learning algorithms that personalize study pacing for individual students. Preply specializes in one-on-one language instruction through its marketplace model, connecting learners with tutors across time zones without geographic constraints.
Private tutoring encompasses supplementary educational instruction delivered outside formal schooling, typically involving personalized or small-group sessions targeting specific academic subjects, standardized test readiness, or skill acquisition through structured curricula and measurable outcome tracking. The service generates value by addressing gaps in mainstream classroom coverage, accelerating concept mastery through individualized attention, and providing credentialing support for university admissions or professional certification. Academic tutoring occupies the largest revenue pool due to persistent competition for university placement in countries with high-stakes examination systems, while online delivery mode represents the fastest-expanding structural segment as broadband penetration and mobile device affordability democratize access to qualified instructors previously restricted by geography. Test preparation retains premium pricing power in markets where standardized scores function as gatekeepers for educational advancement.
China's Ministry of Education and SAMR enforce strict operational caps on tutoring hours, pricing transparency, and nonprofit structuring for compulsory-education services, directly constraining business model design and profitability timelines for providers serving K-12 students. India's UGC and state education boards influence curriculum alignment requirements that determine which tutoring content qualifies as legitimate supplementary instruction versus unregulated coaching. The EU AI Act and national data protection authorities under GDPR impose algorithmic accountability and child data handling standards on platforms deploying adaptive learning technologies. Stakeholders must monitor how regulatory divergence across jurisdictions fragments platform architecture and forces localized compliance investments rather than scalable global product rollouts.
Market Dynamics
China's Ministry of Education and SAMR restructuring mandates have forced tutoring providers to abandon profit-seeking models for compulsory-education services, triggering operational fragmentation across Asia's largest supplementary education market. This regulatory pivot is compressing margins while accelerating platform exits from K-12 academic tutoring into adult upskilling and overseas test preparation.
Growth Catalysts
- Adaptive Learning Algorithms:Machine learning personalization engines analyze student response patterns to calibrate difficulty pacing, reducing time-to-mastery for mathematics and science curricula. Platforms deploying these tools report higher session completion rates and parent renewal intent.
- India's Digital Infrastructure Expansion:BharatNet fiber optic rollout and affordable 4G penetration in tier-2 and tier-3 cities are dissolving geographic barriers to qualified instructor access, expanding addressable learner pools beyond metropolitan clusters.
- EU AI Act Compliance Framework:Algorithmic accountability requirements for educational technology create competitive moats for platforms with established child data governance, disadvantaging smaller entrants lacking compliance infrastructure.
Market Restraints
- Qualified Instructor Supply Bottleneck:STEM-specialized tutors with examination board certification command premium wages, compressing gross margins for providers competing on price in saturated metropolitan markets.
- China Nonprofit Structuring Mandate:SAMR's compulsory-education tutoring caps eliminate equity investment pathways and dividend distributions, freezing capital allocation flexibility for historically profitable K-12 segments.
- Free Open Educational Resources:YouTube tutorial libraries and government-funded learning platforms substitute for paid instruction in standardized test segments where content commoditization is advanced.
Strategic Opportunities
- Vietnam and Indonesia Urban Clusters:Ho Chi Minh City, Jakarta, and Surabaya exhibit rising middle-class density with limited established tutoring brand presence, offering first-mover positioning before local competitors consolidate.
- Corporate Learning and Development Contracts:Enterprise procurement of language and technical certification tutoring for employee mobility is displacing individual consumer subscriptions as the dominant B2B revenue stream.
- Germany's Skilled Immigration Act:Federal language proficiency requirements for work visa applicants create mandated demand for German instruction, with publicly funded integration courses subsidizing provider revenue stability.
Industry Challenges
- Cross-Border Credential Recognition:Tutoring certificates from Indian or Southeast Asian platforms face acceptance barriers when students apply to universities in North America or Europe, requiring expensive accreditation partnerships with established examination boards.
- Legacy Learning Management System Integration:School districts and university continuing education departments operate on outdated software stacks, forcing tutoring platforms to maintain costly API compatibility layers for institutional sales cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Private Tutoring Market |
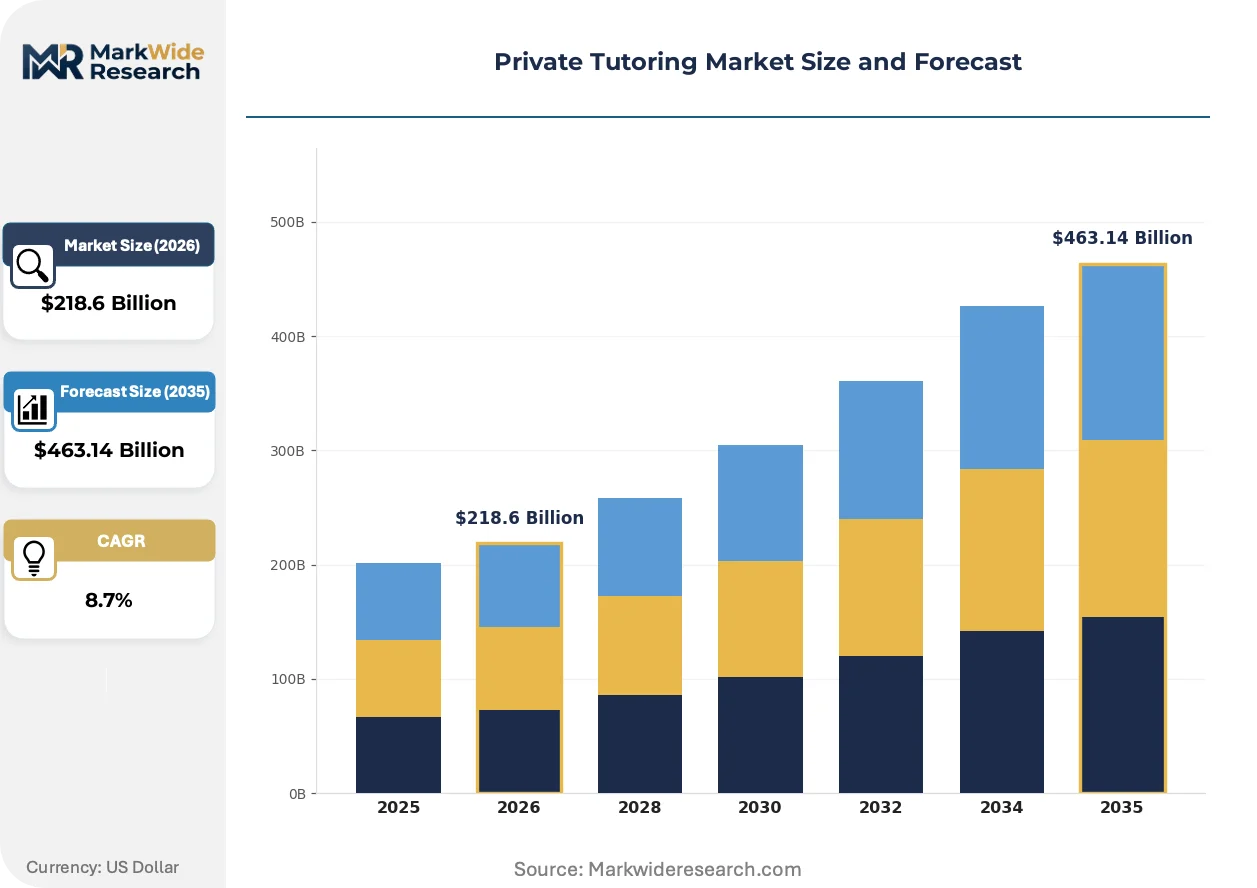
| Market Size in 2026 | $218.6 Billion |
| Market Size in 2035 | $463.14 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Academic Tutoring, Test Preparation, Language Tutoring, Skills Development End User: K-12 Students, College Students, Adult Learners, Professionals Delivery Mode: In-Person, Online, Hybrid, Group Sessions Subjects Offered: Mathematics, Science, Languages, Arts |
| Companies Covered | Kumon Institute of Education, Kaplan, TAL Education Group, Vedantu, Huntington Learning Center, Chegg, Sylvan Learning, Preply, BYJU'S, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Private Tutoring Market Emerging Trajectories
Artificial intelligence is restructuring how tutoring platforms deliver personalization, moving beyond content libraries toward real-time pedagogical adaptation. Regulatory fragmentation is forcing architectural divergence rather than scalable global product rollouts.
Generative AI tutoring assistants are migrating from simple chatbot interfaces to multimodal systems that process handwritten equations, spoken pronunciation, and video problem-solving attempts. Early adopters in South Korean test preparation and Indian engineering entrance coaching are deploying these tools at scale. The technology is compressing the cost structure for one-on-one instruction, enabling price points that compete with small-group formats.
The EU AI Act's risk classification for educational technology mandates algorithmic transparency documentation and human oversight protocols for automated grading and progression decisions. Providers serving European markets must maintain technical files demonstrating bias mitigation in adaptive learning pathways. K-12 platforms face the steepest compliance burden, with some operators segmenting product architectures to isolate high-risk jurisdictions from global codebases.
Subscription fatigue among parents is fragmenting demand toward micro-credential and single-session marketplace models that displace annual package commitments. Preply's tutor marketplace and similar platforms capture this behavioral shift, offering hourly booking without long-term contracts. This pattern concentrates in India's metropolitan clusters and Southeast Asian capital cities where digital payment infrastructure supports transactional flexibility.
Private Tutoring Market Segmentation
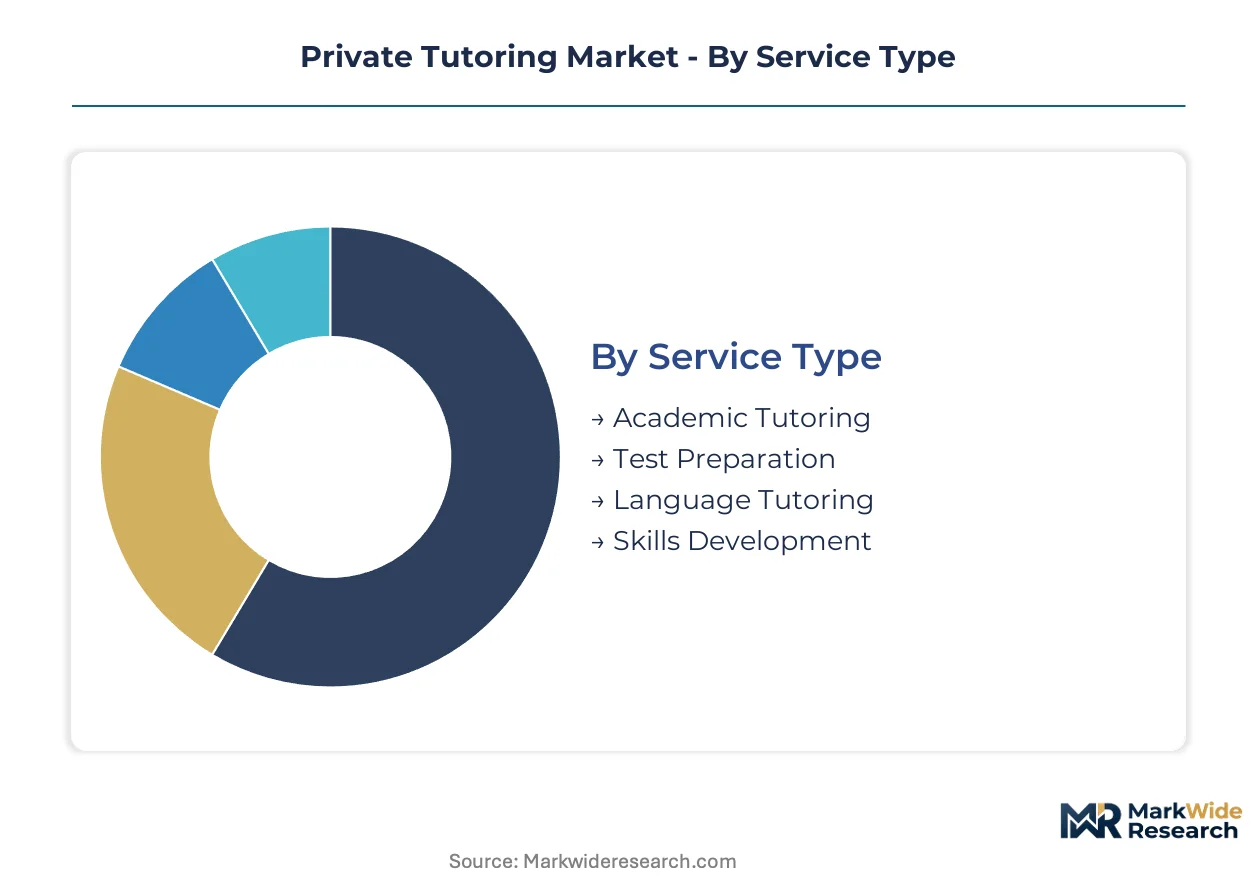
Segmentation in private tutoring reveals how parental purchasing cycles and student lifecycle transitions create distinct revenue velocity profiles. Service type and delivery mode exhibit the sharpest turnover differentials, while end-user categories stretch commitment horizons across multi-year educational journeys.
Service Type:
Academic tutoring operates on semester-aligned renewal cycles with predictable re-enrollment patterns, whereas test preparation compresses decision windows into examination-season spikes. Skills development stretches longest with career-transition pacing.
- Academic Tutoring:Core curriculum supplementation spanning mathematics, sciences, and humanities with structured syllabi mapped to national examination boards. Demand clusters in Chinese tier-1 cities and Indian metropolitan corridors where university placement pressure intensifies parental spending. SAMR nonprofit restructuring in China has forced operational pivots toward adult segments.
- Test Preparation:Intensive, time-bound instruction targeting standardized examinations including university entrance tests, professional certification, and language proficiency assessments. Registration surges concentrate in South Korean college scholastic ability test windows and Indian engineering entrance coaching seasons with compressed 8-12 week engagement cycles.
- Language Tutoring:Proficiency acquisition for academic, immigration, or corporate mobility objectives spanning spoken and written competency development.
- Skills Development:Technical and vocational instruction including coding, digital literacy, and creative arts targeting career transition or enhancement goals.
Academic tutoring dominates installed base. Test preparation is where expansion concentrates.
End User:
Cost tier stratification separates premium individualized instruction from standardized group formats, with professional segments commanding rate multiples above K-12 baseline pricing.
- K-12 Students:Compulsory education learners receiving supplementary instruction aligned with school curricula and examination preparation requirements. China's Ministry of Education hour caps and pricing transparency mandates have eliminated profit-seeking models for this segment, compressing provider margins.
- College Students:Undergraduate and graduate learners pursuing subject mastery, competitive examination readiness, or research methodology support. Indian metropolitan demand concentrates in engineering and medical entrance coaching with high instructor credential requirements.
- Adult Learners:Non-traditional students returning to formal education or pursuing credential acquisition for career advancement.
- Professionals:Corporate employees procuring language certification, technical upskilling, or executive education through employer-funded or individually financed arrangements.
K-12 students retain the deepest enrollment base. Professionals are climbing the fastest as enterprise learning and development budgets displace individual subscriptions.
Delivery Mode:
Volume concentration tracks broadband infrastructure penetration, with online formats gaining share fastest in markets where qualified instructor supply fails to match geographic demand density.
- In-Person:Physical center-based or home-visit instruction with direct tutor-student interaction and immediate feedback loops. Established brand presence in Chinese tiered cities and Vietnamese urban clusters maintains parent loyalty despite higher per-session costs.
- Online:Synchronous and asynchronous digital instruction delivered through video conferencing, adaptive learning platforms, and AI-assisted tutoring systems. BharatNet fiber expansion across Indian tier-2 and tier-3 cities is dissolving prior geographic barriers to qualified instructor access.
- Hybrid:Blended delivery combining scheduled in-person sessions with digital reinforcement and asynchronous practice modules.
- Group Sessions:Small-cohort instruction typically 3-8 students balancing individualized attention with per-capita cost reduction.
In-person retains the largest committed enrollment base. Online delivery is gaining share fastest as mobile device affordability democratizes access.
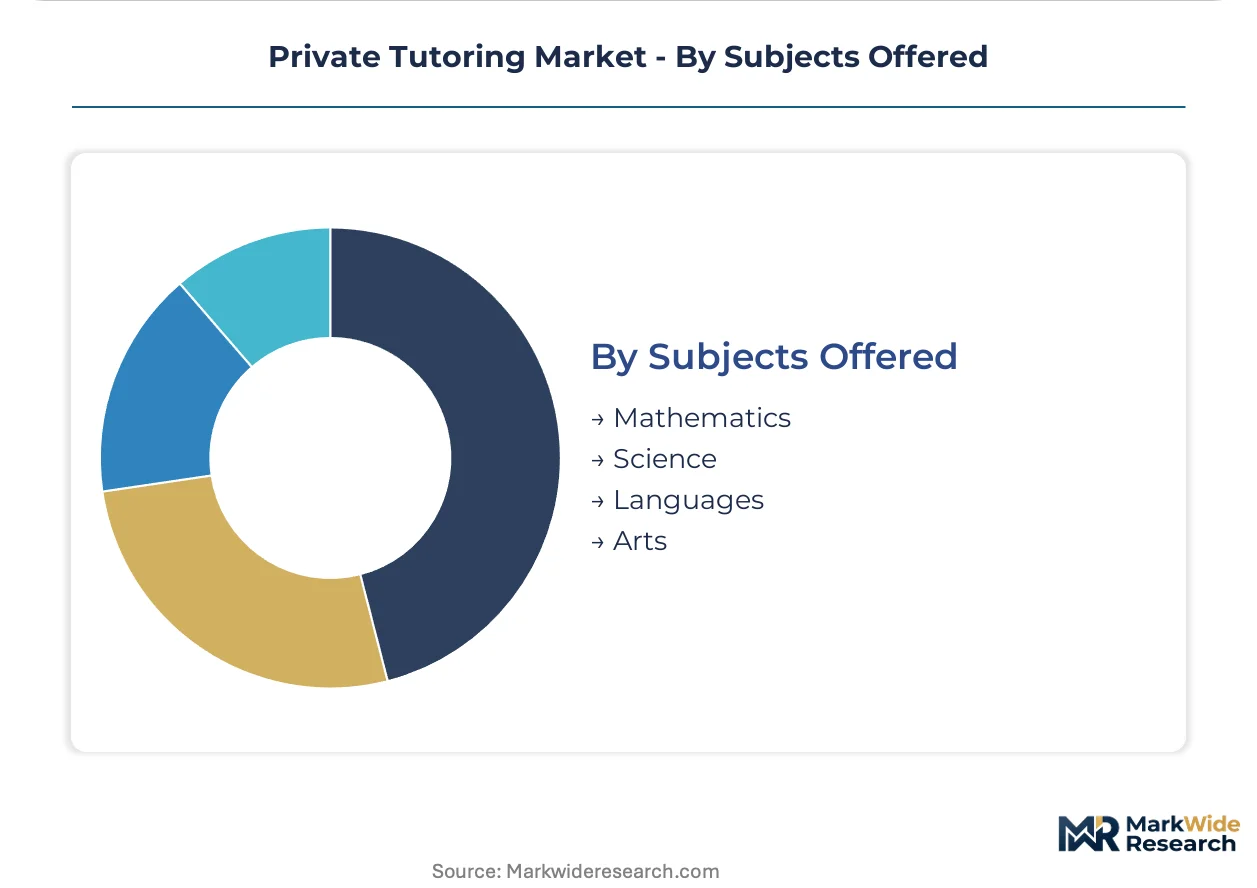
Subjects Offered:
Maturity gradients separate commoditized standardized test content from premium specialized instruction, with STEM subjects commanding sustained pricing power.
- Mathematics:Foundational and advanced quantitative instruction spanning arithmetic through calculus and competition mathematics. TAL Education Group's established brand recognition in this subject category sustains enrollment retention across Chinese city tiers despite regulatory restructuring.
- Science:Physics, chemistry, biology, and integrated laboratory preparation with emphasis on examination board practical assessment requirements. Indian engineering entrance coaching generates concentrated demand spikes with certified instructor wage premiums compressing provider margins.
- Languages:Native and foreign language acquisition including examination preparation for immigration and academic credentialing purposes.
- Arts:Creative and performing arts instruction spanning visual arts, music, and design disciplines with portfolio development for admissions processes.
Mathematics and science dominate revenue concentration. Language instruction is where platform expansion concentrates as immigration policy creates mandated proficiency demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity fragments sharply across geographies: Indian tier-2 city parents demand sub-dollar hourly rates while German professionals accept triple-digit euro premiums for certified language instruction. China's regulatory restructuring has eliminated profit elasticity entirely in K-12 segments.
China
SAMR's nonprofit mandate for compulsory-education tutoring has vaporized equity returns in the world's largest supplementary education market. The Ministry of Education's hour caps and pricing transparency rules force operational pivots toward adult upskilling and overseas test preparation. Beijing and Shanghai providers concentrate on credentialing services for university admissions abroad.
India
BharatNet fiber expansion dissolves geographic barriers to qualified instructor access across tier-2 and tier-3 cities. State education boards influence curriculum alignment requirements that determine legitimate supplementary instruction status. Mumbai, Bangalore, and Delhi-NCR clusters generate concentrated demand spikes for engineering and medical entrance coaching.
Germany
The Skilled Immigration Act's federal language proficiency requirements create mandated demand for German instruction among work visa applicants. Publicly funded integration courses subsidize provider revenue stability. Berlin and Munich metropolitan areas concentrate corporate learning and development procurement for employee mobility.
United States
Subscription fatigue fragments demand toward micro-credential and single-session marketplace models displacing annual package commitments. Enterprise procurement of technical certification tutoring displaces individual consumer subscriptions as the dominant B2B revenue stream. Greater Boston and Silicon Valley clusters concentrate professional upskilling demand.
Vietnam
Ho Chi Minh City exhibits rising middle-class density with limited established tutoring brand presence, offering first-mover positioning before local competitors consolidate. The Ministry of Education and Training influences curriculum standards that shape supplementary instruction legitimacy. Urban clusters concentrate demand for English proficiency acquisition and STEM examination preparation.
Private Tutoring Market Vendor Landscape
Capability concentration sits with specialized content developers; scale advantage sits with platform aggregators. The market structures around three tiers: legacy center-based operators with established geographic footprints, digital-native platforms with adaptive learning infrastructure, and marketplace connectors linking learners with freelance instructors. Strategic moves concentrate on portfolio diversification into adjacent credentialing segments and geographic expansion through franchise licensing rather than organic buildout.
Within the legacy operator tier, Kumon Institute of Education and Kaplan occupy positions exemplifying center-based scale with standardized curriculum delivery. TAL Education Group anchors the Chinese market restructuring pivot toward adult segments. Among digital-native platforms, BYJU'S represents animated content library differentiation, while Preply exemplifies the marketplace model connecting learners with tutors across time zones without geographic constraints.
| Leading Market Players |
|---|
| Kumon Institute of Education |
| Kaplan |
| TAL Education Group |
| Vedantu |
| Huntington Learning Center |
| Chegg |
| Sylvan Learning |
| Preply |
| BYJU'S |
| Others |
Supply Flow & Price Mechanics
The Singapore-Kuala Lumpur fiber corridor carries adaptive learning platform traffic at rates that compress delivery costs for Indian tier-2 city operators while amplifying price differentiation between certified STEM instructors and unaccredited freelance tutors. This bandwidth arbitrage concentrates supply chain leverage with platforms that can aggregate qualified instructor pools across multiple regulatory jurisdictions.
Pricing Analysis
Annual subscription renewals and enterprise L&D contracts drive lifetime value capture in this market. Three-tier pricing structure across premium, standard, and economy levels separates certified examination board tutors from platform-mediated generalists from self-serve content libraries. Cost compression in the economy tier intensifies because YouTube tutorial substitution erodes willingness-to-pay for commoditized test prep content. K-12 parents in Indian tier-2 cities exhibit highest price sensitivity; German corporate procurement officers demonstrate lowest sensitivity due to budgeted employee mobility programs.
Supply Chain Analysis
Contract manufacturing concentration sits with third-party content studios in Bangalore, Ho Chi Minh City, and Manila that produce animated curriculum modules for white-label platform licensing. Raw material dependencies span broadband infrastructure, cloud compute capacity, and payment gateway APIs. Single-source vulnerability concentrates in AWS and Azure hosting regions serving Southeast Asian user bases. Distribution runs through direct-to-consumer app stores and institutional procurement departments with extended sales cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is emerging from a cyclical trough driven by China's regulatory restructuring of K-12 profit-seeking models, which has reset capital allocation patterns across Asia-Pacific supplementary education.
For Market Incumbents: Insulate core revenue by pivoting credentialing services toward adult upskilling and overseas university admissions consulting, reducing exposure to SAMR's nonprofit mandates. Deepen backward integration into proprietary adaptive learning algorithm development to differentiate from marketplace competitors aggregating freelance instructor supply. For New Entrants and Emerging Players: Establish a beachhead in Vietnam's Ho Chi Minh City and Indonesia's Surabaya urban clusters where middle-class density is rising faster than established brand penetration. Target corporate learning and development procurement channels with technical certification bundles rather than competing for saturated individual consumer subscriptions in Indian metropolitan markets. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors platforms with compliant AI governance infrastructure that can absorb EU AI Act documentation burdens without architectural fragmentation. Long-term viability hinges on adaptive learning personalization engines that reduce marginal instructor costs. The signal to watch is enterprise L&D contract renewal rates displacing individual subscription churn as the dominant revenue stability indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Adaptive Learning Algorithm Development | BYJU'S and similar platforms deploy machine learning personalization to compress time-to-mastery for STEM curricula. |
| Corporate L&D Contract Procurement | Enterprise technical certification tutoring for employee mobility displaces individual consumer subscriptions as dominant B2B revenue stream. |
| Regulatory Compliance Architecture Investment | EU AI Act algorithmic transparency documentation creates competitive moats disadvantaging smaller entrants lacking governance infrastructure. |
| Geographic Franchise Licensing Expansion | Vietnam and Indonesia first-mover positioning captures rising middle-class density before local competitors consolidate urban clusters. |
| Content Library Differentiation | Animated curriculum modules and gamified learning pathways sustain parent renewal intent against free open educational resource substitution. |
Methodological Framework
Cross-validation between Ministry of Education regulatory filings and platform enrollment disclosures anchors the qualitative findings. Primary interviews with curriculum directors at supplementary education providers, procurement officers at corporate L&D departments, and parent association representatives in Indian tier-2 cities were combined with secondary validation against BharatNet infrastructure rollout reports, EU AI Act technical documentation requirements, and SAMR nonprofit restructuring mandates. Bottom-up instructor supply modeling and top-down addressable learner population estimates were triangulated to constrain forecast variance.
Calibration against historical enrollment velocity across service type, delivery mode, and end-user segments shaped the analytical framework across the analysis window. Segmentation dimensions modeled include academic tutoring versus test preparation versus skills development, in-person versus online versus hybrid delivery, and K-12 versus college versus adult versus professional end users. CAGRs were derived from enrollment trend extrapolation moderated by regulatory intervention probability assessments and broadband penetration elasticity coefficients for qualified instructor access.
Stress conditions across SAMR enforcement intensity, EU AI Act compliance cost inflation, and BharatNet deployment delays were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding parental willingness-to-pay erosion and enterprise procurement cycle elongation. Cross-checking against UGC curriculum alignment requirements and state education board supplementary instruction legitimacy criteria is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Corporate Training and Talent Development
Europe Management Consulting Services Market
Corporate Training and Talent Development
France Outplacement Services Market
Corporate Training and Talent Development
Corporate Training Market
Corporate Training and Talent Development
Global Outplacement Services Market
Corporate Training and Talent Development
Corporate Leadership Training Market
Corporate Training and Talent Development
Europe Executive Search (Headhunting) Market
Corporate Training and Talent Development
IT Training Market
Corporate Training and Talent Development
Educational Consulting and Training Market
Corporate Training and Talent Development
Europe Corporate Training Market
Corporate Training and Talent Development
Middle East and Africa Management Consulting Services Market
Corporate Training and Talent Development
Canada Outplacement Services Market
Corporate Training and Talent Development
Asia Pacific HR Professional Services Market
Corporate Training and Talent Development
Corporate Training Services Market
Corporate Training and Talent Development
Integrated Talent Management Market
Corporate Training and Talent Development
Executive Coaching Certification Market
Corporate Training and Talent Development
Europe Consulting Services Market