
 Global Cosmetic Antioxidant Market | 2026-2036
Global Cosmetic Antioxidant Market Size, Share, and Industry Trends Forecast 2026-2036
Global Cosmetic Antioxidant Market Foresight
China is narrowing the supply gap for cosmetic-grade ferulic acid and resveratrol through dedicated biotech fermentation parks in Zhejiang and Jiangsu provinces. BASF SE leverages its Ludwigshafen integrated site to sustain captive production of tocopherol derivatives for European formulators. Evonik Industries AG anchors its antioxidant portfolio on high-purity coenzyme Q10 synthesized via proprietary yeast fermentation. Croda International Plc competes through lipid-compatible vitamin C derivatives tailored for anhydrous serum systems.
Cosmetic antioxidants comprise active molecules that neutralize free radicals in skin tissue, typically formulated at concentrations between 0.5% and 20% depending on compound stability and dermal penetration profile. Their primary commercial purpose centers on extending product shelf life while delivering visible anti-aging and photoprotective benefits to consumers. Vitamin C and vitamin E dominate volume consumption due to decades of clinical validation and broad compatibility across cream and serum formulations. Ferulic acid represents the fastest-expanding category as formulators exploit its synergistic stabilization of ascorbic acid in aqueous environments. Powder and oil forms command margin premiums where heat-sensitive actives require anhydrous delivery systems to prevent oxidative degradation prior to application.
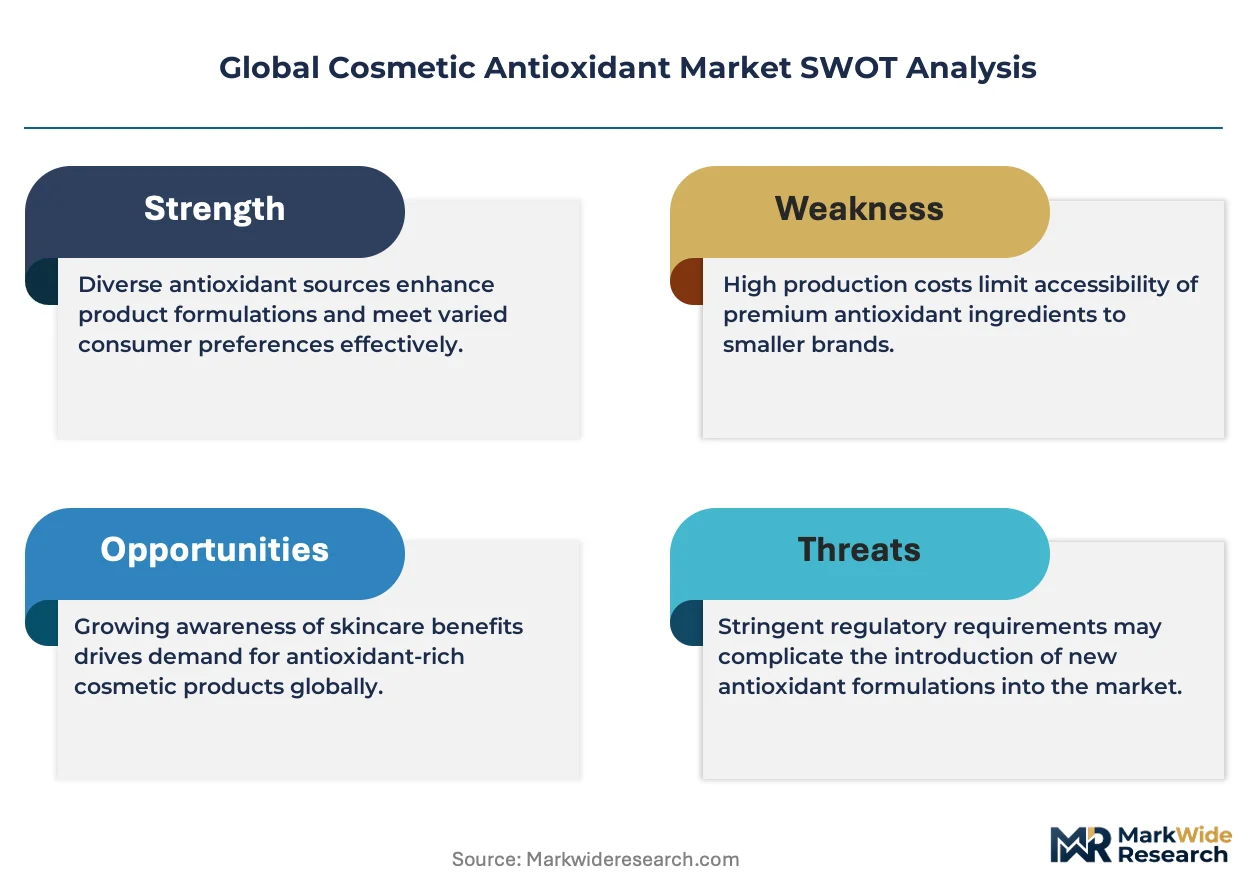
REACH registration requirements in Europe mandate full toxicological dossiers for novel antioxidant imports, while the FDA in the United States exercises post-market surveillance over structure-function claims on cosmeceutical labels. China's NMPA and SAMR enforce mandatory safety assessment protocols for imported antioxidant raw materials through the cosmetics registration and notification system. Stakeholders must monitor evolving divergence between EU Green Deal bio-based content thresholds and China's GB standards for preservative efficacy testing as these frameworks reshape formulation roadmaps and supplier qualification timelines.
Market Dynamics
Biotechnology-derived synthesis routes are displacing solvent extraction for high-purity cosmetic antioxidants, compressing production timelines from weeks to days while altering supplier qualification criteria across European and North American formulator networks.
Growth Catalysts
- REACH registration acceleration:ECHA's streamlined dossier pathways for bio-based actives are reducing market entry barriers for plant-derived antioxidant suppliers targeting European premium skincare brands.
- Dermatology clinic channel expansion:Professional treatment protocols in the United States are creating pull-through demand for clinical-grade antioxidant serums with documented stability data.
- Fermentation infrastructure:Dedicated biotech parks in Zhejiang and Jiangsu provinces are scaling cosmetic-grade resveratrol and ferulic acid output for international export.
Market Restraints
- Raw material concentration:Tocopherol precursor supply chains cluster heavily in Southeast Asian palm derivative processing, exposing formulators to agricultural yield volatility.
- Regulatory friction:Divergent GB standards for preservative efficacy testing versus EU Green Deal bio-based thresholds force dual certification investments for China-bound products.
- Substitution pressure:Synthetic peptide alternatives with antioxidant claims are capturing shelf space in mass-market retail channels where clinical validation carries less weight.
Strategic Opportunities
- Clean beauty certification tailwinds:EWG Verified and Sephora Clean standards in the United States are mandating antioxidant sourcing transparency that favors vertically integrated botanical extractors.
- Anhydrous delivery system convergence:Lipid-compatible vitamin C derivatives combined with silicone elastomer technologies are opening formulation possibilities for hot-fill cosmetic manufacturing.
- Professional channel underpenetration:Medi-spa and aesthetic clinic networks in Brazil and Mexico remain undersupplied with photostabilized antioxidant protocols validated for post-procedure application.
Industry Challenges
- Formulation chemist scarcity:Specialized expertise in ascorbic acid stabilization and pH buffering for aqueous serums remains concentrated among legacy European compounders.
- Stability testing capex:Accelerated aging chambers and HPLC validation equipment require seven-figure investments that mid-tier suppliers struggle to amortize across limited SKU counts.
- IP licensing complexity:Proprietary yeast strains for coenzyme Q10 production are locked behind exclusive fermentation licenses that block independent market entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Cosmetic Antioxidant Market |
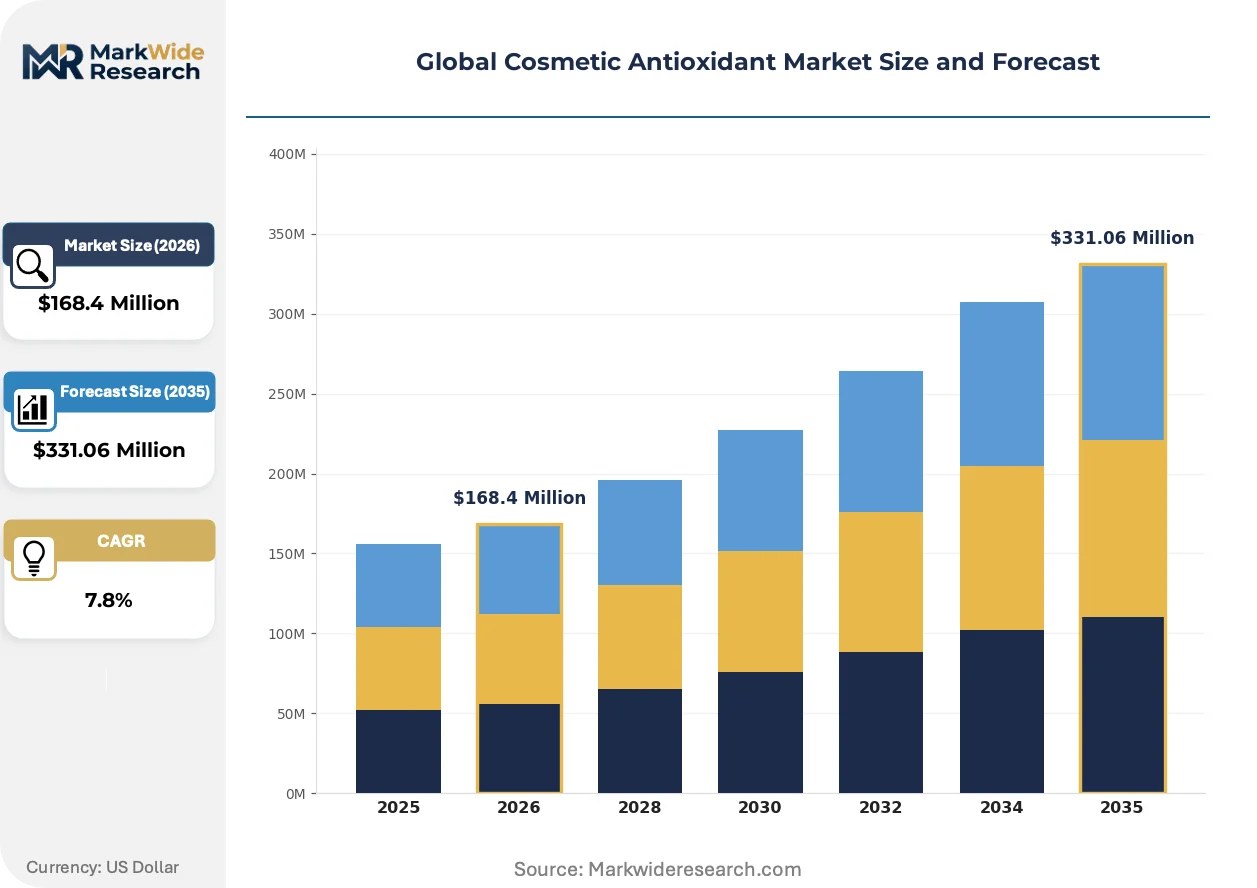
| Market Size in 2026 | $168.4 Million |
| Market Size in 2035 | $331.06 Million |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vitamin C, Vitamin E, Green Tea Extract, Coenzyme Q10, Resveratrol, Ferulic Acid Form: Cream, Serum, Lotion, Gel, Powder, Oil Application: Anti-Aging, Skin Brightening, UV Protection, Moisturizing, Acne Treatment, Wrinkle Reduction End User: Beauty Salons, Dermatology Clinics, Spas, Wellness Centers, Cosmetic Manufacturers |
| Companies Covered | BASF SE, Evonik Industries AG, Croda International Plc, Eastman Chemical Company, Wacker Chemie AG, Kemin Industries, Inc., Ashland Global Holdings, Koninklijke DSM N.V., BTSA Biotecnologias Aplicadas S.L., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Cosmetic Antioxidant Market Shifts & Advancements
Continuous flow biocatalysis and solid-state fermentation are rewriting production economics for cosmetic-grade antioxidants, collapsing the historical trade-off between purity yields and batch scale that governed solvent extraction economics.
Continuous flow biocatalysis platforms utilizing immobilized enzyme columns are enabling gram-to-tonne scale-up without process revalidation. Specialty chemical producers in Germany and Switzerland are adopting these systems for tocopherol derivative manufacturing. This manufacturing flexibility is rendering obsolete the traditional batch campaign scheduling that required six-month forward planning for antioxidant raw material procurement.
EU Green Deal bio-based content thresholds are tightening disclosure requirements for cosmetic ingredient sourcing. Formulators must now document renewable carbon content across supply tiers or risk exclusion from public procurement frameworks. Premium skincare brands with European manufacturing footprints are responding by qualifying fermentation-derived actives ahead of petroleum-sourced alternatives.
Direct-to-clinic distribution models are compressing traditional distributor margins for professional-grade antioxidant products. Aesthetic practitioners in the United States and South Korea now source stabilized ascorbic acid serums through manufacturer-managed portals that bypass regional wholesale networks. This channel shift is most visible in urban dermatology clusters where practice consolidation has concentrated purchasing authority among multi-site clinic groups.
Global Cosmetic Antioxidant Market Segmentation
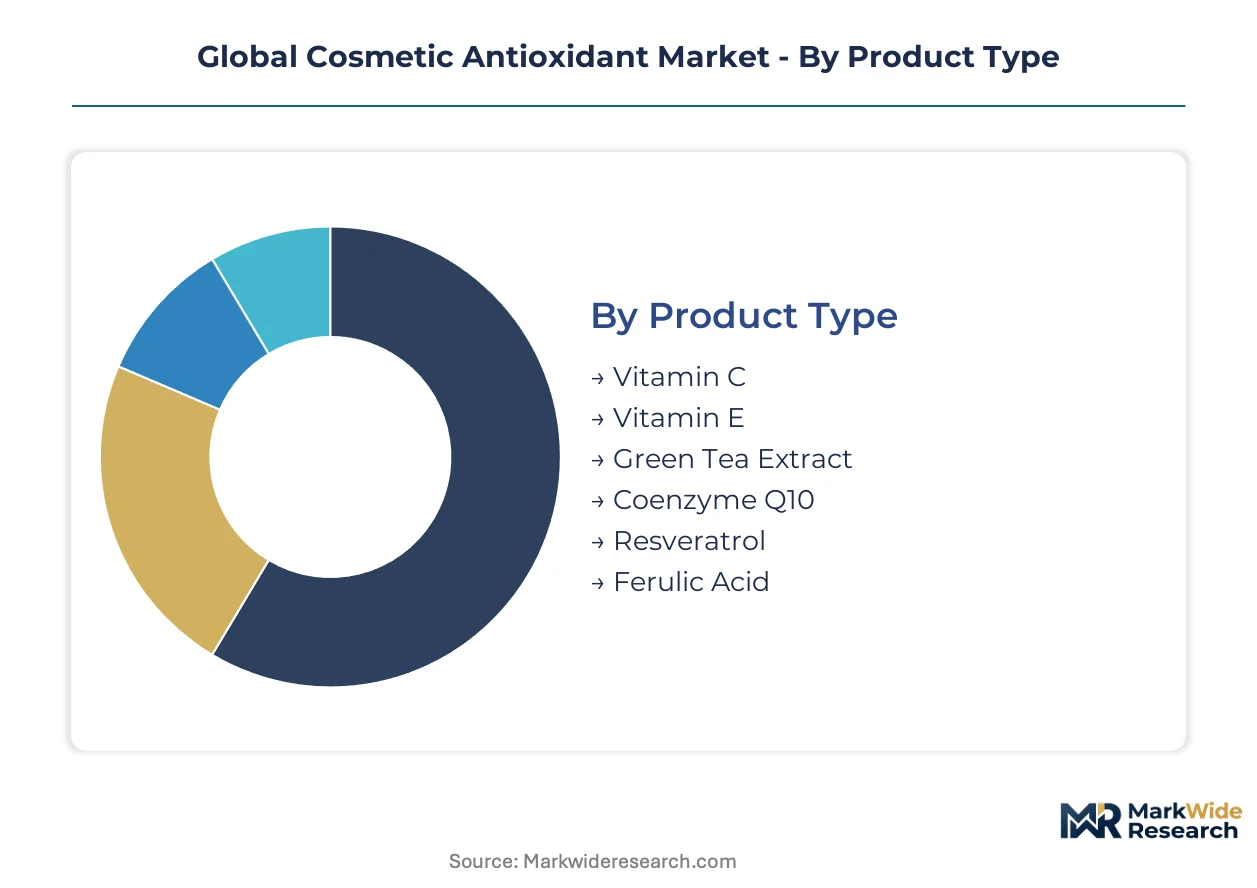
Antioxidant formulators navigate distinct technical requirements across product chemistries, delivery vehicles, and treatment protocols. Segmentation reveals where stability engineering, concentration thresholds, and channel certification standards diverge most sharply.
Product Type:
Use-case spectrum spans clinical-grade photoprotection to mass-market shelf-life extension, with solubility profiles and pH tolerance dictating formulation compatibility.
- Vitamin C:L-ascorbic acid and stabilized derivatives operate at 10-20% concentration in aqueous serums, demanding pH buffers below 3.5 for dermal penetration. Demand clusters in United States dermatology clinics where photodamage protocols require documented stability data. EWG Verified certification mandates exclude petroleum-derived stabilizers, favoring fermentation-sourced ascorbic acid.
- Ferulic Acid:Phenolic compound extracted from rice bran or synthesized via biotransformation, primarily deployed at 0.5-1% to synergistically stabilize vitamin C against oxidative degradation. Zhejiang biotech parks are scaling cosmetic-grade output for export to European premium brands facing EU Green Deal bio-based thresholds. REACH registration dossiers for plant-derived ferulic acid are accelerating versus petroleum-sourced alternatives.
- Vitamin E:Tocopherol and tocotrienol derivatives serve as lipid-phase stabilizers in anhydrous systems, with alpha-tocopherol acetate dominating volume consumption.
- Green Tea Extract:Polyphenol-rich fraction standardized for EGCG content, primarily utilized in Asian markets for anti-inflammatory positioning.
- Coenzyme Q10:Lipid-soluble quinone produced via proprietary yeast fermentation, concentrated in anti-aging creams targeting mitochondrial energy claims.
- Resveratrol:Stilbenoid compound from grape skin or biotech synthesis, positioned for longevity marketing in prestige skincare channels.
Established volume favors vitamin E; emerging adoption favors ferulic acid.
Form:
Delivery vehicle selection hinges on active stability, manufacturing heat exposure, and consumer application ritual preferences across retail and professional channels.
- Serum:Low-viscosity aqueous or anhydrous vehicles enable high active loading with rapid skin penetration, commanding premium pricing where clinical validation supports concentration claims. United States medi-spa networks are standardizing on single-use ampoule formats to eliminate oxidation risk from repeated container opening. Hot-fill manufacturing compatibility with lipid-compatible vitamin C derivatives is opening new formulation possibilities.
- Oil:Anhydrous lipid matrices protect heat-sensitive actives from hydrolytic degradation, requiring silicone elastomer technologies for elegant skin-feel. Sephora Clean certification penetration in North America favors oil-based delivery for preservative-free positioning. Brazil and Mexico aesthetic clinic networks remain undersupplied with photostabilized oil protocols validated for post-procedure application.
- Cream:Emulsion systems balancing water and lipid phases for broad consumer accessibility and moisture retention positioning.
- Lotion:Lower viscosity emulsion for body application and mass-market volume distribution.
- Gel:Hydroalcoholic or hydrogel matrices targeting oily skin segments and tropical climate preferences.
- Powder:Anhydrous active concentrates requiring consumer reconstitution, preserving stability until point of use.
Volume concentration sits with serum; margin expansion concentrates in oil.
Application:
Functional claim categories align with distinct regulatory surveillance intensities and clinical evidence requirements across cosmeceutical and cosmetic positioning.
- Anti-Aging:Collagen synthesis and free radical neutralization claims dominate antioxidant positioning, with FDA post-market surveillance targeting structure-function language on cosmeceutical labels. United States dermatology clinic expansion is pulling clinical-grade antioxidant serums with documented stability data into professional protocols. China's NMPA mandates safety assessment protocols for imported anti-aging actives through the cosmetics registration system.
- UV Protection:Photoprotective claims require photostability validation under simulated solar exposure, with ECHA REACH dossiers demanding full toxicological profiles for novel UV-protective antioxidants. European premium skincare brands are qualifying fermentation-derived actives ahead of petroleum alternatives to meet EU Green Deal bio-based thresholds.
- Skin Brightening:Tyrosinase inhibition and melanin regulation positioning, concentrated in Asian markets with distinct regulatory frameworks.
- Moisturizing:Barrier support and transepidermal water loss reduction, often secondary to primary antioxidant positioning.
- Acne Treatment:Anti-inflammatory and sebum regulation claims targeting younger demographics.
- Wrinkle Reduction:Fine line and texture improvement, overlapping with anti-aging but with distinct marketing positioning.
Regulatory scrutiny intensifies for UV protection; formulation innovation concentrates in anti-aging.
End User:
Channel structure determines certification requirements, volume scale, and technical support intensity across professional and industrial procurement.
- Dermatology Clinics:Professional treatment protocols demand batch-specific stability documentation and direct-to-clinic distribution models that bypass traditional wholesale networks. United States urban dermatology clusters with multi-site practice consolidation are concentrating purchasing authority among clinic groups sourcing through manufacturer-managed portals. FDA post-market surveillance applies heightened scrutiny to structure-function claims on clinic-dispensed products.
- Cosmetic Manufacturers:Industrial-scale procurement of antioxidant raw materials requires REACH registration compliance for European formulation and GB standards adherence for China-bound products. BASF SE's Ludwigshafen integrated site supplies captive tocopherol derivatives to European formulators navigating divergent EU-China regulatory frameworks. Dual certification investments are forcing supplier qualification timeline extensions.
- Beauty Salons:Service-oriented retail channels with moderate technical sophistication and brand-dependent procurement.
- Spas:Wellness-positioned channels emphasizing experiential application and premium pricing tolerance.
- Wellness Centers:Holistic health positioning with regulatory ambiguity between cosmetic and nutraceutical boundaries.
Procurement scale favors cosmetic manufacturers; margin premium concentrates in dermatology clinics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's chemical handling infrastructure underwrites Europe's role as the primary entry point for fermentation-derived antioxidant actives shipped from Asian biotech parks.
United States
Dermatology clinic networks in Manhattan and Los Angeles are consolidating purchasing authority through multi-site practice groups. FDA post-market surveillance applies heightened scrutiny to structure-function claims on clinic-dispensed antioxidant serums. Boston's biotechnology corridor hosts formulation chemistry specialists concentrated in ascorbic acid stabilization protocols.
China
Zhejiang and Jiangsu provinces are scaling cosmetic-grade ferulic acid and resveratrol output through dedicated fermentation parks. NMPA and SAMR enforce mandatory safety assessment protocols for imported antioxidant raw materials. Shanghai's cosmetics registration hub processes dual-certification dossiers for brands targeting both domestic and European markets.
Germany
Ludwigshafen's integrated chemical site sustains captive production of tocopherol derivatives for European formulators. ECHA REACH registration requirements mandate full toxicological dossiers for novel antioxidant imports. Bavaria's specialty chemical producers are adopting continuous flow biocatalysis platforms for gram-to-tonne manufacturing scale-up.
South Korea
Seoul's aesthetic clinic clusters source photostabilized antioxidant protocols through manufacturer-managed portals bypassing wholesale networks. MFDS regulates functional cosmetic claims with documentation requirements for anti-aging and UV protection positioning. Busan-Ulsan's chemical processing corridor concentrates lipid-compatible active manufacturing for anhydrous serum systems.
Brazil
Medi-spa networks in São Paulo and Rio de Janeiro remain undersupplied with clinical-grade antioxidant products validated for post-procedure application. ANVISA governs cosmetic ingredient safety with evolving alignment to international standards. São Paulo's formulation laboratories are developing hot-fill compatible delivery systems for regional climate conditions.
Global Cosmetic Antioxidant Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream. The market structure consolidates around integrated chemical conglomerates with captive fermentation capacity, while mid-tier suppliers compete through niche stabilization technologies and regional distribution partnerships. Three archetypes dominate: integrated petrochemical-to-specialty producers, dedicated biotechnology fermentation houses, and lipid-chemistry formulators. Competitive moves concentrate on dual-certification investments for China-EU regulatory alignment and direct-to-clinic channel bypass strategies.
Among Germany-based chemical conglomerates, BASF SE and Evonik Industries AG exemplify the integrated platform archetype with captive manufacturing infrastructure. Wacker Chemie AG represents the silicones-and-specialty tier with positioning in delivery system technologies. These three occupy positions where scale and regulatory compliance capabilities create separation from regional fermentation specialists.
| Leading Market Players |
|---|
| BASF SE |
| Evonik Industries AG |
| Croda International Plc |
| Eastman Chemical Company |
| Wacker Chemie AG |
| Kemin Industries, Inc. |
| Ashland Global Holdings |
| Koninklijke DSM N.V. |
| BTSA Biotecnologias Aplicadas S.L. |
| Others |
Supply & Pricing Matrix
Zhejiang and Jiangsu fermentation parks are expanding cosmetic-grade ferulic acid and resveratrol capacity, compressing procurement timelines for European formulators while concentrating volume leverage among integrated biotech producers. This supply concentration translates directly into pricing power for fermentation-derived actives versus petroleum-sourced alternatives facing REACH registration delays.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates antioxidant procurement, with clinical-grade serums certified for dermatology clinic channels commanding substantial premiums over mass-market raw materials. Price differentiation hinges on REACH registration completeness and EWG Verified clean beauty certification, with dual-certified materials carrying the steepest markups. Cost compression in standard-grade tocopherol derivatives is intensifying because Southeast Asian palm derivative supply volatility is forcing formulators toward contract-based long-term offtake. Cosmetic manufacturers represent the most price-sensitive buyer segment due to high-volume procurement, while medi-spa networks demonstrate lowest sensitivity where clinical validation supports therapeutic claims.
Supply Chain Analysis
Export-control regimes on immobilized enzyme column technology limit continuous flow biocatalysis platform transfers from German and Swiss specialty producers to Asian manufacturing partners. Geographic supply concentration centers on China for fermentation-derived actives, Germany for tocopherol derivatives, and the United States for clinical-grade serum formulations. Raw material dependencies draw from rice bran for ferulic acid extraction, palm derivatives for tocopherol precursors, and proprietary yeast strains for coenzyme Q10 production. Single-source vulnerability from Evonik's exclusive fermentation licenses for high-purity coenzyme Q10 creates supply chain risk. Distribution runs through manufacturer-managed portals for dermatology clinic channels, bypassing traditional wholesale networks in consolidated urban markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market's defensive moat rests on regulatory entrenchment: REACH dossier requirements and dual-certification investments for China-EU alignment create switching costs that lock in qualified suppliers and deter rapid competitive displacement.
For Market Incumbents: Pre-empt synthetic peptide substitution pressure by securing exclusive fermentation licenses for next-generation yeast strains before proprietary strain IP windows close. Accelerate backward integration into Zhejiang biotech park partnerships to capture captive supply of cosmetic-grade resveratrol and ferulic acid. Lock in direct-to-clinic distribution contracts with consolidating multi-site dermatology groups in Manhattan and Los Angeles to forestall channel bypass by emerging competitors. For New Entrants and Emerging Players: Brazil and Mexico medi-spa networks represent the most penetrable geographic white-space, with ANVISA regulatory alignment creating lower entry barriers than dual EU-China certification requirements. Target photostabilized oil-based antioxidant protocols validated for post-procedure application, where established suppliers remain undersupplied. Deploy hot-fill manufacturing compatibility as the core go-to-market angle, leveraging regional climate conditions in São Paulo formulation laboratories to differentiate from aqueous serum incumbents. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among vertically integrated fermentation houses with captive strain libraries and established REACH dossiers, where long-term supply agreements with European premium skincare brands generate predictable cash flows across extended horizons. Acquisition targets should display proprietary biocatalysis platforms and existing clean beauty certifications. The signal to watch is ECHA's streamlined bio-based active registration pathway uptake rates, which would indicate accelerating market entry for plant-derived alternatives and potential margin compression for petroleum-sourced incumbents.| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Certification Investment | REACH and GB standards alignment opens simultaneous EU and China market access for fermentation-derived actives. |
| Direct-to-Clinic Distribution Launch | Manufacturer-managed portals bypass wholesale margins in consolidated US dermatology practice clusters. |
| Continuous Flow Biocatalysis Scale-Up | Immobilized enzyme platforms collapse production timelines from weeks to days for tocopherol derivatives. |
| Proprietary Strain Acquisition | Exclusive yeast fermentation licenses for coenzyme Q10 production block independent market entry by competitors. |
| Anhydrous Delivery System Development | Lipid-compatible vitamin C derivatives combined with silicone elastomer technologies enable hot-fill manufacturing compatibility. |
Research Methodology
A standing panel of formulation chemistry directors, dermatology clinic procurement leads, biotech fermentation plant managers, and clean beauty certification auditors provided ongoing calibration throughout the study period. Primary interviews with European compounders specializing in ascorbic acid stabilization and pH buffering were cross-validated against secondary sources including ECHA REACH registration databases, NMPA cosmetics notification filings, and customs trade data for antioxidant raw material flows. Bottom-up volume estimates from individual biotech park capacity announcements were triangulated against top-down market sizing derived from premium skincare brand portfolio expansions.
Scenario-bracketing around regulatory pathway acceleration and synthetic peptide substitution rates framed the analytical approach across the projection horizon. Segmentation dimensions modeled included antioxidant chemistry type, delivery vehicle form, functional application claim, and end-user channel structure. CAGRs were derived from elasticity-adjusted demand curves incorporating dermatology clinic channel expansion rates and clean beauty certification penetration trends. Industry-specific forecast inputs encompassed fermentation capacity buildout timelines in Zhejiang and Jiangsu provinces and EWG Verified standard adoption velocity in North American retail.
Macroeconomic conditions sit as an overlay; deviation in agricultural commodity prices for palm derivatives and currency volatility affecting Asian export competitiveness would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory pathway streamlining and biotech fermentation yield improvements. Material shifts in EU Green Deal bio-based content threshold enforcement or China's GB standards divergence would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cosmetics & Skincare
France Lip Care Products Market
Cosmetics & Skincare
Liquid Lipstick Market
Cosmetics & Skincare
Eye Shadow Stick Market
Cosmetics & Skincare
Sweden Cosmetics Products Market
Cosmetics & Skincare
Natural and Organic Lipstick Market
Cosmetics & Skincare
North America Deodorants Market
Cosmetics & Skincare
China Skincare Market
Cosmetics & Skincare
Israel Cosmetics Market
Cosmetics & Skincare
Makeup Remover Pen Market
Cosmetics & Skincare
Body Blurring Cosmetics Market
Cosmetics & Skincare
Japan Bath Soap Market
Cosmetics & Skincare
Eyeliner Market
Cosmetics & Skincare
Cold Pressed Soap Market
Cosmetics & Skincare
GCC Bath Soap Market
Cosmetics & Skincare
United Arab Emirates Cosmetic Products Market
Cosmetics & Skincare
Halal Cosmetic Products Market