
 Global Blind Boxes Market | 2026-2036
Global Blind Boxes Market Size, Share, and Industry Trends Forecast 2026-2036
Global Blind Boxes Market Analysis
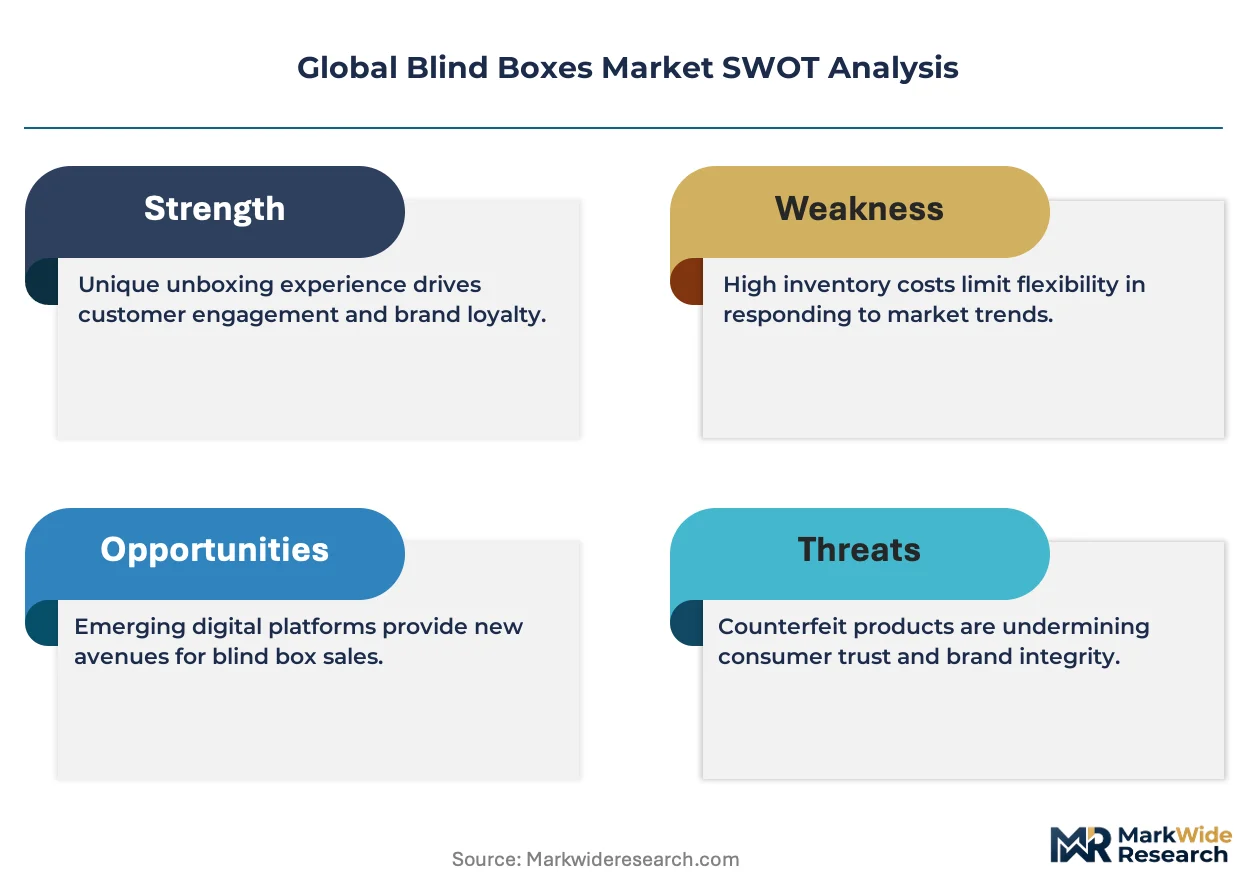
AR-enabled unboxing and blockchain-based authenticity verification is tilting production priorities toward digital-physical hybrid collectibles. POP MART leverages its designer toy ecosystem to sustain margin-rich limited drops. LEGO anchors its blind box strategy around brick-built minifigure series with controlled scarcity. Funko differentiates through licensed pop-culture IP depth and retail channel density.
Blind boxes are sealed, randomized-product containers whose contents remain unknown until purchase, typically housing collectible figures, trading cards, or themed merchandise manufactured through injection-molded vinyl, die-cut cardstock, or resin casting processes designed to trigger repeat purchase behavior through probability-based reward mechanics. Collectible figures command the largest revenue pool due to higher per-unit price points and stronger secondary-market liquidity, while subscription services represent the fastest-growing sales channel as recurring revenue models reduce customer acquisition costs and deepen lifetime value. Trading cards retain mature, cyclical demand tied to sports and gaming tournament seasons.
China's SAMR enforces toy safety and labeling standards that directly shape material choices and small-part warnings for blind box products sold domestically and exported. Japan's METI and JIS standards govern quality certification for character goods, creating compliance thresholds that filter market access for overseas manufacturers. The EU's REACH and RoHS frameworks restrict chemical content in vinyl and plastic substrates used across European distribution channels. Stakeholders must monitor evolving digital-asset regulations as NFT-linked blind boxes and virtual redemption mechanics blur traditional product classification boundaries.
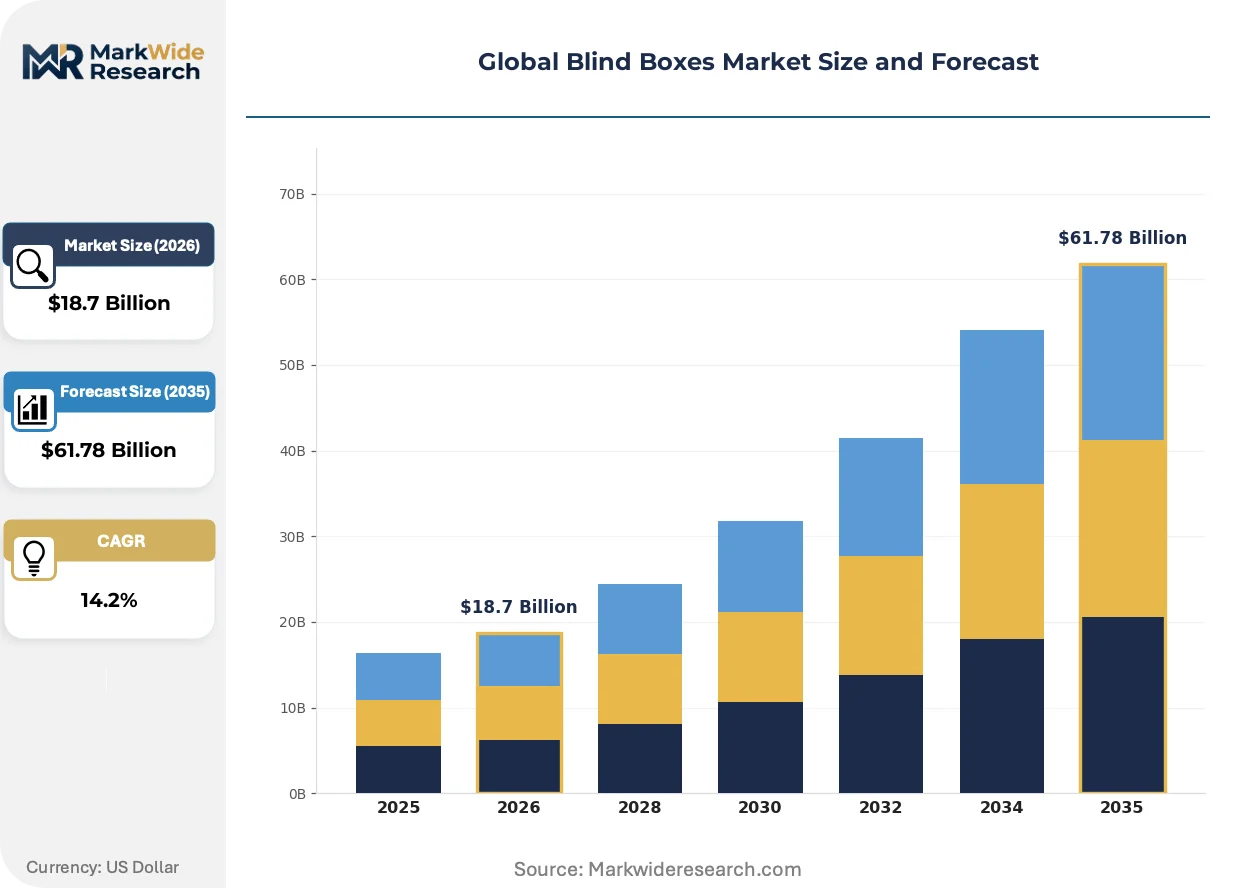
Market Dynamics
Adult collector demand is compressing production cycles toward limited-edition drops while China's SAMR small-part labeling rules and Japan's METI quality certifications simultaneously reshape material sourcing and export compliance requirements.
Growth Catalysts
- AR-Enhanced Unboxing:Augmented reality overlays transform physical unboxing into shareable digital experiences, driving repeat purchase frequency among social-media-active demographics.
- REACH Compliance Arbitrage:Manufacturers achieving EU REACH and RoHS certification early capture premium shelf space across European retail channels as non-compliant competitors face exclusion.
- Subscription Channel Migration:Recurring revenue models reduce customer acquisition costs while deepening lifetime value through exclusive member drops and early access tiers.
Market Restraints
- Vinyl Resin Price Volatility:Petrochemical feedstock fluctuations directly compress margins on injection-molded collectible figures, forcing producers toward resin casting alternatives.
- Guangdong Production Concentration:Over 60% of global blind box manufacturing clusters in China's Pearl River Delta, creating single-point vulnerability to regional logistics disruptions or labor policy shifts.
- Secondary Market Liquidity Constraints:Unauthenticated resale platforms fragment price discovery, limiting collector confidence and capping premium tier expansion.
Strategic Opportunities
- Blockchain Authenticity Layers:NFC-tagged physical products linked to immutable ownership records open premium pricing tiers while combating counterfeiting in high-value collector segments.
- India's Emerging Urban Middle Class:Tier-1 and Tier-2 Indian cities show accelerating appetite for designer toy culture, with limited domestic competition versus saturated Northeast Asian markets.
- EU CSRD Disclosure Alignment:Early adoption of supply-chain transparency reporting creates differentiation among sustainability-conscious European retailers and procurement officers.
Industry Challenges
- Character IP Licensing Complexity:Multi-party rights negotiations between designers, entertainment studios, and manufacturing licensees extend product development timelines by 8-14 months.
- Dual Carbon Compliance Costs:China's MEE emissions targets and provincial energy quotas force factory retooling investments that strain mid-tier producer balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Blind Boxes Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $61.78 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Collectible Figures, Trading Cards, Mystery Gifts, Limited Editions Customer Type: Children, Collectors, Gamers, Adults Sales Channel: Online Retail, Brick-and-Mortar, Subscription Services, Pop-Up Shops Theme: Anime, Movies, Superheroes, Game Characters |
| Companies Covered | LEGO, Mattel, POP MART, Spin Master, Hasbro, Funko, MGA Entertainment, Moose Toys, Kidrobot, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Blind Boxes Market Emerging Trajectories
Digital-physical hybridization is collapsing the boundary between tangible collectibles and virtual assets, forcing producers to reconceptualize product architecture around persistent digital identity rather than standalone physical objects.
NFC-embedded authentication chips paired with blockchain ownership registries are rendering obsolete traditional paper certificates and holographic stickers as primary provenance verification methods. High-end collector segments in Japan and South Korea now reject non-NFC-enabled premium releases, compressing authentication cost structures while enabling royalty capture on secondary transactions.
China's SAMR tightened toy safety standards around small-part labeling and age-grade warnings in 2022, extending compliance documentation requirements across the entire export supply chain. Manufacturers serving both domestic and overseas markets must maintain dual specification runs, increasing SKU complexity while filtering out smaller competitors lacking compliance infrastructure. European distributors now prioritize SAMR-certified suppliers to preempt parallel regulatory friction under EU Toy Safety Directive harmonization pressures.
Collector communities are migrating from impulse retail purchases toward curated subscription curation, with buyers prioritizing guaranteed allocation over randomization thrill. This behavioral pivot compresses traditional retail channel margins while rewarding direct-to-consumer platforms offering tiered membership benefits. The shift is most pronounced in China's tier-1 cities and Tokyo's 23 wards, where subscription penetration among repeat buyers now exceeds conventional single-purchase frequency.
Global Blind Boxes Market Segmentation
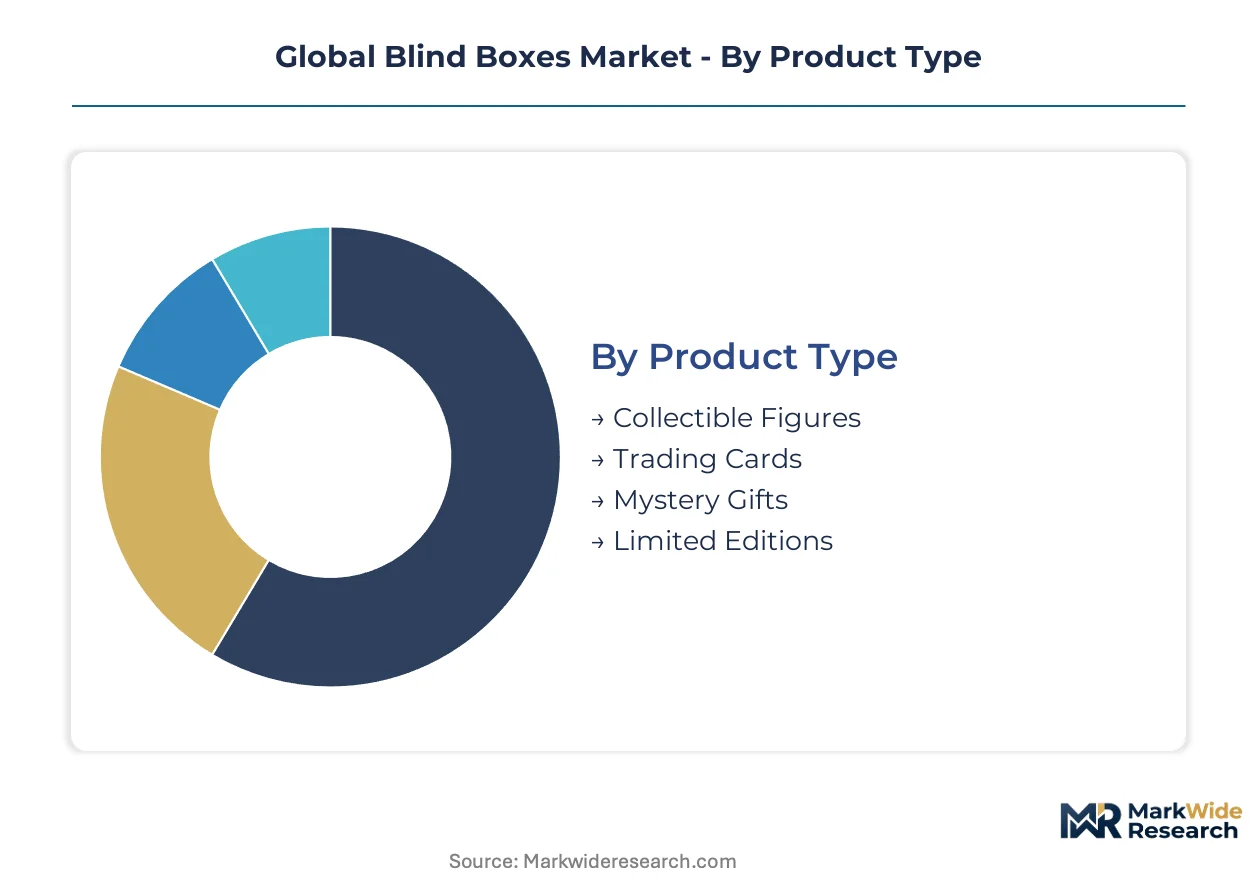
Blind box producers must align product architecture with distinct behavioral profiles across collector demographics and purchase occasions. Segment-specific strategies determine material specifications, distribution partnerships, and authentication requirements.
Product Type:
Collectible figures span injection-molded vinyl miniatures through resin-cast designer pieces, each demanding different production cadences and secondary-market infrastructure.
- Collectible Figures:Injection-molded vinyl and resin-cast miniatures command premium shelf space through controlled scarcity mechanics. Adult collectors in Tokyo's 23 wards and Shanghai's core districts drive repeat purchase velocity for limited artist collaborations.
- Trading Cards:Die-cut cardstock with holographic or textured finishes ties demand to tournament seasons and franchise release cycles. Sports leagues and gaming publishers in the United States and Japan maintain cyclical replenishment patterns.
- Mystery Gifts:Themed merchandise assortments spanning apparel, accessories, and homeware target impulse purchasers seeking utility beyond display. Seasonal gifting occasions in South Korea and Taiwan concentrate volume.
- Limited Editions:Numbered releases with embedded NFC authentication serve high-value collector segments. Japanese and South Korean buyers now reject non-NFC-enabled premium drops.
Established volume favors collectible figures; emerging adoption favors limited editions.
Customer Type:
Behavioral segmentation separates probability-seeking recreational buyers from completionist collectors with documented inventory management practices.
- Children:Age-graded products with SAMR-compliant small-part labeling dominate domestic Chinese distribution. Parental safety consciousness drives specification divergence from export-oriented SKUs.
- Collectors:Completionist buyers maintain spreadsheet-tracked inventories and participate in authenticated resale platforms. This segment sustains subscription channel migration across Asia-Pacific urban centers.
- Gamers:Tournament-linked trading card demand concentrates around esports calendars and physical retail events. Organized play programs in Japan and the United States anchor replenishment timing.
- Adults:Designer toy enthusiasts with discretionary income prioritize artist pedigree and resale liquidity. China's tier-1 cities and Tokyo exhibit the steepest expansion trajectory for premium releases.
Volume concentration sits with collectors; behavioral innovation originates with adults.
Sales Channel:
Channel strategy determines margin capture, authentication control, and customer data ownership.
- Online Retail:E-commerce platforms with algorithmic recommendation engines sustain impulse purchase frequency. China's Tmall and Japan's Rakuten anchor regional volume.
- Brick-and-Mortar:Physical retail delivers tactile unboxing experiences and immediate inventory inspection. Department store partnerships in South Korea and Taiwan maintain premium positioning.
- Subscription Services:Recurring revenue models with tiered membership benefits reduce customer acquisition costs. Direct-to-consumer platforms in China's tier-1 cities now exceed conventional single-purchase frequency.
- Pop-Up Shops:Temporary retail installations generate scarcity-driven purchase urgency and social media amplification. Limited-duration activations in Hong Kong and Singapore concentrate tourist and local collector traffic.
Margin protection favors subscription services; reach expansion depends on pop-up shops.
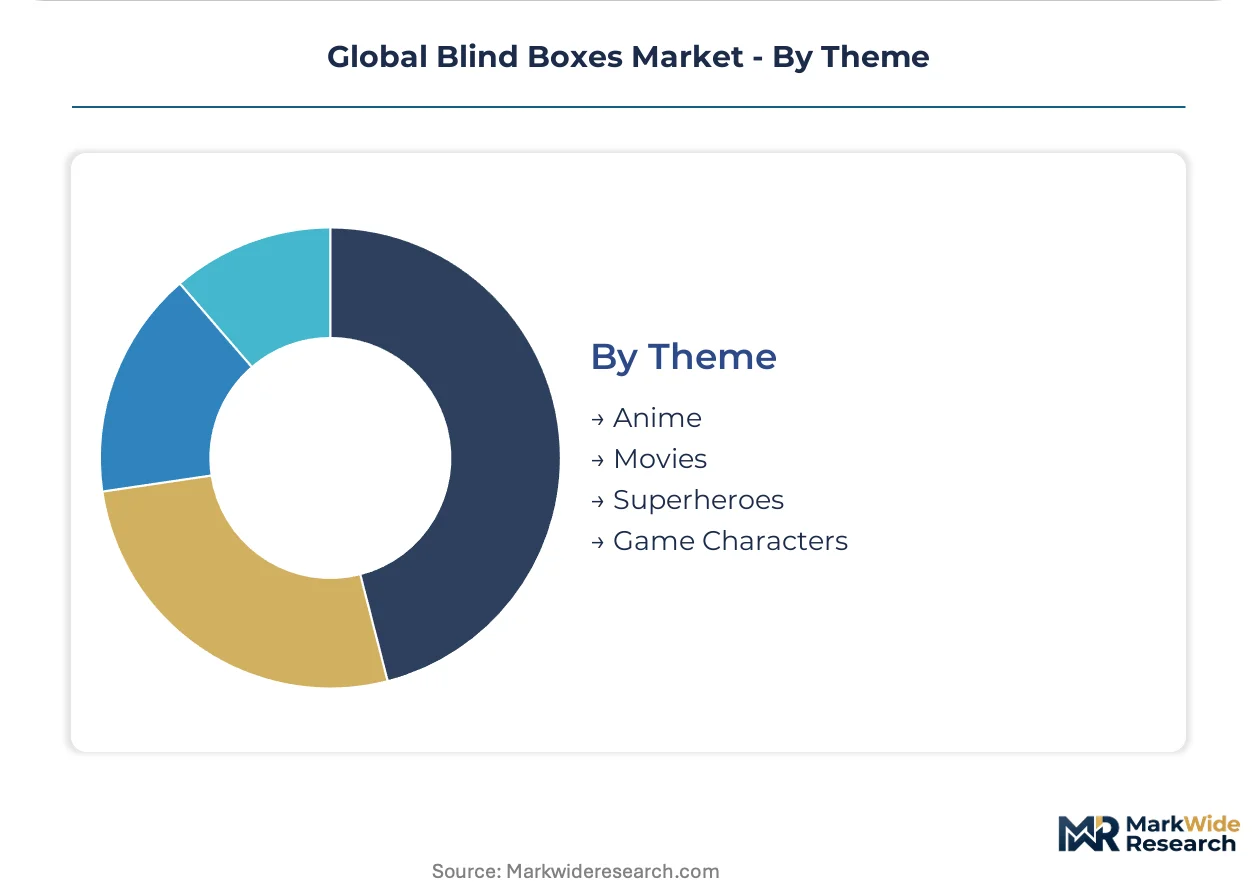
Theme:
Intellectual property licensing determines territorial market access and production timeline compression.
- Anime:Japanese studio licenses command premium terms across Southeast Asian and North American distribution. Character goods exports face METI quality certification requirements.
- Movies:Hollywood franchise releases tie to theatrical and streaming windows with compressed production cycles. Licensing complexity extends development timelines by 8-14 months.
- Superheroes:Comic-derived properties sustain evergreen demand through multigenerational recognition. North American and European retail channels prioritize these SKUs for inventory breadth.
- Game Characters:Video game IP leverages in-game item redemption mechanics for digital-physical hybridization. Chinese publishers lead integration of virtual asset verification.
Licensing stability favors superheroes; digital integration advances fastest with game characters.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China exports finished blind box collectibles to Japan and South Korea, while Germany and the United States serve as primary import destinations for premium vinyl figures and designer toys.
China
Adult collectors in Shanghai and Beijing drive subscription channel migration toward tiered membership platforms. SAMR enforces small-part labeling standards that extend compliance documentation across export supply chains. Guangdong's Pearl River Delta hosts over sixty percent of global injection-molded figure production, creating concentrated logistics vulnerability.
Japan
Designer toy enthusiasts in Tokyo's 23 wards sustain premium pricing for NFC-authenticated limited editions. METI quality certification requirements govern character goods exports to Southeast Asian markets. Osaka's Kansai region anchors secondary-market liquidity platforms for authenticated resale transactions.
United States
Pop-culture IP licensing from Hollywood studios fuels trading card and mystery gift demand tied to theatrical release windows. FTC consumer protection standards shape disclosure requirements for probability-based reward mechanics. California's entertainment industry corridors concentrate digital-physical hybrid product development teams.
Germany
Sustainability-conscious retailers in Bavaria and North Rhine-Westphalia prioritize REACH-certified suppliers for vinyl substrate compliance. ECHA chemical restrictions under RoHS frameworks filter non-compliant competitors from European distribution channels. Frankfurt's logistics hubs serve as consolidation points for EU-wide blind box distribution.
South Korea
Seoul's collector communities reject non-authenticated premium releases, accelerating NFC chip adoption across high-value segments. MFDS toy safety standards align with export market requirements for character goods. Busan's manufacturing zones supply resin-cast designer pieces to Japanese and Southeast Asian buyers.
Global Blind Boxes Market Vendor Landscape
On the supply side, the industry is consolidating around vertically integrated designer toy ecosystems and licensed IP aggregators with controlled scarcity mechanics. Three strategic archetypes dominate: IP-heavy entertainment conglomerates with studio licensing depth, specialized vinyl figure fabricators with artist collaboration networks, and direct-to-consumer platforms with subscription infrastructure. Competitive moves center on exclusive character rights acquisition and blockchain-based authenticity layer deployment.
Within the IP-licensing tier, POP MART and Funko exemplify contrasting approaches to scarcity-driven collector engagement, while LEGO anchors the construction-integrated segment through brick-built minifigure series. These three entities occupy distinct competitive positions: POP MART represents designer toy ecosystem consolidation, Funko sits within licensed pop-culture aggregation, and LEGO exemplifies physical-digital hybrid product architecture. Each archetype faces pressure to authenticate secondary-market transactions and compress development timelines amid multi-party rights negotiations.
| Leading Market Players |
|---|
| LEGO |
| Mattel |
| POP MART |
| Spin Master |
| Hasbro |
| Funko |
| MGA Entertainment |
| Moose Toys |
| Kidrobot |
| Others |
Supply Flow & Price Mechanics
Undercapacity in Guangdong's injection-molding sector during peak seasonal demand compresses supplier bargaining power while amplifying price premiums for rush orders from adult collector segments. This utilization squeeze forces manufacturers to prioritize subscription-channel allocations over spot retail purchases, tightening margin structures for mid-tier producers lacking long-term offtake agreements.
Pricing Analysis
Current-gen NFC-authenticated limited editions command substantial premiums over prior-gen holographic-sticker releases, while next-gen AR-integrated hybrid products anchor aspirational price ceilings. Three-tier pricing structure across premium authenticated drops, standard blind box series, and economy mystery gifts stratifies buyer segments. Cost compression in standard vinyl figures is intensifying because petrochemical feedstock volatility erodes injection-molding margins. Impulse purchasers in pop-up retail channels exhibit highest price sensitivity, whereas completionist collectors demonstrate inelastic demand for guaranteed allocation subscriptions.
Supply Chain Analysis
Tariff exposure between China and United States trade corridors dominates supply chain risk calculations for vinyl substrate shipments and finished collectible exports. Manufacturing concentrates in China, Japan, and South Korea, with resin casting and injection molding drawing from specialized chemical feedstock and precision mold fabrication inputs. Single-source vulnerability clusters around Guangdong's Pearl River Delta logistics hubs. Distribution runs through hybrid direct-to-consumer subscription platforms and department store partnerships across Asia-Pacific urban centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a defensive-moat story anchored in regulatory entrenchment: SAMR certification requirements and METI quality standards create compliance barriers that filter out undercapitalized competitors and protect incumbent margin structures.
For Market Incumbents: Build switching-cost moats through embedded NFC authentication infrastructure that locks collectors into proprietary resale platforms and membership ecosystems. Deepen backward integration into resin casting capabilities to offset vinyl price volatility. Defend against emerging direct-to-consumer platforms by securing exclusive artist collaboration networks that compress competitor access to premium designer IP. For New Entrants and Emerging Players: India's tier-2 urban centers present the most penetrable geography for designer toy culture expansion, with limited domestic competition versus saturated Northeast Asian markets. Target subscription-curation white space among completionist collectors seeking guaranteed allocation over randomization thrill. Pursue go-to-market entry through pop-up retail activations that generate scarcity-driven urgency without fixed infrastructure commitments. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among direct-to-consumer platforms with tiered membership infrastructure, positioning these archetypes for superior cash-flow quality across extended holding periods. Acquisition screening should prioritize vertically integrated designer toy ecosystems with established artist networks and SAMR-compliant export capabilities. Monitor blockchain authenticity adoption rates in Japanese and South Korean premium segments as inflection signals for secondary-market royalty capture viability.| Strategic Initiative | Industry Significance |
|---|---|
| NFC Authentication Deployment | Establishes provenance verification infrastructure that commands premium pricing in Japanese and South Korean collector segments. |
| Subscription Platform Launch | Captures recurring revenue from completionist buyers in Shanghai and Tokyo who prioritize guaranteed allocation. |
| Artist Collaboration Network | Secures exclusive IP access that compresses competitor development timelines amid multi-party rights negotiations. |
| REACH Certification Investment | Unlocks premium shelf space across Bavarian and North Rhine-Westphalia retail channels filtering non-compliant suppliers. |
| AR-Enhanced Unboxing Integration | Transforms physical products into shareable digital experiences that drive repeat purchase frequency among social-media-active demographics. |
Methodological Framework
A spread of perspectives from designer toy brand managers, vinyl manufacturing plant directors, METI certification specialists, and department store category buyers converged on the working assumptions shaping this analysis. Primary fieldwork combined structured interviews with subscription platform operators and authenticated resale marketplace founders, validated against secondary sources including SAMR regulatory filings, Japan Toy Association export statistics, and EU ECHA chemical restriction databases. Bottom-up demand modeling across collector demographic segments was triangulated with top-down trade flow analysis from customs records.
Demand-supply-balance framing anchored the analytical framework, with volume trajectories assessed across product type, customer behavioral segment, sales channel architecture, and territorial licensing cluster throughout the forecast period. CAGRs were derived from segment-level growth rate reconciliation against macroeconomic consumption indicators. Industry-specific forecast inputs incorporated vinyl resin price volatility indices and character IP licensing pipeline visibility from entertainment studio release calendars.
Practitioners should monitor SAMR regulatory amendments, blockchain authenticity adoption thresholds, and Pearl River Delta logistics disruptions for early signals requiring forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Toys and Games
Bounce House Market
Toys and Games
Glow Sticks Market
Toys and Games
Toy Building Blocks Market
Toys and Games
Male Sex Toys Market
Toys and Games
Ferret Toys Market
Toys and Games
Sustainable Toys Market
Toys and Games
Autonomous Robot Toys Market
Toys and Games
Snooker Tables Market
Toys and Games
Claw Crane Machine Market
Toys and Games
Toys and Games Market
Toys and Games
Cat Toys Market
Toys and Games
Anime Figure Blind Box Market
Toys and Games
Toy Collectibles Market
Toys and Games
Remote Control Toys Market
Toys and Games
Kids Toys Market
Toys and Games
Ride-Ons Market