
 Football Kits Market | 2026-2036
Football Kits Market Size, Share, and Industry Trends Forecast 2026-2036
Football Kits Market Insights
The EU Green Deal is rebalancing procurement criteria across European football leagues, forcing suppliers to certify recycled content thresholds and eliminate perfluorinated chemicals from finishing treatments. Nike leverages its vertically controlled dyeing facilities to meet batch-level traceability mandates. Adidas anchors its competitive stance through long-term federation partnerships that span multiple tournament cycles. Macron specializes in mid-tier club supply, where shorter production runs and regional league density sustain margin capture outside the elite tier.
Football kits comprise engineered apparel systems designed for high-intensity athletic performance, typically constructed from 100-150 gsm knitted polyester with sublimated or heat-transferred crest applications to maintain breathability across the torso and underarm panels. Their primary commercial purpose spans match-day identity, fan replica commerce, and training-segment brand extension. Home kits dominate volume commitments through multi-season club contracts, while third kits generate disproportionate margin through limited-drop scarcity models. Polyester maintains material leadership due to sublimation compatibility and durability, though mesh panel integration is expanding as clubs specify thermoregulation for summer tournament schedules.
The EU ECHA enforces REACH restrictions on azo dyes and nickel-release components in sportswear trim, compelling suppliers to reformulate colorant chemistries and metal hardware specifications. The UK's Competition and Markets Authority scrutinizes replica pricing parity and consumer transparency in kit release calendars. Stakeholders must monitor how emerging extended producer responsibility frameworks for textiles reshape cost allocation between clubs, manufacturers, and end consumers.
Market Dynamics
EU Green Deal textile mandates are compressing supplier margins while forcing rapid reformulation of polyester chemistries and dyeing processes across European football kit manufacturing.
Growth Catalysts
- REACH compliance deadlines:ECHA restrictions on azo dyes and nickel-release components are accelerating supplier consolidation as smaller dye houses exit rather than reformulate.
- Recycled polyester certification:Post-consumer plastic feedstock traceability requirements under EU Green Deal procurement rules are creating first-mover advantages for vertically integrated textile groups.
- Club licensing volume concentration:England and Germany's top-tier leagues are expanding kit refresh cycles to capture fan merchandise revenue through limited-drop scarcity models.
Market Restraints
- Petrochemical input volatility:Virgin and recycled polyester pellet pricing fluctuates with crude oil derivatives, compressing margin predictability for multi-season club contracts.
- Waterless dyeing capex thresholds:Supercritical CO2 dyeing equipment requires capital deployment that mid-tier suppliers cannot access, concentrating production among capital-rich manufacturers.
- Perfluorinated chemical elimination:ECHA restrictions on PFAS in finishing treatments remove durable water-repellent performance characteristics that clubs specified for all-weather training kits.
Strategic Opportunities
- Extended producer responsibility frameworks:EU textile waste directives are creating closed-loop take-back service revenue streams for manufacturers with reverse logistics infrastructure.
- Thermoregulation mesh integration:Summer tournament schedules in Qatar and southern US markets are driving specification of zonal ventilation panels as premium kit differentiators.
- Direct-to-consumer channel capture:Club-owned e-commerce platforms are disintermediating traditional sporting goods retail, enabling margin recapture and first-party data accumulation.
Industry Challenges
- Batch-level traceability system integration:EU Green Deal documentation requirements demand ERP upgrades that legacy textile manufacturers lack technical staff to implement.
- Sublimation colorfastness certification timelines:ISO 105-C06 wash testing protocols extend product development cycles, delaying kit launches past optimal retail windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Football Kits Market |
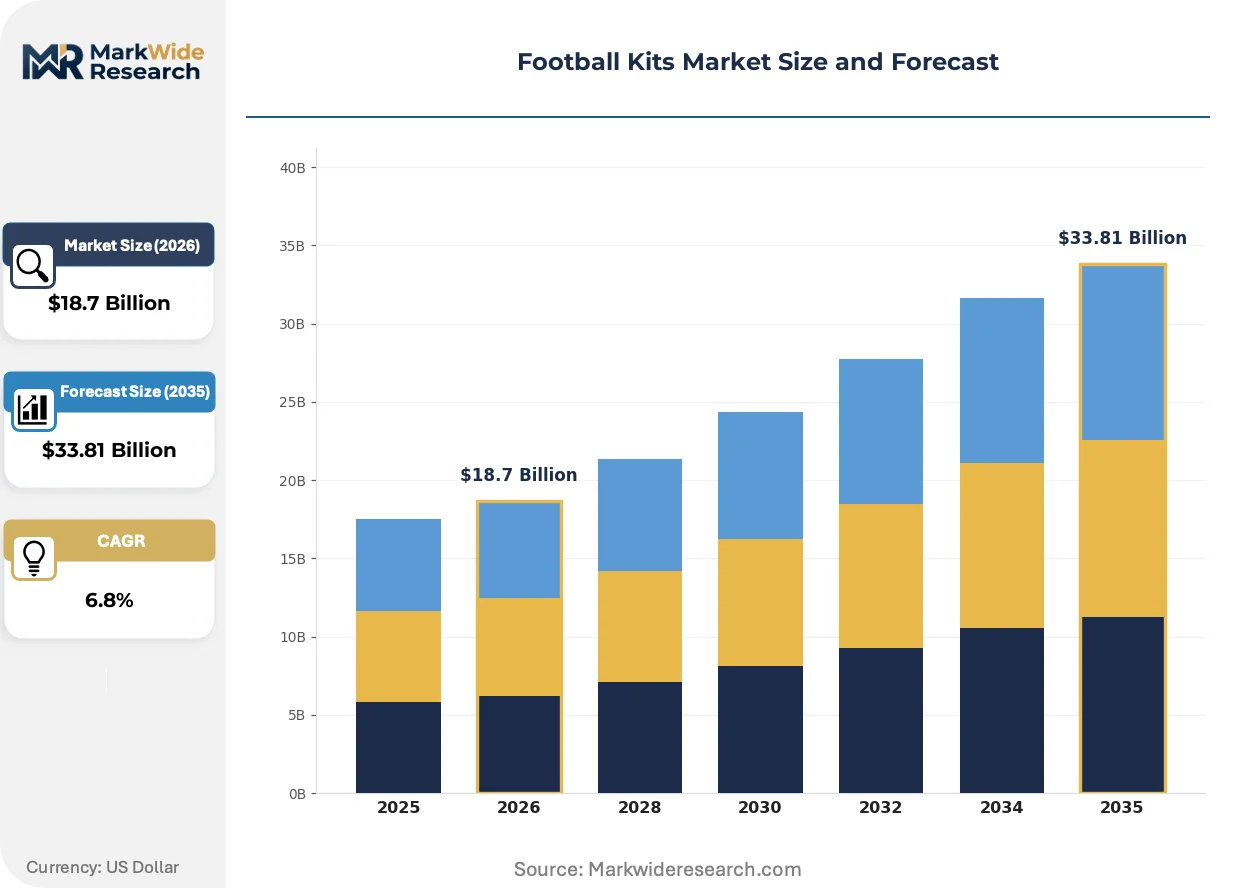
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Home Kits, Away Kits, Third Kits, Training Kits Material: Polyester, Cotton, Blends, Mesh Feature: Moisture-Wicking, Lightweight, Breathable, Stretchable End User: Youth Players, Adult Players, Professional Teams, Amateur Teams |
| Companies Covered | Macron, New Balance, Nike, Under Armour, Joma, adidas, Kappa, Umbro, PUMA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Football Kits Market Trends and Innovations
Waterless dyeing technologies and recycled fiber traceability systems are compressing the competitive set while reshaping procurement criteria across European football supply chains.
Sublimation printing is consolidating its position as the dominant crest application method for match-day and replica kits. Premier League and Bundesliga clubs are specifying sublimated designs for 100% of home and away kits to eliminate embroidered patch weight and maintain breathability across torso panels. This technology is consolidating supplier tiers by rendering traditional embroidery houses obsolete in the performance kit segment.
EU Green Deal textile sustainability requirements are mandating recycled content thresholds and chemical disclosure across all public procurement. REACH restrictions on azo dyes and nickel-release components are forcing reformulation of colorant chemistries and metal hardware specifications. English and German club suppliers are responding fastest due to concentration of federation purchasing power and early adoption of batch-level traceability mandates.
Fan purchasing behavior is fragmenting across generational lines, with younger demographics prioritizing limited-drop authenticity over annual refresh cycles. Club e-commerce platforms and resale marketplaces are capturing volume that traditional sporting goods retailers previously dominated. This shift is most visible in England, where club-owned channels now account for the majority of third kit sales through scarcity-driven release calendars.
Football Kits Market Segmentation
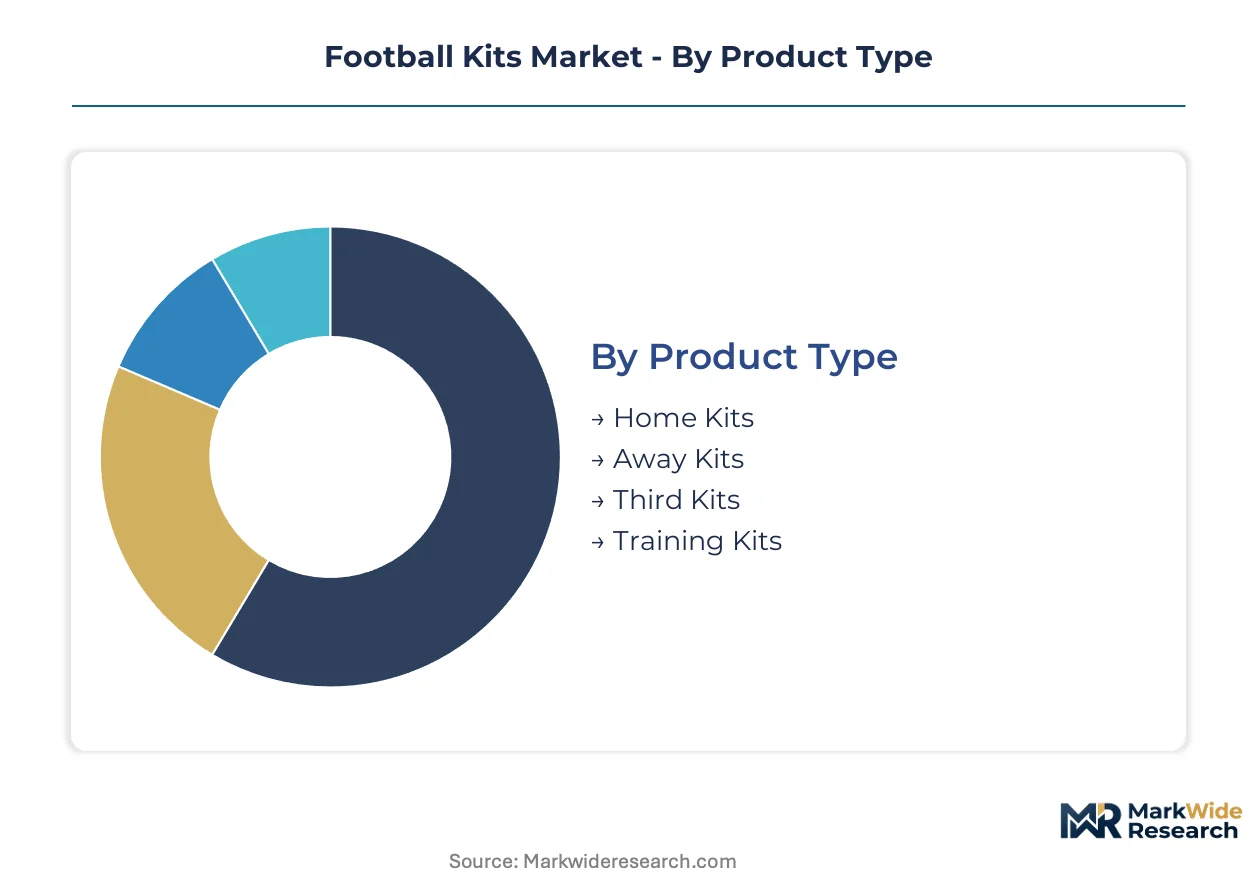
Football kit segmentation reveals how procurement criteria fragment across performance tiers and commercial applications. Manufacturers configure production lines differently for each category, with material specifications and feature sets driving margin structures that vary substantially between match-day and replica segments.
Product Type:
Supply concentration in home kit manufacturing dominates contracted volume, with production lines prioritized for multi-season club commitments.
- Home Kits:Engineered from 100-150 gsm knitted polyester with sublimated crest applications to maintain breathability across torso panels. England and Germany's top-tier clubs drive volume concentration through multi-season contracts that anchor manufacturer capacity planning.
- Away Kits:Constructed to identical performance specifications as home kits but with rotational design cycles that refresh every 1-2 seasons. Bundesliga and Premier League clubs specify these for mid-week fixtures and European competition, creating secondary volume peaks that strain dye house scheduling.
- Third Kits:Limited-drop scarcity models generate disproportionate margin through club-owned e-commerce channels.
- Training Kits:Feature relaxed fit specifications and simplified crest applications for daily squad use.
Today's leader: Home Kits. Tomorrow's challenger: Third Kits.
Material:
Cost tier differentiation separates premium match-day specifications from economy replica grades, with recycled content mandates reshaping procurement thresholds.
- Polyester:Dominates through sublimation compatibility and durability, with EU Green Deal recycled content thresholds now mandatory for federation procurement. Nike and Adidas have reconfigured supply chains around post-consumer plastic feedstock traceability.
- Mesh:Expanding as clubs specify zonal ventilation panels for summer tournament schedules in Qatar and southern US markets. Thermoregulation integration commands premium positioning in professional team contracts.
- Cotton:Limited to lifestyle extensions and retro replica lines where breathability is secondary.
- Blends:Occupy mid-tier positioning where cost constraints override performance specifications.
Polyester holds current volume leadership. Mesh is gaining share fastest through thermoregulation differentiation.
Feature:
Application context determines which performance characteristics clubs prioritize, with moisture management non-negotiable for match-day specifications.
- Moisture-Wicking:Essential for professional team procurement, with hydrophilic fiber treatments now standard across England's Premier League. ECHA REACH compliance mandates reformulation of chemical finishing agents.
- Breathable:Mesh panel integration specified by clubs for summer tournament schedules, creating technical differentiation that manufacturers leverage in contract negotiations.
- Lightweight:Targets elite player preferences for reduced drag during high-intensity fixtures.
- Stretchable:Spandex blends accommodate dynamic movement ranges in training applications.
Moisture-Wicking dominates professional procurement. Breathable features are climbing fastest through climate-adaptive specifications.
End User:
Customer type fragmentation splits volume between institutional contracts and individual purchasing, with age demographics driving sizing and design differentiation.
- Professional Teams:Federation and club procurement concentrates in England and Germany, with multi-season contracts specifying batch-level traceability under EU Green Deal mandates. These accounts anchor manufacturer revenue stability.
- Adult Players:Replica commerce through club e-commerce platforms now exceeds traditional sporting goods retail in England, with scarcity-driven release calendars capturing margin previously lost to intermediaries.
- Youth Players:Sizing standardization and durability priorities dominate parent purchasing decisions.
- Amateur Teams:Price-sensitive volume that mid-tier suppliers like Macron target through regional league density.
Professional Teams anchor current contract value. Adult Players represent the steepest expansion trajectory through direct channel capture.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Kit designers and textile engineers cluster in northern Italy's industrial districts, Manchester's sportswear innovation corridor, and Germany's technical textile belt. These talent pools anchor production decisions for Europe's top-tier football clubs.
Germany
Bundesliga clubs drive specification of batch-level traceability systems under EU Green Deal mandates. ECHA REACH restrictions on azo dyes force reformulation of colorant chemistries across Bavaria's dye houses. The Stuttgart-Munich corridor concentrates technical textile R&D for thermoregulation mesh integration.
England
Premier League licensing volumes anchor manufacturer capacity planning through multi-season contracts. The UK Competition and Markets Authority scrutinizes replica pricing parity in club e-commerce channels. Greater Manchester hosts the densest cluster of kit design studios serving both elite clubs and mid-tier suppliers.
Italy
Serie A clubs sustain demand for premium sublimation finishing through rotational away-kit cycles. ANSM chemical safety protocols align with ECHA restrictions on nickel-release components in trim hardware. The Biella-Turin textile district supplies knitted polyester base fabrics to federation contractors.
Spain
La Liga's broadcast reach extends kit licensing into Latin American markets through club-branded merchandise. The country's national chemical regulator enforces REACH-aligned restrictions on perfluorinated finishing treatments. Barcelona's technical apparel cluster specializes in moisture-wicking fiber treatments for summer tournament specifications.
France
Ligue 1 clubs specify lightweight constructions for high-intensity European fixtures. CNIL data governance frameworks shape how club e-commerce platforms accumulate first-party customer data. The Lyon-Saint-Étienne corridor concentrates mid-tier manufacturing for regional league supply.
Football Kits Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across tiered supply positions. Vertically integrated textile groups control dyeing and finishing capacity, while brand licensors outsource manufacturing to certified subcontractors. Three archetypes dominate: federation-scale contractors with multi-tournament partnerships, mid-tier specialists serving regional league density, and premium athletic brands leveraging direct-to-consumer channels. Consolidation pressures mount through M&A targeting traceability infrastructure and strategic partnerships securing recycled polyester feedstock.
Among federation-scale contractors, Nike, adidas, and PUMA occupy positions defined by long-term tournament cycle anchoring rather than seasonal club volatility. Nike exemplifies the capital-intensive archetype through captive dyeing facilities meeting EU Green Deal documentation mandates. Adidas represents partnership-driven positioning across multiple federation relationships. PUMA sits within the challenger tier, leveraging scarcity-release calendars to capture margin in third-kit segments. These three anchors illustrate how scale, vertical control, and channel strategy separate competitive positions.
| Leading Market Players |
|---|
| Macron |
| New Balance |
| Nike |
| Under Armour |
| Joma |
| adidas |
| Kappa |
| Umbro |
| PUMA |
| Others |
Pricing and Supply Chain Analysis
Elite federation contracts versus mid-tier regional league supply splits the market into two pricing ecosystems with divergent margin structures and sourcing configurations. Federation-scale manufacturers command premium positioning through multi-tournament partnerships and captive dyeing capacity, while mid-tier suppliers compete on shorter production runs with compressed margins and outsourced finishing.
Pricing Analysis
Kit supply bundles design services, manufacturing capacity, and after-sales replenishment into multi-season contracts rather than transactional per-unit sales. Three-tier pricing structure across premium, standard, and economy levels separates federation partners from club-direct suppliers and amateur team wholesalers. Pricing pressure stems from EU Green Deal compliance costs as recycled polyester certification and waterless dyeing capex compress margins at the mid-tier. Amateur teams and youth leagues exhibit highest price sensitivity, while Premier League and Bundesliga clubs prioritize traceability and speed over unit cost.
Supply Chain Analysis
Polyester pellet feedstock rests on petrochemical complexes in Germany, Belgium, and the Netherlands, with recycled post-consumer plastic sourcing concentrating in France and Spain. Sublimation inks, thermoregulation mesh fabrics, and nickel-free trim hardware constitute critical component dependencies. Single-source vulnerability pervades supercritical CO2 dyeing equipment, where only a handful of European manufacturers produce compliant machinery. Distribution runs through club-owned e-commerce platforms disintermediating traditional sporting goods retail, particularly in England where direct channel capture now dominates third kit sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU Green Deal textile mandates compound procurement requirements into a structural demand driver for traceability infrastructure and certified recycled content systems.
For Market Incumbents: Acquire batch-level traceability software assets to defend federation contract renewals against emerging competitors with native compliance architecture. Consolidate dye house capacity in Germany and northern Italy before REACH reformulation deadlines eliminate smaller suppliers. Backward integration into post-consumer plastic feedstock collection secures recycled polyester certification pipelines. For New Entrants and Emerging Players: Regional league density in France and Spain offers underserved buyer concentration outside the Premier League-Bundesliga duopoly. Amateur team customization and rapid-turnaround replenishment services penetrate price-sensitive segments where federation suppliers lack operational flexibility. Direct-to-club digital platforms bypass traditional wholesale distribution. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-tier manufacturers possessing dyeing infrastructure but lacking federation brand recognition, as EU compliance costs force consolidation. Five-to-ten year viability hinges on recycled content certification and reverse logistics capability. Watch for ECHA enforcement actions against non-compliant suppliers as inflection indicator for acquisition timing.| Strategic Initiative | Industry Significance |
|---|---|
| Recycled Polyester Certification | EU Green Deal procurement rules mandate post-consumer plastic traceability for federation contracts. |
| Waterless Dyeing Capacity Expansion | Supercritical CO2 equipment concentrates production among capital-rich manufacturers meeting ECHA restrictions. |
| Direct-to-Consumer Platform Launch | Club-owned e-commerce in England captures margin previously lost to sporting goods retail intermediaries. |
| Reverse Logistics Infrastructure Buildout | Extended producer responsibility frameworks create closed-loop take-back service revenue streams. |
| Thermoregulation Mesh Integration | Summer tournament specifications in Qatar and southern US markets command premium kit positioning. |
Research Methodology
Bottom-up club and federation procurement modeling reconciled against top-down manufacturer capacity tracking forms the analytical core of this study. Primary interviews with kit design directors, textile procurement leads at Premier League and Bundesliga clubs, dye house operations managers, and federation licensing executives combined with secondary validation from customs trade databases, ECHA regulatory filings, and club financial disclosures. Triangulation across supply-side capacity announcements and demand-side contract values ensures measurement consistency.
Historical trendline analysis of kit refresh cycles, recycled polyester adoption curves, and direct channel revenue migration informs the projection framework. Segmentation dimensions span product type, material specification, performance feature, and end-user archetype across the analysis window. CAGRs derive from club contract value trajectories, manufacturer revenue disclosures, and federation licensing volume patterns. Thermoregulation feature penetration and scarcity-release calendar frequency constitute football-specific forecast inputs.
Underlying measurement precision varies by segment; professional team contract values carry tighter precision than amateur team estimates. Forecasts reflect documented assumptions regarding EU Green Deal enforcement timelines and petrochemical input stability. Regulatory acceleration, club insolvency events, or sublimation technology disruption could revise projections. A small set of triggers—ECHA penalty actions, federation supplier switches, and direct channel revenue inflections—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Apparel & Footwear
Women's Coats and Jackets Market
Apparel & Footwear
Rugby Apparel Market
Apparel & Footwear
Mister Cap Market
Apparel & Footwear
Brazil Pet Clothing Market
Apparel & Footwear
Fast Fashion Market
Apparel & Footwear
Europe Second-Hand Apparel Market
Apparel & Footwear
Decorated Apparel Market
Apparel & Footwear
Smart Wardrobe Market
Apparel & Footwear
Touchscreen Gloves Market
Apparel & Footwear
Apparel Re-Commerce Market
Apparel & Footwear
Smart Heating Scarf Market
Apparel & Footwear
Denim Jeans Market
Apparel & Footwear
Hats Market
Apparel & Footwear
Streetwear Market
Apparel & Footwear
Women's Shirts and Blouses Market
Apparel & Footwear
Women's Tights and Leggings Market