
 Europe Social Media Analytics Market | 2026-2036
Europe Social Media Analytics Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Social Media Analytics Market Foresight
Platform licensing revenue is fragmenting across specialized sentiment analysis modules and integrated marketing suites. Salesforce anchors its position through deep CRM connectivity that embeds social listening into customer journey workflows. Brandwatch differentiates through real-time brand monitoring capabilities that serve European retail and media clients. IBM Corporation sustains enterprise credibility with AI-powered natural language processing tailored to regulated industries.
Social media analytics encompasses the systematic collection, processing, and interpretation of user-generated content across digital platforms to extract actionable intelligence on consumer behavior, brand perception, and competitive dynamics. The discipline employs natural language processing, machine learning classification, and network graph analysis to transform unstructured social data into structured metrics for commercial decision-making. Cloud-based solutions currently capture the dominant deployment share as financial services and retail brands prioritize scalable infrastructure with minimal capital commitment. Customer sentiment analysis represents the fastest-expanding application segment, driven by real-time response requirements in travel and media sectors where reputation volatility demands immediate detection.
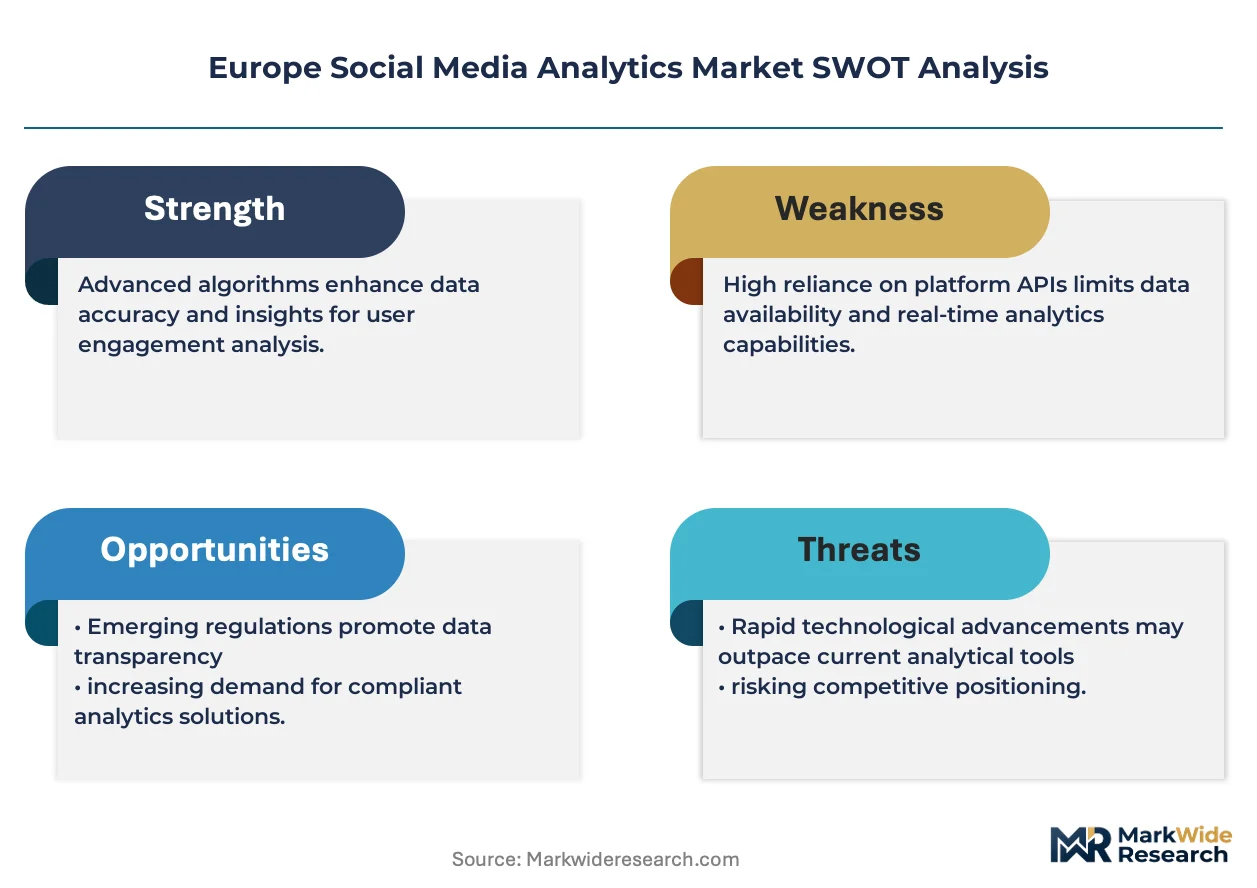
The EU AI Act imposes transparency obligations on automated decision systems that process social data, compelling vendors to document algorithmic training methodologies and risk classifications. GDPR enforcement by national data protection authorities across Germany, France, and Spain restricts cross-border sentiment data aggregation, creating compliance architecture as a competitive differentiator. EASA guidelines on AI safety and the proposed EU Data Act will further constrain how aviation and logistics firms deploy predictive social analytics. Stakeholders must evaluate whether their current tooling satisfies emerging algorithmic accountability standards before procurement cycles finalize.
Market Dynamics
The EU AI Act's algorithmic transparency mandates are compressing procurement timelines as financial services and retail buyers demand pre-certified analytics architectures before contract execution.
Growth Catalysts
- GDPR-Compliant Architectures:Privacy-preserving federated learning techniques enable cross-border sentiment aggregation without raw data transfer, unlocking previously restricted German-French analytics pipelines.
- Real-Time Response Requirements:Travel and media sectors deploy automated alert systems that flag reputation volatility within seconds of viral content emergence.
- Cloud Infrastructure Scaling:German and UK financial institutions prioritize SaaS deployments to minimize capital commitment while expanding computational capacity for NLP workloads.
Market Restraints
- Cross-Border Data Friction:German, French, and Spanish national data protection authorities enforce divergent interpretations of GDPR Article 44, fragmenting sentiment data lakes.
- Algorithmic Audit Costs:EU AI Act documentation requirements for high-risk systems impose recurring compliance expenditures that squeeze mid-tier vendor margins.
- Specialized Talent Scarcity:Shortages of bilingual NLP engineers fluent in European language variants limit deployment velocity for sentiment models.
Strategic Opportunities
- Underpenetrated Southern Europe:Italian and Spanish retail banking segments show minimal current adoption of social listening tools for customer experience optimization.
- Aviation Safety Analytics:EASA guidelines on AI safety create compliant pathways for predictive social analytics in passenger sentiment monitoring.
- Regulatory Technology Bundling:Vendors integrating CSRD reporting modules with social sentiment dashboards capture procurement budgets from sustainability officers.
Industry Challenges
- Legacy CRM Integration Complexity:European enterprises operating SAP and Oracle ecosystems face extended deployment timelines for API-connected social analytics layers.
- Certification Timeline Uncertainty:Pending clarifications from EU AI Act implementing acts delay product roadmap commitments for vendors serving regulated industries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Social Media Analytics Market |
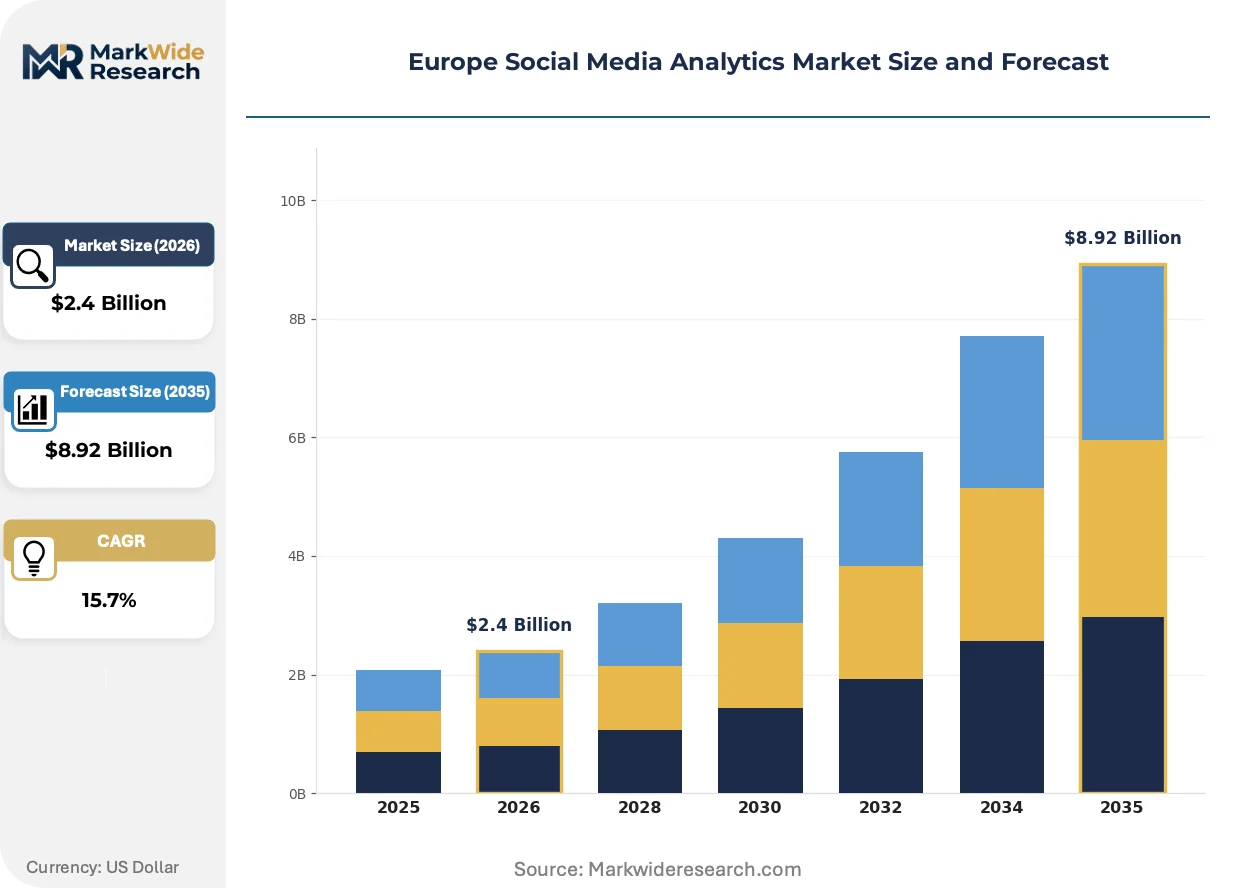
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $8.92 Billion |
| CAGR (2026 – 2036) | 15.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution: Managed Services, Cloud-Based Solutions, On-Premise Solutions, Consulting Services End User: Retail Brands, Financial Services, Media & Entertainment, Travel Companies Deployment: Private Cloud, Public Cloud, Hybrid Cloud, Edge Computing Application: Brand Monitoring, Customer Sentiment Analysis, Marketing Campaigns, Competitor Analysis |
| Companies Covered | Adobe Systems Incorporated, Salesforce, IBM Corporation, Brandwatch, SAP, SAS Institute Inc., Oracle Corporation, Talkwalker, Clarabridge Inc., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Social Media Analytics Market Shifts & Advancements
Natural language processing architectures are fragmenting into specialized modules as buyers reject monolithic platforms in favor of composable, API-first analytics stacks.
Transformer-based large language models are migrating from general-purpose sentiment classification to domain-specific financial and healthcare ontologies. German insurance underwriters and UK hospital networks pilot these narrow-trained systems for complaint triage. The shift is compressing time-to-insight from hours to minutes while elevating accuracy benchmarks for regulated use cases.
The EU AI Act's risk classification framework imposes documentation burdens on automated decision systems processing social data. Vendors must now maintain algorithmic training logs and bias assessment protocols for high-risk deployments. Financial services procurement teams in Frankfurt and London are inserting compliance verification clauses into RFP evaluations before technical assessment.
Subscription fatigue among mid-market buyers is fragmenting purchasing authority from central IT to line-of-business units. Marketing directors in French retail chains and Dutch logistics firms now procure standalone sentiment modules without enterprise platform commitments. Procurement patterns concentrate in monthly-billed, low-implementation tools that bypass traditional vendor consolidation strategies.
Europe Social Media Analytics Market Segmentation
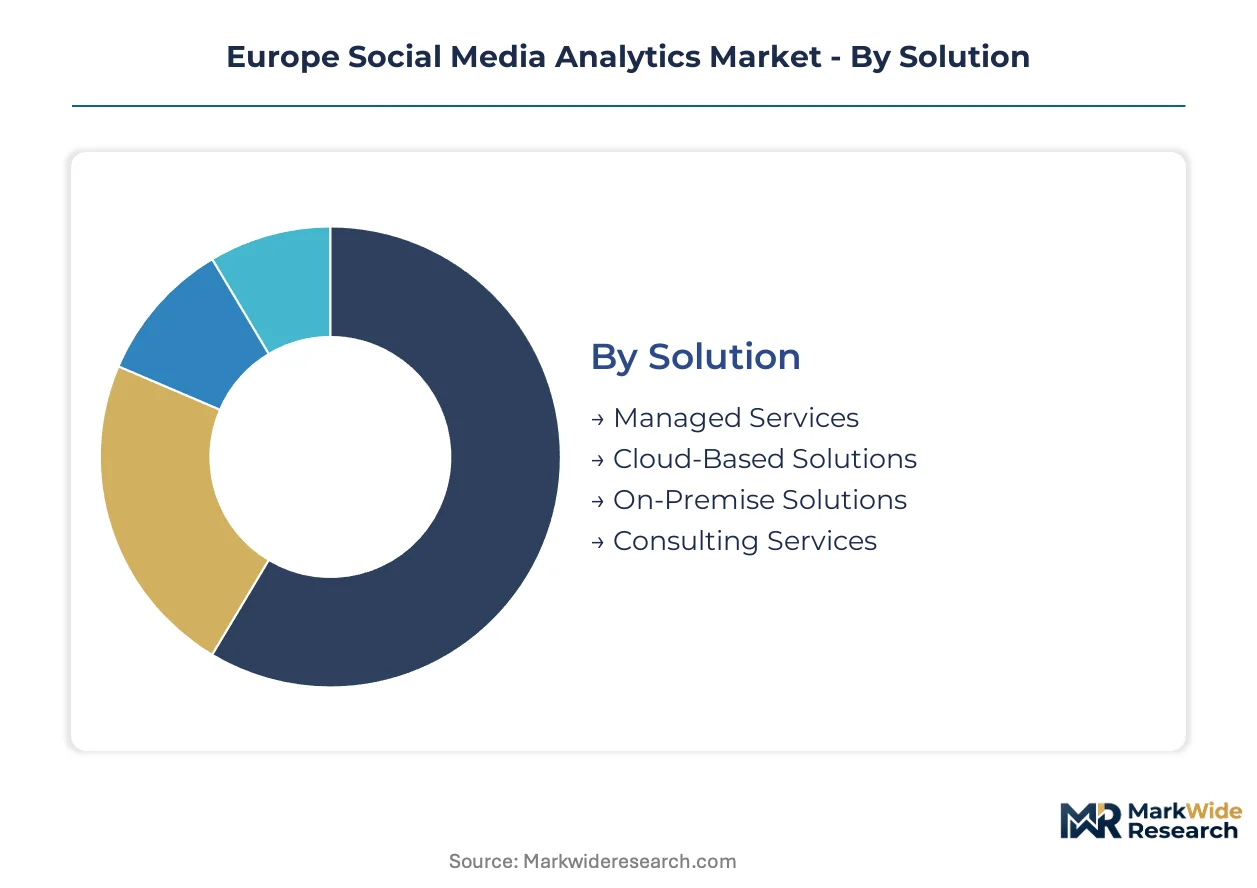
Social media analytics vendors configure service intensity and technical architecture around distinct operational models. Procurement patterns diverge sharply between enterprises demanding hands-on implementation support and those prioritizing self-service scalability.
Solution:
After-sales service intensity varies dramatically across deployment modes, with managed services requiring continuous engineering touchpoints while cloud solutions minimize ongoing vendor interaction.
- Managed Services:Vendors deliver end-to-end platform operation including model retraining, alert configuration, and compliance documentation. German financial institutions in Frankfurt and Munich dominate procurement, driven by EU AI Act audit trail requirements that internal teams cannot satisfy.
- Cloud-Based Solutions:Scalable SaaS architectures with API-first integration patterns enable rapid deployment without capital expenditure. UK retail chains and French media groups prioritize these for seasonal campaign spikes where infrastructure elasticity proves decisive.
- On-Premise Solutions:Air-gapped deployments for classified or restricted data environments.
- Consulting Services:Advisory engagements for analytics strategy and organizational transformation.
Cloud-based solutions hold the largest share; momentum sits with managed services.
End User:
Cost tier differentiation separates enterprise buyers with dedicated procurement functions from mid-market adopters purchasing through line-of-business budgets.
- Retail Brands:Real-time sentiment monitoring for product launches and crisis response. Demand concentrates in German fashion houses and UK grocery chains where social reputation directly correlates with foot traffic.
- Financial Services:Regulatory compliance and customer complaint triage. Frankfurt and London banking clusters drive premium pricing for explainable AI features mandated by supervisory authorities.
- Media & Entertainment:Audience engagement optimization and content performance prediction.
- Travel Companies:Reputation volatility detection for service disruption management.
Financial services commands premium pricing; retail brands are expanding most quickly.
Deployment:
Volume concentration patterns reflect data sovereignty requirements and latency sensitivity across European regulatory jurisdictions.
- Private Cloud:Single-tenant infrastructure with dedicated compute resources and geographic data residency. French luxury brands and German automotive suppliers mandate these for GDPR Article 44 compliance in cross-border analytics pipelines.
- Public Cloud:Multi-tenant shared infrastructure with consumption-based pricing. UK fintech startups and Dutch logistics platforms favor these for NLP workload burst capacity without infrastructure ownership.
- Hybrid Cloud:Split architectures balancing sensitive on-premise data with scalable cloud processing.
- Edge Computing:Distributed processing for real-time inference at point of data generation.
Public cloud holds the largest share; hybrid cloud is gaining share fastest.
Application:
Customer type maturity separates organizations with established social listening programs from first-time adopters seeking quick wins.
- Brand Monitoring:Continuous tracking of mentions, share of voice, and emerging reputation threats. Spanish telecommunications providers and Italian automotive brands deploy these for competitive positioning in fragmented markets.
- Customer Sentiment Analysis:NLP classification of emotional valence and intent across multilingual content. UK hospital networks and German insurance underwriters pilot these for complaint triage with domain-specific ontologies.
- Marketing Campaigns:Performance attribution and creative optimization through social feedback loops.
- Competitor Analysis:Benchmarking and strategic intelligence through rival social presence monitoring.
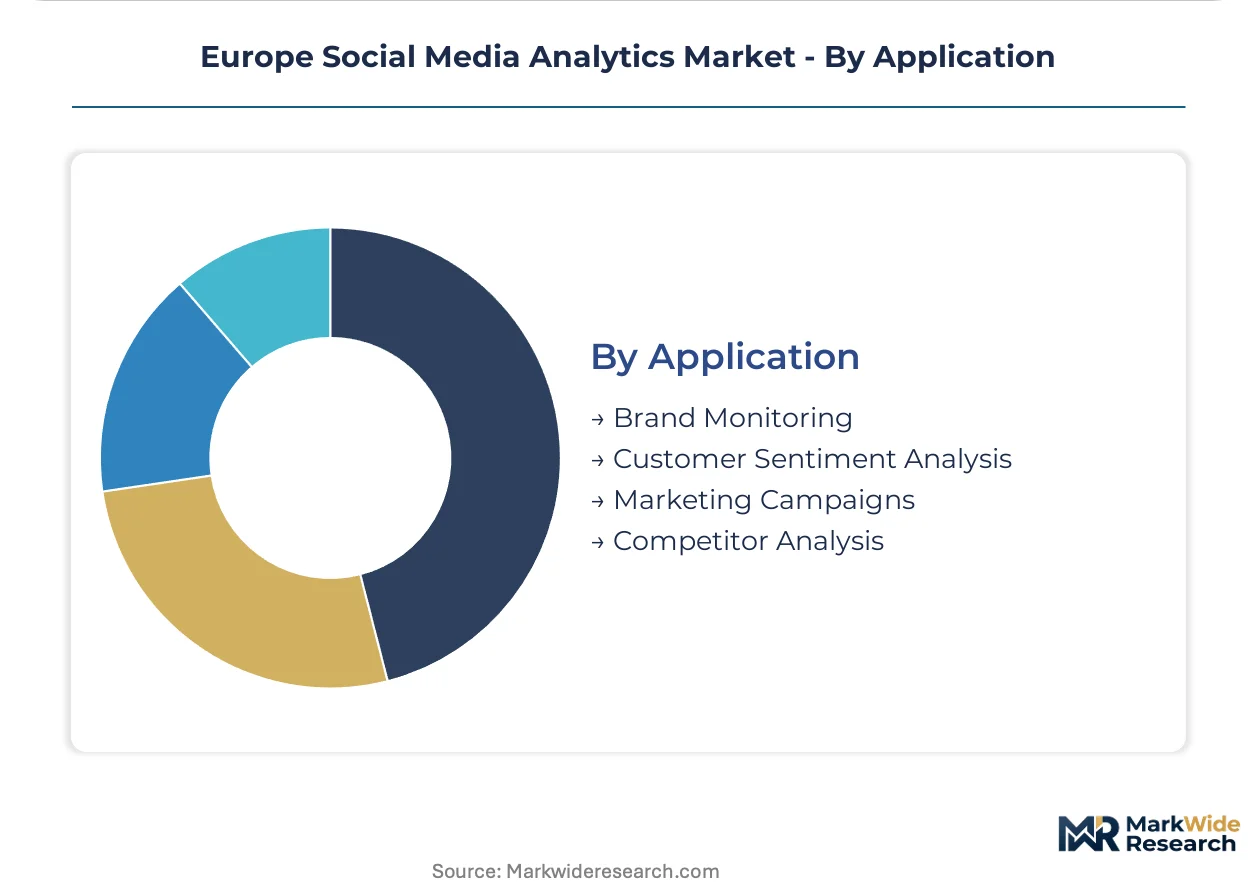
Brand monitoring holds the largest share; customer sentiment analysis shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German financial institutions deploy sentiment analytics primarily for regulatory compliance documentation, while UK retail chains emphasize real-time campaign optimization—a divergence that shapes vendor feature roadmaps across the continent.
Germany
Frankfurt and Munich banking clusters drive demand for explainable AI architectures that satisfy BaFin supervisory expectations. The EU AI Act's high-risk system documentation mandates compress procurement timelines for sentiment analysis platforms. Bavarian automotive suppliers mandate private cloud deployments to maintain GDPR Article 44 compliance in cross-border data pipelines.
United Kingdom
London fintech startups favor public cloud burst capacity for NLP workloads without infrastructure ownership commitments. The Financial Conduct Authority's operational resilience requirements shape vendor selection criteria for real-time monitoring tools. Manchester and Birmingham retail headquarters concentrate seasonal campaign analytics procurement.
France
Parisian luxury brands demand geographic data residency guarantees for customer sentiment aggregation across multilingual markets. CNIL enforcement of GDPR cross-border transfer restrictions fragments analytics data lakes. Lyon-based logistics platforms pilot automated alert systems for reputation volatility detection.
Italy
Milan and Rome retail banking segments show minimal current adoption of social listening tools for customer experience optimization. The country's data protection authority enforces divergent interpretations of algorithmic transparency obligations. Lombardy-based fashion houses concentrate brand monitoring investments for competitive positioning.
Spain
Barcelona and Madrid telecommunications providers deploy continuous mention tracking for market share defense in fragmented Iberian markets. Spanish data protection authority enforcement restricts sentiment data aggregation across EU borders. Andalusian tourism operators pilot real-time response systems for service disruption management.
Europe Social Media Analytics Market Competitive Landscape
Capability concentration sits with specialized sentiment analysis vendors; scale advantage sits with integrated enterprise software conglomerates. The vendor landscape stratifies into three functional tiers: CRM-embedded platforms, standalone monitoring specialists, and consulting-heavy systems integrators. Dominant competitive moves include strategic API partnerships with cloud infrastructure providers and vertical specialization around regulated industry ontologies.
Within the enterprise software tier, Salesforce, IBM Corporation, and SAP exemplify divergent strategic positioning. Salesforce anchors its market presence through deep CRM connectivity that embeds social listening into customer journey workflows. IBM Corporation sustains credibility with AI-powered natural language processing tailored to regulated industries. SAP occupies a position serving European enterprises operating legacy ERP ecosystems with extended deployment requirements.
| Leading Market Players |
|---|
| Adobe Systems Incorporated |
| Salesforce |
| IBM Corporation |
| Brandwatch |
| SAP |
| SAS Institute Inc. |
| Oracle Corporation |
| Talkwalker |
| Clarabridge Inc. |
| Others |
Supply & Pricing Matrix
The Rotterdam-Frankfurt data corridor's bandwidth cost dynamics concentrate supply-side power among hyperscale cloud providers while forcing downstream price differentiation between GDPR-compliant private cloud deployments and standard SaaS tiers. German financial institutions absorb premium pricing for managed services architectures that satisfy BaFin audit requirements, whereas UK retail chains negotiate volume discounts on public cloud burst capacity.
Pricing Analysis
Long-term managed service contracts dominate enterprise procurement in Frankfurt and Munich, locking in 24-36 month commitments with escalating penalty clauses for early termination. Price differentiation rests on EU AI Act certification status and geographic data residency guarantees, with private cloud single-tenant deployments commanding substantial premiums over multi-tenant alternatives. Cost compression in mid-market SaaS tiers is intensifying because subscription fatigue drives procurement decentralization to line-of-business units with constrained budgets. Mid-market French retail chains exhibit highest price sensitivity, while German banking clusters demonstrate lowest elasticity due to compliance-driven vendor stickiness.
Supply Chain Analysis
Tariff exposure between Ireland and continental EU data centers dominates supply chain risk planning for vendors serving GDPR-sensitive clients. Cloud infrastructure concentrates in Ireland, Netherlands, and Germany, with NLP model training drawing from proprietary datasets, open-source language corpora, and licensed third-party sentiment libraries. Single-source vulnerability sits with transformer model providers whose API rate limits constrain scaling velocity for real-time analytics workloads. Distribution runs through direct enterprise sales teams for regulated industries and self-service marketplaces for mid-market adopters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among procurement consortiums at German banking clusters and UK retail headquarters, fragmenting vendor pricing power as collective negotiation replaces individual contracts.
For Market Incumbents: Pre-empt margin erosion from API-first challengers by embedding compliance documentation modules directly into CRM workflows, leveraging existing BaFin relationship credibility to lock in multi-year renewals before EU AI Act implementing acts clarify audit standards. Prioritize backward integration into proprietary language model training to reduce dependency on third-party API providers.
For New Entrants and Emerging Players: Pursue white-space expansion in Italian and Spanish retail banking segments where social listening penetration remains minimal and procurement authority sits with customer experience officers rather than centralized IT. Target monthly-billed sentiment modules with rapid deployment timelines as the primary go-to-market angle, bypassing lengthy enterprise sales cycles.
For Investors and Strategic Acquirers: Specialized NLP boutiques with domain-specific ontologies for financial services or healthcare represent the most defensible acquisition targets, given their irreplaceable training data assets and regulatory relationship depth. Watch for inflection signals in EASA guideline finalization, which will unlock aviation sector procurement budgets previously inaccessible to generalist vendors.
| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Compliance Certification | BaFin and CNIL enforcement patterns make pre-certified architectures mandatory for Frankfurt and Paris procurement. |
| API-First Platform Integration | Salesforce and SAP ecosystem connectivity determines vendor inclusion in enterprise RFP shortlists. |
| Vertical Ontology Development | Domain-specific models for insurance complaint triage command pricing premiums from German underwriters. |
| Federated Learning Architecture | Privacy-preserving cross-border analytics unlocks previously restricted German-French data pipelines. |
| Managed Services Expansion | Continuous compliance documentation satisfies EU AI Act audit trail requirements that internal teams cannot fulfill. |
Research Methodology
Cross-validation between primary interviews with CTOs at UK fintech startups and secondary analysis of hyperscaler capex disclosures anchors the qualitative findings on cloud infrastructure scaling patterns. Conversations with data protection officers at German automotive suppliers, platform engineers at Dutch logistics firms, and integration specialists at French retail chains combined with SEC filings, EU regulatory implementing act drafts, and sentiment analytics vendor pricing documentation. Bottom-up deployment volume estimates triangulate against top-down market sizing derived from cloud provider regional revenue allocations.
Calibration against historical adoption curves in adjacent analytics markets informs the projection framework across the analysis window. Segmentation dimensions include deployment model, organization size tier, vertical industry, integration complexity level, and regional regulatory cluster. CAGRs derive from fitted growth curves adjusted for compliance timeline acceleration and procurement cycle compression observed in financial services verticals. NLP workload intensity benchmarks and GDPR enforcement variance across national data protection authorities constitute key forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive moves by well-capitalized cloud hyperscalers into vertical-specific sentiment modules would shift outcomes substantially. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Social Media Analytics
Audience Intelligence Platforms Market
Social Media Analytics
US Social Media Management Market
Social Media Analytics
China Social Media Management Market
Social Media Analytics
Social Media Analytics Market
Social Media Analytics
Italy Social Media Management Market
Social Media Analytics
Global TV Analytics Market
Social Media Analytics
Global Audience Analytics Market
Social Media Analytics
Europe Social Media Management Market
Social Media Analytics
Brazil Social Media Management Market
Social Media Analytics
Social Media Listening Market
Social Media Analytics
Social Media Management Market
Social Media Analytics
Germany Social Media Management Market
Social Media Analytics
Media Monitoring Tools Market
Social Media Analytics
Social Advertising Tools Market
Social Media Analytics
Social Media Records Management Market