
 Global Audience Analytics Market | 2026-2036
Global Audience Analytics Market Size, Share, and Industry Trends Forecast 2026-2036
Global Audience Analytics Market Foresight
ISO/IEC 27001 certification cycles for data security management is collapsing from eighteen-month intervals to nine-month audits, squeezing vendor compliance budgets. Google LLC leverages its cloud infrastructure and first-party data reservoirs to dominate real-time audience measurement. Oracle Corporation anchors enterprise-grade deployments through backward integration into its marketing cloud stack. Adobe, Inc. differentiates via creative workflow tethering to analytics dashboards.
Audience analytics encompasses the computational extraction, aggregation, and interpretation of behavioral signals across digital and physical touchpoints to infer viewer composition, engagement depth, and conversion propensity. The discipline processes streaming event logs, device graphs, and biometric proxies through machine learning pipelines operating at sub-100-millisecond latency for programmatic ad insertion. Cloud-based deployment leads solution uptake among mid-market advertising firms lacking capital for server farms, while edge computing architectures grow fastest in live event analytics where venue bandwidth constraints demand local preprocessing. Predictive analytics commands premium pricing in media planning workflows, whereas sentiment analysis tools face margin compression from open-source natural language libraries.
The EU AI Act restricts automated profiling for behavioral targeting, compelling platform operators to implement explainability layers and human-in-the-loop review. The Federal Trade Commission in the United States and the Information Commissioner's Office in the United Kingdom independently scrutinize dark pattern design and opaque algorithmic amplification. Stakeholders must monitor divergent jurisdictional enforcement calendars and pre-position consent architecture that satisfies the strictest applicable standard rather than retrofitting territory by territory.
Market Dynamics
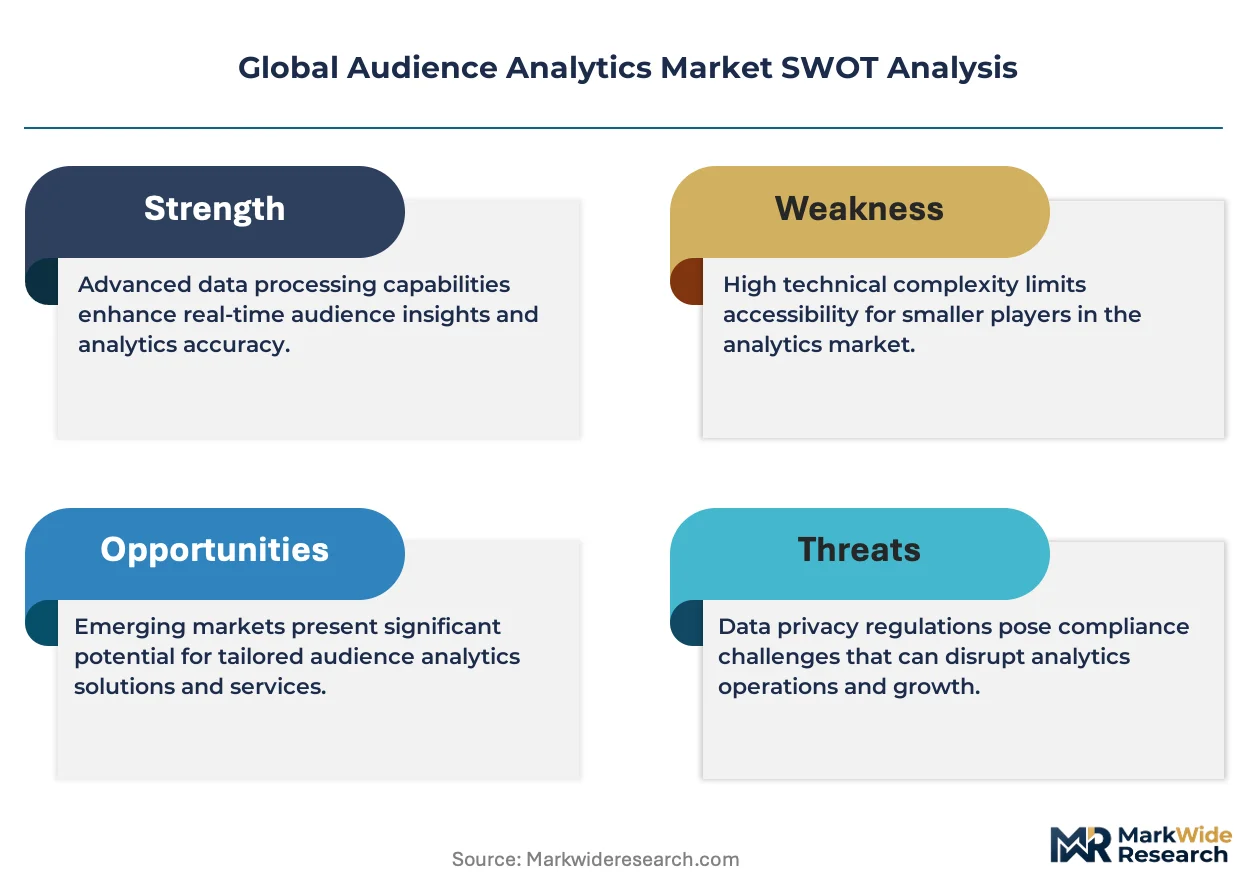
Real-time content personalization engines are compressing decision cycles from days to milliseconds, forcing media buyers to re-architect data pipelines around sub-100-millisecond latency thresholds. This velocity imperative is redistributing competitive advantage toward cloud-native infrastructure operators with first-party data reservoirs.
Growth Catalysts
- EU AI Act explainability mandates:Platform operators must deploy human-in-the-loop review systems for automated profiling, creating specialized demand for interpretable machine learning tooling.
- Live event biometric integration:Venue operators in Germany and the United States are deploying edge-computing architectures to preprocess facial sentiment and engagement depth without exhausting venue bandwidth.
- Programmatic advertising technology stacks:Mid-market advertising firms lacking server farm capital are accelerating cloud-based deployment adoption for audience measurement infrastructure.
Market Restraints
- ISO/IEC 27001 audit compression:Certification cycles collapsing from eighteen-month to nine-month intervals are squeezing vendor compliance budgets and diverting engineering resources from product development.
- First-party data reservoir concentration:Dominant cloud infrastructure operators control proprietary behavioral signal lakes, creating asymmetric access for downstream analytics vendors.
- Open-source natural language libraries:Freely available sentiment analysis tooling is compressing margins for standalone emotional inference software providers.
Strategic Opportunities
- Indian advertising technology penetration:Deepening ad-tech stacks in Mumbai and Bangalore present underexploited deployment opportunities for predictive media planning workflows.
- Creative workflow tethering:Convergence between analytics dashboards and content production pipelines enables premium pricing for unified planning-to-execution platforms.
- Edge computing venue retrofitting:Bandwidth-constrained stadiums and concert halls require localized preprocessing hardware, opening hardware-software bundled service models.
Industry Challenges
- Sub-100-millisecond pipeline engineering:Talent scarcity in stream processing and low-latency machine learning inference is inflating compensation for specialized data infrastructure architects.
- Cross-jurisdictional consent architecture:Divergent enforcement calendars between the FTC in the United States and the ICO in the United Kingdom demand pre-positioned compliance systems satisfying the strictest applicable standard.
- Legacy data warehouse integration:Enterprise marketing cloud migrations face friction from incompatible schema standards and historical event log formats.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Audience Analytics Market |
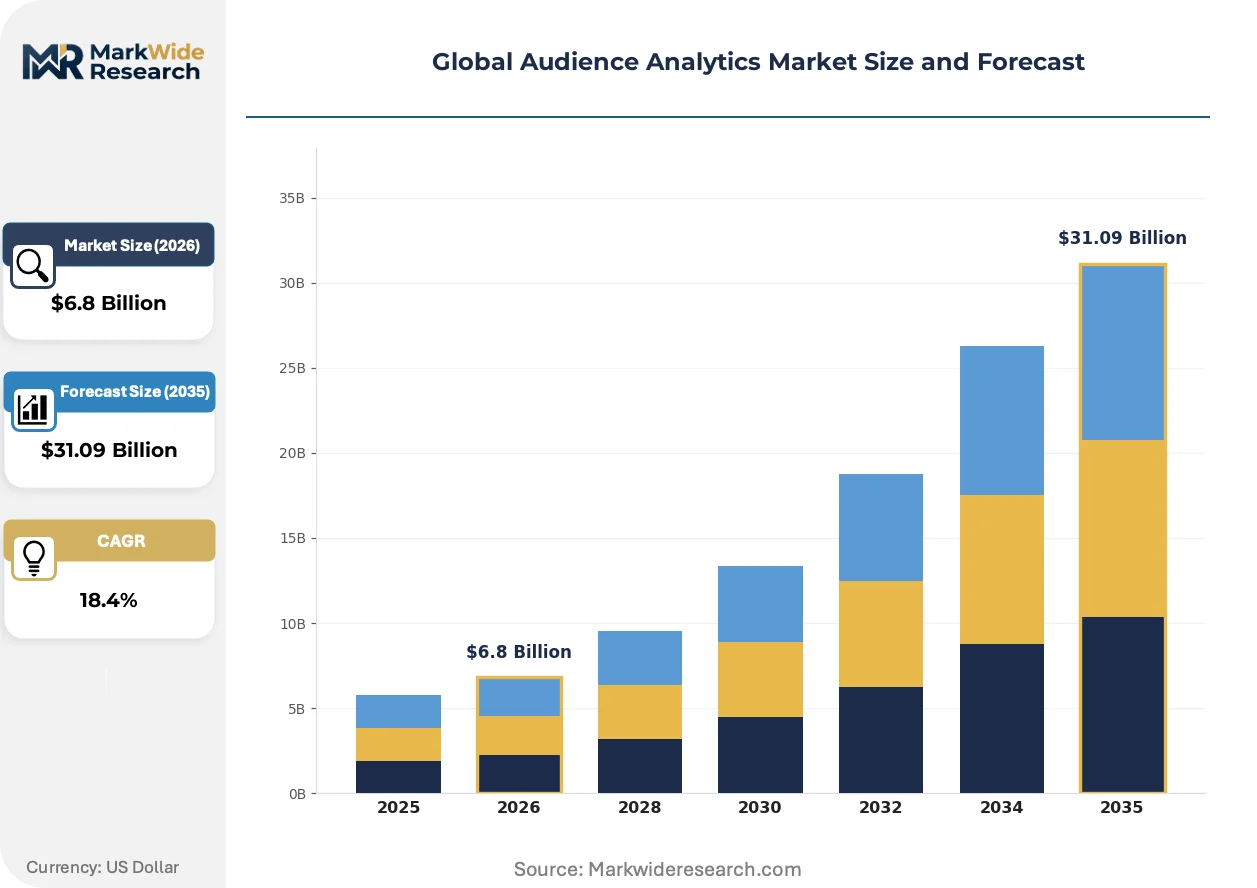
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $31.09 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premise, Hybrid, Edge Computing Solution/Offering: Real-Time Analytics, Predictive Analytics, Sentiment Analysis, Segmentation Tools, Data Visualization Application/Use Case: Content Personalization, Campaign Effectiveness, Consumer Behavior Tracking, Media Planning, Brand Monitoring End User/Industry Vertical: Media Companies, Advertising Firms, Public Relations Agencies, Market Research Firms, Event Organizers |
| Companies Covered | Adobe, Inc., Oracle Corporation, IBM Corporation, Google LLC, SAS Institute, Inc., Akamai Technologies, Inc., Comscore, Inc., NetBase Solutions, Inc., Sightcorp, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Audience Analytics Market Shifts & Advancements
Machine learning inference at the network edge is redrawing competitive boundaries between centralized cloud providers and distributed hardware vendors. Three developments are compressing incumbent advantage while opening specialized niches.
Federated learning architectures are displacing centralized model training for audience segmentation in privacy-sensitive deployments. Media conglomerates with dispersed geographic operations are adopting these distributed approaches to keep raw behavioral signals local while aggregating model updates. This pattern is compressing demand for conventional data lake centralization and enabling regional infrastructure providers to capture workloads previously routed to hyperscale clouds.
The EU AI Act's prohibition on opaque automated profiling is forcing explainability layer investments across behavioral targeting pipelines. Platform operators must document decision logic for human reviewers, increasing computational overhead but creating specialized demand for interpretability tooling vendors. Germany's advertising technology clusters are responding fastest, embedding local review workflows into real-time bidding systems ahead of enforcement deadlines.
Buyers are unbundling after-sales service from core analytics licenses, demanding usage-based pricing tied to actual query volumes rather than seat-based subscriptions. Mid-market advertising firms in India and the United States are driving this shift, preferring operational expense treatment over capital deployment for perpetual licenses. This compression is forcing incumbent vendors to restructure revenue recognition and customer success functions around consumption metrics.
Global Audience Analytics Market Segmentation
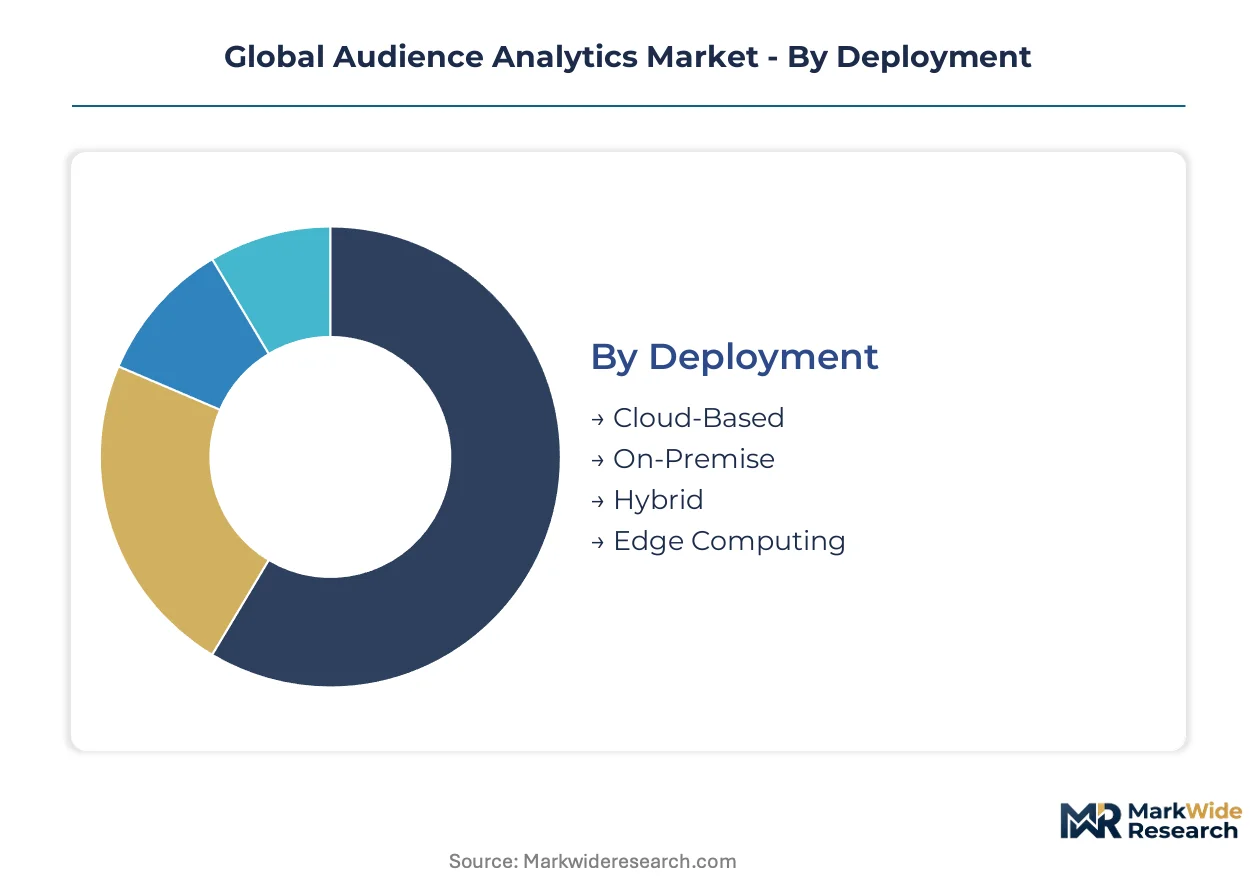
Audience analytics procurement splits across infrastructure topology, analytical sophistication, and buyer sophistication. Deployment mode determines latency tolerance and regulatory exposure, while solution type governs pricing power and margin structure.
Deployment:
EU AI Act data sovereignty requirements and ISO/IEC 27001 audit compression are reshaping infrastructure location decisions.
- Cloud-Based:Hyperscale infrastructure from Google LLC and Oracle Corporation dominates mid-market advertising firms lacking server farm capital. Procurement concentrates in the United States and India where operational expense treatment outweighs data residency concerns.
- Edge Computing:Localized preprocessing architectures process facial sentiment and engagement depth in bandwidth-constrained German stadiums and US concert venues. Federated learning deployments keep raw behavioral signals local while aggregating model updates.
- On-Premise:Enterprise media conglomerates maintain captive infrastructure for legacy data warehouse integration.
- Hybrid:Split architectures balance real-time bidding latency against archival compliance requirements.
Established volume favors Cloud-Based; emerging adoption favors Edge Computing.
Solution/Offering:
Pricing power correlates with computational intensity and interpretability overhead.
- Real-Time Analytics:Sub-100-millisecond inference pipelines for programmatic ad insertion command premium licensing. Media buyers in the United States and Germany re-architect data pipelines around velocity thresholds.
- Predictive Analytics:Machine learning pipelines for media planning workflows attract sustained investment from Indian advertising technology clusters in Mumbai and Bangalore.
- Sentiment Analysis:Open-source natural language libraries compress margins for standalone emotional inference providers.
- Segmentation Tools:Audience composition modeling supports cross-channel identity resolution.
- Data Visualization:Dashboard tethering to creative workflows enables Adobe's differentiation strategy.
Margin compression hits Sentiment Analysis; pricing power concentrates in Real-Time Analytics.
Application/Use Case:
Use case maturity determines buyer sophistication and implementation failure rates.
- Content Personalization:Real-time engines compress decision cycles from days to milliseconds. EU AI Act explainability mandates force human-in-the-loop review system investments.
- Media Planning:Predictive workflows attract mid-market advertising firms in India seeking operational expense treatment over capital deployment.
- Campaign Effectiveness:Attribution modeling faces friction from incompatible schema standards.
- Consumer Behavior Tracking:Cross-device graph construction confronts first-party data reservoir concentration.
- Brand Monitoring:Social listening deployments encounter open-source tooling substitution.
Implementation maturity favors Media Planning; regulatory complexity favors Content Personalization.
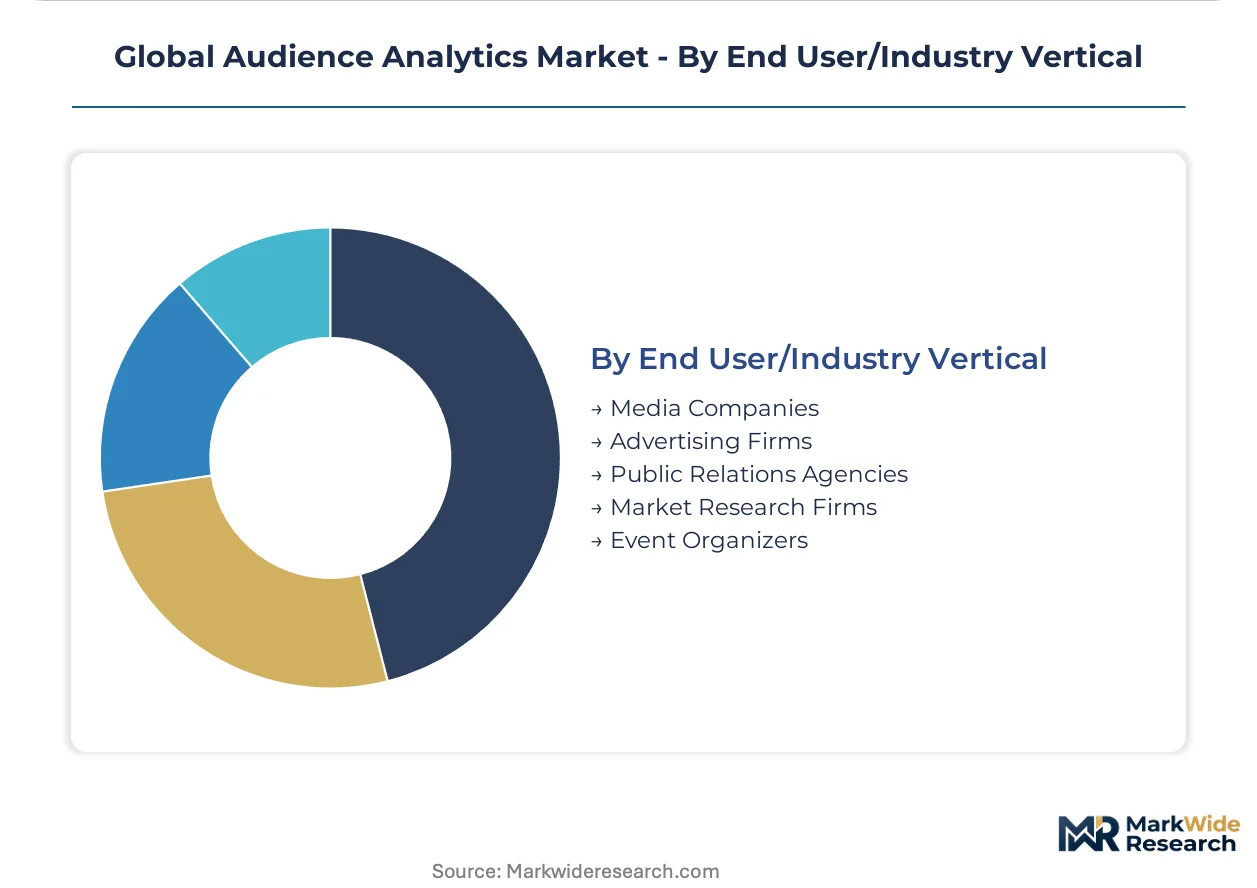
End User/Industry Vertical:
Vertical technology stack depth determines procurement authority and integration complexity.
- Media Companies:Real-time analytics deployment for content personalization drives fastest procurement expansion. EU AI Act reshapes permissible data processing methods.
- Advertising Firms:Mid-market players lacking server farm capital accelerate cloud-based adoption. Usage-based pricing tied to query volumes displaces seat-based subscriptions.
- Event Organizers:German and US venue operators deploy edge-computing architectures for live biometric integration.
- Market Research Firms:Legacy data warehouse integration creates schema friction.
- Public Relations Agencies:Sentiment analysis demand faces margin compression from open-source alternatives.
Procurement scale favors Media Companies; fastest expansion trajectory belongs to Event Organizers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU AI Act explainability mandates are redrawing procurement patterns across advertising technology clusters, with enforcement timelines diverging between jurisdictions. Data residency requirements and audit compression cycles are forcing infrastructure location decisions that favor specific national regulatory environments over regional convenience.
United States
FTC scrutiny of dark pattern design and algorithmic amplification is accelerating consent architecture investments among platform operators. Mid-market advertising firms in New York and Los Angeles are driving usage-based pricing adoption for cloud-based audience measurement infrastructure. The Greater Boston corridor hosts specialized data infrastructure architects commanding premium compensation for sub-100-millisecond pipeline engineering.
Germany
Bavarian advertising technology clusters are embedding human-in-the-loop review workflows into real-time bidding systems ahead of EU AI Act enforcement deadlines. KBA and federal data protection authorities are scrutinizing biometric preprocessing in Munich and Frankfurt venue retrofits. Edge-computing architectures for facial sentiment analysis are deploying fastest in Hamburg stadiums and Berlin concert halls.
India
TRAI guidelines on data localization are shaping procurement decisions for predictive media planning workflows in Mumbai and Bangalore. Mid-market advertising firms lacking server farm capital are accelerating cloud-based deployment adoption. The Karnataka and Maharashtra technology corridors present underexploited opportunities for operational expense treatment over capital deployment.
United Kingdom
ICO enforcement calendars on opaque algorithmic amplification are diverging from FTC timelines, demanding pre-positioned compliance systems. London-based media buyers are re-architecting data pipelines around velocity thresholds for programmatic ad insertion. The Manchester-Leeds corridor is developing specialized interpretability tooling vendors responding to explainability mandates.
Japan
METI initiatives on data sovereignty are influencing infrastructure topology decisions for media conglomerates with dispersed geographic operations. Tokyo and Osaka advertising technology stacks are adopting federated learning architectures to keep raw behavioral signals local. Kansai region venue operators are piloting edge-computing preprocessing for bandwidth-constrained live events.
Global Audience Analytics Market Competitive Landscape
Player mix skews toward cloud-native infrastructure operators with first-party data reservoirs and enterprise marketing cloud incumbents with backward integration capabilities. The vendor base concentrates around three strategic archetypes: hyperscale cloud providers controlling proprietary behavioral signal lakes, creative workflow platforms tethering analytics to content production pipelines, and specialized interpretability tooling vendors responding to regulatory explainability mandates. Dominant competitive moves include M&A activity targeting edge-computing hardware vendors and strategic partnerships between analytics platforms and venue operators for biometric integration deployments.
Within the hyperscale infrastructure tier, Google LLC and Oracle Corporation exemplify divergent approaches to market positioning, with the former leveraging cloud infrastructure dominance and the latter anchoring enterprise-grade deployments through marketing cloud stack integration. Adobe, Inc. occupies a distinct position among creative workflow platforms, representing the convergence strategy between analytics dashboards and content production pipelines. These three entities collectively illustrate the competitive tension between infrastructure control, enterprise integration depth, and creative workflow tethering as distinct vectors for differentiation.
| Leading Market Players |
|---|
| Adobe, Inc. |
| Oracle Corporation |
| IBM Corporation |
| Google LLC |
| SAS Institute, Inc. |
| Akamai Technologies, Inc. |
| Comscore, Inc. |
| NetBase Solutions, Inc. |
| Sightcorp |
| Others |
Supply & Pricing Matrix
Nine-month ISO/IEC 27001 recertification cycles compress vendor cash conversion timelines, concentrating pricing power among hyperscale cloud operators with captive compliance infrastructure while squeezing mid-market analytics providers into usage-based consumption models.
Pricing Analysis
Certification level creates the primary spread between premium and standard tiers, with ISO/IEC 27001 and EU AI Act explainability compliance commanding 40-60% licensing uplifts over uncertified alternatives. Subscription pricing stratifies across real-time inference volume tiers, seat-based creative workflow bundles, and consumption-metered query architectures. Cost compression in sentiment analysis tooling is intensifying because open-source natural language libraries eliminate licensing friction. Mid-market advertising firms in India exhibit highest price sensitivity, while German media conglomerates absorbing EU AI Act compliance costs show lowest elasticity.
Supply Chain Analysis
Port congestion on Asia-Europe trade lanes elevates inbound logistics costs for edge-computing hardware destined to German stadium retrofit projects. Component supply concentrates in Taiwan for GPU accelerators, South Korea for high-bandwidth memory modules, and China for server chassis fabrication. Raw material dependencies span silicon wafers, rare earth elements for magnetic storage, and cobalt for battery-backed edge deployments. Single-source vulnerability in NVIDIA GPU allocation creates procurement bottlenecks for sub-100-millisecond inference pipelines. Distribution runs through hyperscale cloud marketplaces for software licensing, with hardware-software bundles deploying via systems integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU AI Act enforcement timelines compress decision windows for compliance architecture investments, forcing stakeholders to pre-position explainability layers before jurisdictional divergence hardens competitive moats.
For Market Incumbents: Consolidate around first-party data reservoir depth and captive cloud infrastructure to defend against federated learning disintermediation. Acquire specialized interpretability tooling vendors in Germany and the United Kingdom before EU AI Act deadlines eliminate acquisition targets. Lock in venue operator partnerships for biometric edge deployments in Hamburg and Munich stadium networks.
For New Entrants and Emerging Players: Human-in-the-loop review workflow gaps in mid-market Indian advertising firms present underexploited service-layer opportunities. Target Mumbai and Bangalore technology corridors with usage-based predictive analytics offerings that bypass capital-intensive server farm requirements. Lead with operational expense treatment and rapid ISO/IEC 27001 certification support as primary go-to-market angles.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-arbitrage play because jurisdictional divergence between FTC and ICO enforcement calendars creates persistent demand for multi-territory compliance solutions. Acquire regional infrastructure providers with federated learning capabilities and existing German venue operator relationships. Monitor EU AI Act penalty issuance velocity as the critical inflection signal for compliance tooling demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Acquisition of Edge-Computing Hardware Vendors | Captures bandwidth-constrained venue retrofit opportunities in German stadiums and US concert halls. |
| Strategic Partnership with Venue Operators | Locks in biometric preprocessing deployments ahead of competitor cloud-native infrastructure plays. |
| ISO/IEC 27001 Certification Acceleration | Compresses audit cycles to nine-month intervals, differentiating against compliance-burdened rivals. |
| Federated Learning Architecture Deployment | Enables privacy-sensitive audience segmentation without hyperscale cloud data centralization. |
| Creative Workflow Platform Integration | Tethers analytics dashboards to Adobe's content production pipelines for premium pricing capture. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with advertising technology CTOs, media company data infrastructure architects, venue operator technology procurement leads, and compliance officers at EU-regulated platform operators. Secondary validation drew from SEC 10-K filings of listed cloud infrastructure providers, TRAI data localization guidance documents, EU AI Act implementation timelines, and ISO/IEC 27001 certification registry databases. Bottom-up segment sizing triangulated against top-down macroeconomic anchoring across deployment modes, solution types, and geographic adoption clusters.
Across the analysis window, the forecasting framework modeled cloud versus edge versus on-premise infrastructure splits, real-time versus predictive versus sentiment solution tier trajectories, and media company versus advertising firm versus event organizer vertical penetration patterns. CAGRs were derived from elasticity-adjusted adoption curves incorporating latency threshold engineering constraints and regulatory compliance cost absorption rates. Federated learning deployment velocity and open-source library substitution effects served as industry-specific demand modifiers.
Material uncertainties — EU AI Act enforcement calibration divergence, FTC dark pattern scrutiny escalation, and GPU supply allocation shocks — sit outside the modeled envelope. Forecasts reflect assumptions around nine-month certification cycle sustainability and sub-100-millisecond pipeline engineering talent availability. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Social Media Analytics
Audience Intelligence Platforms Market
Social Media Analytics
Germany Social Media Management Market
Social Media Analytics
China Social Media Management Market
Social Media Analytics
Italy Social Media Management Market
Social Media Analytics
Social Advertising Tools Market
Social Media Analytics
Social Media Records Management Market
Social Media Analytics
Global TV Analytics Market
Social Media Analytics
US Social Media Management Market
Social Media Analytics
Europe Social Media Analytics Market
Social Media Analytics
Brazil Social Media Management Market
Social Media Analytics
Europe Social Media Management Market
Social Media Analytics
Social Media Management Market
Social Media Analytics
Social Media Analytics Market
Social Media Analytics
Media Monitoring Tools Market
Social Media Analytics
Social Media Listening Market