
 Audience Intelligence Platforms Market | 2026-2036
Audience Intelligence Platforms Market Size, Share, and Industry Trends Forecast 2026-2036
Audience Intelligence Platforms Market Outlook
Market Context
The capital-intensity divergence between cloud-native specialists and legacy enterprise suites is reorganizing competitive tiers in audience intelligence. Sprinklr leverages its unified customer experience infrastructure to anchor premium deployments for multinational brands. Brandwatch sustains technology leadership through proprietary NLP architectures that process multilingual social signals at scale. GWI differentiates via panel-based first-party data that competes directly with inferred behavioral models.
Technical Definition and Structural Segments
Audience intelligence platforms are software systems that aggregate, process, and analyze consumer behavioral signals from digital and offline sources to generate actionable segmentation and targeting guidance for commercial communicators. These platforms typically ingest structured and unstructured data through APIs and web crawlers, apply machine learning classification with sub-second latency requirements, and output audience profiles mapped to media activation endpoints. ML Technologies and NLP Tools dominate current deployment value, while Predictive Modeling represents the fastest-expanding capability layer as brands shift from descriptive reporting to anticipatory audience behavior forecasting. Cloud-Based deployment absorbs the majority of new capacity, though Hybrid Solutions command margin premiums among regulated sectors requiring data residency controls.
Regulatory Frame and Outlook
The EU AI Act classifies certain audience profiling systems as high-risk, imposing conformity assessment obligations that reshape product development roadmaps for vendors serving European enterprises. The GDPR's automated decision-making restrictions and the US state-level privacy patchwork—California's CCPA/CPRA, Virginia's VCDPA, Colorado's CPA—fragment compliance engineering requirements across deployment architectures. Stakeholders must monitor emerging algorithmic accountability standards in Brazil's LGPD enforcement trajectory and India's Digital Personal Data Protection Act implementation to anticipate next-wave market access conditions.
Market Dynamics
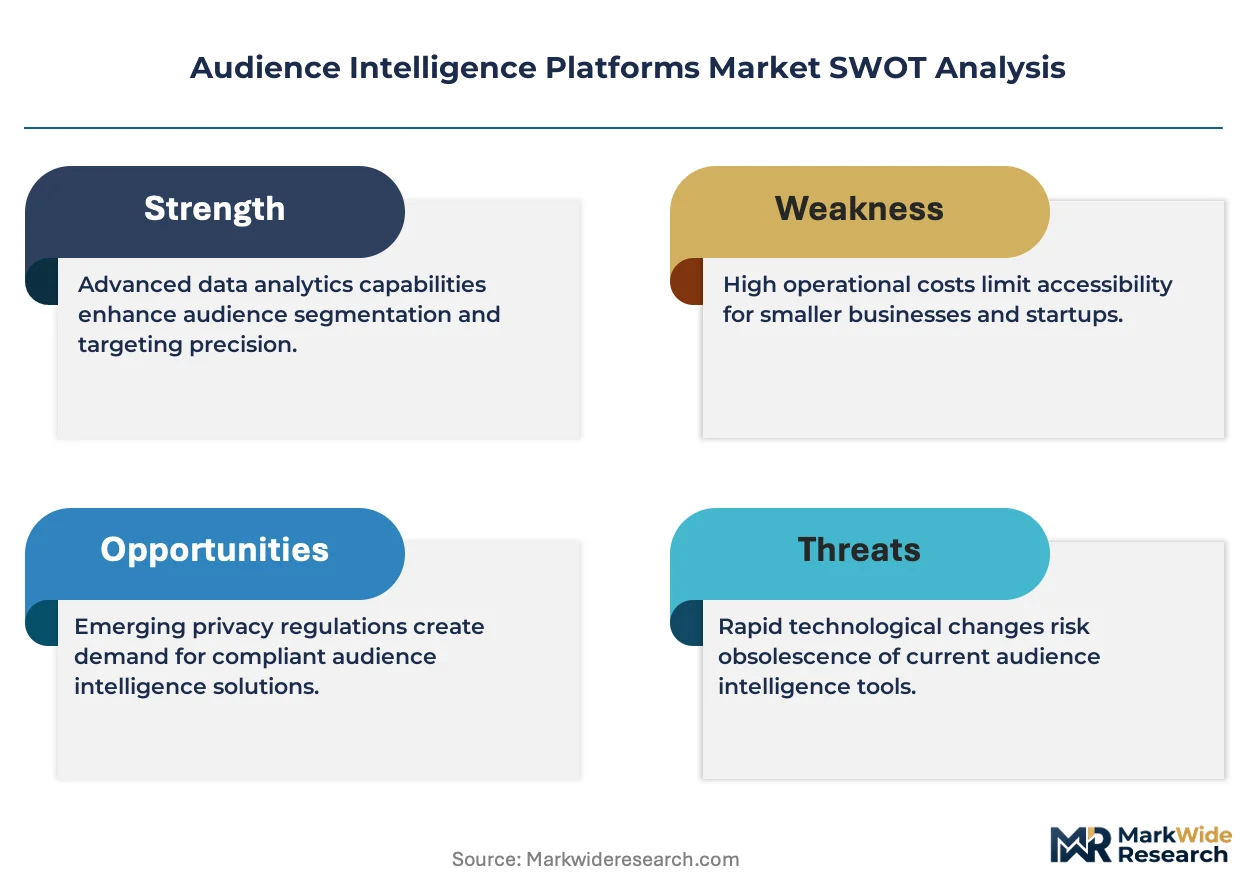
The market's central structural force is the collision between real-time behavioral data processing demands and tightening algorithmic accountability mandates across major economies. This tension is compressing vendor margins while elevating privacy-preserving architectures to competitive differentiators.
Growth Catalysts
- EU AI Act Conformity Assessments:The high-risk classification of certain audience profiling systems is accelerating vendor investment in auditable ML pipelines. European enterprises now prioritize vendors with pre-certified architectures.
- Retail Media Networks:First-party data monetization by retailers like Walmart and Target is creating new demand signals for audience intelligence platforms that bridge retail and brand ecosystems.
- Multilingual NLP:Proprietary natural language processing architectures capable of processing non-English social signals at scale are unlocking expansion into Southeast Asian and Middle Eastern markets.
Market Restraints
- Cloud Infrastructure Concentration:Overreliance on hyperscale cloud providers for sub-second latency processing creates single-point-of-failure risk and limits negotiation leverage on compute pricing.
- GDPR Automated Decision-Making Restrictions:The prohibition on solely automated decisions with legal or significant effects constrains predictive modeling deployment for credit, insurance, and employment verticals in Europe.
- First-Party Data Scarcity:The depreciation of third-party cookies is bifurcating data access between large platforms with logged-in user bases and mid-tier vendors dependent on inferred behavioral models.
Strategic Opportunities
- Brazil LGPD Enforcement Trajectory:Emerging algorithmic accountability standards in Latin America's largest digital advertising market create first-mover positioning for privacy-preserving analytics vendors.
- Edge Computing Convergence:The pairing of on-device inference with federated learning architectures enables real-time personalization without centralizing sensitive behavioral data.
- Outcome-Based Pricing Models:Media agencies and brand direct procurement teams are piloting platform fees tied to verified audience reach or conversion lift rather than seat-based subscriptions.
Industry Challenges
- ML Operations Talent Scarcity:The specialized engineering required for sub-second latency classification and model drift monitoring commands premium compensation that strains mid-cap vendor economics.
- Legacy Stack Integration Complexity:Enterprise marketing technology environments built on decades of point solutions demand costly custom API development and data harmonization workstreams.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Audience Intelligence Platforms Market |
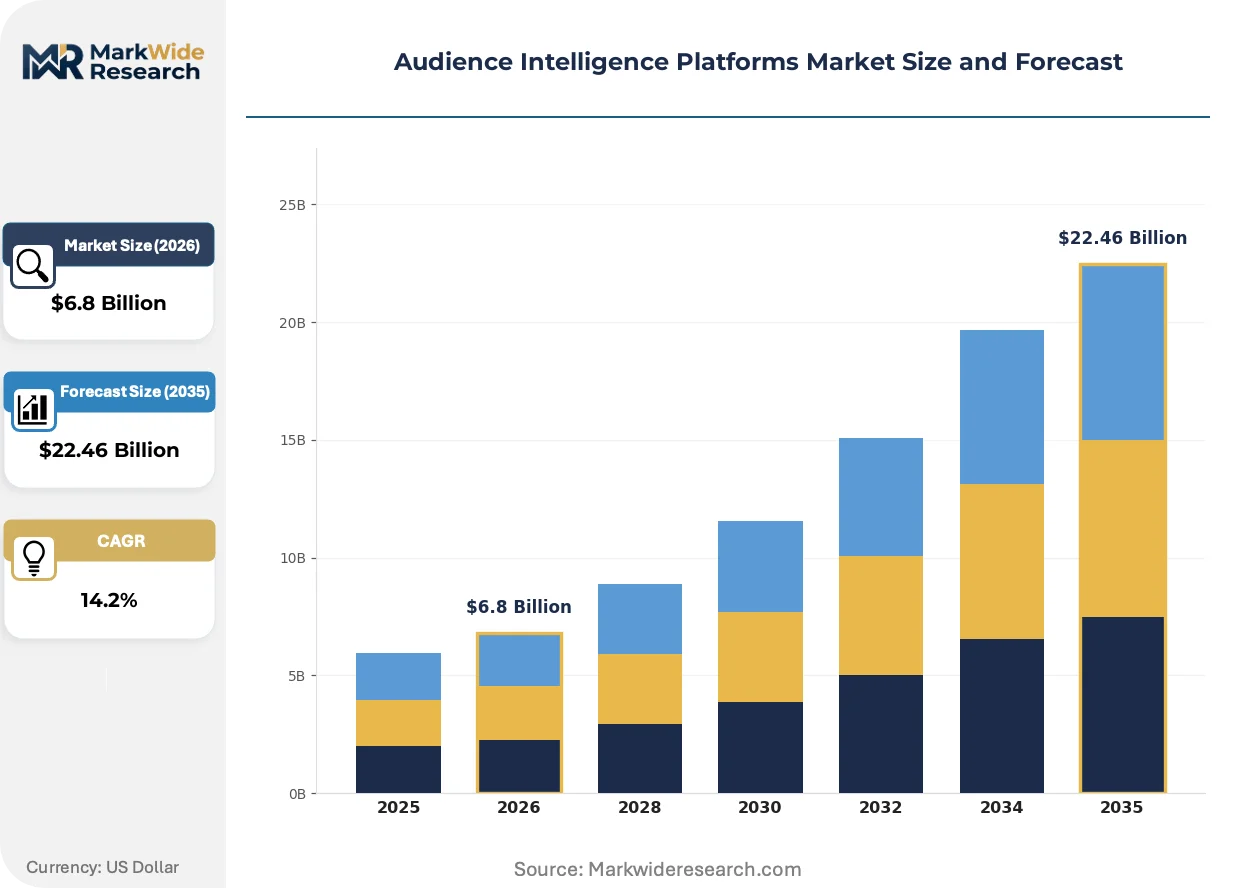
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $22.46 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: ML Technologies, NLP Tools, Data Analytics, Predictive Modeling Application: Social Media Monitoring, Ad Targeting, Customer Segmentation, Content Personalization End User: Marketing Agencies, Retail Brands, Publishers, Corporations Deployment: Cloud-Based, On-Premise, Hybrid Solutions, Mobile Platforms |
| Companies Covered | Meltwater, Pulsar, GWI, Talkwalker, Sprinklr, Brandwatch, YouScan, Salesforce Data 360, Adobe Analytics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Audience Intelligence Platforms Market Strategic Shifts
Real-time signal processing architectures are displacing batch-oriented analytics as the default expectation among enterprise buyers. This shift is compressing vendor development cycles and elevating infrastructure engineering to core competitive capability.
Federated learning infrastructure is bifurcating the vendor landscape between cloud-native specialists offering distributed training capabilities and legacy suites dependent on centralized data lakes. Retail media networks and pharmaceutical marketers are adopting these architectures fastest. The structural consequence is a margin squeeze on vendors lacking edge-deployment expertise while privacy-preserving specialists capture premium pricing.
The EU AI Act's high-risk system classification is forcing product roadmap recalibration for vendors serving European enterprises. Conformity assessment obligations now precede commercial deployment for profiling systems used in credit, insurance, and employment contexts. German and French enterprise procurement teams are prioritizing vendors with pre-certified technical documentation.
Buyer procurement patterns are rotating toward composable platform architectures that unbundle audience intelligence from broader customer experience suites. Mid-market brands in the United States are assembling best-of-breed stacks through API-first vendors rather than accepting bundled functionality from incumbent suites. This disaggregation is most visible in New York and San Francisco marketing technology procurement.
Audience Intelligence Platforms Market Segmentation
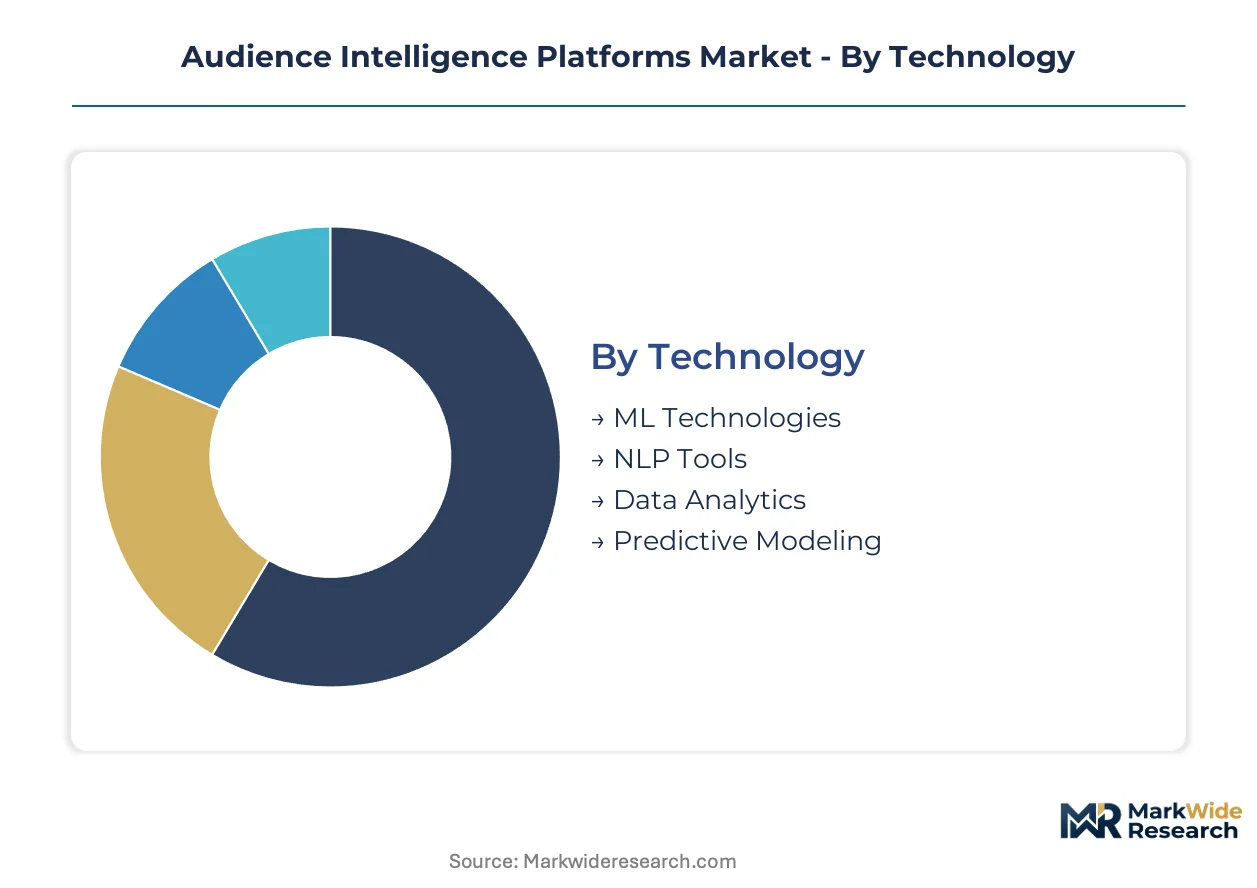
Segmentation in audience intelligence platforms determines how vendors allocate engineering resources and price their offerings. Buyers select technology combinations based on latency requirements, data sovereignty needs, and integration complexity with existing marketing stacks.
Technology:
Margin pools concentrate in proprietary NLP architectures and real-time ML inference engines where vendor differentiation is defensible.
- ML Technologies:Core classification and clustering engines process behavioral signals through supervised and unsupervised learning models. Financial services and pharmaceutical marketers in the United States drive demand for sub-second inference capabilities that support real-time bidding systems.
- NLP Tools:Multilingual semantic analysis systems extract sentiment and intent from unstructured text across social platforms and review sites. Southeast Asian market expansion depends heavily on proprietary NLP architectures that handle tonal languages without accuracy degradation.
- Data Analytics:Descriptive dashboards and attribution modeling for campaign performance measurement.
- Predictive Modeling:Anticipatory audience behavior forecasting using time-series and reinforcement learning approaches.
The dominant share belongs to ML Technologies, while Predictive Modeling is climbing the fastest as brands shift from reporting to anticipation.
Application:
Application selection tracks directly to buyer maturity, with sophisticated users unbundling point solutions from suites.
- Social Media Monitoring:Real-time tracking of brand mentions, competitor activity, and emerging conversation trends across platforms. Crisis communications teams at consumer packaged goods companies prioritize this capability for rapid response protocols.
- Ad Targeting:Audience activation for programmatic media buying with deterministic and probabilistic matching. Retail media networks at Walmart and Target require specialized integrations that bridge first-party retail data with brand advertising systems.
- Customer Segmentation:Clustering consumers by behavioral, demographic, and psychographic attributes for strategic planning.
- Content Personalization:Dynamic creative optimization and recommendation engines for owned-channel experiences.
Ad Targeting commands the largest deployment value, though Content Personalization shows the steepest expansion trajectory as brands invest in owned-channel retention.
End User:
End user type dictates pricing tolerance and implementation complexity, with enterprise direct buyers demanding outcome-based contracts.
- Marketing Agencies:Multi-client service providers requiring scalable seat-based access and white-label reporting capabilities. Holding company procurement teams in New York and London negotiate enterprise-wide platform licenses across portfolio agencies.
- Retail Brands:Direct-to-consumer and omnichannel retailers building first-party data assets for closed-loop measurement. Target and Best Buy operate retail media networks that monetize audience intelligence as a revenue stream.
- Publishers:Media companies optimizing inventory yield through audience-based selling and subscription conversion.
- Corporations:Non-marketing enterprises applying audience intelligence to investor relations, employer branding, and competitive intelligence.
Marketing Agencies retain the deepest platform penetration, while Retail Brands are gaining share fastest through retail media network expansion.
Deployment:
Deployment architecture selection reflects data residency requirements and latency sensitivity across regulated and unregulated use cases.
- Cloud-Based:Fully managed SaaS delivery with automatic scaling and shared infrastructure economics. The majority of new capacity deploys through AWS, Google Cloud, and Azure regions to minimize latency for real-time processing.
- Hybrid Solutions:Split architectures keeping sensitive data on-premise while leveraging cloud compute for model training. German automotive and pharmaceutical enterprises mandate this approach for GDPR compliance and trade secret protection.
- On-Premise:Self-managed installations for air-gapped environments and maximum data sovereignty control.
- Mobile Platforms:Edge-deployed inference on iOS and Android devices for on-device personalization without data centralization.
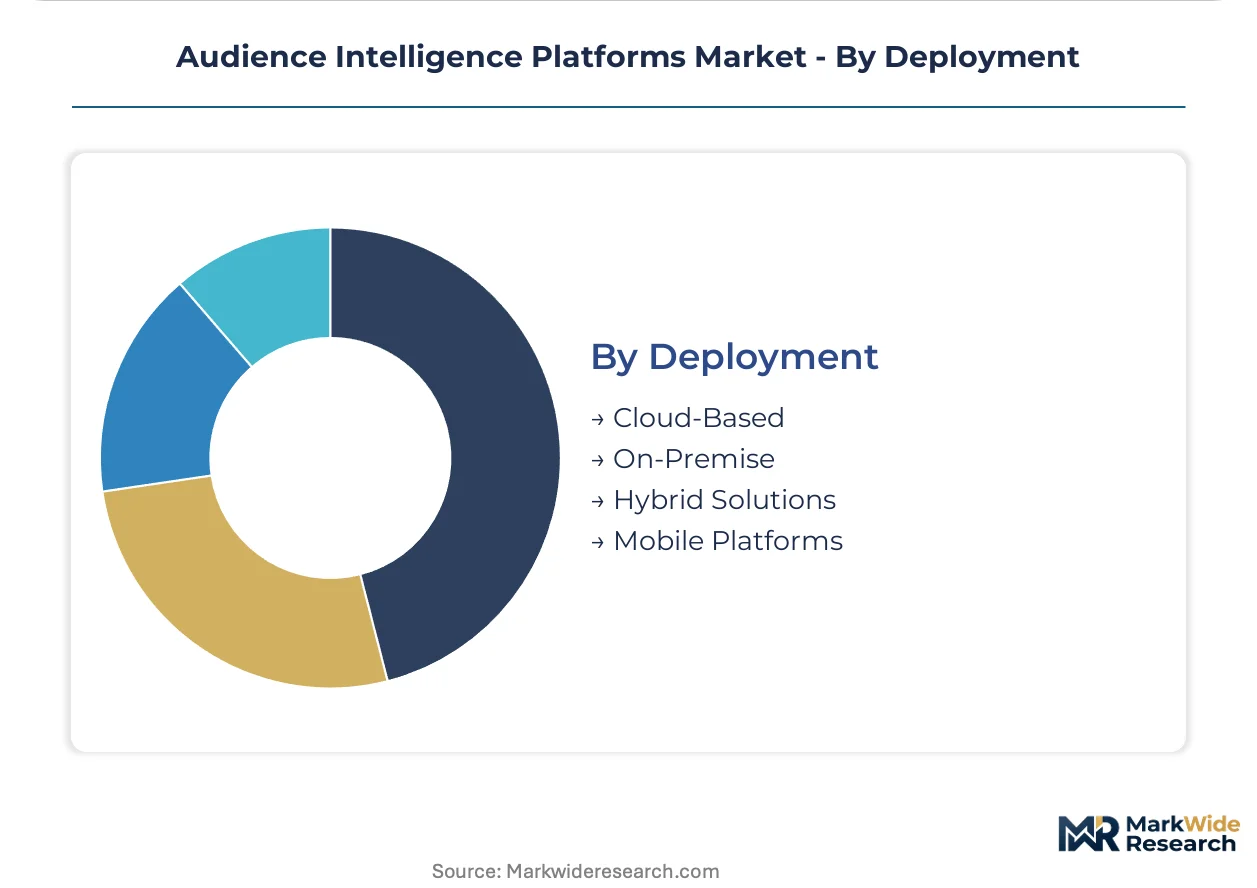
Cloud-Based deployments absorb most new capacity, though Hybrid Solutions capture the highest margins among regulated European and Middle Eastern enterprises.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies: US enterprises prioritize real-time bidding integration while European buyers emphasize auditable ML pipelines for regulatory compliance. This differential shapes vendor product roadmaps and pricing architectures.
United States
Enterprise marketing technology stacks in New York and San Francisco drive demand for sub-second latency classification and programmatic media activation. The FTC and state-level frameworks including California's CCPA/CPRA fragment compliance engineering requirements. Procurement teams at retail media networks in Minneapolis and Chicago pilot outcome-based platform contracts tied to verified conversion lift.
Germany
Automotive and pharmaceutical marketers mandate hybrid deployment architectures for GDPR compliance and trade secret protection. The EU AI Act imposes conformity assessment obligations on high-risk audience profiling systems used in credit and insurance contexts. Munich and Frankfurt host the densest concentration of enterprise procurement teams prioritizing pre-certified technical documentation.
United Kingdom
Marketing agencies in London negotiate enterprise-wide platform licenses across holding company portfolios. The Information Commissioner's Office enforces automated decision-making restrictions that constrain predictive modeling deployment for employment verticals. The Manchester and Birmingham tech corridors attract mid-market brands assembling best-of-breed stacks through API-first vendors.
France
Luxury goods and cosmetics marketers deploy multilingual NLP architectures for tonal language processing across Southeast Asian expansion. The CNIL coordinates with EDPB guidance on algorithmic accountability standards. Paris-based enterprise procurement teams prioritize vendors with documented conformity assessment procedures for EU AI Act compliance.
Brazil
Digital advertising investment in São Paulo and Rio de Janeiro creates first-mover positioning for privacy-preserving analytics vendors. ANVISA and emerging LGPD enforcement trajectories reshape algorithmic accountability expectations. Local media agencies demand platforms bridging first-party retail data with brand advertising systems for closed-loop measurement.
Audience Intelligence Platforms Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier in audience intelligence platforms. Cloud-native specialists with federated learning capabilities command margin premiums while legacy enterprise suites face compression from unbundling procurement patterns. Two strategic archetypes dominate: unified customer experience infrastructure providers and proprietary NLP architecture specialists. Competitive moves concentrate on M&A for ML operations talent and strategic partnerships with retail media networks.
Within the integrated infrastructure tier, Sprinklr and Salesforce Data 360 exemplify vendors anchoring premium deployments through unified customer experience platforms. Brandwatch occupies a position among specialists with proprietary natural language processing capabilities. Adobe Analytics represents the analytics suite incumbents adapting product roadmaps for real-time signal processing demands. GWI sits within the panel-based first-party data archetype competing directly with inferred behavioral models.
| Leading Market Players |
|---|
| Meltwater |
| Pulsar |
| GWI |
| Talkwalker |
| Sprinklr |
| Brandwatch |
| YouScan |
| Salesforce Data 360 |
| Adobe Analytics |
| Others |
Value Chain & Pricing Dynamics
Capacity reservation contracts with hyperscale cloud providers lock in compute access for sub-second latency processing while anchoring price visibility for enterprise SaaS tiers. These arrangements concentrate procurement leverage among vendors with sufficient scale to negotiate multi-year commitments across AWS, Google Cloud, and Azure regions.
Pricing Analysis
Seat-based subscription tiers dominate enterprise contracts, with pricing stratifying across premium, standard, and economy levels based on data volume throughput and real-time inference latency guarantees. GDPR compliance certification and EU AI Act pre-certification command 15-25% premiums over baseline SaaS rates. Cost compression in mid-market tiers is intensifying because retail media networks are piloting outcome-based contracts tied to verified conversion lift rather than fixed subscriptions. Marketing agencies exhibit highest price sensitivity due to multi-client margin pressure, while pharmaceutical marketers show lowest sensitivity given regulatory compliance imperatives.
Supply Chain Analysis
Just-in-time provisioning of GPU compute clusters prevails among cloud-native specialists, though strategic stockpiling of specialized ML accelerators is emerging among vendors anticipating export control restrictions. Supply concentrates in United States, Ireland, and Singapore data center regions for latency-optimized delivery. Raw material dependencies span NVIDIA H100/A100 GPUs, high-bandwidth memory modules, and optical interconnect hardware. Single-source vulnerability around NVIDIA's datacenter GPU allocation creates bottleneck risk for training-intensive workloads. Distribution runs through direct enterprise sales teams with embedded solutions architects rather than channel partners.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Audience intelligence platforms sit in early-cycle expansion as retail media networks and privacy-preserving architectures unlock new deployment categories beyond traditional social listening. Federated learning adoption is accelerating penetration into regulated verticals previously inaccessible to centralized data models.
For Market Incumbents: Fortify defensive moats through backward integration into proprietary NLP training infrastructure rather than relying on open-source model fine-tuning. Pre-certification investments for EU AI Act high-risk system classifications will lock out mid-tier competitors from German and French enterprise procurement cycles. Channel control through exclusive retail media network partnerships at Walmart and Target limits entrant access to first-party data monetization workflows. For New Entrants and Emerging Players: Differentiate on edge-deployed inference capabilities that enable real-time personalization without centralizing sensitive behavioral data. Brazil's LGPD enforcement trajectory represents the most penetrable geography, with São Paulo-based media agencies demanding platforms that bridge first-party retail data with brand advertising systems. A vertical-specific go-to-market targeting pharmaceutical marketers in the United States bypasses incumbent saturation in generalist social monitoring. For Investors and Strategic Acquirers: Cloud-native specialists with federated learning engineering teams offer the strongest acquisition target archetype for platform consolidation plays. Long-term viability hinges on 5-10 year algorithmic accountability regime maturation across Brazil, India, and Southeast Asian markets. The signal to watch is ANVISA guidance alignment with EU AI Act conformity assessment procedures, which would validate privacy-preserving architecture premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Retail Media Network Partnership | Walmart and Target first-party data integrations unlock closed-loop measurement capabilities for brand advertisers. |
| Federated Learning Infrastructure Buildout | Edge-deployed training architectures satisfy GDPR automated decision-making restrictions for European pharmaceutical marketers. |
| EU AI Act Pre-Certification Investment | Documented conformity assessment procedures secure procurement priority from Munich and Frankfurt enterprise buyers. |
| Multilingual NLP Architecture Acquisition | Proprietary tonal language processing capabilities enable Southeast Asian market expansion without accuracy degradation. |
| Outcome-Based Pricing Model Pilot | Conversion-lift contracts align vendor incentives with retail media network performance metrics. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of SEC filings, hyperscaler capex disclosures, and EU regulatory guidance documents. Chief technology officers, IT procurement officers at enterprise marketing stacks, platform integration specialists, and retail media network data science leads provided structured input across New York, San Francisco, London, and São Paulo. Bottom-up triangulation against top-down market sizing validates deployment volume estimates across cloud-native and legacy vendor categories.
Segmentation dimensions modeled span deployment architecture, organization size, vertical industry, integration complexity with existing martech stacks, and regional regulatory framework. CAGRs were derived through logarithmic trend fitting of historical adoption curves and forward projection of compliance-driven replacement cycles. Real-time inference latency requirements and GDPR automated decision-making restriction enforcement trajectories served as primary forecast sensitivity inputs across the analysis window.
The analysis sits within stated boundaries; outcomes outside sustained retail media network expansion or accelerated EU AI Act enforcement timelines would require recalibration. Forecasts reflect assumptions regarding cloud infrastructure pricing stability and ML operations talent availability. Revision becomes warranted when hyperscale GPU allocation constraints cross thresholds that materially extend model training cycles for mid-tier vendors.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Social Media Analytics
Italy Social Media Management Market
Social Media Analytics
Global Audience Analytics Market
Social Media Analytics
Social Media Listening Market
Social Media Analytics
Social Media Analytics Market
Social Media Analytics
Germany Social Media Management Market
Social Media Analytics
Brazil Social Media Management Market
Social Media Analytics
Europe Social Media Management Market
Social Media Analytics
China Social Media Management Market
Social Media Analytics
Media Monitoring Tools Market
Social Media Analytics
Social Advertising Tools Market
Social Media Analytics
Social Media Management Market
Social Media Analytics
US Social Media Management Market
Social Media Analytics
Social Media Records Management Market
Social Media Analytics
Global TV Analytics Market
Social Media Analytics
Europe Social Media Analytics Market