
 US Social Media Management Market | 2026-2036
US Social Media Management Market Size, Share, and Industry Trends Forecast 2026-2036
US Social Media Management Market Insights
California's SaaS developer ecosystem is rebalancing capacity toward AI-native workflow tools for social media orchestration. Hootsuite leverages its established channel partnerships to sustain platform-agnostic scheduling dominance across mid-market accounts. Sociallyin anchors its position through specialized creator-network relationships that differentiate it from generalist competitors. Power Digital occupies the performance-marketing niche, competing on attribution depth rather than content production scale.
Social media management encompasses the strategic planning, automated publishing, audience engagement, and performance analytics executed across digital social platforms to build brand equity and drive commercial outcomes. Core technical functions include API-driven multi-platform content distribution, sentiment analysis engines, and real-time engagement response protocols designed to maintain consistent brand voice at scale. Cloud-based SaaS deployment models lead structural adoption among enterprises seeking elastic compute for campaign spikes, while content creation services capture disproportionate margin pools due to labor intensity and creative specialization. Small business demand for bundled analytics and advertising services represents the fastest-expanding segment as self-serve tools lower operational barriers.
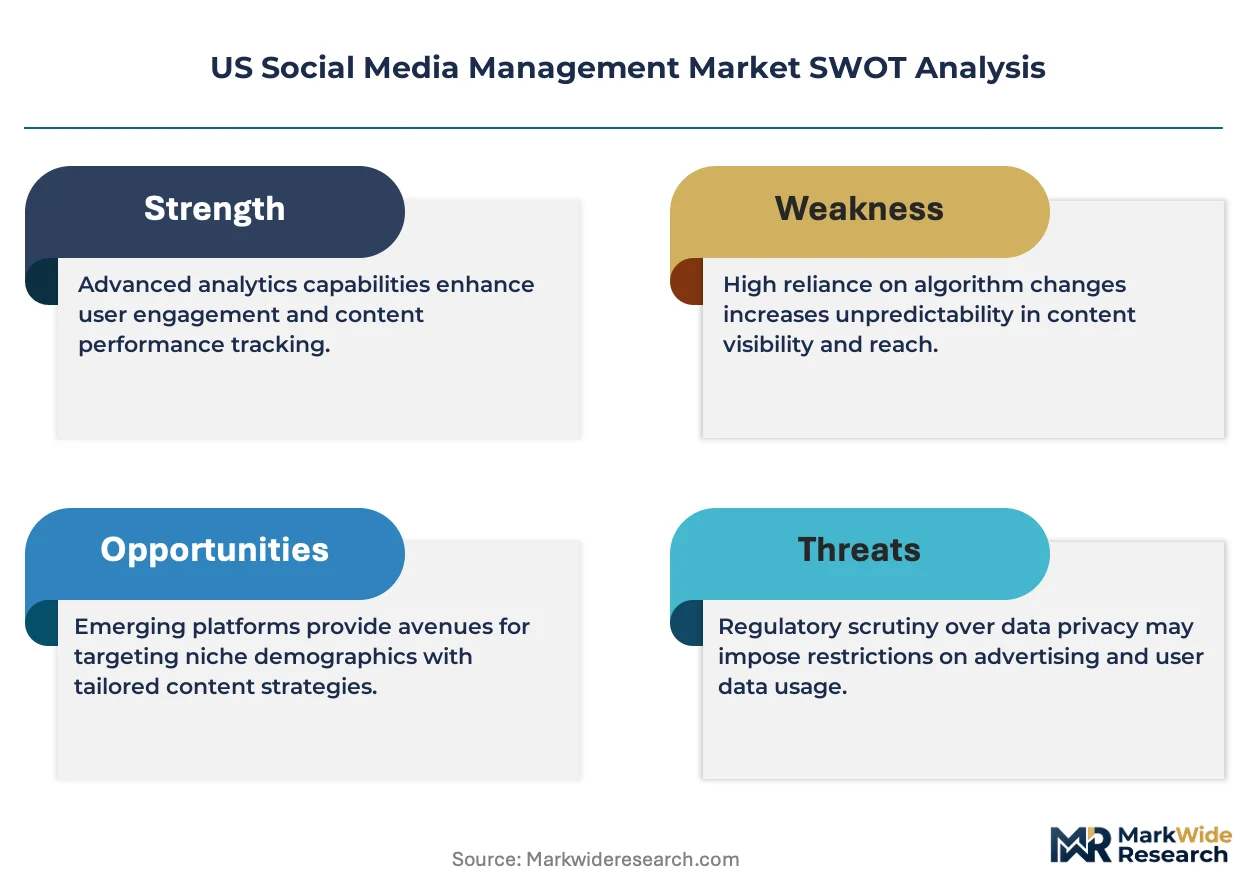
The Federal Trade Commission enforces disclosure standards for sponsored content, compelling management platforms to embed automated compliance tagging that shapes product roadmaps and client retention. The Securities and Exchange Commission monitors social media communications by publicly traded firms, creating specialized demand for archival and audit-trail functionality among enterprise buyers. Stakeholders must weigh platform dependency risks against the operational efficiency of consolidated management stacks as algorithmic shifts and regulatory scrutiny intensify simultaneously.
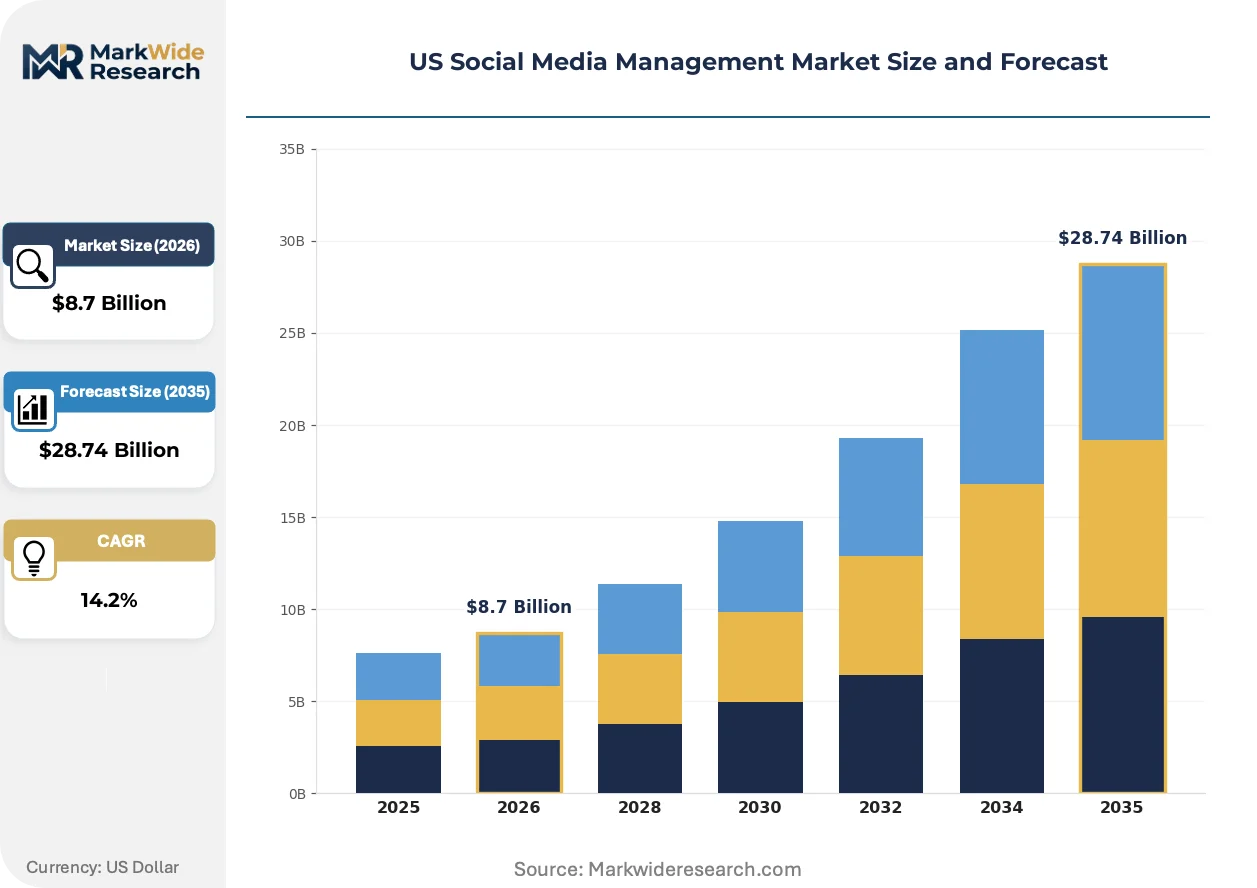
Market Dynamics
The FTC's updated endorsement disclosure mandates and algorithmic transparency requirements are compressing campaign approval timelines and forcing platform providers to embed compliance automation into core workflows.
Growth Catalysts
- Creator economy infrastructure:Direct-to-consumer retailers are scaling dedicated social commerce teams that require orchestration tools for multi-platform content distribution and real-time performance tracking.
- FTC disclosure automation:Federal enforcement of sponsored content tagging is driving enterprise procurement of management platforms with built-in compliance verification and audit trail generation.
- California SaaS density:The San Francisco-Los Angeles corridor concentrates AI-native workflow developers whose tools reduce content production cycle times for mid-market brand teams.
Market Restraints
- Platform API dependency:Algorithmic feed changes by Meta, TikTok, and X create unpredictable reach volatility that management platforms cannot hedge through technical means alone.
- Talent cost inflation:Specialized creator-network managers and short-form video editors command premium compensation that compresses service provider margins in content creation segments.
- SEC archival mandates:Publicly traded firms face elevated compliance costs for social media record-keeping requirements that smaller competitors cannot amortize across client bases.
Strategic Opportunities
- Mid-market self-serve penetration:Bundled analytics-advertising packages targeting sub-50-employee retailers in Texas and Florida represent underexploited demand pools.
- AI-native workflow convergence:Generative content engines integrated with scheduling automation are compressing creative production timelines for enterprise campaign teams.
- Infrastructure Act digital equity programs:Federal broadband expansion into rural counties is creating first-time social media management demand among geographically isolated small businesses.
Industry Challenges
- Cross-functional talent scarcity:Professionals combining data analytics fluency with platform-native creative judgment remain concentrated in New York and California metro areas.
- Multi-platform integration complexity:Legacy CRM and e-commerce systems require costly middleware development to achieve real-time social data synchronization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Social Media Management Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Platform Type: Facebook, Instagram, Twitter, LinkedIn Service Type: Content Creation, Analytics, Engagement, Advertising End User: Small Businesses, Enterprises, Agencies, Nonprofits Deployment Model: Cloud-Based, On-Premises, Hybrid, SaaS |
| Companies Covered | Fresh Content Society, Sociallyin, Hootsuite, Ignite Social Media, Thrive Internet Marketing Agency, Firebelly Marketing, Sculpt, Power Digital, Hawke Media, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Social Media Management Market Trends and Innovations
Generative AI is compressing content production timelines while regulatory disclosure mandates reshape platform feature roadmaps. Buyer procurement patterns are shifting toward integrated analytics-advertising bundles.
Natural language generation models are automating first-draft caption writing and visual asset variation testing for high-volume retail campaigns. Mid-market direct-to-consumer brands in California and New York are deploying these tools at scale to maintain posting frequency without linear headcount expansion. The technology is automating routine creative tasks that previously consumed 40-60% of junior strategist hours.
The FTC's updated endorsement guidelines now require automated disclosure tagging for all compensated creator partnerships. Platform providers must embed compliance verification into publishing workflows or risk enterprise client attrition to competitors with audit-ready systems. Retail and financial services verticals in New York and Illinois are driving procurement decisions based on archival and traceback capabilities.
Self-serve procurement of bundled analytics and paid media management is displacing traditional agency retainer relationships among sub-500-employee retailers. These buyers now prioritize tools with native advertising API access over standalone scheduling platforms. The pattern is most visible in Texas and Florida metropolitan areas where digital advertising spend growth outpaces national averages.
US Social Media Management Market Segmentation
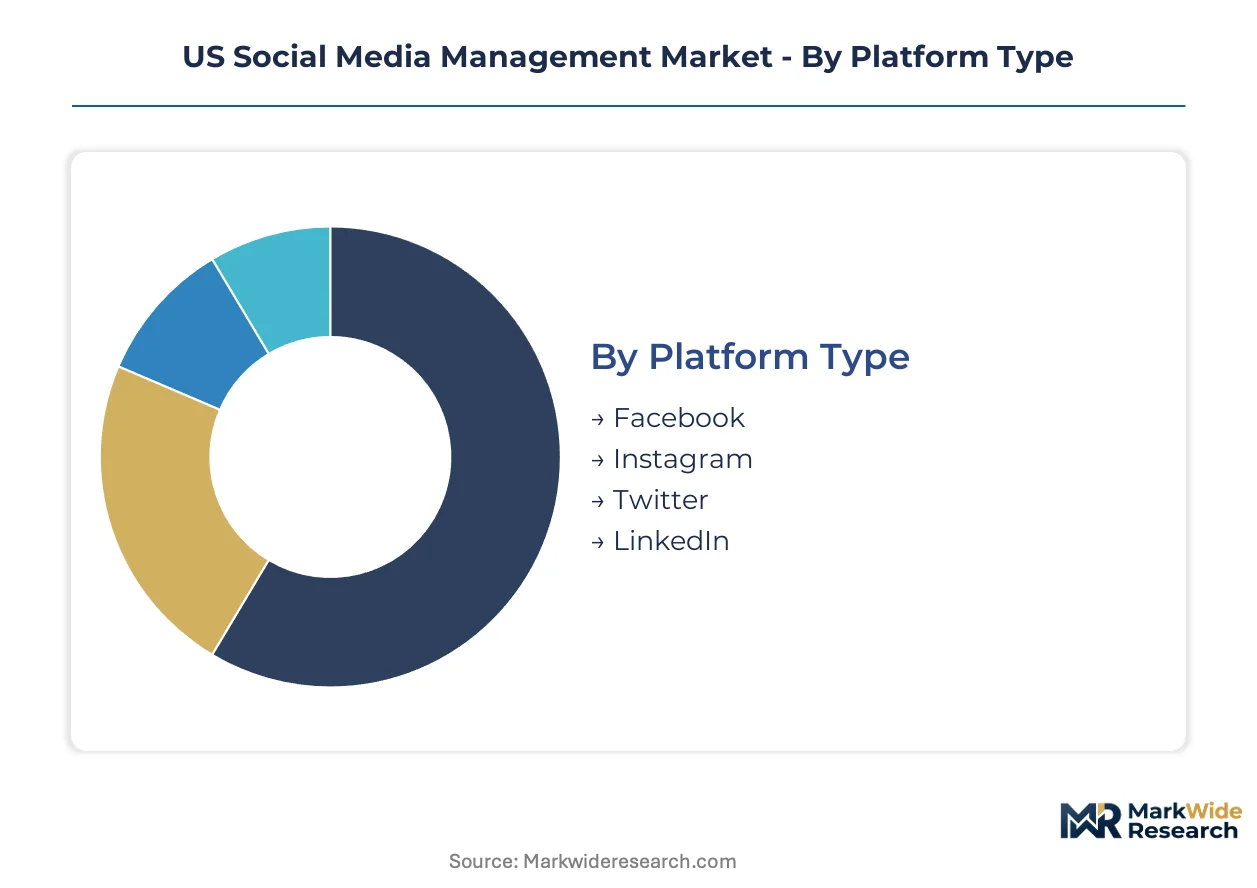
Platform heterogeneity and regulatory complexity create divergent capability requirements across buyer segments. Procurement patterns cluster around deployment sophistication and compliance burden rather than firm size alone.
Platform Type:
FTC disclosure mandates apply unevenly across platforms, with video-centric networks requiring automated tagging infrastructure that text-based platforms do not.
- Facebook:Meta's advertising API and commerce integrations support the most mature attribution tooling for direct-to-consumer retailers. California-based enterprise buyers concentrate procurement here due to native Shops functionality and first-party data access post-iOS privacy changes.
- Instagram:Visual-first format demands specialized creator-network management and short-form video production workflows. New York fashion and beauty brands drive premium service spend for Reels orchestration and influencer compliance automation.
- Twitter:Real-time engagement protocols and SEC-mandated archival requirements dominate enterprise procurement decisions. Financial services firms in Illinois and Texas prioritize audit-trail functionality for executive communications.
- LinkedIn:B2B lead generation and professional content distribution require distinct workflow tooling. Enterprise technology vendors concentrate paid media management here for account-based marketing campaigns.
Facebook sits at the top of the volume ranking, with Instagram climbing the fastest among direct-to-consumer retailers expanding into social commerce.
Service Type:
Margin structures diverge sharply between labor-intensive creative production and software-driven analytics automation.
- Content Creation:Short-form video production and creator partnership management command premium pricing due to talent scarcity. New York and Los Angeles metro areas concentrate specialized editors and network managers whose compensation compresses agency margins.
- Analytics:Cross-platform attribution and sentiment analysis engines deliver scalable SaaS economics. Mid-market retailers in Texas and Florida prioritize bundled analytics-advertising packages over standalone scheduling tools.
- Engagement:Real-time response protocols and community management require 24/7 operational coverage. Nonprofit and advocacy organizations concentrate demand here for donor relationship maintenance.
- Advertising:Native API access for paid media management is displacing traditional agency retainer relationships. Self-serve procurement patterns favor platforms with direct billing integration over managed service intermediaries.
Advertising services generate the highest revenue concentration, with analytics expanding most quickly as AI-native tools compress reporting cycle times.
End User:
Compliance infrastructure requirements scale with public visibility and regulatory scrutiny rather than revenue alone.
- Small Businesses:Bundled self-serve tools with native advertising access lower operational barriers for sub-50-employee retailers. Federal broadband expansion into rural counties is creating first-time demand among geographically isolated service providers.
- Enterprises:FTC and SEC mandates drive procurement of audit-ready platforms with automated disclosure tagging and archival functionality. Publicly traded firms face elevated compliance costs that smaller competitors cannot amortize.
- Agencies:Multi-client workflow orchestration requires white-label analytics and cross-platform publishing automation. Creator-network specialization differentiates competitive positioning against generalist software providers.
- Nonprofits:Donor engagement and volunteer coordination prioritize cost-efficient scheduling over paid media management. Grant-funded operations constrain procurement to free-tier or heavily discounted SaaS offerings.
Enterprises dominate current procurement volume, with small businesses gaining share fastest as self-serve pricing tiers expand addressable market reach.
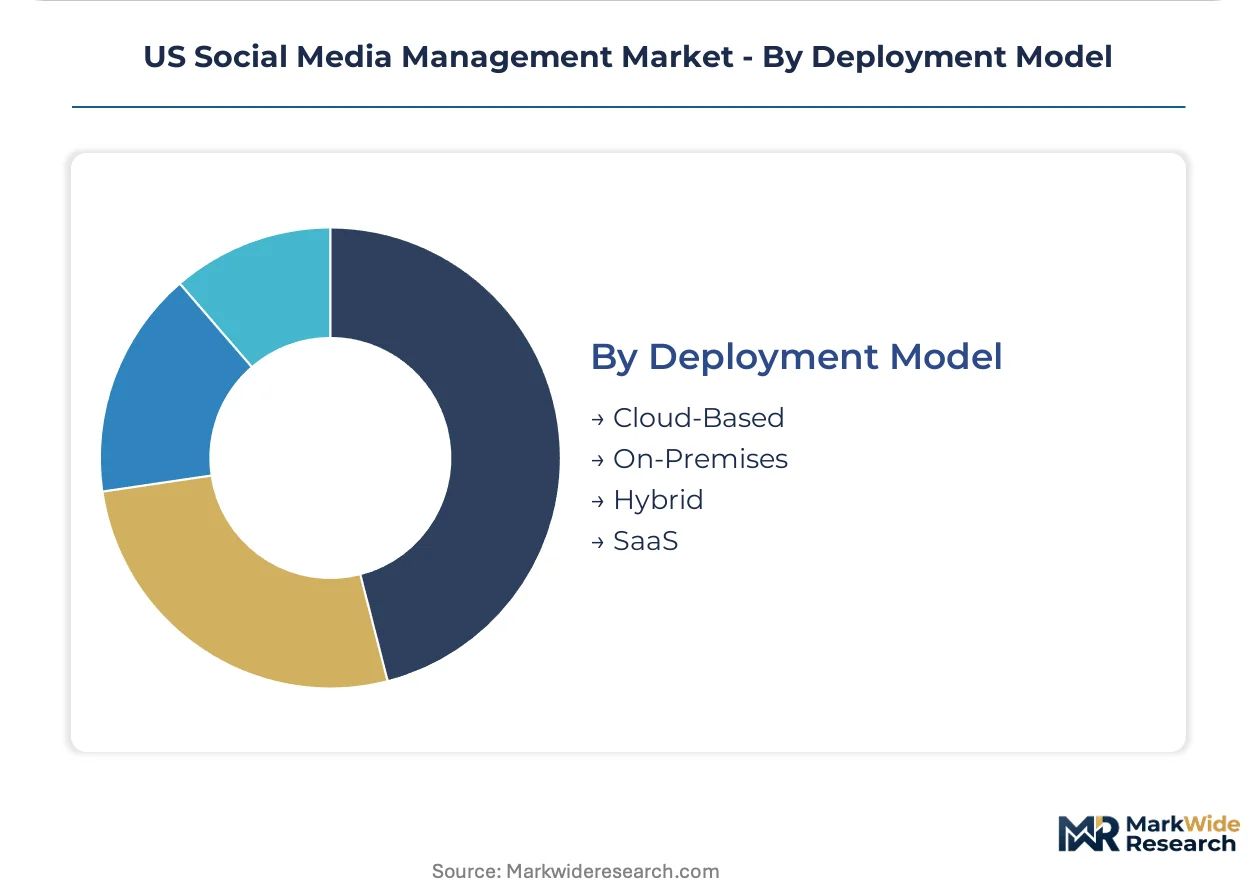
Deployment Model:
Data sovereignty requirements and integration complexity shape infrastructure decisions across regulated and unregulated verticals.
- Cloud-Based:Elastic compute for campaign spikes and multi-region content delivery supports enterprise scale. California SaaS density concentrates vendor development and buyer procurement in the San Francisco-Los Angeles corridor.
- On-Premises:Air-gapped archival systems satisfy SEC record-keeping mandates for publicly traded financial services firms. Compliance-driven procurement accepts higher total cost of ownership for audit certainty.
- Hybrid:Sensitive creative assets remain on-premises while publishing workflows leverage cloud APIs. Healthcare and government verticals prioritize this architecture for HIPAA-aligned social communications.
- SaaS:Subscription pricing and rapid feature deployment dominate mid-market adoption. Texas and Florida metropolitan areas show steepest expansion trajectory as digital advertising spend growth outpaces national averages.
Cloud-Based deployments lead current installation base, with SaaS gaining share fastest as vendor roadmaps prioritize API-native workflow automation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are minimal in social media management given the FTC's nationwide enforcement of endorsement disclosure rules, yet state-level digital infrastructure investments and creator economy clustering create measurable performance gaps across sub-regional markets.
California
San Francisco and Los Angeles anchor the densest concentration of SaaS developers building AI-native workflow tools for content orchestration. State-level privacy regulations including the California Consumer Privacy Act shape data handling protocols for platforms serving enterprise clients. The Bay Area-to-Los Angeles corridor generates disproportionate procurement volume as direct-to-consumer retailers cluster near creator talent pools and venture capital networks.
New York
Financial services and fashion verticals drive demand for SEC-compliant archival systems and influencer disclosure automation. The state's Department of Financial Services supervises social media communications by regulated institutions, elevating compliance infrastructure requirements. Manhattan-based agencies command premium pricing for creator-network management services that bundle FTC-mandated tagging with short-form video production.
Texas
Dallas-Fort Worth and Austin metropolitan areas show steepest growth in self-serve platform adoption among sub-500-employee retailers. Federal Infrastructure Act broadband expansion into rural counties is creating first-time management tool demand among geographically isolated service providers. Austin's emerging tech corridor attracts mid-market SaaS vendors targeting bundled analytics-advertising procurement patterns.
Illinois
Chicago-based financial services firms prioritize audit-trail functionality for executive social media communications under SEC supervision. The state's manufacturing and logistics verticals generate steady demand for B2B LinkedIn campaign management and professional content distribution. Regional procurement favors hybrid deployment models that keep sensitive creative assets on-premises while leveraging cloud publishing APIs.
Florida
Miami and Tampa metropolitan areas concentrate hospitality and real estate marketing spend on visual-first platform management. State-level economic development incentives for digital media production are attracting creator economy infrastructure investment. Regional buyers show above-average preference for bundled self-serve tools with native advertising API access over traditional agency retainers.
US Social Media Management Market Competitive Landscape
California-based platform developers anchor the software tier; New York and Chicago specialists hold the managed services tier. The market structure fragments across three distinct capability layers: enterprise-grade compliance platforms, mid-market self-serve tools, and creative production agencies. Strategic archetypes include API-native workflow automators, creator-network relationship brokers, and performance-marketing attribution specialists. Dominant competitive moves center on AI feature integration and vertical-specific compliance module development.
Within the established platform tier, Hootsuite occupies a position as a channel-agnostic scheduling anchor, while Sociallyin exemplifies the creator-network specialization archetype through differentiated influencer relationship infrastructure. Power Digital represents the performance-marketing positioning vector, competing on attribution depth rather than content production scale. These three companies illustrate how geographic clustering around California SaaS density and New York creative talent pools shapes competitive differentiation in adjacent market segments.
| Leading Market Players |
|---|
| Fresh Content Society |
| Sociallyin |
| Hootsuite |
| Ignite Social Media |
| Thrive Internet Marketing Agency |
| Firebelly Marketing |
| Sculpt |
| Power Digital |
| Hawke Media |
| Others |
Pricing and Supply Chain Analysis
Cloud compute pricing indices at AWS, Google Cloud, and Azure cascade through SaaS vendor cost structures into three-tier subscription tiers that separate enterprise compliance bundles from mid-market self-serve tools and freemium entry points.
Pricing Analysis
Direct-to-customer subscription margins compress as platform API access fees from Meta and TikTok absorb an expanding share of vendor cost bases. Pricing stratifies across premium enterprise compliance tiers with FTC-automated tagging, standard mid-market bundles with native advertising APIs, and economy self-serve tools with limited analytics depth. Cost compression in the creative services layer intensifies because specialized short-form video editors and creator-network managers command compensation premiums that agency margins cannot fully pass through. Small business buyers in Texas and Florida metropolitan areas exhibit highest price sensitivity, while publicly traded financial services firms in New York and Illinois accept premium pricing for SEC-compliant archival functionality.
Supply Chain Analysis
Dual-sourcing requirements for cloud infrastructure mandate that enterprise buyers qualify both AWS and Azure or Google Cloud for campaign spike elasticity, preventing single-vendor lock-in. Software development concentrates in the United States, India, and Eastern Europe, with San Francisco-Los Angeles corridor teams anchoring AI-native workflow innovation. Raw material dependencies include GPU compute cycles for generative content engines, API licensing fees from platform providers, and specialized creative talent pools concentrated in New York and Los Angeles metro areas. Supply chain risk centers on platform API dependency, where algorithmic feed changes by Meta, TikTok, and X create unpredictable reach volatility that management platforms cannot hedge through technical means alone. Distribution runs through direct sales teams for enterprise accounts, self-serve web portals for mid-market adoption, and agency partnerships for bundled creative production services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US Social Media Management Market functions as a stable compounder where regulatory disclosure mandates generate durable demand for compliance-automation infrastructure regardless of macroeconomic cycles.
For Market Incumbents: Hedge platform dependency risk by deepening creator-network relationship infrastructure that differentiates beyond scheduling commoditization. Invest in vertical-specific compliance modules for financial services and healthcare to capture SEC and HIPAA-aligned procurement. Defensive moves should prioritize API-native workflow automation that reduces client switching costs while embedding audit-trail functionality that satisfies FTC enforcement timelines. For New Entrants and Emerging Players: The price-point gap between premium enterprise compliance platforms and economy self-serve tools creates white-space opportunity for mid-market bundled analytics-advertising packages. Target sub-500-employee retailers in Texas and Florida metropolitan areas where digital advertising spend growth outpaces national averages and agency retainer displacement accelerates. Go-to-market positioning should emphasize native advertising API access with simplified compliance tagging that bridges the self-serve and managed-service divide. For Investors and Strategic Acquirers: Asymmetric upside sits with AI-native workflow developers whose generative content engines compress production timelines for high-volume retail campaigns. Long-term viability favors platforms with embedded compliance automation that deepens switching costs as FTC enforcement intensifies. Acquisition target archetype: mid-market SaaS vendors with proven self-serve adoption in Texas and Florida and nascent enterprise compliance functionality. Signal to watch: enterprise procurement RFPs that weight archival and traceback capabilities above content production scale.| Strategic Initiative | Industry Significance |
|---|---|
| AI-Native Workflow Integration | Generative content engines from California developers compress creative production timelines for enterprise campaign teams. |
| FTC Compliance Module Development | Automated disclosure tagging satisfies federal enforcement mandates that reshape platform feature roadmaps and client retention. |
| Mid-Market Self-Serve Expansion | Native advertising API access in bundled tools captures sub-500-employee retailers displacing traditional agency retainers. |
| Creator-Network Infrastructure Investment | Specialized influencer relationship management differentiates positioning against generalist scheduling competitors in New York. |
| Hybrid Deployment Architecture | Air-gapped archival systems satisfy SEC record-keeping requirements for publicly traded financial services firms in Illinois. |
Research Methodology
Multiple input streams — primary interviews with platform product managers, agency operations directors, and enterprise social media strategists, combined with secondary validation from SEC filings, FTC enforcement actions, and hyperscaler capex disclosures — were reconciled through bottom-up and top-down triangulation. Stakeholder conversations spanned SaaS vendor executives in California, creator-network specialists in New York, and mid-market retailer marketing leads in Texas and Florida. Secondary sources included platform API documentation, federal regulatory dockets, and digital advertising spend benchmarks from industry associations.
Data-stream reconciliation anchored the analytical framework across the analysis window, modeling segmentation by deployment model, organization size, vertical compliance burden, platform integration complexity, and regional adoption pattern. CAGRs were derived from trend extrapolation of self-serve penetration rates and enterprise compliance procurement cycles. Industry-specific forecast inputs incorporated FTC enforcement intensity projections and Infrastructure Act broadband expansion timelines into rural counties.
Caveats apply where platform algorithmic shifts, FTC enforcement escalation, or cloud infrastructure cost volatility could materially shift the outlook. Forecasts reflect assumptions about regulatory stability and API access continuity that deviation in Meta or TikTok platform policies would shift materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Social Media Analytics
Italy Social Media Management Market
Social Media Analytics
Social Media Listening Market
Social Media Analytics
Europe Social Media Analytics Market
Social Media Analytics
Social Advertising Tools Market
Social Media Analytics
Audience Intelligence Platforms Market
Social Media Analytics
Social Media Records Management Market
Social Media Analytics
Global Audience Analytics Market
Social Media Analytics
Media Monitoring Tools Market
Social Media Analytics
Germany Social Media Management Market
Social Media Analytics
Social Media Analytics Market
Social Media Analytics
Global TV Analytics Market
Social Media Analytics
Social Media Management Market
Social Media Analytics
Brazil Social Media Management Market
Social Media Analytics
China Social Media Management Market
Social Media Analytics
Europe Social Media Management Market