
 Social Advertising Tools Market | 2026-2036
Social Advertising Tools Market Size, Share, and Industry Trends Forecast 2026-2036
Social Advertising Tools Market Analytics
North American software engineering capacity is expanding as cloud-native development clusters in Seattle, San Francisco, and Toronto feed platform innovation. Meta leverages its first-party data architecture to sustain advertiser lock-in across Instagram and Facebook placements. Google competes through deep integration between Google Analytics and its broader cloud ecosystem. Hootsuite anchors its position among mid-market buyers who require multi-platform publishing workflows without enterprise complexity.
Social advertising tools are software platforms that automate campaign creation, audience targeting, bid management, and performance measurement across social networks, typically operating through API connections to platform ad managers and delivering real-time optimization algorithms. Their primary commercial purpose is to reduce customer acquisition costs while improving return on ad spend for brands running paid social campaigns. Programmatic advertising tools capture the largest margin pools as algorithmic buying commands premium pricing from performance marketers. Analytics tools represent the fastest-growing segment as attribution complexity rises across fragmented platform ecosystems. Social media management functions remain mature, with differentiation shifting from scheduling features to AI-powered content recommendations.
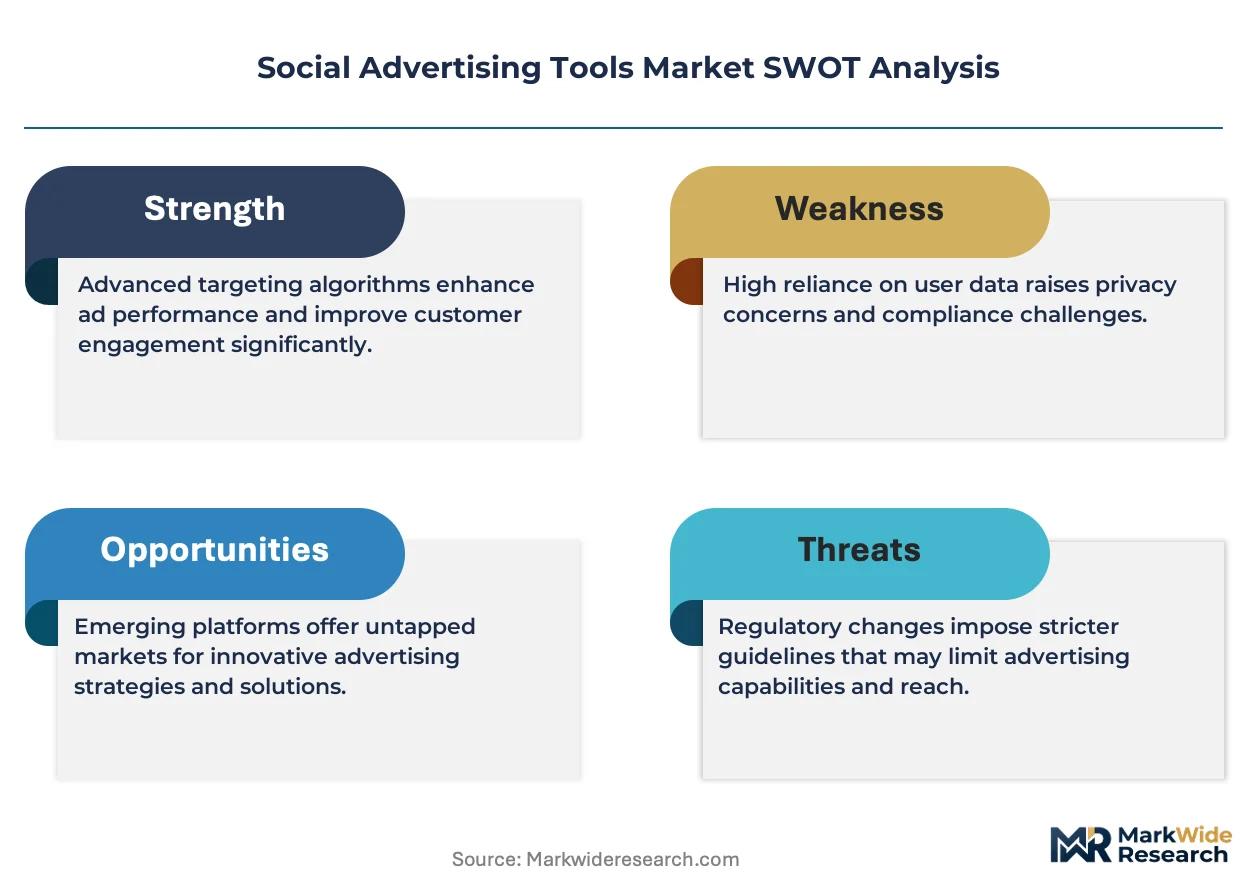
FDA oversight of health claims in pharmaceutical social advertising and FTC endorsement disclosure requirements shape creative compliance workflows that tool vendors must embed. The EU's GDPR and Digital Services Act impose data-handling and transparency obligations that restrict targeting granularity and mandate ad repository access. Stakeholders must monitor how platform API policy changes alter competitive moats for third-party tool vendors.
Market Dynamics
Platform API policy volatility is compressing third-party tool margins as Meta and Google tighten data access permissions, forcing vendors to rebuild core targeting and reporting functionality around diminished signal availability.
Growth Catalysts
- India's small-business digitalization:Platform penetration among micro-retailers and local service providers is outpacing mature-market saturation, creating fresh demand for simplified campaign automation tools.
- EU Digital Services Act transparency mandates:Ad repository APIs and algorithmic disclosure requirements are expanding the addressable market for compliance-embedded analytics modules.
- Generative creative workflows:AI-powered asset generation is reducing production bottlenecks for performance marketers managing high-velocity multivariate testing across Instagram, TikTok, and YouTube placements.
Market Restraints
- Signal loss from iOS privacy frameworks:Apple's ATT implementation has degraded deterministic attribution, forcing reliance on probabilistic modeling that increases customer acquisition cost volatility for direct-response advertisers.
- Cloud infrastructure concentration:AWS and Azure dominance in ad-tech compute creates vendor lock-in risk and limits price negotiation leverage for mid-scale tool providers.
- Platform self-serve tool improvement:Native ad managers from Meta and Google are absorbing functionality previously exclusive to third-party platforms, narrowing differentiation headroom.
Strategic Opportunities
- Brazil's underpenetrated SME segment:WhatsApp Business API expansion and rising Instagram commerce adoption among regional retailers creates whitespace for localized campaign automation.
- Retail media network convergence:Integration between social advertising tools and Amazon, Walmart, and Target ad platforms enables unified planning across social and commerce media.
- FTC endorsement disclosure automation:AI-powered content scanning for paid partnership tags and material connection flags addresses rising regulatory scrutiny of influencer marketing workflows.
Industry Challenges
- Cross-platform identity resolution:Fragmented user graphs across TikTok, Instagram, and emerging channels complicate frequency capping and sequential messaging execution.
- API deprecation cycles:Platform engineering teams retire endpoints with minimal notice, forcing emergency redevelopment sprints that destabilize product roadmaps.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Social Advertising Tools Market |
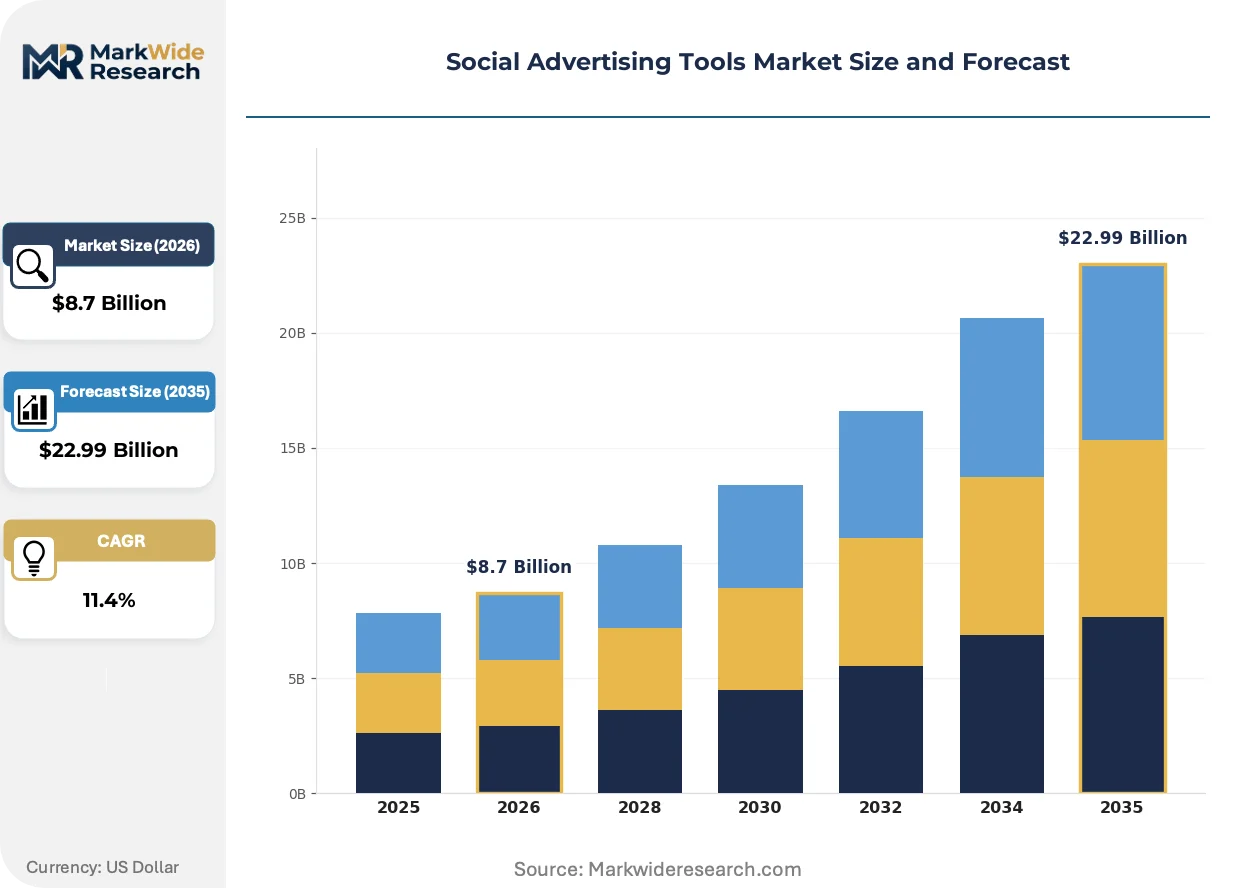
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Tool Type: Programmatic Advertising, Social Media Management, Ad Optimization, Analytics Tools Platform: Facebook, Instagram, Twitter, LinkedIn Target Audience: Small Businesses, Enterprises, Nonprofits, E-commerce Pricing Model: Subscription-Based, Pay-Per-Click, Tiered Pricing, Freemium |
| Companies Covered | Meta (Facebook Ads Manager), Google (Google Analytics), Hootsuite, Sprout Social, Buffer, Adobe, Semrush, HubSpot, Smartly.io, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Social Advertising Tools Market Evolving Landscape
Real-time optimization architectures are displacing rule-based automation as machine learning inference moves to edge deployment, compressing bid decision latency from minutes to milliseconds.
Predictive creative intelligence is integrating generative asset production with performance forecasting, enabling advertisers to simulate click-through and conversion outcomes before campaign launch. Mid-market e-commerce operators are adopting these capabilities fastest, replacing static creative libraries with dynamically assembled variants. The technology is integrating previously siloed creative and media planning functions into unified workflow platforms.
The EU AI Act's risk classification framework is imposing documentation and human oversight requirements on algorithmic ad targeting systems deployed within the European Economic Area. Tool vendors must now maintain model cards and audit trails for automated bidding logic. Performance marketing suites serving EU-based advertisers are responding by building explainability dashboards and manual override protocols.
Buyer concentration among direct-to-consumer aggregators is compressing sales cycles and unbundling implementation services from software subscriptions. Large holding companies are consolidating vendor relationships, demanding consolidated billing and cross-platform analytics. This pattern is most visible in North America, where agency holding company procurement teams are reducing approved vendor lists from twelve to three platforms.
Social Advertising Tools Market Segmentation
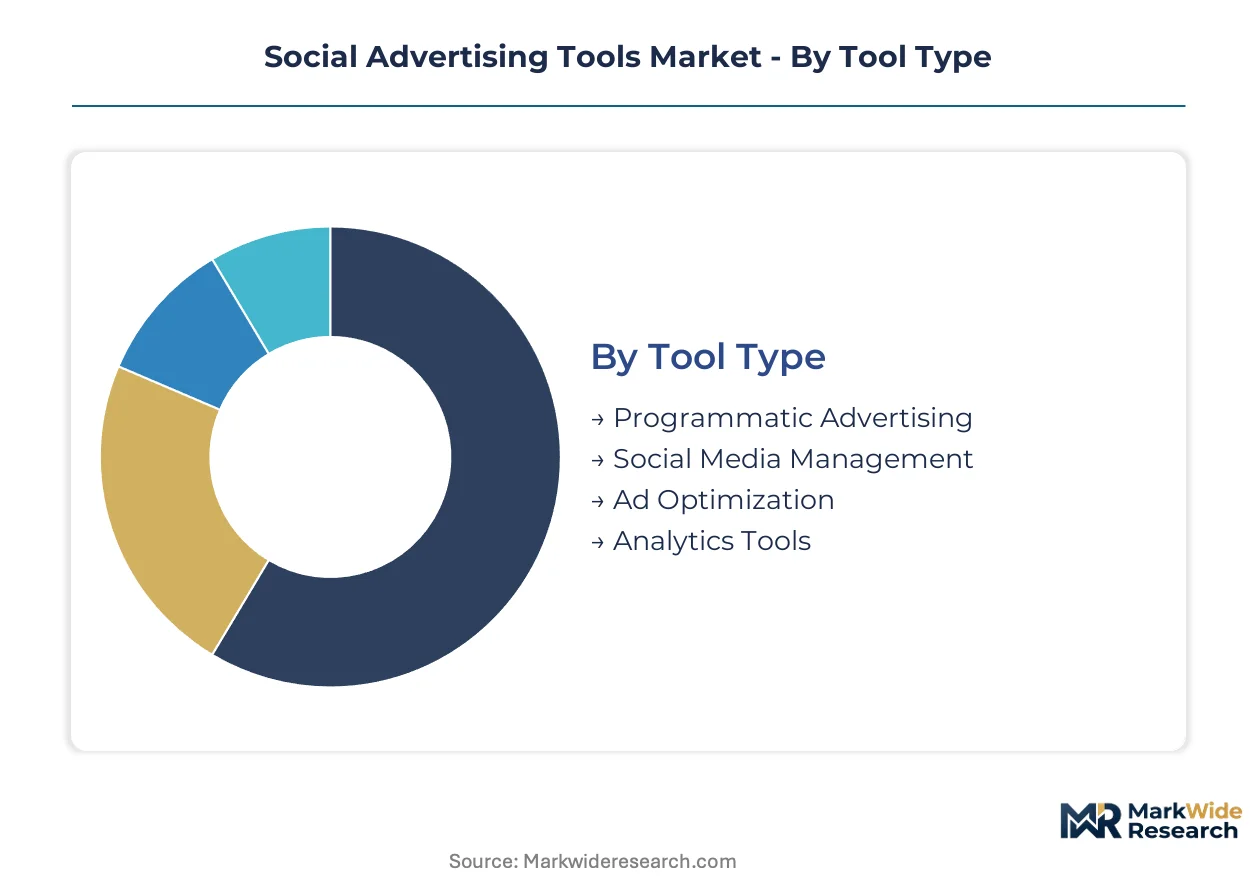
Segmentation in social advertising tools determines API integration depth, workflow complexity, and compliance burden. Buyers select configurations matching their creative velocity, platform diversity, and regulatory exposure. Vendor profitability hinges on serving the right segment with appropriately scoped feature bundles.
Tool Type:
Customization-to-standardization tension runs deepest here — enterprise buyers demand bespoke algorithmic configurations while SMBs accept templated automation.
- Programmatic Advertising:Algorithmic buying engines execute real-time bidding across auction-based inventory pools. Demand concentrates among performance marketers in India, where small-business digitalization outpaces mature-market saturation and drives need for automated cost-per-acquisition controls.
- Analytics Tools:Cross-platform attribution dashboards aggregate fragmented signal sources into unified reporting views. E-commerce retailers form the fastest-expanding buyer segment as they shift budgets from search-first to social-first acquisition strategies and confront iOS privacy framework signal degradation.
- Social Media Management:Multi-platform publishing workflows with collaborative approval chains.
- Ad Optimization:Automated bid adjustment and budget reallocation modules.
Most installed capacity flows through Programmatic Advertising. Expansion is steepest in Analytics Tools.
Platform:
Cost tier structures diverge sharply — Meta ecosystem tools command premium pricing while Twitter-facing solutions compete on accessibility.
- Facebook:First-party data architecture sustains granular targeting capabilities despite signal loss elsewhere. Enterprise buyers in North America leverage deep API access for custom audience segmentation, though EU Digital Services Act transparency mandates are forcing expanded repository integrations.
- Instagram:Visual commerce optimization dominates feature roadmaps. E-commerce operators adopt generative creative workflows fastest here, replacing static libraries with dynamically assembled variants for high-velocity multivariate testing.
- Twitter:Real-time conversation targeting with compressed creative cycles.
- LinkedIn:B2B account-based marketing with professional demographic filters.
Revenue concentration sits with Facebook. Climbing the fastest is Instagram.
Target Audience:
Application complexity scales inversely with buyer size — enterprises demand orchestration layers while micro-retailers need single-click deployment.
- E-commerce:Inventory-synced dynamic creative and purchase-event optimization. This segment absorbs AI-powered asset generation most aggressively as merchants manage high-velocity testing across placements.
- Enterprises:Multi-brand governance, consolidated billing, and cross-platform analytics. Agency holding company procurement teams in North America are reducing approved vendor lists from twelve to three platforms, compressing sales cycles.
- Small Businesses:Simplified campaign automation with pre-built templates.
- Nonprofits:Donation-optimized conversion tracking and grant compliance reporting.
Deployment volume peaks with E-commerce. Gaining share fastest is Enterprises.
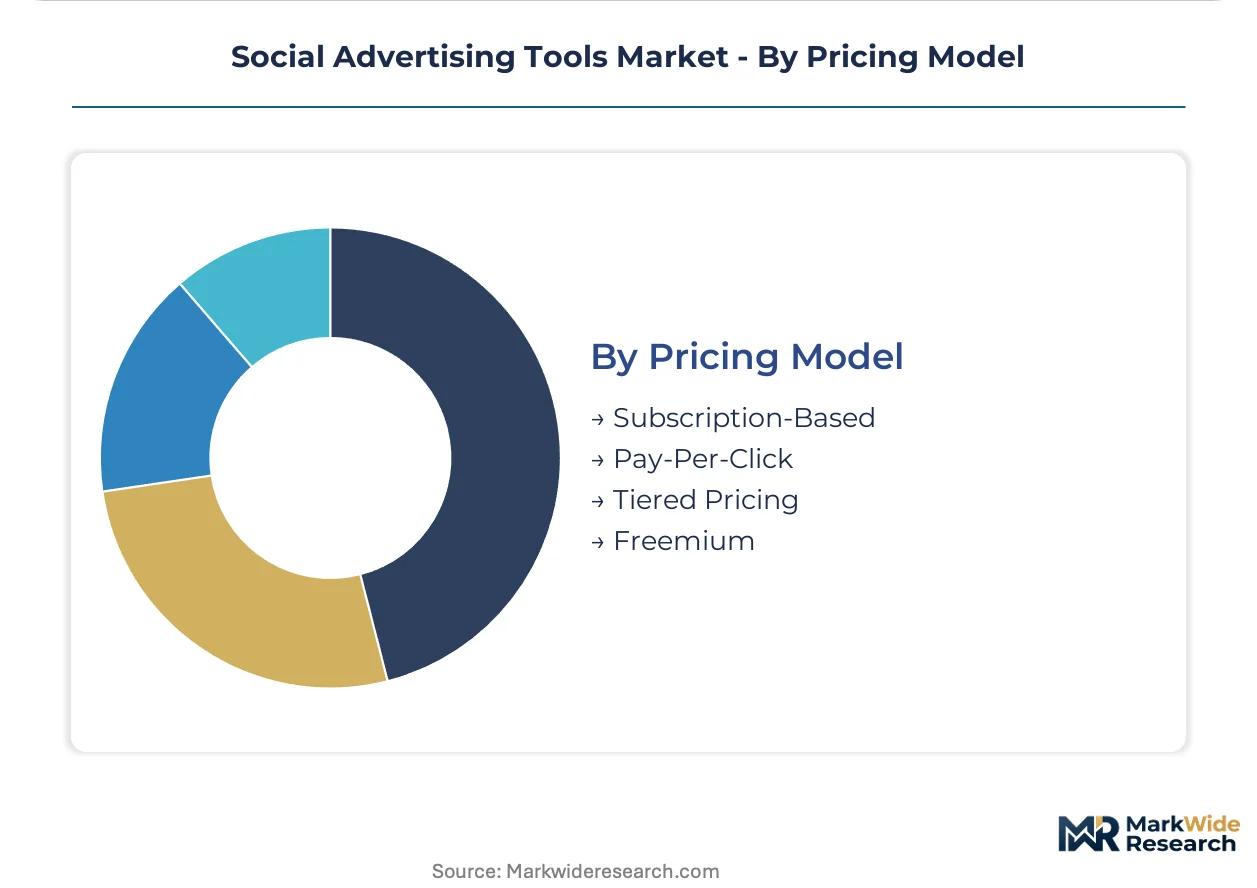
Pricing Model:
Margin profiles separate predictable subscription streams from volatile performance-linked revenue.
- Subscription-Based:Recurring revenue with tiered feature access. Mid-market buyers anchor here, requiring multi-platform publishing workflows without enterprise complexity.
- Pay-Per-Click:Revenue tied to media spend through platform API connections. Direct-response advertisers tolerate this model despite customer acquisition cost volatility from probabilistic attribution modeling.
- Tiered Pricing:Feature stratification across user count or ad volume thresholds.
- Freemium:Conversion funnel from basic scheduling to paid optimization modules.
Recurring revenue stability concentrates in Subscription-Based. Steepest expansion trajectory belongs to Pay-Per-Click.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping vendor footprints as compliance costs diverge across jurisdictions. Tool providers migrate engineering resources toward jurisdictions with lighter algorithmic oversight while maintaining sales presence in high-enforcement markets.
United States
Enterprise advertisers and DTC aggregators drive platform spend concentration. FTC endorsement disclosure requirements and FDA health-claim oversight force compliance module integration into creative workflows. Seattle and San Francisco cloud-native clusters feed platform innovation through API-first development.
India
Micro-retailers and local service providers form the fastest-expanding buyer segment as platform penetration outpaces mature-market saturation. TRAI data-localization guidelines and RBI digital payment integration shape tool architecture for commerce-linked campaigns. Mumbai and Bangalore house the primary vendor development centers serving Asia-Pacific demand.
Germany
Mid-market e-commerce operators adopt AI-powered asset generation for high-velocity multivariate testing. GDPR enforcement and EU AI Act risk classification impose documentation burdens on algorithmic targeting systems. Berlin and Munich clusters concentrate compliance-embedded analytics engineering.
United Kingdom
Agency holding companies consolidate vendor relationships, reducing approved platform lists from twelve to three. ICO guidance on automated decision-making intersects with CMA digital market scrutiny. London anchors European sales operations for North American SaaS providers.
Brazil
WhatsApp Business API expansion and Instagram commerce adoption among regional retailers create whitespace for localized automation. ANVISA pharmaceutical advertising rules and consumer protection disclosure mandates shape creative compliance. São Paulo concentrates both vendor technical support and brand headquarters demand.
Social Advertising Tools Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue vertical specialization around regulatory compliance and generative creative workflows. The vendor base separates into three maturity tiers: platform-native suites with first-party data architecture, independent multi-platform orchestration tools, and point-solution specialists in attribution or creative automation. Consolidation pressure intensifies as agency procurement teams reduce approved vendor lists. Dominant competitive moves include API access negotiation with platform owners and M&A to acquire probabilistic attribution capabilities.
Within the platform-native tier, Meta and Google anchor competitive positioning through data architecture lock-in. Hootsuite occupies a position among mid-market buyers requiring multi-platform publishing without enterprise complexity. These three exemplify how vendor profitability hinges on serving segment-appropriate feature bundles while managing platform policy volatility.
| Leading Market Players |
|---|
| Meta (Facebook Ads Manager) |
| Google (Google Analytics) |
| Hootsuite |
| Sprout Social |
| Buffer |
| Adobe |
| Semrush |
| HubSpot |
| Smartly.io |
| Others |
Value Network & Pricing Analysis
EU AI Act documentation mandates gate qualified supply and premium-tier pricing access, as vendors must maintain model cards and audit trails for automated bidding logic deployed within the European Economic Area, compressing margins for non-compliant providers while rewarding those with embedded compliance engineering.
Pricing Analysis
Direct-to-SMB channel margins absorb the steepest compression as self-serve platform tools narrow differentiation headroom for third-party vendors. Subscription-based SaaS tiers dominate enterprise relationships, while pay-per-click models tie revenue to media spend volatility. Price differentiation rests on API access depth and generative creative capabilities. Mid-market buyers show highest price sensitivity; enterprise procurement teams least, consolidating vendor lists from twelve to three platforms.
Supply Chain Analysis
Direct-to-hyperscale channels handle enterprise buyer demand, while tiered distributor networks serve mid-market and SMB segments. Engineering talent concentrates in Seattle, San Francisco, Toronto, Mumbai, and Bangalore. Cloud infrastructure draws from AWS and Azure compute pools, with API connectivity and machine learning inference engines as critical components. Single-source vulnerability runs through hyperscaler concentration, limiting price negotiation leverage for mid-scale tool providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play. EU AI Act compliance costs in Berlin and Munich clusters exceed Bangalore development center economics by multiples, creating margin expansion for vendors with India-based engineering and EU-facing sales.
For Market Incumbents: Acquire probabilistic attribution capabilities to offset iOS privacy framework signal degradation. Consolidate API access negotiations with Meta and Google into long-term partnership frameworks. Defensive moves must address platform self-serve tool improvement that absorbs previously exclusive third-party functionality.
For New Entrants and Emerging Players: Capture Brazil's WhatsApp Business API expansion whitespace among regional retailers underserved by localized campaign automation. India's micro-retailer segment offers penetrable entry with simplified templates. Go-to-market through Instagram commerce adoption curves rather than direct platform competition.
For Investors and Strategic Acquirers: Roll-up economics work for mid-market analytics specialists because agency holding company procurement consolidation demands cross-platform orchestration from fewer vendors. Five-to-ten year viability hinges on API policy volatility management. Watch Meta and Google data access permission tightening as inflection signal for margin compression timing.
| Strategic Initiative | Industry Significance |
|---|---|
| API Access Negotiation | Long-term platform partnership agreements secure targeting and reporting functionality against deprecation cycles. |
| Compliance Module Development | Embedded EU AI Act documentation and FTC disclosure automation open regulated market access. |
| Generative Creative Acquisition | Predictive intelligence capabilities unify previously siloed creative and media planning workflows. |
| India Engineering Expansion | Bangalore and Mumbai clusters reduce compliance-embedded analytics development costs versus EU centers. |
| Retail Media Integration | Amazon and Walmart ad platform connections enable unified planning across social and commerce media. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary fieldwork engaged social advertising platform engineers, performance marketing directors at e-commerce operators, agency holding company procurement leads, and API product managers at Meta and Google. Secondary validation drew from SEC filings, hyperscaler capex disclosures, EU regulatory repository filings, and platform transparency report data. Bottom-up segment sizing and top-down market triangulation cross-checked volume estimates.
Historical reference periods anchored the projection horizon to observed platform policy shifts and privacy framework implementations. The analytical framework modeled deployment model, organization size, vertical specialization, integration complexity, and regional adoption pattern dimensions. CAGRs derived from segment-level growth rate synthesis and platform spend trajectory analysis. Forecast inputs incorporated API deprecation cycle frequency and generative creative adoption velocity assumptions.
Underlying measurement precision varies by segment; programmatic advertising and analytics tools carry tighter precision than emerging retail media network convergence categories. Forecasts reflect documented assumptions about platform self-serve tool improvement rates and signal loss recovery technology diffusion. Periodic stress-testing of base assumptions is recommended given API policy volatility and regulatory enforcement timing uncertainty.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Social Media Analytics
Germany Social Media Management Market
Social Media Analytics
Social Media Records Management Market
Social Media Analytics
Social Media Management Market
Social Media Analytics
Global TV Analytics Market
Social Media Analytics
Audience Intelligence Platforms Market
Social Media Analytics
US Social Media Management Market
Social Media Analytics
Italy Social Media Management Market
Social Media Analytics
Europe Social Media Analytics Market
Social Media Analytics
Global Audience Analytics Market
Social Media Analytics
Europe Social Media Management Market
Social Media Analytics
Media Monitoring Tools Market
Social Media Analytics
China Social Media Management Market
Social Media Analytics
Social Media Listening Market
Social Media Analytics
Brazil Social Media Management Market
Social Media Analytics
Social Media Analytics Market