
 Europe Social Media Management Market | 2026-2036
Europe Social Media Management Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Social Media Management Market Analytics
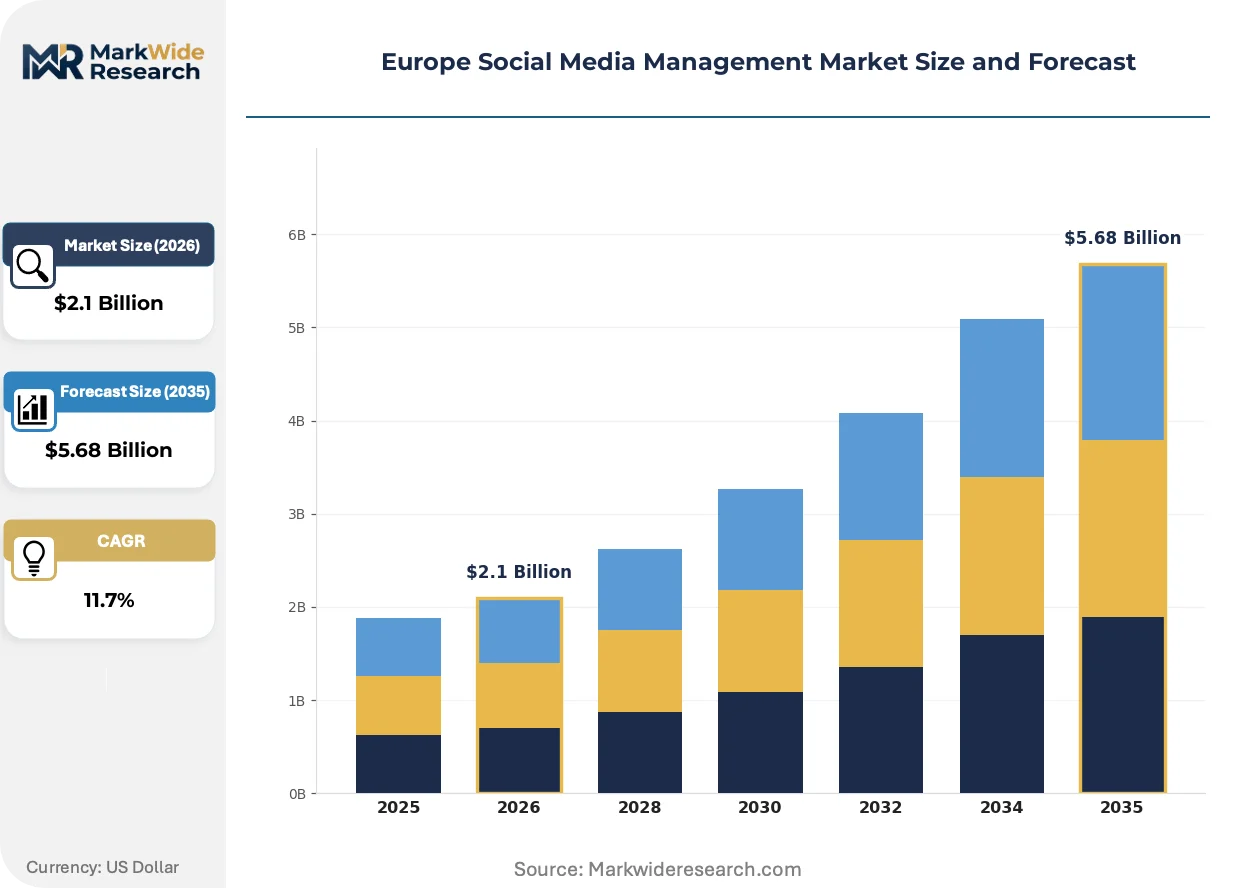
Subscription-based analytics tiers is restructuring how European vendors monetize social media management, shifting buyers from perpetual licenses toward recurring revenue models. Hootsuite anchors its position through deep integration with major European platforms. Sprinklr competes on enterprise-scale governance tools for regulated industries. Adobe extends its creative cloud footprint into social publishing workflows.
Social media management encompasses software platforms and services that schedule, publish, monitor, and analyze content across social networks, typically operating through API connections to platform backends with throughput measured in thousands of posts per hour. The primary commercial purpose is to centralize brand voice, reduce response latency, and generate engagement metrics for marketing attribution. Cloud-based SaaS deployment leads European adoption due to elastic scaling and reduced IT overhead. Content creation services command premium pricing as brands outsource creative production. Analytics functionality is the fastest-growing segment as attribution demands intensify under privacy constraints.
The EU Digital Services Act and GDPR jointly determine data handling architectures, forcing platforms to document algorithmic recommendations and limit cross-border data flows. EMA guidelines on pharmaceutical promotion extend into social channels, requiring audit trails for healthcare communications. France's CNIL and Germany's regional data protection authorities actively enforce cookie consent and profiling restrictions. Stakeholders must monitor evolving platform API policies and national interpretations of the AI Act as automated content generation tools proliferate.
Market Dynamics
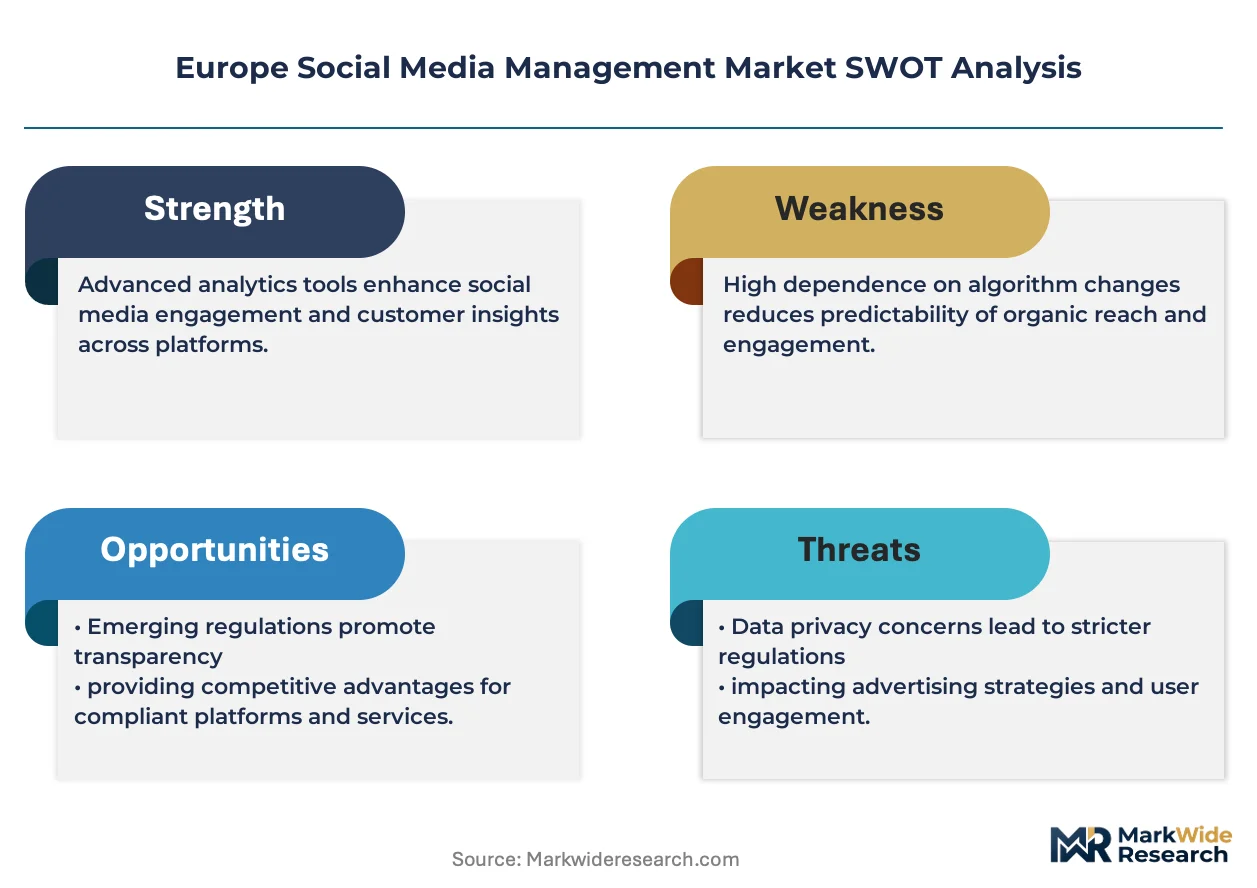
The EU Digital Services Act is restructuring platform accountability architectures, forcing social media management vendors to rebuild data pipelines around documented algorithmic transparency and cross-border flow restrictions. This regulatory pressure cascades through API access terms, consent management workflows, and audit trail requirements.
Growth Catalysts
- GDPR enforcement intensity:France's CNIL and Germany's regional data protection authorities are issuing substantial fines for profiling violations, compelling brands to invest in compliant scheduling and analytics infrastructure with built-in consent orchestration.
- Social commerce expansion:Retail brands in France and Germany are integrating shoppable posts into their operational workflows, generating demand for unified content-to-transaction platforms that bridge organic engagement with direct revenue attribution.
- SaaS elasticity:Cloud-native deployment models allow marketing teams to scale publishing throughput during campaign peaks without provisioning on-premise infrastructure, accelerating replacement of legacy perpetual-license tools.
Market Restraints
- API policy volatility:Platform providers unilaterally modify rate limits and data access scopes, disrupting third-party tool functionality and forcing vendors into reactive engineering cycles.
- Cross-border data friction:Schrems II rulings invalidate EU-US data transfer mechanisms, complicating hosting architectures for vendors serving multinational clients with US-based cloud infrastructure.
- Privacy-compliant attribution erosion:Cookie deprecation and consent fatigue degrade clickstream fidelity, undermining the core value proposition of engagement analytics and ROI demonstration.
Strategic Opportunities
- Healthcare vertical penetration:EMA guidelines on pharmaceutical promotion create demand for audit-ready social governance tools with version-controlled content approval workflows and retention policies.
- AI-generated content governance:The EU AI Act's transparency requirements for automated systems position compliance-native vendors to capture enterprise accounts ahead of enforcement timelines.
- Eastern European expansion:Poland and Romania exhibit underpenetrated mid-market demand as regional brands mature from organic-only posting toward scheduled, measured social operations.
Industry Challenges
- Consent management complexity:Divergent national interpretations of valid consent under GDPR require region-specific legal engineering, fragmenting product roadmaps and delaying feature rollouts.
- Creative production bottlenecks:Real-time content demands outpace in-house studio capacity, forcing brands to orchestrate distributed freelancer networks with inconsistent brand guideline adherence.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Social Media Management Market |
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $5.68 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Content Creation, Analytics, Scheduling, Monitoring Customer Type: Small Businesses, Medium Enterprises, Large Corporations, Agencies Platform Type: Facebook, Twitter, Instagram, LinkedIn Deployment: Cloud-Based, On-Premise, Hybrid, SaaS |
| Companies Covered | Hootsuite, Sprinklr, Sprout Social, Brandwatch, Meltwater, HubSpot, Adobe, Salesforce, Oracle Corporation, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Social Media Management Market Evolving Landscape
Federated content architectures and algorithmic transparency mandates are converging to reshape how European brands orchestrate social presence. Vendors must now engineer around distributed data sovereignty while maintaining unified campaign execution.
Decentralized identity protocols are decentralizing user authentication and consent management across social platforms. Enterprise marketing teams in the Netherlands and United Kingdom are piloting self-sovereign credential systems to streamline cross-platform login workflows. This architecture is decentralizing control over audience data from platform operators back to brand custodians, compressing vendor lock-in effects.
The EU AI Act's risk classification framework is mandating documentation trails for automated content generation tools. Social media management platforms must now embed provenance logging and human-in-the-loop verification for high-risk deployment scenarios. Healthcare and financial services verticals in Germany and France are responding by procuring only those tools with pre-built compliance modules.
Outcome-based pricing models are displacing seat-based subscription tiers among mid-market buyers. Marketing procurement teams in the United Kingdom now negotiate contracts tied to measurable engagement lift rather than user licenses. This shift is most visible among direct-to-consumer retail brands seeking to align vendor costs with attributable revenue contribution.
Europe Social Media Management Market Segmentation
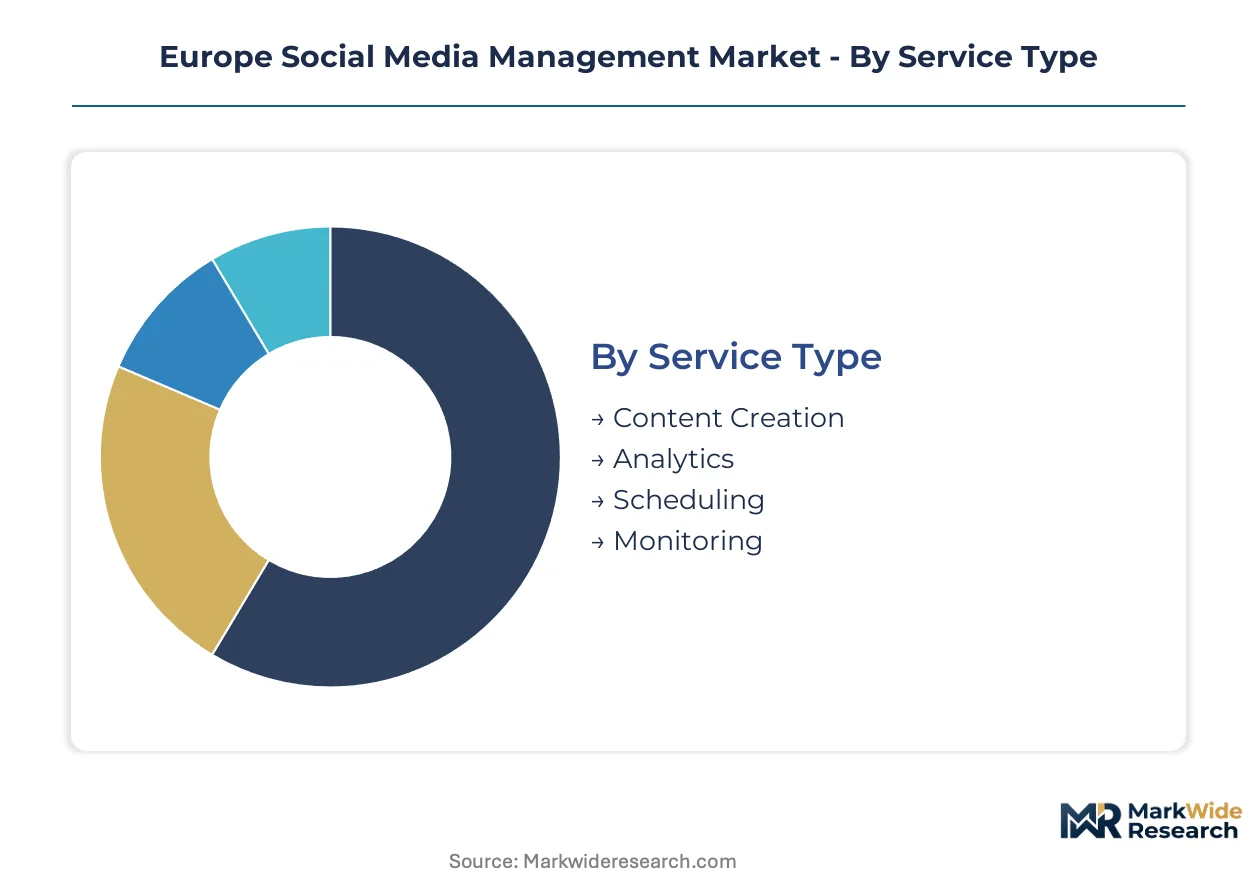
Segmentation in European social media management reflects divergent compliance burdens, workflow complexity, and IT governance standards across buyer types. Each dimension shapes vendor product architecture and pricing elasticity differently.
Service Type:
Service selection correlates directly with in-house creative capacity and attribution maturity among European marketing organizations.
- Content Creation:Production of native-format assets including short-form video, carousel posts, and platform-optimized copy. French and German retail brands with limited studio resources drive outsourcing demand here, prioritizing localized creative that satisfies GDPR consent documentation for user-generated content integration.
- Analytics:Engagement attribution, sentiment analysis, and competitive benchmarking dashboards. United Kingdom and Netherlands procurement teams concentrate spending in this segment as privacy-compliant measurement becomes the primary vendor selection criterion following cookie deprecation.
- Scheduling:Calendar-based publishing orchestration with approval workflows.
- Monitoring:Real-time brand mention tracking and response queue management.
Scheduling leads volumes today; analytics is gaining share fastest.
Customer Type:
Scale determines regulatory exposure and integration depth requirements across the buyer base.
- Large Corporations:Enterprise-grade deployments with multi-market governance, audit trails, and API throughput exceeding thousands of posts hourly. German automotive and pharmaceutical headquarters mandate on-premise data residency options to satisfy works council agreements and EMA documentation requirements.
- Agencies:Multi-tenant architectures serving portfolio clients with segregated workspaces and consolidated billing. London and Paris agency holding companies expand fastest here, driven by client demand for unified reporting across fragmented brand portfolios.
- Medium Enterprises:Mid-market buyers seeking scalable seats without enterprise implementation overhead.
- Small Businesses:Single-user or small-team subscriptions with template-driven content capabilities.
Agencies dominate current seat counts; large corporations show steepest expansion trajectory.
Platform Type:
Platform prioritization varies by B2B versus B2C orientation and demographic targeting precision.
- LinkedIn:Professional network management with employee advocacy and lead generation focus. B2B technology vendors in Ireland and the Netherlands allocate disproportionate tooling spend here, leveraging native targeting for account-based marketing programs subject to GDPR professional data restrictions.
- Instagram:Visual commerce and influencer collaboration workflows. French luxury houses and Italian fashion brands drive premium feature adoption, requiring shoppable post integration and creator contract management compliant with national influencer disclosure rules.
- Facebook:Community management and paid social orchestration.
- Twitter:Real-time customer service and executive communications.
Instagram captures highest per-seat pricing; LinkedIn is climbing the fastest among platform-specific tool investments.
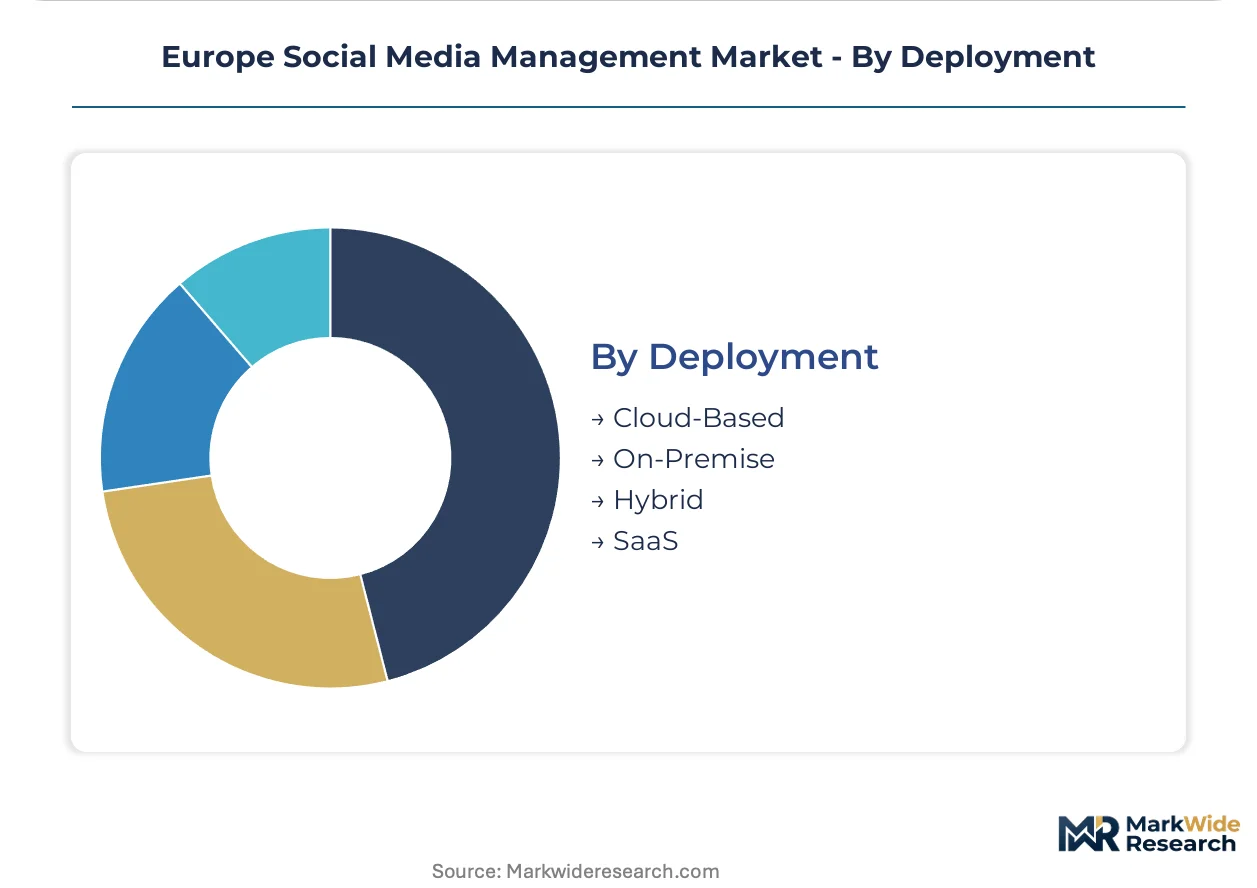
Deployment:
Infrastructure choice reflects data sovereignty priorities and IT department involvement levels.
- Cloud-Based:Fully managed SaaS with elastic compute and automatic updates. United Kingdom marketing teams lead adoption here, prioritizing rapid deployment and reduced infrastructure ownership despite Schrems II complications for US-hosted instances.
- SaaS:Subscription-native delivery with API-first architecture and monthly billing flexibility. Polish and Romanian mid-market brands gravitate toward this model as they transition from organic-only posting toward measured, scheduled operations.
- On-Premise:Self-hosted installations with local data storage.
- Hybrid:Mixed architectures with sensitive data on-premise and publishing layers cloud-hosted.
SaaS holds the dominant share; hybrid deployments are expanding most quickly among regulated German and French verticals.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's automotive and pharmaceutical headquarters demand stricter data residency than United Kingdom marketing teams, who prioritize rapid SaaS deployment despite cross-border complications. France enforces influencer disclosure rules that reshape creator economy workflows. The Netherlands pilots decentralized identity protocols. Poland and Romania represent underpenetrated mid-market expansion zones.
Germany
Automotive and pharmaceutical headquarters in Stuttgart and Munich mandate on-premise data residency options to satisfy works council agreements and EMA documentation requirements for healthcare communications. Regional data protection authorities enforce cookie consent and profiling restrictions with substantial fines. Frankfurt and Berlin host enterprise procurement teams scaling API throughput for thousands of posts hourly.
United Kingdom
London marketing teams lead cloud-based adoption prioritizing elastic scaling and reduced infrastructure ownership, though Schrems II rulings complicate US-hosted instances. Procurement teams negotiate outcome-based contracts tied to measurable engagement lift rather than user licenses. The capital's agency holding companies expand multi-tenant architectures serving fragmented brand portfolios with unified reporting demands.
France
Luxury houses and retail brands in Paris drive premium feature adoption for shoppable post integration and creator contract management compliant with national influencer disclosure rules. CNIL actively enforces GDPR profiling violations, compelling investment in compliant scheduling infrastructure with built-in consent orchestration. Lyon and Marseille clusters mature from organic-only posting toward measured, scheduled operations.
Netherlands
Amsterdam and Rotterdam enterprise teams pilot self-sovereign credential systems to streamline cross-platform login workflows, decentralizing audience data control from platform operators back to brand custodians. Dutch procurement concentrates spending on privacy-compliant analytics as vendor selection criterion following cookie deprecation. Eindhoven's technology vendors leverage native LinkedIn targeting for account-based marketing programs.
Poland
Warsaw and Krakow mid-market brands gravitate toward SaaS subscription-native delivery with API-first architecture as they transition from organic-only posting toward scheduled, measured social operations. Regional brands exhibit underpenetrated demand for unified content-to-transaction platforms bridging organic engagement with revenue attribution. Local marketing teams prioritize monthly billing flexibility over enterprise implementation overhead.
Europe Social Media Management Market Competitive Landscape
Top-tier vendors anchor enterprise governance capabilities, while mid-market specialists compete on pricing elasticity and rapid deployment. The vendor base stratifies across three tiers: full-suite platforms with multi-market compliance modules, vertical specialists targeting regulated industries, and template-driven solutions for small-team workflows. Two dominant competitive moves are reshaping positioning: M&A activity consolidating adjacent analytics and creative production capabilities, and strategic partnerships with cloud infrastructure providers to resolve data sovereignty requirements.
Within the full-suite platform tier, Hootsuite and Sprinklr occupy positions defined by integration depth and enterprise-scale governance respectively. Sprout Social exemplifies the mid-market vector with subscription-native delivery models. These three anchors represent divergent strategic archetypes: Hootsuite emphasizes platform connectivity, Sprinklr competes on compliance-heavy vertical penetration, and Sprout Social captures pricing-sensitive buyers transitioning from organic-only operations. Adobe extends from adjacent creative software into social publishing workflows, while Salesforce and Oracle Corporation sit within broader enterprise cloud ecosystems where social management functions as a module rather than standalone offering.
| Leading Market Players |
|---|
| Hootsuite |
| Sprinklr |
| Sprout Social |
| Brandwatch |
| Meltwater |
| HubSpot |
| Adobe |
| Salesforce |
| Oracle Corporation |
| Others |
Value Network & Pricing Analysis
API access fees from Meta, LinkedIn, and X traverse downstream through SaaS vendor cost structures, compressing margins at the mid-market tier while enterprise buyers absorb premium pricing for guaranteed throughput. Cloud infrastructure costs in Frankfurt and Amsterdam data centers feed into subscription tiers, with German automotive and pharmaceutical headquarters paying surcharges for on-premise data residency options.
Pricing Analysis
Capacity additions in Poland and Romania are reshaping price floors for SaaS-native social media management tools. Subscription tiers stratify across premium compliance-heavy enterprise modules, standard multi-tenant agency configurations, and economy self-serve plans for small teams. Price differentiation rests on audit trail depth and consent orchestration sophistication. Pricing pressure stems from outcome-based contract demands in the United Kingdom, where procurement teams negotiate engagement-lift guarantees. Small businesses exhibit highest price sensitivity; large corporations in regulated German verticals show least.
Supply Chain Analysis
Cross-border data routing costs between EU and UK instances complicate hosting architectures for vendors serving multinational clients. Software development concentrates in Ireland, Germany, and the Netherlands, with cloud infrastructure anchored in Frankfurt, Amsterdam, and Dublin data centers. Raw material dependencies include API rate licenses from platform operators, compute capacity from hyperscalers, and specialized talent for compliance engineering. Supply chain risk centers on Schrems II invalidation of EU-US data transfer mechanisms. Distribution runs through direct SaaS sales, agency channel partnerships, and cloud marketplace listings.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Arbitrage opportunities emerge between German data residency premiums and Polish SaaS elasticity, exploiting regulatory cost differentials across the single market.
For Market Incumbents: Deploy compliance-native product modules to capture healthcare and financial services verticals ahead of EU AI Act enforcement timelines. Consolidate adjacent analytics capabilities through targeted acquisitions. Threat substitution from decentralized identity protocols demands preemptive integration with self-sovereign credential systems. Capacity expansion in Eastern European R&D centers reduces engineering costs. For New Entrants and Emerging Players: Direct-to-brand SaaS routes bypass entrenched agency relationships in Poland and Romania. White-space targets include mid-market manufacturers transitioning from organic-only posting and healthcare marketing teams requiring EMA-compliant audit trails. The most penetrable segment is scheduled analytics for underpenetrated Eastern European brands. Go-to-market leverage rests on outcome-based pricing aligned with attributable revenue lift. For Investors and Strategic Acquirers: Consolidation pressure builds where compliance engineering costs outstrip standalone vendor R&D budgets. Long-term viability favors platforms with pre-built vertical modules for regulated industries. Acquisition target archetype: mid-market SaaS vendors with strong API integration layers but limited governance depth. Signal to watch: EMA guideline enforcement intensity on pharmaceutical social promotion.| Strategic Initiative | Industry Significance |
|---|---|
| Compliance Module Development | Pre-built EMA and GDPR-native tools capture regulated German healthcare accounts. |
| Eastern European Expansion | Polish and Romanian mid-market demand shifts from organic posting toward measured operations. |
| Outcome-Based Pricing Pivot | UK procurement teams align vendor costs with attributable engagement lift metrics. |
| Hybrid Deployment Architecture | Frankfurt data residency options satisfy German works council agreements. |
| AI Governance Integration | EU AI Act documentation trails embed provenance logging for automated content tools. |
Research Methodology
Bottom-up enterprise procurement modeling reconciled against top-down vendor revenue tracking forms the analytical core of this study. Primary interviews with social media management platform executives, marketing procurement officers at German automotive and pharmaceutical headquarters, agency holding company technology directors, and CNIL regulatory affairs specialists combined with secondary validation. Secondary sources include EMA guideline documentation, GDPR enforcement actions from France's CNIL and German regional data protection authorities, platform API policy disclosures, and cloud infrastructure provider regional capacity reports.
Historical trendline analysis of subscription revenue growth and seat expansion patterns informed projection frameworks across the analysis window. Segmentation dimensions modeled include deployment architecture, customer scale tier, platform integration depth, vertical regulatory exposure, and geographic data residency requirement. CAGRs derived from fitted growth curves applied to disclosed vendor metrics and procurement survey data. Industry-specific inputs encompass EMA enforcement timelines, Schrems II ruling implementation status, and cookie deprecation impact on attribution tool valuation.
The model assumes a particular technology adoption path; alternative pathways for decentralized identity protocols would alter the outlook. Forecasts reflect underlying assumptions about regulatory enforcement intensity and platform API policy stability. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Social Media Analytics
Social Media Records Management Market
Social Media Analytics
Social Media Management Market
Social Media Analytics
Audience Intelligence Platforms Market
Social Media Analytics
Brazil Social Media Management Market
Social Media Analytics
Social Media Listening Market
Social Media Analytics
Germany Social Media Management Market
Social Media Analytics
Italy Social Media Management Market
Social Media Analytics
Social Media Analytics Market
Social Media Analytics
Media Monitoring Tools Market
Social Media Analytics
China Social Media Management Market
Social Media Analytics
Global Audience Analytics Market
Social Media Analytics
Social Advertising Tools Market
Social Media Analytics
US Social Media Management Market
Social Media Analytics
Global TV Analytics Market
Social Media Analytics
Europe Social Media Analytics Market