
 Germany Social Media Management Market | 2026-2036
Germany Social Media Management Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Social Media Management Market Insights
Subscription-based SaaS financing is reshaping competitive entry in the Germany Social Media Management Market, lowering capital barriers for mid-tier agencies. Glasmeyer Branding GmbH leverages its creative specialization to anchor premium positioning among DAX-listed clients. Social Media Pirates competes through performance-driven campaign structures tailored to e-commerce verticals. MONSOON sustains geographic dominance through embedded relationships with Munich-based enterprise accounts.
Germany Social Media Management encompasses the strategic planning, content creation, scheduling, analytics, and community engagement functions executed across digital platforms to build brand equity and customer relationships. Core technical parameters include API integration depth for multi-platform publishing, real-time sentiment analysis throughput, and GDPR-compliant data handling architectures that encrypt user metadata at rest and in transit. Managed Services command the largest revenue share as enterprises outsource complexity, while Hybrid Solutions represent the fastest-expanding segment as brands blend in-house oversight with external creative production. DIY Platforms occupy a mature niche among freelancers and micro-businesses with standardized needs.
The EU Digital Services Act and Germany's NetzDG framework impose transparency obligations and rapid takedown requirements that elevate demand for compliance-integrated management tools. BSI technical guidelines on cloud security and ISO 27001 certification standards further shape vendor selection criteria for data-sensitive sectors. Stakeholders must monitor how forthcoming EU AI Act provisions on automated content moderation will redefine platform liability and service architecture requirements.
Market Dynamics
GDPR and the EU Digital Services Act are compressing vendor selection timelines as German enterprises demand compliance-integrated architectures from the outset, eliminating point solutions that require retrofitting.
Growth Catalysts
- NetzDG Enforcement:Germany's Network Enforcement Act mandates rapid content takedown protocols, compelling brands to adopt automated moderation tools with embedded legal workflows.
- Automotive Vertical Expansion:German OEMs are redirecting customer service budgets toward social channels, creating sustained demand for enterprise-grade engagement platforms.
- API Ecosystem Maturation:Deepened platform integrations enable real-time cross-channel publishing, reducing operational overhead for multi-brand conglomerates.
Market Restraints
- Data Localization Costs:GDPR-mandated EU server requirements inflate infrastructure spend for foreign entrants seeking German market access.
- Talent Pool Concentration:Berlin and Munich absorb the majority of certified social media strategists, creating wage pressure for operations outside these hubs.
- Platform Dependency Risk:Algorithm changes at Meta and TikTok unpredictably disrupt organic reach calculations, eroding campaign ROI predictability.
Strategic Opportunities
- Baden-Württemberg Manufacturing Belt:Mid-sized industrial firms in Stuttgart and Mannheim remain underpenetrated by managed service providers.
- AI-Generated Content Convergence:Text-to-image models paired with sentiment analysis engines enable hyper-personalized creative production at scale.
- EU AI Act Preparation:Early compliance positioning around automated decision-making disclosures creates differentiation before 2025 implementation deadlines.
Industry Challenges
- Cross-Functional Talent Scarcity:Professionals combining legal compliance expertise with creative strategy command premium compensation, constraining team expansion.
- Legacy CRM Integration Complexity:SAP-dominated enterprise stacks require custom middleware development, extending deployment timelines and inflating project costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Social Media Management Market |
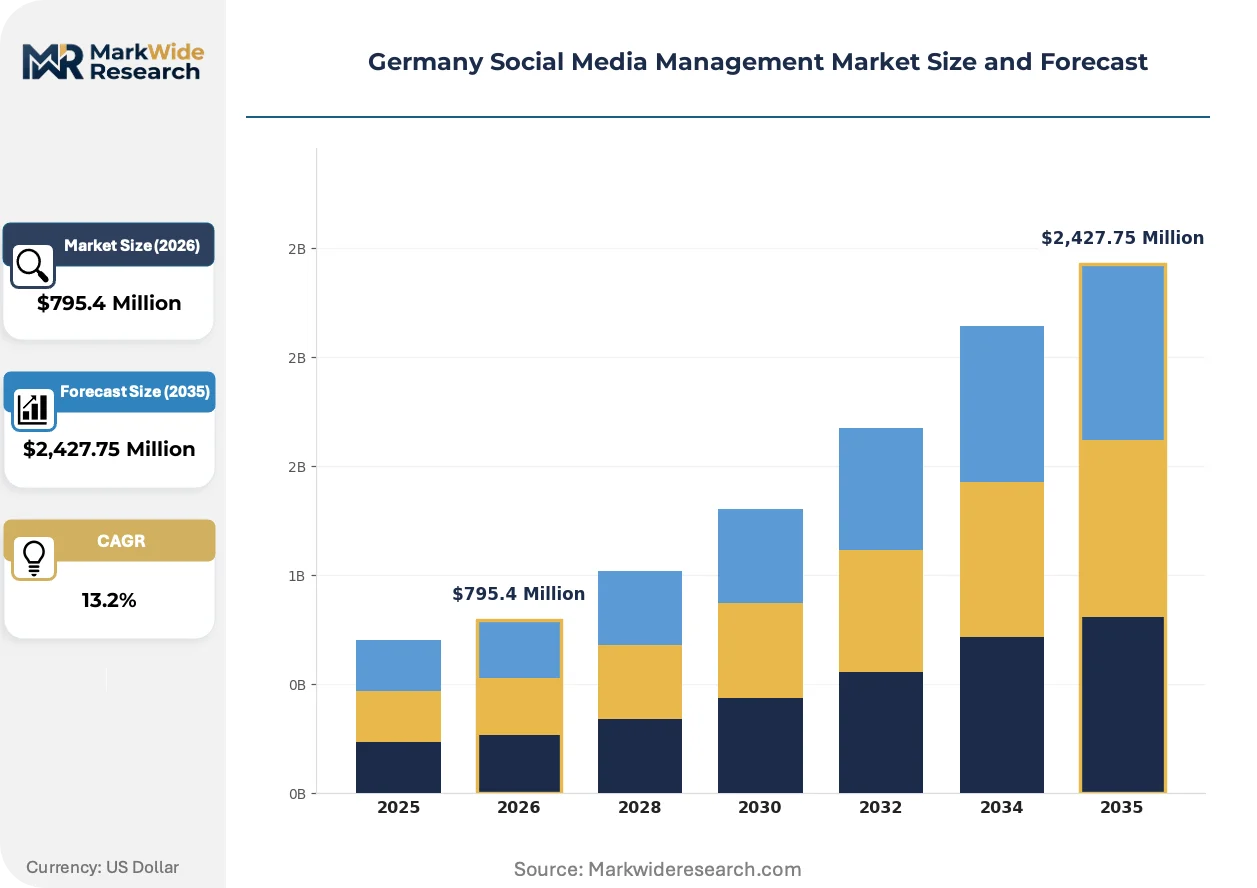
| Market Size in 2026 | $795.4 Million |
| Market Size in 2035 | $2,427.75 Million |
| CAGR (2026 – 2036) | 13.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Platform Type: Facebook, Instagram, Twitter, LinkedIn End User Type: Small Businesses, Enterprises, Marketing Agencies, Freelancers Service Model: Managed Services, DIY Platforms, Hybrid Solutions, Consulting Services Content Type: Text, Images, Videos, Stories |
| Companies Covered | Glasmeyer Branding GmbH, Social Media Pirates, MONSOON, Skalory (Digital Union GmbH), Lomavis, Metanow, Online Digital X GmbH & Co.KG, Elespacio, GOCOMO GmbH, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Social Media Management Market Trends and Innovations
Real-time sentiment analysis and predictive engagement modeling are compressing campaign optimization cycles from weeks to hours, forcing workflow restructuring across German agency ecosystems.
Natural language processing engines with German-language fine-tuning are digitizing community management functions previously handled by human moderators. Mid-market e-commerce operators in Hamburg and Cologne are deploying these tools to maintain 24/7 response coverage without proportional headcount expansion. The shift is digitizing cost structures and enabling service tiering previously uneconomical at smaller scale.
The EU AI Act's transparency requirements for automated content systems are mandating algorithmic audit trails across German social media operations. Vendors must now document decision logic for content promotion and suppression, creating documentation overhead but also competitive moats for compliant providers. Financial services and healthcare verticals in Frankfurt are advancing fastest on implementation due to pre-existing risk management frameworks.
Brand procurement teams are unbundling creative production from strategic planning, awarding separate contracts to specialized studios and management platforms. This fragmentation disrupts traditional full-service agency retainers in Berlin's corporate headquarters cluster. The pattern concentrates among DAX-listed firms seeking granular cost attribution across marketing functions.
Germany Social Media Management Market Segmentation
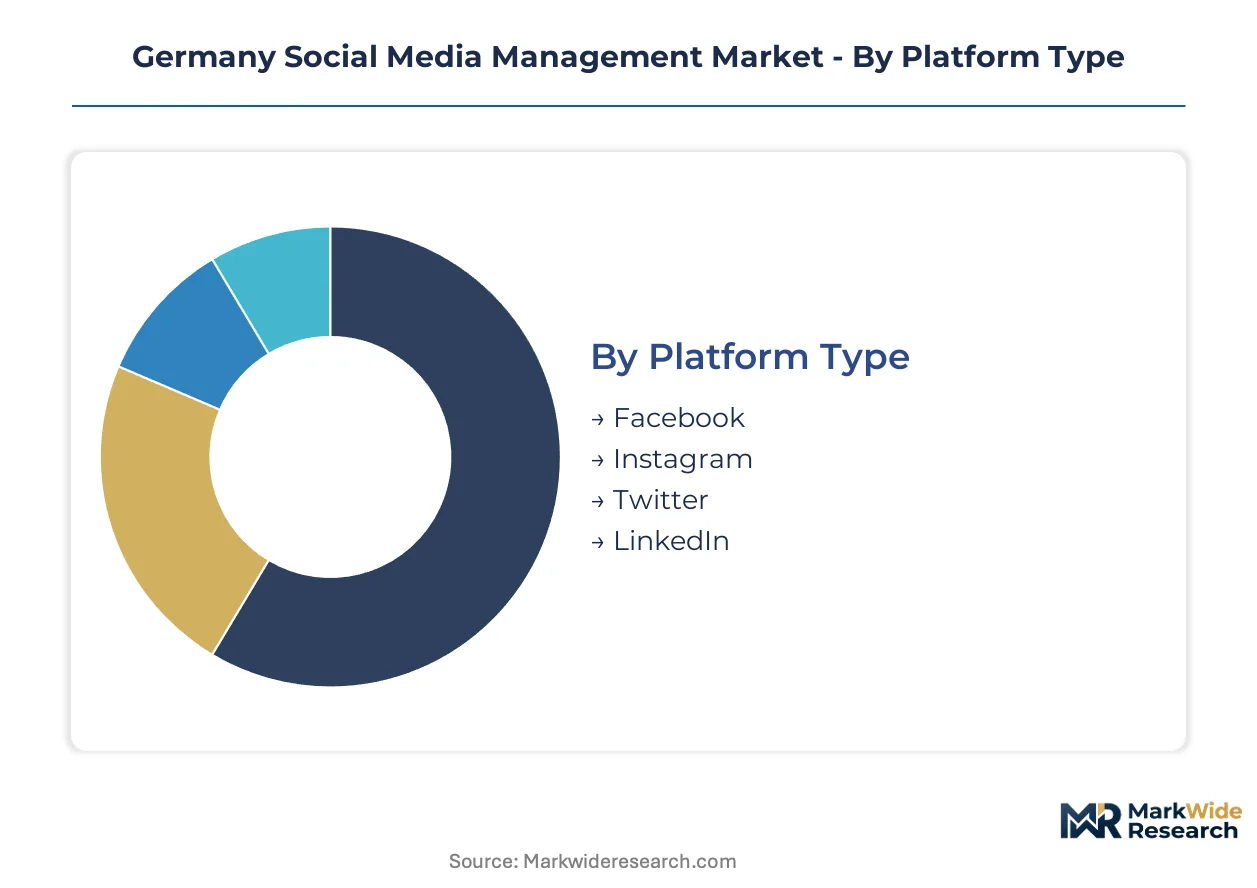
German enterprises structure procurement around compliance architecture and creative velocity. Platform selection and service models diverge sharply across DAX-listed conglomerates versus Stuttgart industrial mid-caps.
Platform Type:
Maturity varies dramatically across platform ecosystems, with established networks commanding enterprise budgets while emerging formats capture experimental spend.
- Facebook:Meta's advertising infrastructure retains the deepest API integration for German automotive and retail verticals. Berlin-based media buyers prioritize its conversion tracking granularity for performance campaigns, though organic reach compression forces paid amplification strategies.
- Instagram:Visual commerce integration drives adoption among Düsseldorf fashion and Munich luxury goods marketers. Shoppable post functionality and Reels distribution now anchor content production budgets for direct-to-consumer brands targeting under-35 demographics.
- Twitter:B2B technology vendors and Frankfurt financial services firms maintain presence for executive thought leadership and crisis communications.
- LinkedIn:Employer branding and lead generation concentrate among Mannheim industrial equipment manufacturers and Hamburg shipping conglomerates seeking qualified professional audiences.
Facebook handles the majority of throughput; Instagram is expanding most quickly on share.
End User Type:
Customer sophistication determines service tier selection, with procurement complexity scaling from individual practitioners to matrixed enterprise buying centers.
- Small Businesses:Cologne and Dresden retail operators deploy templated scheduling tools with limited customization. GDPR self-assessment requirements drive adoption of pre-configured compliance modules over manual policy construction.
- Enterprises:SAP-integrated workflow demands dominate procurement for Munich and Frankfurt headquarters. Procurement teams mandate ISO 27001 certification and EU data residency guarantees, disqualifying offshore SaaS providers without localized infrastructure.
- Marketing Agencies:Hamburg and Berlin full-service shops bundle strategic planning with creative production for industrial clients lacking in-house capabilities.
- Freelancers:Individual practitioners in Leipzig and Nuremberg trade flexibility for platform subscription costs, concentrating in content creation and community moderation niches.
Enterprises drive the majority of contract value; Small Businesses are gaining share fastest through verticalized SaaS templates.
Service Model:
Delivery architecture choices reflect internal capability gaps and risk tolerance around brand governance.
- Managed Services:Outsourced end-to-end execution dominates among NetzDG-affected sectors requiring 24/7 moderation coverage. Stuttgart automotive suppliers and Frankfurt insurers delegate community management to specialized providers with embedded legal escalation protocols.
- DIY Platforms:Self-service tools retain traction among Nuremberg craft producers and Rostock hospitality operators with standardized content needs and limited compliance exposure.
- Hybrid Solutions:Strategic in-house oversight paired with external creative production captures fastest expansion as procurement teams unbundle functions for cost attribution clarity.
- Consulting Services:Transformation advisory concentrates among legacy industrial firms in Dortmund and Essen modernizing digital customer engagement architectures.
Managed Services handles the majority of throughput; Hybrid Solutions shows the steepest expansion trajectory.
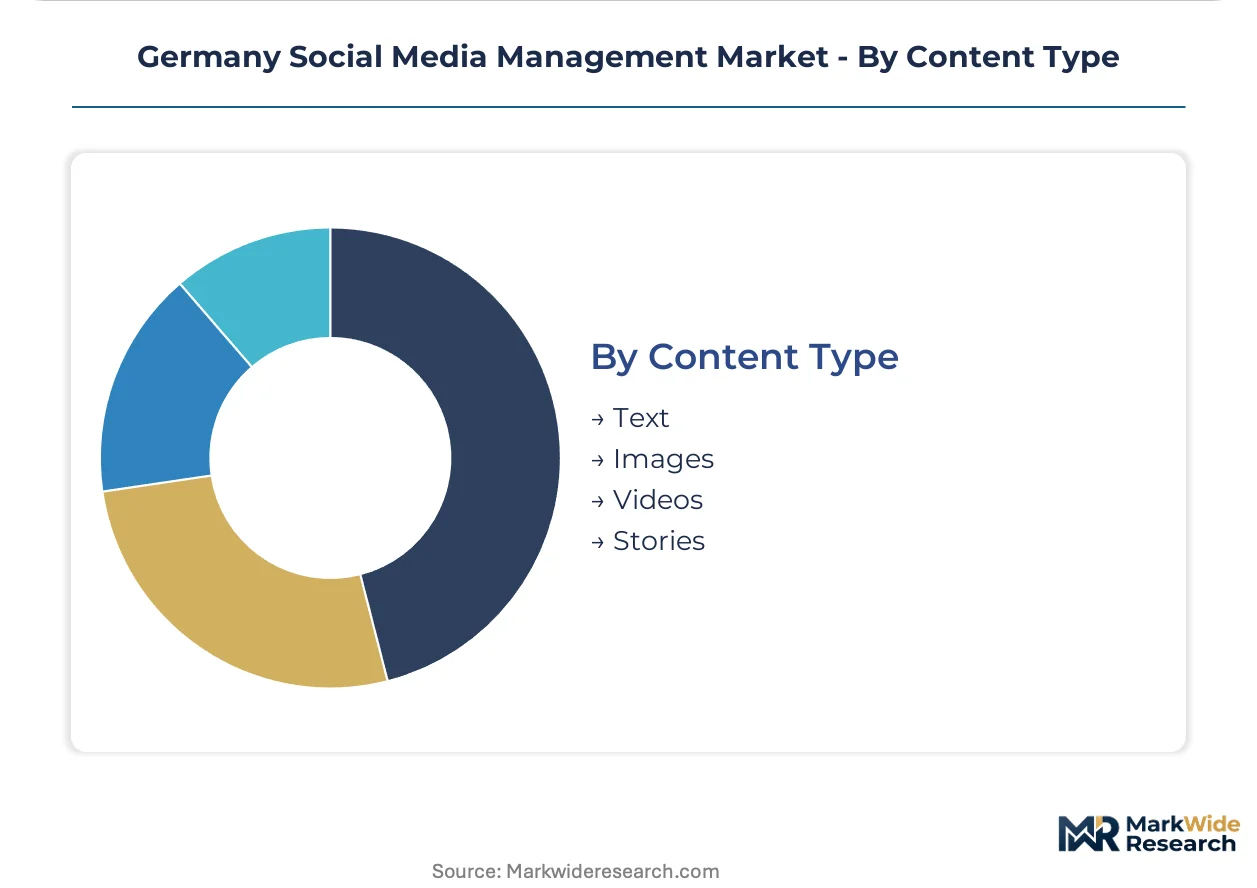
Content Type:
Format investment correlates with platform algorithm priorities and production cost curves.
- Text:Regulatory disclosure requirements and NetzDG documentation obligations sustain demand for compliant copywriting across all verticals.
- Images:Product photography and brand asset libraries anchor e-commerce operations in Hamburg and Berlin with established visual identity systems.
- Videos:Short-form production dominates resource allocation as TikTok and Reels algorithms prioritize motion content. Munich and Cologne studios expand capacity for vertical video formats optimized for mobile consumption.
- Stories:Ephemeral content commands dedicated creative teams for fashion and lifestyle brands seeking engagement velocity over archival value.
Videos absorbs the largest production budgets; Stories climbs fastest on share as platform algorithms reward ephemeral formats.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Berlin and Munich, where agency ecosystems and corporate headquarters cluster, while secondary industrial regions absorb compressed margins from standardized service tiers. The EU Digital Services Act and Germany's NetzDG framework impose uniform compliance costs that disadvantage smaller operators outside major metros.
Bavaria
Automotive OEMs and luxury goods marketers anchor Munich's enterprise-grade demand for managed services. The BSI's cloud security guidelines shape vendor certification requirements for data-sensitive sectors. Stuttgart automotive suppliers in neighboring Baden-Württemberg extend procurement influence northward, consolidating contract awards with Munich-based providers.
North Rhine-Westphalia
Düsseldorf fashion houses and Cologne e-commerce operators drive visual commerce adoption across Instagram and TikTok. GDPR enforcement by the state's data protection authority maintains strict EU server residency mandates. The Ruhr industrial legacy cities of Dortmund and Essen generate consulting demand for legacy CRM modernization and digital transformation advisory.
Berlin-Brandenburg
Startup density and creative agency concentration sustain the highest platform subscription velocity nationally. NetzDG's rapid takedown protocols compel adoption of automated moderation tools with embedded legal workflows. The capital's procurement teams unbundle creative production from strategic planning, fragmenting traditional full-service retainers.
Hesse
Frankfurt financial services and healthcare verticals advance fastest on EU AI Act compliance positioning due to pre-existing risk management frameworks. ISO 27001 certification requirements dominate vendor selection for insurer and bank procurement teams. The city's SAP-dominated enterprise stacks necessitate custom middleware development, extending deployment timelines.
Baden-Württemberg
Mid-sized industrial firms in Stuttgart and Mannheim remain underpenetrated by managed service providers, creating whitespace for specialized entrants. The state's manufacturing belt generates demand for B2B LinkedIn lead generation and employer branding campaigns. Regional wage pressure stays muted compared to Berlin and Munich talent markets.
Germany Social Media Management Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in creative production and compliance tooling. The vendor base organizes around three strategic archetypes: creative-specialist boutiques anchoring premium positioning, performance-driven operators targeting e-commerce verticals, and geography-embedded incumbents sustaining enterprise relationships. Competitive moves concentrate on unbundling service portfolios for procurement transparency and building AI-augmented content production capabilities ahead of regulatory deadlines.
Within the creative-specialist tier, Glasmeyer Branding GmbH exemplifies premium positioning among DAX-listed clients through brand equity focus. Social Media Pirates occupies a performance-driven archetype tailored to e-commerce campaign structures. MONSOON represents geography-embedded dominance through sustained relationships with Munich-based enterprise accounts. These three patterns illustrate how German market participants differentiate amid compliance complexity and procurement fragmentation.
| Leading Market Players |
|---|
| Glasmeyer Branding GmbH |
| Social Media Pirates |
| MONSOON |
| Skalory (Digital Union GmbH) |
| Lomavis |
| Metanow |
| Online Digital X GmbH & Co.KG |
| Elespacio |
| GOCOMO GmbH |
| Others |
Pricing and Supply Chain Analysis
Overcapacity among mid-tier SaaS providers in Berlin and Hamburg compresses margins for standardized scheduling tools while concentrating pricing power with compliance-integrated platforms serving Frankfurt insurers and Munich automotive OEMs. This utilization asymmetry forces undifferentiated vendors toward volume discounting while premium operators capture configured-to-order premiums.
Pricing Analysis
The customization-premium spread separates GDPR-configured enterprise suites from templated small-business subscriptions by a factor of three to five. Subscription SaaS tiers dominate, with price differentiation driven by ISO 27001 certification status and API integration depth. Cost compression in the DIY tier intensifies because of freemium platform saturation. Small businesses in Leipzig and Nuremberg exhibit highest price sensitivity; DAX-listed procurement teams in Frankfurt prioritize compliance guarantees over unit cost.
Supply Chain Analysis
Extended payment terms from Munich enterprise buyers strain working capital for Hamburg creative studios dependent on freelance talent pools. Software development concentrates in Germany, Poland, and Estonia; cloud infrastructure draws from Ireland, Germany, and the Netherlands. Single-source vulnerability runs through Meta's API ecosystem for advertising optimization. Distribution runs through direct SaaS sales for mid-market accounts and agency-mediated procurement for enterprise retainers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
German buyer power is concentrating as DAX procurement teams consolidate vendor rosters from fragmented agency panels toward preferred-platform agreements with compliance-certified providers.
For Market Incumbents: Entrench through embedded SAP integration investments that extend deployment timelines for substitutes, and anchor Munich enterprise relationships with NetzDG-compliant moderation workflows. The threat of AI-native content generation tools demands preemptive API ecosystem deepening to maintain platform lock-in. For New Entrants and Emerging Players: Build out specialized compliance tooling for the EU AI Act's automated decision transparency requirements, targeting Frankfurt financial services and healthcare verticals with pre-existing risk management frameworks. The most penetrable whitespace sits with Stuttgart industrial mid-caps lacking dedicated social media capabilities. A channel partnership route through regional IT system integrators accelerates credibility. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because procurement fragmentation is unsustainable under mounting regulatory documentation burdens. Target acquisition archetypes combine German-language NLP engines with established NetzDG escalation protocols. The signal to watch is agency M&A volume as creative boutiques seek compliance infrastructure through acquisition rather than organic build.| Strategic Initiative | Industry Significance |
|---|---|
| AI-Generated Content Engine Launch | Text-to-image models paired with sentiment analysis compress production cycles for Düsseldorf fashion marketers. |
| EU AI Act Compliance Certification | Algorithmic audit trail capabilities differentiate vendors for Frankfurt financial services procurement teams. |
| SAP-CRM Integration Partnership | Custom middleware development accelerates deployment timelines for Munich automotive enterprise accounts. |
| Geographic Expansion to Baden-Württemberg | Stuttgart industrial belt penetration captures underexploited manufacturing demand for B2B LinkedIn campaigns. |
| Acquisition of Compliance Specialist | NetzDG workflow expertise bolts onto creative agencies serving NetzDG-affected sectors requiring rapid takedown protocols. |
Research Methodology
The analysis maps managed services, DIY platforms, hybrid solutions, and consulting advisory, each validated through social media directors at DAX-listed enterprises, procurement leads at mid-sized industrial firms, compliance officers at Frankfurt financial institutions, and creative directors at Hamburg agencies. Secondary sources include BSI technical guidelines, NetzDG enforcement records, EU Digital Services Act implementation documents, and platform API documentation. Bottom-up contract value estimates triangulate against top-down market sizing across service model segments.
Assumptions held fixed include NetzDG enforcement intensity and GDPR data localization requirements, while variables included AI Act implementation pacing and Meta platform algorithm shifts. Segmentation dimensions modeled encompass service model, platform type, end-user category, and content format across the projection horizon. CAGRs derive from installed base expansion rates and average revenue per account trajectories, with German automotive social spend reallocation and SaaS subscription velocity as primary forecast inputs.
Stress conditions across EU AI Act compliance deadlines, platform API access restrictions, and talent wage inflation in Berlin and Munich were modeled; outcomes outside those bands fall beyond the analytical envelope. Macroeconomic contraction, regulatory enforcement divergence, or generative AI capability breakthroughs would prompt forecast revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Social Media Analytics
Media Monitoring Tools Market
Social Media Analytics
Social Media Listening Market
Social Media Analytics
Social Media Management Market
Social Media Analytics
Global TV Analytics Market
Social Media Analytics
Global Audience Analytics Market
Social Media Analytics
Italy Social Media Management Market
Social Media Analytics
Brazil Social Media Management Market
Social Media Analytics
China Social Media Management Market
Social Media Analytics
Europe Social Media Analytics Market
Social Media Analytics
Social Media Records Management Market
Social Media Analytics
Social Advertising Tools Market
Social Media Analytics
Europe Social Media Management Market
Social Media Analytics
US Social Media Management Market
Social Media Analytics
Social Media Analytics Market
Social Media Analytics
Audience Intelligence Platforms Market